
 Peach Extract Market | 2026-2036
Peach Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Peach Extract Market Analytics
REACH compliance in Europe is pivoting the cost-of-entry calculus for peach extract suppliers by mandating exhaustive substance safety dossiers and restricting certain solvent residues in botanical processing. Givaudan leverages its integrated flavor creation platform to sustain premium positioning across regulated European markets. Martin Bauer Group anchors its supply security through controlled agricultural partnerships in peach-growing regions. Synthite Industries competes on extraction technology leadership, specializing in supercritical CO2 methods that reduce thermal degradation of volatile aroma compounds.
Peach extract comprises concentrated bioactive compounds—primarily phenolic acids, flavonoids, and volatile esters such as benzaldehyde and gamma-decalactone—obtained through aqueous ethanol extraction or cold-pressing of Prunus persica fruit flesh, serving as natural flavoring, coloring, and antioxidant additives across food, cosmetic, and pharmaceutical matrices. Liquid extract formulations dominate commercial volumes due to their ease of incorporation into beverage bases and syrups, while powder formats are gaining traction in dry-mix nutraceutical applications where shelf stability and dosing precision matter. Organic formulation certification commands margin premiums as European and North American procurement policies tighten botanical traceability requirements.
FDA GRAS determinations and EFSA novel food assessments shape market access timelines for peach extract innovators, with compliance costs diverting smaller suppliers toward contract manufacturing arrangements. ISO 22000 and HACCP frameworks govern extraction facility certifications that large buyers mandate for vendor qualification. Stakeholders must monitor evolving EU botanical health claim restrictions and U.S. state-level pesticide residue limits as these regulatory vectors increasingly determine which extraction sources and processing geographies qualify for premium supply contracts.
Market Dynamics
Clean-label procurement mandates from European beverage manufacturers are restructuring supplier qualification requirements, forcing extraction facilities to document solvent residues below REACH thresholds and secure organic certification chain-of-custody.
Growth Catalysts
- REACH solvent residue limits:European regulators now enforce sub-ppm thresholds for hexane and acetone in botanical processing, disqualifying legacy extraction facilities and creating procurement premiums for compliant suppliers.
- Ready-to-drink beverage formulation:German and French premium soft drink producers are replacing synthetic peach flavoring with natural extracts to meet retailer clean-label requirements.
- Supercritical CO2 extraction:This non-thermal processing method preserves volatile ester profiles that aqueous ethanol destroys, enabling flavor house differentiation in high-end applications.
Market Restraints
- Input cost volatility:Spanish and Italian peach concentrate prices fluctuate with Mediterranean frost cycles, compressing margins for fixed-contract extract suppliers.
- Supply concentration risk:Over half of EU organic peach cultivation clusters in Sicily and Calabria, creating geographic vulnerability to climate-driven crop failures.
- Regulatory friction:EFSA novel food assessments for new peach extract delivery formats extend commercialization timelines by 18-24 months versus GRAS-equivalent US pathways.
Strategic Opportunities
- Underpenetrated nutraceutical applications:Polish and Romanian supplement manufacturers remain dependent on synthetic antioxidants, creating white space for phenolic-rich peach extract positioning.
- EU Green Deal bioeconomy incentives:Circular processing grants now subsidize extraction facilities that convert peach pomace waste into high-value antioxidant concentrates.
- Direct-to-manufacturer digital platforms:B2B marketplaces are collapsing traditional three-tier distribution, allowing mid-size extractors to access formulation R&D labs without broker intermediation.
Industry Challenges
- Specialized technician scarcity:Supercritical CO2 equipment operation and maintenance requires certified pressure-system engineers that extraction facilities in Eastern Europe struggle to recruit.
- Organic certification timeline compression:Three-year conversion periods for conventional peach orchards limit supply elasticity when spot organic premiums spike.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peach Extract Market |
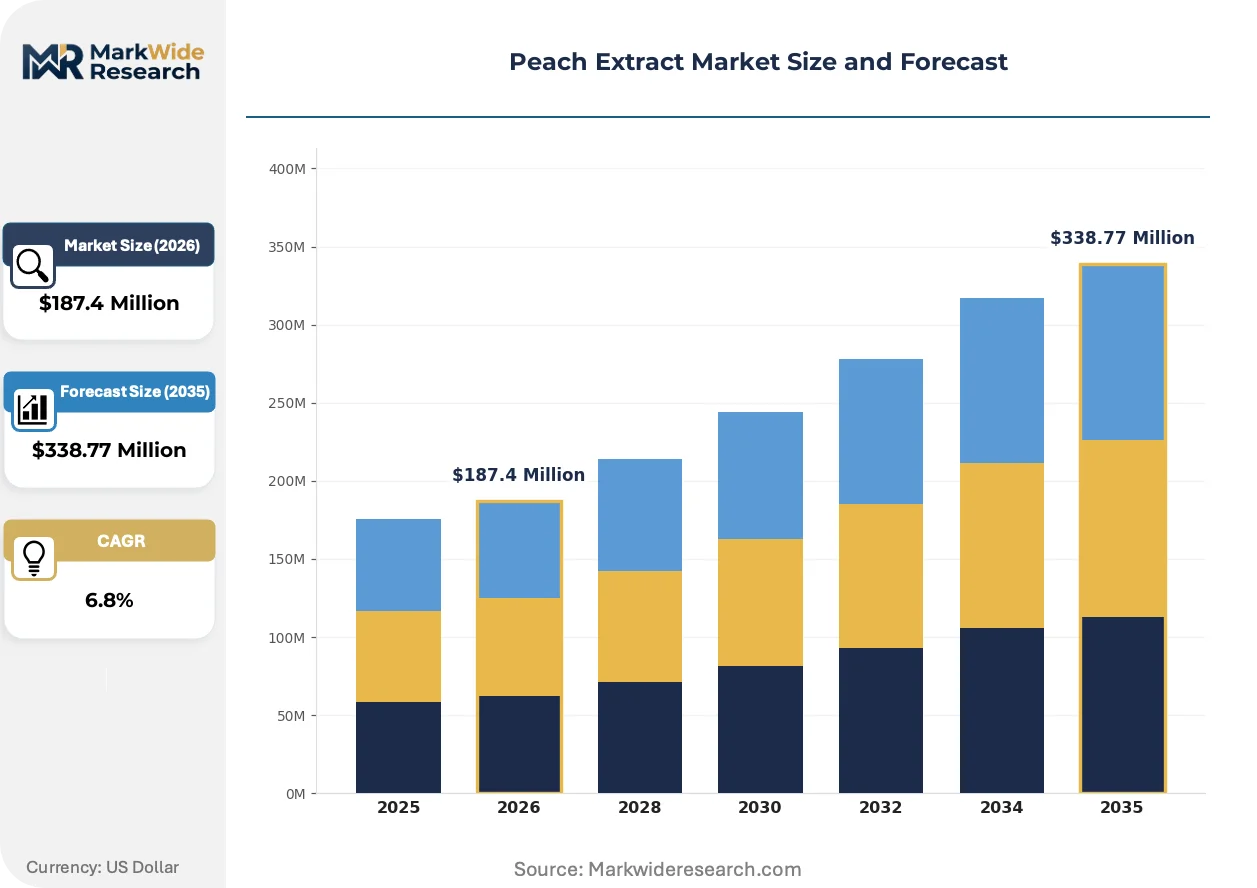
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder, Concentrate, Capsule Application: Food & Beverages, Cosmetics, Pharmaceuticals, Nutraceuticals Formulation: Organic, Conventional, Non-GMO, All-Natural Distribution Channel: Online Retail, Supermarkets, Health Stores, Distributors |
| Companies Covered | Givaudan, Indena, Martin Bauer Group, Döhler, Kalsec, Synthite Industries, Vidya Herbs, Sabinsa, Bio Botanica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peach Extract Market Evolving Landscape
Extraction technology maturation and regulatory transparency mandates are converging to reshape how peach-derived compounds move from agricultural sourcing to finished formulation.
Supercritical CO2 extraction systems are decentralizing production geography by enabling smaller-scale facilities to achieve pharmaceutical-grade purity without the capital intensity of legacy solvent-recovery infrastructure. Mid-size European flavor houses in Portugal and Greece are deploying modular 50-liter units to process regional peach varieties previously uneconomical for export. This distributed processing model is compressing supply chain distances between extraction and formulation, reducing thermal degradation risks in transit.
EFSA's evolving botanical health claim restrictions are forcing extract suppliers to restructure substantiation dossiers, eliminating implied antioxidant benefits from consumer-facing packaging. The industrial consequence is a pivot toward B2B technical marketing that emphasizes flavor performance metrics rather than wellness positioning. German and Dutch beverage manufacturers are responding by demanding batch-specific volatile compound certificates of analysis to verify sensory consistency.
Formulation R&D procurement is consolidating vendor relationships, with multinational food manufacturers reducing qualified supplier pools from twelve to four in favor of integrated botanical portfolios. Long-term offtake agreements with volume commitments are displacing spot purchasing for peach extract, mirroring contract structures already standard in vanilla and citrus markets. This concentration is most visible in Scandinavian markets, where three dairy conglomerates now account for the majority of Nordic peach flavoring procurement.
Peach Extract Market Segmentation
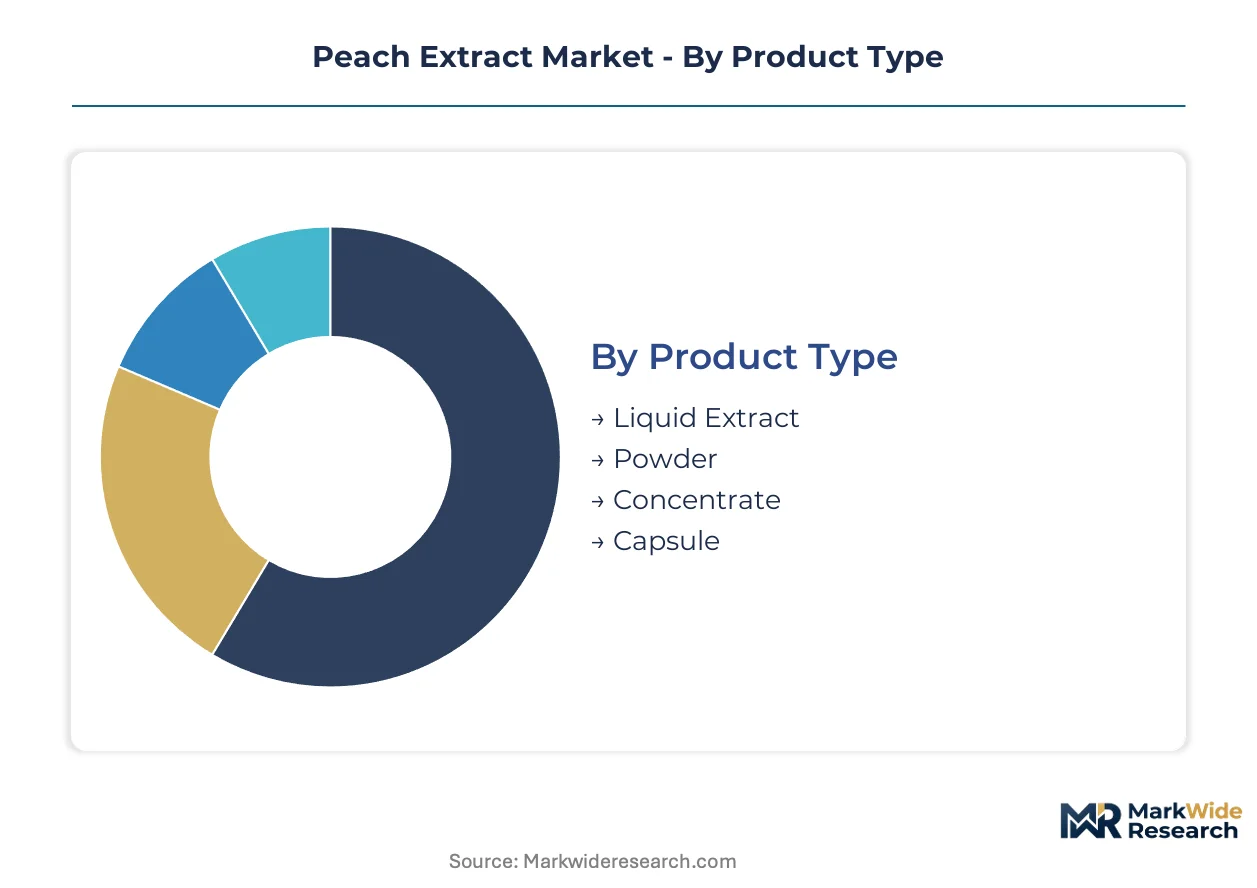
Peach extract procurement patterns diverge sharply between commodity-scale beverage manufacturers and premium formulation houses. Segment boundaries reflect extraction technology capabilities, certification premiums, and channel access rather than simple product morphology.
Product Type:
Liquid formats dominate tonnage while powder commands margin premiums in functional applications.
- Liquid Extract:Aqueous ethanol or cold-pressed suspensions with 15-25% soluble solids content, standardized for beverage dosing consistency. German ready-to-drink producers specify liquid formats for seamless syrup incorporation, though thermal degradation during transit constrains sourcing radius.
- Powder:Spray-dried or freeze-dried matrices with maltodextrin carriers, enabling precise nutraceutical dosing and extended shelf stability. Polish supplement manufacturers are shifting procurement toward powder as clean-label dry-mix applications expand.
- Concentrate:High-Brix reductions from peach puree processing, primarily captive-produced by juice conglomerates for internal flavor standardization.
- Capsule:Encapsulated oil or dried extract for direct-to-consumer supplement positioning, limited by EFSA botanical health claim restrictions on antioxidant messaging.
Mature deployment sits with liquid extract in beverage manufacturing. Newer deployment is concentrated in powder formats for nutraceutical compounding.
Application:
End-use economics separate flavor-driven procurement from bioactive extraction value chains.
- Food & Beverages:Natural flavoring and coloring in soft drinks, dairy, and confectionery, with REACH-compliant solvent residues now mandatory for EU retail access. French premium beverage brands specify supercritical CO2 extracts for volatile ester preservation.
- Cosmetics:Antioxidant and fragrance applications in skincare formulations, particularly peach kernel oil derivatives for emollient properties.
- Pharmaceuticals:Standardized phenolic extracts for API adjuvants, governed by EMA quality guidelines and USP monograph compliance.
- Nutraceuticals:Polyphenol concentrates for dietary supplements, climbing fastest as Romanian and Bulgarian manufacturers replace synthetic antioxidants with botanical alternatives.
Volume leadership resides in food and beverage procurement. Margin expansion concentrates in nutraceutical applications with certified organic chain-of-custody.
Formulation:
Certification tiering creates three distinct price bands with limited cross-tier substitution.
- Organic:Three-year conversion orchards with EU 2018/848 compliance, commanding 40-60% premiums over conventional. Sicilian and Calabrian supply concentration creates procurement vulnerability.
- Conventional:Standard agricultural inputs with MRL monitoring, serving cost-sensitive beverage and flavor house volume contracts.
- Non-GMO:Identity-preserved supply chains without organic certification, filling price gaps in mid-tier cosmetic applications.
- All-Natural:Clean-label positioning without formal certification, increasingly displaced by verified organic or Non-GMO Project standards.
Contracting velocity runs highest for organic formulations. Conventional supply maintains baseline volume coverage for price-sensitive accounts.
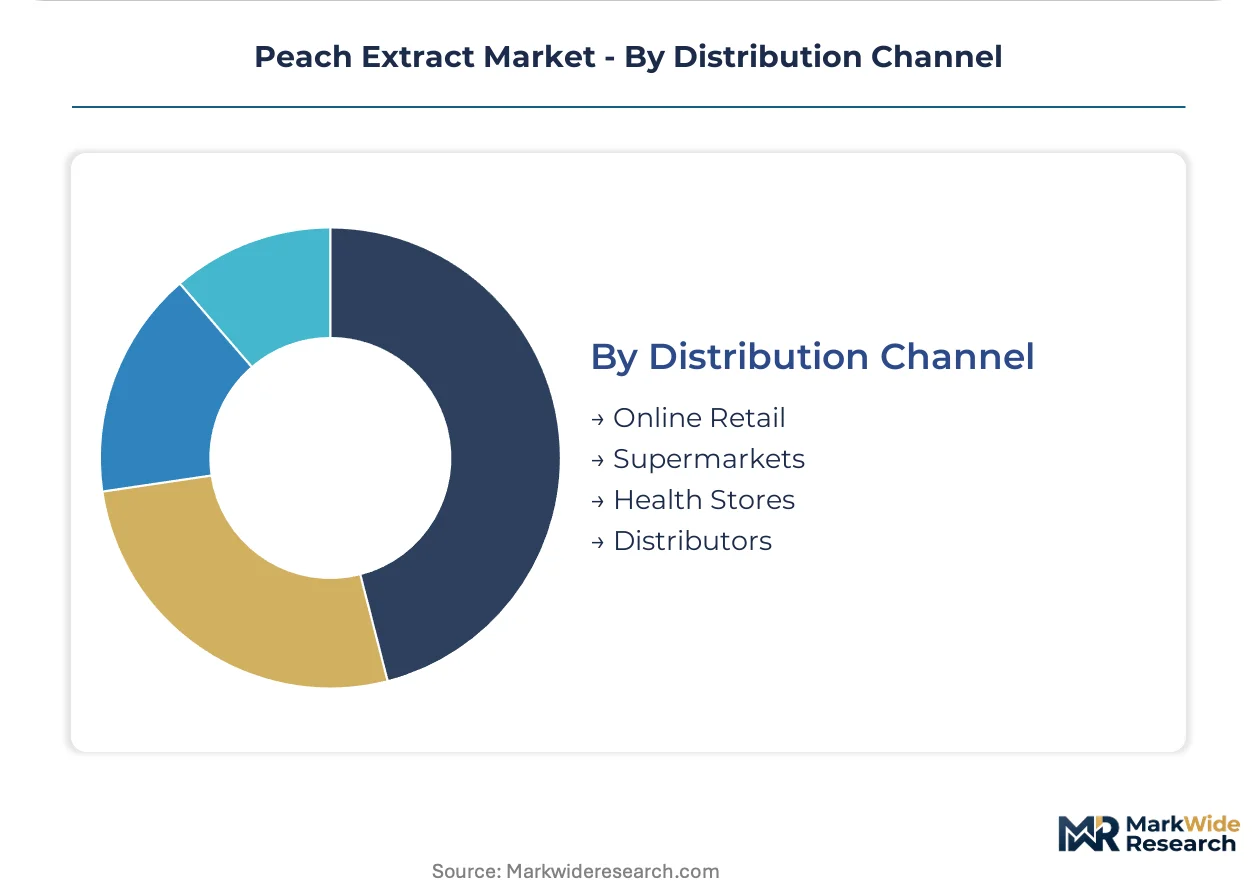
Distribution Channel:
Channel selection determines lot size flexibility and technical service intensity.
- Online Retail:Direct-to-manufacturer platforms collapsing traditional broker tiers, enabling mid-size extractors to access R&D labs with batch-specific COA documentation.
- Supermarkets:Indirect procurement for private-label supplement and beverage brands, requiring mass-market pricing and simplified SKUs.
- Health Stores:Specialty retail for premium organic extracts, with smaller lot sizes and higher per-unit margins.
- Distributors:Traditional three-tier structures still dominating pharmaceutical and cosmetic ingredient procurement, though consolidation is reducing qualified vendor pools.
Established volume flows through distributor networks. Emerging growth concentrates in online retail with integrated technical marketing support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement from German beverage manufacturers concentrates demand for REACH-compliant peach extracts, while Italian and Spanish agricultural clusters supply the raw material base. Regulatory divergence between EFSA novel food pathways and FDA GRAS determinations creates distinct commercialization timelines across Atlantic markets.
Germany
Premium ready-to-drink beverage brands in Bavaria and North Rhine-Westphalia specify supercritical CO2 extracts for volatile ester preservation. REACH solvent residue mandates now require sub-ppm documentation for hexane and acetone traces. The Rhine-Main industrial corridor hosts formulation R&D labs that source directly from Sicilian organic orchards.
Italy
Sicilian and Calabrian organic peach cultivation supplies over half of EU-certified raw material, creating geographic concentration risk from Mediterranean climate volatility. EU 2018/848 compliance timelines extend three-year conversion periods for conventional orchards. The Po Valley hosts extraction facilities that process regional varieties for French and German flavor houses.
United States
California Central Valley peach processing generates pomace feedstock for antioxidant concentrate production. FDA GRAS self-determination pathways accelerate commercialization versus EFSA equivalents, though state-level pesticide residue limits in California and Washington tighten sourcing requirements. Pacific Northwest beverage startups drive demand for organic-certified liquid extracts.
France
Paris-based flavor houses and Lyonnaise dairy conglomerates consolidate supplier relationships toward integrated botanical portfolios. ANSM cosmetic ingredient oversight intersects with REACH compliance for dual-use extracts. The Provence-Alpes-Côte d'Azur region sees emerging cultivation of heritage peach varieties for niche fragrance applications.
Poland
Warsaw and Kraków supplement manufacturers represent underpenetrated demand for phenolic-rich peach extracts as synthetic antioxidant replacements. National agricultural policy incentives support orchard modernization, though organic certification infrastructure remains less developed than Western European counterparts. Poznań-based distributors bridge supply from Italian processors to Eastern European nutraceutical compounders.
Peach Extract Market Competitive Landscape
Swiss and German producers anchor the premium formulation tier; Indian specialists hold cost-competitive extraction technology positions. The vendor base separates into three strategic groupings: integrated flavor houses with captive R&D pipelines, agricultural processors controlling upstream orchard partnerships, and technology-focused extractors deploying advanced solvent systems. Competitive moves concentrate on long-term offtake contracting and modular processing capacity deployment.
Within the integrated flavor house tier, Givaudan and Döhler exemplify archetypes combining formulation science with regulatory navigation capabilities. Among agricultural processors, Martin Bauer Group occupies a position emphasizing controlled sourcing relationships. Synthite Industries represents the technology-specialist vector, with its company name indicating Indian origin and extraction-method focus. These three anchors illustrate how competitive positioning stratifies across supply chain control points rather than product differentiation alone.
| Leading Market Players |
|---|
| Givaudan |
| Indena |
| Martin Bauer Group |
| Döhler |
| Kalsec |
| Synthite Industries |
| Vidya Herbs |
| Sabinsa |
| Bio Botanica |
| Others |
Value Network & Pricing Analysis
Supercritical CO2 extraction adoption simultaneously compresses per-unit processing costs and decentralizes production geography, fragmenting pricing power away from legacy solvent-based concentrators in Italy and Spain while elevating margin capture for technology-deploying mid-size facilities in Portugal and Greece.
Pricing Analysis
Volume leadership resides in conventional liquid extract contracts serving German beverage manufacturers, while margin expansion concentrates in certified organic powder formats for Polish and Romanian nutraceutical compounders. Price differentiation hinges on EU 2018/848 organic certification tier and supercritical CO2 processing verification. Cost compression in conventional tiers intensifies because Mediterranean frost cycles spike Spanish and Italian concentrate input costs. Mass-market beverage brands exhibit highest price sensitivity; premium French flavor houses and Scandinavian dairy conglomerates absorb certification premiums.
Supply Chain Analysis
Single-source vulnerability sits with Sicilian and Calabrian organic peach cultivation, which feeds over half of EU-certified raw material demand. Raw material supply draws from Spanish and Italian concentrate processors, German extraction equipment fabricators, and Indian technology specialists deploying modular CO2 systems. Tariff exposure looms for REACH-compliant extracts should EU-UK regulatory divergence harden border checks. Distribution runs through traditional three-tier pharmaceutical and cosmetic ingredient networks, though direct-to-manufacturer digital platforms are collapsing broker intermediation for mid-size extractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
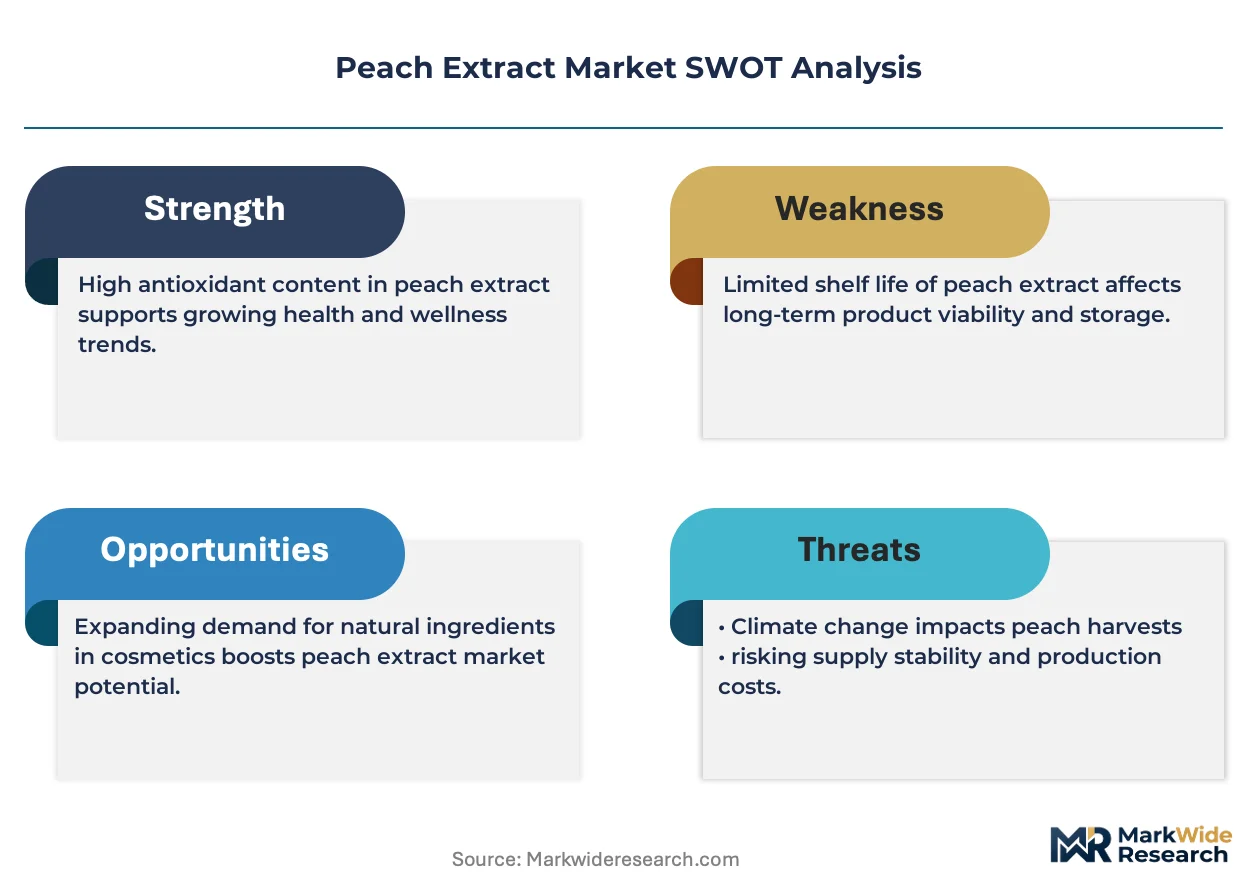
This market reads as supply-constrained, with three-year organic orchard conversion timelines propping pricing premiums regardless of spot demand fluctuations.
For Market Incumbents: To counter climate-driven raw material volatility in Mediterranean growing regions, secure backward integration into controlled orchard partnerships in Sicily and Calabria. Prioritize supercritical CO2 capacity additions in Portugal and Greece to capture decentralized processing premiums.
For New Entrants and Emerging Players: Enter via Polish and Romanian supplement manufacturing channels, where synthetic antioxidant replacement demand remains underpenetrated. Target certified organic powder formats for dry-mix nutraceutical applications, leveraging digital B2B platforms to bypass traditional distributor tiers.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of technology-specialist extractors with modular supercritical CO2 deployment capabilities. Long-term viability favors facilities combining REACH compliance infrastructure with circular processing grants for peach pomace valorization. Watch EFSA novel food assessment timelines as inflection indicators for delivery format commercialization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Partnerships | Sicilian and Calabrian cultivation control secures organic supply chain-of-custody for premium contracts. |
| Supercritical CO2 Capacity Expansion | Modular 50-liter unit deployment in Portugal and Greece enables pharmaceutical-grade purity without legacy solvent infrastructure. |
| EU Green Deal Circular Processing Grants | Pomace-to-antioxidant concentrate conversion unlocks subsidized waste valorization revenue streams. |
| Direct-to-Manufacturer Digital Platform Launch | B2B marketplace integration collapses three-tier distribution, granting mid-size extractors R&D lab access. |
| REACH Compliance Certification Investment | Sub-ppm solvent residue documentation qualifies suppliers for German and French premium beverage procurement. |
Research Methodology
Multi-period observation of extraction technology deployment rates, organic certification conversion timelines, and REACH compliance qualification patterns anchored the trend analysis, supplemented by interviews with supercritical CO2 equipment engineers, procurement leads at German beverage manufacturers, regulatory affairs specialists navigating EFSA novel food pathways, and Italian orchard cooperative managers. Secondary validation drew from ECHA substance safety dossiers, EU 2018/848 organic certification registries, and customs trade data for peach concentrate flows. Bottom-up facility capacity modeling triangulated against top-down end-use demand estimates across food, cosmetic, and pharmaceutical matrices.
Segment-weighting approaches applied differential growth assumptions across liquid extract, powder, concentrate, and capsule formats, with further stratification by organic, conventional, Non-GMO, and all-natural certification tiers. Application-level modeling separated flavor-driven procurement from bioactive extraction value chains, while distribution channel weights reflected collapsing broker intermediation against persistent pharmaceutical distributor dominance. CAGRs derived from regression analysis of historical input cost volatility and procurement premium trajectories, incorporating Mediterranean climate indices and regulatory assessment timeline distributions as exogenous variables.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA botanical health claim restriction tightening or California state-level pesticide residue limit escalation. Forecasts reflect documented assumptions regarding supercritical CO2 equipment cost curves and organic orchard conversion elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Spain Table Grape Market
Fruits and Vegetables
Global Dehydrated Onion Flakes Market
Fruits and Vegetables
Freeze Dried Bananas Market
Fruits and Vegetables
Pea Flakes Market
Fruits and Vegetables
Infused Dried Fruits Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
United States Blueberry Market
Fruits and Vegetables
Qatar Fruits and Vegetables Market
Fruits and Vegetables
Global Organic Fruits and Vegetables Market
Fruits and Vegetables
Dragon Fruit Powder Market
Fruits and Vegetables
Dried Blueberries Market
Fruits and Vegetables
Avocado Puree Market
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
Adzuki Beans Market
Fruits and Vegetables
Dehydrated Green Beans Market
Fruits and Vegetables
Bahrain Fruits and Vegetables Market