
 Dehydrated Green Beans Market | 2026-2036
Dehydrated Green Beans Market Size, Share, and Industry Trends Forecast 2026-2036
Dehydrated Green Beans Market Intelligence
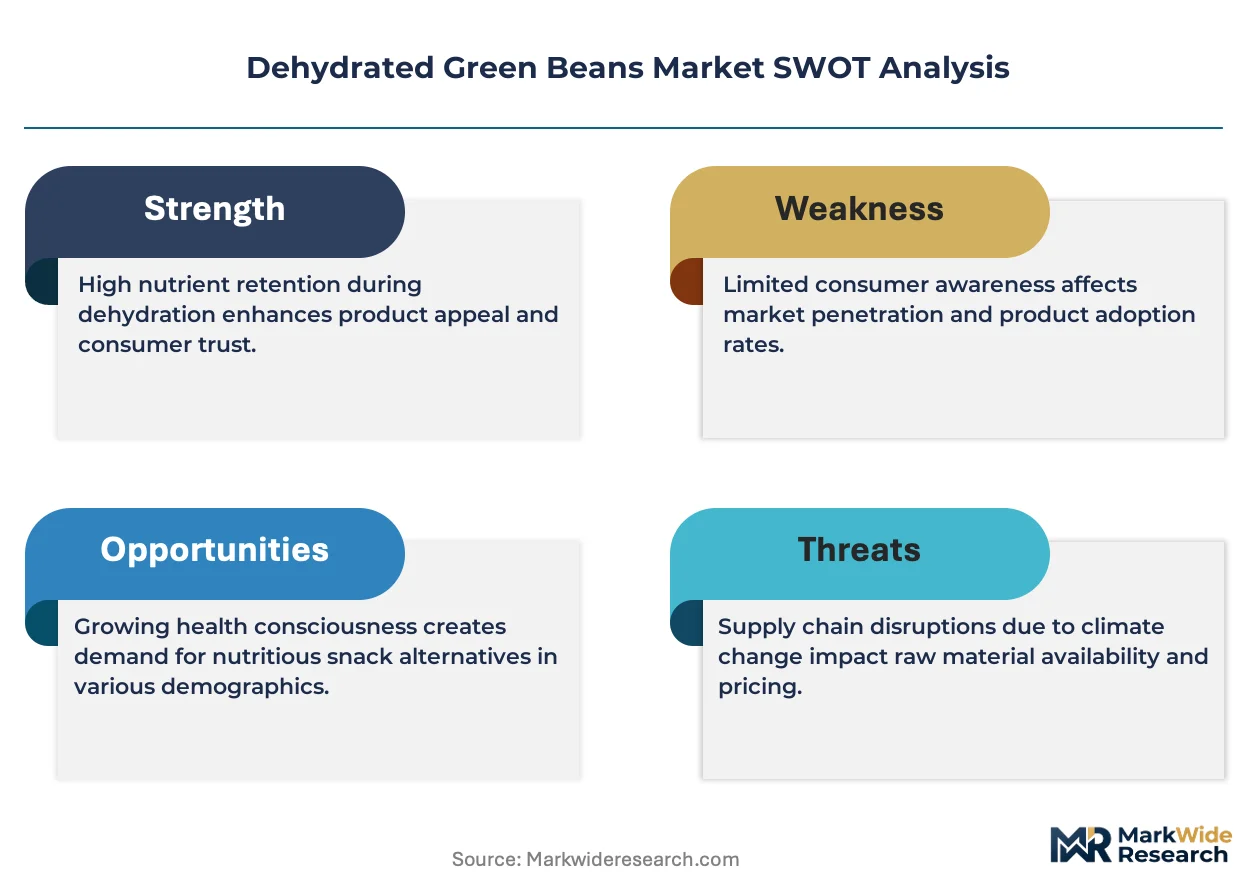
European dehydration facility capacity is hardening as energy costs and sustainability mandates reshape capital deployment decisions. Freeze-Dry Foods GmbH leverages its German engineering base to sustain premium lyophilized output for pharmaceutical-adjacent food applications. Van Drunen Farms anchors North American supply through its vertically controlled Illinois processing network. Harmony House Foods differentiates through direct-to-consumer retail packaging specialization.
Dehydrated green beans are fresh Phaseolus vulgaris pods subjected to controlled moisture reduction, typically achieving water activity below 0.6 for shelf-stable storage without refrigeration; hot-air drying dominates commercial scale, though freeze-drying preserves cellular structure and rehydration performance for premium segments. Powdered and minced formats lead volume in industrial channels where food manufacturers seek homogeneous dispersion in soups, stews, and ready meals. Sliced formats command margin pools in foodservice and retail cooking segments where visual identity matters. Vacuum packs and bulk bags concentrate procurement attention from food distributors managing just-in-line supply to restaurant chains.
FDA food facility registration and USDA organic certification govern US market access, while EFSA novel food assessments and EU Green Deal farm-to-fork targets shape European formulation choices. REACH chemical safety obligations and evolving CSRD sustainability disclosures are pressing dehydration operators to document supply chain water and energy intensity. Stakeholders must monitor how dual carbon goals in China and emerging carbon border adjustments in Europe redirect sourcing patterns for raw bean inputs and finished dehydrated products.
Market Dynamics
Energy cost volatility and EU F-Gas Regulation compliance deadlines are forcing dehydration facility operators to reconfigure capital deployment toward lower-carbon thermal systems. This structural pressure cascades through equipment procurement, raw bean contracting, and geographic sourcing decisions.
Growth Catalysts
- Clean-label ready-meal manufacturing:Food processors in Germany and the Netherlands are standardizing dehydrated vegetable inputs to meet retailer ESG sourcing mandates. Hot-air dried green beans integrate into standardized soup and stew bases without additive declarations.
- REACH chemical safety documentation:European dehydration operators completing full supply chain water and energy intensity disclosures under evolving CSRD sustainability rules are securing preferred supplier status with multinational food manufacturers.
- Illinois processing cluster expansion:Vertically controlled Midwestern US dehydration infrastructure is capturing North American institutional foodservice demand through captive raw bean supply and reduced transportation moisture loss.
Market Restraints
- Natural gas price exposure:Hot-air drying operations in Germany and the Netherlands face margin compression from contracted energy rates that reset quarterly against TTF benchmark volatility.
- Raw bean supply concentration:Phaseolus vulgaris procurement for European dehydration facilities concentrates in Polish and Romanian growing regions, creating weather-driven volume risk.
- Freeze-drying capex barriers:Lyophilization equipment for premium cellular-structure preservation requires 4-6x the capital intensity of conventional thermal systems, limiting capacity expansion to specialized pharmaceutical-adjacent applications.
Strategic Opportunities
- Carbon border adjustment preparation:EU importers sourcing dehydrated green beans from Chinese processing facilities can secure competitive positioning by documenting embedded emissions ahead of 2026 CBAM full implementation.
- Direct-to-consumer retail channel development:Specialty dehydrated vegetable packagers are building subscription revenue through camping and emergency-preparedness verticals, bypassing traditional foodservice distribution markups.
- Heat pump drying technology convergence:Integration of industrial heat pumps with solar thermal arrays is enabling fossil-free dehydration at commercial scale for operators with 7-10 year capital recovery horizons.
Industry Challenges
- USDA organic certification timeline compression:Three-year transition requirements for conventional bean acreage are mismatched with food manufacturer quarterly reformulation deadlines for clean-label product lines.
- Legacy ERP integration with blockchain traceability:Dehydration facilities implementing farm-to-fork tracking for EU Green Deal compliance are facing data architecture conflicts with established inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dehydrated Green Beans Market |
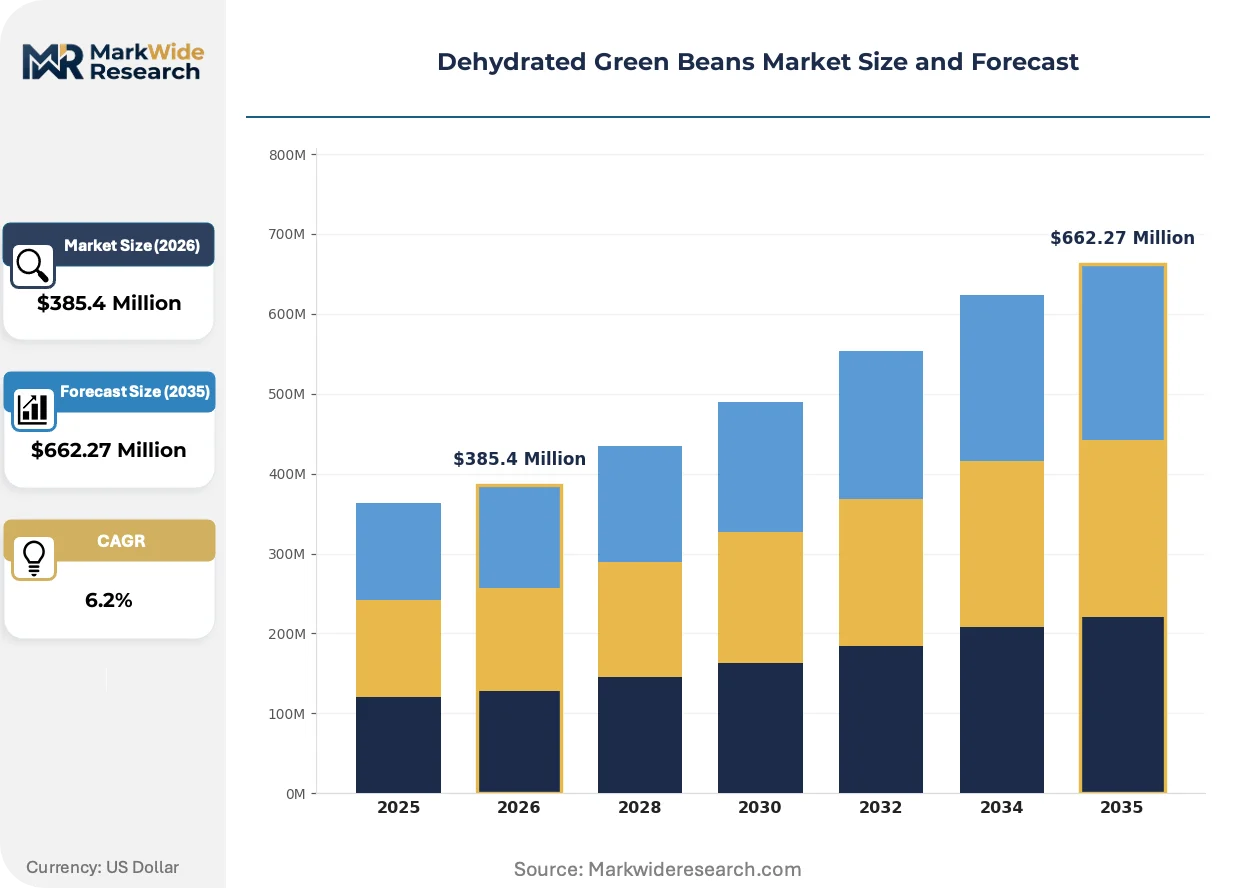
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole, Sliced, Powdered, Minced, Diced Packaging Type: Vacuum Packs, Cans, Sachets, Jars, Bulk Bags Application: Foodservice, Home Cooking, Ready Meals, Soups & Stews, Snacks End User: Food Manufacturers, Restaurants, Caterers, Retail Chains, Food Distributors |
| Companies Covered | Freeze-Dry Foods GmbH, Harmony House Foods, Van Drunen Farms, Garlico Industries Ltd, Silva International, BCFoods, Inc., F R Benson & Partners Ltd., Olam International, Mevive International Food Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dehydrated Green Beans Market Strategic Shifts & Innovations
Dehydration technology selection is bifurcating between efficiency-optimized thermal systems and structure-preserving lyophilization, with regulatory emissions tracking now embedded in equipment procurement criteria.
Closed-loop heat pump dryers are automating moisture extraction sequences while slashing natural gas consumption by 60-70% compared to conventional direct-fired systems. German engineering firms are installing these units at Hamburg-area facilities to meet F-Gas Regulation phase-down schedules. The technology is automating compliance documentation for CSRD energy intensity disclosures while compressing payback periods through combined heat and power integration.
EU Green Deal farm-to-fork targets are mandating 25% pesticide reduction and 50% nutrient loss limitation across vegetable supply chains by 2030. Dehydration operators must now validate raw bean provenance through digital traceability platforms to retain retail channel access. Sliced format producers serving foodservice visual-identity requirements face the steepest reformulation pressure, as whole-pod appearance standards conflict with imperfect-grade sourcing incentives.
Food manufacturers are consolidating dehydrated vegetable procurement through sole-source contracts with vertically integrated processors. Ready-meal producers in the Netherlands are replacing spot-market purchasing with 3-5 year volume commitments to Illinois and German dehydration facilities. This concentration is most visible in industrial soup and stew channels, where homogeneous dispersion specifications eliminate multi-supplier qualification costs.
Dehydrated Green Beans Market Segmentation
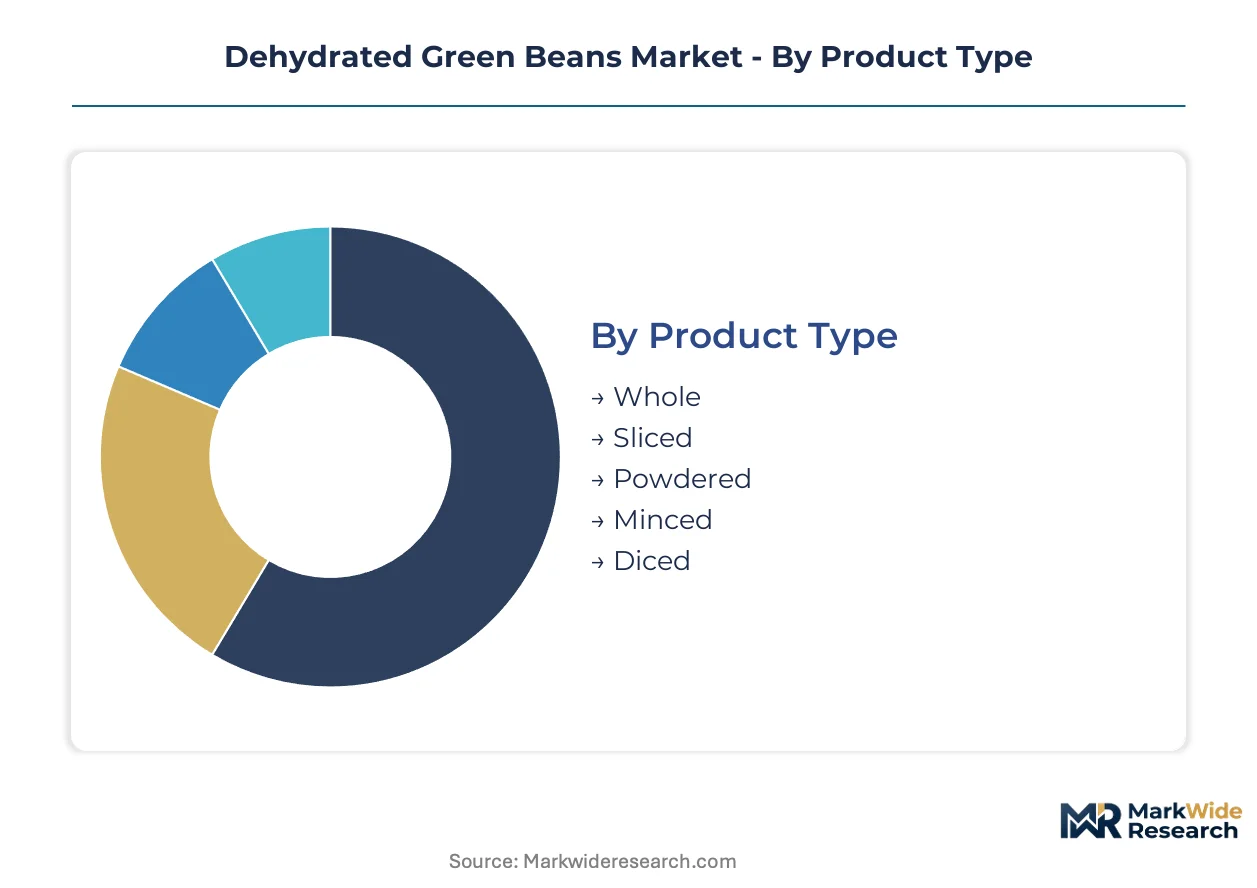
Dehydrated green bean segmentation reflects divergent processing economics and channel requirements. Format selection determines energy intensity, equipment depreciation, and moisture specification tolerances. Packaging and application choices separate commodity industrial supply from branded retail positioning.
Product Type:
Supply concentration in industrial dehydration favors formats that maximize throughput per thermal cycle and minimize handling damage during transport.
- Powdered:Fine particle reduction below 500 microns enables homogeneous dispersion in dry soup bases and seasoning blends. German ready-meal manufacturers specify this format for clean-label product lines requiring no additive declarations. Demand concentrates in Hamburg-area processing clusters serving EFSA-compliant formulations.
- Minced:Irregular 2-5mm fragments balance rehydration speed with structural integrity in extended-simmer applications. Illinois dehydration facilities supply North American institutional foodservice through captive raw bean networks. This format captures the steepest expansion trajectory as quick-service chains standardize vegetable inclusion in grain bowls.
- Sliced:Cross-sectional cuts preserve visual pod identity for foodservice plating requirements. Polish and Romanian raw bean supply feeds European processors.
- Whole:Intact pod dehydration demands extended drying cycles and premium grade sourcing. Limited to specialty retail and gift channels.
- Diced:Uniform 5-10mm cubes suit industrial portion control in frozen meal applications. Chinese processing facilities dominate export volume.
Today's leader: Powdered. Tomorrow's challenger: Minced.
Packaging Type:
Packaging selection tracks moisture sensitivity requirements and customer procurement scale, with vacuum technology commanding premium positioning.
- Vacuum Packs:Oxygen exclusion below 1% extends shelf stability to 24+ months without preservative additives. Dutch restaurant chains specify this format for just-in-line inventory management. Premium positioning aligns with ESG sourcing mandates from German retailers.
- Bulk Bags:10-25kg polywoven containers minimize unit cost for food manufacturers with high-throughput processing lines. Van Drunen Farms anchors North American supply through Illinois-based captive distribution. Volume concentration is accelerating as sole-source contracts replace spot purchasing.
- Cans:Metal containment suits humid climate distribution in Asian and Latin American markets. Regional canning infrastructure determines competitive access.
- Sachets:Single-serve portions target camping and emergency-preparedment verticals with direct-to-consumer subscription models.
- Jars:Transparent presentation supports retail visual inspection requirements in specialty grocery channels.
Volume concentrates in Bulk Bags. Margin migrates toward Vacuum Packs.
Application:
Application segmentation reveals divergent specification tolerances between visual-identity and homogeneous-dispersion requirements.
- Ready Meals:Standardized inclusion rates and rehydration protocols enable automated production line integration. Netherlands-based manufacturers are consolidating procurement through 3-5 year volume commitments to German dehydration facilities. This segment is expanding most quickly as European retailers enforce clean-label standards.
- Soups & Stews:Extended simmer compatibility favors minced and powdered formats with rapid moisture absorption. Illinois processing clusters serve North American institutional demand through reduced transportation moisture loss.
- Foodservice:Plating aesthetics require sliced and whole formats with intact cellular structure. Polish raw bean supply quality determines European processor access.
- Home Cooking:Convenience positioning drives sachet and jar packaging specialization. Direct-to-consumer channels bypass traditional distribution markups.
- Snacks:Crisp texture requirements favor low-moisture specification below 5% water activity. Limited to premium lyophilization output.
Procurement consolidates in Ready Meals. Innovation concentrates in Snacks.
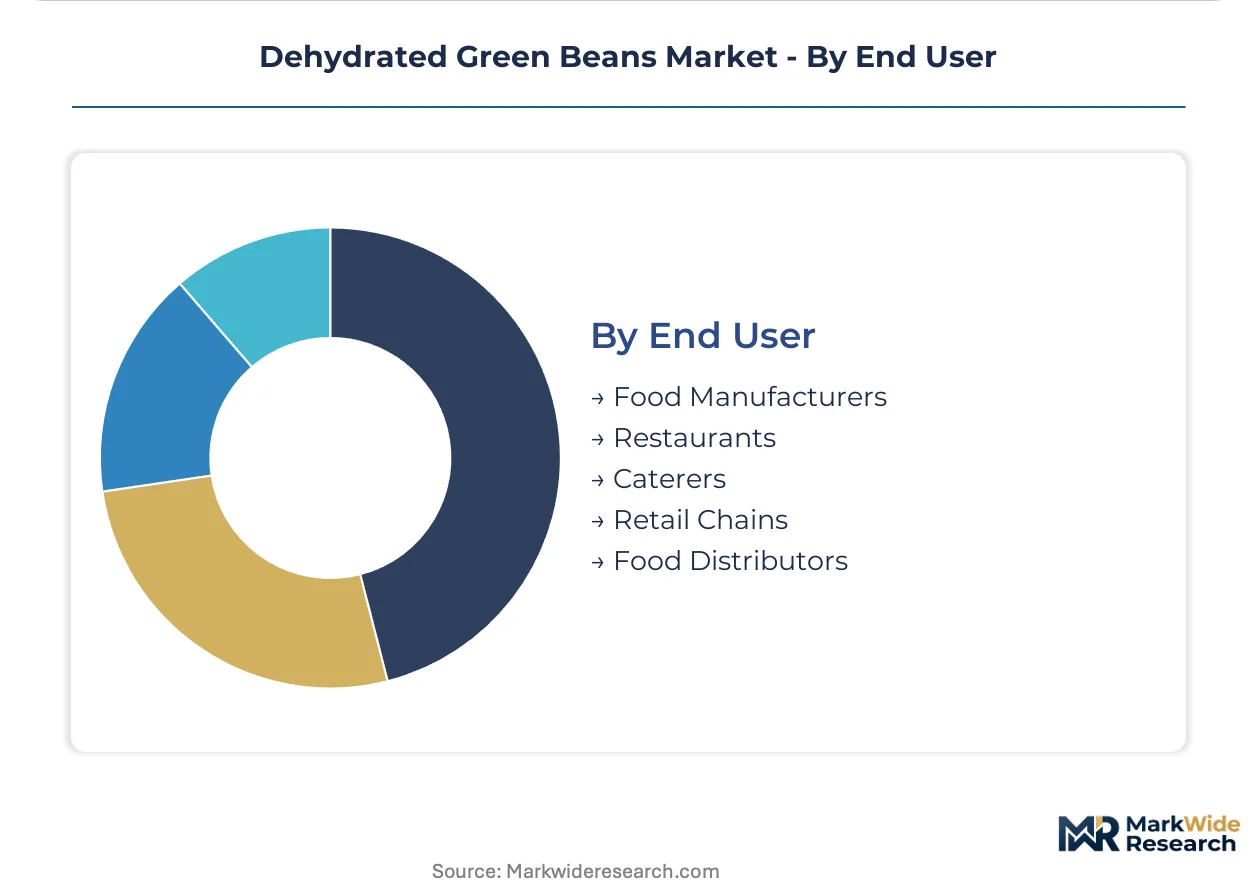
End User:
End user structure separates specification-heavy manufacturing demand from price-sensitive foodservice procurement.
- Food Manufacturers:Technical documentation requirements for FDA facility registration and USDA organic certification govern supplier qualification. German operators completing CSRD energy intensity disclosures secure preferred status with multinational accounts.
- Food Distributors:Inventory breadth and logistics integration determine competitive positioning. Hamburg-area clusters serve pan-European retail consolidation.
- Restaurants:Just-in-line delivery schedules favor regional dehydration proximity. Illinois and German facilities capture respective continental demand.
- Retail Chains:Private-label development requires traceability documentation for EU Green Deal compliance. Blockchain integration faces legacy ERP conflicts.
- Caterers:Event-volume volatility favors flexible procurement terms and reconstitution speed specifications.
Contracting power concentrates in Food Manufacturers. Margin pressure accumulates in Caterers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium lyophilization capacity while the United States anchors North American supply through vertically controlled Midwestern processing clusters. China dominates export-oriented thermal dehydration at scale. France and the Netherlands concentrate ready-meal manufacturing demand that shapes procurement patterns.
Germany
Ready-meal manufacturers in Hamburg and Frankfurt drive specification-heavy demand for EFSA-compliant clean-label inputs. The F-Gas Regulation and CSRD sustainability disclosure mandates force facility operators toward heat pump drying systems. Bavarian engineering firms supply closed-loop thermal equipment to processing clusters around Hamburg.
United States
Institutional foodservice chains and quick-service restaurants standardize dehydrated vegetable inclusions in grain bowls and soup bases. FDA facility registration and USDA organic certification govern supplier qualification timelines. Illinois-based processing infrastructure captures Midwestern raw bean supply with reduced transportation moisture loss.
China
Export-oriented thermal dehydration facilities serve global food manufacturers seeking cost-optimized powdered and diced formats. Dual carbon goals and emerging carbon border adjustment mechanisms pressure documentation of embedded emissions. Shandong and Jiangsu provinces concentrate processing capacity for international shipment.
France
Retail chains enforce EU Green Deal farm-to-fork compliance through blockchain traceability requirements for private-label development. EFSA novel food assessments shape formulation choices for innovative product lines. The Île-de-France region hosts procurement decision-making for pan-European retail consolidation.
Netherlands
Food manufacturers standardize 3-5 year volume commitments to German dehydration facilities, replacing spot-market purchasing. REACH chemical safety documentation and evolving CSRD rules determine preferred supplier status. Rotterdam-area logistics integration supports just-in-line inventory management for restaurant chains.
Dehydrated Green Beans Market Key Industry Players
German producers anchor the premium lyophilization tier; North American specialists hold the vertically integrated commodity supply position. The vendor base splits between engineering-driven European precision and scale-oriented North American captive supply. Three archetypes dominate: freeze-drying technology licensors, vertically integrated agricultural processors, and direct-to-consumer retail packagers. Capacity expansion and sole-source contracting represent the dominant competitive moves as procurement consolidates around documented sustainability credentials.
Within the premium lyophilization tier, Freeze-Dry Foods GmbH exemplifies German engineering-based positioning for pharmaceutical-adjacent food applications. Van Drunen Farms occupies the North American vertically integrated archetype through Illinois-based captive processing infrastructure. Harmony House Foods represents the direct-to-consumer retail specialization archetype with subscription-channel development in camping and emergency-preparedness verticals.
| Leading Market Players |
|---|
| Freeze-Dry Foods GmbH |
| Harmony House Foods |
| Van Drunen Farms |
| Garlico Industries Ltd |
| Silva International |
| BCFoods, Inc. |
| F R Benson & Partners Ltd. |
| Olam International |
| Mevive International Food Ingredients |
| Others |
Cost & Logistics Intelligence
EU Green Deal farm-to-fork compliance requirements gate qualified supply access and premium-tier pricing power, as dehydration facilities lacking blockchain-validated provenance documentation face exclusion from German and Dutch retail procurement channels while CSRD-compliant operators command 15-20% price premiums.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity-grade powdered and diced formats, pressuring European thermal dehydration margins. Three-tier pricing structure across lyophilized premium, CSRD-compliant standard, and conventional economy levels segments buyer access, with food manufacturers least sensitive to price and foodservice distributors most responsive to delivered-cost differentials. Cost compression in hot-air dried segments is intensifying because Shandong processing facilities undercut EU energy-adjusted production costs.
Supply Chain Analysis
USDA organic certification and EFSA facility registration gate supplier qualification timelines, filtering raw bean procurement through documented growing regions. Phaseolus vulgaris supply draws from Poland, Romania, and Illinois growing belts, with natural gas pricing and F-Gas Regulation compliance costs determining regional competitiveness. Single-source vulnerability concentrates in Chinese thermal dehydration capacity serving export markets. Distribution runs through Hamburg-area clusters for European retail consolidation and Illinois-based captive networks for North American institutional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU regulatory compliance costs and Chinese scale economics, with the carbon border adjustment mechanism widening the effective cost differential for documented low-emission supply.
For Market Incumbents: Lock in sole-source contracts with ready-meal manufacturers before 2026 CBAM full implementation consolidates procurement around documented-emissions suppliers. Invest in heat pump drying retrofit at Hamburg-area facilities to defend margin position against Polish and Romanian entrants facing equivalent energy cost pressure. Prioritize backward integration into Illinois raw bean acreage to secure captive supply for North American institutional demand.
For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer white-space access in camping and emergency-preparedness verticals, bypassing established foodservice distribution markups. Target foodservice sliced-format supply gaps where Polish raw bean quality inconsistencies create qualification openings for new entrants with verified provenance systems. Deploy blockchain-integrated traceability as the primary go-to-market differentiator for EU retail chain private-label development.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap dehydration specialists with CSRD-compliant documentation because sustainability disclosure mandates are consolidating procurement around qualified supplier pools. Focus acquisition screening on Illinois and German facilities with captive raw bean networks and heat pump drying infrastructure already deployed. Watch carbon border adjustment implementation timing as the inflection signal for Chinese supply displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Drying Retrofit | F-Gas Regulation compliance secures German facility operating permits against phase-down deadlines. |
| Blockchain Traceability Integration | Farm-to-fork documentation satisfies EU Green Deal pesticide reduction verification requirements. |
| Backward Integration into Raw Bean Supply | Captive Illinois acreage reduces transportation moisture loss for North American institutional channels. |
| Direct-to-Consumer Channel Launch | Subscription revenue in camping verticals bypasses traditional foodservice distribution markups. |
| CSRD Energy Intensity Disclosure Completion | Full supply chain documentation secures preferred supplier status with multinational food manufacturers. |
Research Approach
Multiple input streams — dehydration facility engineering specifications, raw bean procurement contract structures, and regulatory filing documentation — were reconciled through structured primary interviews with plant operations managers, food manufacturer procurement leads, and EFSA regulatory affairs specialists, validated against secondary sources including EU customs trade data, CSRD sustainability disclosure filings, and USDA organic certification records, with bottom-up capacity modeling and top-down demand estimation triangulated for convergence.
Data-stream reconciliation applied across the projection horizon modeled segmentation by dehydration technology type, format specification, packaging configuration, and end-use application, with CAGRs derived from equipment deployment pipelines and raw bean acreage expansion trajectories, incorporating F-Gas Regulation phase-down schedules and carbon border adjustment implementation timing as scenario-dependent forecast modifiers.
The model assumes a particular technology adoption path; alternative pathways for heat pump drying penetration would alter the outlook for German facility competitiveness and associated premium-tier pricing power. Forecasts reflect documented assumptions regarding energy cost trajectories and regulatory enforcement intensity. A model refresh is warranted upon material change in EU carbon border adjustment scope or Chinese dual carbon policy implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Jalapeno Pepper Market
Fruits and Vegetables
Celery Juice Market
Fruits and Vegetables
Basil Leaves Market
Fruits and Vegetables
United States Guacamole Market
Fruits and Vegetables
Global Papaya Puree Market
Fruits and Vegetables
Tropical Fruit Puree Market
Fruits and Vegetables
Middle East and Africa Sweet Potatoes Market
Fruits and Vegetables
Pineapple Market
Fruits and Vegetables
North America Fruits & Vegetables Market
Fruits and Vegetables
Olive Market
Fruits and Vegetables
Fruit Puree Market
Fruits and Vegetables
Adzuki Beans Market
Fruits and Vegetables
Europe Blueberry Market
Fruits and Vegetables
Guanabana Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Banana Puree Market