
 Vaccinium Myrtillus Market | 2026-2036
Vaccinium Myrtillus Market Size, Share, and Industry Trends Forecast 2026-2036
Vaccinium Myrtillus Market Analytics
Pharmaceutical end-use is rebalancing toward nutraceuticals as eye-health and vascular-support formulations drive bilberry extract procurement. Naturex S.A. anchors European supply through specialized wild-harvesting partnerships in Nordic zones. Eevia Health Oy leverages its Finnish Arctic location to control upstream berry sourcing. BASF SE competes on synthetic-to-natural pigment substitution, positioning its phytochemical portfolio against botanical rivals.
Vaccinium myrtillus denotes a low-growing Ericaceous shrub yielding dark blue berries with 15-20% anthocyanin content by dry weight; processors macerate and concentrate these polyphenols for standardized extract production. Extracts command the largest value share among product types due to pharmaceutical-grade purity requirements and dosage standardization. The dried form segment sustains premium positioning in herbal medicine channels where shelf stability and traditional preparation methods retain buyer loyalty. Nutraceuticals leads end-user demand as supplement brands reformulate with EU-permitted health claims.
EFSA evaluates substantiation for bilberry eye-health claims under the Nutrition and Health Claims Regulation, while REACH governs solvent residues in extraction processes. The EU Organic Regulation shapes competitive access through certification mandates for wild-harvested Nordic material. Stakeholders must monitor EFSA claim-authorization timelines and Nordic organic harvest yields to secure long-term supply positions.
Market Dynamics
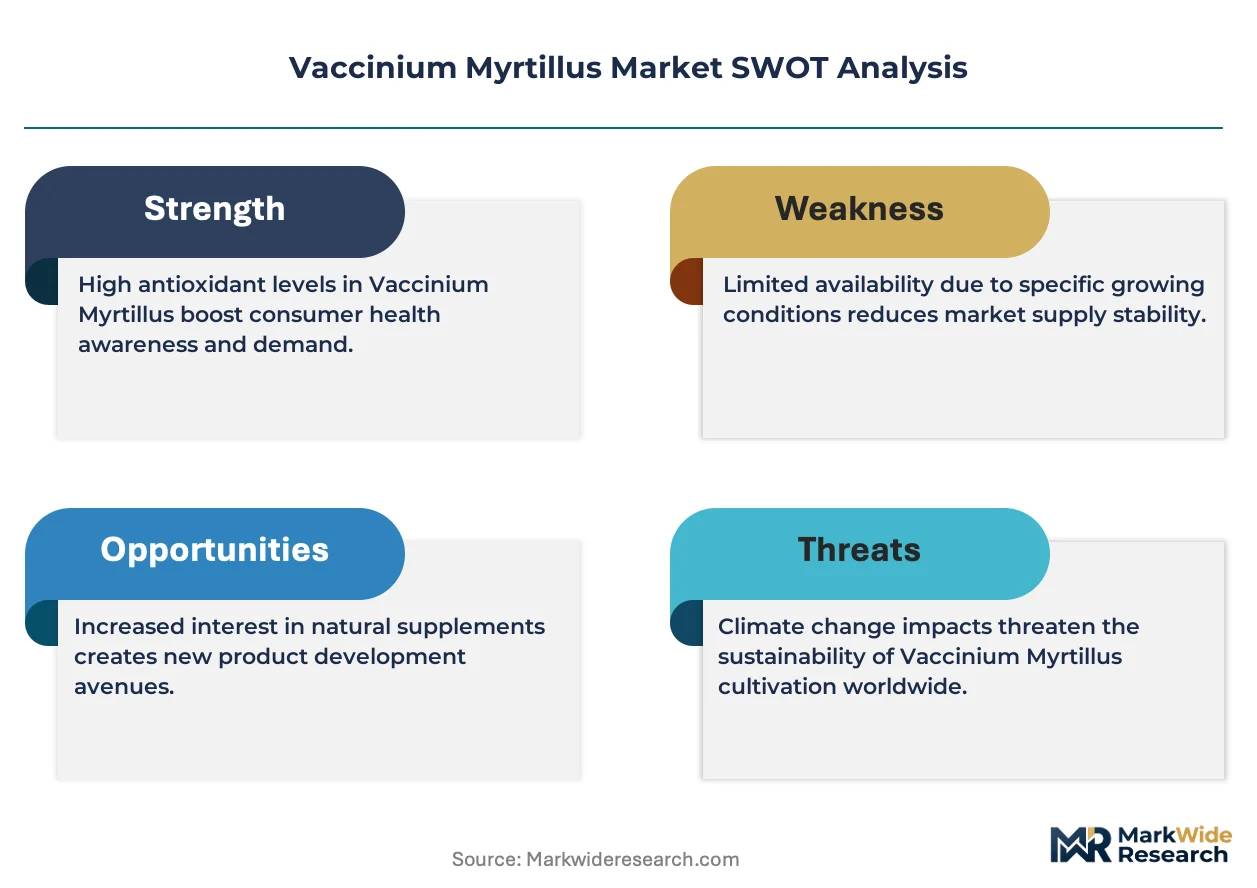
Nordic wild-harvesting zones are consolidating upstream control as organic certification mandates from the EU Organic Regulation concentrate supply among Finnish and Swedish operators with certified collection permits.
Growth Catalysts
- EFSA health-claims authorization:Substantiated eye-health claims under EU Nutrition and Health Claims Regulation enable supplement brands to market bilberry extracts with verified efficacy language.
- Nutraceutical formulation demand:German and French manufacturers are accelerating procurement of anthocyanin extracts for vascular-support and vision-health product lines.
- Finnish Arctic sourcing:Concentrated wild-harvesting partnerships in Lapland provide processors with traceable organic raw material meeting pharmaceutical-grade purity thresholds.
Market Restraints
- Wild-harvest yield volatility:Nordic berry crop fluctuations from weather pattern shifts create raw material scarcity for processors dependent on non-cultivated Vaccinium myrtillus.
- REACH solvent residue limits:Extraction operators face compliance costs and technical reformulation requirements to meet ECHA-mandated purity thresholds for ethanolic concentrates.
- Synthetic pigment substitution:BASF's phytochemical portfolio competes on price and color stability against botanical anthocyanins in food and beverage applications.
Strategic Opportunities
- Underpenetrated German pharmacy channel:Direct-to-pharmacist distribution of standardized extracts remains fragmented compared to concentrated nutraceutical supply chains in France.
- EU Green Deal bioeconomy incentives:Circular processing subsidies for berry waste valorization create margin expansion for operators investing in polyphenol recovery systems.
- Convergence of HPLC fingerprinting and blockchain:Integrated authentication platforms enable real-time provenance verification from Finnish harvest sites to finished supplement batches.
Industry Challenges
- Certification timeline compression:EU Organic Regulation wild-harvest audits require 18-24 month authorization cycles that delay new Nordic collection zone commercialization.
- Anthocyanin stability expertise gap:Formulation chemists with specialized knowledge of pH-dependent pigment degradation in extract storage command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaccinium Myrtillus Market |
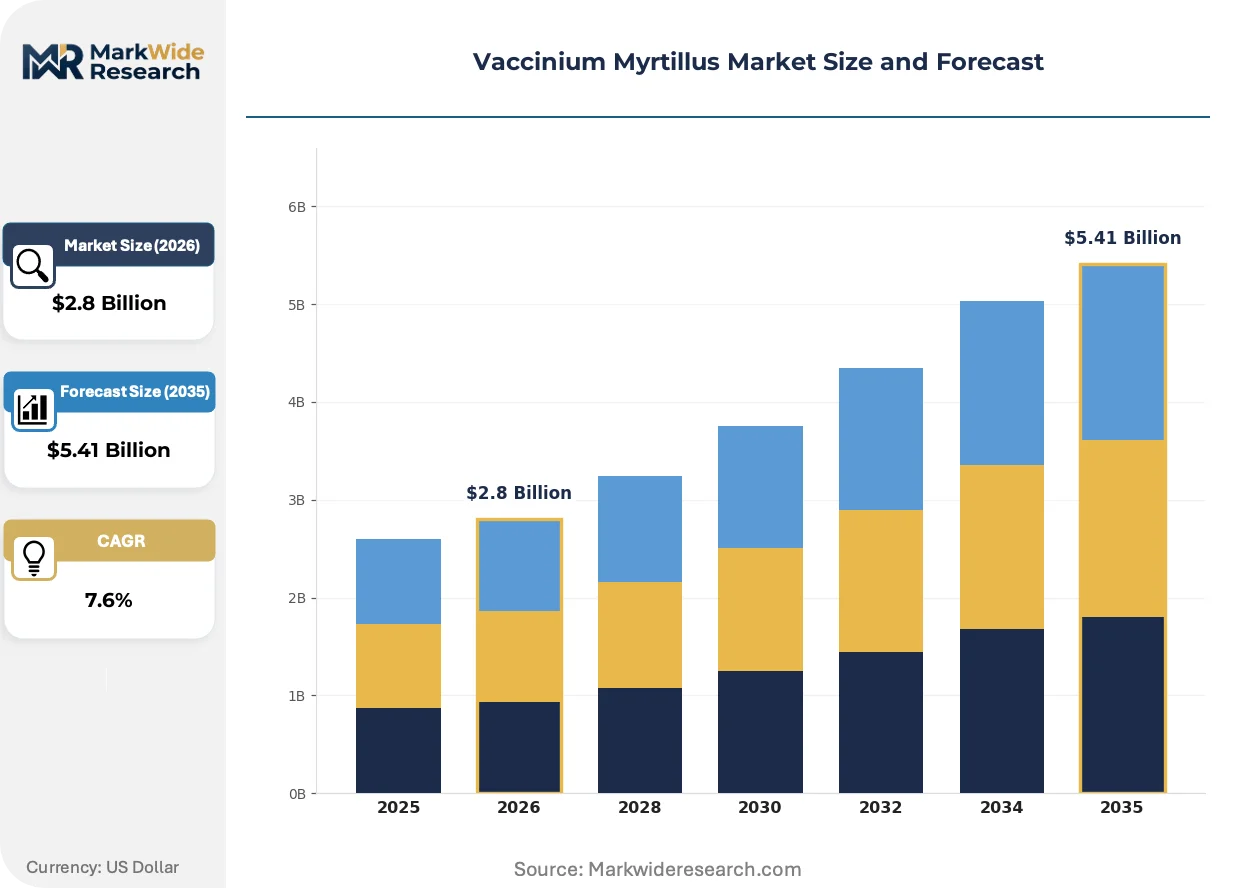
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracts, Powders, Capsules, Juices Form: Dried, Fresh, Frozen, Liquid End User: Food Industry, Pharmaceuticals, Cosmetics, Nutraceuticals Distribution Channel: Online, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | BASF SE, Naturex S.A., Eevia Health Oy, Swanson Health Products, Bio-Botanica, Indena, Herbalife Nutrition Ltd., ETchem, NOW Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaccinium Myrtillus Market Evolving Landscape
Extraction technology and authentication protocols are reshaping how bilberry-derived polyphenols move from Nordic harvest sites to finished dosage forms.
Supercritical CO2 extraction is decentralizing production economics for mid-scale processors. Equipment manufacturers in Germany and Italy are deploying modular systems that slash solvent handling costs. Regional cooperatives in Finnish Lapland now operate captive extraction units, compressing reliance on centralized toll processing facilities.
REACH enforcement on residual solvents is tightening compliance windows for ethanolic extraction operators. ECHA inspection protocols now mandate quarterly residue testing for facilities supplying pharmaceutical-grade material. French and German extract houses are responding by retrofitting molecular distillation capabilities to eliminate methanol traces.
Direct-procurement contracts between supplement brands and Finnish harvesting cooperatives are displacing traditional trader intermediaries. German nutraceutical formulators now negotiate three-year offtake agreements specifying organic certification tiers and anthocyanin concentration floors. This channel restructuring concentrates volume with vertically integrated Nordic suppliers holding EU Organic and FSSC 22000 credentials.
Vaccinium Myrtillus Market Segmentation
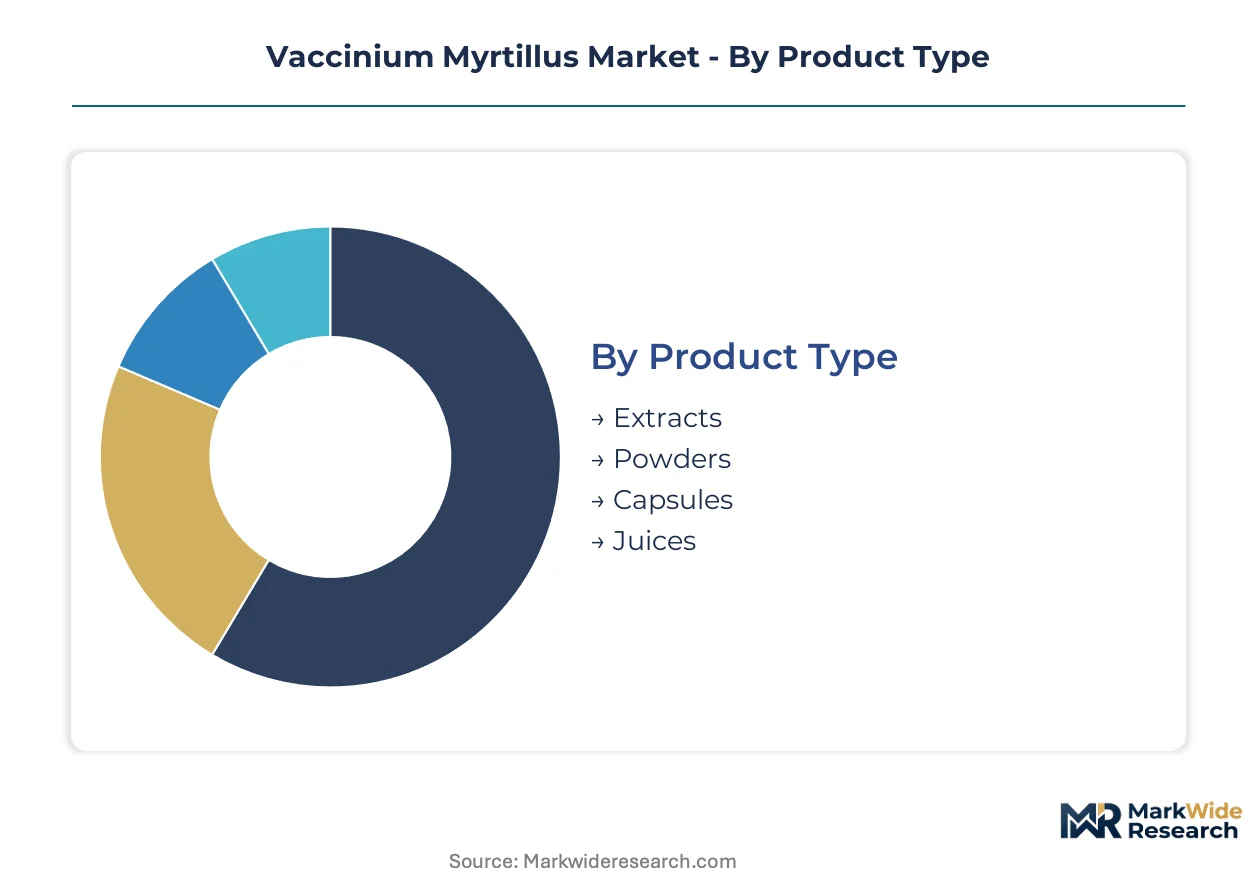
Vaccinium myrtillus procurement patterns diverge sharply across product formats, with pharmaceutical-grade extracts commanding premium positioning while bulk dried material serves traditional herbal channels. Segmentation reveals how Nordic wild-harvesting constraints reshape competitive access by form factor and purity tier.
Product Type:
Supply concentration in Finnish Lapland and Swedish Norrland directly shapes which product categories processors prioritize for anthocyanin recovery and standardization.
- Extracts:Standardized anthocyanin concentrates at 15-25% purity by HPLC analysis dominate pharmaceutical procurement from German and French formulators. EFSA health-claims substantiation requirements drive demand for batch-traceable extracts with documented polyphenol fingerprinting.
- Powders:Spray-dried berry pulp with retained fiber content serves functional food manufacturers seeking natural colorants with moderate antioxidant activity. Demand concentrates in Nordic domestic markets where organic certification commands shelf-space premiums.
- Capsules:Encapsulated dried berry powder offers dosage convenience for direct-to-consumer supplement channels. German pharmacy distribution networks favor blister-packed formats with EU Organic Regulation compliance seals.
- Juices:Single-strength and concentrated beverage bases retain volatile aromatic compounds lost in dried processing. Finnish and Swedish foodservice operators source NFC juices for premium smoothie formulations.
Extracts absorb the bulk of installed capacity; Capsules is expanding most quickly as German and French supplement brands accelerate direct-to-consumer launches.
Form:
Cost tier stratification separates pharmaceutical-grade material from commodity bulk, with organic certification premiums widening spreads between dried and fresh-frozen categories.
- Dried:Low-moisture whole berries and sliced material sustain traditional herbal medicine preparation methods. Shelf stability enables long-dated inventory positions for traders serving Asian traditional medicine channels.
- Fresh:Rapidly perishable whole berries with intact cuticle structure support premium cosmetic extraction where enzymatic activity preservation matters. Finnish harvesting cooperatives limit fresh allocations to pre-contracted cosmetic houses.
- Frozen:IQF-processed berries at -18°C lock anthocyanin content for year-round industrial processing. French nutraceutical extractors prefer frozen raw material for controlled thaw-batch processing.
- Liquid:Aqueous suspensions and glycerinated preparations serve liquid dietary supplement formulations. German pharmacy channel demand concentrates in alcohol-free pediatric and geriatric SKUs.
Frozen commands the steepest expansion trajectory as processors seek to decouple production schedules from narrow Nordic harvest windows.
End User:
Application-specific purity requirements fragment procurement specifications, with nutraceuticals and pharmaceuticals imposing divergent testing protocols on identical raw material lots.
- Nutraceuticals:Dietary supplement brands in Germany and France drive anthocyanin extract procurement for vision-health formulations with EU-permitted structure-function claims. REACH solvent residue compliance separates qualified from disqualified suppliers.
- Pharmaceuticals:Prescription and OTC phytomedicine manufacturers require GMP-certified processing with full batch documentation. EMA herbal monograph compliance creates entry barriers for non-EU extractors.
- Food Industry:Natural colorant and flavor applications in beverages and confectionery compete on price with synthetic alternatives. BASF phytochemical portfolios pressure botanical anthocyanin pricing in this segment.
- Cosmetics:Dermocosmetic formulators seek antioxidant active ingredients with INCI-compliant designation. French and Italian skincare brands specify organic-certified Nordic material for clean beauty positioning.
Nutraceuticals captures the largest volume commitment; Cosmetics is gaining share fastest as antioxidant positioning proliferates across premium skincare lines.
Distribution Channel:
Customer type determines channel selection, with institutional procurement favoring direct contracting while fragmented retail demand flows through intermediaries.
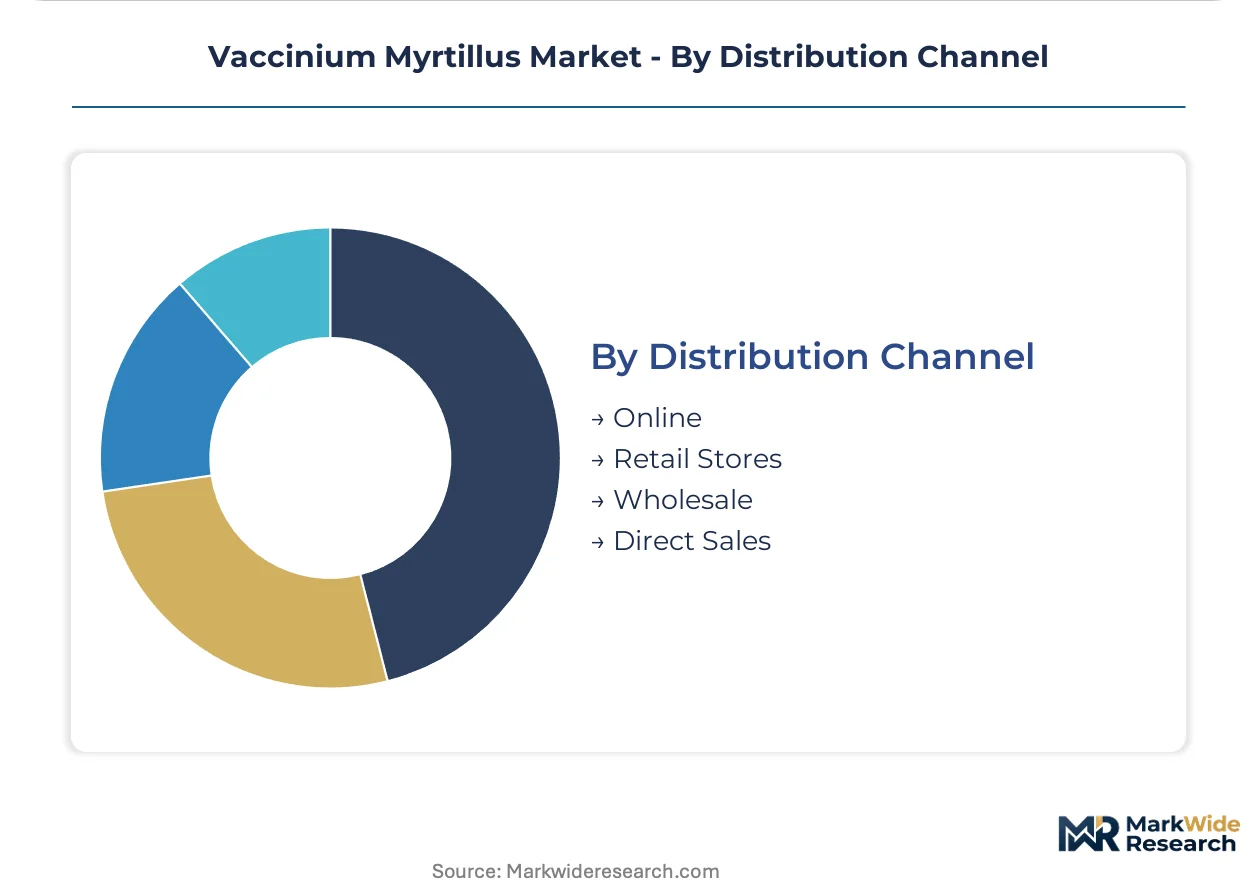
- Direct Sales:Three-year offtake agreements between German supplement brands and Finnish harvesting cooperatives eliminate trader margins. FSSC 22000 and EU Organic dual certification requirements concentrate volume with vertically integrated Nordic suppliers.
- Wholesale:Commodity dried berry traders in Hamburg and Rotterdam serve Asian traditional medicine importers with spot-market liquidity. Organic premiums in this channel remain thin due to certification documentation gaps.
- Online:Direct-to-consumer supplement brands bypass pharmacy distribution with subscription-model bilberry SKUs. German e-commerce operators dominate EU-wide fulfillment for standardized extract capsules.
- Retail Stores:Health food specialists and pharmacy chains stock packaged dried berries and finished supplements. French parapharmacy channel fragmentation creates underpenetrated expansion opportunity for branded extract lines.
Direct Sales holds the dominant procurement volume; Online is climbing the fastest as supplement brands build first-party customer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish Lapland's Arctic harvesting zones concentrate wild Vaccinium myrtillus collection through EU Organic Regulation-certified cooperatives. German nutraceutical formulators negotiate three-year offtake agreements directly with Nordic suppliers, bypassing traditional commodity traders.
Germany
German pharmacy and nutraceutical manufacturers drive anthocyanin extract procurement for vision-health supplements. REACH solvent residue mandates from ECHA enforce quarterly purity testing on ethanolic concentrates. Hamburg serves as the primary import gateway for dried berry material entering Central European processing facilities.
France
French dermocosmetic brands specify organic-certified Nordic bilberry for antioxidant skincare positioning. ANSM oversees INCI compliance for botanical actives entering cosmetic formulations. The parapharmacy channel in Île-de-France remains fragmented, creating expansion opportunity for standardized extract distribution.
Finland
Finnish harvesting cooperatives in Lapland control upstream supply through dual EU Organic and FSSC 22000 certification. The EU Green Deal bioeconomy framework subsidizes circular processing investments for berry waste valorization. Rovaniemi-based operators deploy modular supercritical CO2 extraction units to reduce toll-processing dependence.
Sweden
Swedish Norrland collection zones compete with Finnish Lapland for German and French procurement contracts. The Swedish Board of Agriculture enforces wild-harvest permit systems aligned with EU Organic Regulation audit cycles. Umeå processors specialize in IQF frozen material for year-round industrial supply to French extract houses.
United States
US dietary supplement brands source standardized bilberry extracts for structure-function eye-health claims. FDA cGMP enforcement separates qualified from disqualified ingredient suppliers. Utah and California-based formulators dominate direct-to-consumer e-commerce distribution for encapsulated berry products.
Vaccinium Myrtillus Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade extract supply, while mid-scale Nordic cooperatives compete on traceable organic certification. The vendor base stratifies across three tiers: multinational chemical conglomerates with synthetic-to-natural substitution portfolios, specialized European botanical extract houses with GMP-certified facilities, and regional harvesting cooperatives with captive upstream control. Strategic moves concentrate on backward integration into certified wild-harvest zones and molecular distillation retrofitting for REACH compliance.
Among the specialized extract tier, Naturex S.A. and Eevia Health Oy exemplify divergent geographic anchoring strategies. Naturex S.A. occupies a position representing traditional French botanical extraction expertise. Eevia Health Oy sits within the Arctic-sourcing archetype, leveraging Finnish location for upstream berry control. BASF SE anchors the synthetic-to-natural substitution vector, competing on phytochemical portfolio breadth against botanical rivals.
| Leading Market Players |
|---|
| BASF SE |
| Naturex S.A. |
| Eevia Health Oy |
| Swanson Health Products |
| Bio-Botanica |
| Indena |
| Herbalife Nutrition Ltd. |
| ETchem |
| NOW Foods |
| Others |
Value Network & Pricing Analysis
Wild-harvest labor costs in Finnish Lapland cascade through pharmaceutical-grade extract pricing, compressing margins for toll processors while concentrating premium capture among EU Organic-certified cooperatives with captive upstream control.
Pricing Analysis
Short lead-time premiums for fresh-frozen Nordic material command substantial markups over spot-market dried berry inventory. Contract-based long-term offtake agreements dominate German nutraceutical procurement, with price differentiation driven by EU Organic certification tier and anthocyanin concentration floors. Pricing pressure stems from BASF's synthetic phytochemical substitution in food colorant applications. Commodity bulk buyers in Asian traditional medicine channels exhibit highest price sensitivity; GMP-certified pharmaceutical formulators demonstrate lowest.
Supply Chain Analysis
EU Organic and FSSC 22000 dual certification gates supplier qualification, filtering Nordic wild-harvest cooperatives from commodity traders. Geographic supply concentrates in Finland, Sweden, and Estonia. Raw material dependencies center on Arctic berry crop yields, IQF freezing capacity, and supercritical CO2 extraction equipment. Single-source vulnerability from Nordic weather-driven harvest volatility threatens year-round supply continuity. Distribution runs through direct-procurement contracts between Finnish cooperatives and German supplement brands, displacing Hamburg and Rotterdam trader intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction technology is displacing legacy ethanolic solvent processing, compressing compliance costs and decentralizing production economics for mid-scale Nordic operators.
For Market Incumbents: Hedge against synthetic pigment substitution by deepening captive berry sourcing in Finnish Lapland through three-year organic certification lockups. Retrofit molecular distillation capabilities to eliminate methanol traces and sustain REACH compliance against ECHA inspection protocols. Channel control through direct-to-pharmacist distribution in fragmented German pharmacy networks offers defensive margin protection.
For New Entrants and Emerging Players: Blockchain-integrated HPLC fingerprinting platforms offer a technology-first wedge into authentication-starved supply chains. Target underpenetrated French parapharmacy distribution with blister-packed EU Organic capsule formats. A go-to-market angle anchored in real-time provenance verification from harvest site to finished batch addresses pharmaceutical-grade traceability gaps.
For Investors and Strategic Acquirers: EFSA health-claims authorization timelines for bilberry eye-health substantiation are the leading indicator that premium extract demand will concentrate among validated suppliers. Long-term viability favors vertically integrated Nordic operators with dual EU Organic and FSSC 22000 credentials over toll-dependent processors. Acquisition target archetype: Finnish cooperatives with installed supercritical extraction and direct German offtake relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Wild-Harvest Zones | EU Organic Regulation mandates concentrate supply access among Finnish operators with permitted collection zones. |
| Molecular Distillation Retrofitting | ECHA-mandated REACH compliance on residual solvents forces technical upgrading for ethanolic extraction facilities. |
| Blockchain-HPLC Authentication Platform Deployment | Integrated provenance verification from Lapland harvest sites to German supplement batches commands pharmaceutical-grade premiums. |
| Direct-to-Pharmacist Distribution Expansion | Fragmented German pharmacy channel structure creates margin capture opportunity bypassing concentrated nutraceutical supply chains. |
| Circular Processing Investment for Berry Waste Valorization | EU Green Deal bioeconomy subsidies enable polyphenol recovery margin expansion for Nordic operators. |
Research Methodology
Independent corroboration across Finnish harvesting cooperative managers, German nutraceutical procurement directors, French dermocosmetic formulators, and EFSA regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from EU Organic Regulation audit documentation, ECHA REACH compliance filings, EMA herbal monograph databases, and Nordic trade customs records. Bottom-up volume triangulation from individual processor capacities reconciles with top-down demand aggregation across end-use segments.
Rate-of-change decomposition across the analysis window segments growth drivers by product type, form tier, end-user application, and distribution channel. Modeled dimensions include pharmaceutical-grade versus food-grade purity specifications, wild-harvest versus cultivated sourcing origin, and direct-contract versus spot-market procurement patterns. CAGRs derive from weighted average of segment growth trajectories, with Nordic organic harvest yield volatility and EFSA claim-authorization timelines as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme Arctic weather disruption or accelerated synthetic pigment substitution. Model assumptions reflect documented EFSA evaluation timelines, EU Organic Regulation audit cycles, and REACH enforcement intensity. A model refresh is warranted upon material change in Nordic berry crop yields or ECHA solvent residue threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
North Africa Table Olives Market
Fruits and Vegetables
North America Olive Market
Fruits and Vegetables
Dill Pickles Market
Fruits and Vegetables
Fruit Pulp Market
Fruits and Vegetables
Asia-Pacific Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Edible Flowers Market
Fruits and Vegetables
Packaged Fresh Fruits Market
Fruits and Vegetables
Fresh Cherries Market
Fruits and Vegetables
Asia Pacific Lime Market
Fruits and Vegetables
South America Olive Market
Fruits and Vegetables
Boysenberry Market
Fruits and Vegetables
Cyanidin Market
Fruits and Vegetables
Sea Buckthorn Market
Fruits and Vegetables
Cambodia Fruits and Vegetables Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market