
 Spain Tropical Fruits Market | 2026-2036
Spain Tropical Fruits Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Tropical Fruits Market Analytics
Buyer concentration among Spanish supermarket chains is restructuring procurement dynamics for tropical fruit suppliers. Dole plc leverages its vertical integration across Latin American growing regions to secure consistent supply lines into Valencia and Barcelona ports. Frutas Montosa S.A. anchors its competitive position through specialized ripening facilities that extend shelf life for retail distribution. Reyes Gutiérrez S.A. differentiates via direct relationships with Canary Island banana growers, reducing intermediary costs.
Tropical fruits comprise climacteric and non-climacteric produce cultivated in equatorial zones, harvested at physiological maturity, and transported under controlled atmosphere conditions at 13°C for bananas and 10-13°C for mangoes to delay ethylene-triggered ripening during Atlantic transit. Spain's tropical fruit trade serves domestic consumption, food manufacturing, and re-export hub functions for the broader European market. The mango segment leads value contribution due to higher unit prices and expanding Ataulfo variety preference among Spanish retail consumers. Online Retail distribution channels represent the fastest-growing structural segment, driven by subscription box models and direct-to-consumer platforms targeting urban households in Madrid and Barcelona.
BIS-equivalent EU standards, EFSA residue monitoring protocols, and Spain's national food safety agency (AESAN) enforcement of EU import phytosanitary certificates shape market access requirements for third-country tropical fruit shipments. The EU Green Deal's sustainable food system targets are forcing importers to document carbon footprint metrics and deforestation-free supply chain evidence for tropical fruit categories. Stakeholders must monitor evolving EU due diligence regulations and cold chain energy cost trajectories to preserve margin structures in the Spanish tropical fruit trade.
Market Dynamics
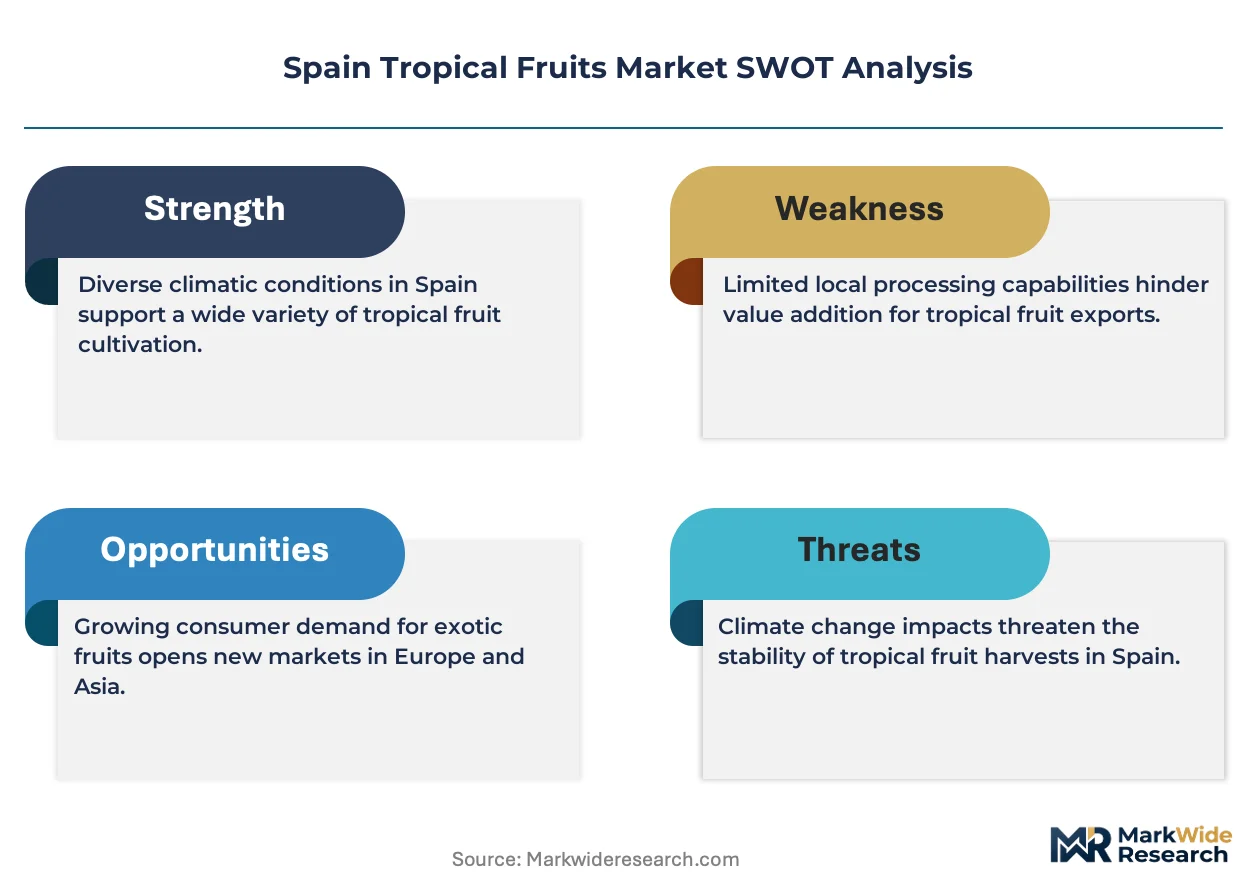
Spain's tropical fruit trade operates under intensifying pressure from the EU Green Deal's deforestation-free supply chain mandates, which force importers to reconfigure sourcing documentation and carbon accounting systems for Latin American and African origins.
Growth Catalysts
- Food service menu expansion:Spanish juice bars and smoothie chains are diversifying into mango, pineapple, and passion fruit formulations, creating pull-through demand for wholesale ripening services and pre-cut processing.
- EU Green Deal sustainable sourcing mandates:Regulatory pressure for documented deforestation-free supply chains is accelerating investment in traceability platforms and supplier certification programs among Valencia-based importers.
- Andalusia port infrastructure:Algeciras and Málaga container terminals are expanding controlled-atmosphere storage capacity, enabling faster turnaround for re-export shipments to France, Germany, and the Netherlands.
Market Restraints
- Atlantic shipping cost volatility:Fuel price swings and container availability constraints from West African and Latin American origins compress margin predictability for seasonal mango and pineapple procurement cycles.
- Latin American supply concentration:Overreliance on Ecuadorian and Costa Rican banana exporters exposes Spanish distributors to phytosanitary disruption risks and currency fluctuation impacts on landed costs.
- F-Gas Regulation compliance costs:The EU's phasedown of hydrofluorocarbon refrigerants is forcing cold chain operators to retrofit reefer containers and warehouse cooling systems with alternative technologies before 2030 deadlines.
Strategic Opportunities
- Subscription box penetration:Direct-to-consumer platforms targeting Madrid and Barcelona households are bypassing traditional retail markups through weekly exotic fruit assortments with ripening guidance.
- Canary Island banana premium positioning:Proximity sourcing from local growers enables same-day harvest-to-shelf cycles that differentiate against Atlantic-imported competition in freshness-sensitive segments.
- Controlled-atmosphere technology convergence:Integration of ethylene scrubbing with IoT monitoring is extending mango shelf life from 14 to 21 days, opening new re-export corridors into Central European retail.
Industry Challenges
- Phytosanitary certification timelines:AESAN enforcement of EU import documentation for fruit fly and mealybug compliance creates 48-72 hour port delays that degrade ripeness windows for climacteric produce.
- Cold chain energy cost exposure:Spanish electricity pricing volatility and F-Gas retrofit capital requirements are squeezing third-party logistics margins in the Valencia-Algeciras corridor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Tropical Fruits Market |
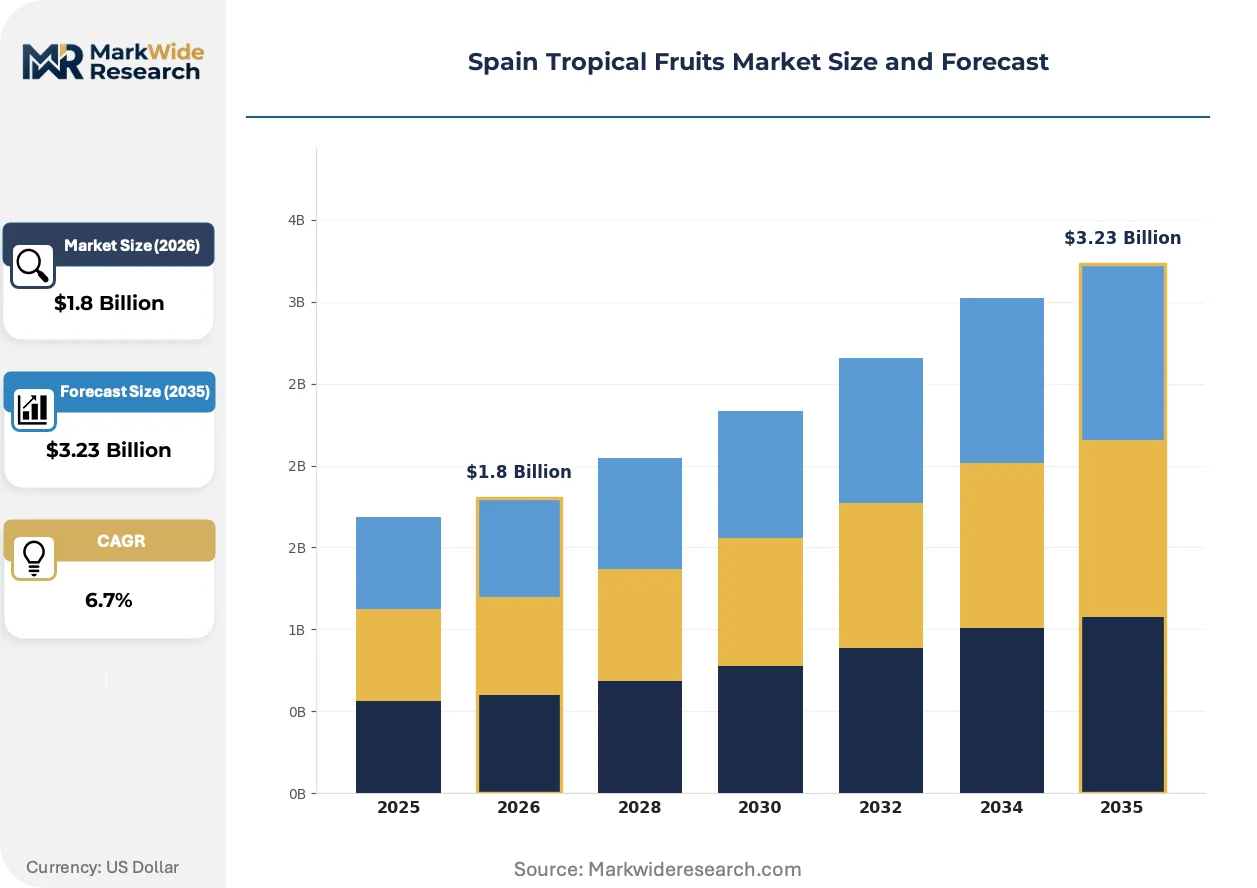
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mango, Pineapple, Banana, Papaya Distribution Channel: Supermarkets, Online Retail, Wholesalers, Convenience Stores Customer Type: Retail Consumers, Food Service, Exporters, Manufacturers Variety: Hass, Ataulfo, Gold, Dwarf Cavendish |
| Companies Covered | Frutas Montosa S.A., Anecoop S. Coop., Reyes Gutiérrez S.A., Dole plc, Fyffes, Trops, Unica Group S.C.A., Chiquita Brands International, Grupo La Cana, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Tropical Fruits Market Evolving Landscape
Spanish tropical fruit distribution is fragmenting across digital channels and localized ripening networks, compressing traditional wholesale hierarchies while elevating traceability and freshness as competitive differentiators.
Blockchain-enabled provenance tracking is decentralizing supply chain visibility for Spanish supermarket buyers. Mercadona and Carrefour España are piloting QR-code batch tracing for Ataulfo mangoes from Costa Rican cooperatives, enabling real-time verification of harvest dates and transport temperatures. This transparency architecture is compressing trust premiums previously captured by established importer brands, allowing smaller Latin American exporters to access Spanish retail directly.
The EU Deforestation Regulation is mandating geolocation-verified sourcing documentation for all tropical fruit shipments entering Spanish ports. AESAN enforcement protocols now require polygon mapping of production plots and harvest date timestamps, creating compliance friction for informal smallholder networks in West Africa. Spanish importers are responding by consolidating procurement through certified cooperative structures in Ecuador and Colombia that can deliver standardized traceability data.
Urban households in Madrid and Barcelona are migrating toward curated subscription formats for exotic fruit assortments. Platforms like Frutas Selectas and specialized Amazon Fresh storefronts are displacing conventional supermarket trips through pre-ripened mango and papaya deliveries synchronized to consumption schedules. This channel shift is most visible among dual-income professionals aged 28-42, who prioritize convenience and waste reduction over price sensitivity in fruit purchasing decisions.
Spain Tropical Fruits Market Segmentation
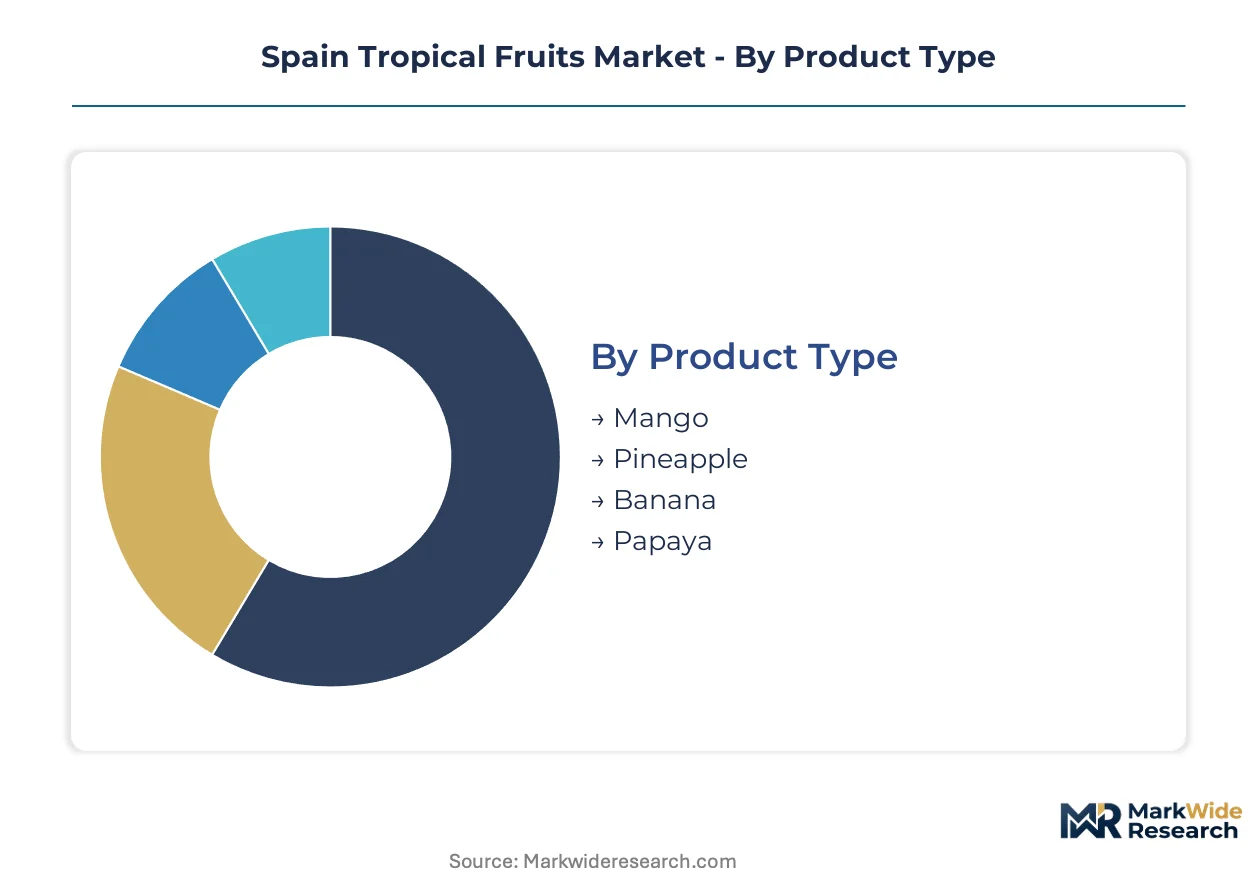
Spain's tropical fruit trade fragments across ripening-sensitive product categories, digital-native distribution channels, and re-export-oriented customer bases. Segmentation clarity determines margin capture for importers navigating EU phytosanitary compliance and cold chain cost pressures.
Product Type:
Supply concentration in climacteric varieties dictates ripening infrastructure investments across Valencia and Algeciras port zones.
- Mango:Climacteric stone fruit harvested at physiological maturity requiring 10-13°C controlled-atmosphere transit to delay ethylene-triggered ripening. Demand concentrates in Madrid and Barcelona retail networks driven by Ataulfo variety preference and smoothie bar menu expansion.
- Banana:Starch-to-sugar converting climacteric fruit shipped at 13°C with continuous ethylene scrubbing. Andalusia's port cities anchor re-export volumes to France and Germany where ripening facility proximity creates landed cost advantages over direct Atlantic shipments.
- Pineapple:Non-climacteric tropical fruit harvested at full ripeness with shorter shelf life constraints. Costa Rican supply lines through Algeciras serve Spanish food manufacturing and fresh-cut processing segments.
- Papaya:Heat-sensitive produce requiring rapid cold chain insertion post-harvest. Canary Island cultivation supplies same-day freshness positioning against Brazilian and Mexican import competition.
Today's leader: Mango. Tomorrow's challenger: Banana.
Distribution Channel:
Channel cost tiers separate capital-intensive ripening networks from asset-light digital platforms.
- Supermarkets:Mercadona and Carrefour España dominate procurement through centralized ripening facilities and private label programs. Their volume concentration forces supplier compliance with EU Deforestation Regulation geolocation documentation.
- Online Retail:Subscription box models and Amazon Fresh storefronts bypass traditional wholesale markups through direct-to-consumer ripening guidance. Madrid and Barcelona urban households aged 28-42 drive steepest expansion trajectory in this channel.
- Wholesalers:Mercamadrid and Mercabarna terminal markets aggregate fragmented supply for food service and independent retail redistribution. Their margin compression intensifies under supermarket direct-sourcing expansion.
- Convenience Stores:Limited SKU availability focuses on pre-ripened banana and pineapple grab-and-go formats. Urban density in Barcelona and Valencia determines viable catchment zones for tropical fruit placement.
Supermarkets command volume. Online Retail gains share fastest.
Customer Type:
End-use application diversity stretches from freshness-sensitive retail to shelf-stable manufacturing inputs.
- Retail Consumers:Individual households purchasing whole fruit or pre-cut formats through supermarket and digital channels. Ataulfo mango preference and waste-reduction priorities shape purchasing decisions among dual-income professionals.
- Food Service:Juice bars, smoothie chains, and hospitality operators requiring consistent ripeness staging and pre-cut processing. Their menu diversification into passion fruit and mango formulations pulls wholesale ripening service demand.
- Exporters:Valencia and Algeciras-based traders re-exporting to France, Germany, and Netherlands. Controlled-atmosphere technology investments determine competitive positioning in Central European retail penetration.
- Manufacturers:Yogurt, ice cream, and baby food producers sourcing processed tropical fruit purees and concentrates. Their procurement prioritizes year-round supply security over fresh fruit price volatility.
Retail Consumers anchor volume. Food Service expands most quickly.
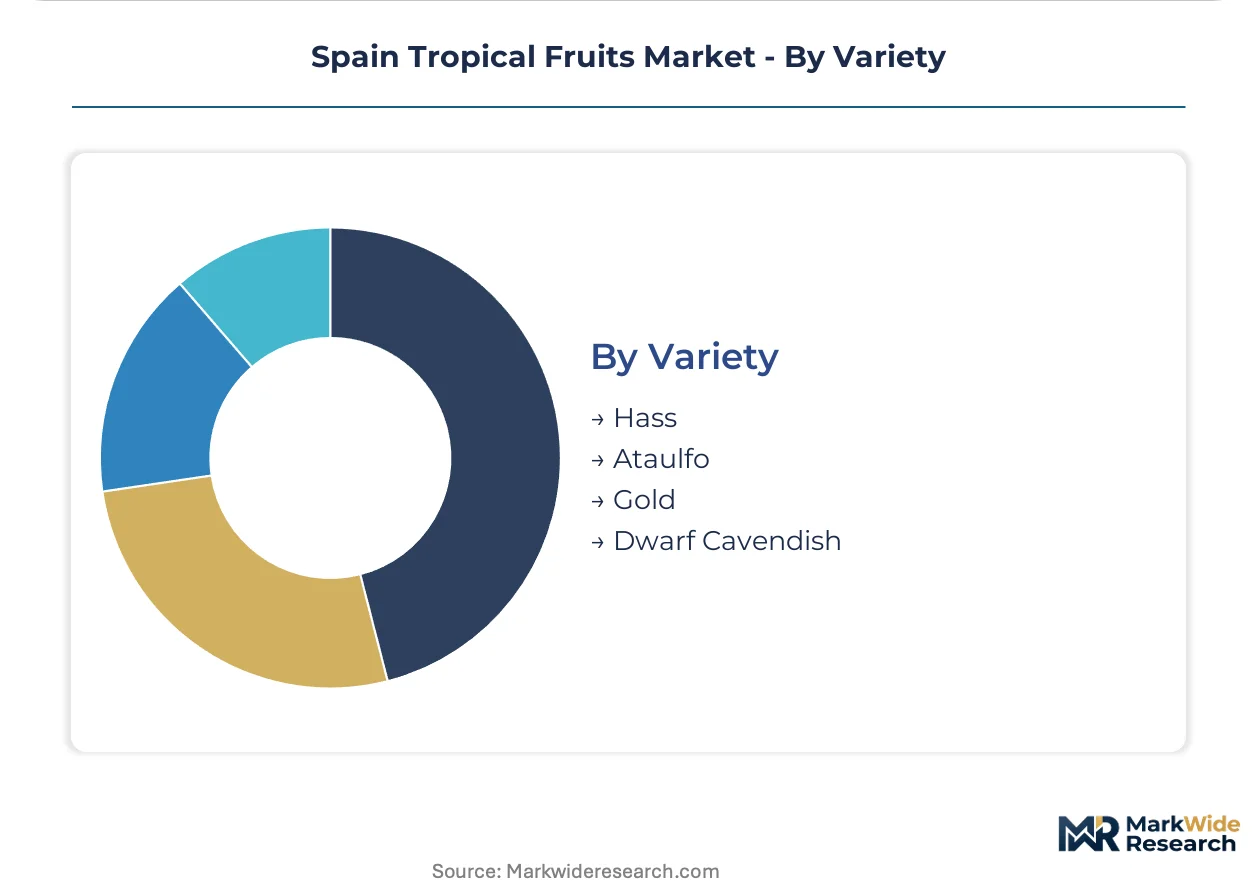
Variety:
Genetic differentiation creates pricing stratification across premium, standard, and economy tiers.
- Ataulfo:Creamy-textured mango variety with small seed and fiberless flesh commanding retail price premiums. Spanish consumer preference for this cultivar concentrates procurement through Costa Rican and Peruvian cooperative networks.
- Gold:MD-2 pineapple variety standardized for global export with uniform sweetness and extended shelf life. Costa Rican supply dominance through Algeciras creates procurement concentration risk for Spanish distributors.
- Hass:Avocado variety occasionally miscategorized in tropical fruit segmentation though climatically distinct. Its inclusion reflects broader exotic fruit assortment strategies in Spanish retail.
- Dwarf Cavendish:Standard banana cultivar dominating mass-market retail with consistent sizing and ripening predictability. Ecuadorian and Costa Rican supply concentration exposes Spanish importers to phytosanitary disruption risks.
Ataulfo leads premium positioning. Gold standardizes volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain outpaces Portugal in tropical fruit re-export volumes through Mediterranean port infrastructure, while both countries face identical EU Green Deal compliance timelines for deforestation-free supply chain documentation.
Andalusia
Algeciras and Málaga container terminals process Atlantic arrivals from Ecuador and Costa Rica for banana redistribution into France and Germany. AESAN phytosanitary enforcement at these ports creates 48-72 hour documentation delays that degrade ripeness windows. Controlled-atmosphere storage expansion at Algeciras is accelerating re-export turnaround times for Central European retail penetration.
Catalonia
Barcelona's Mercabarna wholesale terminal aggregates fragmented tropical fruit supply for food service redistribution across northeastern Spain. The region's dual-income professional households aged 28-42 drive subscription box demand through Amazon Fresh and specialized platforms. Cold chain operators here face acute F-Gas Regulation retrofit deadlines before 2030.
Madrid
The capital's retail concentration anchors Mercadona and Carrefour España procurement through centralized ripening facilities. Urban density supports convenience store pre-ripened formats in grab-and-go segments. Madrid-based importers are consolidating Costa Rican cooperative relationships to satisfy EU Deforestation Regulation geolocation documentation requirements.
Valencia
Spain's largest port complex handles pineapple and mango shipments from West African origins for food manufacturing inputs. Valencia-based logistics providers are retrofitting reefer containers with alternative refrigerants to meet F-Gas phasedown mandates. The city's wholesale markets serve as ripening staging points for Ataulfo variety distribution to inland retail networks.
Canary Islands
Local banana cultivation on Tenerife and Gran Canaria enables same-day harvest-to-shelf cycles that differentiate against Atlantic-imported competition. Reyes Gutiérrez S.A. maintains direct grower relationships here, reducing intermediary costs for freshness-sensitive segments. Island production falls under Spanish national jurisdiction but benefits from proximity logistics unavailable to Latin American supply lines.
Spain Tropical Fruits Market Competitive Landscape
Latin American producers anchor one tier; Spanish specialists hold re-export and ripening infrastructure advantages. The vendor base separates into integrated plantation-to-port operators, regional ripening service providers, and cooperative aggregation networks. Three archetypes dominate: vertically integrated multinationals with captive growing assets, mid-scale Iberian distributors with controlled-atmosphere facilities, and island-based proximity specialists. Competitive moves concentrate on supplier certification programs and cold chain technology licensing.
Within the multinational tier, Dole plc and Chiquita Brands International represent plantation-origin supply control. Among Spanish distributors, Frutas Montosa S.A. and Reyes Gutiérrez S.A. occupy positions emphasizing ripening infrastructure and Canary Island proximity sourcing respectively. Cooperative structures exemplified by Anecoop S. Coop. and Unica Group S.C.A. sit within the aggregation archetype, consolidating smallholder output for EU compliance documentation.
| Leading Market Players |
|---|
| Frutas Montosa S.A. |
| Anecoop S. Coop. |
| Reyes Gutiérrez S.A. |
| Dole plc |
| Fyffes |
| Trops |
| Unica Group S.C.A. |
| Chiquita Brands International |
| Grupo La Cana |
| Others |
Value Network & Pricing Analysis
Atlantic shipping fuel costs cascade through Spanish tropical fruit pricing tiers, with bunker fuel surcharges from Ecuadorian and Costa Rican origins compressing margin structures for Valencia-based importers serving Mercadona and Carrefour España procurement contracts.
Pricing Analysis
Capacity additions in Algeciras controlled-atmosphere storage are reshaping price floors for banana re-export volumes into France and Germany. Three-tier pricing structure across premium Canary Island origin, standard Latin American import, and economy-grade West African supply reflects certification grade and freshness window differentiation. Price compression intensifies in the economy tier as AESAN phytosanitary delays degrade ripeness quality upon arrival. Food service operators exhibit lowest price sensitivity due to menu premiumization, while independent convenience stores face acute margin pressure from supermarket private label expansion.
Supply Chain Analysis
Single-source vulnerability sits with Ecuadorian banana exporters supplying over sixty percent of Spanish Atlantic port arrivals. Raw material dependencies center on Costa Rican Ataulfo mango cultivars, Costa Rican Gold pineapple stock, and Canary Island Dwarf Cavendish banana production. Tariff exposure through evolving EU-ACP trade preferences threatens landed cost predictability for West African origins. Distribution runs through Mercamadrid and Mercabarna wholesale terminals for food service fragmentation, with direct-to-consumer platforms bypassing traditional markup hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's tropical fruit market functions as a regulatory compounder where EU Deforestation Regulation geolocation mandates are accelerating traceability platform investments and supplier consolidation.
For Market Incumbents: Cement backward integration into Costa Rican cooperative networks to secure deforestation-free documentation streams before AESAN enforcement tightens. Lock in controlled-atmosphere capacity at Algeciras and Valencia to defend ripening service margins against cold chain energy cost volatility. Prioritize certification investment in EUDR-compliant polygon mapping systems to preempt smaller Latin American exporter direct access to Mercadona procurement. For New Entrants and Emerging Players: Subscription box platforms represent the most penetrable channel wedge for Madrid and Barcelona dual-income professional households aged 28-42. Target food service ripening-as-a-service contracts where incumbent wholesalers lack pre-cut processing capabilities. Pursue direct sourcing from Canary Island banana growers to exploit same-day freshness positioning unavailable to Atlantic importers. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented West African smallholder networks fail to deliver standardized traceability data for EU compliance. Mid-scale Iberian distributors with captive ripening infrastructure and EUDR-certified supplier relationships offer strongest five-to-ten year viability positioning. Watch for AESAN enforcement intensity at Algeciras and Valencia as the inflection signal determining which importers absorb compliance costs versus exit.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperative Sourcing | Secures EUDR-compliant geolocation documentation from Costa Rican and Ecuadorian grower networks. |
| Controlled-Atmosphere Capacity Expansion | Extends mango shelf life from fourteen to twenty-one days for Central European re-export penetration. |
| Direct-to-Consumer Platform Launch | Bypasses Mercamadrid wholesale markups through Madrid and Barcelona subscription box models. |
| F-Gas Alternative Refrigerant Retrofit | Prevents 2030 compliance deadline disruption for Valencia-Algeciras cold chain operators. |
| Blockchain Provenance Tracking Deployment | Enables QR-code batch verification for Ataulfo mangoes at Carrefour España retail. |
Research Methodology
Direct dialogue with tropical fruit import executives, AESAN regulatory affairs specialists, Mercadona category buyers, Algeciras port logistics managers, and Costa Rican cooperative export directors grounded qualitative findings. Secondary validation drew from EU COMEXT trade statistics, EFSA residue monitoring reports, AESAN import certification databases, and FAO tropical fruit production bulletins. Bottom-up shipment volume aggregation and top-down consumption survey triangulation anchored market sizing.
Bottom-up modeling traced product flows through ripening facility capacity, cold chain energy cost structures, and channel-specific markup hierarchies across the analysis window. Segmentation dimensions included climacteric versus non-climacteric physiology, distribution channel cost tiers, and end-use application freshness sensitivity. CAGRs derived from regression against historical trade flow velocities and EU regulatory implementation timelines. Forecast inputs incorporated F-Gas retrofit capital expenditure trajectories and EUDR compliance friction coefficients.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Atlantic shipping cost volatility and AESAN enforcement intensity variations. Projections assume stable EU-ACP trade preferences and no phytosanitary disruption to Ecuadorian banana supply lines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Pickle Market
Fruits and Vegetables
Coconut Products Market
Fruits and Vegetables
US Fruit Puree Market
Fruits and Vegetables
North Africa Table Olives Market
Fruits and Vegetables
Argentina Lime Market
Fruits and Vegetables
United States Frozen Fruits and Vegetables Market
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
Dried Blueberries Market
Fruits and Vegetables
Dried Figs Market
Fruits and Vegetables
Fresh Fruits Market
Fruits and Vegetables
Europe Blueberry Market
Fruits and Vegetables
North Africa Fruits and Vegetables Processing Market
Fruits and Vegetables
Cucumber and Gherkins Market
Fruits and Vegetables
Fresh Strawberry Market
Fruits and Vegetables
Acai Berry Market
Fruits and Vegetables
Europe Stone Fruits Market