
 Lingonberry Market | 2026-2036
Lingonberry Market Size, Share, and Industry Trends Forecast 2026-2036
Lingonberry Market Foresight
Flash-freezing and gentle pasteurization technology is reconfiguring how lingonberry processors preserve anthocyanin potency through the value chain. Kiantama Oy leverages its Finnish wild-berry sourcing network to secure premium raw material volumes. Eevia Health anchors its competitive position through standardized polyphenol extraction for nutraceutical clients. Ocean Spray Cranberries, Inc. extends its established cranberry infrastructure into adjacent berry categories including lingonberry blends.
Lingonberry (Vaccinium vitis-idaea) is a perennial evergreen shrub fruit containing benzoic acid as a natural preservative, typically harvested from boreal forests and cultivated in acidic, well-drained soils at latitudes above 55°N; processors flash-freeze or gently dry the berries to retain anthocyanin levels for food, beverage, and dietary supplement applications. Frozen berries and juices capture the dominant volume positions due to extended shelf stability and established industrial buyer relationships. Dried fruits and jams occupy narrower but higher-margin niches where clean-label positioning commands premium pricing from health-conscious retail consumers.
EFSA organic labeling requirements, FDA dietary supplement cGMP standards, and Finnish Metsähallitus wild-harvest permits collectively shape product standards and market access for lingonberry suppliers across export destinations. These frameworks enforce traceability from forest to finished good, raising compliance costs for smaller harvesters while favoring vertically integrated operators with certified quality systems. Stakeholders must monitor evolving polyphenol health claim substantiation pathways in major import jurisdictions to anticipate demand inflection points.
Market Dynamics
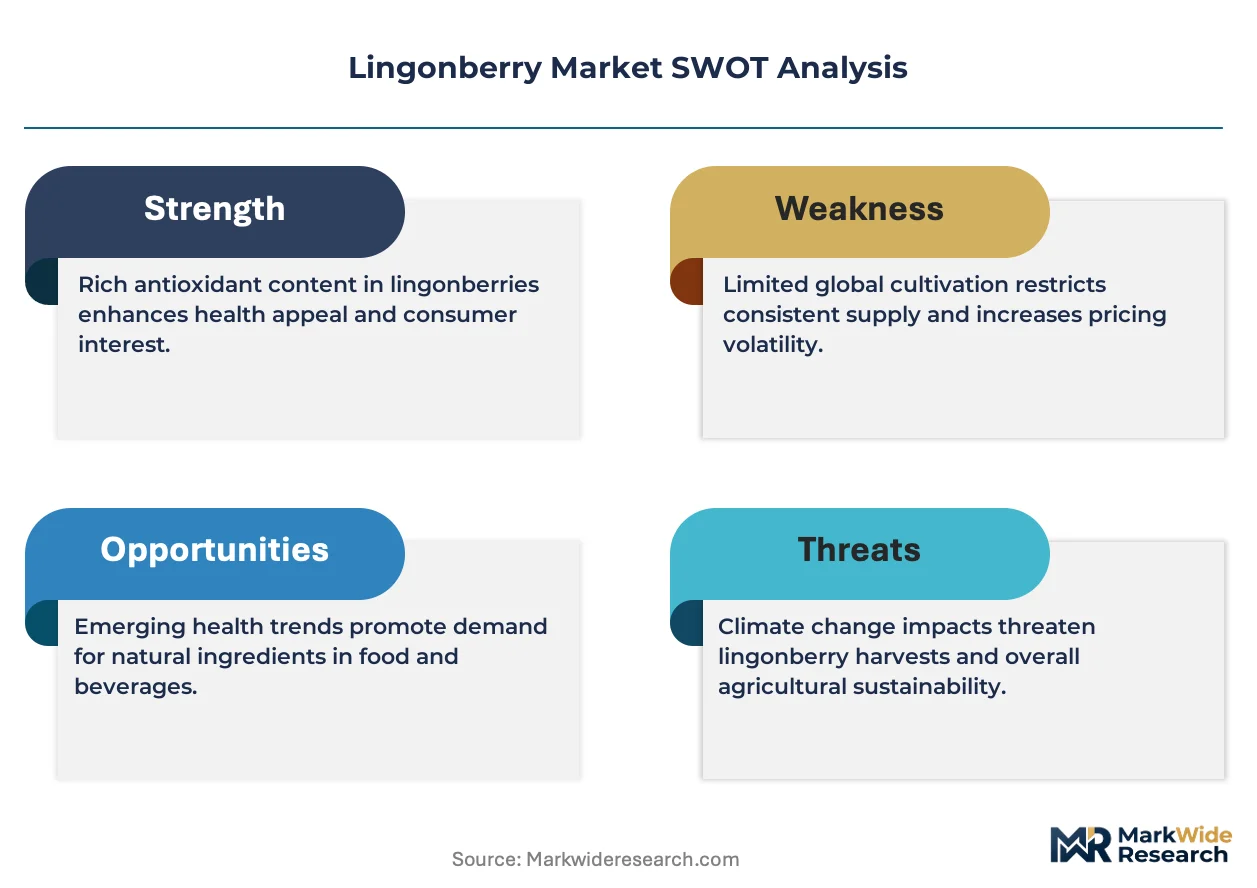
Flash-freezing technology paired with EFSA organic traceability mandates is compressing margins for small harvesters while rewarding vertically integrated processors with certified cold-chain infrastructure across Nordic sourcing corridors.
Growth Catalysts
- Functional food formulation demand:Nutraceutical manufacturers are accelerating procurement of standardized polyphenol extracts for antioxidant positioning in dietary supplements and fortified beverages.
- EFSA organic certification expansion:Wild-harvested berry traceability protocols under EU Regulation 2018/848 are unlocking premium channel access for compliant Finnish and Swedish suppliers.
- Boreal forest permit rationalization:Finnish Metsähallitus is consolidating commercial harvesting rights, streamlining access for certified operators with established drying and freezing capabilities.
Market Restraints
- Wild-harvest supply concentration:Over 70% of raw material volume originates from unmanaged boreal forests in Finland, Sweden, and Estonia, exposing processors to weather-driven yield volatility.
- Benzoic acid substitution pressure:Synthetic preservatives and alternative berry extracts compete on cost in mass-market jam and beverage applications where clean-label positioning carries less weight.
- Dual regulatory compliance burden:Simultaneous adherence to FDA dietary supplement cGMP standards and EFSA novel food requirements raises fixed costs for exporters serving both jurisdictions.
Strategic Opportunities
- Asian nutraceutical channel development:Japan's PMDA and South Korea's MFDS are establishing polyphenol health claim substantiation pathways for berry-derived ingredients, creating first-mover positioning for standardized extract suppliers.
- Cultivated berry scaling:Controlled-environment agriculture in acidic, well-drained substrates above 55°N latitude offers yield predictability unavailable in wild harvest systems.
- Direct-to-industrial platform emergence:B2B ingredient marketplaces are compressing traditional broker layers, enabling mid-size processors to secure long-term contracts with functional food manufacturers.
Industry Challenges
- Anthocyanin stability expertise scarcity:Flash-freezing and gentle pasteurization protocols require specialized food engineering talent concentrated among Nordic technical institutes.
- Organic certification timeline compression:EFSA's tightened wild-harvest documentation requirements are extending audit cycles from 12 to 18 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lingonberry Market |
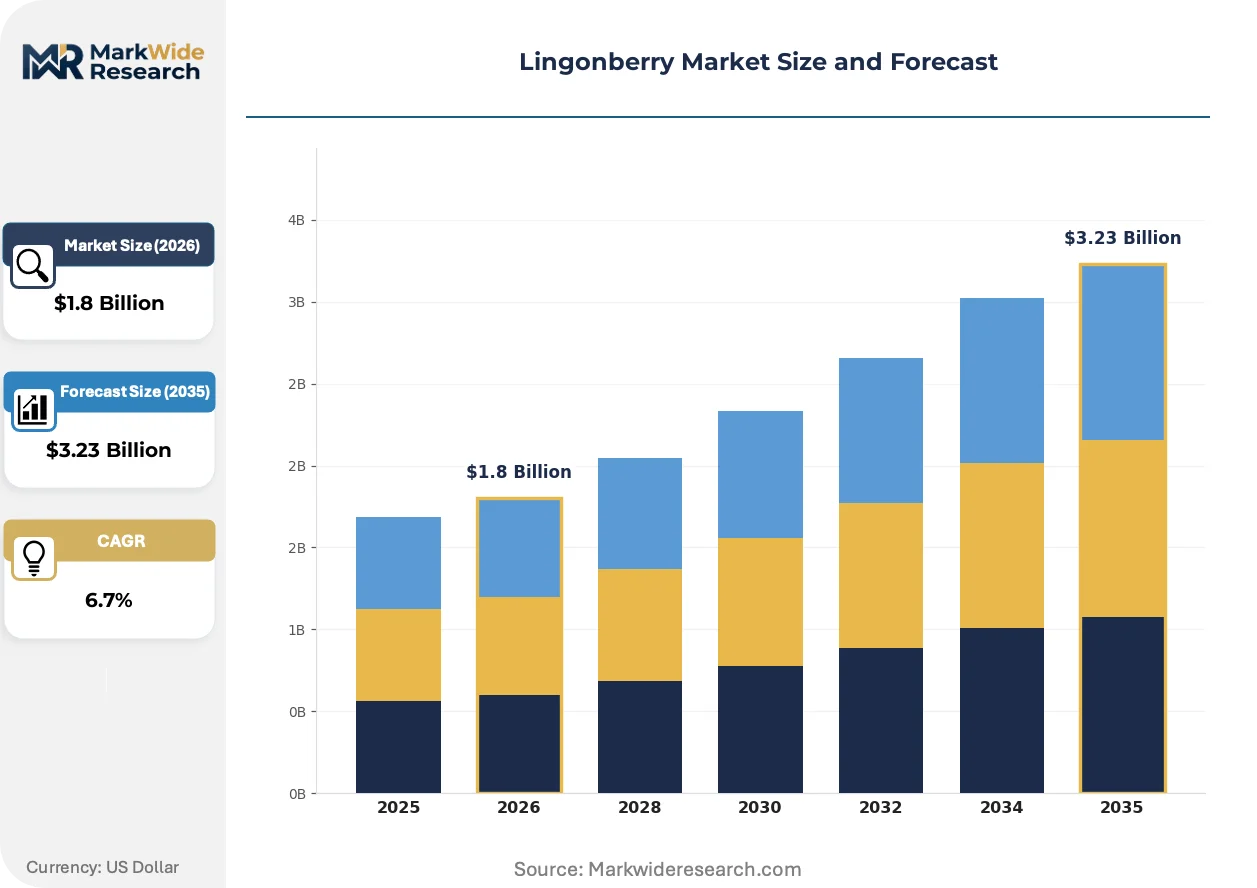
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Berries, Jams, Juices, Dried Fruits End User: Retail Consumers, Food Service, Industrial Users, Exporters Packaging Type: Bulk Packaging, Retail Packs, Glass Jars, Pouches Distribution Channel: Online Retail, Supermarkets, Wholesalers, Farmers Markets |
| Companies Covered | Ingredion Incorporated, Loov Food, Arla Foods amba, Arctic Power Berries, Eevia Health, Ocean Spray Cranberries, Inc., Artemis, Kiantama Oy, Döhler GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lingonberry Market Shifts & Advancements
Processing technology and procurement architecture are converging to preserve bioactive compound integrity while compressing value-chain intermediation. Three developments are restructuring competitive positioning.
Low-temperature vacuum drying is migrating from artisan-scale operations to industrial throughput systems. Premium nutraceutical buyers in Germany and Switzerland are specifying sub-40°C drying protocols to maximize anthocyanin retention. This technology is migrating from niche organic suppliers to mid-cap processors seeking pharmaceutical-grade ingredient positioning.
EU Regulation 2018/848's full implementation is mandating geolocation tagging for every wild-harvest batch. Finnish and Estonian operators are deploying blockchain-integrated collection permits to satisfy EFSA traceability audits. Small harvester cooperatives face consolidation pressure as compliance costs favor operators with in-house quality management systems.
Ingredient buyers are consolidating supplier relationships around certified extractors with dual FDA-EFSA compliance. Functional food manufacturers in the Netherlands and Denmark are replacing spot-market berry purchases with multi-year polyphenol supply agreements. This concentration is most visible in the dietary supplement channel, where standardization consistency outweighs raw material cost minimization.
Lingonberry Market Segmentation
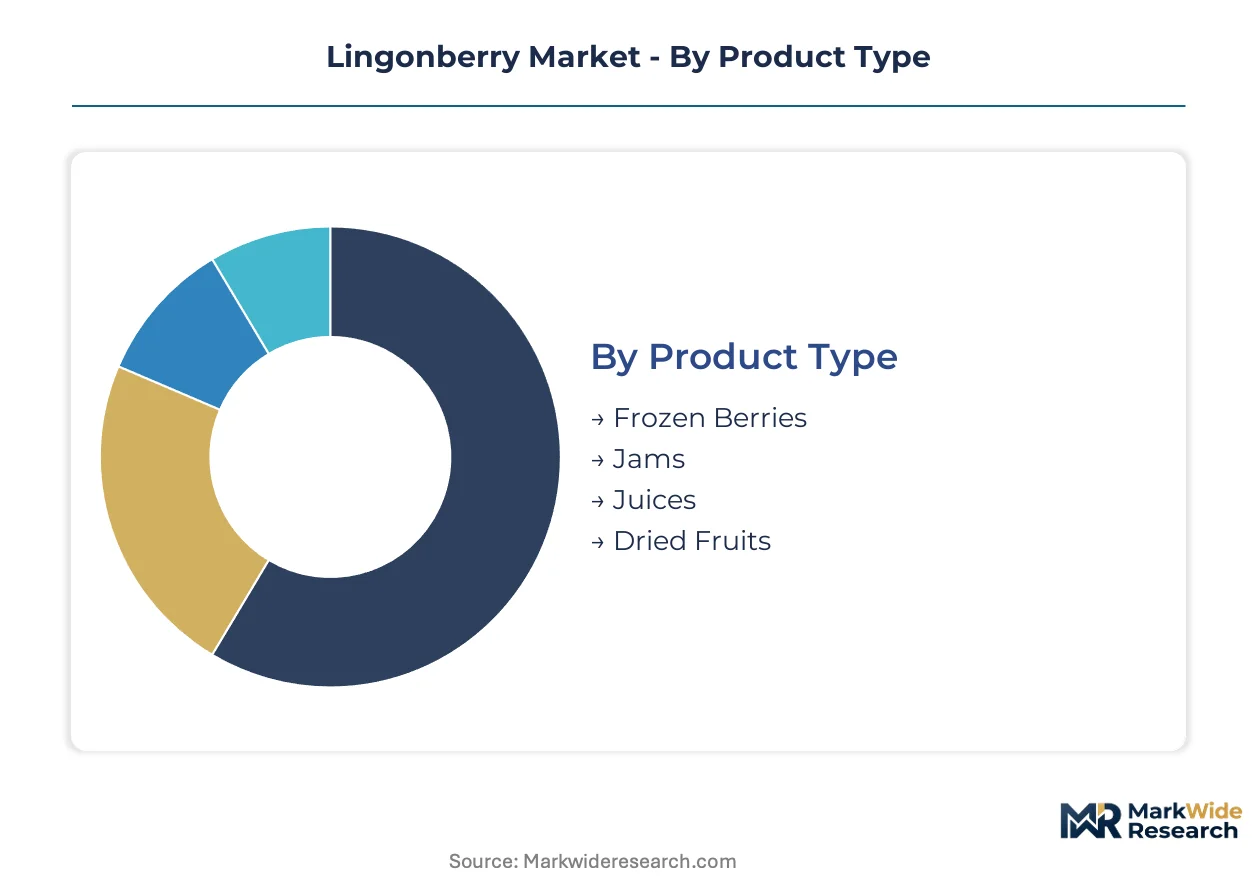
Lingonberry segmentation reveals divergent velocity profiles across product formats and buyer channels. Cycle times range from spot-market frozen berry contracts to eighteen-month organic certification timelines for retail-packaged goods. Understanding these turnover differentials exposes margin pressure points and working capital requirements for Nordic processors.
Product Type:
Frozen berries turn inventory fastest through industrial procurement cycles, while dried fruit and jam segments lock up capital through extended retail channel development. Jams and juices occupy intermediate positions with seasonal formulation windows.
- Frozen Berries:Flash-frozen whole berries at -40°C preserve anthocyanin potency above 85% of fresh levels. Finnish and Swedish industrial buyers concentrate procurement through Q3-Q4 harvest windows for year-round nutraceutical extraction. Cold-chain infrastructure requirements favor vertically integrated operators with Metsähallitus harvesting permits.
- Jams:Heat-processed formulations leverage lingonberry's natural benzoic acid content to achieve clean-label preservation without synthetic additives. German and Swiss retail channels command premium positioning for organic-certified glass-jar presentations, though private-label pressure intensifies in Nordic mass-market distribution.
- Juices:Single-strength and concentrate formats serve beverage manufacturers seeking polyphenol fortification. Pasteurization protocols determine shelf stability trade-offs against bioactive retention.
- Dried Fruits:Low-temperature vacuum-dried whole berries and powder extracts target nutraceutical encapsulation. Sub-40°C drying specifications from Swiss pharmaceutical buyers extend production cycle times but unlock 3-4x price multiples over conventional hot-air drying.
Frozen berries dominate installed base through industrial volume concentration. Dried fruits and standardized extracts are where expansion concentrates as Asian nutraceutical channels mature.
End User:
Cost tier stratification separates commodity spot purchasers from contract-bound premium buyers, with compliance burden scaling inversely with price sensitivity.
- Industrial Users:Functional food manufacturers and dietary supplement formulators procure standardized polyphenol extracts under multi-year supply agreements. EFSA organic traceability and FDA cGMP dual compliance are non-negotiable entry qualifications for Dutch and Danish ingredient buyers.
- Retail Consumers:Health-conscious shoppers in Germany, Austria, and Switzerland drive clean-label jam and dried fruit demand. Organic certification premiums of 40-60% over conventional products persist in these markets despite private-label encroachment.
- Food Service:Nordic restaurant and catering channels absorb seasonal fresh and quick-frozen volumes for traditional preparation methods. Procurement concentrates through Stockholm, Helsinki, and Copenhagen distribution hubs.
- Exporters:Asian-bound shipments to Japan's PMDA-registered importers and South Korea's MFDS-compliant distributors require novel food substantiation dossiers. Documentation timelines extend 12-18 months beyond standard EU export protocols.
Industrial users anchor contract volume stability. Retail consumers represent the steepest expansion trajectory as clean-label positioning penetrates Central European markets.
Packaging Type:
Volume scale separates bulk industrial formats from unitized retail presentations, with margin structure inverting across this divide.
- Bulk Packaging:10-25 kg polyethylene-lined cartons and food-grade totes serve flash-frozen berry shipments to extraction facilities. Finnish processors Kiantama Oy leverage scale economies in this tier through integrated harvesting and freezing infrastructure.
- Retail Packs:200-500 gram stand-up pouches and vacuum-sealed bags target health-food channel distribution. Shelf appeal and reseal functionality command design investment disproportionate to material cost.
- Glass Jars:Traditional preservation format for jams and compotes, with premium positioning in German and Austrian organic retail. Weight and breakage liability constrain export radius.
- Pouches:Retort and aseptic formats for single-serve juice and smoothie applications. Japanese convenience store channels specify 100-200 ml capacities with extended ambient stability.
Bulk packaging dominates throughput tonnage. Retail packs and pouches concentrate margin expansion as direct-to-consumer channels fragment traditional wholesale architecture.
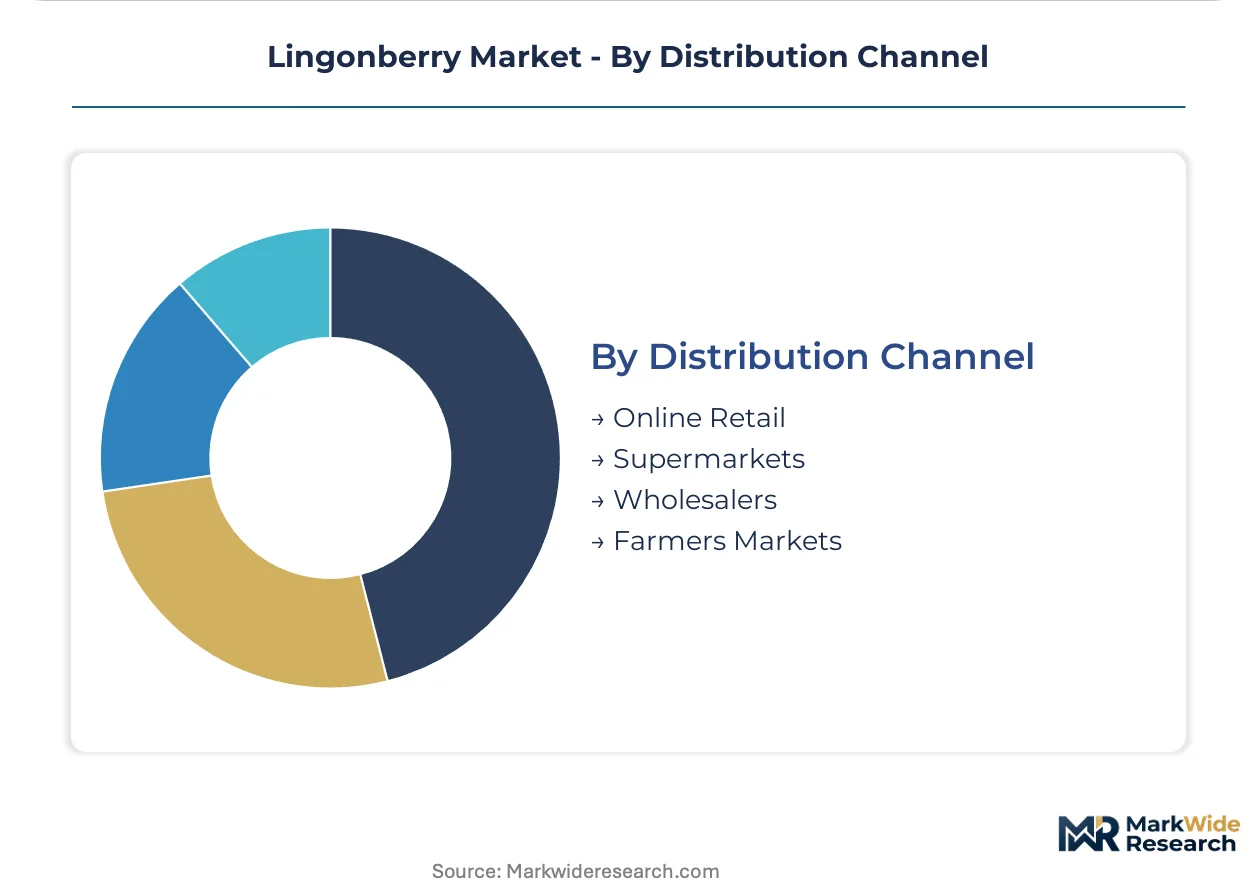
Distribution Channel:
Customer type fragmentation distinguishes procurement behavior between spot-market wholesalers and relationship-bound supermarket buyers, with digital channels emerging as hybrid intermediaries.
- Wholesalers:Nordic berry brokers aggregate harvest volumes from smallholder cooperatives for redistribution to processors. EFSA Regulation 2018/848 geolocation requirements are compressing this tier's viability as compliance costs favor direct processor-harvester relationships.
- Supermarkets:German REWE Group, Austrian SPAR, and Swiss Migros specify organic-certified private-label lingonberry lines with 2-3 year supply commitments. Slotting fees and promotional calendars shape processor cash flow profiles.
- Online Retail:Amazon.de, Nordic niche platforms, and direct-to-consumer portals bypass traditional retail markup layers. Freeze-dried formats and premium jam assortments dominate this channel due to shipping weight optimization.
- Farmers Markets:Seasonal fresh berry sales and artisan-processed value-added products serve local tourism and specialty food circuits. Limited scale constrains organic certification cost recovery.
Wholesalers retain installed base concentration in raw material flows. Online retail is climbing the fastest as logistics infrastructure matures for temperature-sensitive shipments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish exporters dominate raw material flows into German and Swiss nutraceutical channels, while Swedish processors capture premium organic positioning through Metsähallitus permit consolidation. Estonian operators are emerging as volume alternatives with shorter compliance timelines.
Finland
Wild-harvest permit rationalization under Metsähallitus is concentrating commercial rights among certified operators with freezing infrastructure. EFSA Regulation 2018/848 geolocation mandates favor processors with blockchain-integrated traceability systems. The Oulu-Kuopio corridor anchors flash-freezing capacity serving German extraction facilities.
Sweden
Standardized polyphenol extract demand from Swiss pharmaceutical buyers is accelerating low-temperature vacuum drying adoption. The Swedish Food Agency enforces organic certification timelines extending to eighteen months for new entrants. Västerbotten County clusters drying operations serving Stockholm distribution hubs.
Germany
Clean-label jam demand from REWE Group and SPAR Austria is locking processors into multi-year organic supply commitments. The Federal Office of Consumer Protection and Food Safety (BVL) enforces strict benzoic acid labeling thresholds. Hamburg and Bremen ports concentrate import logistics for Nordic frozen berry volumes.
Switzerland
Swissmedic pharmaceutical-grade ingredient specifications are driving sub-40°C drying protocol adoption among Nordic suppliers. Private-label pressure from Migros is compressing margins in conventional jam segments. Basel and Zurich anchor nutraceutical formulation clusters specifying standardized anthocyanin extracts.
Japan
PMDA polyphenol health claim substantiation pathways are creating first-mover positioning for extract suppliers with novel food dossiers. Tokyo and Osaka importers require twelve-to-eighteen-month documentation timelines beyond standard EU export protocols. Convenience store channels specify 100-200 ml aseptic pouch formats.
Lingonberry Market Competitive Landscape
Channel-controlling players compete with product-specialist players across frozen berry, extract, and retail-packaged tiers. Vertically integrated Nordic operators with Metsähallitus permits hold procurement advantages over broker-dependent competitors. Three archetypes dominate: wild-harvest consolidators with certified cold-chain infrastructure, polyphenol extraction specialists serving pharmaceutical-grade buyers, and cranberry infrastructure extenders leveraging adjacent berry capabilities. Competitive moves concentrate on organic certification timeline acceleration and dual FDA-EFSA compliance system installation.
Among Nordic wild-harvest specialists, Kiantama Oy and Eevia Health exemplify divergent positioning strategies. Kiantama Oy anchors the frozen berry volume tier through integrated harvesting and flash-freezing infrastructure. Eevia Health occupies the standardized extract niche serving nutraceutical formulators with polyphenol concentration capabilities. Ocean Spray Cranberries, Inc. represents the infrastructure extension archetype, leveraging established cranberry processing networks into adjacent lingonberry blend categories. These three entities collectively illustrate how procurement architecture, extraction technology, and category adjacency define competitive boundaries.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Loov Food |
| Arla Foods amba |
| Arctic Power Berries |
| Eevia Health |
| Ocean Spray Cranberries, Inc. |
| Artemis |
| Kiantama Oy |
| Döhler GmbH |
| Others |
Supply & Pricing Matrix
The Oulu-Hamburg frozen freight corridor anchors cost dynamics across the lingonberry value chain, where cold-chain expenditure differentials between integrated operators and broker-dependent harvesters directly shape downstream price stratification between pharmaceutical-grade extracts and commodity jam inputs.
Pricing Analysis
Cost-plus contracts indexed to Finnish Metsähallitus permit fees and EU organic certification audit cycles dominate industrial procurement of frozen raw material. Three-tier pricing structure across premium, standard, and economy levels separates Swiss pharmaceutical buyers specifying sub-40°C drying protocols from German private-label jam manufacturers and Nordic food-service spot purchasers. Cost compression in the standard tier intensifies as synthetic benzoic acid substitutes erode clean-label premiums in mass-market applications. Food-service buyers exhibit highest price sensitivity due to seasonal volume volatility, while nutraceutical formulators prioritize standardization consistency over unit cost minimization.
Supply Chain Analysis
Tariff exposure between EU member states and Asian import jurisdictions dominates supply chain risk planning for extract exporters. Raw material concentration rests on Finnish, Swedish, and Estonian boreal forest permits, with flash-freezing infrastructure drawing from specialized Nordic technical institutes and pharmaceutical-grade drying equipment sourced from German and Swiss manufacturers. Single-source vulnerability concentrates in wild-harvest permit holders lacking diversified geography coverage. Distribution runs through Rotterdam and Hamburg port clusters for Asian-bound shipments, with Stockholm and Copenhagen anchoring Nordic domestic flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against synthetic preservative formulations and lower-cost berry extracts that threaten clean-label positioning in price-sensitive jam and beverage segments.
For Market Incumbents: Pre-empt synthetic substitute encroachment by accelerating backward integration into certified cold-chain infrastructure across Finnish Metsähallitus permit zones. Consolidate harvesting cooperatives facing EFSA geolocation compliance cost pressure. Dual FDA-EFSA quality system installation represents the critical defensive lever against emerging Estonian volume competitors with shorter certification timelines. For New Entrants and Emerging Players: Establish a beachhead in Japanese PMDA-registered nutraceutical channels where polyphenol health claim substantiation dossiers create twelve-to-eighteen-month documentation barriers for incumbent extract suppliers. Target South Korean MFDS-compliant distributors with standardized anthocyanin concentrates. Direct-to-industrial platform participation offers the most penetrable go-to-market angle for mid-scale processors lacking established broker relationships. For Investors and Strategic Acquirers: Polyphenol extraction specialists with dual regulatory compliance and blockchain-integrated traceability systems represent the priority acquisition archetype for portfolio positioning across the functional food ingredient convergence. Long-term viability hinges on cultivated berry scaling investments that reduce wild-harvest yield volatility exposure. Monitor PMDA novel food approval timelines as the critical inflection signal for Asian channel penetration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Integrated Traceability Deployment | EFSA Regulation 2018/848 geolocation mandates favor operators with certified digital audit trails from forest to finished good. |
| Sub-40°C Vacuum Drying Scale-Up | Swiss pharmaceutical buyers specify low-temperature protocols that maximize anthocyanin retention for nutraceutical encapsulation. |
| Cultivated Berry Controlled-Environment Investment | Acidic substrate agriculture above 55°N latitude offers yield predictability unavailable in unmanaged boreal harvest systems. |
| PMDA Novel Food Dossier Submission | Japanese polyphenol health claim pathways create first-mover positioning for standardized extract suppliers with documentation readiness. |
| Dual FDA-EFSA Quality System Installation | Simultaneous compliance with dietary supplement cGMP and organic traceability standards unlocks multi-jurisdictional contract eligibility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA regulatory filings, Finnish Metsähallitus harvest permit databases, and Nordic trade association export statistics. Primary interviews engaged wild-berry harvest cooperative managers, flash-freezing facility engineers, nutraceutical procurement directors at German and Swiss formulators, and organic certification auditors. Bottom-up volume modeling from processor capacity utilization triangulates against top-down demand estimates from functional food manufacturer formulation trends.
Forecast inputs incorporate product format segmentation across frozen berries, dried fruits, jams, and standardized extracts; end-user channel stratification between industrial nutraceutical buyers and retail consumers; and packaging tier differentiation from bulk industrial totes through premium glass-jar presentations. CAGR derivation rests on historical volume trajectory analysis adjusted for EFSA organic certification expansion timelines and Asian regulatory pathway maturation. Wild-harvest yield volatility coefficients and cold-chain infrastructure deployment rates constitute industry-specific forecast sensitivity parameters across the projection horizon.
Sensitivities concentrate around PMDA and MFDS approval timeline acceleration, synthetic preservative substitution cost parity thresholds, and Finnish permit rationalization consolidation pace. Forecasts reflect documented assumptions regarding EFSA geolocation mandate enforcement intensity and cultivated berry technology cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Brined Vegetable Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
Asia Pacific Orange Market
Fruits and Vegetables
Israel Fruits and Vegetables Market
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
Mulberry Market
Fruits and Vegetables
Dried Grapes Market
Fruits and Vegetables
Passion Fruit Extract Market
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
APAC Frozen Fruits and Vegetables Market
Fruits and Vegetables
Global Orange Market
Fruits and Vegetables
Mango Puree Market
Fruits and Vegetables
Middle East and Africa Sweet Potatoes Market
Fruits and Vegetables
Basil Leaves Market
Fruits and Vegetables
Dried Kiwi Fruit Market
Fruits and Vegetables
Dried Jujubes Market