
 Global Bean Sprouts Market | 2026-2036
Global Bean Sprouts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bean Sprouts Market Analysis
ISO 22000 certification for sprout-specific hazard control is collapsing the supplier base into fewer qualified operators. Pulmuone leverages captive wash-and-pack facilities to sustain shelf-stable output across Korean retail. Fuji Natural Foods Co., Ltd. anchors premium tray-pack distribution through Tokyo-area supermarket chains. Van der Plas Sprouts dominates European foodservice supply with dedicated hydroponic growing rooms.
Bean sprouts are germinated legume seeds—typically mung bean or soybean—harvested at 3-7 days with hypocotyl lengths of 5-15 cm, valued for crisp texture, protein content, and enzymatic activity in raw or lightly cooked applications. Green Mung Bean sprouts lead volume due to established Asian culinary integration and shorter germination cycles. Restaurant and catering end users represent the fastest-expanding demand pool, while retail bag formats remain the mature margin anchor in conventional grocery.
FDA sprout safety guidelines and China's SAMR fresh produce standards both mandate seed lot testing and irrigation water monitoring, elevating compliance costs for smaller growers. The EU's EFSA baseline studies on sprout-associated pathogens inform member-state inspection frequency. Stakeholders must monitor how seed sourcing traceability requirements reshape procurement geography before committing to capacity expansion.
Market Dynamics
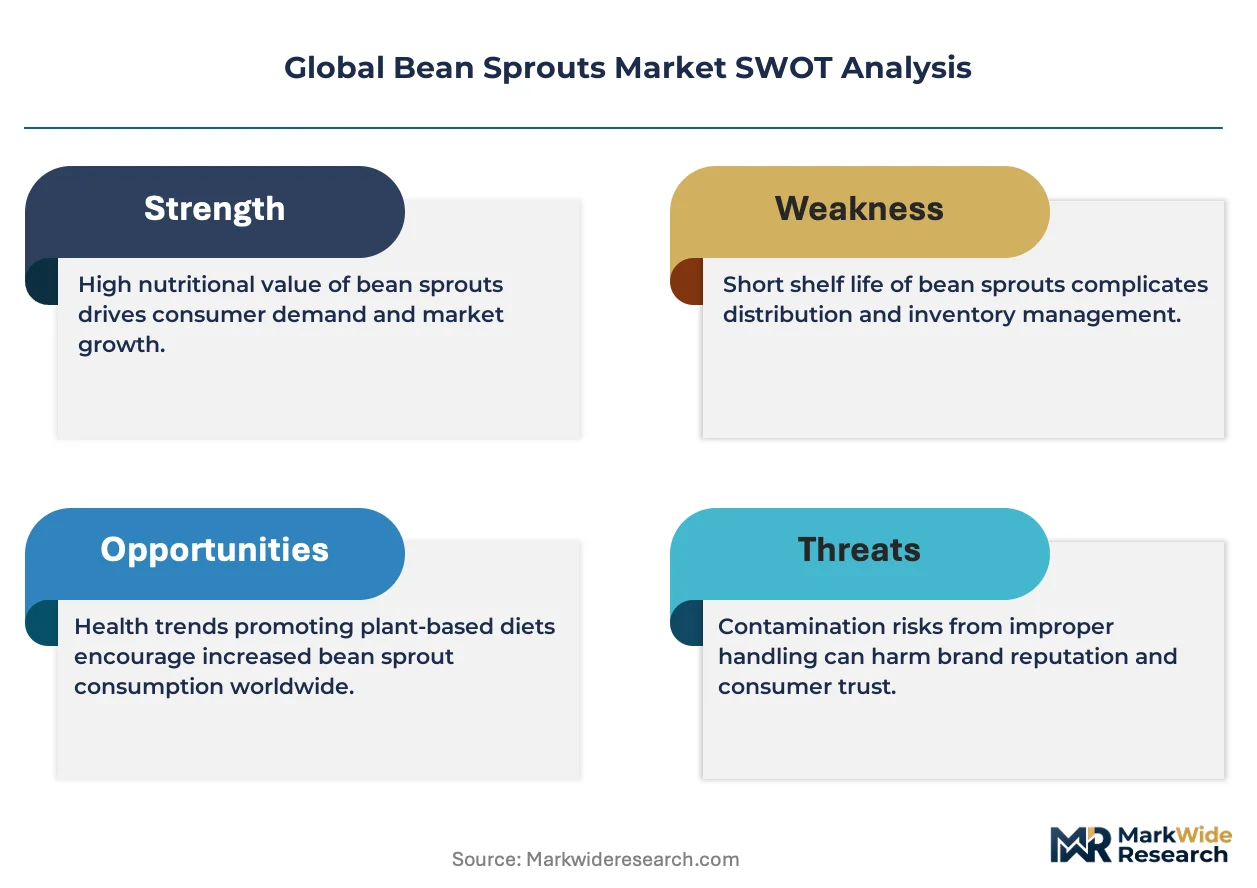
ISO 22000 certification requirements are compressing the supplier base into fewer qualified operators, while East Asian restaurant chains expand sprout-based menu offerings and microbial safety thresholds tighten across major producing jurisdictions.
Growth Catalysts
- East Asian foodservice expansion:Restaurant chains in South Korea and Japan are adding dedicated sprout-based dishes to capture health-conscious diners, creating sustained volume pull through centralized procurement contracts.
- GB standards enforcement:China's SAMR fresh produce standards mandate seed lot testing and irrigation water monitoring, which elevates compliance barriers for informal growers and clears market share for certified operators.
- Enzymatic activity demand:Raw and lightly cooked culinary applications in Vietnamese and Thai street food sectors prize sprout crispness and protein content, reinforcing consumption frequency in established markets.
Market Restraints
- Seed input volatility:Mung bean and soybean seed prices fluctuate with Australian and Canadian pulse harvests, compressing margin predictability for growers without long-term supply contracts.
- Pathogen surveillance intensity:FDA sprout safety guidelines and EFSA baseline studies on sprout-associated pathogens drive inspection frequency increases, raising operational overhead for smaller facilities.
- Short shelf-life economics:The 3-7 day harvest-to-spoilage window forces rapid cold-chain throughput, limiting distribution radius and excluding inland geographies from fresh supply.
Strategic Opportunities
- Vietnamese retail underpenetration:Modern trade expansion in Ho Chi Minh City and Hanoi creates first-mover potential for tray-pack formats in supermarkets still dominated by wet-market loose sales.
- Hydroponic growing convergence:Integration of controlled-environment agriculture with automated irrigation is displacing traditional soil-based methods, enabling year-round output consistency in temperate climates.
- EU organic certification tailwind:The EU Green Deal's farm-to-fork strategy incentivizes reduced pesticide use, aligning with sprout cultivation's minimal chemical input profile and opening premium channel access.
Industry Challenges
- Microbiological control expertise gap:Facilities struggle to recruit technicians proficient in seed sanitization protocols and environmental monitoring for salmonella and E. coli prevention.
- ISO 22000 certification timeline:The 12-18 month accreditation process for sprout-specific hazard control delays market entry for new entrants and expansion for existing players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bean Sprouts Market |
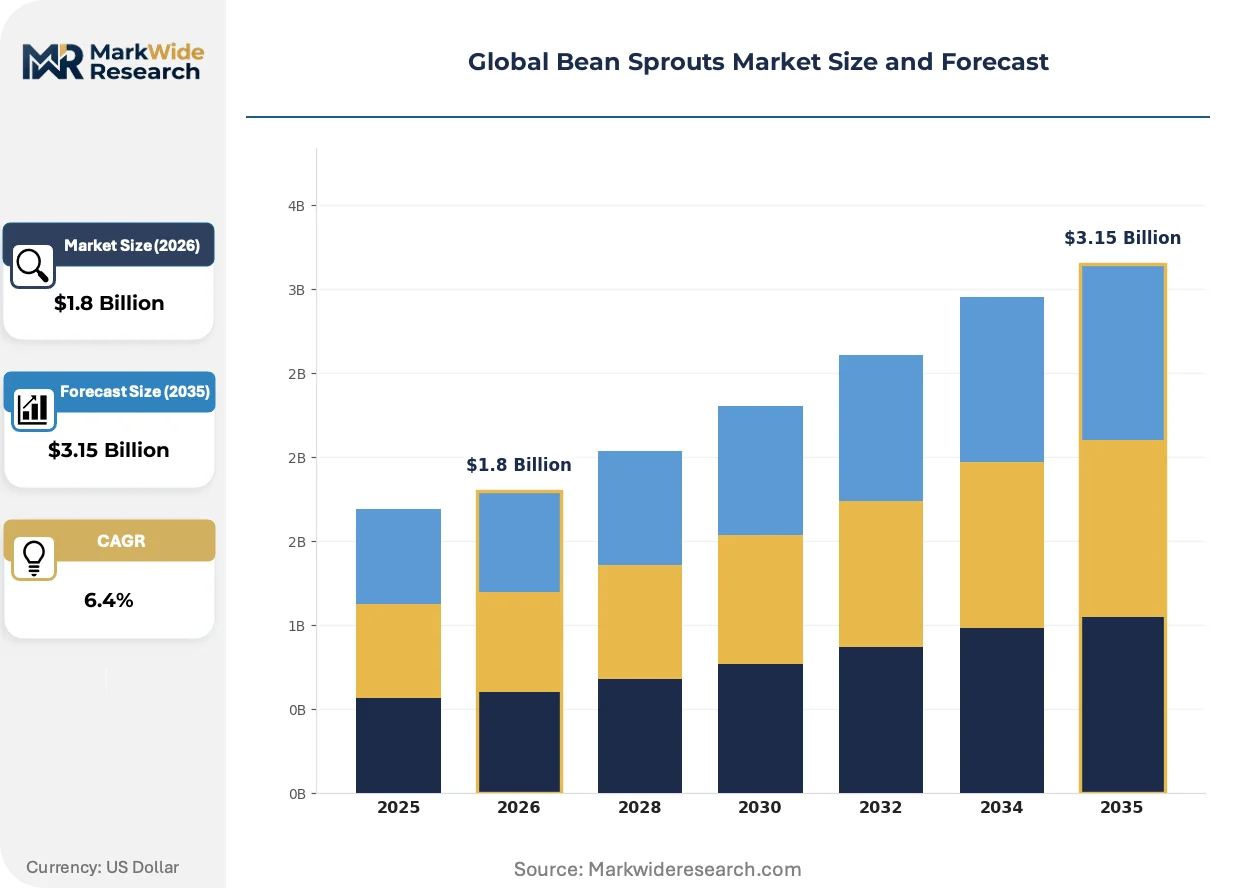
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Mung Bean, Soybean, Pea, Lentil Distribution Channel: Retail Stores, Online Stores, Wholesalers, Farmers' Markets End User: Households, Restaurants, Food Processing Units, Catering Services Packaging Type: Bags, Trays, Plastic Containers, Bulk |
| Companies Covered | Narita Foods, Sun Sprout Enterprises Ltd., Pulmuone, Nanjing Tanshanhu, Van der Plas Sprouts, Fuji Natural Foods Co., Ltd., Mungchi Food Co., Ltd., Anhui Anxin, Daesang, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bean Sprouts Market Emerging Trajectories
Controlled-environment agriculture and automated seed handling are reshaping production economics, while regulatory harmonization pressures and foodservice procurement consolidation rewrite competitive rules across the value chain.
Closed-loop hydroponic growing rooms with automated temperature and humidity control are displacing open-field and greenhouse methods previously dominant in European supply. Dutch and Belgian foodservice distributors are retrofitting dedicated sprout facilities to capture margin from reduced spoilage and labor input. The technology is displacing seasonal production patterns that once forced import dependency during winter months.
REACH chemical safety protocols and the EU's CSRD sustainability disclosure requirements are extending traceability obligations backward to seed suppliers. European sprout processors must now document input origins and water treatment methods for downstream buyers. German and French retail chains are responding by consolidating vendor lists to those with pre-verified compliance documentation.
Centralized procurement by multi-unit restaurant groups is compressing supplier bases and demanding consistent volume contracts with penalty clauses for contamination events. South Korean foodservice channels are leading this shift, with national chains replacing fragmented local sourcing. The behavioral pivot is most visible in Seoul's franchise restaurant density, where single-source sprout supply agreements now cover hundreds of outlets.
Global Bean Sprouts Market Segmentation
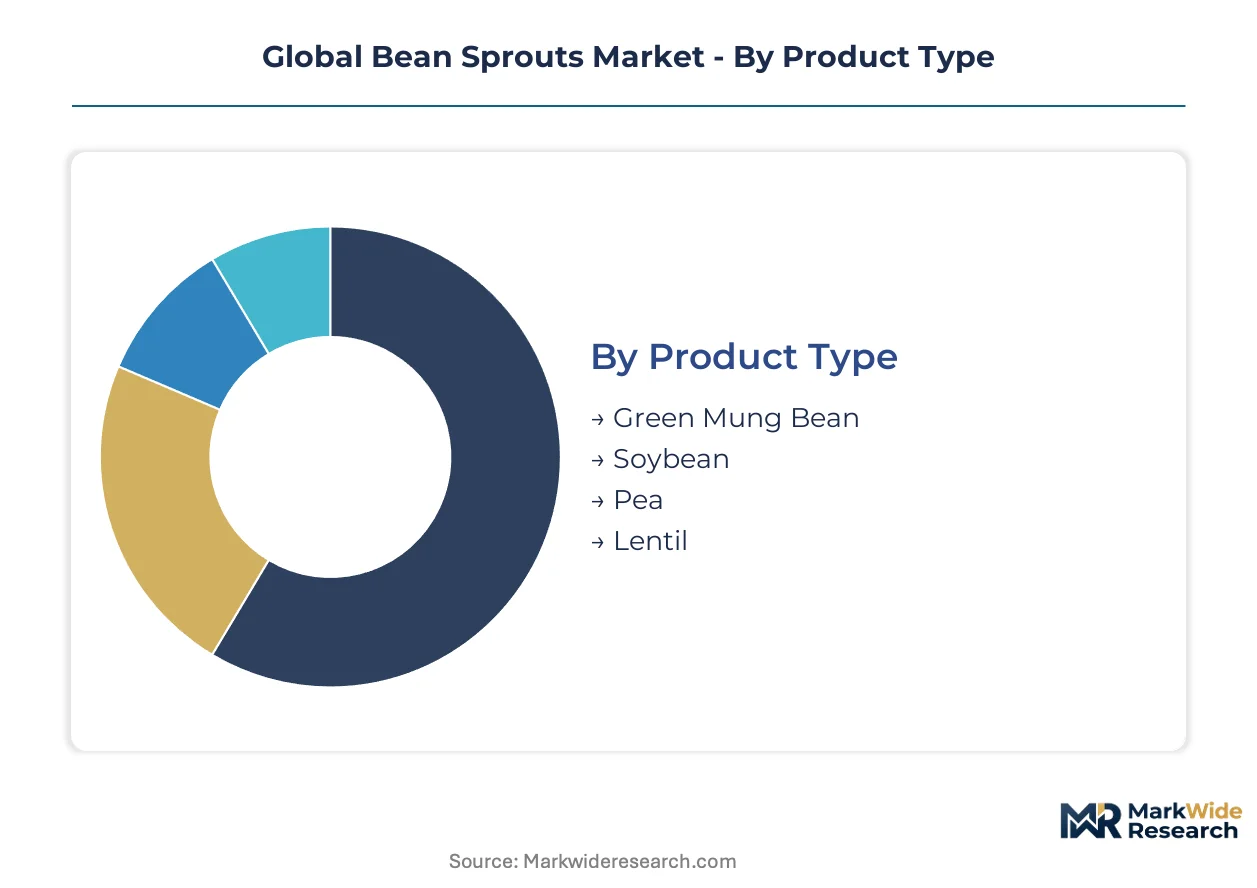
Bean sprout segmentation reveals how product characteristics dictate channel economics and regulatory exposure. Each dimension carries distinct margin profiles, shelf-life constraints, and certification requirements that reshape competitive positioning across supply chains.
Product Type:
Green Mung Bean sprouts flow predominantly through Asian foodservice channels, while Soybean variants concentrate in Korean retail and North American health-food segments.
- Green Mung Bean:These 5-15 cm hypocotyls germinate in 3-5 days, delivering crisp texture optimized for raw Vietnamese pho garnishes and Thai stir-fry applications. Seoul's franchise restaurant networks now specify Green Mung Bean for standardized bowl presentations, though China's SAMR microbial testing mandates compress supplier qualification timelines.
- Soybean:Larger cotyledons and denser protein content suit Korean jjigae stews and Japanese hot pot formats. Pulmuone's captive wash-and-pack facilities in South Korea anchor retail tray-pack distribution, while FDA seed lot testing requirements elevate compliance costs for US-bound shipments.
- Pea:Sweet flavor profile and tender shoot texture command premium positioning in European organic retail channels aligned with EU Green Deal farm-to-fork incentives.
- Lentil:Earthier taste and firmer bite attract North American plant-based protein formulations and specialty salad kit inclusion.
By volume, Green Mung Bean leads. By growth pace, Soybean is climbing the fastest.
Distribution Channel:
Channel selection determines cold-chain investment intensity and traceability documentation depth, with foodservice procurement consolidation favoring direct wholesale relationships over fragmented retail intermediation.
- Retail Stores:Tokyo-area supermarket chains demand ISO 22000-certified tray-pack formats with 7-day shelf-life guarantees. Fuji Natural Foods anchors this channel through dedicated hydroponic output, though REACH chemical safety protocols now extend documentation burdens backward to seed suppliers.
- Wholesalers:European foodservice distributors in the Netherlands and Belgium retrofit dedicated growing rooms to capture margin from reduced spoilage and year-round consistency. Van der Plas Sprouts dominates this channel with automated temperature-controlled facilities displacing seasonal import dependency.
- Online Stores:Direct-to-consumer subscription models in South Korea bundle sprout varieties with recipe kits, though 3-7 day harvest-to-spoilage windows force rapid fulfillment infrastructure.
- Farmers' Markets:Loose sales persist in Vietnamese wet markets and Southeast Asian street vendor supply, bypassing formal certification but facing tightening GB standards enforcement in cross-border trade.
Wholesalers capture the steepest expansion trajectory as restaurant procurement centralizes. Retail Stores retain the mature margin anchor.
End User:
End-use differentiation separates high-frequency raw consumption from processed ingredient applications, with enzymatic activity requirements driving specification divergence.
- Restaurants:East Asian chains in Seoul and Tokyo add dedicated sprout-based dishes to capture health-conscious diners, creating sustained volume pull through centralized contracts with contamination penalty clauses.
- Households:Bag formats in conventional grocery remain the volume foundation, particularly in Chinese urban retail where SAMR fresh produce standards elevate barriers for uncertified suppliers.
- Food Processing Units:Flash-frozen and dehydrated applications for ready-meal manufacturing demand consistency specifications that hydroponic methods increasingly satisfy.
- Catering Services:Institutional volume contracts in South Korea's corporate dining sector specify single-source supply agreements covering hundreds of outlets.
Restaurants are gaining share fastest. Households maintain absolute volume dominance.
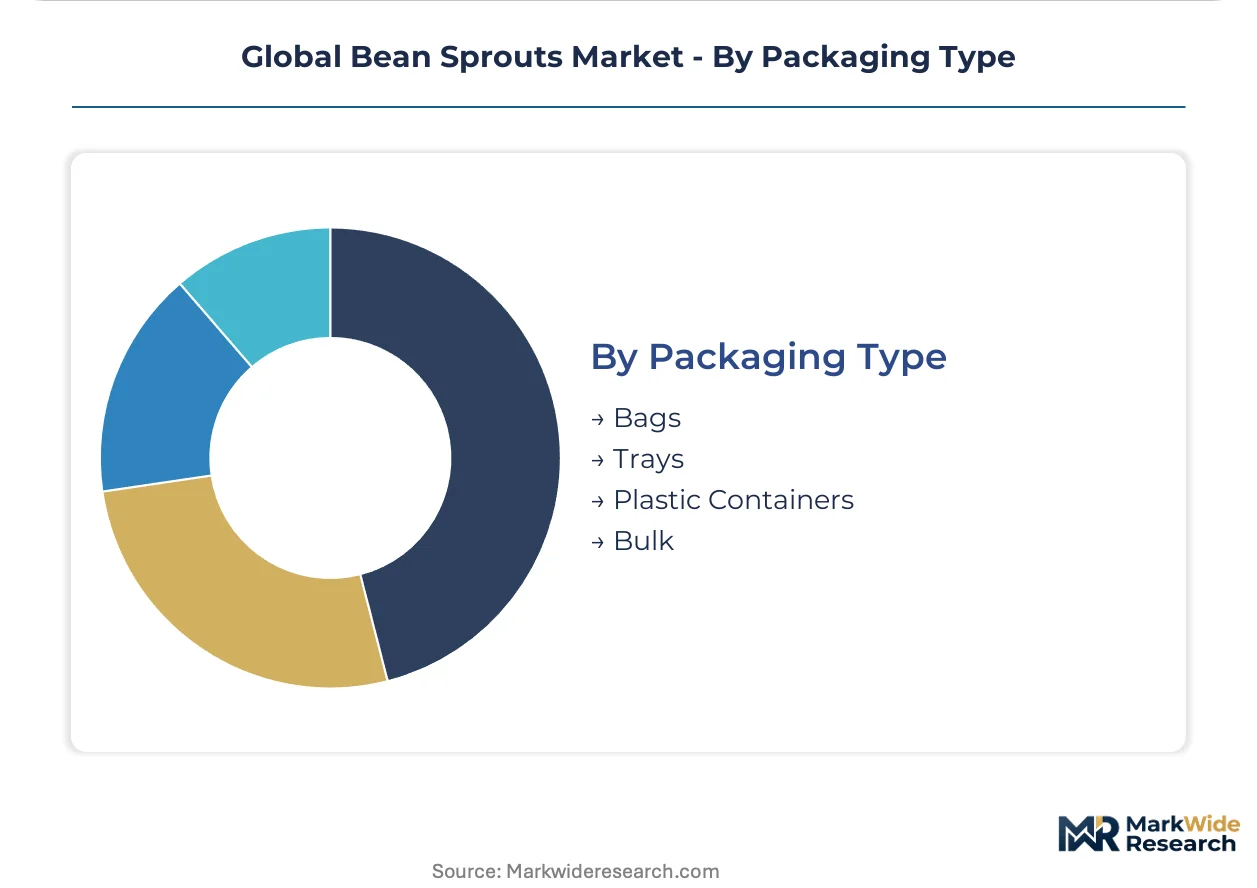
Packaging Type:
Packaging economics balance shelf-life extension against material cost and regulatory compliance, with premium formats capturing certification-driven price differentiation.
- Trays:Modified atmosphere packaging extends retail shelf life to 10-14 days, enabling Tokyo supermarket premium placement and EU organic certification channel access.
- Bags:Perforated polyethylene dominates Vietnamese and Thai wet-market distribution, though microbial safety threshold tightening pressures format upgrade.
- Plastic Containers:Rigid clamshells protect hypocotyl integrity in North American e-commerce fulfillment, absorbing higher material costs for damage reduction.
- Bulk:Foodservice tote systems minimize unit economics for high-throughput restaurant chains, though traceability documentation gaps create regulatory exposure.
Trays command premium positioning. Bags retain volume leadership in emerging market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foodservice procurement consolidation concentrates buyer power in East Asian metropolitan clusters, while retail modernization in Southeast Asia and regulatory tightening in Europe reshape supplier qualification requirements across distinct national frameworks.
China
Seoul-based restaurant chains source standardized sprout volumes through centralized contracts, though China's SAMR fresh produce standards now mandate seed lot testing and irrigation water monitoring for cross-border suppliers. GB standards enforcement elevates compliance barriers for informal growers in Shandong and Jiangsu provinces. Yangtze River Delta processing clusters near Nanjing and Shanghai are retrofitting captive wash-and-pack facilities to meet microbial safety thresholds.
South Korea
Franchise restaurant density in Seoul drives single-source supply agreements covering hundreds of outlets with contamination penalty clauses. MFDS enforcement of HACCP protocols for fresh-cut produce compresses supplier qualification timelines. Busan-Ulsan logistics corridors anchor cold-chain distribution infrastructure for tray-pack retail formats penetrating conventional grocery.
Japan
Tokyo-area supermarket chains demand ISO 22000-certified tray-pack formats with 7-day shelf-life guarantees, creating premium channel segmentation. METI guidelines on agricultural chemical residues in fresh produce inform retailer procurement specifications. Kanto region hydroponic facilities displace seasonal import dependency through year-round controlled-environment output.
Netherlands
Belgian and Dutch foodservice distributors retrofit dedicated sprout growing rooms to capture margin from reduced spoilage and labor input. EFSA baseline studies on sprout-associated pathogens drive inspection frequency increases across member-state enforcement. Rotterdam-Antwerp logistics clusters concentrate EU organic certification processing for premium retail channel access.
Vietnam
Modern trade expansion in Ho Chi Minh City and Hanoi creates first-mover potential for tray-pack formats in supermarkets still dominated by wet-market loose sales. Street vendor supply chains bypass formal certification but face tightening cross-border microbial safety thresholds. Mekong Delta growing regions supply raw material for flash-frozen export processing.
Global Bean Sprouts Market Vendor Landscape
Player mix skews toward vertically integrated food conglomerates with captive agricultural operations and specialized sprout processors with dedicated hydroponic infrastructure. Market structure exhibits tiered consolidation where ISO 22000 certification compresses the qualified supplier base into fewer operators capable of meeting foodservice procurement specifications. Strategic archetypes include conglomerate-affiliated processors leveraging backward integration into seed sourcing, independent specialists concentrating on premium organic certification channels, and regional distributors retrofitting controlled-environment facilities. Dominant competitive moves encompass M&A activity targeting captive wash-and-pack capabilities and strategic partnerships with seed suppliers to secure long-term input contracts.
Among East Asian conglomerates, Pulmuone and Daesang occupy positions representing integrated food processing scale, while Fuji Natural Foods Co., Ltd. exemplifies premium-tier specialization through dedicated hydroponic output. Van der Plas Sprouts anchors European foodservice supply with automated temperature-controlled facilities. These named entities serve as archetype anchors for understanding how geographic origin and corporate structure map to competitive positioning within certification-tiered market segmentation.
| Leading Market Players |
|---|
| Narita Foods |
| Sun Sprout Enterprises Ltd. |
| Pulmuone |
| Nanjing Tanshanhu |
| Van der Plas Sprouts |
| Fuji Natural Foods Co., Ltd. |
| Mungchi Food Co., Ltd. |
| Anhui Anxin |
| Daesang |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with Korean foodservice chains lock in seed supply access and price visibility across volatile Australian and Canadian pulse harvests. These agreements insulate certified operators from spot market swings while committing buyers to volume minimums with contamination penalty clauses.
Pricing Analysis
Cost-plus contracts with mung bean indexation dominate procurement between East Asian processors and seed suppliers. Three-tier pricing structure across ISO 22000-certified premium, HACCP-compliant standard, and uncertified economy levels separates Pulmuone's tray-pack retail formats from wet-market loose sales. Cost compression in the economy tier is intensifying because China's SAMR microbial testing mandates force format upgrades. Household buyers in Vietnamese wet markets exhibit highest price sensitivity, while Tokyo-area supermarket chains accept premium positioning for 7-day shelf-life guarantees.
Supply Chain Analysis
China and South Korea anchor fresh sprout processing capacity, with Dutch and Belgian distributors retrofitting dedicated hydroponic facilities for European foodservice. Production draws from Australian and Canadian mung bean seed inputs, with irrigation water treatment systems representing critical capital requirements. Single-source vulnerability concentrates in Seoul's franchise restaurant networks where single suppliers cover hundreds of outlets. Distribution runs through Busan-Ulsan cold-chain corridors for Korean retail and Rotterdam-Antwerp logistics clusters for EU organic certification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 22000 certification timelines and microbiological control expertise gaps constrain qualified supplier expansion, creating durable positioning for operators with accredited hazard control systems and captive wash-and-pack infrastructure.
For Market Incumbents: Secure backward integration into seed sourcing through long-term supply contracts with Australian and Canadian pulse growers to buffer margin volatility from harvest fluctuations. Expand tray-pack capacity in Vietnamese modern trade channels before wet-market format upgrades accelerate. Defend against emerging hydroponic specialists by accelerating automation investment in controlled-environment growing rooms. For New Entrants and Emerging Players: Lead with Vietnamese retail underpenetration where supermarket expansion in Ho Chi Minh City and Hanoi outpaces certified supplier presence. Target foodservice procurement consolidation in South Korea's corporate catering sector with single-source volume proposals. Establish differentiated positioning through EU organic certification alignment with farm-to-fork incentive structures. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap processors with captive wash-and-pack capabilities and existing ISO 22000 accreditation, avoiding the 12-18 month market entry delay. Long-term viability hinges on hydroponic infrastructure ownership enabling year-round output consistency. Watch for seed lot testing mandate expansion beyond China into Southeast Asian cross-border trade as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22000 Certification Investment | Twelve-to-eighteen month accreditation process collapses supplier base into qualified operators capable of Seoul foodservice contracts. |
| Captive Seed Sourcing Contracts | Long-term offtake agreements with Australian and Canadian growers buffer margin volatility from pulse harvest fluctuations. |
| Hydroponic Facility Retrofit | Automated temperature-controlled growing rooms displace seasonal import dependency in Dutch and Belgian foodservice supply. |
| Tray-Pack Format Expansion | Modified atmosphere packaging extends shelf life for Tokyo supermarket premium placement and EU organic channel access. |
| Vietnamese Modern Trade Entry | First-mover positioning in Ho Chi Minh City and Hanoi supermarkets captures format upgrade ahead of wet-market displacement. |
Methodological Framework
A standing panel of sprout processing facility managers, Korean foodservice procurement directors, seed supplier agronomists, and EU organic certification auditors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with hydroponic equipment vendors and cold-chain logistics operators against secondary validation through FDA sprout safety guidance documents, China's SAMR fresh produce standards, EFSA baseline pathogen studies, and MFDS HACCP enforcement records. Bottom-up volume modeling from individual facility throughput triangulated against top-down trade flow analysis.
Consistency checks validated volume and value outputs against customs data for mung bean seed imports and supermarket scanner data from Tokyo-area chains across the projection horizon. Segmentation modeling incorporated product type, distribution channel, end user, and packaging format dimensions with geographic regulatory cluster differentiation. CAGRs were derived from trend extrapolation of foodservice procurement consolidation and retail format upgrade patterns, with seed price volatility and microbial safety threshold tightening as key sensitivity inputs.
The analysis sits within stated boundaries; outcomes outside sustained East Asian restaurant chain expansion or accelerated GB standards enforcement would require recalibration. Forecasts reflect documented assumptions regarding hydroponic adoption rates and certification timeline stability. Recalibration cycles align with material shifts in seed input pricing, regulatory harmonization pressures, or foodservice procurement centralization velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Europe Dried Mushroom Market
Fruits and Vegetables
Global Banana Market
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
North America Fruits & Vegetables Market
Fruits and Vegetables
United Kingdom Berries Market
Fruits and Vegetables
Edible Flowers Market
Fruits and Vegetables
Global Shiitake Mushroom Market
Fruits and Vegetables
Cranberries Market
Fruits and Vegetables
Global IQF Fruits Market
Fruits and Vegetables
Israel Fruits and Vegetables Market
Fruits and Vegetables
Fruit and Vegetable Pulp Market
Fruits and Vegetables
Asia-Pacific Sweet Potatoes Market
Fruits and Vegetables
Fresh Fruits Market
Fruits and Vegetables
Asia-Pacific Fruit and Vegetable Ingredient Market
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
North America Olive Market