
 Israel Fruits and Vegetables Market | 2026-2036
Israel Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Fruits and Vegetables Market Foresight
The gap between premium greenhouse tomatoes and open-field commodity produce is restructuring Israel's horticultural supply chain. Strauss Group leverages its cold-chain logistics to dominate branded salad and fresh-cut categories in domestic retail. Mehadrin anchors export-grade citrus operations with strict phytosanitary protocols for European supermarket chains. Fresh Fruit Robotics differentiates through autonomous harvesting platforms that reduce labor dependency in peak seasons.
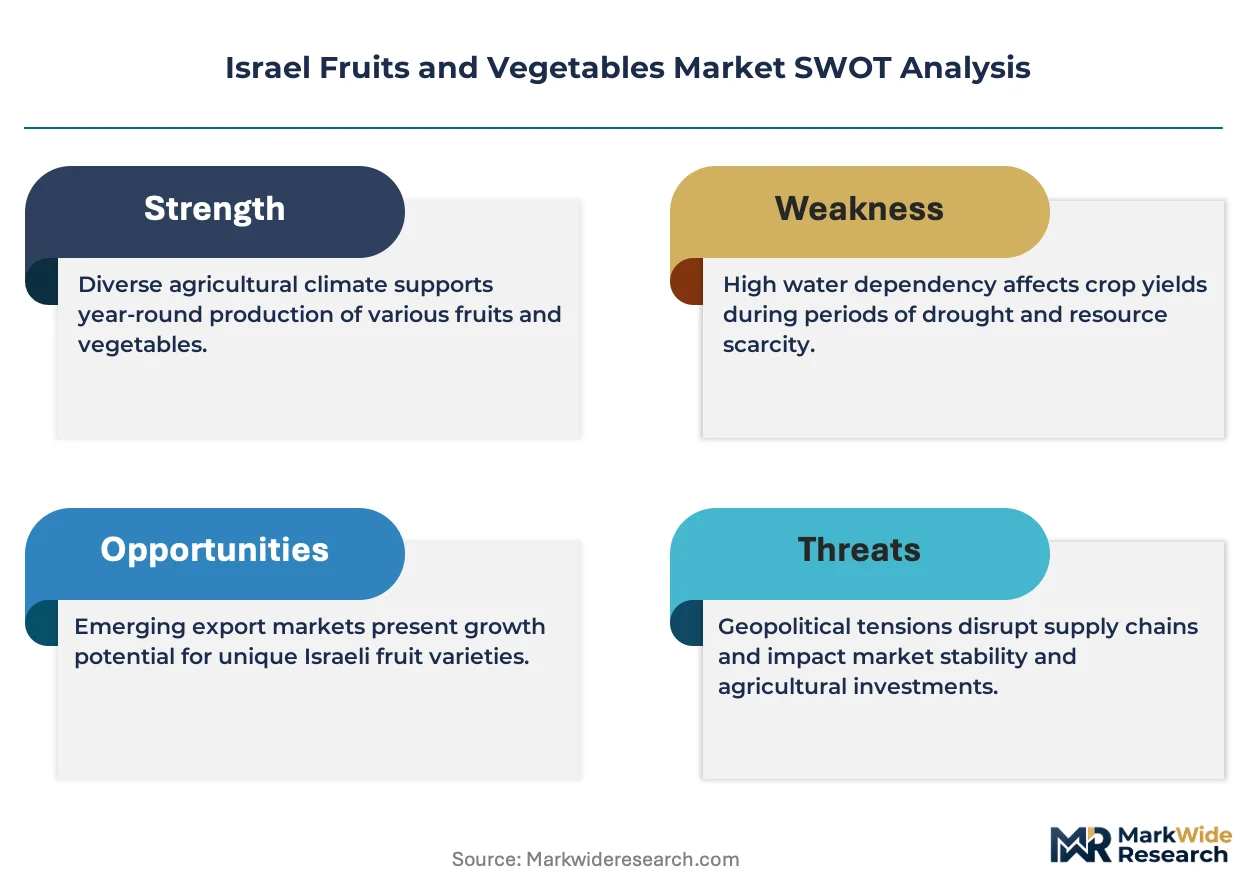
Israel fruits and vegetables encompass fresh and minimally processed plant products cultivated across controlled-environment greenhouses, open fields, and hydroponic installations, with shelf-life extension achieved through post-harvest cooling within four hours of picking and precision moisture management. The primary commercial purpose is to supply raw nutrition inputs for direct consumption, foodservice preparation, and downstream processing into juices, preserves, and frozen formulations. Citrus Fruits sustain the largest export revenue pool through established EU and Russian trade corridors, while Berries occupy the fastest-expanding domestic segment driven by health-conscious urban consumers. Sustainable Packaging is concentrating investment as Israeli retailers face tightening municipal waste regulations and consumer backlash against single-use plastics.
The Plant Protection and Inspection Services of Israel's Ministry of Agriculture enforces phytosanitary export standards aligned with EU directive 2000/29/EC, while the Israel Standards Institute certifies organic production under regulations equivalent to USDA NOP and EU 2018/848. These frameworks shape market access by determining which growers qualify for premium European retail slots and which remain confined to lower-margin domestic fresh markets. Stakeholders must monitor how proposed amendments to the Plant Protection Law will alter pesticide residue thresholds for export-bound Berries and Leafy Greens.
Market Dynamics
Drip irrigation alumni networks from Netafim are diffusing precision agriculture expertise across Israel's Central District greenhouse clusters, compressing yield variance and reconfiguring procurement relationships between growers and retail chains.
Growth Catalysts
- Controlled-Environment Agriculture Expansion:Greenhouse complexes near Rehovot and Rishon LeZion deploy advanced climate control systems that extend growing seasons and stabilize supply volumes for restaurant chain contracts.
- EU Directive 2000/29/EC Alignment:Israeli phytosanitary certification under the Plant Protection and Inspection Services opens premium retail slots in European supermarket chains, commanding price premiums for export-grade citrus.
- Autonomous Harvesting Adoption:Robotics platforms reduce peak-season labor dependency in berry operations, cutting per-unit harvest costs while maintaining fruit integrity for fresh-cut processing.
Market Restraints
- Water Input Volatility:National water allocation quotas from the Israel Water Authority constrain hectare expansion for open-field producers during drought cycles.
- Phytosanitary Compliance Friction:Pending amendments to the Plant Protection Law threaten to tighten pesticide residue thresholds for export-bound leafy greens, disqualifying marginal growers from EU access.
- Single-Use Plastic Substitution Pressure:Municipal waste regulations and consumer backlash accelerate packaging cost inflation without fully viable biodegradable alternatives at scale.
Strategic Opportunities
- Negev Desert Hydroponic Development:Underutilized arid land in Israel's southern district offers expansion terrain for solar-powered vertical farming installations with closed-loop water systems.
- Organic Certification Equivalence:Israel Standards Institute alignment with EU 2018/848 and USDA NOP creates regulatory tailwind for growers transitioning to certified organic production for dual-market access.
- Direct Restaurant Sourcing Channels:Traceability demands from Israeli restaurant chains enable bypass of traditional wholesale layers, capturing margin through farm-to-table logistics investments.
Industry Challenges
- Agronomic Robotics Integration:Autonomous harvesting platforms require retraining programs for existing field crews on equipment calibration and maintenance protocols.
- Post-Harvest Cold-Chain Capex:Four-hour cooling mandates from picking to storage necessitate infrastructure investment that strains smallholder balance sheets.
- Multi-Standard Certification Timelines:Simultaneous compliance with EU, USDA, and domestic organic frameworks extends approval cycles and defers revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Fruits and Vegetables Market |
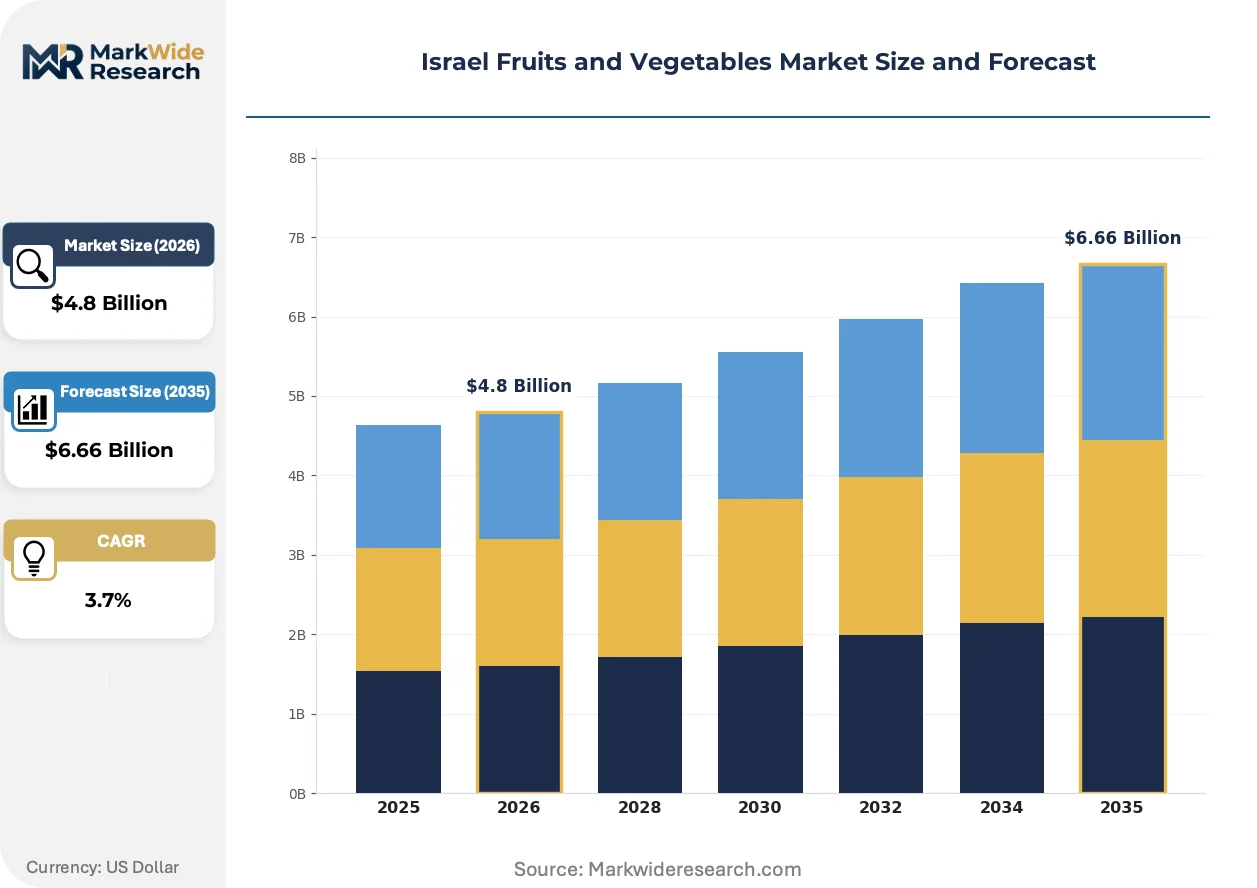
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus Fruits, Leafy Greens, Root Vegetables, Berries Packaging Type: Bulk, Retail Packs, Sustainable Packaging, Modified Atmosphere Distribution Channel: Supermarkets, Fresh Markets, Online Retail, Export End User: Households, Restaurants, Food Processing, Retailers |
| Companies Covered | Strauss Group, Zanlakol, Mehadrin, Fresh Fruit Robotics, Tevel Aerobotics Technologies, Hazera, Osem, ClariFruit, Tnuva, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Fruits and Vegetables Market Shifts & Advancements
Precision moisture management and post-harvest automation are compressing spoilage windows and enabling new distribution formats across Israel's horticultural supply chain.
Sensor-driven irrigation scheduling is decentralizing water management authority from centralized district cooperatives to individual greenhouse operators. Mid-scale tomato producers in the Rehovot corridor deploy soil-moisture telemetry that triggers valve actuation without agronomist intervention. This shift fragments historical procurement power held by regional water boards and accelerates farm-level experimentation with deficit irrigation protocols.
The Plant Protection Law amendments under Ministry of Agriculture review are tightening maximum residue limits for export-bound produce categories. Berry and leafy green operations face expanded laboratory testing obligations and extended pre-shipment quarantine holds. Growers with integrated pest management documentation systems capture preferential treatment from EU import inspectors, while conventional chemical-dependent farms confront slot loss.
Restaurant chain procurement departments now mandate blockchain-traceable sourcing certificates for local produce contracts. Fresh-cut salad suppliers to Strauss Group retail networks must demonstrate field-to-shelf temperature logging within two-degree variance. This behavioral shift concentrates supplier qualification work among logistics-capable mid-tier growers and excludes open-field commodity producers lacking cold-chain infrastructure.
Israel Fruits and Vegetables Market Segmentation
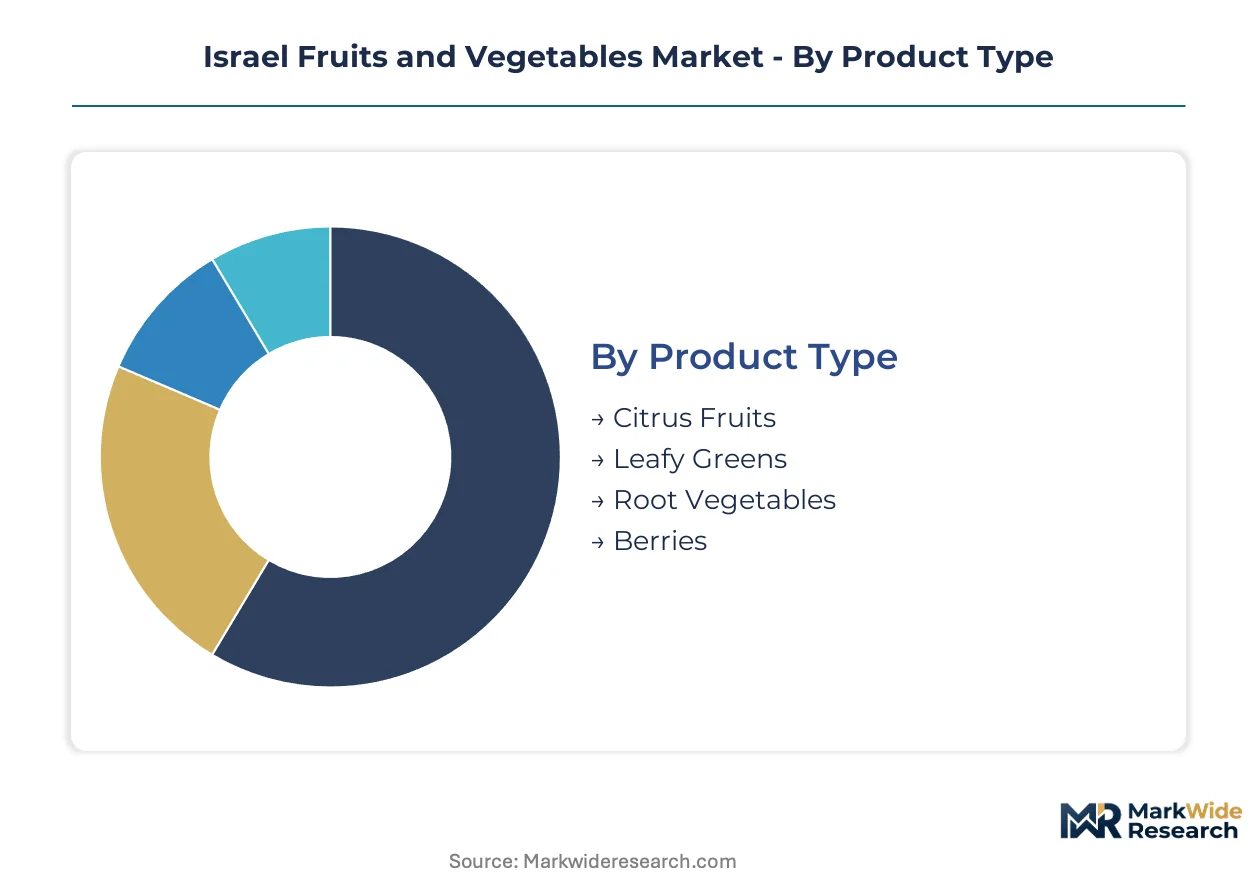
Segmentation reveals how Israeli horticultural supply chains bifurcate between export-grade certification tracks and domestic freshness-driven procurement. Understanding these divides exposes where margin concentrates and which infrastructure investments determine competitive survival.
Product Type:
Upgrade cycles in Israeli horticulture trace from commodity open-field production toward controlled-environment premiumization, with cultivar replacement and greenhouse retrofitting accelerating varietal turnover.
- Citrus Fruits:Oranges, grapefruits, and easy-peelers dominate export revenue through EU and Russian trade corridors. Mehadrin and similar operators anchor this segment with strict phytosanitary protocols that secure supermarket shelf space in Germany, France, and the Netherlands.
- Berries:Strawberry, blueberry, and raspberry cultivation expands fastest in Central District greenhouse clusters near Rehovot. Fresh Fruit Robotics deploys autonomous harvesting platforms here to reduce peak-season labor dependency while maintaining fruit integrity for fresh-cut processing.
- Leafy Greens:Lettuce, spinach, and kale operations face tightening pesticide residue thresholds under proposed Plant Protection Law amendments.
- Root Vegetables:Carrots, potatoes, and sweet potatoes supply domestic food processing and institutional foodservice with lower per-unit handling costs.
Citrus Fruits sits at the top of the volume ranking, with Berries climbing the fastest.
Packaging Type:
Cost tier differentiation separates bulk commodity handlers from premium-positioned operators investing in shelf-life extension technologies.
- Bulk:Loose produce in bins and crates serves institutional buyers and fresh market wholesalers with minimal handling overhead. Open-field root vegetable producers dominate this tier, accepting margin compression for volume throughput to food processing facilities.
- Retail Packs:Pre-weighed bags and clamshells command supermarket placement through barcode traceability and standardized SKUs. Strauss Group leverages cold-chain logistics to dominate branded salad and fresh-cut categories in this tier.
- Sustainable Packaging:Compostable trays and cellulose films respond to municipal waste regulations and consumer backlash against single-use plastics. Investment concentrates here as biodegradable alternatives achieve partial scale.
- Modified Atmosphere:Gas-flushed films extend berry and leafy green shelf life for export logistics, requiring precision moisture management infrastructure.
Bulk retains the largest shipment volumes, though Sustainable Packaging gains share fastest as regulatory pressure intensifies.
Distribution Channel:
Customer type fragmentation splits procurement between traceability-demanding restaurant chains and price-sensitive household segments.
- Supermarkets:Shufersal, Rami Levy, and similar chains demand blockchain-traceable sourcing certificates with field-to-shelf temperature logging. This channel concentrates supplier qualification among logistics-capable mid-tier growers.
- Fresh Markets:Traditional wholesale layers in Tel Aviv, Haifa, and Jerusalem serve price-conscious consumers with minimal cold-chain infrastructure. Open-field commodity producers lacking certification access dominate here.
- Online Retail:Quick-commerce platforms and subscription box services require four-hour post-harvest cooling compliance that strains smallholder balance sheets.
- Export:EU-bound shipments through Ashdod and Haifa ports depend on Plant Protection and Inspection Services certification aligned with directive 2000/29/EC.
Supermarkets anchor volume throughput, while Online Retail expands most quickly with urban consumer adoption.
End User:
Application-driven demand splits between direct consumption, foodservice preparation, and downstream processing into juices, preserves, and frozen formulations.
- Households:Health-conscious urban consumers drive berry and organic leafy green demand through retail channels. This segment rewards premium positioning and transparent provenance marketing.
- Restaurants:Israeli restaurant chains now mandate local sourcing with complete traceability documentation. Farm-to-table logistics investments enable bypass of traditional wholesale layers for margin capture.
- Food Processing:Juice, preserve, and frozen formulation facilities procure root vegetables and citrus in bulk volumes with lower per-unit quality specifications.
- Retailers:Strauss Group and similar operators integrate backward into controlled-environment agriculture to secure supply for private-label fresh-cut lines.
Households represent the largest addressable base, with Restaurants gaining share fastest as traceability requirements reshape procurement relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Netafim alumni networks concentrate precision agriculture expertise in Israel's Central District, diffusing drip irrigation innovations across greenhouse clusters near Rehovot and Rishon LeZion.
Central District
Controlled-environment agriculture complexes anchor domestic berry and leafy green supply for restaurant chain contracts. The Plant Protection and Inspection Services enforces phytosanitary standards aligned with EU directive 2000/29/EC. Greenhouse operators near Rehovot deploy sensor-driven irrigation scheduling that fragments historical procurement power held by regional water boards.
Southern District
Negev Desert arid land offers expansion terrain for solar-powered vertical farming with closed-loop water systems. Israel Water Authority national allocation quotas constrain hectare expansion for open-field producers during drought cycles. Hydroponic installations near Beersheba experiment with deficit irrigation protocols enabled by farm-level telemetry autonomy.
Haifa District
Port infrastructure at Haifa handles EU-bound citrus shipments requiring strict phytosanitary certification. Mehadrin anchors export-grade operations here with protocols securing supermarket shelf space in Germany and France. Cold-chain logistics investments concentrate near the port to satisfy four-hour post-harvest cooling mandates.
Tel Aviv District
Urban consumer density drives quick-commerce platform adoption for fresh-cut and organic produce categories. Municipal waste regulations accelerate packaging cost inflation without fully viable biodegradable alternatives at scale. Restaurant procurement departments in Tel Aviv mandate blockchain-traceable sourcing certificates that bypass traditional wholesale layers.
Israel Fruits and Vegetables Market Competitive Landscape
Top-tier vendors anchor branded retail and export-grade citrus operations, while mid-scale greenhouse specialists and robotics developers occupy fragmented technology niches. The market structures around three archetypes: integrated food conglomerates with cold-chain logistics, export-focused citrus operators with phytosanitary compliance infrastructure, and autonomous harvesting technology vendors reducing labor dependency. Competitive moves concentrate on backward integration into controlled-environment agriculture and strategic partnerships with restaurant chains for direct sourcing relationships.
Among Israel-based food conglomerates, Strauss Group and Tnuva exemplify the integrated retail archetype through cold-chain dominance in branded fresh-cut categories. Mehadrin occupies a position representing the export-grade citrus specialist tier, while Fresh Fruit Robotics sits within the agricultural automation segment developing autonomous harvesting platforms. These three anchors illustrate how competitive positioning splits between supply security through vertical control and labor cost reduction through robotics adoption.
| Leading Market Players |
|---|
| Strauss Group |
| Zanlakol |
| Mehadrin |
| Fresh Fruit Robotics |
| Tevel Aerobotics Technologies |
| Hazera |
| Osem |
| ClariFruit |
| Tnuva |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between export-bound EU-compliant produce and domestic fresh-market commodities splits Israeli horticulture into parallel pricing regimes with distinct supply chain architectures. Premium greenhouse operators near Rehovot command price premiums through cold-chain investments that satisfy supermarket traceability mandates, while open-field root vegetable growers accept thinner margins serving wholesale layers lacking temperature-controlled infrastructure.
Pricing Analysis
Unbundled cold-chain services versus bundled farm-to-retail contracts define the dominant pricing split. Three-tier pricing structure across premium, standard, and economy levels tracks certification investment: EU-grade citrus with Plant Protection and Inspection Services documentation captures supermarket placement premiums, domestic retail-grade produce competes on freshness metrics, and bulk commodity shipments to food processors trade on volume scale. Cost compression in the economy tier is intensifying because municipal waste regulations accelerate packaging cost inflation without biodegradable alternatives at commercial scale. Food processing buyers exhibit highest price sensitivity, while restaurant chains sourcing through direct farm partnerships demonstrate lowest sensitivity to per-unit premiums.
Supply Chain Analysis
Water input supply rests on Israel Water Authority national allocation quotas that constrain hectare expansion during drought cycles. Precision irrigation equipment draws from Netafim alumni networks diffusing across Central District greenhouse clusters, while phytosanitary certification services hinge on Ministry of Agriculture laboratory capacity. Single-source vulnerability concentrates in the four-hour post-harvest cooling infrastructure gap facing smallholder operations. Distribution runs through Ashdod and Haifa ports for EU-bound citrus, Tel Aviv wholesale markets for domestic fresh trade, and direct logistics partnerships for restaurant chain contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Israeli horticulture offers margin expansion through autonomous harvesting adoption that compresses peak-season labor costs while premium greenhouse tier pricing strengthens on traceability mandates.
For Market Incumbents: Cement cold-chain dominance through backward integration into controlled-environment agriculture near Rehovot and Rishon LeZion greenhouse clusters. Autonomous harvesting platforms from Fresh Fruit Robotics and Tevel Aerobotics Technologies threaten labor-dependent berry operations; incumbents should anchor certification investment under EU directive 2000/29/EC alignment to defend supermarket shelf access against emerging greenhouse specialists. For New Entrants and Emerging Players: A mid-tier price-point gap between Strauss Group branded fresh-cut premiums and open-field commodity bulk shipments creates entry space for logistics-capable mid-scale growers. The Negev Desert solar-powered vertical farming segment offers lowest competitive density and highest policy support through Israel Water Authority quota relief. Go-to-market positioning should target direct restaurant sourcing channels with blockchain-traceable field-to-shelf documentation. For Investors and Strategic Acquirers: Consolidation pressure builds where smallholder balance sheets strain under four-hour cooling infrastructure mandates and multi-standard certification timelines. Long-term viability favors operators with captive water rights and integrated pest management documentation systems. Acquisition targets should display dual EU and USDA organic certification equivalence; signal to monitor is Ministry of Agriculture finalization of Plant Protection Law amendments tightening residue thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Environment Agriculture Expansion | Greenhouse retrofitting near Rehovot extends growing seasons for restaurant chain contract security. |
| Autonomous Harvesting Platform Deployment | Fresh Fruit Robotics adoption reduces peak-season labor dependency in Central District berry operations. |
| Dual Organic Certification Investment | Israel Standards Institute alignment with EU 2018/848 and USDA NOP unlocks premium retail placement. |
| Direct Restaurant Sourcing Channel Development | Farm-to-table logistics bypass traditional wholesale layers for margin capture in Tel Aviv procurement. |
| Sustainable Packaging Transition | Compostable tray adoption responds to municipal waste regulations before biodegradable alternatives achieve scale. |
Research Methodology
Direct dialogue with greenhouse operators, cold-chain logistics managers, restaurant procurement directors, and Ministry of Agriculture regulatory officials grounded qualitative findings in operational reality. Secondary validation drew from Israel Water Authority allocation data, Plant Protection and Inspection Services export certification records, EU phytosanitary directive compliance databases, and customs trade statistics through Ashdod and Haifa ports. Bottom-up hectare and yield estimates triangulated against top-down retail revenue audits from Shufersal and Rami Levy category data.
Segment-level value outputs across the projection horizon reflect modeled interactions between water quota constraints, certification compliance timelines, and autonomous harvesting adoption curves. Segmentation dimensions included product type, packaging format, distribution channel, and end-use application with regional production cluster differentiation. CAGRs derived from historical trade flow analysis and forward-looking infrastructure investment pipelines, incorporating drip irrigation yield coefficients and post-harvest loss rates specific to Israeli climatic conditions.
Caveats apply where Ministry of Agriculture finalization of Plant Protection Law amendments, Israel Water Authority drought-cycle quota revisions, or biodegradable packaging cost curves could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Dehydrated Beets Market
Fruits and Vegetables
Avocado-Based Products Market
Fruits and Vegetables
Mexico Fruits & Vegetables Market
Fruits and Vegetables
Japan Fresh Fruits Market
Fruits and Vegetables
APAC Frozen Fruits and Vegetables Market
Fruits and Vegetables
Fresh Strawberry Market
Fruits and Vegetables
Dried Kiwi Fruit Market
Fruits and Vegetables
Mulberry Market
Fruits and Vegetables
Pomegranate Market
Fruits and Vegetables
Japan Frozen Fruit Puree Market
Fruits and Vegetables
Bahrain Fruits and Vegetables Market
Fruits and Vegetables
Qatar Fruits and Vegetables Market
Fruits and Vegetables
Water Chestnut Market
Fruits and Vegetables
Mexico Lime Market
Fruits and Vegetables
Chile Fruits and Vegetables Market
Fruits and Vegetables
Middle East and Africa Shiitake Mushroom Market