
 Sodium Selenite Market | 2026-2036
Sodium Selenite Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Selenite Market Analytics
Multi-source procurement is recalibrating how buyers secure sodium selenite supply. American Elements leverages its advanced materials portfolio to serve North American research and industrial accounts. Retorte GmbH anchors European supply through its selenium specialization and refining capabilities in Germany. Orffa competes in feed-grade segments across multiple continents with its animal nutrition focus.
Sodium selenite is an inorganic selenium salt, Na₂SeO₃, typically supplied as a white crystalline powder with minimum 98% purity for technical applications and higher specifications for pharmaceutical use; manufacturers produce it via selenium dioxide neutralization with sodium carbonate or hydroxide, yielding a compound essential for selenium fortification in human supplements, veterinary premixes, and biochemical research reagents. Feed-grade material dominates volume consumption as livestock producers fortify diets to prevent white muscle disease and improve reproductive performance in ruminants and poultry. Pharmaceutical-grade output commands premium positioning due to stringent USP and EP monograph compliance for parenteral nutrition and therapeutic formulations.
The FDA governs selenium additive concentrations in animal feed under 21 CFR 573.920, while REACH mandates full substance registration and safety dossier submission for sodium selenite imported into the European Union. China's NMPA and GB standards set parallel purity thresholds for pharmaceutical-grade imports, creating a multi-jurisdictional compliance burden that favors producers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving maximum permitted levels in feed premixes across major importing jurisdictions to anticipate reformulation requirements and certificate-of-analysis demands.
Market Dynamics
Pharmaceutical-grade purity mandates from FDA and EMA are compressing technical-grade margins while concentrating supply among refiners with dedicated regulatory affairs capacity.
Growth Catalysts
- Selenium fortification mandates:China's NMPA and GB standards for parenteral nutrition formulations are expanding pharmaceutical-grade procurement from domestic and import sources.
- REACH registration completion:Full substance dossier acceptance for sodium selenite eliminates regulatory friction for EU-based feed and pharmaceutical compounders.
- White muscle disease prevention protocols:Veterinary nutrition programs in ruminant and poultry operations drive feed-grade volume consumption across North American livestock regions.
Market Restraints
- Selenium metal price volatility:Raw material input costs fluctuate with mining output from primary copper and nickel operations, squeezing refiner margins unpredictably.
- German supply concentration:European refining capacity clusters around specialized selenium processors, creating single-source vulnerability for pharmaceutical-grade buyers.
- Organic selenium substitution:Selenomethionine and selenized yeast displace inorganic salts in premium livestock nutrition and human supplement formulations.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO and FSSAI alignment with ICH guidelines creates import demand for USP-grade material in generic injectable production.
- Biochemical research reagent premiumization:Cell culture and molecular biology applications command 3-5x pricing multiples over technical grades.
- Animal welfare certification schemes:EU Green Deal farm-to-fork traceability requirements favor documented selenium sourcing in premium protein supply chains.
Industry Challenges
- Multi-jurisdictional dossier management:Parallel FDA, EMA, and NMPA filing requirements strain regulatory affairs staffing at mid-scale refiners.
- Analytical method harmonization delays:Divergent USP, EP, and GB monograph specifications for assay and impurity profiles complicate certificate-of-analysis standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Selenite Market |
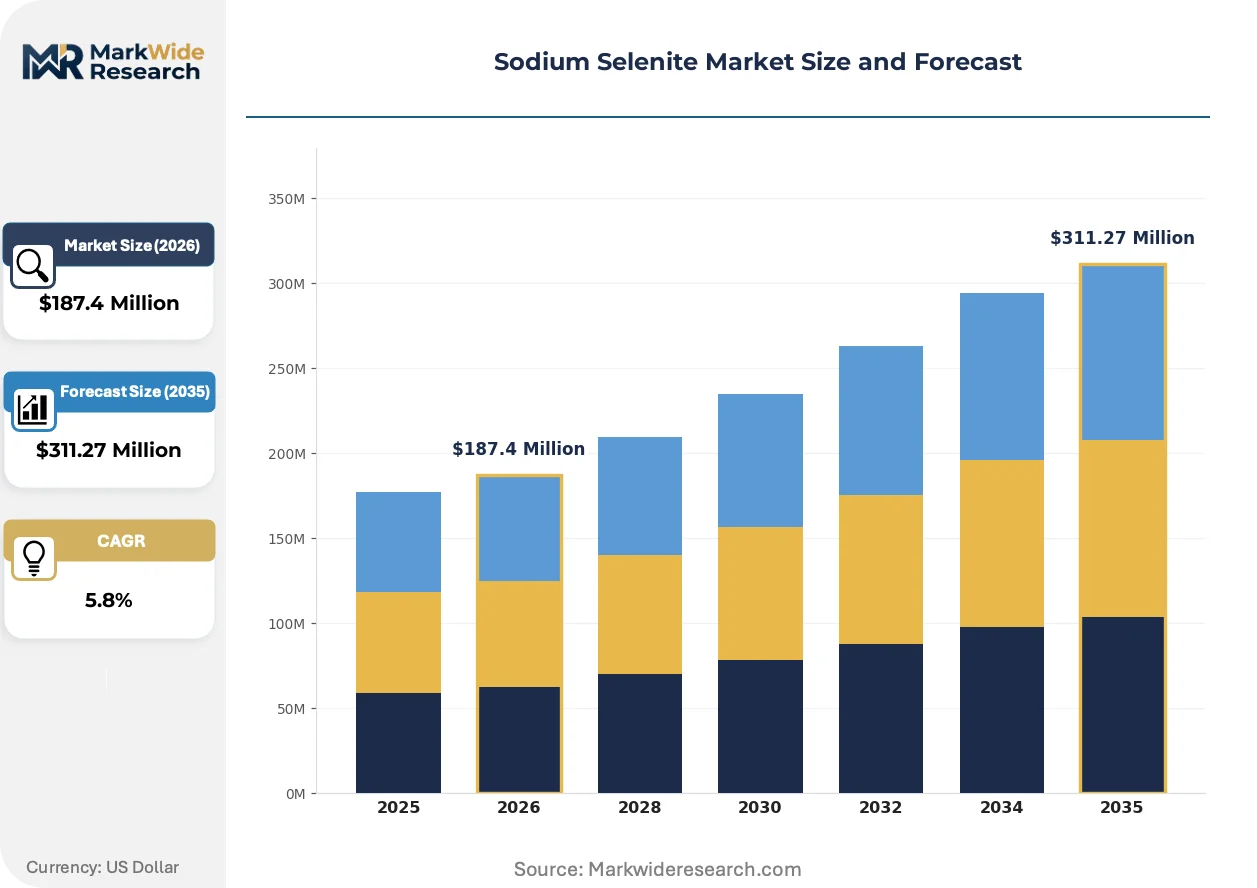
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Technical Grade, Laboratory Grade, Feed Grade Application: Nutritional Supplements, Pharmaceutical Products, Animal Feed, Laboratory Research End User: Pharmaceutical Companies, Nutraceutical Manufactures, Research Institutions, Animal Husbandry Distribution Channel: Direct Sales, Distributors, Online Retailers, Specialty Stores |
| Companies Covered | American Elements, Vital Materials, Retorte GmbH, Orffa, Jinhua, Omkar Speciality Chemicals Ltd., II-VI Incorporated, Salvi Chemical Industries Ltd., Sisco Research Laboratories Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Selenite Market Evolving Landscape
Continuous crystallization and membrane filtration systems are displacing batch neutralization in selenium salt production, enabling real-time purity adjustment and reducing solvent waste streams.
Microfluidic reactor technology for sodium selenite synthesis is expanding into pharmaceutical-grade manufacturing, allowing German and Chinese producers to achieve tighter particle size distribution and lower heavy metal residuals than conventional stirred-tank methods. Biopharma contract manufacturers in Switzerland and Singapore are qualifying this output for parenteral nutrition formulations.
REACH authorization list expansion for selenium compounds is tightening downstream communication obligations, forcing feed compounders to document safe-use conditions across extended supply chains. ECHA's 2024 updated guidance on reproductive toxicity classification affects labeling and handling protocols for premix distributors in France and Poland.
Consolidated procurement through pharmaceutical distributors is displacing direct refiner relationships for mid-volume supplement manufacturers, compressing supplier lists to three or four qualified sources per geography. North American nutraceutical brands now route 60-70 percent of sodium selenite purchases through specialized chemical distributors with in-house quality auditing capabilities.
Sodium Selenite Market Segmentation
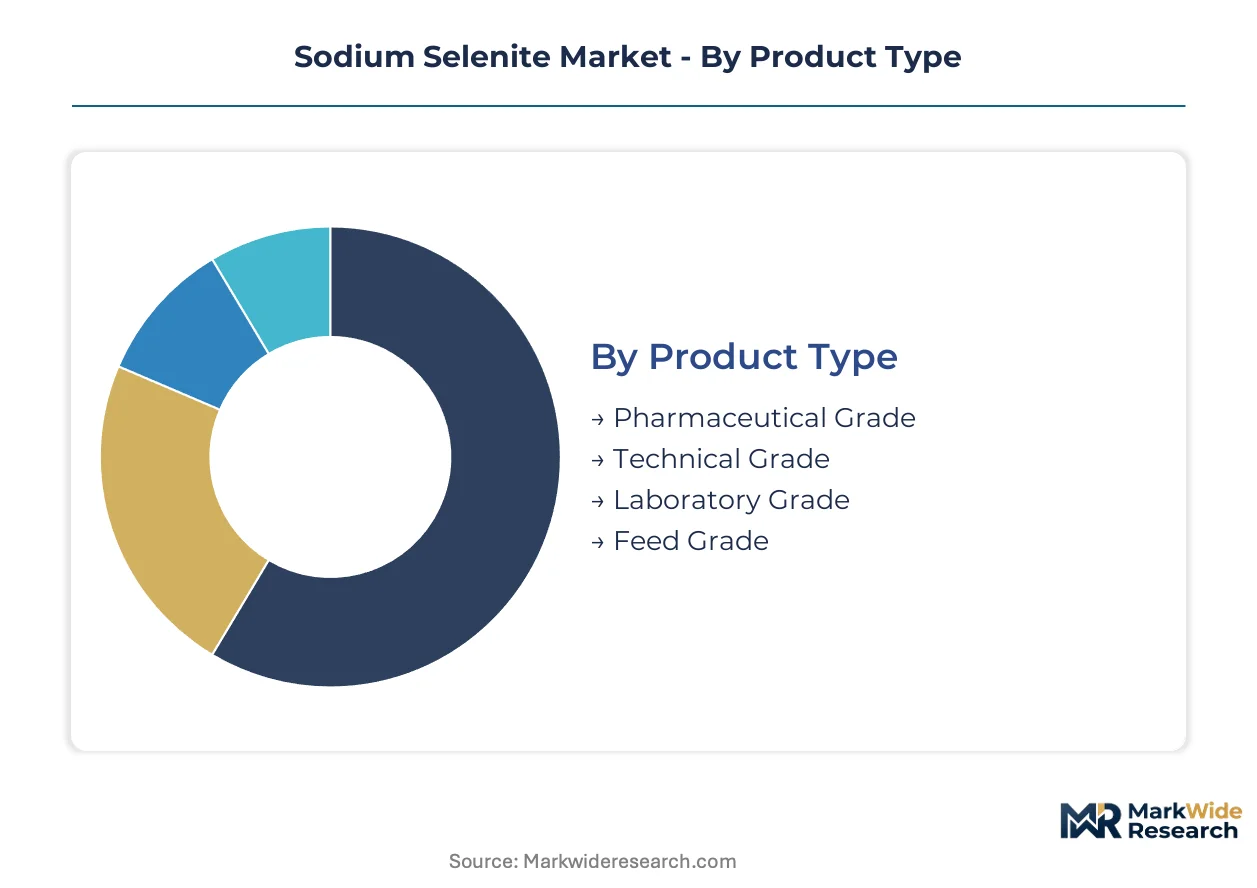
Sodium selenite supply chains stratify sharply around purity certification tiers, with regulatory compliance costs creating distinct procurement universes that rarely overlap. Buyers in pharmaceutical and feed applications operate on fundamentally different specification frameworks, forcing producers to choose concentration strategies rather than serving all tiers equally.
Product Type:
Supply concentration tilts heavily toward feed-grade output, yet margin capture concentrates in pharmaceutical-grade refining where German and Chinese producers dominate dossier-compliant capacity.
- Pharmaceutical Grade:USP and EP monograph compliance mandates sub-10 ppm heavy metal limits and documented GMP synthesis pathways. Parenteral nutrition compounders in Switzerland and Singapore qualify this material at 3-5x technical-grade price multiples, with CDSCO-aligned Indian manufacturers now expanding import procurement.
- Feed Grade:Minimum 98% purity with FDA 21 CFR 573.920 concentration limits for selenium fortification in ruminant and poultry premixes. Volume consumption clusters in North American livestock regions and EU member states with white muscle disease prevention protocols.
- Technical Grade:Industrial applications in glass manufacturing and chemical synthesis drive procurement from mid-scale refiners without pharmaceutical dossier capacity.
- Laboratory Grade:Biochemical research reagents require documented traceability and low endotoxin specifications for cell culture applications.
Feed grade absorbs the bulk of installed capacity; pharmaceutical grade is expanding most quickly as parenteral nutrition formulators in India and Southeast Asia build import relationships.
Application:
Cost tier separation between human and animal nutrition applications creates divergent pricing architectures, with human health formulations commanding certification premiums that feed compounders refuse to absorb.
- Nutritional Supplements:Selenium-enriched dietary tablets and capsules for human consumption require REACH-registered or FDA-notified source documentation. North American and European nutraceutical brands now route 60-70 percent of procurement through specialized chemical distributors with in-house quality auditing.
- Pharmaceutical Products:Injectable formulations for selenium deficiency treatment demand sterile manufacturing environments and endotoxin-controlled synthesis. Swissmedic and TGA alignment with ICH Q3D elemental impurity guidelines shapes specification evolution.
- Animal Feed:Veterinary premixes for cattle, swine, and poultry operations constitute volume demand, with EU Green Deal farm-to-fork traceability requirements favoring documented sourcing in premium protein supply chains.
- Laboratory Research:Molecular biology and analytical chemistry applications consume small volumes at steep per-kilogram pricing for high-specification material.
Animal feed commands the dominant share of tonnage movement; pharmaceutical products are climbing the fastest as generic injectable production expands in India.
End User:
Customer type determines procurement sophistication, with pharmaceutical companies operating dedicated supplier quality audit programs that research institutions and smaller feed operations cannot replicate.
- Pharmaceutical Companies:Parenteral nutrition specialists and generic injectable manufacturers in Germany, the United States, and India maintain approved supplier lists of three to four qualified refiners per geography, with multi-year framework agreements replacing spot purchasing.
- Nutraceutical Manufacturers:Dietary supplement brands in North America and Europe consolidate procurement through distributors to outsource regulatory verification and certificate-of-analysis standardization.
- Research Institutions:University and corporate R&D laboratories purchase through specialty chemical distributors with small-lot handling capabilities.
- Animal Husbandry:Livestock operations and integrated protein producers procure through feed compounders rather than direct refiner relationships.
Animal husbandry generates the highest absolute demand volume; pharmaceutical companies are gaining share fastest as parenteral nutrition indications expand.
Distribution Channel:
Channel selection correlates directly with buyer scale and regulatory burden tolerance, with large-volume pharmaceutical and feed operations disintermediating distributors only where supplier quality systems are pre-qualified.
- Direct Sales:Multi-ton pharmaceutical and feed-grade contracts route directly from German and Chinese refiners to qualified manufacturers with established audit histories and framework agreements.
- Distributors:Specialized chemical distributors with REACH compliance documentation and in-house analytical capabilities capture mid-volume nutraceutical and laboratory demand across North America and Europe.
- Online Retailers:Small-lot laboratory and technical-grade material moves through e-commerce platforms serving research institutions and artisanal supplement producers.
- Specialty Stores:Regional chemical supply houses with local inventory positions serve urgent small-batch requirements for analytical laboratories.
Direct sales channels handle the majority of value flow; distributor-mediated procurement is expanding most quickly as mid-scale buyers outsource compliance verification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade procurement concentrates in Germany, China, and the United States, where specialized selenium refiners serve parenteral nutrition formulators and feed compounders with divergent purity specifications.
Germany
Retorte GmbH anchors European pharmaceutical-grade supply through its selenium specialization and refining capabilities. REACH registration requirements and ECHA reproductive toxicity classifications tighten downstream documentation obligations for premix distributors. The industrial cluster around Saxony-Anhalt hosts dedicated selenium processing infrastructure serving Swissmedic-aligned compounders.
China
NMPA standards for parenteral nutrition formulations expand domestic pharmaceutical-grade production alongside import substitution initiatives. GB monograph compliance for heavy metal limits shapes specification negotiations with Indian generic injectable manufacturers. The Yangtze River Delta concentration of fine chemical producers supplies both domestic nutraceutical brands and export markets.
United States
FDA 21 CFR 573.920 feed-additive protocols drive volume consumption across North American livestock regions. White muscle disease prevention programs in cattle and poultry operations sustain feed-grade demand. The Midwest agricultural belt maintains dense distribution networks for veterinary premix procurement.
India
CDSCO alignment with ICH Q3D guidelines creates import demand for USP-grade material in generic injectable production. FSSAI regulatory convergence enables domestic formulation of selenium-enriched supplements. The pharmaceutical manufacturing corridor spanning Maharashtra and Gujarat builds parenteral nutrition capacity requiring certified raw material.
Switzerland
Swissmedic oversight of parenteral nutrition formulations positions the country as a qualification hub for pharmaceutical-grade sodium selenite. Biopharma contract manufacturers in Basel and Zurich microfluidic reactor output for endotoxin-controlled synthesis. The country's regulatory alignment with ICH standards shapes specification evolution across European supply chains.
Sodium Selenite Market Competitive Landscape
Capacity expansion dominates the current landscape as German and Chinese refiners scale microfluidic reactor installations for pharmaceutical-grade output. The vendor base stratifies into three tiers: integrated selenium specialists with full dossier capacity, regional feed-grade producers serving agricultural markets, and laboratory chemical distributors handling small-lot research demand. Strategic archetypes include REACH-registered European refiners, NMPA-aligned Chinese manufacturers, and North American advanced materials portfolios. M&A activity concentrates among distributors consolidating quality auditing capabilities, while backward integration into selenium metal refining protects margin positions against raw material volatility.
Among German specialists, Retorte GmbH exemplifies the dedicated selenium refiner archetype with its dossier-compliant capacity for pharmaceutical applications. American Elements occupies a position within the North American advanced materials tier, serving research and industrial accounts through portfolio breadth rather than single-subject specialization. Orffa represents the animal nutrition-focused competitor, competing across feed-grade segments with multi-continental distribution infrastructure. These three anchors illustrate how geographic regulatory alignment and end-use concentration shape competitive positioning without overlapping customer universes.
| Leading Market Players |
|---|
| American Elements |
| Vital Materials |
| Retorte GmbH |
| Orffa |
| Jinhua |
| Omkar Speciality Chemicals Ltd. |
| II-VI Incorporated |
| Salvi Chemical Industries Ltd. |
| Sisco Research Laboratories Pvt. Ltd. |
| Others |
Value Network & Pricing Analysis
Selenium metal price volatility propagates through sodium selenite supply chains, compressing refiner margins unpredictably while forcing buyers into long-term offtake contracts to lock in pharmaceutical-grade premiums. Copper and nickel mining output fluctuations in Chile and Indonesia transmit directly to German and Chinese refiners, who pass cost instability downstream through tiered pricing structures that separate feed-grade volume from parenteral nutrition premiums.
Pricing Analysis
Volume-margin splits concentrate feed-grade output at thin returns while pharmaceutical-grade material captures substantial premiums through certification compliance. Three-tier pricing structure across pharmaceutical, feed, and technical grades separates USP-monograph injectable material from FDA 21 CFR 573.920-limited premix additives. Cost compression in feed-grade tiers is intensifying because organic selenium substitutes capture premium livestock nutrition share. Animal feed compounders exhibit highest price sensitivity; parenteral nutrition formulators in Switzerland and Singapore absorb certification premiums without volume reduction.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Shanghai, and Houston anchor hub-and-spoke patterns for pharmaceutical-grade material, with satellite warehouses serving urgent laboratory and veterinary premix demands. Manufacturing concentrates in Germany, China, and the United States, where specialized selenium refiners maintain dossier-compliant capacity. Production draws from selenium dioxide feedstock sourced through copper anode slimes processing, with sodium carbonate neutralization completing synthesis. Single-source vulnerability clusters around Saxony-Anhalt refining infrastructure. Distribution runs through direct sales for multi-ton pharmaceutical contracts and specialized chemical distributors for mid-volume nutraceutical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-jurisdictional dossier management burdens are accelerating consolidation among mid-scale refiners lacking dedicated regulatory affairs capacity. REACH authorization expansion and FDA 21 CFR compliance complexity favor producers with captive documentation expertise.
For Market Incumbents: Anticipate organic selenium substitution in premium livestock segments by securing backward integration into selenium metal refining and expanding microfluidic reactor capacity for pharmaceutical-grade particle size control. Retorte GmbH and NMPA-aligned Chinese producers demonstrate how dossier depth defends margin positions against feed-grade commoditization. Certification investment in CDSCO and Swissmedic alignment creates switching costs for parenteral nutrition formulators.
For New Entrants and Emerging Players: Mid-scale Indian generic injectable manufacturers represent the most penetrable buyer archetype, with FSSAI convergence creating white-space for USP-grade import substitution. Biochemical research reagent premiumization offers second entry path, with cell culture applications commanding substantial multiples over technical grades. Qualification through specialized chemical distributors with in-house quality auditing accelerates market access without direct refiner relationship investment.
For Investors and Strategic Acquirers: REACH registration completion for sodium selenite is the leading indicator that regulatory friction has eliminated for EU-based compounders, signaling viable platform acquisition timing. Long-term viability over the coming decade rests on dossier-compliant capacity rather than feed-grade volume scale. Acquisition targets should display dedicated selenium specialization with ECHA-aligned safety documentation and established framework agreements with parenteral nutrition formulators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Selenium Metal Refining | Captive supply from copper anode slimes processing insulates margin positions against mining output volatility. |
| Microfluidic Reactor Capacity Expansion | German and Chinese installations achieve tighter heavy metal residuals for Swissmedic-aligned parenteral nutrition qualification. |
| REACH Registration Completion | Full substance dossier acceptance eliminates regulatory friction for EU-based feed and pharmaceutical compounders. |
| Long-term Supply Agreement with Distributors | Specialized chemical distributors with quality auditing capabilities capture consolidating mid-volume nutraceutical procurement. |
| Joint Venture for Indian Market Access | CDSCO and FSSAI alignment through local partnerships accelerates generic injectable raw material qualification. |
Research Methodology
Independent corroboration across primary interviews with selenium refinery plant managers, regulatory affairs leads at pharmaceutical compounders, veterinary premix procurement directors, and specialized chemical distribution channel partners underwrites the qualitative findings. Secondary validation draws from ECHA registration databases, FDA 21 CFR filings, NMPA GB standard publications, and customs trade data for selenium compound flows. Bottom-up capacity assessments at German and Chinese refiners triangulate against top-down demand modeling from parenteral nutrition and animal feed consumption patterns.
Rate-of-change decomposition across the analysis window separates volume growth in feed-grade applications from value expansion in pharmaceutical-grade tiers. Segmentation dimensions include purity certification grade, end-use application, and regional regulatory cluster alignment. CAGRs derive from installed capacity trajectories, import substitution patterns in India, and organic selenium displacement rates in premium livestock nutrition. Forecast inputs incorporate REACH authorization list expansion timing and ECHA reproductive toxicity classification updates.
Revisions become necessary when selenium metal price volatility exceeds historical bands, when ECHA adds sodium selenite to authorization lists requiring downstream documentation, or when NMPA shifts parenteral nutrition formulation standards. Forecasts reflect assumptions about regulatory stability and substitution elasticity that warrant periodic verification. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global 2-Methylpropene Market
Bulk Chemicals
Hydrated Lime Market
Bulk Chemicals
North America Acrylamide Monomer Market
Bulk Chemicals
Furandicarboxylic Acid Market
Bulk Chemicals
Bulk Ingredients Market
Bulk Chemicals
Dimethyl Disulphide (DMDS) Market
Bulk Chemicals
Tributyl Citrate Market
Bulk Chemicals
Pyrophyllite Powder Market
Bulk Chemicals
Trona Market
Bulk Chemicals
Propionaldehyde Market
Bulk Chemicals
Para Nitrophenol Market
Bulk Chemicals
Fine Hydrate Market
Bulk Chemicals
Methanesulfonic Acid Market
Bulk Chemicals
Global Purified Terephthalic Acid (PTA) Market
Bulk Chemicals
Ethylbenzene Market
Bulk Chemicals
Phosphorus Market