
 Glacial Methacrylic Acid Market | 2026-2036
Glacial Methacrylic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Glacial Methacrylic Acid Market Analysis
Specialty coatings formulators are rotating away from commodity acrylic acid derivatives toward glacial methacrylic acid for premium automotive and industrial finishes. Mitsubishi Chemical Corporation leverages captive cumene oxidation streams to sustain cost-advantaged feedstock positions across Asia. BASF SE anchors European supply through integrated Ludwigshafen production, while Evonik Industries AG differentiates via high-purity grades tailored to optical and medical polymer specifications.
Glacial methacrylic acid is a high-purity, crystalline form of methacrylic acid containing less than 1% water and inhibitor residues, produced via catalytic oxidation of isobutylene or tert-butanol followed by fractional crystallization or melt crystallization purification; it serves as a monomer building block for polymethacrylates demanding optical clarity, weather resistance, and thermal stability. Coatings applications dominate volume consumption due to acrylic copolymer demand in automotive OEM and refinish formulations, while high-purity grades command margin premiums from electronics and medical device polymer processors. Drum delivery occupies the largest share of logistics configurations, though bulk delivery grows fastest among integrated consumers operating adjacent esterification or polymerization units.
EPA VOC regulations and REACH registration requirements constrain product specifications and cross-border market access for non-compliant suppliers. ECHA substance evaluation under REACH drives testing burdens for impurities and polymerization inhibitor residuals. FDA indirect food contact and medical device polymer standards shape qualification protocols for suppliers serving healthcare and packaging end users. Stakeholders must monitor regulatory divergence between jurisdictions and assess backward integration options as feedstock volatility and certification costs reshape competitive economics.
Market Dynamics
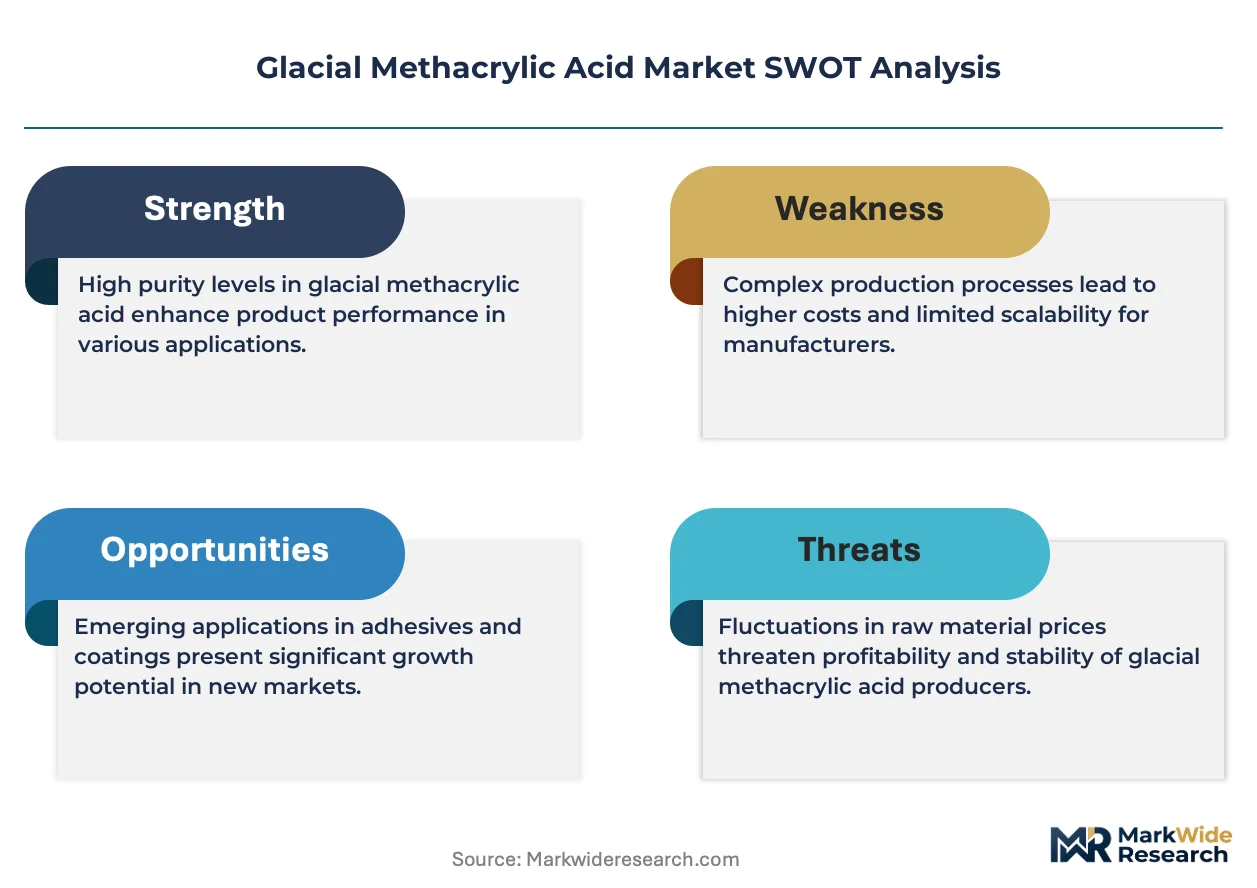
REACH compliance deadlines and EPA VOC enforcement are compressing supplier margins while simultaneously advantaging integrated methacrylate producers with captive purification capabilities.
Growth Catalysts
- Automotive OEM clearcoat specifications:Premium vehicle manufacturers in Germany and the United States are mandating high-purity glacial methacrylic acid for scratch-resistant and UV-stable topcoat formulations.
- REACH registration completion:ECHA substance evaluation protocols are disqualifying non-registered importers, consolidating volume toward compliant European producers.
- Medical polymer qualification:FDA indirect food contact and medical device polymer standards are expanding addressable demand for optical-grade material in surgical equipment and diagnostic housings.
Market Restraints
- Isobutylene feedstock volatility:Crude oil price swings and refinery operating rates directly transmit to methacrylic acid production economics, compressing margin predictability for non-integrated operators.
- Supply concentration in Northeast Asia:Cumene oxidation capacity clusters around integrated chemical complexes in Japan and South Korea, creating geographic vulnerability for Atlantic basin consumers.
- Melt crystallization capex intensity:High-purity grade production requires fractional crystallization trains that demand substantial capital deployment and extended commissioning timelines.
Strategic Opportunities
- India specialty coatings penetration:BIS certification alignment and domestic automotive production expansion are opening procurement channels previously dominated by commodity acrylic resins.
- Electronics-grade optical polymer demand:Display substrate and light-guide plate manufacturers in Taiwan and South Korea are qualifying ultra-high-purity grades for next-generation panel architectures.
- Bulk delivery infrastructure investment:Integrated consumers operating adjacent esterification units are converting from drum to tank-car delivery, reducing per-unit logistics costs and handling losses.
Industry Challenges
- Polymerization inhibitor residual management:ECHA testing burdens for phenolic inhibitor traces are extending batch release timelines and complicating just-in-time supply contracts.
- Cross-jurisdictional specification divergence:FDA, EMA, and PMDA polymer standards for medical applications lack harmonization, forcing redundant qualification campaigns for multi-regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glacial Methacrylic Acid Market |
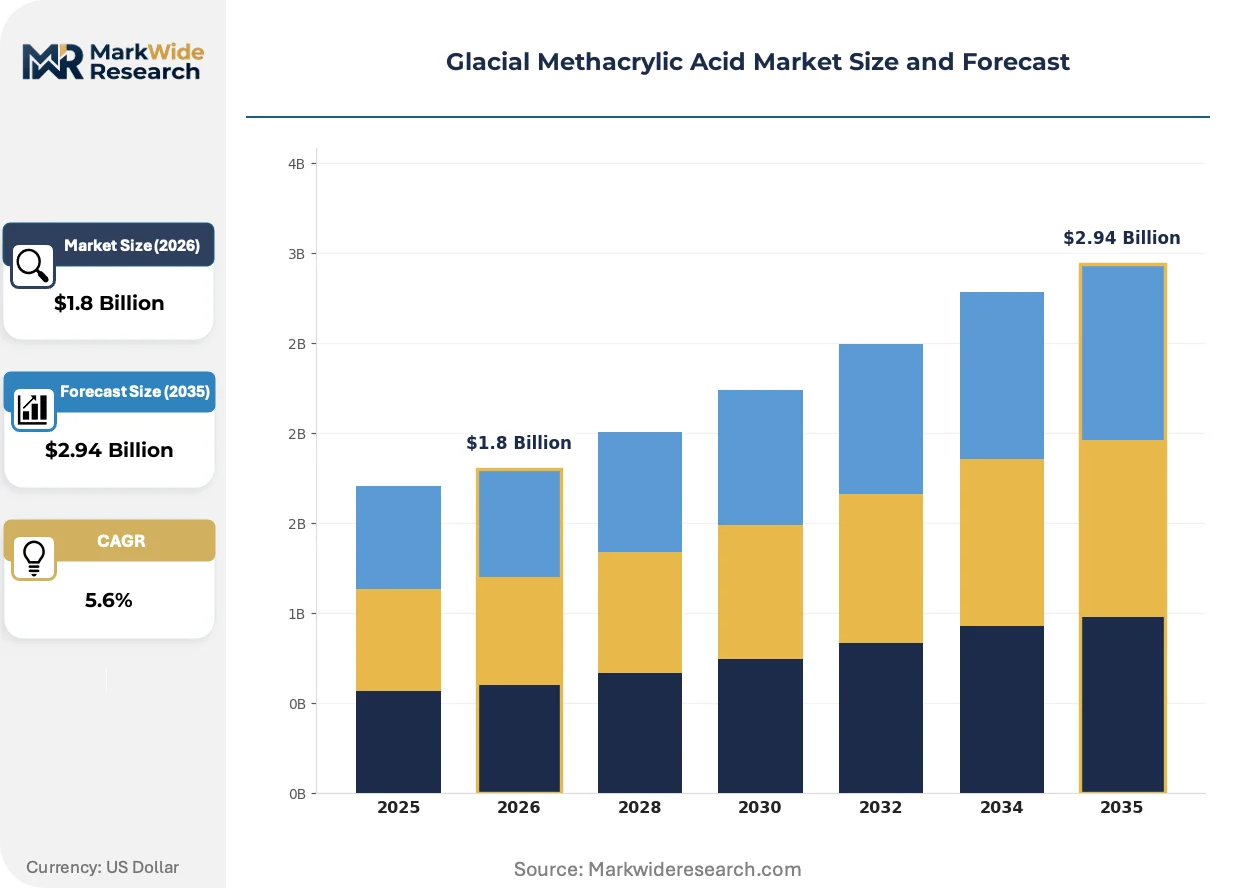
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Grade, High Purity, Specialty Grade, Low Viscosity Application: Adhesives, Coatings, Plastics, Automotive Parts End User: Construction, Automotive, Electronics, Consumer Goods Delivery Mode: Bulk Delivery, Drum Delivery, Container Delivery, Packaged Delivery |
| Companies Covered | Mitsubishi Chemical Corporation, BASF SE, Evonik Industries AG, Dow, Arkema, Formosa Plastics Corporation, KH Chemicals, NIPPON SHOKUBAI CO., LTD., KURARAY CO., LTD., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glacial Methacrylic Acid Market Emerging Trajectories
Melt crystallization technology is fragmenting the traditional supplier base while regulatory pressure on VOC emissions is reshaping formulation chemistry across automotive and industrial coatings.
Advanced melt crystallization purification is fragmenting cost structures among high-purity grade producers. This technology enables single-stage upgrading of technical-grade feedstock to optical specifications. Automotive clearcoat formulators in Germany and Japan are qualifying crystallization-derived material for premium OEM contracts. The technology is fragmenting incumbent positions by lowering the capital threshold for specialty-grade entry.
EPA VOC regulations and REACH Annex XVII restrictions are tightening permissible solvent content in industrial coatings. These frameworks are forcing reformulation toward higher-solids acrylic systems that demand purer methacrylic acid monomer inputs. Refinish and marine coating segments in the United States and Mediterranean Europe are accelerating compliance-driven procurement switches.
Specification-driven procurement consolidation is compressing supplier lists among integrated methacrylate consumers. Tier-one automotive OEMs are reducing qualified acid suppliers from multiple sources to dual-source or single-source arrangements contingent on REACH and FDA certification status. This concentration is most visible in German and Japanese automotive supply chains where material traceability requirements are most stringent.
Glacial Methacrylic Acid Market Segmentation
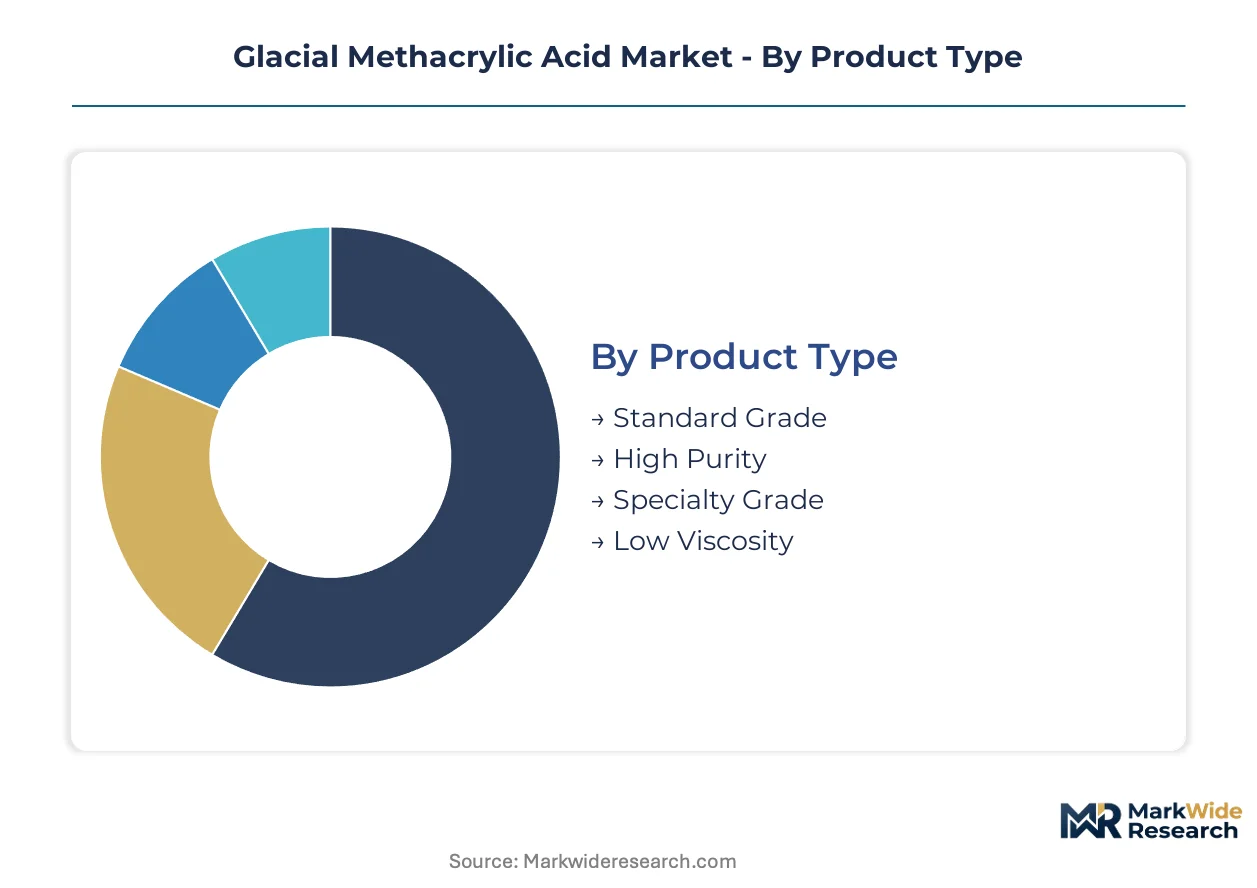
Segmentation in glacial methacrylic acid reveals how purity thresholds, logistics configurations, and end-use specifications fragment procurement economics. Buyers face divergent qualification burdens across automotive clearcoat, medical polymer, and electronics substrate applications.
Product Type:
Domestic consumption concentrates on standard and high-purity grades in Germany and the United States, while specialty and low-viscosity variants flow disproportionately to export markets in Taiwan and South Korea.
- Standard Grade:Contains crystalline methacrylic acid with controlled water content below 1% and residual inhibitor levels meeting industrial coating specifications. German automotive OEM clearcoat formulators anchor regional demand, though EPA VOC compliance deadlines are compressing acceptable impurity windows.
- High Purity:Achieves sub-0.1% total impurities through fractional crystallization, qualifying for optical polymer and medical device applications. FDA indirect food contact standards and ECHA REACH registration requirements concentrate procurement among Ludwigshafen and Japanese integrated producers with captive purification trains.
- Specialty Grade:Custom inhibitor packages and moisture specifications for electronics-grade polymethacrylates.
- Low Viscosity:Reduced molecular weight variants for UV-curable adhesive formulations in industrial assembly.
Standard grade commands the established base. The steepest expansion runs through high purity.
Application:
Cost tier differentiation separates commodity volume from margin-accretive specialty formulations, with coatings commanding logistics scale and automotive parts extracting purity premiums.
- Coatings:Acrylic copolymer demand in automotive OEM and refinish formulations drives the largest volume consumption segment. German premium vehicle manufacturers mandate REACH-registered material with full inhibitor traceability, while US Gulf Coast marine coating producers navigate EPA VOC enforcement timelines.
- Automotive Parts:Interior and exterior polymer components require thermal stability and weather resistance specifications that disqualify commodity acrylic acid derivatives. Japanese tier-one suppliers qualify high-purity grades through PMDA-aligned polymer standards, creating dual-certification burdens for multi-regional material.
- Adhesives:Structural and pressure-sensitive formulations for industrial bonding and assembly applications.
- Plastics:General-purpose polymethacrylate molding compounds for signage, lighting, and consumer products.
Coatings maintains volume leadership. Automotive parts is climbing the fastest on specification premiums.
End User:
Customer type maturity varies sharply, with automotive and electronics demanding exhaustive qualification protocols while construction and consumer goods accept broader supplier lists.
- Automotive:OEM clearcoat specifications and interior polymer qualification dominate high-purity consumption. German and US manufacturers reduce qualified suppliers from multiple sources to dual-source arrangements contingent on REACH and FDA certification status.
- Electronics:Display substrate and light-guide plate manufacturers in Taiwan and South Korea drive ultra-high-purity demand. Melt crystallization technology is fragmenting incumbent positions by lowering capital thresholds for optical-grade entry.
- Construction:Sealants, coatings, and architectural adhesives for commercial and residential building applications.
- Consumer Goods:Packaging, lighting fixtures, and household products utilizing general-purpose polymethacrylates.
Automotive anchors margin extraction. Electronics is expanding most quickly on next-generation panel architectures.
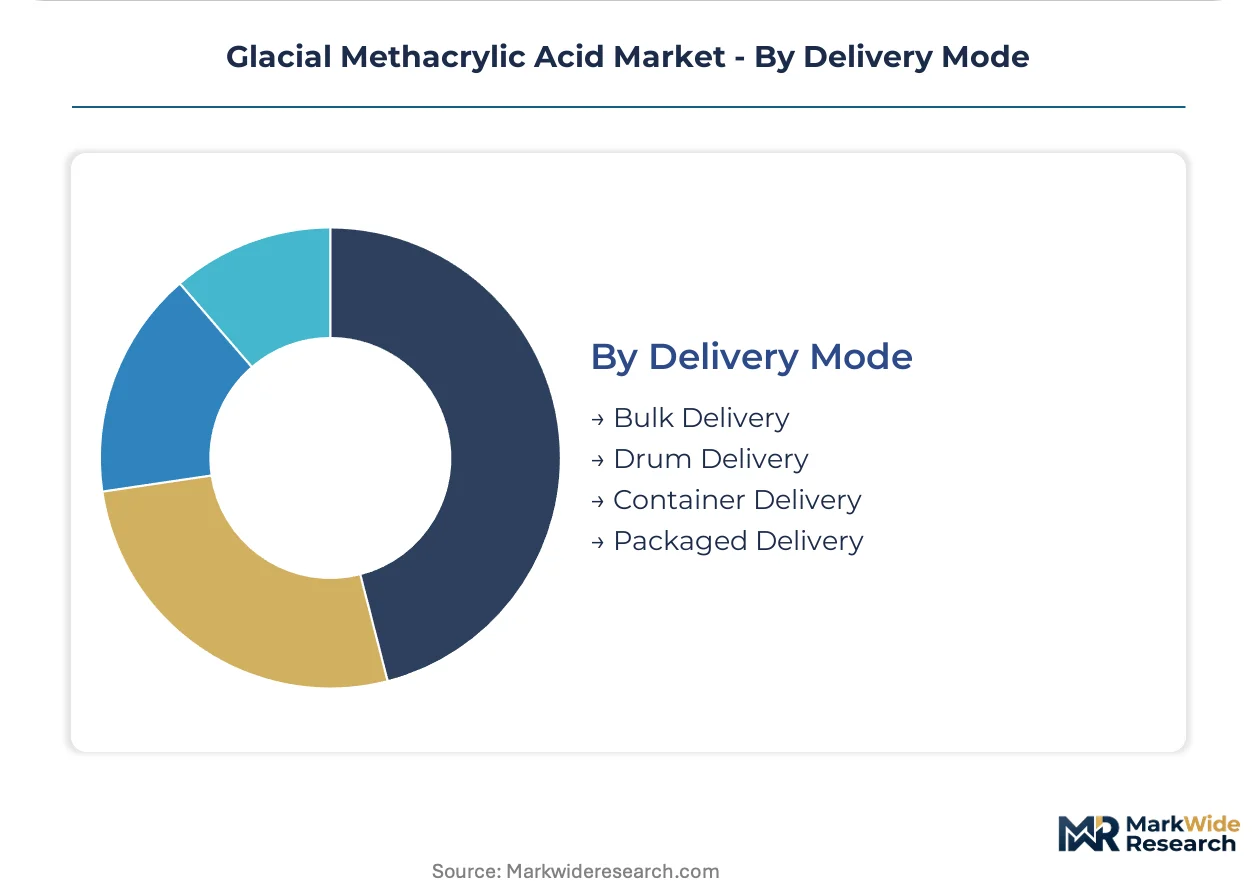
Delivery Mode:
Supply concentration shapes logistics economics, with integrated esterification units converting from packaged formats to bulk infrastructure while drum delivery retains fragmented geographic coverage.
- Drum Delivery:Retains the largest share of logistics configurations due to geographic reach and handling flexibility. Small and mid-scale coating formulators across Mediterranean Europe and the US Northeast rely on drum formats for just-in-time procurement, though ECHA testing burdens for inhibitor residuals extend batch release timelines.
- Bulk Delivery:Tank-car and dedicated vessel configurations serve integrated consumers operating adjacent esterification or polymerization units. Ludwigshafen and US Gulf Coast chemical corridors are converting procurement channels to reduce per-unit logistics costs and handling losses.
- Container Delivery:Intermediate-scale shipments for regional distribution hubs and compounders.
- Packaged Delivery:Small-lot formats for laboratory, R&D, and specialty formulation sampling.
Drum delivery holds the installed base. Bulk delivery is gaining share fastest among integrated methacrylate consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese producers ship high-purity grades to Taiwanese electronics manufacturers under PMDA-aligned specifications. German integrated complexes supply automotive OEMs across the Rhine corridor with REACH-certified material. Chinese domestic capacity serves regional coating formulators while South Korean exports target display substrate fabricators.
United States
Automotive OEM clearcoat formulators in Detroit and the Southeast mandate EPA VOC-compliant material for premium vehicle programs. The EPA enforces tightening solvent content thresholds through regional implementation plans. Gulf Coast chemical corridors around Houston are converting procurement channels from drum to bulk delivery for integrated methacrylate consumers.
Germany
Premium vehicle manufacturers in Bavaria and Baden-Württemberg require full inhibitor traceability for scratch-resistant topcoat formulations. ECHA REACH registration protocols disqualify non-registered importers from European supply chains. The Ludwigshafen chemical complex anchors continental production with captive purification trains serving medical polymer processors.
China
Domestic automotive production expansion in the Yangtze River Delta and Pearl River Delta drives standard-grade consumption for industrial coatings. The country's national chemical regulator enforces GB standards alignment for cross-border material qualification. Integrated methacrylate complexes in Shandong and Jiangsu provinces are expanding esterification capacity for adjacent polymerization units.
Japan
Display substrate and light-guide plate manufacturers qualify ultra-high-purity grades under METI industrial standards for next-generation panel architectures. PMDA polymer standards for medical applications create dual-certification burdens for multi-regional suppliers. Cumene oxidation capacity clusters around integrated chemical complexes in the Chubu region serving optical polymer demand from South Korea and Taiwan.
South Korea
Electronics-grade optical polymer demand from Seoul-area display manufacturers is accelerating qualification of melt crystallization-derived material. The country's national pharmaceutical and food safety regulator enforces polymer standards for indirect food contact applications. Busan-Ulsan chemical corridors host integrated production serving regional adhesive and coating formulators.
Glacial Methacrylic Acid Market Vendor Landscape
Listed leaders compete with private specialists across purification technology tiers. The supplier base concentrates around integrated methacrylate producers with captive cumene oxidation streams and fractional crystallization capabilities. Three archetypes dominate: Asian petrochemical conglomerates with backward integration into isobutylene feedstock, European diversified chemical groups with REACH-registered purification assets, and regional specialists targeting electronics-grade optical specifications. Competitive dynamics center on capacity expansion for high-purity trains and strategic partnerships with automotive OEM qualification programs.
Within the integrated producer tier, Mitsubishi Chemical Corporation and BASF SE exemplify contrasting geographic anchoring strategies. Mitsubishi Chemical Corporation represents the Asian petrochemical conglomerate archetype with oxidation capacity positioned to serve display substrate demand across Northeast Asia. BASF SE occupies the European diversified chemical group position with Ludwigshafen-based purification trains qualified for medical polymer and automotive clearcoat specifications. Evonik Industries AG sits within the specialty-grade specialist category, differentiating through optical and medical polymer certification protocols that command margin premiums from surgical equipment and diagnostic housing manufacturers.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| BASF SE |
| Evonik Industries AG |
| Dow |
| Arkema |
| Formosa Plastics Corporation |
| KH Chemicals |
| NIPPON SHOKUBAI CO., LTD. |
| KURARAY CO., LTD. |
| Others |
Supply Flow & Price Mechanics
REACH registration protocols and FDA polymer certification standards gate both supplier qualification and price differentiation simultaneously, compressing margins for non-compliant operators while enabling margin premiums for integrated producers with captive purification capabilities. Buyers face divergent cost structures across drum and bulk delivery configurations, with logistics scale directly feeding into contract negotiation leverage.
Pricing Analysis
Crystallization-technology pricing gaps separate melt-derived optical grades from standard technical-grade material, with the former commanding substantial premiums from electronics and medical polymer processors. Pricing stratifies across premium, standard, and economy tiers based on purity thresholds and certification status, with EPA VOC compliance deadlines intensifying cost compression in commodity coating segments. Automotive OEM procurement teams exhibit the lowest price sensitivity due to specification-locked supply chains, while small-scale refinish formulators face acute margin pressure from regulatory testing burdens.
Supply Chain Analysis
Japan and South Korea anchor cumene oxidation capacity for high-purity glacial methacrylic acid production, with German integrated complexes serving as the Atlantic basin's primary supply source. Production economics rest on isobutylene feedstock availability, fractional crystallization train deployment, and phenolic inhibitor supply security. Single-source vulnerability concentrates around the Chubu region's oxidation clusters, which feed display substrate demand across Taiwan and South Korea. Distribution runs through drum formats for fragmented coating formulators and bulk tank-car configurations for integrated esterification consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as tier-one automotive OEMs compress qualified supplier lists from multiple sources to dual-source arrangements, fragmenting pricing leverage toward specification-compliant integrated producers.
For Market Incumbents: Shield margin positions by accelerating REACH certification completion for non-registered import volumes and deepening backward integration into isobutylene feedstock to offset crude oil volatility. Prioritize capacity additions in Ludwigshafen and Chubu corridor complexes to serve medical polymer qualification pipelines. For New Entrants and Emerging Players: Differentiate on melt crystallization technology entry to capture electronics-grade optical polymer demand from Taiwanese display substrate manufacturers. Target India's specialty coatings penetration as the most penetrable geography, leveraging BIS certification alignment to displace commodity acrylic resin procurement channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-purity fractional crystallization trains, favoring acquisition targets with existing purification assets over greenfield deployment. Focus on integrated methacrylate specialists with dual REACH-FDA certification status. Monitor ECHA substance evaluation timelines as the critical inflection signal for import disqualification waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isobutylene Feedstock | Captive oxidation streams at Mitsubishi Chemical and BASF insulate margin predictability from crude oil volatility. |
| High-Purity Crystallization Capacity Expansion | Melt crystallization trains at Ludwigshafen and Chubu complexes serve FDA-qualified medical polymer processors. |
| REACH Registration Completion | ECHA-compliant producers consolidate European supply chains as non-registered importers face disqualification. |
| Bulk Delivery Infrastructure Conversion | Tank-car configurations at US Gulf Coast corridors reduce per-unit logistics costs for integrated esterification consumers. |
| Electronics-Grade Optical Certification | PMDA-aligned specifications at Japanese producers unlock Taiwanese display substrate procurement channels. |
Methodological Framework
A spread of perspectives from plant managers at integrated methacrylate complexes, procurement leads at automotive OEM coating formulators, distribution channel partners, and technical R&D directors converged on the working assumptions. Primary fieldwork combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up volume modeling and top-down value triangulation cross-checked segmentation outputs.
Segmentation dimensions modeled include grade tier purity thresholds, end-use industry application, packaging format logistics configurations, and regional production hub concentration. CAGRs were derived through demand elasticity analysis and supply-side capacity utilization assessment across the projection horizon. Forecast inputs incorporated automotive OEM clearcoat specification evolution and electronics-grade optical polymer qualification timelines.
Forecasts assume regulatory continuity in REACH, EPA VOC enforcement, and PMDA polymer standards; material policy shifts would require re-modeling. Specific risks include isobutylene feedstock price volatility, ECHA testing burden escalation, and cross-jurisdictional specification divergence. Recalibration cycles align with material shifts in automotive OEM procurement consolidation and display substrate technology transitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
2-Methylfuran Market
Bulk Chemicals
Calcined Petcoke Market
Bulk Chemicals
Europe Lipids Market
Bulk Chemicals
Sodium Bicarbonate Market
Bulk Chemicals
Cyclamate Market
Bulk Chemicals
Global Sodium Chlorate Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
Sheet Molding and Bulk Molding Compounds Market
Bulk Chemicals
Magnesium Carbonate Market
Bulk Chemicals
Brazil Magnesium Phosphate Market
Bulk Chemicals
Glacial Acrylic Acid (GAA) Market
Bulk Chemicals
Calcium Nitrate Market
Bulk Chemicals
Global Cyclohexylbenzene Market
Bulk Chemicals
Vinyl Cyclohexane Market
Bulk Chemicals
Global Benzaldehyde Market
Bulk Chemicals
Global Vinyl Chloride Monomer Market