
 Clomiphene Citrate Market | 2026-2036
Clomiphene Citrate Market Size, Share, and Industry Trends Forecast 2026-2036
Clomiphene Citrate Market Insights
EMA's tightened active pharmaceutical ingredient manufacturing standards is repositioning the competitive landscape for European market access. Sanofi S.A. leverages its established gynecology portfolio to sustain brand loyalty among fertility specialists. Teva Pharmaceutical Industries Ltd. anchors its position through vertical integration into generic API production. Cipla Inc. competes on cost-optimized oral tablet supply chains serving South Asian reproductive hospitals.
Clomiphene citrate is a synthetic non-steroidal triphenylethylene derivative that functions as a selective estrogen receptor modulator, typically formulated as 50 mg oral tablets or compounded suspensions for ovulation induction in anovulatory female patients. The compound stimulates gonadotropin release by blocking hypothalamic estrogen receptors, thereby triggering follicular development and subsequent ovulation in assisted reproductive protocols. Tablet formulations dominate current prescription volumes due to established bioequivalence profiles and patient compliance advantages, while extended-release tablet development represents a faster-growing delivery innovation targeting reduced dosing frequency. Fertility clinics command the largest end-user margin pool given their centralized procurement power and protocol standardization, whereas assisted reproductive technology applications are expanding fastest as in-vitro fertilization cycles incorporate clomiphene citrate in ovarian stimulation regimens.
FDA oversight of generic bioequivalence standards and EPA environmental discharge guidelines for pharmaceutical manufacturing shape product quality and production site location decisions across the value chain. CDSCO registration requirements in India and BIS pharmaceutical grade standards further segment export-qualified suppliers from domestic-only manufacturers. Stakeholders must monitor evolving EMA good manufacturing practice inspections and FDA warning letter trends to anticipate which production facilities will retain supply chain eligibility.
Market Dynamics
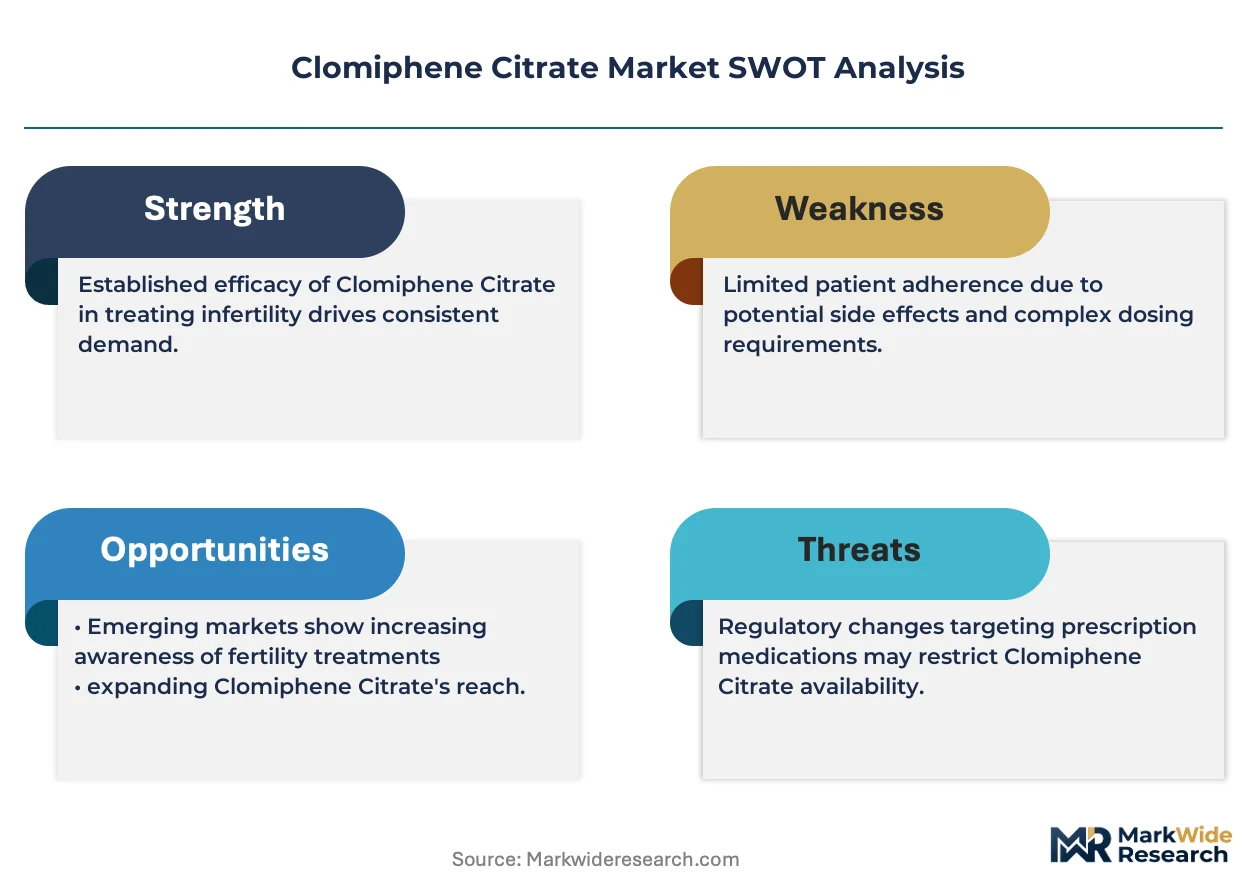
EMA's tightened active pharmaceutical ingredient manufacturing standards are forcing production facility upgrades across European supply chains, while fertility clinic consolidation in India and the United States concentrates procurement leverage among fewer buyers.
Growth Catalysts
- EMA GMP Inspection Intensification:Stricter facility audits in Europe are disqualifying substandard API manufacturers, creating procurement windows for compliant suppliers serving fertility clinics.
- Assisted Reproductive Technology Expansion:In-vitro fertilization protocols increasingly incorporate clomiphene citrate in ovarian stimulation regimens, driving prescription volumes at specialized reproductive hospitals.
- India CDSCO Registration Harmonization:Simplified export qualification pathways enable domestic manufacturers to supply regulated markets, accelerating API sourcing diversification.
Market Restraints
- API Supply Concentration:Bulk active pharmaceutical ingredient production clusters among fewer Indian and Chinese manufacturers, exposing buyers to single-source disruption risks.
- EPA Environmental Discharge Compliance:Pharmaceutical manufacturing wastewater standards in the United States raise capital requirements for production site maintenance and expansion.
- Letrozole Substitution Pressure:Alternative aromatase inhibitors demonstrate comparable ovulation induction efficacy in polycystic ovary syndrome protocols, threatening clomiphene citrate's first-line position.
Strategic Opportunities
- Extended-Release Formulation Development:Modified-release tablet technologies reduce dosing frequency for patient compliance, opening differentiation opportunities in fertility clinic protocols.
- Brazil ANVISA Market Access:Latin American regulatory alignment creates expansion potential for export-qualified manufacturers with established bioequivalence documentation.
- Telemedicine-Enabled Prescription Channels:Remote fertility consultations accelerate direct-to-clinic distribution models, bypassing traditional wholesale intermediaries.
Industry Challenges
- API Sourcing Qualification Timelines:CDSCO and FDA dual-registration requirements extend supplier onboarding cycles, compressing margin recovery windows for generic manufacturers.
- REACH Compliance Documentation Burden:European chemical substance registration demands specialized regulatory affairs capabilities that strain mid-scale API producers.
- Batch-to-Batch Bioequivalence Verification:Narrow therapeutic index requirements for ovulation induction necessitate stringent quality control investments across oral tablet production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clomiphene Citrate Market |
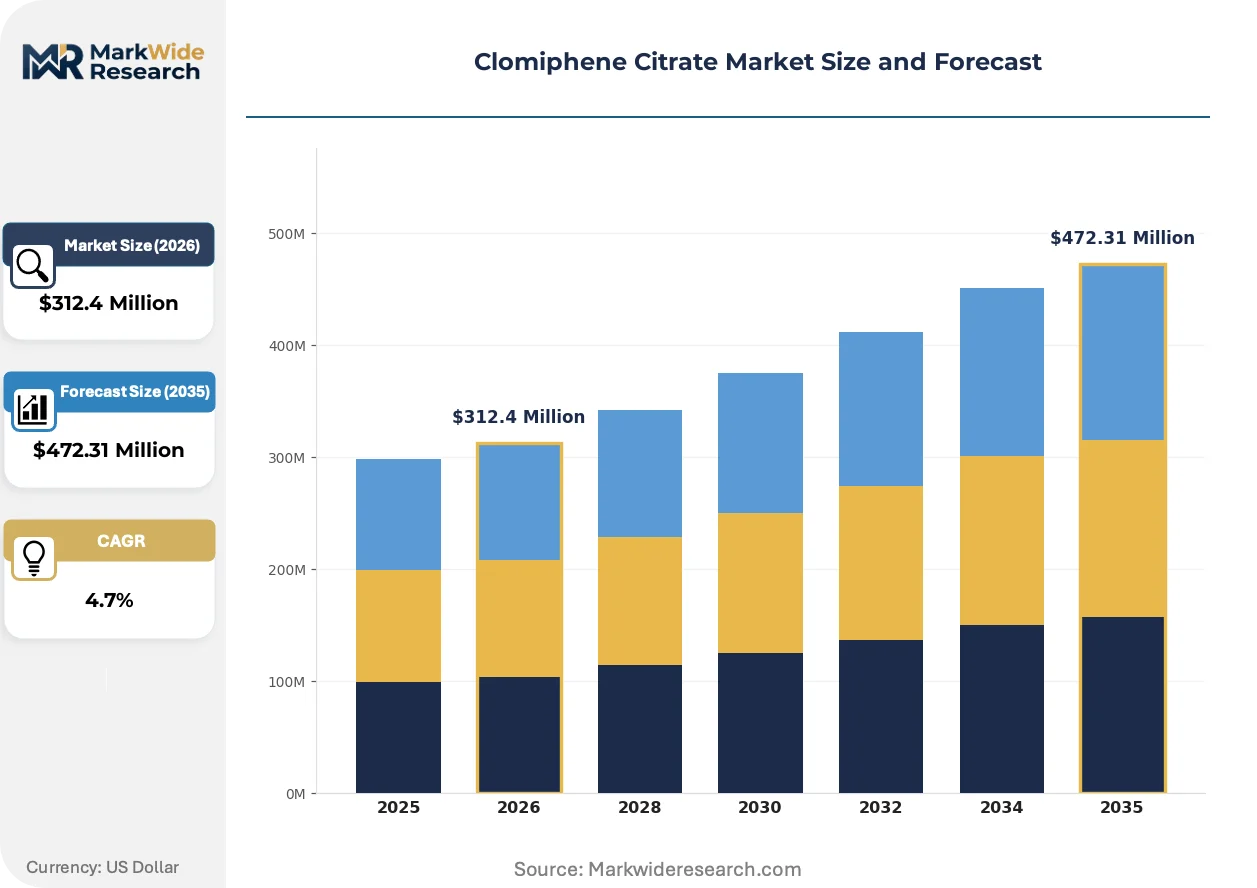
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Oral Suspension, Injectable, Extended-Release Tablet Therapy Area: Female Infertility, Male Hypogonadism, Ovulation Induction, Assisted Reproductive Technology End User: Fertility Clinics, Gynecology Centers, Andrology Labs, Reproductive Hospitals Delivery Mode: Oral, Parenteral, Controlled-Release, Sustained-Release |
| Companies Covered | Par Pharmaceutical, Unichem Laboratories Ltd., Sanofi S.A., Serum Institute of India Pvt. Ltd., Emcure Pharmaceuticals Ltd., Teva Pharmaceutical Industries Ltd., Cipla Inc., Incepta Pharmaceuticals Ltd., Merck & Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clomiphene Citrate Market Trends and Innovations
Formulation technology advances and regulatory harmonization pressures are compressing competitive differentiation timelines, while fertility clinic procurement centralization rewards suppliers with integrated quality documentation systems.
Extended-release tablet platforms are unifying patient compliance advantages with protocol standardization needs in fertility clinic settings. Reproductive endocrinology specialists at high-volume centers adopt these formulations to reduce monitoring visit frequency. The technology is unifying dosing convenience with centralized procurement preferences, compressing demand toward suppliers with demonstrated bioequivalence data packages.
REACH substance registration deadlines in Europe are eliminating non-compliant API intermediaries from qualified supplier lists. Chemical manufacturers face downstream user notification obligations that increase documentation transparency requirements. Fertility-focused pharmaceutical companies with pre-registered supply chains capture procurement preference from clinics seeking audit-ready documentation.
Centralized purchasing consortia among fertility clinic networks are consolidating supplier relationships around integrated service agreements. Multi-site reproductive health systems negotiate volume commitments that bundle API supply with regulatory compliance support. This concentration is most visible in United States metropolitan markets where hospital-affiliated fertility centers dominate referral volumes.
Clomiphene Citrate Market Segmentation
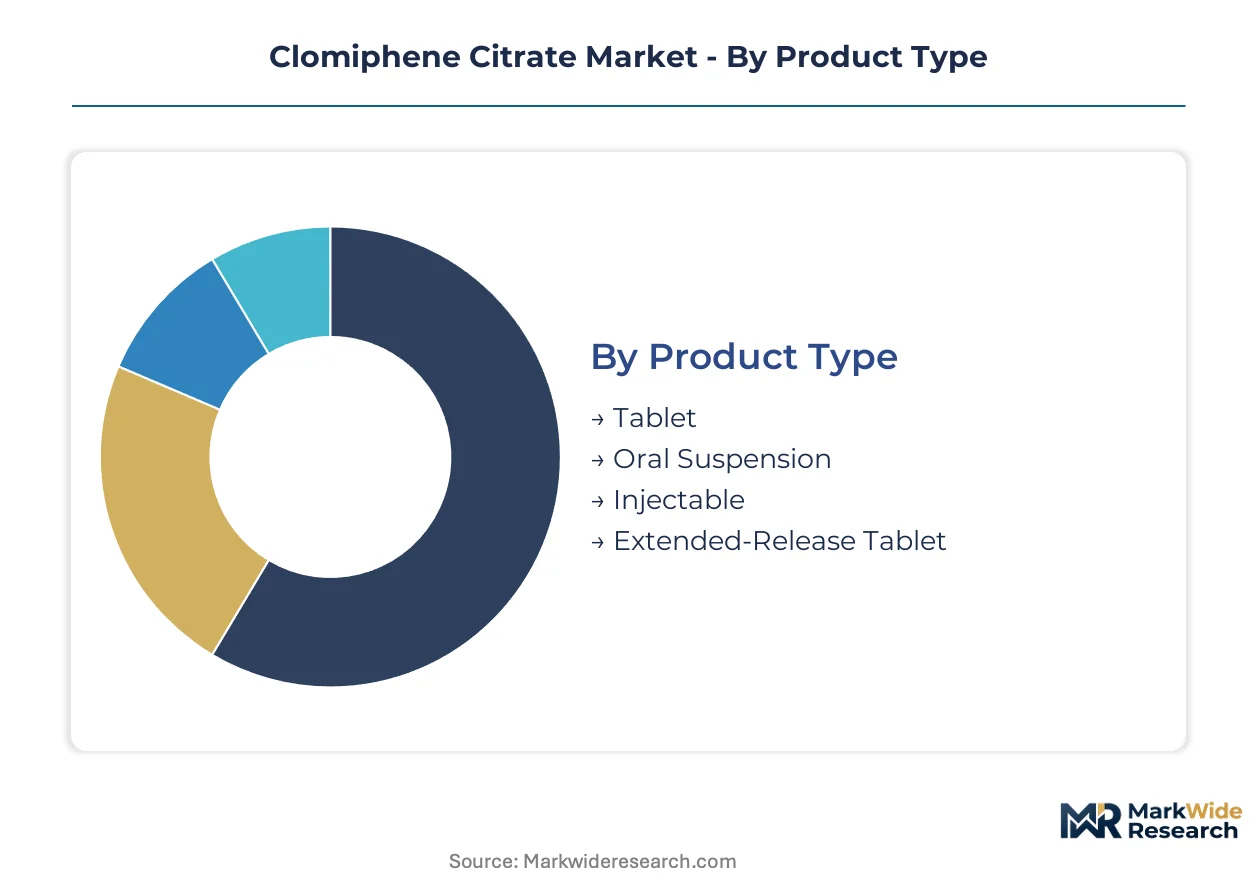
Clomiphene citrate market segmentation reflects divergent formulation preferences across reproductive medicine protocols. Each dimension captures distinct procurement patterns, from fertility clinic tablet purchasing power to extended-release development investments targeting patient compliance advantages.
Product Type:
Formulation upgrades follow patient compliance demands and protocol standardization pressures at high-volume fertility centers.
- Tablet:Standard 50 mg oral tablets dominate procurement volumes through established bioequivalence profiles and centralized fertility clinic purchasing. Fertility clinics in India and the United States concentrate demand around this dosage form due to protocol familiarity and cost-optimized supply chains.
- Extended-Release Tablet:Modified-release technologies reduce dosing frequency from daily to twice-weekly regimens, attracting reproductive endocrinology specialists seeking monitoring visit reduction. Development pipelines at European and North American manufacturers prioritize this format for premium clinic contracts.
- Oral Suspension:Compounded liquid formulations serve pediatric dosing requirements and patients with swallowing difficulties.
- Injectable:Parenteral formats occupy niche applications in specialized ovarian stimulation protocols requiring precise bioavailability control.
Tablet formulations sit at the top of the volume ranking, with extended-release tablet development climbing the fastest.
Therapy Area:
Application concentration tracks assisted reproductive technology expansion and polycystic ovary syndrome prevalence patterns.
- Assisted Reproductive Technology:In-vitro fertilization protocols increasingly incorporate clomiphene citrate in ovarian stimulation regimens alongside gonadotropins. Reproductive hospitals in metropolitan United States markets drive prescription acceleration through high-cycle-volume centers.
- Ovulation Induction:First-line anovulatory treatment maintains protocol dominance despite letrozole substitution pressure in polycystic ovary syndrome cases. CDSCO-registered Indian manufacturers supply cost-optimized volumes to South Asian reproductive hospitals.
- Female Infertility:Unexplained infertility applications represent mature demand with stable prescription patterns across gynecology centers.
- Male Hypogonadism:Off-label hypogonadism treatment occupies limited volume through specialized andrology lab protocols.
Ovulation induction commands the largest patient base, while assisted reproductive technology applications gain share fastest.
End User:
Customer concentration follows fertility clinic network consolidation and hospital-affiliated reproductive center expansion.
- Fertility Clinics:High-volume specialized centers exercise centralized procurement leverage through multi-site purchasing consortia. United States metropolitan markets demonstrate the most pronounced consolidation, with hospital-affiliated centers dominating referral volumes and standardizing around preferred suppliers.
- Reproductive Hospitals:Academic medical center fertility divisions integrate clomiphene citrate into comprehensive assisted reproductive technology service lines. Indian reproductive hospitals represent concentrated demand growth through expanding IVF cycle capacity.
- Gynecology Centers:Community-based obstetrics-gynecology practices serve initial ovulation induction prescriptions before specialist referral.
- Andrology Labs:Male-focused reproductive health facilities generate limited volume through specialized hypogonadism protocols.
Fertility clinics anchor procurement volume concentration, with reproductive hospitals expanding their share most rapidly.
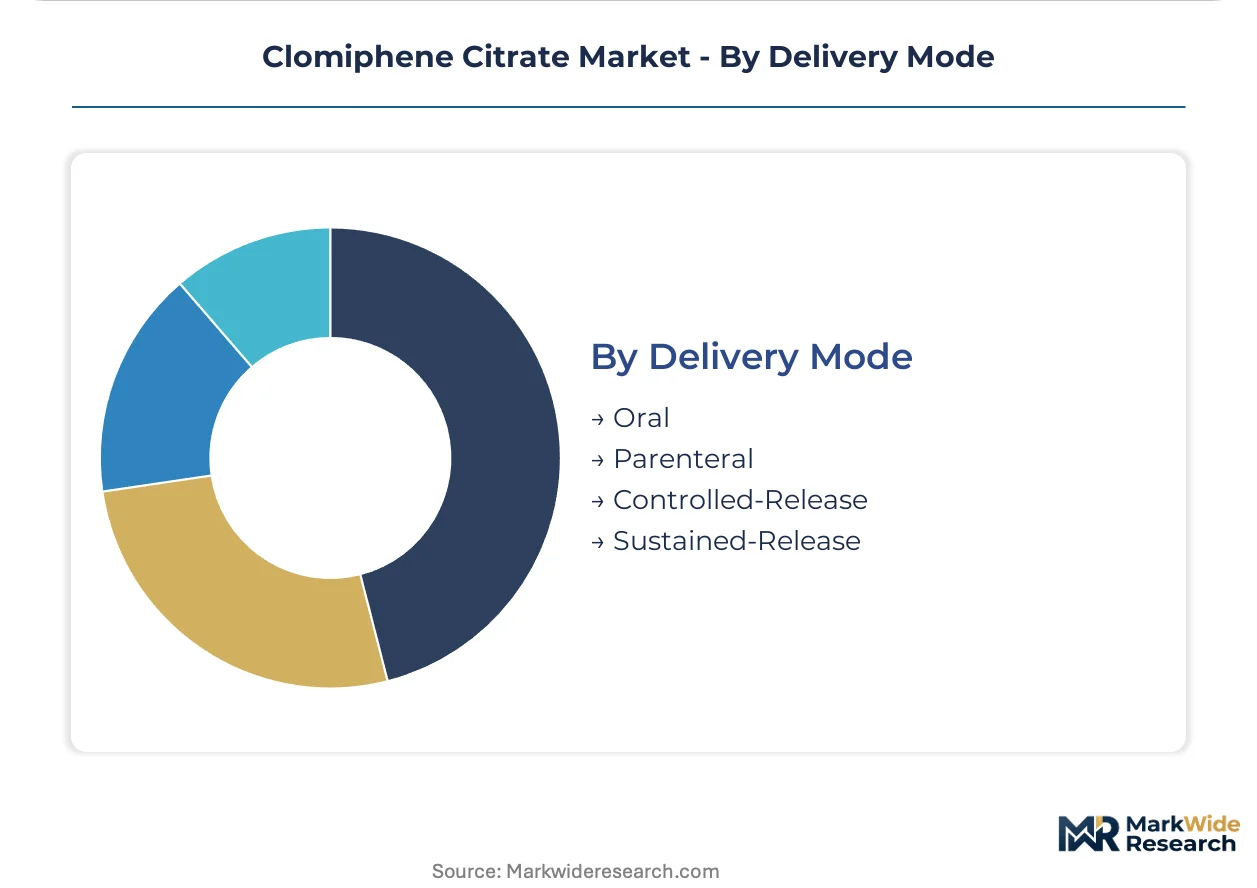
Delivery Mode:
Route selection reflects bioavailability requirements and patient compliance optimization across protocol types.
- Oral:Immediate-release oral administration dominates through established pharmacokinetic profiles and patient self-administration convenience. EMA GMP-compliant European manufacturers and FDA-registered United States suppliers compete for fertility clinic contracts.
- Controlled-Release:Precision release kinetics match follicular development timing in sophisticated ovarian stimulation protocols. Development investments concentrate among manufacturers with demonstrated bioequivalence documentation capabilities.
- Parenteral:Injectable delivery serves specialized applications requiring bypass of gastrointestinal absorption variability.
- Sustained-Release:Long-acting depot formulations occupy experimental positions in extended ovarian suppression protocols.
Oral delivery maintains absolute volume leadership, with controlled-release formats showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reproductive endocrinology specialists cluster in metropolitan hospital networks across five countries where fertility clinic consolidation and regulatory harmonization reshape procurement patterns.
United States
Fertility clinic networks in metropolitan markets exercise centralized purchasing leverage through hospital-affiliated reproductive centers. FDA oversight of generic bioequivalence standards and EPA environmental discharge guidelines shape supplier qualification decisions. Boston and New York anchor high-cycle-volume assisted reproductive technology corridors where procurement consortia bundle API supply with compliance documentation.
India
CDSCO-registered manufacturers supply cost-optimized oral tablet volumes to expanding reproductive hospitals in South Asian markets. BIS pharmaceutical grade standards segment export-qualified suppliers from domestic-only producers. Mumbai and Hyderabad concentrate API production facilities serving both regulated export markets and domestic fertility clinic demand.
Germany
EMA good manufacturing practice inspections disqualify substandard API intermediaries from European supply chains. REACH substance registration deadlines eliminate non-compliant chemical manufacturers from qualified supplier lists. Frankfurt and Munich host reproductive medicine centers that standardize procurement around audit-ready documentation packages.
China
NMPA registration requirements and dual carbon goals reshape pharmaceutical manufacturing investment patterns for ovulation induction compounds. MIIT industrial policies favor consolidation among API producers with environmental compliance capabilities. Shanghai and Jiangsu province concentrate formulation facilities serving both domestic fertility clinics and export markets.
Brazil
ANVISA regulatory alignment creates expansion potential for export-qualified manufacturers with established bioequivalence documentation. São Paulo and Rio de Janeiro fertility centers drive prescription acceleration as assisted reproductive technology protocols incorporate clomiphene citrate in ovarian stimulation regimens.
Clomiphene Citrate Market Competitive Landscape
The competitive structure tilts toward vertically integrated pharmaceutical conglomerates with captive API production and established gynecology portfolios. Tiered differentiation separates premium-brand reproductive medicine specialists from cost-optimized generic suppliers serving high-volume fertility clinic contracts. Three archetypes dominate: multinational originators with legacy brand equity, Indian generic houses with CDSCO export registration, and vertically integrated API-to-formulation producers. Capacity expansion in extended-release tablet platforms and strategic partnerships for telemedicine-enabled distribution represent the dominant competitive moves.
Within the multinational originator tier, Sanofi S.A. and Merck & Co. Inc. occupy positions anchored by established gynecology portfolios and brand recognition among fertility specialists. Teva Pharmaceutical Industries Ltd. exemplifies the vertically integrated archetype through in-house production of generic active pharmaceutical ingredients. Cipla Inc. and Emcure Pharmaceuticals Ltd. represent Indian generic houses competing on cost-optimized oral tablet supply chains with CDSCO-registered export capabilities. Par Pharmaceutical and Unichem Laboratories Ltd. sit within mid-scale specialist positions serving regional fertility clinic networks.
| Leading Market Players |
|---|
| Par Pharmaceutical |
| Unichem Laboratories Ltd. |
| Sanofi S.A. |
| Serum Institute of India Pvt. Ltd. |
| Emcure Pharmaceuticals Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Cipla Inc. |
| Incepta Pharmaceuticals Ltd. |
| Merck & Co. Inc. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into generic API production anchors both supply security and margin defense for established pharmaceutical manufacturers serving fertility clinic networks. Teva Pharmaceutical Industries Ltd. and comparable vertically integrated players capture procurement preference by controlling upstream active pharmaceutical ingredient supply while insulating formulation pricing from raw material volatility.
Pricing Analysis
Bundled service agreements that combine API supply with regulatory compliance documentation command premium positioning against unbundled tablet-only transactions. Three-tier pricing structure across premium, standard, and economy levels separates EMA GMP-certified European manufacturers from CDSCO-registered Indian suppliers and domestic-only producers. Cost compression in standard-tier oral tablets is intensifying because fertility clinic purchasing consortia concentrate volume leverage among fewer buyers. Hospital-affiliated reproductive centers in the United States demonstrate the least price sensitivity due to protocol standardization requirements, while independent gynecology centers in South Asia exhibit the highest.
Supply Chain Analysis
Direct-to-fertility-clinic distribution channels handle high-volume procurement from metropolitan reproductive health systems, bypassing traditional wholesale intermediaries. Active pharmaceutical ingredient production concentrates in India, China, and the United States, with formulation finishing distributed across European and North American facilities. Clomiphene citrate synthesis draws from triphenylethylene intermediates, specialty chemical precursors, and pharmaceutical-grade excipients. Single-source vulnerability in Indian API manufacturing exposes buyers to disruption risks from CDSCO enforcement actions or environmental compliance shutdowns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The clomiphene citrate market functions as a stable compounder underpinned by demographic-driven expansion in assisted reproductive technology cycles. Sustained prescription volume growth from fertility clinic network consolidation generates predictable cash flow characteristics for positioned suppliers.
For Market Incumbents: Deepen captive API production capabilities to defend margin position against letrozole substitution pressure and generic price erosion. Prioritize EMA GMP certification investments for European fertility clinic access while extending controlled-release formulation pipelines to capture premium protocol positioning. For New Entrants and Emerging Players: Telemedicine-enabled prescription channels offer the most penetrable route for bypassing established wholesale relationships and accessing direct-to-clinic distribution. Target reproductive hospitals in Brazil and Mexico where ANVISA regulatory alignment creates qualification windows for export-ready manufacturers with bioequivalence documentation. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale API-to-formulation producers because fertility clinic procurement centralization rewards suppliers with integrated quality documentation systems. Platform consolidation around CDSCO-registered Indian manufacturers with FDA dual-registration capabilities offers durable value creation across a five-to-ten year window. Monitor EMA warning letter trends as the inflection signal for supply chain eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Development | Modified-release tablets reduce dosing frequency for fertility clinic protocol compliance advantages. |
| EMA GMP Certification Investment | Facility upgrades secure European procurement preference as inspection intensification disqualifies competitors. |
| Telemedicine Distribution Partnership | Remote fertility consultations enable direct-to-clinic channels bypassing wholesale intermediaries. |
| CDSCO-FDA Dual Registration | Dual qualification opens regulated export markets while serving domestic reproductive hospital demand. |
| REACH Compliance Documentation | Pre-registered supply chains capture procurement preference from audit-ready documentation requirements. |
Research Methodology
Bottom-up fertility clinic procurement modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with reproductive endocrinologists, hospital procurement managers, regulatory affairs specialists, and pharmaceutical manufacturing executives combined with secondary validation from FDA filings, EMA inspection reports, CDSCO registration databases, and ClinicalTrials.gov ovarian stimulation protocol records. Cross-referencing prescription volume data against manufacturing capacity disclosures enables triangulation between demand-side and supply-side indicators.
Input-output matrices map clomiphene citrate flows from API synthesis through formulation finishing to end-user dispensing across dosage form, therapy area, delivery mode, and regional regulatory cluster dimensions. Compound annual growth rate derivation rests on fertility clinic expansion trajectories, IVF cycle penetration rates, and formulation technology adoption curves throughout the forecast period. Ovarian stimulation protocol evolution and letrozole substitution elasticity inform scenario-weighted projections.
The model assumes a particular technology adoption path for extended-release tablet platforms; alternative pathways for immediate-release dominance would alter the outlook. Forecasts reflect assumptions regarding EMA inspection enforcement intensity, CDSCO export harmonization progress, and fertility clinic network consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ground Calcium Carbonate Market
Bulk Chemicals
Bulk Ingredients Market
Bulk Chemicals
Dextrin Market
Bulk Chemicals
Global Sodium Phosphate Market
Bulk Chemicals
United States Calcium Chloride Market
Bulk Chemicals
Global Bitumen Market
Bulk Chemicals
Alunite Market
Bulk Chemicals
Lignin Waste Market
Bulk Chemicals
Asia-Pacific Quicklime Market
Bulk Chemicals
Acetochlor Market
Bulk Chemicals
1-Hexene Market
Bulk Chemicals
Asia-Pacific Ammonium Nitrate Market
Bulk Chemicals
Nahcolite Market
Bulk Chemicals
Calcium Chloride Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market