
 United States IT Services Market | 2026-2036
United States IT Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States IT Services Market Analytics
Healthcare delivery is pivoting toward cloud-native patient management systems, pulling IT services demand from traditional on-premises installations. Microsoft leverages its Azure health data services to anchor hospital network migrations. IBM sustains mainframe modernization contracts with federal health agencies. Accenture differentiates through workflow automation for clinical operations.
United States IT Services encompasses the design, implementation, management, and optimization of information technology infrastructure, software systems, and digital operations for commercial and government clients, typically delivered through service-level agreements specifying uptime, response time, and security performance thresholds. Cloud Services now captures the fastest expansion as enterprises retire legacy data centers, while Cybersecurity commands premium pricing due to zero-trust architecture mandates. Managed Services remains the mature revenue base, though margin compression intensifies in commoditized server monitoring contracts.
NIST, FedRAMP, and HIPAA collectively shape procurement standards, with FedRAMP authorization now a prerequisite for federal cloud contracts and HIPAA Security Rule updates driving healthcare encryption investments. State-level data privacy laws in California and Virginia add compliance layers for cross-border service delivery. Stakeholders must monitor evolving SEC cybersecurity disclosure rules for material incident reporting.
Market Dynamics
FedRAMP authorization requirements and NIST cybersecurity frameworks are compressing vendor qualification timelines while concentrating federal cloud procurement among pre-authorized providers. Healthcare encryption mandates under HIPAA Security Rule updates are forcing infrastructure refresh cycles.
Growth Catalysts
- Zero-trust architecture mandates:Federal agencies now require continuous identity verification and micro-segmentation, expanding managed security service contracts.
- Texas data center corridor expansion:Hyperscale facility construction in Dallas-Fort Worth and Austin is pulling fiber connectivity and edge computing deployments.
- Legacy mainframe retirement:Federal health agencies are accelerating COBOL system migrations to cloud-native platforms, sustaining multi-year modernization programs.
Market Restraints
- Specialized talent scarcity:FedRAMP-certified security engineers and cleared cloud architects command premium compensation, compressing service margins.
- Input cost volatility:GPU and high-bandwidth memory pricing fluctuations are destabilizing AI infrastructure project economics.
- Regulatory friction:State-level data privacy fragmentation between California CCPA amendments and Virginia CDPA creates compliance duplication for multi-state service delivery.
Strategic Opportunities
- Rural healthcare networks:Critical Access Hospitals in Montana, Wyoming, and Alaska remain underpenetrated for telehealth infrastructure and remote patient monitoring integration.
- AI-workload optimization services:Convergence of machine learning operations platforms with Kubernetes orchestration creates new advisory and implementation revenue streams.
- SEC cybersecurity disclosure rules:Material incident reporting requirements for publicly traded clients are expanding governance, risk, and compliance consulting engagements.
Industry Challenges
- Multi-cloud integration complexity:Enterprises operating across AWS, Azure, and Google Cloud environments face escalating interoperability and cost-optimization challenges.
- FedRAMP authorization timelines:The 12-18 month certification process delays product launches and freezes engineering resources in documentation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States IT Services Market |
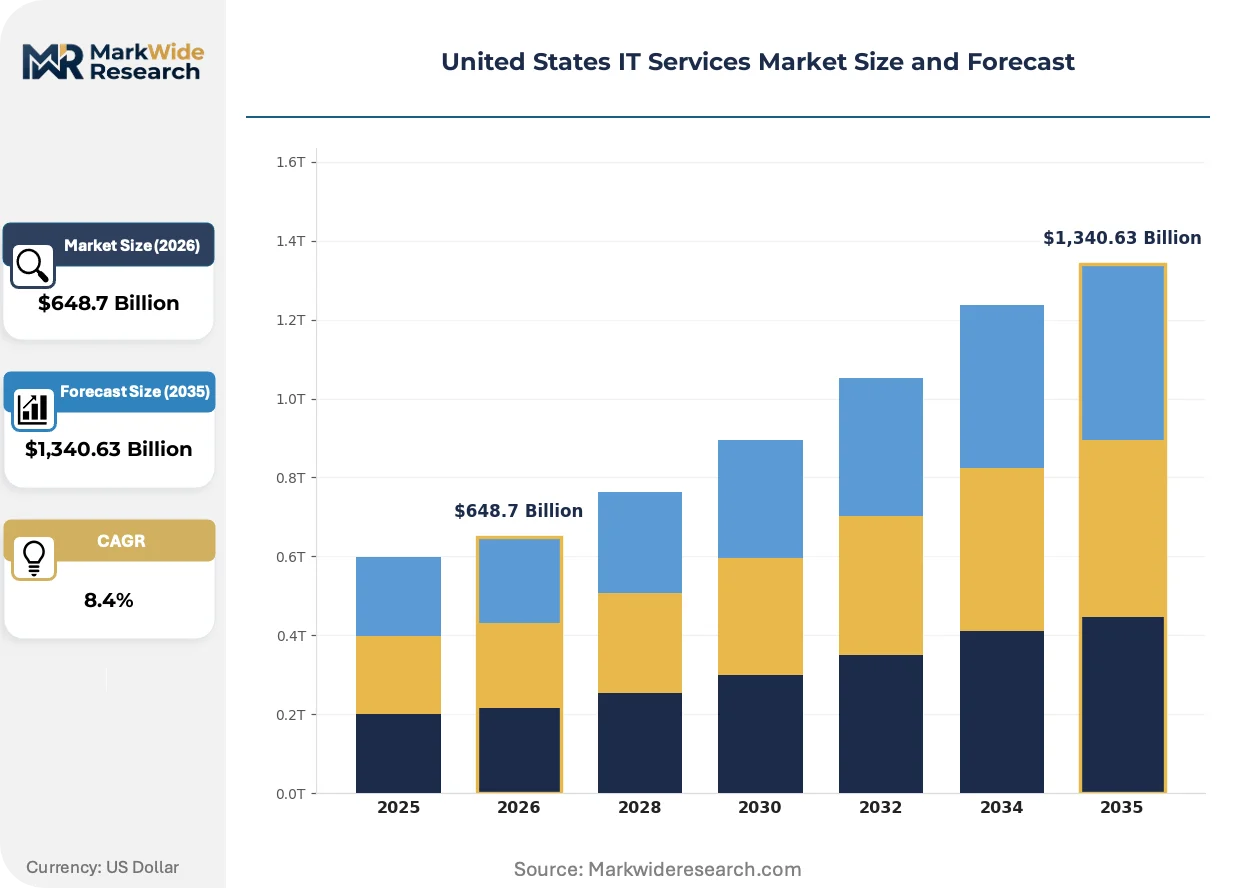
| Market Size in 2026 | $648.7 Billion |
| Market Size in 2035 | $1,340.63 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Services, Cloud Services, IT Consulting, Cybersecurity End User: SMBs, Large Enterprises, Government Agencies, Non-Profits Technology: Artificial Intelligence, Machine Learning, Blockchain, IoT Deployment: On-Premises, Cloud-Based, Hybrid, Virtual |
| Companies Covered | TCS, Microsoft, IBM, Google, Amazon, Accenture, Oracle, Cisco Systems, Cognizant, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States IT Services Market Evolving Landscape
Edge computing architectures and sovereign cloud deployments are fragmenting the traditional hyperscale concentration model. Service providers are reconfiguring delivery networks to address latency-sensitive workloads and data residency requirements.
Distributed edge nodes are decentralizing compute placement away from centralized hyperscale regions toward metropolitan and rural aggregation points. Manufacturing firms and autonomous vehicle developers are deploying these architectures for sub-20-millisecond response requirements. This topology is decentralizing the vendor landscape by enabling regional colocation providers to capture workloads previously monopolized by cloud giants.
SEC cybersecurity disclosure mandates are forcing publicly traded enterprises to document material incident response protocols and board-level oversight structures. This regulatory pressure is expanding demand for virtual Chief Information Security Officer services and automated compliance monitoring tools. Financial services and energy sector clients in New York and Texas are accelerating these investments ahead of enforcement deadlines.
Consumption-based pricing models are displacing fixed-term enterprise agreements across mid-market software procurement. Value-added resellers and managed service providers are unbundling implementation from ongoing support to capture recurring revenue streams. This transition is most visible among SaaS-heavy healthcare and professional services clients in California and Massachusetts seeking operational expenditure alignment.
United States IT Services Market Segmentation
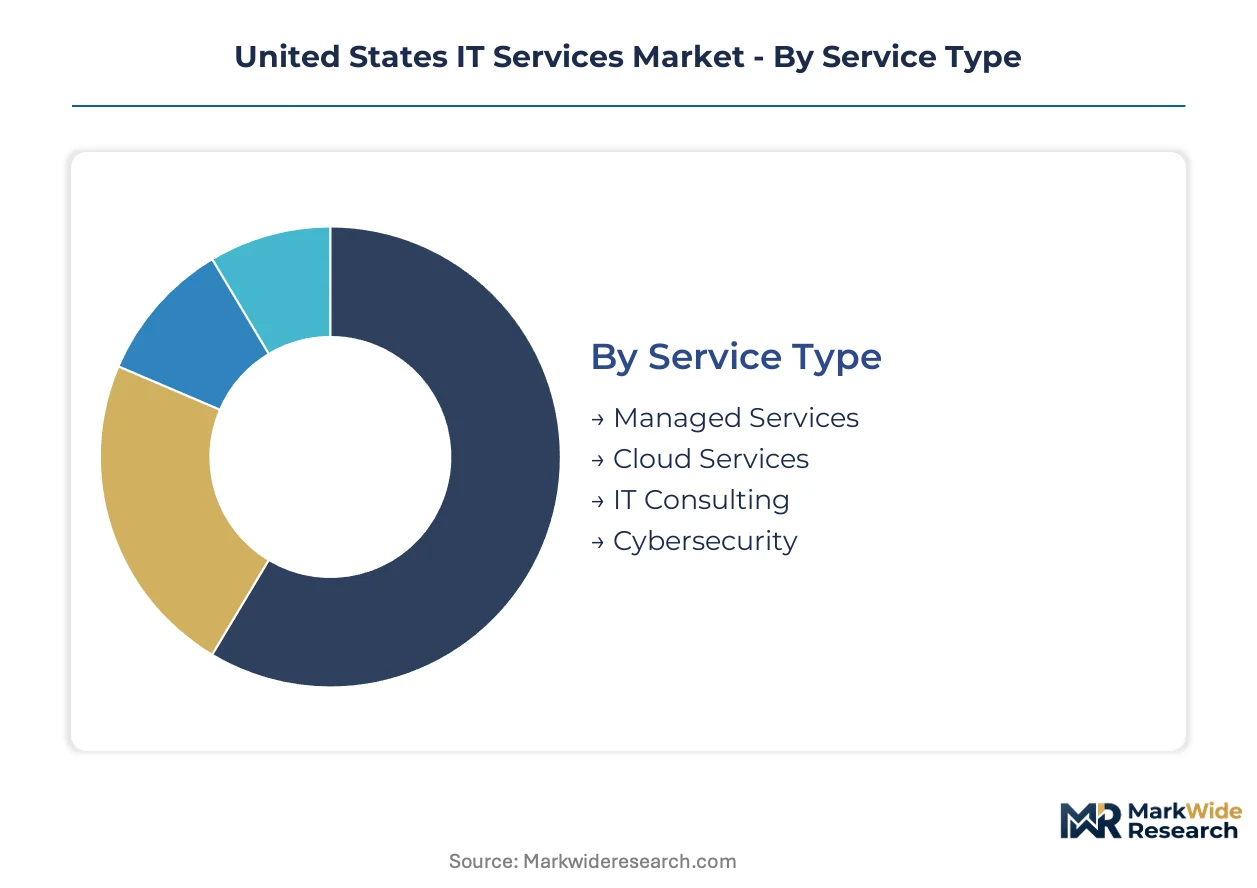
IT services procurement in the United States fractures across service delivery models, buyer scale, technology maturity, and infrastructure topology. Each segmentation axis carries distinct margin profiles, contract structures, and regulatory exposure that reshape competitive positioning.
Service Type:
Buyer selection hinges on internal capability gaps versus capital efficiency trade-offs.
- Managed Services:Comprehensive outsourcing of infrastructure monitoring, patch management, and helpdesk operations through multi-year contracts with SLA-guaranteed uptime. Federal health agencies in Maryland and Virginia sustain the largest contract volumes as COBOL mainframe retirement accelerates, though margin compression intensifies in commoditized server monitoring tiers.
- Cloud Services:Scalable compute, storage, and platform resources delivered via subscription or consumption models with FedRAMP authorization prerequisites. Texas and California data center corridors absorb hyperscale facility investment, pulling fiber connectivity and edge computing deployments from enterprise buyers retiring legacy data centers.
- IT Consulting:Advisory engagements spanning digital transformation roadmapping, vendor selection, and change management implementation.
- Cybersecurity:Managed detection and response, zero-trust architecture deployment, and compliance auditing services.
Volume sits with Managed Services; growth tilts toward Cloud Services.
End User:
Contract complexity and procurement cycle length scale directly with organizational sophistication and regulatory burden.
- SMBs:Mid-market firms with 100-999 employees purchasing standardized service bundles through channel partners and value-added resellers. California and Massachusetts professional services firms are displacing fixed-term enterprise agreements with consumption-based pricing models to align operational expenditure with revenue cycles.
- Large Enterprises:Fortune 1000 corporations operating multi-cloud environments across AWS, Azure, and Google Cloud with dedicated procurement teams. Multi-cloud integration complexity is escalating interoperability and cost-optimization challenges for these buyers.
- Government Agencies:Federal, state, and local entities with FedRAMP authorization mandates and NIST cybersecurity framework compliance requirements.
- Non-Profits:Healthcare systems, educational institutions, and charitable organizations with grant-funded technology investments.
Revenue concentrates with Large Enterprises; expansion accelerates fastest among SMBs.
Technology:
Adoption velocity correlates with demonstrated ROI transparency and implementation risk mitigation.
- Artificial Intelligence:Generative AI deployment, predictive analytics, and intelligent automation requiring GPU-intensive infrastructure. GPU and high-bandwidth memory pricing fluctuations are destabilizing project economics for these workloads.
- Machine Learning:Model training pipelines, MLOps platforms, and inference optimization services. Convergence with Kubernetes orchestration is creating new advisory and implementation revenue streams for service providers.
- Blockchain:Distributed ledger implementations for supply chain traceability and digital identity verification.
- IoT:Sensor network deployment, edge data processing, and device fleet management across industrial and healthcare settings.
Investment flows heaviest into Artificial Intelligence; Machine Learning gains share fastest.
Deployment:
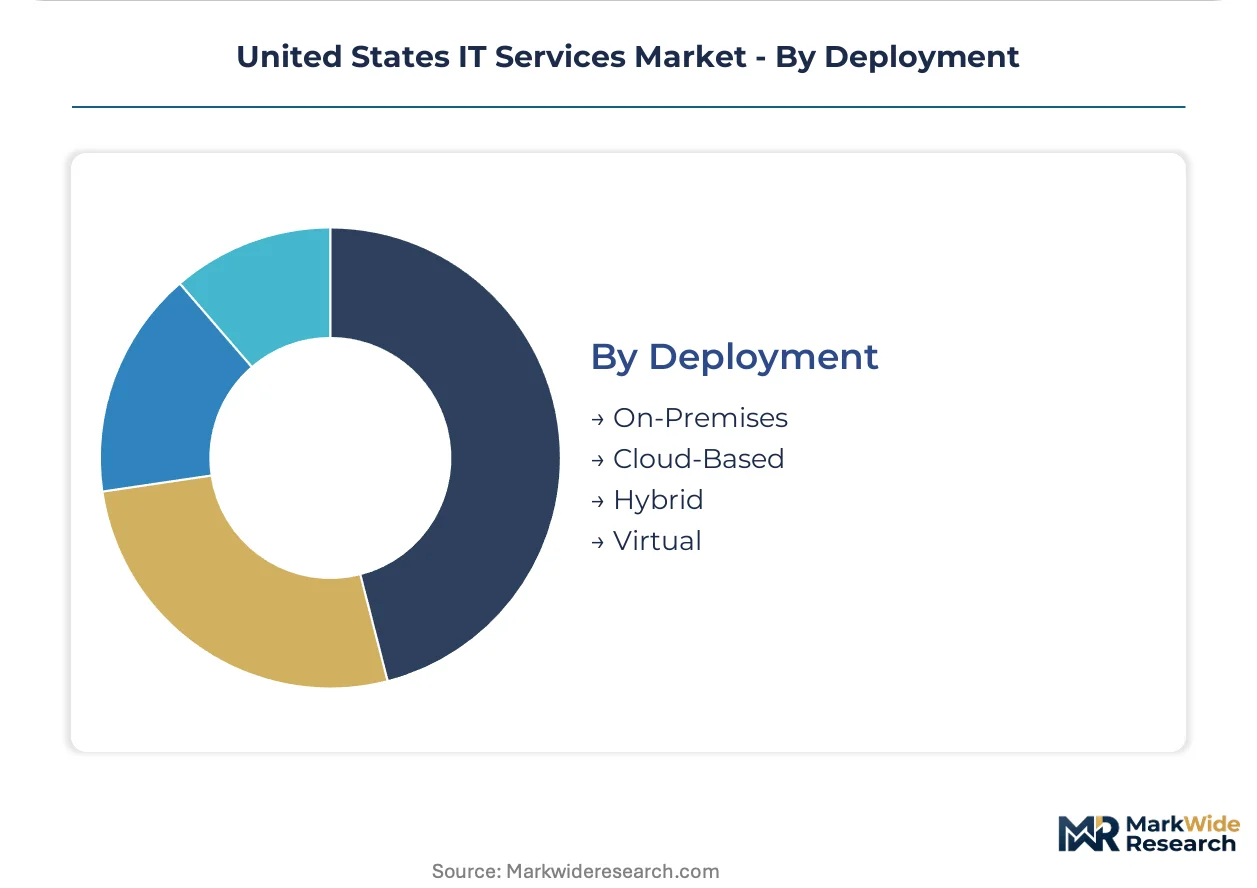
Latency requirements and data sovereignty obligations are fragmenting the traditional hyperscale concentration model.
- On-Premises:Dedicated hardware and software installations within client-controlled facilities with full capital ownership. Federal health agencies sustain residual demand for air-gapped systems handling classified patient data.
- Cloud-Based:Fully outsourced infrastructure with no local hardware footprint and subscription-based pricing. SEC cybersecurity disclosure mandates are expanding governance, risk, and compliance consulting engagements for publicly traded cloud adopters.
- Hybrid:Orchestrated workloads spanning private data centers and public cloud resources with unified management planes.
- Virtual:Desktop-as-a-service and application virtualization delivered through thin-client endpoints.
Hybrid architectures command the largest project values; Cloud-Based deployments scale most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and federal data center tax incentives are concentrating IT services investment in designated enterprise corridors. State-level compliance regimes and specialized workforce pools further fragment procurement patterns across sub-regional markets.
Texas
Hyperscale facility construction in Dallas-Fort Worth and Austin is pulling fiber connectivity and edge computing deployments from enterprise buyers retiring legacy data centers. The Texas Economic Development Act provides property tax abatements for data center investments exceeding $200 million. Houston's energy sector headquarters are expanding managed security service contracts to meet SEC cybersecurity disclosure mandates ahead of enforcement deadlines.
Virginia
Federal cloud procurement concentrates in Northern Virginia's data center alley, where FedRAMP-authorized providers capture multi-year modernization contracts. NIST cybersecurity frameworks govern vendor qualification timelines for agencies in the national capital region. Loudoun County and Prince William County host the densest fiber interconnection points for latency-sensitive government workloads.
California
Healthcare systems in the Bay Area and Los Angeles metro are displacing fixed-term enterprise agreements with consumption-based pricing models for operational expenditure alignment. CCPA amendments and emerging state privacy regulations create compliance duplication for multi-state service delivery. San Diego's defense contractors are expanding zero-trust architecture deployments under federal mandates.
Illinois
Chicago's financial services sector is accelerating governance, risk, and compliance consulting engagements ahead of SEC cybersecurity disclosure rule enforcement. The Illinois Data Transparency and Privacy Act adds state-level compliance layers for cross-border service delivery. The city's derivatives exchanges and commodity trading firms are deploying AI-workload optimization services for algorithmic trading infrastructure.
Massachusetts
Greater Boston's biotechnology cluster is expanding cloud-native patient management system migrations from traditional on-premises installations. HIPAA Security Rule updates are forcing infrastructure refresh cycles among Cambridge and Waltham pharmaceutical headquarters. The region's research hospitals are sustaining demand for workflow automation in clinical operations.
United States IT Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud providers capturing volume in standardized infrastructure while systems integrators retain premium positioning in regulated verticals. The vendor base organizes around three strategic archetypes: platform-native service arms of infrastructure giants, legacy technology consultancies with federal clearance pipelines, and boutique cybersecurity specialists with FedRAMP certification. Competitive moves concentrate on strategic partnerships for multi-cloud orchestration capabilities and vertical-specific compliance automation.
Within the platform-native tier, Microsoft and Amazon exemplify the infrastructure-anchored service model, leveraging hyperscale facility investments to capture enterprise workload migrations. IBM occupies a position bridging legacy mainframe modernization and cloud-native federal health agency contracts. Accenture represents the workflow automation specialist archetype, with clinical operations optimization distinguishing its healthcare vertical positioning.
| Leading Market Players |
|---|
| TCS |
| Microsoft |
| IBM |
| Amazon |
| Accenture |
| Oracle |
| Cisco Systems |
| Cognizant |
| Others |
Value Network & Pricing Analysis
FedRAMP-certified security engineers concentrated in Northern Virginia and Maryland command compensation premiums that compress service margins and widen pricing spreads between authorized and non-authorized provider tiers. Labor-cost differentials between cleared federal contractors and commercial IT service providers create three distinct pricing bands across the market.
Pricing Analysis
Short lead-time engagements for zero-trust architecture deployments carry 30-40 percent premiums over standard procurement cycles, while spot availability of GPU-intensive infrastructure for AI workloads commands additional surcharges. The dominant structure is subscription-based SaaS-tiered pricing with consumption scaling, differentiated by FedRAMP authorization status and vertical-specific compliance automation depth. Pricing pressure stems from GPU and high-bandwidth memory cost volatility destabilizing AI project economics. SMB buyers in California and Massachusetts exhibit highest price sensitivity through their shift to consumption-based models, while federal health agencies in Maryland demonstrate lowest sensitivity given mandate-driven procurement requirements.
Supply Chain Analysis
FedRAMP authorization and NIST framework compliance function as qualification gates that filter vendor participation and concentrate federal procurement among pre-cleared providers. Supply concentrates in the United States, India, and Ireland for IT services delivery, with domestic hyperscale facilities in Texas and Virginia anchoring cloud infrastructure. Raw material dependencies center on NVIDIA GPUs, high-bandwidth memory modules, and specialized fiber optic interconnects. Single-source vulnerability around GPU supply from Taiwan Semiconductor Manufacturing creates procurement risk for AI workload providers. Distribution runs through direct enterprise sales teams, value-added resellers, and systems integrators with federal clearance pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where FedRAMP authorization timelines create artificial scarcity that props pricing for certified providers. Capacity bottlenecks in cleared security engineering talent sustain margin premiums across federal-facing service tiers.
For Market Incumbents: Deploy workflow automation platforms to offset clinical operations labor costs and defend margin position against boutique cybersecurity specialists. Consolidate multi-cloud orchestration capabilities through strategic partnerships to address interoperability complexity threatening renewal rates. Accelerate mainframe modernization capture in federal health agencies before COBOL skill scarcity forces price concessions. For New Entrants and Emerging Players: Value-added resellers with existing healthcare relationships represent the most viable channel wedge for cloud-native patient management system penetration. Rural Critical Access Hospitals in Montana, Wyoming, and Alaska present underpenetrated white-space for telehealth infrastructure integration. Target AI-workload optimization advisory services as the fastest-expanding implementation revenue stream with lowest incumbent saturation. For Investors and Strategic Acquirers: Re-rating potential sits with boutique cybersecurity specialists holding FedRAMP certification given SEC disclosure mandate expansion and zero-trust architecture proliferation. Long-term viability favors providers with dual commercial-federal revenue streams that smooth procurement cycle volatility. Monitor FedRAMP authorization timeline compression as the critical inflection signal for competitive entry dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Multi-cloud orchestration capabilities address interoperability complexity across AWS, Azure, and Google Cloud environments for Fortune 1000 clients. |
| Strategic Partnership | Regional colocation alliances enable edge computing capture in Texas and Virginia corridors previously monopolized by hyperscale providers. |
| Acquisition of Specialist Firm | FedRAMP-certified boutique security providers command scarcity premiums under federal zero-trust architecture mandates. |
| Geographic Expansion | Rural healthcare network penetration in Montana and Alaska unlocks telehealth infrastructure contracts with Critical Access Hospitals. |
| Product Launch | AI-workload optimization services leveraging Kubernetes orchestration capture new advisory revenue from biotechnology clusters in Massachusetts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with CTOs, IT procurement officers, platform engineers, and federal contracting officers. SEC cybersecurity disclosure submissions, FedRAMP authorization databases, hyperscaler capex disclosures, and hospital procurement records provided validation layers. Bottom-up service line builds and top-down macroeconomic adjustment were triangulated to ensure consistency.
Reconciliation across demand-side deployment schedules and supply-side capacity announcements informed the analytical framework over the projection horizon. Segmentation dimensions modeled include service type, end-user scale, deployment topology, and regional regulatory cluster. CAGRs were derived from weighted average growth trajectories across these segments. GPU pricing volatility and FedRAMP authorization velocity served as key forecast sensitivity inputs.
Caveats apply where NIST framework revisions or SEC enforcement timeline shifts could materially shift the outlook for compliance-driven procurement. Forecasts reflect assumptions regarding sustained federal health agency modernization budgets and continued hyperscale facility investment in designated data center corridors. A model refresh is warranted upon material change in FedRAMP authorization processing timelines or GPU supply chain normalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Municipal Software Market
Software & Services
Global Database Management Software Market
Software & Services
Global Online Assessment Software Market
Software & Services
Global Business Management Software Market
Software & Services
Bank Reconciliation Software Market
Software & Services
Global Data Extraction Software Market
Software & Services
Saas-Based Expense Management Market
Software & Services
Construction Enterprise Resource Planning (ERP) Software Market
Software & Services
Lead Scoring Software Market
Software & Services
Employee Wellness Software Market
Software & Services
Live Chat Software Market
Software & Services
Global Android Kiosk Software Market
Software & Services
Machine Translation Software Market
Software & Services
Computer Backup Software Market
Software & Services
Global VR Game Engine Software Market
Software & Services
Dropshipping Software Solutions Market