
 Global Qualitative Data Analysis Software Market | 2026-2036
Global Qualitative Data Analysis Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Qualitative Data Analysis Software Market Foresight
ISO 27001 certification is unwinding the competitive landscape for qualitative data analysis platforms, elevating data security credentials from optional to mandatory for institutional procurement. NVivo leverages its long-standing academic relationships to sustain dominant positioning across research-intensive universities. ATLAS.ti differentiates through multi-language support and visual mapping tools that anchor its appeal in European social science departments. MAXQDA competes aggressively on pricing flexibility, extending modular subscription tiers that occupy the mid-market segment between premium and entry-level offerings.
Qualitative data analysis software comprises computational platforms designed for systematic coding, categorization, and pattern extraction from unstructured text, audio, video, and mixed-media sources, typically supporting concurrent multi-user collaboration with audit trails and inter-rater reliability metrics. These systems serve primary commercial and industrial purposes in academic research validation, consumer insight generation, and policy evidence-building where human interpretive rigor must combine with scalable data processing. Cloud-based deployment leads solution architecture as research teams prioritize remote collaboration and reduced IT maintenance burdens, while coding and categorization functions capture concentrated margin pools due to their centrality in every analytical workflow. Text analysis capabilities within the solution layer are gaining fastest traction as natural language processing integrations expand automated theme detection beyond manual coding protocols.
FDA 21 CFR Part 11 guidelines shape demand for audit-capable platforms in clinical and health-related qualitative research, while GDPR and EU AI Act provisions in Europe enforce strict data residency and algorithmic transparency requirements that filter vendor eligibility. Japan's METI guidelines on AI utilization in research further complicate cross-border software deployment for multinational studies. Stakeholders must monitor evolving national AI governance frameworks and align platform selection with jurisdiction-specific compliance architectures rather than assuming uniform global deployability.
Market Dynamics
Cloud migration is compressing deployment cycles for qualitative data analysis platforms while ISO 27001 certification requirements are hardening institutional procurement gates. Academic research institutions and government bodies now mandate audit-capable systems with transparent algorithmic processing.
Growth Catalysts
- EU AI Act compliance mandates:European research institutions must deploy platforms with algorithmic transparency and data residency controls, filtering vendor eligibility toward certified providers.
- Mixed-methods research expansion:Academic departments across the United States, Germany, and Australia are consolidating quantitative and qualitative workflows onto unified platforms.
- Natural language processing integration:Automated theme detection capabilities are accelerating coding workflows in text-heavy disciplines like sociology and public health.
Market Restraints
- Specialized talent scarcity:Research teams lack personnel trained in both qualitative methodology and computational platform administration.
- Cross-border data friction:Japan's METI guidelines on AI utilization complicate multinational study deployments requiring jurisdictional segmentation.
- Legacy system stickiness:Established university IT infrastructures resist cloud-native migrations due to sunk costs in on-premise security architectures.
Strategic Opportunities
- Underpenetrated health research segment:FDA 21 CFR Part 11 guidelines create demand for audit-trail-capable platforms in clinical qualitative studies.
- Modular subscription innovation:Tiered access models are opening mid-market segments between premium institutional licenses and entry-level individual subscriptions.
- Visual analytics convergence:Integration of network mapping tools with traditional coding interfaces is capturing interest in European social science departments.
Industry Challenges
- Interoperability complexity:Research teams struggle to synchronize qualitative platforms with statistical software like R and SPSS in mixed-methods workflows.
- Certification timeline compression:ISO 27001 and SOC 2 audit cycles delay product launches as vendors race to meet institutional procurement deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Qualitative Data Analysis Software Market |
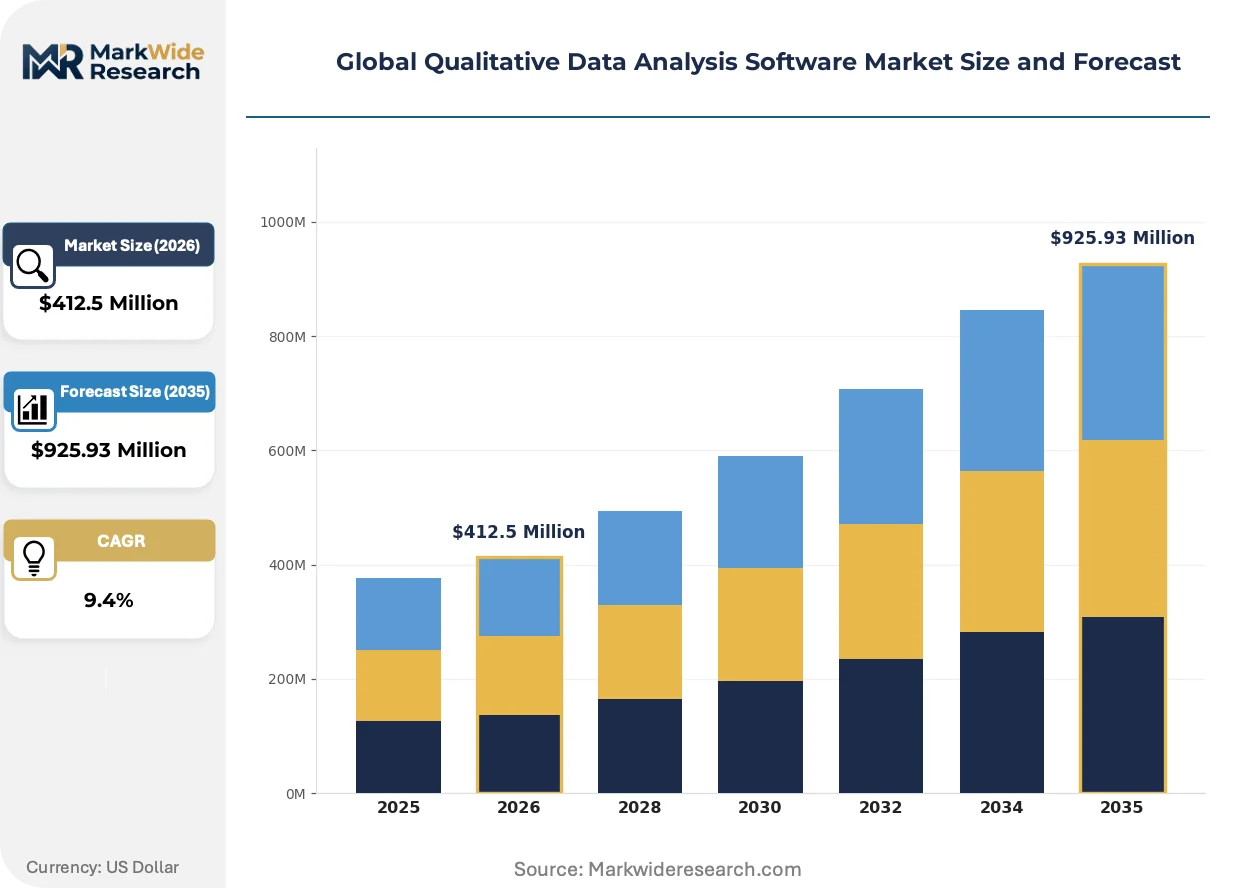
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $925.93 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Web-Based, Mobile Solution: Coding & Categorization, Text Analysis, Audio & Video Analysis, Survey Analysis, Report Generation Application: Academic Research, Market Intelligence, Social Sciences, Customer Experience, Competitive Analysis End User: Research Firms, Government Agencies, Educational Institutes, Nonprofit Organizations, Media Companies |
| Companies Covered | Dedoose, Quirkos, NVivo, Raven’s Eye, QuestionPro, ATLAS.ti, QDA Miner, Lumivero, MAXQDA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Qualitative Data Analysis Software Market Shifts & Advancements
Computational platforms for qualitative research are undergoing architectural transformation as remote collaboration requirements and automated analysis capabilities reshape core functionality. Three distinct vectors are redirecting competitive investment and user adoption patterns.
Natural language processing engines embedded within coding interfaces are miniaturizing manual theme extraction workflows. Social science departments at research-intensive universities are adopting these tools at accelerating pace. The technology is miniaturizing traditional coding labor, compressing project timelines from months to weeks while raising methodological debates about human interpretive validity.
Germany's implementation of GDPR data residency provisions alongside EU AI Act algorithmic transparency requirements is forcing platform architecture redesigns. Vendors must now maintain European-hosted infrastructure with explainable AI documentation. Health-related qualitative research in France and the Netherlands faces the strictest compliance filters, pushing procurement toward established providers with pre-certified deployments.
Subscription unbundling is fragmenting traditional license structures. Research teams now purchase modular access to specific functions rather than comprehensive platform suites. This pattern is most visible in Australian university consortia, where shared service models distribute costs across departments with divergent methodological needs.
Global Qualitative Data Analysis Software Market Segmentation
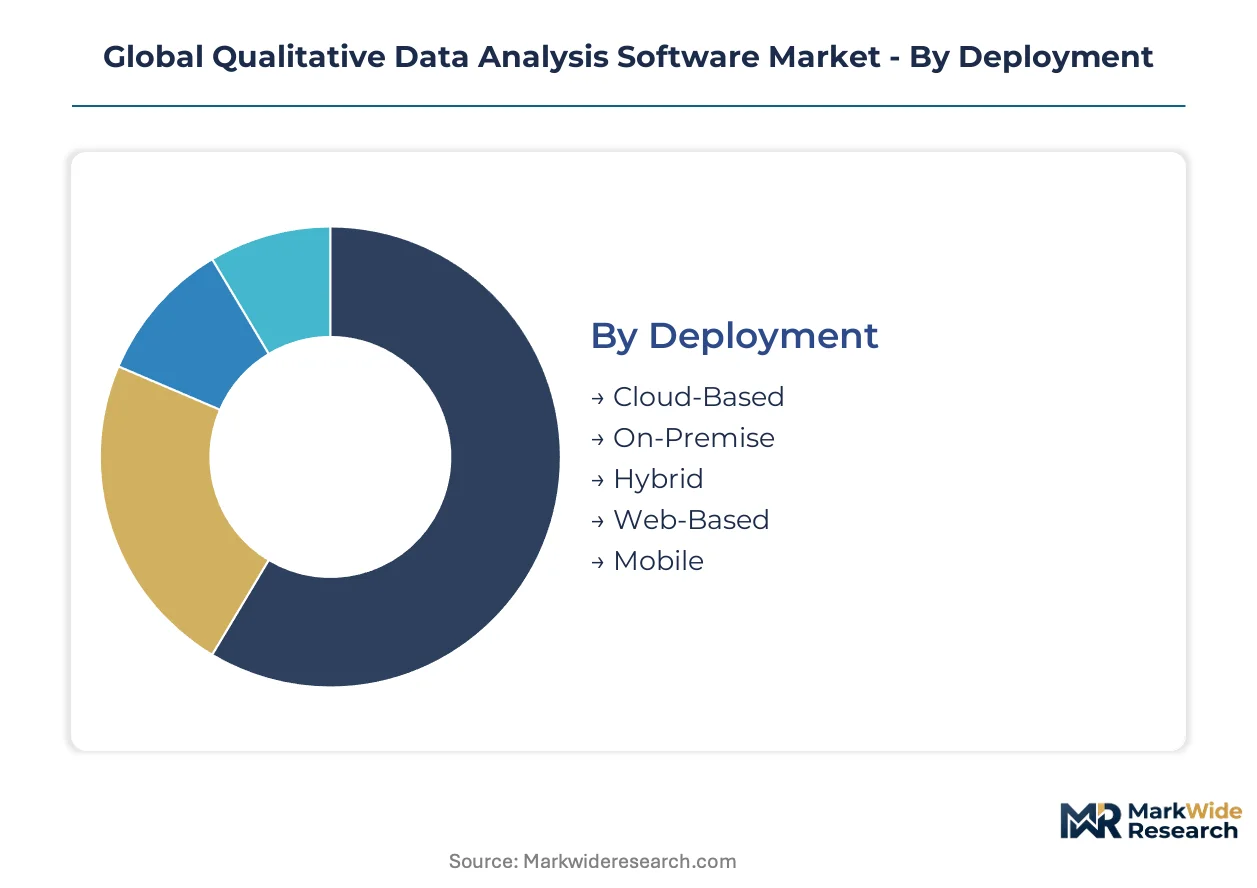
Segmentation in qualitative data analysis software reveals how procurement patterns diverge across deployment architectures, analytical functions, and institutional buyer types. Understanding these fault lines helps vendors align certification investments and channel strategies with where purchasing power actually concentrates.
Deployment:
Channel mix varies sharply by deployment mode, with cloud-based solutions flowing through direct vendor sales and academic consortia while on-premise deployments route through systems integrators and university IT procurement offices.
- Cloud-Based:Multi-tenant SaaS architectures with automatic updates and browser-based access. Demand concentrates at research-intensive universities in the United States and Germany where IT departments lack resources for self-managed infrastructure. EU AI Act data residency requirements are forcing European-hosted instance offerings.
- On-Premise:Locally installed software running on institutional servers with full data sovereignty. Government agencies in Australia and defense-related research bodies in Germany maintain procurement preference here due to classified data handling protocols. Higher upfront license costs and dedicated IT staffing requirements constrain adoption outside well-funded institutional buyers.
- Hybrid:Split architectures with sensitive data processed on-premise and collaborative features cloud-hosted. Australian university systems and Canadian health research networks are adopting this model to balance GDPR compliance with remote team coordination.
- Web-Based:Lightweight browser applications with limited offline functionality. Individual researchers and small nonprofit teams in the United Kingdom and Netherlands favor this for rapid project initiation without IT approval cycles.
- Mobile:Smartphone and tablet applications for field data capture and preliminary coding. Anthropology and ethnography departments at universities in Kenya and Brazil are early adopters for remote community research.
By volume, Cloud-Based leads. By growth pace, Hybrid is climbing the fastest as compliance complexity drives architectural compromise.
Solution:
Margin concentration follows functional centrality, with coding and categorization modules commanding premium pricing while report generation tools face commoditization from adjacent business intelligence platforms.
- Coding & Categorization:Core functionality for systematic tagging of qualitative data with hierarchical code structures and inter-rater reliability metrics. Sociology and public health departments across German and Australian universities drive concentrated demand here. ISO 27001 certification has become table stakes for institutional procurement.
- Text Analysis:Natural language processing engines for automated theme extraction and sentiment scoring. Mixed-methods researchers in United States political science and epidemiology departments are adopting these tools to compress project timelines. Algorithmic transparency documentation under EU AI Act is reshaping vendor qualification.
- Audio & Video Analysis:Transcription synchronization, timestamped coding, and multimodal annotation capabilities. Market intelligence teams at consumer research firms in the United Kingdom and Japan use these for focus group analysis.
- Survey Analysis:Integration with quantitative survey platforms for convergent mixed-methods designs. Australian government policy evaluation units and Canadian health services research groups are primary buyers.
- Report Generation:Automated visualization and manuscript preparation tools. This segment faces margin pressure from generic data visualization platforms and academic writing assistants.
By revenue contribution, Coding & Categorization dominates. By adoption velocity, Text Analysis is expanding most quickly as NLP capabilities mature.
Application:
Customer lifetime value diverges across application segments, with market intelligence buyers showing higher churn and academic research clients demonstrating stronger renewal persistence.
- Academic Research:Dissertation projects, grant-funded studies, and institutional repository requirements. Universities in the United States, Germany, and Australia represent the concentrated demand core. Budget cycles tied to fiscal year ends create predictable procurement seasonality.
- Market Intelligence:Consumer insight generation and brand positioning research. Corporate research departments and specialized agencies in the United Kingdom and Japan drive demand here. Project-based purchasing creates revenue volatility.
- Social Sciences:Ethnography, anthropology, and sociology field studies. European departments in the Netherlands and France maintain strong preference for multi-language and visual mapping capabilities.
- Customer Experience:Voice-of-customer programs and service journey mapping. Retail and telecommunications firms in Australia and Canada are expanding deployment.
- Competitive Analysis:Rival strategy assessment and industry intelligence synthesis. Management consultancies and private equity research teams in the United States and United Kingdom are primary users.
By installed base, Academic Research leads. By expansion trajectory, Customer Experience is gaining share fastest as enterprises broaden VoC program scope.
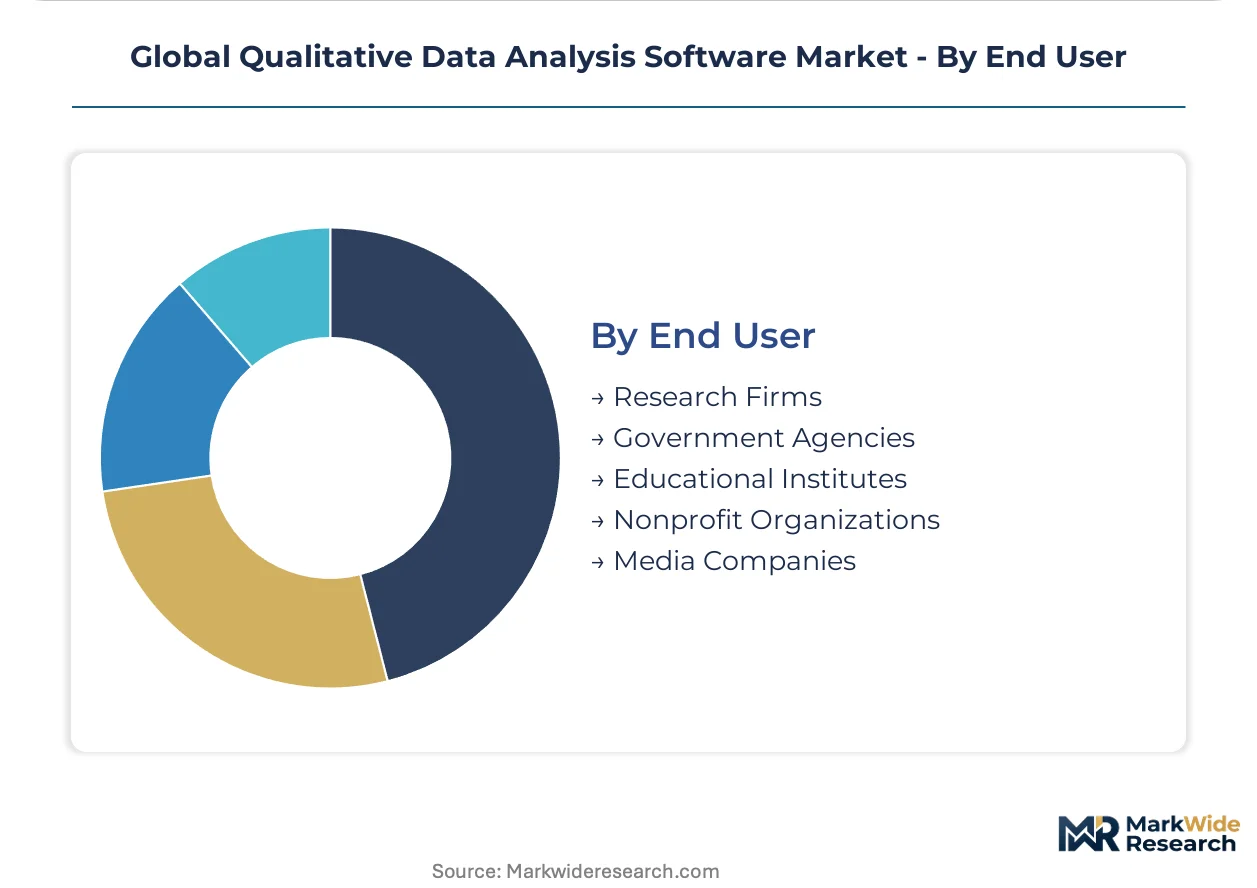
End User:
Procurement sophistication varies by end user type, with government agencies imposing the most stringent compliance requirements and educational institutes showing the longest sales cycles.
- Research Firms:Commercial organizations selling analytical services to corporate and government clients. Firms in the United States and United Kingdom prioritize platform interoperability with statistical software like R and SPSS. Project-based licensing flexibility is a decisive selection criterion.
- Government Agencies:National statistical offices, policy evaluation units, and regulatory research bodies. Australian and Canadian agencies are mandating audit trails and data residency controls. FDA 21 CFR Part 11 compliance shapes health-related procurement in the United States.
- Educational Institutes:Universities, colleges, and research centers with mixed undergraduate and graduate programs. Campus-wide licensing negotiations in Germany and Australia involve consortium purchasing with multi-year terms.
- Nonprofit Organizations:NGOs, advocacy groups, and international development organizations. Budget constraints drive preference for entry-level subscriptions and open-source alternatives, particularly in sub-Saharan Africa and South Asia.
- Media Companies:Newsrooms and content analysis departments tracking public discourse and audience sentiment. Publishers in the United Kingdom and Japan are deploying these tools for social media monitoring and investigative research.
By contract value, Research Firms lead. By procurement momentum, Government Agencies are advancing most quickly as audit requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 guidelines in the United States and EU AI Act mandates in Europe are redirecting procurement budgets toward audit-capable platforms with transparent algorithmic processing. Research software vendors must now maintain jurisdiction-specific infrastructure to retain institutional eligibility.
United States
Academic medical centers and NIH-funded research consortia drive concentrated demand for FDA-compliant platforms. HIPAA privacy rules intersect with 21 CFR Part 11 audit trail requirements for clinical qualitative studies. The Boston-Cambridge research corridor anchors adoption of mixed-methods platforms integrating with statistical software workflows.
Germany
Max Planck Institute networks and federal research funding bodies mandate GDPR-compliant data residency for all grant-supported projects. EU AI Act algorithmic transparency documentation filters vendor eligibility toward established providers with European-hosted infrastructure. Berlin and Munich university systems lead procurement volume for multi-language qualitative platforms.
Australia
National Health and Medical Research Council audit requirements shape platform selection for health-related qualitative studies. State-level university consortia in New South Wales and Victoria negotiate shared service agreements distributing costs across departments. Government policy evaluation units in Canberra drive demand for survey-integrated mixed-methods solutions.
United Kingdom
ESRC funding guidelines emphasize reproducibility standards that favor platforms with documented inter-rater reliability metrics. UK Research and Innovation data management policies require institutional data sovereignty controls. London-based media companies and management consultancies deploy text analysis tools for competitive intelligence and audience sentiment tracking.
Japan
METI guidelines on AI utilization in research complicate multinational study deployments requiring jurisdictional segmentation. Corporate market intelligence teams in Tokyo prioritize platforms with Japanese-language NLP capabilities. Keio and University of Tokyo social science departments balance international collaboration needs against domestic regulatory constraints.
Global Qualitative Data Analysis Software Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and institutional relationship tenure. The vendor landscape stratifies into three tiers: established academic platforms with decades-long university relationships, mid-market modular providers competing on pricing flexibility, and emerging cloud-native entrants prioritizing remote collaboration features. Competitive moves center on ISO 27001 certification acceleration and European infrastructure deployment to satisfy EU AI Act data residency mandates.
Within the established academic tier, NVivo and ATLAS.ti exemplify divergent geographic positioning strategies. NVivo anchors dominant relationships across Anglophone research-intensive universities. ATLAS.ti occupies strong positioning in European social science departments through multi-language interface support. MAXQDA sits within the mid-market modular segment, representing pricing-tier innovation through unbundled subscription access that opens procurement paths for smaller research teams and individual scholars.
| Leading Market Players |
|---|
| Dedoose |
| Quirkos |
| NVivo |
| Raven's Eye |
| QuestionPro |
| ATLAS.ti |
| QDA Miner |
| Lumivero |
| MAXQDA |
| Others |
Supply & Pricing Matrix
Scale economies in cloud infrastructure provision compress cost bases for SaaS-native vendors while elevating price floors for on-premise competitors serving compliance-heavy institutional buyers. United States-based hyperscaler capacity anchors the cost structure for multi-tenant deployments, whereas German and Australian data residency requirements force vendor investment in localized hosting that translates into regional pricing premiums.
Pricing Analysis
Certification level creates the primary spread between vendor tiers, with ISO 27001 and FDA-grade audit capabilities commanding subscription premiums from academic medical centers and government research bodies. Three-tier pricing structure across premium, standard, and economy levels segments by compliance depth and collaboration scale, with modular unbundling accelerating in Australian university consortia seeking function-specific procurement. Cost compression in mid-market tiers intensifies as MAXQDA-style subscription innovation erodes legacy license stickiness. Nonprofit organizations and individual researchers exhibit highest price sensitivity, while NIH-funded consortia and Max Planck Institute networks demonstrate lowest elasticity due to grant-embedded software budgets.
Supply Chain Analysis
United States and Germany anchor cloud infrastructure provisioning for research software platforms, with Ireland and Netherlands serving as GDPR-compliant European hosting nodes. Software development draws from distributed engineering talent pools in India and Poland, while customer success and methodology consulting feed from academic hubs in Boston-Cambridge and Berlin. Single-source vulnerability concentrates in hyperscaler dependencies for AI/ML compute layers. Distribution runs through direct vendor sales teams for enterprise licenses, academic consortia for volume purchasing, and systems integrators for on-premise government deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs durable defensive moats for established platforms, as ISO 27001 certification and jurisdiction-specific infrastructure deployment create switching costs that lock institutional buyers into multi-year relationships.
For Market Incumbents: Consolidate certification depth by accelerating SOC 2 and EU AI Act compliance documentation ahead of procurement deadline compression at German and Australian funding bodies. Deepen vertical integration into European-hosted infrastructure to defend margin position against cloud-native entrants lacking data residency capabilities. Channel control through exclusive academic consortium partnerships represents the decisive lever for volume retention. For New Entrants and Emerging Players: Differentiate on visual analytics convergence and mobile-first field capture to penetrate anthropology and ethnography departments at universities in Kenya and Brazil where legacy platform presence remains thin. Target health research segments in Canada and Australia where FDA 21 CFR Part 11 and NHMRC audit requirements filter vendor eligibility toward audit-capable challengers. Freemium-to-modular conversion paths open procurement channels for underfunded nonprofit researchers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platforms with established academic consortium relationships, as campus-wide licensing agreements generate predictable renewal streams across multi-year horizons. Acquisition target archetypes include mid-market modular providers with pricing-tier innovation and European social science specialists with multi-language interface depth. Monitor EU AI Act implementation timelines as inflection indicators for compliance-driven vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| European Infrastructure Deployment | EU AI Act data residency mandates filter vendor eligibility toward providers with Frankfurt or Amsterdam hosting. |
| Platform Integration with Statistical Software | R and SPSS interoperability addresses mixed-methods workflow friction at United States political science departments. |
| Modular Subscription Unbundling | Function-specific access tiers penetrate mid-market segments between premium institutional licenses and individual subscriptions. |
| NLP Engine Embedding | Automated theme detection compresses project timelines for text-heavy sociology and public health disciplines. |
| Academic Consortium Partnership | Shared service agreements across New South Wales and Victoria university systems distribute procurement costs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vendor certification databases, funding body procurement guidelines, and hyperscaler infrastructure disclosures. Research directors at Max Planck Institutes, NIH program officers, and Australian NHMRC evaluation leads provided qualitative input on platform selection criteria. IT procurement managers at German universities and cloud architects at SaaS vendors supplied technical validation. Secondary sources include FDA 21 CFR Part 11 guidance documents, EU AI Act implementation texts, ISO 27001 certification registries, and academic consortium licensing agreements. Bottom-up deployment modeling triangulates against top-down market sizing.
Segmentation dimensions modeled span deployment architecture, analytical function, application use case, and end-user procurement sophistication across the projection horizon. Organization size and vertical integration complexity further stratify demand estimates. CAGRs derive from trend extrapolation against regulatory deadline impacts and technology adoption S-curves. NLP capability maturation and cloud migration velocity serve as primary forecast inputs.
The analysis sits within stated boundaries; outcomes outside EU AI Act enforcement intensity or academic funding stability assumptions would require recalibration. Forecasts reflect documented procurement patterns and compliance-driven vendor filtering. Shifts in national AI governance frameworks or hyperscaler pricing architecture would necessitate revision. Recalibration cycles align with material shifts in regulatory enforcement and infrastructure cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
United Arab Emirates (UAE) Cloud Accounting Software Market
Software & Services
Global Business Software Market
Software & Services
Estate Management Software Market
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Global Decision Support Software Market
Software & Services
Global Mobile Middleware Market
Software & Services
North America Saas-Based Expense Management Market
Software & Services
House Cleaning App Market
Software & Services
Global Database Management Software Market
Software & Services
Test Automation Market
Software & Services
PLM Software Market
Software & Services
Agile Application Life-Cycle Management Market
Software & Services
Hypervisor Market
Software & Services
Debt Collection Software Market
Software & Services
Global Digital Signage Software Market
Software & Services
Global Custom Software Development Services Market