
 Global Ipad POS Software Market | 2026-2036
Global Ipad POS Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ipad POS Software Market Outlook
GDPR is expanding the cost-of-entry calculus for iPad POS software vendors targeting European hospitality chains. Toast leverages cloud-native architecture to sustain compliance overhead without fragmenting its product stack. Square anchors its position through integrated payment hardware and merchant banking services that reduce third-party dependency. Lightspeed competes across retail and restaurant verticals with modular inventory tools that extend platform stickiness.
iPad POS software comprises tablet-native point-of-sale applications that leverage iOS touch interfaces, Bluetooth peripheral connectivity, and cloud-synced transaction databases to process payments, manage inventory, and generate real-time analytics for merchant operations. Cloud-based deployment leads the segment due to lower upfront infrastructure requirements and automatic security patching, while subscription pricing dominates revenue models by converting capital expenditure into predictable recurring streams. Hardware-integrated solutions command premium positioning as merchants seek unified terminal-printer-scanner bundles that reduce setup complexity and support tickets.
The EU AI Act, PCI DSS standards, and state-level biometric privacy laws in Illinois and Texas shape product development roadmaps and market access conditions for iPad POS vendors. FDA food-safety traceability rules indirectly drive restaurant demand for inventory-linked POS systems that capture lot-level ingredient data. Stakeholders must monitor how fragmented privacy regulations across California, Europe, and emerging Asian markets fragment certification requirements and inflate compliance engineering budgets.
Market Dynamics
Cloud-native iPad POS architectures are compressing deployment timelines from weeks to days, forcing legacy terminal vendors to abandon on-premise hardware stacks or cede mid-market restaurant chains to software-first competitors.
Growth Catalysts
- Quick-service restaurant digitization:Texas and Florida restaurant clusters are replacing fixed terminals with tablet-based checkout systems to reduce counter footprint and labor handoff delays.
- GDPR compliance automation:European hospitality chains now require certified data-handling architectures, accelerating replacement cycles for non-compliant legacy POS systems.
- Bluetooth peripheral ecosystems:Wireless receipt printers and barcode scanners are eliminating cable management costs in high-turnover retail environments.
Market Restraints
- Payment processor concentration:Three dominant networks control interchange fee structures, squeezing margin for independent software vendors that lack captive banking licenses.
- Biometric privacy fragmentation:Illinois BIPA and Texas biometric laws impose conflicting consent architectures, forcing vendors to maintain parallel codebases for state-specific deployments.
- Hardware bundle margin compression:Unified terminal-printer-scanner packages face input cost volatility from semiconductor foundry capacity constraints in East Asia.
Strategic Opportunities
- India FSSAI traceability mandates:Food-safety lot-tracking requirements are creating demand for inventory-linked POS systems in organized food retail and quick-service chains.
- Embedded finance convergence:Integration of merchant cash advances and business banking within POS interfaces is displacing standalone lending relationships.
- Saudi MOHAP hospitality licensing:New digital compliance requirements for food establishments are accelerating tablet-based system adoption in Riyadh and Jeddah foodservice clusters.
Industry Challenges
- PCI DSS certification timelines:Annual security audits and SAQ validation create 4-6 month product release delays for feature updates touching payment data flows.
- Legacy ERP synchronization:Mid-market restaurant groups operating 20-year-old back-office systems require expensive custom API development for real-time inventory sync.
- ISO 27001 talent scarcity:Security engineering roles with cloud infrastructure and compliance documentation expertise command 40% salary premiums in competitive labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ipad POS Software Market |
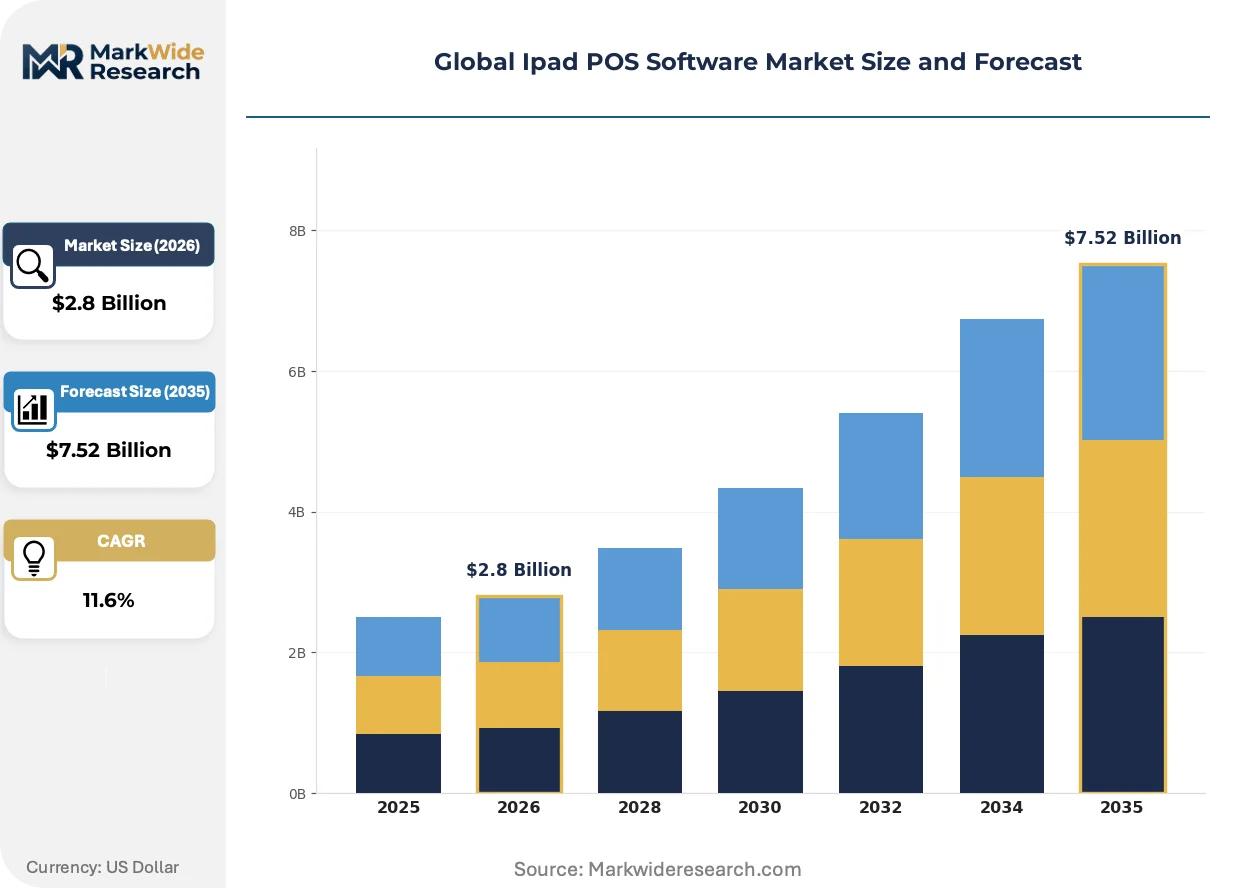
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.52 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premise, Cloud-based, Hybrid, Web-based End User: Retail Stores, Restaurants, Hospitality, E-commerce Product Type: Software Suites, Mobile Applications, Hardware Integrated Solutions, Custom Solutions Pricing Model: Subscription, One-time License, Freemium, Usage-based |
| Companies Covered | Revel Systems, Lightspeed, Shopify POS, ShopKeep, Toast, Square, TouchBistro, Talech, Bindo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ipad POS Software Market Strategic Shifts
Touch-first iOS interfaces are redefining merchant onboarding expectations, compressing training requirements while expanding the addressable market to smaller operators previously priced out of enterprise-grade POS capabilities.
API-first POS platforms is overtaking monolithic software suites in the mid-market restaurant segment. These modular systems allow operators to swap payment processors, loyalty engines, and delivery aggregators without re-platforming. Fast-casual chains with 10-50 locations are adopting at the fastest pace, enabling multi-vendor best-of-breed stacks that reduce vendor lock-in and accelerate feature iteration cycles.
REACH substance restrictions and EU AI Act algorithmic transparency requirements are forcing vendors to document training data provenance for recommendation engines embedded in upsell modules. Hospitality software providers must now maintain technical files demonstrating compliance with automated decision-making disclosure rules. Full-service restaurant chains deploying AI-driven wine pairing or menu suggestions face the steepest documentation burdens and are consolidating vendor relationships to reduce audit surface area.
Merchant preference for subscription pricing over perpetual licenses is restructuring vendor cash flow patterns and customer lifetime value calculations. Monthly SaaS arrangements with hardware-as-a-service add-ons are displacing five-year amortized purchase contracts in the United States quick-service segment. Operators in Texas and Florida clusters increasingly favor all-inclusive per-location fees that bundle software, support, and equipment replacement, transferring obsolescence risk to vendors while preserving capital for kitchen equipment and real estate expansion.
Global Ipad POS Software Market Segmentation
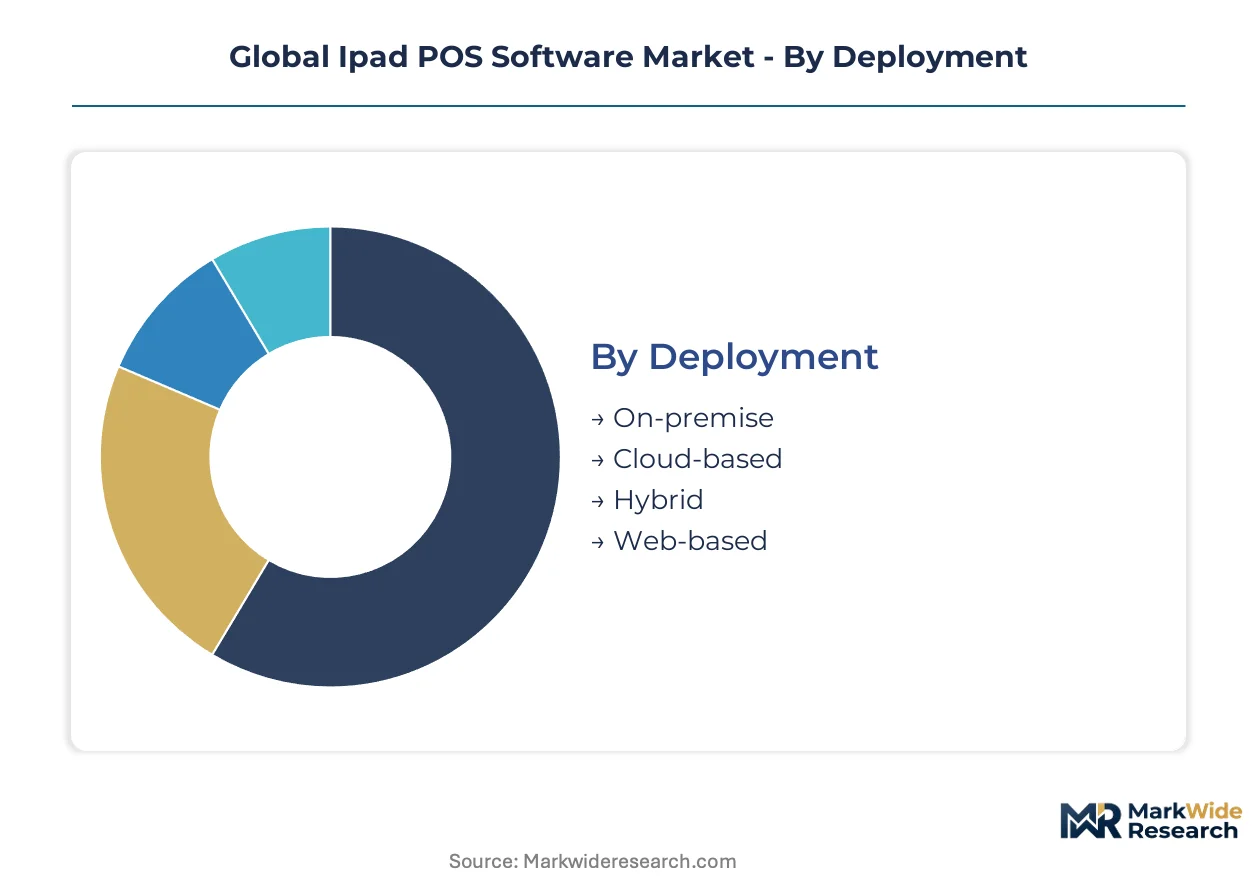
iPad POS software segments fragment across deployment architecture, end-use vertical, product packaging, and pricing mechanics. Each axis carries distinct margin profiles, compliance burdens, and customer acquisition economics that reshape vendor resource allocation.
Deployment:
Cloud-native architectures dominate new installations, compressing provisioning timelines and automating security patching cycles.
- Cloud-based:Multi-tenant SaaS platforms with automatic iOS compatibility updates and centralized PCI DSS certification. Quick-service restaurant clusters in Texas and Florida favor this model for zero on-site server maintenance and instant feature rollouts.
- Hybrid:Local transaction caching with cloud-synced analytics, preserving offline payment continuity during connectivity outages. European hospitality chains under GDPR mandate this architecture for data residency control combined with centralized reporting.
- On-premise:Dedicated server installations with manual update cycles, retaining relevance for high-security casino and government cafeteria environments with air-gapped network requirements.
- Web-based:Browser-rendered interfaces bypassing App Store distribution, appealing to multi-location operators seeking uniform experience across iPad and non-Apple tablets.
Cloud-based leads on scale; Hybrid leads on momentum among compliance-sensitive operators.
End User:
Vertical specialization determines peripheral integration depth and workflow customization intensity.
- Restaurants:Kitchen display system integration, table management, and tip distribution engines define core functionality. Texas and Florida quick-service chains drive replacement cycles from legacy terminals to tablet-based checkout.
- Retail Stores:Inventory-linked barcode scanning, customer loyalty tracking, and omnichannel return handling. Bluetooth peripheral ecosystems eliminate cable management in high-turnover environments.
- Hospitality:Property management system synchronization and guest folio charging. Saudi MOHAP licensing requirements in Riyadh and Jeddah accelerate tablet adoption for digital compliance documentation.
- E-commerce:Pop-up retail and dark kitchen operations requiring mobile-first transaction capture without fixed counter infrastructure.
Restaurants anchor current revenue; Hospitality climbs fastest on regulatory digitization mandates.
Product Type:
Packaging strategy shapes customer lifetime value and support ticket economics.
- Hardware Integrated Solutions:Bundled iPad-terminal, receipt printer, and cash drawer configurations with unified warranty coverage. Operators in Florida restaurant clusters favor all-inclusive per-location fees transferring obsolescence risk to vendors.
- Software Suites:Comprehensive modules spanning POS, inventory, and analytics without captive hardware. Mid-market restaurant groups with 20-year-old back-office systems require expensive custom API development for synchronization.
- Mobile Applications:Standalone iOS apps for line-busting and tableside ordering, often deployed as supplements to fixed terminals.
- Custom Solutions:White-label development for franchise systems with proprietary loyalty programs and reporting hierarchies.
Hardware Integrated Solutions dominate transaction volume; Software Suites gain share fastest on API-first platform preferences.
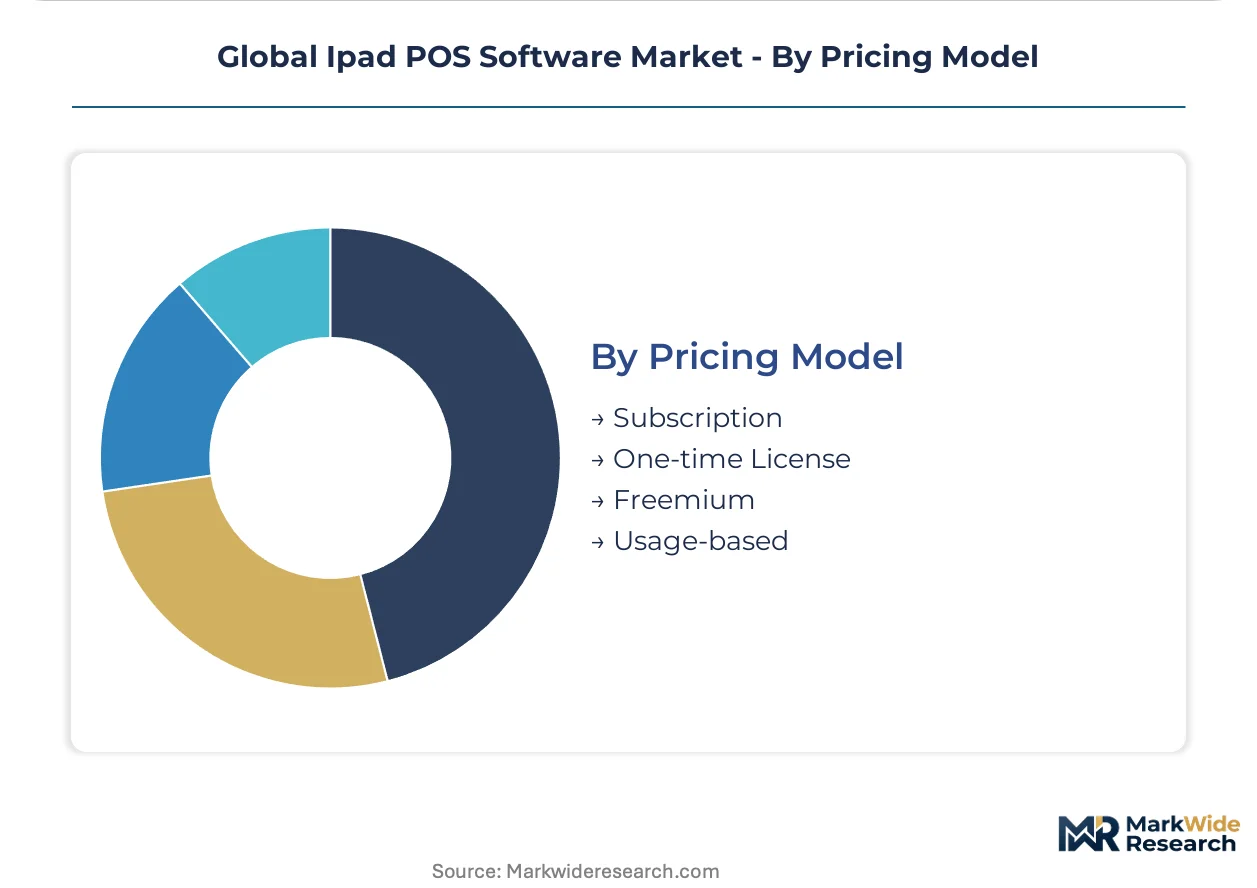
Pricing Model:
Revenue recognition patterns and customer acquisition costs vary sharply across payment structures.
- Subscription:Monthly SaaS arrangements with hardware-as-a-service add-ons displacing five-year amortized purchase contracts. United States quick-service segment shows strongest preference for predictable operating expenditure treatment.
- Freemium:Base transaction processing at no cost with premium features tiered by volume or capability. Micro-merchants and seasonal operators reduce upfront commitment while preserving upgrade pathway.
- One-time License:Perpetual software purchase with annual maintenance contracts, retaining foothold in institutional settings with capital budget cycles.
- Usage-based:Transaction-fee scaling without fixed platform charges, aligning costs directly with revenue generation for variable-volume operators.
Subscription leads on scale; Freemium shows steepest expansion trajectory among new merchant acquisition channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure talent concentrates in Seattle and San Francisco Bay Area engineering hubs, while hospitality software expertise clusters in Austin and Miami metro areas. These workforce distributions shape vendor R&D placement and customer support proximity.
United States
Texas and Florida quick-service restaurant clusters drive tablet-based checkout replacement cycles from legacy terminals. State-level biometric privacy laws in Illinois and Texas impose conflicting consent architectures that fragment vendor codebases. Miami and Orlando foodservice operators favor all-inclusive per-location subscription bundles that transfer hardware obsolescence risk to vendors.
Germany
GDPR compliance automation requirements accelerate replacement cycles for non-certified legacy POS systems among European hospitality chains. ECHA REACH substance restrictions force documentation of hardware component provenance for bundled terminal-printer-scanner packages. Berlin and Munich restaurant groups prioritize hybrid deployment architectures that preserve data residency control alongside centralized analytics.
India
FSSAI food-safety traceability mandates create demand for inventory-linked POS systems in organized food retail and quick-service chains. RBI payment aggregator licensing requirements constrain independent software vendor market entry without banking partnerships. Bangalore and Mumbai foodservice clusters adopt cloud-native tablet systems to compress deployment timelines from weeks to days.
Saudi Arabia
MOHAP hospitality licensing requirements mandate digital compliance documentation for food establishments. SFDA traceability rules indirectly drive demand for lot-level ingredient data capture in POS-linked inventory modules. Riyadh and Jeddah foodservice clusters accelerate tablet-based system adoption to satisfy new regulatory digitization requirements.
United Kingdom
FCA open banking regulations enable embedded finance convergence within POS interfaces, displacing standalone merchant lending relationships. GDPR and emerging AI transparency requirements pressure vendors to document algorithmic decision-making in upsell recommendation engines. London hospitality operators lead adoption of API-first platforms that allow processor swapping without re-platforming.
Global Ipad POS Software Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across deployment architecture and vertical specialization vectors. The market structure tilts toward consolidation as cloud-native architectures compress mid-market access for legacy terminal vendors. Three archetypes dominate: hardware-integrated platform operators, modular API-first specialists, and vertical-focused restaurant software providers. M&A activity concentrates on payment processor acquisitions and geographic expansion into compliance-heavy European and Middle Eastern markets.
Within the hardware-integrated tier, Toast and Square anchor positions through unified terminal-printer-scanner bundles and captive payment processing relationships. Lightspeed occupies a position exemplifying the modular API-first archetype, competing across retail and restaurant verticals with inventory tools that extend platform stickiness. These three companies represent the dominant competitive positioning patterns visible across the vendor landscape, with each anchoring a distinct strategic approach to customer acquisition and retention economics.
| Leading Market Players |
|---|
| Revel Systems |
| Lightspeed |
| Shopify POS |
| ShopKeep |
| Toast |
| Square |
| TouchBistro |
| Talech |
| Bindo |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure engineers concentrated in Seattle and San Francisco Bay Area engineering hubs command 40% salary premiums over comparable roles in secondary markets, widening the spread between premium-tier SaaS pricing and entry-level freemium offerings that target cost-conscious micro-merchants.
Pricing Analysis
Bundled hardware-software-service packages diverge sharply from unbundled software-only subscriptions across the Global Ipad POS Software Market. Three-tier pricing structure across premium, standard, and economy levels separates hardware-integrated solutions with unified warranty coverage from freemium entry points with transaction-fee scaling. Pricing pressure stems from semiconductor foundry capacity constraints in East Asia squeezing margins on terminal-printer-scanner bundles. Micro-merchants and seasonal operators exhibit highest price sensitivity, while full-service restaurant chains deploying AI-driven upsell modules demonstrate lowest sensitivity due to documentation burden consolidation needs.
Supply Chain Analysis
PCI DSS certification and ISO 27001 compliance documentation act as gating mechanisms that filter component suppliers and assembly partners across the Global Ipad POS Software Market. Semiconductor fabrication concentrates in Taiwan and South Korea, with final assembly and peripheral manufacturing anchored in China and Vietnam. Supply chains draw from Bluetooth chipsets, iOS-compatible receipt printer mechanisms, and cloud server capacity as critical inputs. Single-source vulnerability runs through Taiwan semiconductor foundries for payment processing chipsets. Distribution runs through direct vendor sales teams targeting mid-market restaurant groups and value-added resellers serving smaller independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Ipad POS Software Market functions as a regulatory compounder where compliance mandates—including the EU AI Act and GDPR—continuously refresh replacement demand by disqualifying non-certified legacy systems.
For Market Incumbents: Acquire payment processor banking licenses to reduce third-party dependency and capture interchange fee revenue streams. Consolidate vendor relationships with full-service restaurant chains facing steep AI documentation burdens under EU algorithmic transparency rules. Defensive positioning requires backward integration into captive hardware production to offset semiconductor cost volatility.
For New Entrants and Emerging Players: Begin with API-first platform architectures targeting fast-casual chains with 10-50 locations seeking multi-vendor best-of-breed stacks. Saudi Arabia and India offer the most penetrable geographies where MOHAP licensing and FSSAI traceability mandates accelerate tablet adoption without entrenched incumbent saturation. Go-to-market execution should emphasize zero on-site server maintenance and instant feature rollouts.
For Investors and Strategic Acquirers: Payment processors seeking merchant banking expansion represent the most active acquirer category in this space. Long-term viability favors vendors with hybrid deployment architectures that preserve data residency control alongside centralized analytics. Monitor PCI DSS certification timeline compression as the inflection signal indicating which vendors can sustain feature velocity under audit burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Payment Processor Acquisition | Captures interchange revenue and reduces third-party dependency for independent software vendors. |
| Hybrid Deployment Architecture | Preserves GDPR data residency control while enabling centralized analytics for European hospitality chains. |
| API-First Platform Integration | Allows fast-casual operators to swap loyalty engines and delivery aggregators without re-platforming. |
| Embedded Finance Convergence | Displaces standalone merchant lending relationships through integrated cash advances within POS interfaces. |
| Geographic Expansion into Compliance-Heavy Markets | EU AI Act and Saudi MOHAP mandates create replacement demand with limited incumbent saturation. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary research incorporated conversations with POS platform engineers, restaurant operations directors, hospitality procurement managers, and payment industry compliance officers. Secondary validation drew from SEC filings of publicly traded vendors, App Store distribution metrics, hyperscaler cloud infrastructure disclosures, and PCI DSS certification registries. Bottom-up merchant adoption modeling and top-down market sizing triangulated volume estimates.
Segment-weighting approaches distributed value across deployment architecture, end-use vertical, product packaging, and pricing mechanics. Cloud-native, hybrid, on-premise, and web-based deployment models each carried distinct provisioning timeline and compliance burden assumptions. CAGRs derived from replacement cycle analysis, regulatory mandate acceleration effects, and per-location subscription expansion patterns. Forecast inputs included quick-service restaurant digitization rates in Texas and Florida clusters and GDPR-driven replacement timelines among European hospitality chains.
Several conditions sit outside the modeled scope, including sudden shifts in semiconductor foundry capacity allocation, unilateral payment network interchange fee restructuring, and state-level biometric privacy law proliferation beyond Illinois and Texas. Forecasts reflect documented assumptions about cloud infrastructure cost trajectories and iOS compatibility maintenance burdens. A model refresh is warranted upon material change in PCI DSS audit timeline compression or EU AI Act enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Curriculum Mapping Software Market
Software & Services
Global Trade Promotion Management Software Market
Software & Services
Global Journal App Market
Software & Services
Global Customer Communications Management (CCM) Software Market
Software & Services
Global Reference Check Software Market
Software & Services
Real Estate Software Market
Software & Services
Global HVAC Software Market
Software & Services
Latin America Human Resource (HR) Technology Market
Software & Services
APAC Workforce Management Software Market
Software & Services
Asia Pacific Content Services Platform Market
Software & Services
Salesforce Services Market
Software & Services
Global Workforce Management Software Market
Software & Services
Global Disk Imaging Software Market
Software & Services
SAP Digital Services Ecosystem Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Fiber Simulation Software Market