
 Global Client Portal Software Market | 2026-2036
Global Client Portal Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Client Portal Software Market Foresight
ISO 27001 certification is rotating as the baseline qualification for enterprise procurement of client portal software. Moxo leverages its workflow automation specialization to anchor mid-market professional services firms. Clinked sustains geographic dominance across European accounting and legal partnerships through localized data residency controls. Zoho Desk competes on channel density, extending its portal modules through an established CRM distribution network.
Client portal software integrates authentication frameworks, role-based access controls, and API connectivity into a unified interface for external stakeholder interaction, typically deployed via RESTful architectures supporting SAML or OAuth 2.0 protocols for single sign-on. Its primary commercial purpose is to reduce service delivery costs while improving transparency in document exchange and project status communication. Cloud-based deployment leads solution type adoption as enterprises abandon on-premise maintenance overhead, though hybrid configurations are growing fastest among regulated industries requiring data sovereignty. Workflow automation within solution types captures concentrated margin pools where custom integration services attach to subscription renewals.
The EU AI Act and GDPR impose algorithmic transparency and data localization requirements that reshape product roadmaps for vendors serving European end users. The SEC and FINRA in the United States enforce communications archiving standards that drive financial services procurement toward compliant audit trail functionality. Stakeholders must monitor how divergent regulatory timelines across jurisdictions fragment platform standardization and inflate compliance engineering costs.
Market Dynamics
Financial services institutions are consolidating vendor relationships around platforms that embed audit-grade compliance infrastructure, compressing procurement cycles for standalone document management tools.
Growth Catalysts
- GDPR Article 30 mandates:EU-based asset managers must maintain records of processing activities, driving automated data lineage features into portal procurement specifications.
- Workflow automation convergence:Professional services firms now expect embedded e-signature, task routing, and milestone tracking within a single interface rather than stitching together point solutions.
- India's digital public infrastructure:The country's Account Aggregator framework and DigiLocker integration create native demand for citizen-facing portal architectures in banking and insurance.
Market Restraints
- API rate-limiting costs:Third-party identity verification services charge per-call fees that scale unpredictably with user volume, compressing margins on fixed-price SaaS contracts.
- Cloud concentration risk:Overreliance on hyperscale infrastructure in Ireland and Frankfurt creates operational vulnerability under EU data sovereignty rulings.
- Legacy authentication debt:Enterprises running Active Directory forests older than 2016 face SAML 2.0 compatibility gaps that delay cloud migration timelines.
Strategic Opportunities
- Brazil's Open Finance expansion:The central bank's phased consent-management rules create demand for customer-facing data sharing dashboards among mid-tier lenders.
- AI-assisted document classification:Natural language processing for contract extraction converges with portal upload workflows, reducing manual indexing labor in legal and real estate verticals.
- Embedded insurance distribution:Bancassurance partnerships require white-labeled client interfaces that carriers can deploy without core system replacement.
Industry Challenges
- ISO 27001 auditor scarcity:Certification backlog stretches to 14 weeks in key markets, delaying enterprise sales cycles that require proof of controls.
- Multi-tenant architecture tradeoffs:Shared infrastructure designs complicate data segregation proofs required by HIPAA-covered entities and German public sector buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Client Portal Software Market |
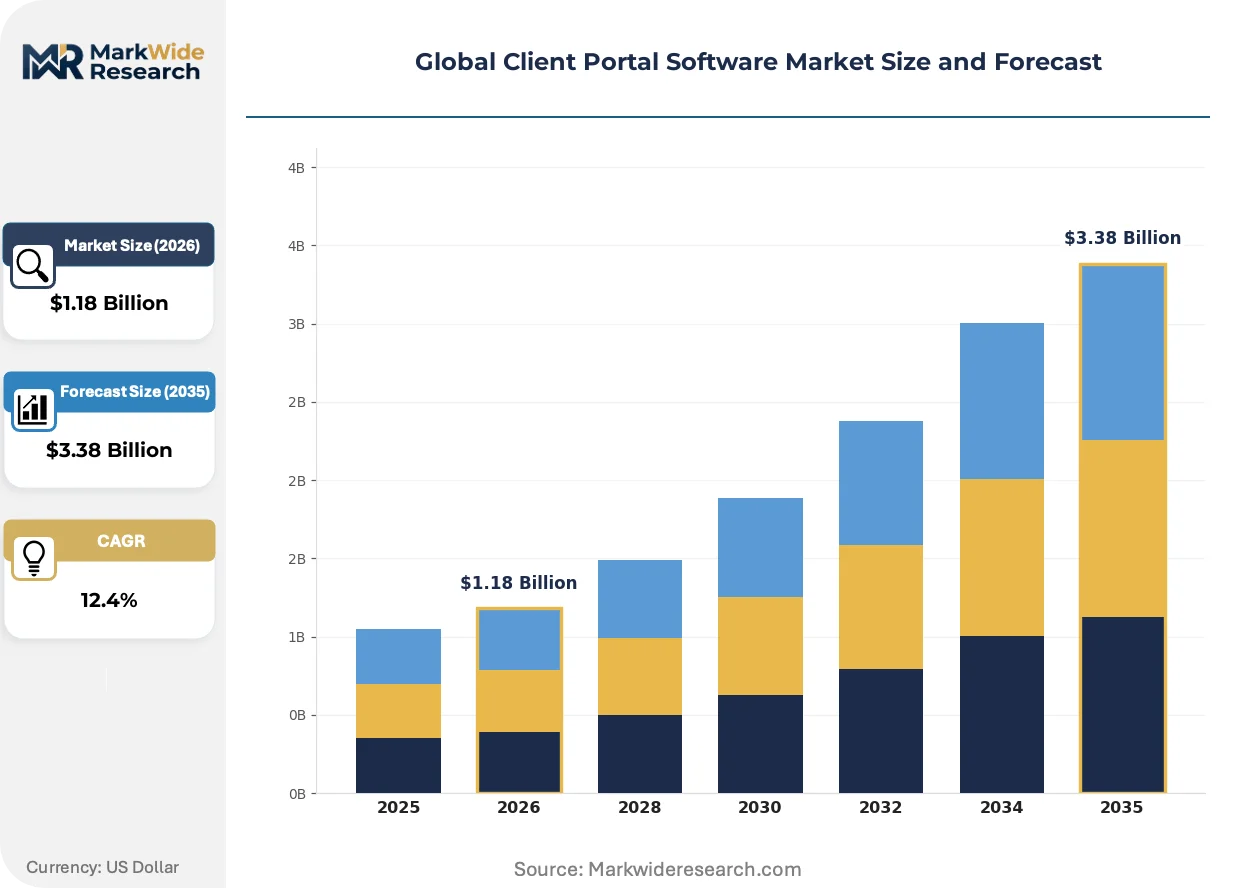
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $3.38 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution Type: Customer Support, Document Management, Collaboration, Analytics, Workflow Automation End User: Financial Services, Telecommunications, Public Sector, Education, Hospitality, Manufacturing Pricing Model: Subscription, Perpetual License, Freemium, Pay-As-You-Go, Enterprise Licensing |
| Companies Covered | SuiteFiles, Clinked, SuiteDash, Copilot, Moxo, Zite, Softr, Stacker, Zoho Desk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Client Portal Software Market Shifts & Advancements
Platform architectures are fragmenting into composable service meshes that let enterprises swap identity, storage, and workflow components without full-stack replacement.
Micro-frontend architectures are decomposing monolithic portal codebases into independently deployable modules. Large insurance carriers in Germany and the United States are piloting this approach to isolate regulatory updates from core feature releases. This decomposition is compressing vendor lock-in by letting IT teams retain control over routing and data layers while sourcing UI components from specialists.
The EU AI Act's risk classification framework is forcing vendors serving European financial institutions to document automated decision logic in client-facing disclosures. Product teams must now embed explainability interfaces for credit scoring and document routing algorithms. German and French banks are front-loading procurement evaluations to verify these capabilities before 2025 enforcement deadlines.
Subscription fatigue among mid-market professional services firms is displacing annual contracts with consumption-based pricing indexed to active user seats or document transaction volumes. Accounting partnerships in the United Kingdom and Australia are negotiating these terms to align software costs with seasonal client engagement patterns. This pricing rotation pressures vendors to instrument granular usage telemetry that legacy billing systems cannot support.
Global Client Portal Software Market Segmentation
Segmentation in client portal software reveals how procurement specifications diverge across regulatory environments, operational maturity, and integration complexity. Deployment choices carry compliance consequences that reshape vendor selection criteria in financial services and public sector procurement.
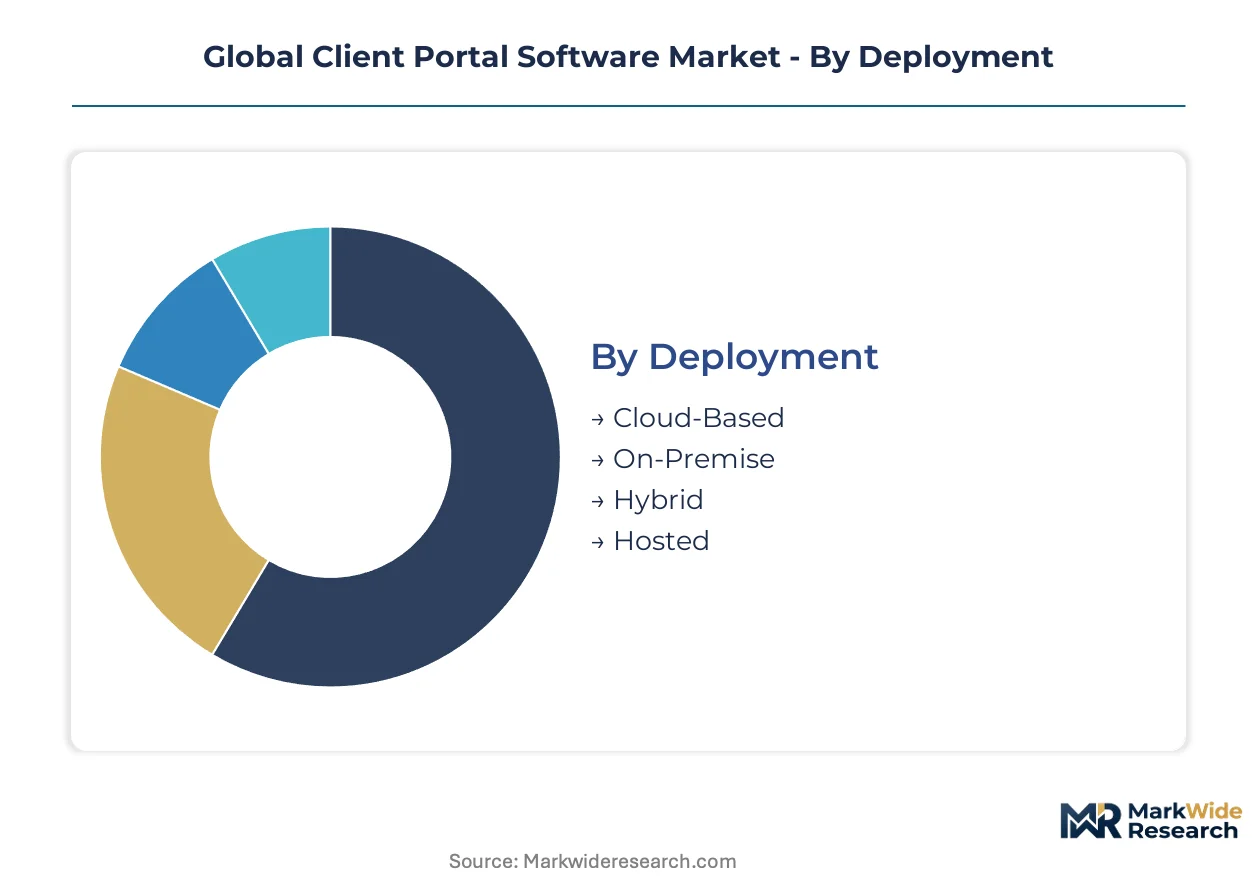
Deployment:
GDPR Article 44 cross-border transfer rules and SEC 17a-4 archiving mandates create divergent infrastructure requirements that fragment deployment preferences across jurisdictions.
- Cloud-Based:Multi-tenant SaaS architectures dominate mid-market professional services adoption in the United States and United Kingdom, where FINRA and FCA communications rules permit third-party custody with audit-grade SLAs. German asset managers resist pure cloud configurations due to BaFin data localization guidance, compressing addressable market share in continental Europe.
- Hybrid:Split-stack designs separating authentication and document layers satisfy India's RBI data residency circulars while preserving UX flexibility for NRI client access. Brazilian Open Finance phased rollout is accelerating hybrid procurement among mid-tier lenders requiring consent-dashboard sovereignty without core system replacement.
- On-Premise:Air-gapped installations persist in Swiss private banking and Saudi GOSI-regulated entities where sovereign cloud certifications remain pending.
- Hosted:Single-tenant managed deployments serve Australian superannuation funds navigating APRA CPS 234 third-party risk standards with dedicated infrastructure isolation.
Cloud-Based handles the majority of throughput; Hybrid is expanding most quickly on share as data sovereignty rulings proliferate.
Solution Type:
Margin concentration follows integration depth, with workflow automation capturing renewal pricing power through custom service attachment.
- Workflow Automation:Embedded e-signature, task routing, and milestone tracking command premium pricing in UK and Australian accounting partnerships where seasonal engagement patterns demand consumption-indexed contracts. Moxo anchors mid-market share through vertical specialization in professional services orchestration.
- Document Management:Audit-trail functionality with immutable versioning satisfies SEC and FINRA archiving standards for US broker-dealers, compressing standalone tool procurement. Clinked sustains European legal and accounting dominance through localized data residency controls.
- Customer Support:Ticket-to-portal convergence drives Zoho Desk channel density through CRM distribution network leverage.
- Collaboration:Project workspace modules integrate with existing Microsoft 365 or Google Workspace estates in North American enterprise deployments.
- Analytics:Usage telemetry instrumentation supports consumption-based pricing migration but requires legacy billing system replacement.
Document Management retains the largest installed base; Workflow Automation is gaining share fastest through services-led renewal economics.
End User:
Procurement sophistication varies sharply by sector compliance burden and digital maturity.
- Financial Services:Consolidating vendor relationships around audit-grade compliance infrastructure, with EU AI Act risk classification documentation now mandatory in German and French bank evaluations. Embedded explainability interfaces for credit scoring algorithms front-load procurement verification.
- Public Sector:German federal and state buyers impose multi-tenant data segregation proofs that complicate shared infrastructure designs. India's DigiLocker integration creates native demand for citizen-facing architectures in banking and insurance.
- Telecommunications:TRAI data protection compliance drives customer self-service portal investment among Indian operators.
- Education:FERPA-covered US institutions prioritize role-based access granularity for student record exchange.
- Hospitality:Loyalty program integration and guest preference management dominate specification requirements.
- Manufacturing:Supplier collaboration portals with ISO 27001 certification baseline serve automotive tier-1 procurement networks.
Financial Services commands the highest compliance-driven pricing premium; Public Sector is climbing fastest as digital sovereignty mandates expand.
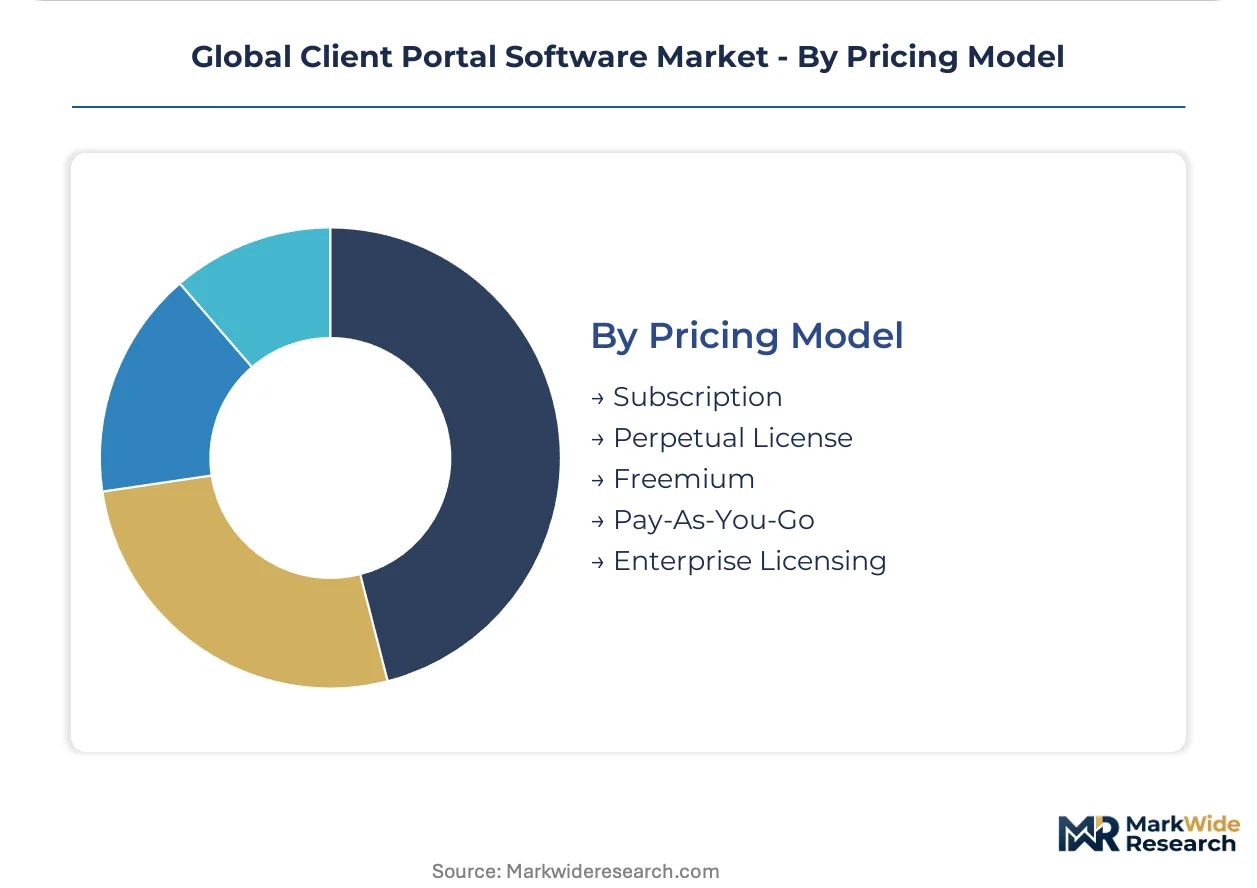
Pricing Model:
Customer type and usage predictability determine model viability and margin stability.
- Subscription:Annual recurring revenue dominates enterprise procurement with ISO 27001 certification requirements, though mid-market professional services firms in the United Kingdom and Australia are negotiating consumption-indexed terms to align costs with seasonal patterns.
- Enterprise Licensing:Unlimited-seat contracts with custom integration services attach serve US healthcare systems navigating HIPAA business associate agreement complexity.
- Perpetual License:Capital expenditure treatment persists in Japanese manufacturing and some German public sector entities with depreciation-driven procurement cycles.
- Freemium:Seat-limited entry tiers convert to paid workflow automation modules in startup and SME professional services segments.
- Pay-As-You-Go:Document transaction or active user indexing aligns software costs with variable client engagement volumes but requires granular telemetry infrastructure.
Subscription retains the dominant revenue share; Pay-As-You-Go is expanding most quickly as procurement patterns shift toward outcome alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR enforcement timelines and SEC audit-trail mandates are fragmenting procurement specifications across jurisdictions, forcing vendors to engineer jurisdiction-specific compliance modules rather than unified global platforms.
United States
FINRA and SEC 17a-4 archiving standards compress standalone document management procurement cycles as broker-dealers consolidate around embedded compliance infrastructure. New York and Boston financial services clusters drive demand for immutable audit trails and single sign-on architectures supporting SAML 2.0 protocols.
Germany
BaFin data localization guidance and EU AI Act risk classification documentation reshape vendor evaluations ahead of enforcement deadlines. Frankfurt's asset management concentration resists pure cloud configurations, accelerating hybrid deployment procurement among mid-tier private banks requiring sovereign data controls.
India
RBI data residency circulars and the Account Aggregator framework create native demand for citizen-facing portal architectures in Mumbai and Bangalore banking clusters. DigiLocker integration requirements push domestic vendors to embed government API connectivity into onboarding workflows.
United Kingdom
FCA communications archiving rules and seasonal accounting engagement patterns drive consumption-indexed contract negotiations among London and Manchester professional services partnerships. GDPR Article 30 processing records mandates sustain demand for automated data lineage features.
Brazil
Central Bank Open Finance phased consent-management rules generate demand for customer-facing data sharing dashboards among São Paulo mid-tier lenders. Hybrid configurations satisfy data sovereignty requirements without core system replacement, accelerating procurement among regional banking cooperatives.
Global Client Portal Software Market Competitive Landscape
Player mix skews toward workflow automation specialists and established CRM platform extenders, with mid-market professional services firms consolidating vendor relationships around integrated compliance infrastructure. Strategic archetypes include vertical specialists anchoring sector-specific orchestration, horizontal platform vendors leveraging distribution density, and emerging no-code builders targeting rapid deployment scenarios. Competitive moves concentrate on custom integration service attachment and consumption-based pricing instrumentation to align renewal economics with variable client engagement volumes.
Within the workflow automation tier, Moxo and Clinked exemplify divergent geographic positioning strategies, with the former anchoring mid-market professional services share through vertical specialization and the latter sustaining European accounting and legal dominance via localized data residency controls. Zoho Desk occupies a position representing horizontal platform extension, competing through CRM distribution network leverage rather than native portal engineering. These three anchors illustrate how vendor selection increasingly hinges on pre-existing infrastructure alignment and jurisdiction-specific compliance certification rather than feature parity alone.
| Leading Market Players |
|---|
| SuiteFiles |
| Clinked |
| SuiteDash |
| Copilot |
| Moxo |
| Zite |
| Softr |
| Stacker |
| Zoho Desk |
| Others |
Supply & Pricing Matrix
Consumption-indexed contracts with annual minimums lock in both supply access and price visibility for mid-market professional services firms, aligning software costs with seasonal client engagement patterns while securing vendor capacity commitments across the United States, United Kingdom, and Australia.
Pricing Analysis
Certification level (ISO 27001/SOC 2 Type II) creates the primary spread between enterprise and mid-market tiers, with audit-grade compliance infrastructure commanding premium subscription rates. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration complexity and data residency controls. Pricing pressure stems from API rate-limiting costs scaling unpredictably with user volume, compressing margins on fixed-price SaaS contracts. Mid-market accounting partnerships exhibit highest price sensitivity, while financial services institutions prioritize compliance over cost.
Supply Chain Analysis
The United States and Ireland anchor hyperscale cloud infrastructure for multi-tenant SaaS deployments, with Germany and India building sovereign data center capacity to satisfy localization mandates. Component dependencies center on identity verification APIs, e-signature orchestration layers, and telemetry instrumentation for consumption-based billing. Single-source vulnerability concentrates in Ireland and Frankfurt data centers under EU data sovereignty rulings. Distribution runs through direct enterprise sales teams and CRM platform extension partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of ISO 27001 auditors stretches certification backlogs to fourteen weeks in key markets, delaying enterprise sales cycles and compressing competitive timelines for vendors seeking baseline qualification.
For Market Incumbents: Compound workflow automation specialization with custom integration service attachment to anchor renewal economics, while investing in consumption-based pricing instrumentation that legacy billing systems cannot replicate. Address emerging no-code builders through vertical-specific orchestration depth that generic platforms cannot match. For New Entrants and Emerging Players: Lead with AI-assisted document classification capabilities targeting legal and real estate verticals where manual indexing labor remains concentrated. Brazil's Open Finance phased rollout presents the most penetrable geography, with hybrid deployment architectures satisfying consent-dashboard sovereignty without core system replacement. For Investors and Strategic Acquirers: Workflow automation specialists with embedded compliance infrastructure represent the priority acquisition archetype, as financial services consolidation around audit-grade platforms compresses standalone tool valuations. Monitor ISO 27001 certification timelines as an inflection indicator for enterprise sales cycle velocity and pricing power sustainability across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | CRM distribution network leverage accelerates portal module adoption among existing Zoho Desk customers. |
| Geographic Expansion | Localized data residency controls sustain Clinked's dominance across European accounting and legal partnerships. |
| Product Launch | Micro-frontend architectures isolate regulatory updates from core feature releases for German insurance carriers. |
| Strategic Partnership | DigiLocker API connectivity embeds government integration into domestic Indian vendor onboarding workflows. |
| Acquisition of Specialist Firm | Workflow automation capabilities capture concentrated margin pools through services-led renewal economics. |
Research Methodology
Desk research of SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory guidance documents preceded structured interviews with CTOs, IT procurement officers, platform engineers, and integration specialists across financial services and professional services verticals. Secondary validation drew from FINRA communications archiving standards, GDPR Article 30 implementation guidance, and RBI data residency circulars. Bottom-up deployment model sizing triangulated against top-down enterprise software spending estimates.
Variance decomposition across deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern shaped the analytical framework. CAGRs derived from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs incorporated EU AI Act enforcement timelines, India's Account Aggregator framework adoption curves, and consumption-based pricing migration velocity among UK and Australian accounting partnerships.
The analysis sits within stated boundaries; outcomes outside sustained regulatory fragmentation or accelerated sovereign cloud certification would require recalibration. Forecasts reflect documented assumptions regarding compliance engineering cost trajectories and procurement cycle compression rates. Recalibration cycles align with material shifts in data sovereignty rulings, auditor availability, and Open Finance regulatory phase transitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Customer Journey Mapping Software Market
Software & Services
Fiber Simulation Software Market
Software & Services
API Design Software Market
Software & Services
Course Authoring Software Market
Software & Services
Asia Pacific Content Services Platform Market
Software & Services
Employee Engagement Solutions Market
Software & Services
Global Claims Processing Software Market
Software & Services
Europe HR Payroll Software Market
Software & Services
Salon Booking Software Market
Software & Services
Photobooth Software Market
Software & Services
Enterprise Backup and Recovery Software Market
Software & Services
Advanced Mobile UX Design Services Market
Software & Services
Mainframe Software Market
Software & Services
Freight Forwarding Software Market
Software & Services
Procure to Pay Software Market
Software & Services
Investor Relations (IR) Website Builder Software Market