
 Buckwheat Market | 2026-2036
Buckwheat Market Size, Share, and Industry Trends Forecast 2026-2036
Buckwheat Market Analysis
Subscription-based crop intelligence and predictive yield analytics is realigning what buckwheat processors sell beyond raw commodity volumes. Birkett Mills leverages proprietary milling technology to sustain premium groat positioning in North American health food channels. Cargill, Incorporated anchors large-scale supply security through backward integration into Canadian prairie contract farming. Ningxia Newfield Foods Co., Ltd. dominates China's domestic buckwheat noodle segment with integrated processing from regional cultivation bases.
Buckwheat, a pseudocereal from Fagopyrum esculentum with complete protein containing all nine essential amino acids and high rutin flavonoid content, serves industrial food formulation, gluten-free baking, and functional ingredient extraction. Flour leads product type revenue due to bakery sector absorption, while groats capture margin concentration through health-conscious retail consumers willing to pay certification premiums. The nutraceuticals application is expanding fastest as rutin isolates gain traction in cardiovascular supplement formulations, though animal feed remains the volume anchor across Eastern European livestock operations.
The USDA's National Organic Program and China's SAMR food safety standards collectively shape buckwheat market access through divergent residue limits and organic certification reciprocity challenges. The EU's REACH framework and EFSA novel food evaluations further condition ingredient approvals for buckwheat-derived functional extracts entering European nutraceutical channels. Stakeholders must monitor evolving pseudocereal classification debates among Codex Alimentarius member states, as reclassification would ripple through tariff schedules and labeling requirements across major import jurisdictions.
Market Dynamics
The buckwheat market is being fundamentally restructured by the EU's Farm to Fork Strategy tightening pesticide residue thresholds for pseudocereals, forcing processors to redesign sourcing networks and invest in traceability infrastructure to maintain European market access.
Growth Catalysts
- Gluten-free bakery demand:North American food manufacturers are reformulating wheat-based products with buckwheat flour to capture celiac and health-conscious consumers, expanding contract volumes with prairie growers.
- REACH framework alignment:EFSA novel food evaluations for buckwheat-derived rutin extracts are unlocking nutraceutical channel access across Western Europe, creating premium extraction demand.
- Ningxia contract farming expansion:China's drought-prone Ningxia Hui Autonomous Region is scaling irrigated buckwheat cultivation for domestic noodle production and export groat processing.
Market Restraints
- Input cost volatility:Synthetic nitrogen fertilizer price swings directly compress margins for buckwheat growers in Saskatchewan and Manitoba, where soil nitrogen fixation remains limited.
- Supply concentration risk:China's dominance in groat processing infrastructure creates single-source dependency for Asian export markets seeking rutin extraction feedstock.
- Quinoa substitution threat:Peruvian and Bolivian quinoa suppliers are capturing shelf space in European health food channels that previously stocked premium buckwheat groats.
Strategic Opportunities
- South Korean nutraceutical penetration:MFDS functional food approvals for cardiovascular health claims present white space for rutin isolate suppliers targeting Seoul-based supplement formulators.
- Precision fermentation convergence:Cell-cultured protein startups are exploring buckwheat protein hydrolysates as functional binders, creating novel offtake agreements with milling operations.
- EU Green Deal carbon credits:The European Commission's soil carbon sequestration incentives reward buckwheat cultivation for its short growing season and minimal tillage requirements.
Industry Challenges
- Organic certification timeline compression:USDA National Organic Program transition periods and China's SAMR equivalency negotiations are delaying cross-border organic groat shipments by 18-24 months.
- Milling technician scarcity:Specialized knowledge of buckwheat dehulling and groat fractionation is retiring with veteran operators in Minnesota and North Dakota processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buckwheat Market |
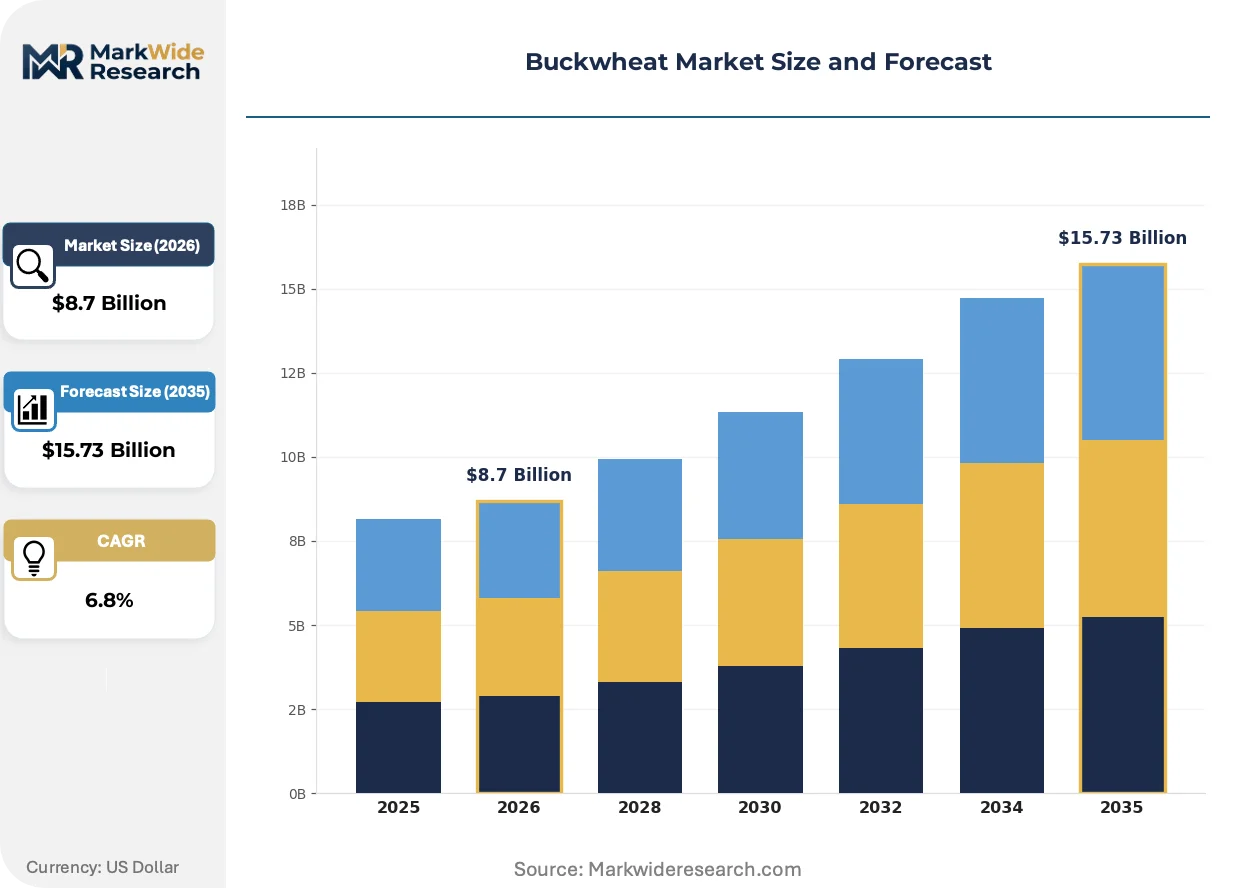
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Grain, Flour, Groats, Noodles Application: Food & Beverage, Animal Feed, Nutraceuticals, Personal Care End User: Retail Consumers, Food Manufacturers, Bakeries, Livestock Producers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Wilmar International Limited, Galinta IR Partneriai, Archer Daniels Midland Company (ADM), Cargill, Incorporated, Homestead Organics, Birkett Mills, Minn-Dak Growers Ltd., Ningxia Newfield Foods Co., Ltd., Bob's Red Mill Natural Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buckwheat Market Emerging Trajectories
Technological convergence between precision agriculture and blockchain traceability is rewriting how buckwheat processors demonstrate provenance to European buyers. Three developments are compressing competitive timelines across the value chain.
Hyperspectral imaging for in-field protein and rutin content prediction is converging with automated contract pricing algorithms. Canadian prairie cooperatives are deploying drone-mounted sensors to pre-qualify harvest lots for premium nutraceutical extraction. This convergence is compressing price discovery cycles from post-harvest laboratory testing to real-time field valuation.
REACH registration requirements for novel food ingredients are forcing buckwheat extract suppliers to submit comprehensive toxicological dossiers to ECHA. The regulatory burden is favoring larger processors with dedicated regulatory affairs functions over small-scale organic operators. Nutraceutical formulators in Germany and France are responding by consolidating supplier bases to three to five qualified vendors per ingredient category.
Direct-to-manufacturer procurement platforms are displacing traditional grain elevator intermediaries in North American buckwheat sourcing. Bakery and pasta manufacturers in Minnesota and Wisconsin are contracting directly with Ningxia processors for specified groat sizes, bypassing regional distributors. This channel shift is most visible among mid-sized gluten-free brands seeking certified organic supply with batch-level documentation.
Buckwheat Market Segmentation
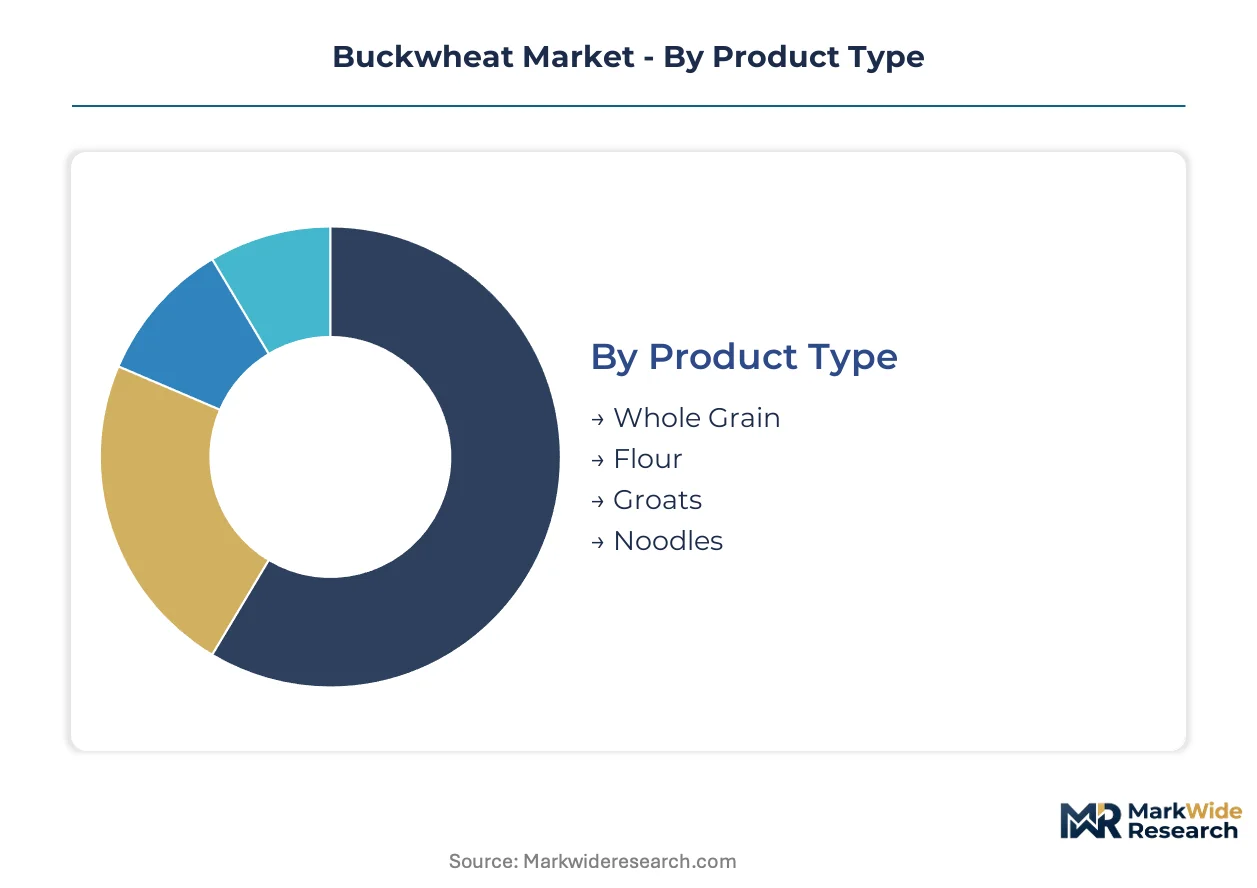
Buckwheat processors must navigate four distinct segmentation axes simultaneously. Product form determines margin structure, while application choice dictates regulatory exposure and end-user requirements shape channel strategy.
Product Type:
Upgrade cycles in buckwheat processing favor value-added formats over raw commodity sales, with dehulling technology advances enabling finer groat fractionation.
- Whole Grain:Unprocessed seeds retain hull integrity for long-haul export shipments to Eastern European dehulling facilities. Livestock feed compounders in Poland and Ukraine absorb volume for protein supplementation in poultry rations.
- Flour:Stone-milled and roller-milled varieties command divergent price positions in gluten-free bakery formulation. North American pasta manufacturers specify ash content below 0.6% for premium noodle production.
- Groats:Dehulled kernels with rutin concentrates above 2% qualify for nutraceutical extraction contracts. Health food retailers in Germany and France stock certified organic groats for direct consumer preparation.
- Noodles:Extruded soba and instant noodle formats anchor demand in China's Ningxia Hui Autonomous Region processing clusters. Japanese importers specify diameter tolerances within 0.3mm for traditional soba house supply.
Flour sits at the top of the volume ranking, with Groats climbing the fastest.
Application:
Cost tier differentiation separates commodity feed applications from premium extraction channels, with regulatory compliance burden scaling directly with end-use sophistication.
- Food & Beverage:Gluten-free bakery absorption drives flour demand across Minnesota and Wisconsin manufacturing plants. Celiac certification requirements from the Gluten Intolerance Group add $0.12-0.18 per pound in third-party audit costs.
- Animal Feed:Whole grain diversion to poultry and swine operations in Saskatchewan provides price floor support during food-grade oversupply. Rutin content limitations restrict inclusion rates above 15% in layer hen diets.
- Nutraceuticals:Rutin isolate extraction for cardiovascular supplement formulations commands 8-12x flour pricing. EFSA novel food evaluations under REACH framework condition European market access for extract suppliers.
- Personal Care:Buckwheat-derived peptides appear in Korean skincare formulations targeting antioxidant positioning. Cosmetic ingredient filings with MFDS in Seoul precede mass-market distribution.
Nutraceuticals expands most quickly, with Animal Feed anchoring absolute volume.
End User:
Customer type fragmentation creates channel conflict, with food manufacturers demanding batch documentation that retail consumers ignore.
- Retail Consumers:Health-conscious households purchase groats through natural food cooperatives and direct-to-consumer platforms. Organic certification premiums of 35-50% above conventional pricing persist in this channel.
- Food Manufacturers:Large-scale pasta and cereal producers contract directly with Ningxia processors for specified protein content. Quality agreements specify 48-hour rejection windows for out-of-specification deliveries.
- Bakeries:Artisan gluten-free bakeries in Paris and London specify stone-milled flour for texture differentiation. Small-batch requirements conflict with minimum order quantities from prairie cooperatives.
- Livestock Producers:Eastern European pork integrators purchase whole grain through forward contracts tied to Chicago Board of Trade corn futures. Price hedging instruments remain underdeveloped for buckwheat-specific exposure.
Food Manufacturers capture the largest volume share, with Retail Consumers gaining share fastest.
Distribution Channel:
Supply concentration in groat processing infrastructure favors direct procurement over intermediary channels for volume buyers.
- Online Retail:Amazon and specialized health platforms enable traceable organic certification display through QR-linked blockchain records. Return logistics complexity limits frozen noodle distribution in this channel.
- Supermarkets:Mass-market grocery placement requires slotting fees exceeding $25,000 per SKU for regional chain access. Private label buckwheat flour programs at Kroger and Albertsons compress branded margin.
- Health Food Stores:Independent natural retailers in California and Oregon stock sprouted groat products with enzymatic activation claims. Staff training requirements favor established brands with field representative coverage.
- Specialty Shops:Japanese soba equipment suppliers in Tokyo and Osaka bundle noodle sales with cooking class enrollment. Cultural authenticity positioning resists price competition from mass-market alternatives.
Supermarkets dominate volume throughput, with Online Retail expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting buckwheat cultivation toward jurisdictions with lower compliance costs, as EU pesticide residue thresholds under the Farm to Fork Strategy push processing investment into regions with equivalency agreements or lighter novel food evaluation burdens.
China
Ningxia Hui Autonomous Region anchors groat processing capacity for domestic noodle production and export extraction feedstock. SAMR food safety standards and dual carbon goals shape cultivation practices across drought-tolerant farming zones. Contract farming clusters around Yinchuan coordinate irrigated buckwheat expansion with integrated milling infrastructure serving Japanese soba importers.
United States
Minnesota and North Dakota house specialized dehulling facilities supplying gluten-free bakery channels across the upper Midwest. USDA National Organic Program certification timelines delay cross-border organic shipments but sustain premium positioning in health food retail. Birkett Mills in New York State leverages proprietary milling technology for groat fractionation serving nutraceutical extraction contracts.
Canada
Saskatchewan and Manitoba prairie growers face synthetic nitrogen fertilizer price volatility compressing margins on non-leguminous pseudocereal production. Prairie cooperatives deploy drone-mounted hyperspectral imaging for field-level protein and rutin content prediction. Winnipeg-based processors coordinate forward contracts with Minneapolis pasta manufacturers specifying ash content below 0.6%.
Germany
REACH framework registration requirements and EFSA novel food evaluations condition buckwheat-derived rutin extract access for cardiovascular supplement formulators. Berlin-Brandenburg processing facilities consolidate supplier bases to three to five qualified vendors per ingredient category. German nutraceutical buyers demand batch-level blockchain traceability documentation from Ningxia processors.
South Korea
MFDS functional food approvals for cardiovascular health claims present white space for rutin isolate suppliers targeting Seoul-based supplement formulators. Korean skincare formulators incorporate buckwheat-derived peptides into antioxidant positioning products. Seoul Capital Area distribution hubs coordinate import logistics from Chinese groat processors with cosmetic ingredient filing requirements.
Buckwheat Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium groat positioning concentrated among proprietary technology holders while commodity flour supply consolidates around backward-integrated grain traders. The vendor base organizes into three archetypes: prairie cooperative processors with dehulling specialization, multinational grain houses with captive farming contracts, and integrated Chinese noodle manufacturers with captive cultivation bases. Dominant competitive moves include direct-to-manufacturer procurement platform deployment and precision agriculture convergence with automated contract pricing algorithms.
Among North American milling specialists, Birkett Mills and Minn-Dak Growers Ltd. occupy positions emphasizing proprietary groat fractionation technology for nutraceutical channel supply. Cargill, Incorporated represents the scale-driven archetype with backward integration into Canadian prairie contract farming securing large-scale supply security. Ningxia Newfield Foods Co., Ltd. anchors the integrated processing model with regional cultivation bases feeding domestic noodle production and export groat processing infrastructure.
| Leading Market Players |
|---|
| Wilmar International Limited |
| Galinta IR Partneriai |
| Archer Daniels Midland Company (ADM) |
| Cargill, Incorporated |
| Homestead Organics |
| Birkett Mills |
| Minn-Dak Growers Ltd. |
| Ningxia Newfield Foods Co., Ltd. |
| Bob's Red Mill Natural Foods |
| Others |
Supply Flow & Price Mechanics
Backward integration into Canadian prairie contract farming anchors both supply security and pricing power for large-scale processors serving North American gluten-free manufacturers. This captive sourcing model compresses input cost volatility exposure while enabling premium positioning through batch-level traceability documentation demanded by EFSA-aligned European buyers.
Pricing Analysis
Distributor margin compression in traditional grain elevator channels is accelerating direct-to-manufacturer procurement platform adoption across Minnesota and Wisconsin bakery operations. Three-tier pricing structure across premium, standard, and economy levels stratifies by organic certification status and rutin content thresholds, with certified organic groats commanding 35-50% premiums above conventional grades. Price differentiation stems from Gluten Intolerance Group celiac certification requirements and volume scale commitments in forward contracts. Pricing pressure intensifies in commodity flour tiers due to synthetic nitrogen fertilizer cost swings in Saskatchewan and Manitoba, while nutraceutical extraction contracts show lowest buyer price sensitivity due to 8-12x flour pricing multiples for rutin isolates.
Supply Chain Analysis
Specialized milling technician scarcity in Minnesota and North Dakota processing facilities is constraining groat fractionation capacity expansion despite extraction demand growth. Supply concentrates in China's Ningxia Hui Autonomous Region for groat processing infrastructure, Canada's prairie provinces for raw cultivation, and Germany for REACH-registered rutin extract formulation. Raw material flows draw from drought-tolerant farming zones, synthetic nitrogen fertilizer markets, and dehulling equipment supply chains. Single-source vulnerability in Asian groat processing creates dependency risk for rutin extraction feedstock. Distribution runs through direct procurement platforms displacing regional grain elevator intermediaries, with blockchain-traceable shipments bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The buckwheat market functions as a stable compounder anchored by gluten-free bakery sector absorption and nutraceutical extraction demand expansion. Functional ingredient premiumization and drought-tolerant cultivation advantages sustain margin resilience across input cost cycles.
For Market Incumbents: To counter quinoa substitution threats in European health food channels, Birkett Mills and prairie cooperative processors should deepen proprietary groat fractionation technology investment and secure EFSA novel food evaluation dossiers for rutin extract suppliers. Capacity addition in Ningxia irrigated farming zones, coupled with blockchain traceability infrastructure deployment, reinforces premium positioning against Peruvian and Bolivian pseudocereal competitors.
For New Entrants and Emerging Players: Artisan gluten-free bakeries in Paris and London represent an underserved buyer archetype seeking stone-milled flour with texture differentiation and small-batch flexibility that prairie cooperatives currently refuse. South Korean nutraceutical formulators seeking MFDS cardiovascular health claim approvals present white space for rutin isolate suppliers. Precision fermentation startups exploring buckwheat protein hydrolysates as functional binders offer novel offtake agreement pathways bypassing established milling relationships.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap prairie dehulling specialists because organic certification timeline compression and milling technician scarcity create seller urgency among family-owned Minnesota and North Dakota facilities. Long-term viability over a 5-10 year horizon rests on EU Green Deal carbon credit monetization for short-season cultivation and nutraceutical channel penetration. The signal to watch is ECHA REACH registration completion rates for buckwheat-derived novel food ingredients, which would consolidate supplier bases and elevate acquisition premiums for compliant processors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | Cargill's captive prairie cultivation secures supply continuity against synthetic nitrogen fertilizer volatility. |
| Blockchain Traceability Deployment | Ningxia processors deploy QR-linked documentation to satisfy German nutraceutical buyer provenance requirements. |
| EFSA Novel Food Dossier Submission | REACH registration completion unlocks cardiovascular supplement formulation access across Berlin-Brandenburg facilities. |
| Precision Fermentation Partnership | Cell-cultured protein startups create novel offtake agreements for buckwheat protein hydrolysate functional binders. |
| Direct-to-Manufacturer Platform Launch | Mid-sized gluten-free brands in Wisconsin bypass regional distributors for certified organic batch-level documentation. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with buckwheat mill operators, gluten-free bakery procurement managers, nutraceutical formulation chemists, and EFSA regulatory affairs specialists with secondary validation. Trade data from customs records, USDA National Organic Program certification databases, SAMR food safety filings, and ECHA REACH registration disclosures anchored supply-side modeling. Bottom-up cultivation area estimates and top-down extraction demand projections were cross-referenced against prairie cooperative shipment records.
Historical reference periods spanning pre-Farm to Fork Strategy implementation through current pesticide residue threshold enforcement anchored projection parameters across the analysis window. Segmentation dimensions modeled include product form, application tier, end-user archetype, and distribution channel, with regional regulatory cluster differentiation for EU, North American, and Chinese market access conditions. CAGRs were derived from iterative convergence between supply-side capacity expansion announcements and demand-side formulation adoption curves, incorporating rutin content prediction accuracy from hyperspectral imaging deployment rates.
Underlying measurement precision varies by segment; nutraceutical extraction contracts carry tighter precision than commodity animal feed diversions due to documented offtake agreements. Forecasts reflect assumptions regarding EU-China organic certification reciprocity negotiations and Codex Alimentarius pseudocereal classification stability. Material deviation in synthetic nitrogen fertilizer price trajectories or EFSA novel food evaluation timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Chamomile Seeds Market
Seeds
Ghana Seeds Market
Seeds
Safflower Seeds Market
Seeds
Asia-Pacific Grain Seed Market
Seeds
United States Forage Seed Market
Seeds
Global Vegetable Seed Market
Seeds
Europe Forage Seed Market
Seeds
Apple Seed Oil Market
Seeds
China Vegetable Seed Market
Seeds
North America Seeds Market
Seeds
Organic Seed Market
Seeds
Sesame Seeds Market
Seeds
Sprouted Grains and Seeds Market
Seeds
Genetically Modified Seeds Market
Seeds
Australia Oilseed Market
Seeds
India Vegetable Seed Market