
 Australia Oilseed Market | 2026-2036
Australia Oilseed Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Oilseed Market Outlook
Food processing buyers are redrawing procurement patterns toward high-oleic canola for healthier packaged goods, while biofuel offtake accelerates. GrainCorp leverages its east coast storage and handling network to anchor supply security for crush operators. Cargill Australia competes through specialized oil refining capabilities that serve food manufacturers and industrial users. Wilmar International controls a significant share of oilseed crushing capacity with integrated refining and export infrastructure.
Australia oilseed encompasses cultivated crops bred for oil extraction, with canola containing 40-45% oil content by weight and soybeans at 18-20%, processed through mechanical pressing or solvent extraction to yield edible oils, protein meals, and industrial feedstocks. Canola dominates planted area and crush volume, sustaining mature margin pools in food-grade oil production while biofuel applications represent the fastest-expanding demand segment. Soybeans occupy a smaller but specialized position, serving domestic feed compounders and niche food processing needs where protein meal specifications matter.
Food Standards Australia New Zealand (FSANZ) governs oil composition and labeling requirements, while the Australian Pesticides and Veterinary Medicines Authority (APVMA) regulates crop protection inputs that shape farm-level production costs and residue standards. The Clean Energy Regulator administers biofuel certificates that directly influence crusher investment in renewable diesel feedstock supply chains. Stakeholders must monitor how gene technology approvals intersect with carbon credit mechanisms to capture value from low-emission oilseed varieties.
Market Dynamics
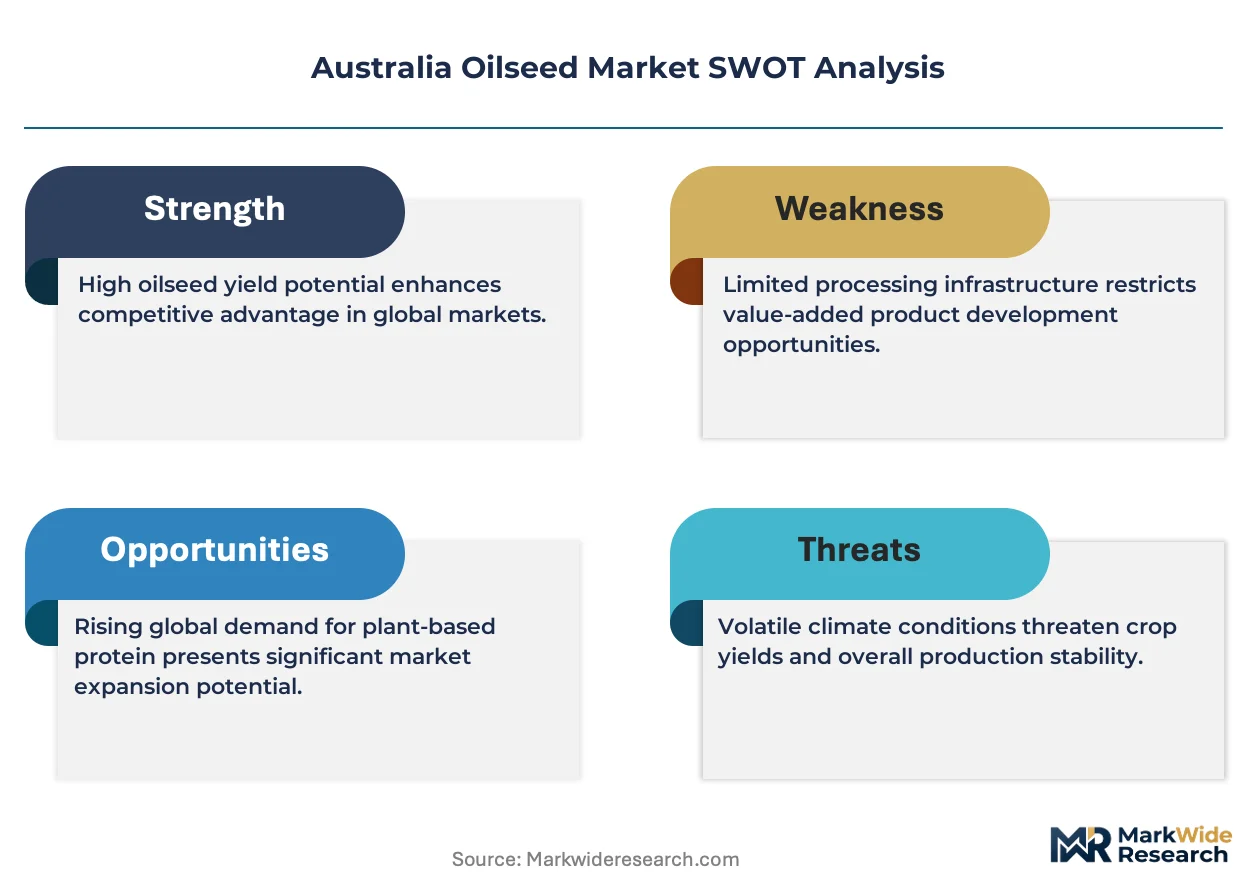
Biofuel refineries are scaling purchases of canola oil for renewable diesel production, forcing crushers to reconfigure supply chains around feedstock certification requirements and carbon intensity scoring systems that determine offtake premiums.
Growth Catalysts
- Clean Energy Regulator biofuel certificates:The Australian certificate scheme directly influences crusher investment in renewable diesel feedstock supply chains, creating pull-through demand for low-emission oilseed varieties.
- New South Wales crushing capacity:Concentrated farm output and processing infrastructure in this state anchors supply security for domestic oil production and export positioning.
- High-oleic canola breeding programs:Novel trait development is expanding addressable market into premium packaged goods segments where oil stability and health claims command price premiums.
Market Restraints
- APVMA crop protection regulation:Residue standards and input approval timelines constrain farm-level production cost structures and limit chemical tool availability for pest management.
- Solvent extraction energy intensity:Natural gas and electricity costs for hexane-based processing compress margin pools, particularly for smaller crush operators lacking scale efficiencies.
- Soybean import dependency:Limited domestic soybean production forces protein meal compounders to source from international suppliers, exposing crush margins to currency and freight volatility.
Strategic Opportunities
- Gene Technology Regulator streamlined approvals:Faster novel trait commercialization timelines enable breeders to capture value from climate-adaptive and low-emission oilseed genetics ahead of competitor jurisdictions.
- Victoria farm-to-refinery integration:Geographic proximity between canola production zones and biofuel processing infrastructure supports dedicated supply contract structures.
- FSANZ health claim pathways:Regulatory frameworks for oil composition and labeling enable differentiated positioning in functional food categories where omega-3 and trans-fat claims drive purchase decisions.
Industry Challenges
- Crushing asset utilization:Seasonal harvest concentration requires capital-intensive storage and logistics coordination to maintain plant throughput across the operating year.
- Gene technology licensing complexity:Stacked trait intellectual property from multiple breeders creates royalty stacking and freedom-to-operate verification burdens for seed distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Oilseed Market |
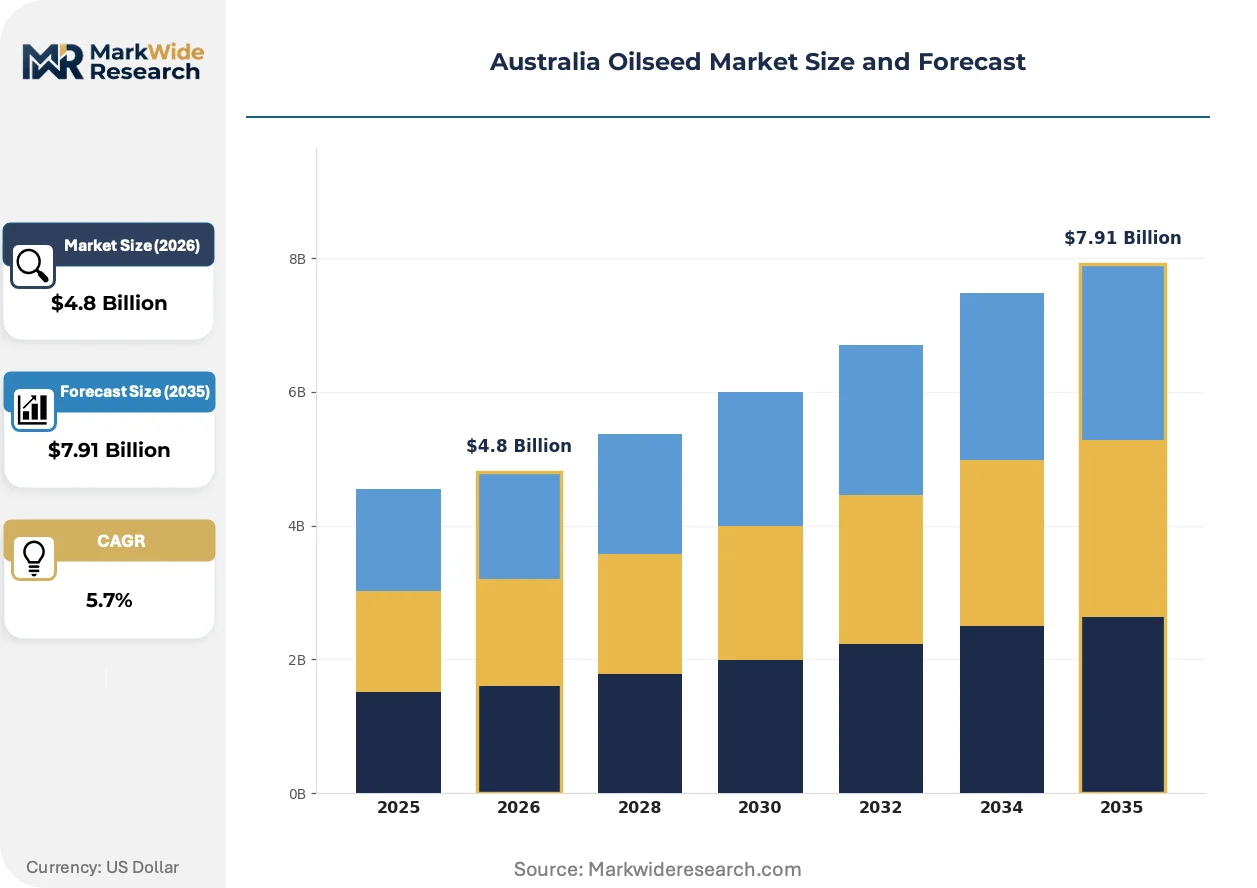
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canola, Soybeans, Sunflower Seeds, Cottonseed Application: Food, Feed, Biofuels, Oil Production End User: Agriculture, Food Processing, Industrial, Retail Distribution Channel: Direct Sales, Wholesale, Online, Export |
| Companies Covered | GrainCorp, Cargill Australia, ADM Trading Australia Pty Ltd, Bunge Limited, Viterra, Ridley Corporation, Wilmar International, Louis Dreyfus Company, Syngenta Australia Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Oilseed Market Strategic Shifts
Mechanical pressing technology is advancing extraction efficiency while gene-edited oil profiles are opening new industrial applications, and procurement models are compressing traditional merchant trading structures.
Precision gene-editing platforms are decomposing the trait development timeline for novel fatty acid profiles. Canola breeders are deploying CRISPR-derived varieties to biofuel processors seeking optimized cetane numbers. This acceleration is compressing the competitive window between trait discovery and commercial scale-up.
FSANZ is tightening oil composition disclosure requirements for packaged food manufacturers. The regulator's updated labeling standards force reformulation decisions across margarine and frying oil categories. Food processors in Victoria and New South Wales are accelerating high-oleic substitution programs to preempt compliance costs.
Long-term supply agreements are displacing spot market purchases among biofuel refineries. Crush operators are responding with dedicated farm contracting programs that guarantee origin and carbon intensity scores. This shift concentrates procurement leverage with the largest renewable diesel producers in Queensland and Western Australia.
Australia Oilseed Market Segmentation
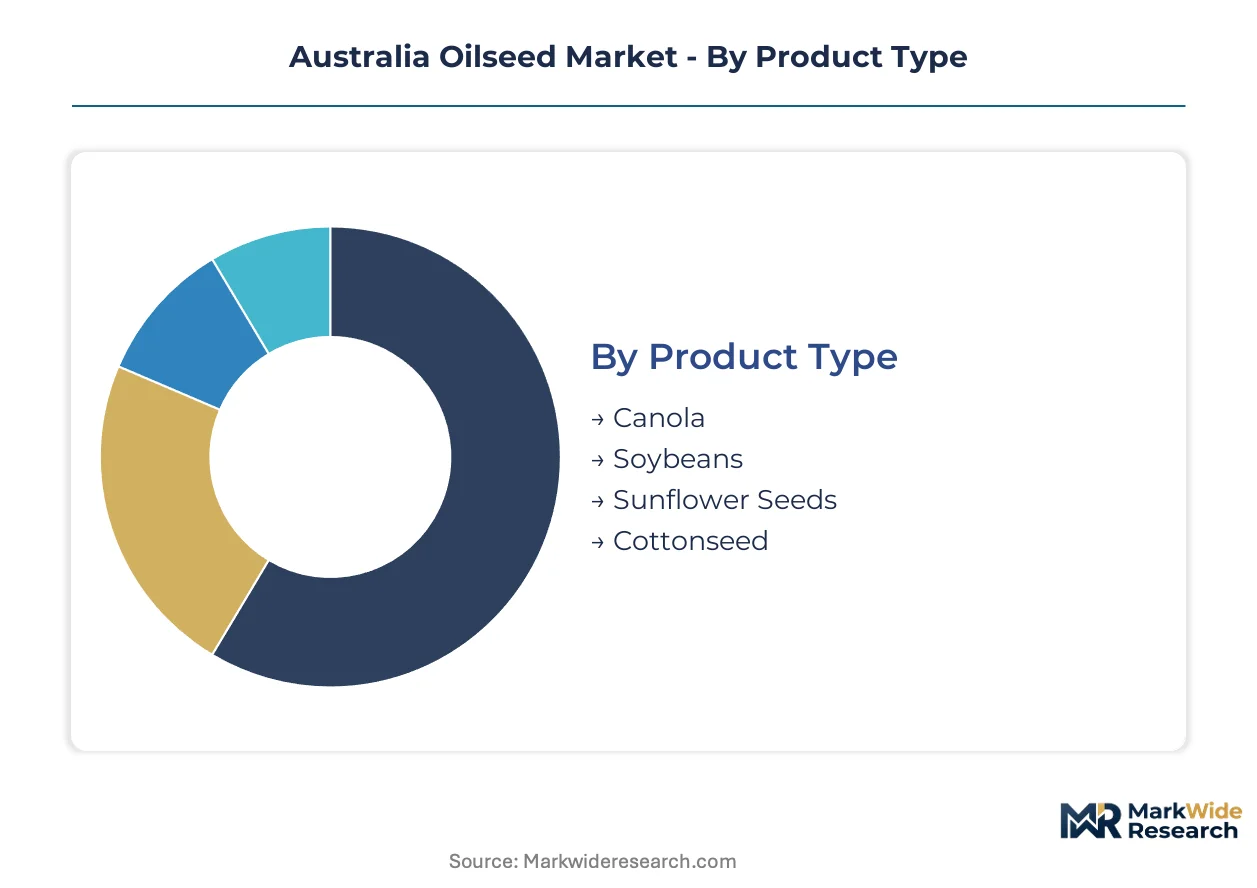
Oilseed procurement patterns in Australia diverge sharply across product categories and end-use applications, with biofuel offtake rewiring traditional crush economics while food-grade specifications tighten. Understanding these segment boundaries clarifies where margin pools concentrate and which substitution threats reshape competitive positioning.
Product Type:
Substitution pressure runs strongest against cottonseed as renewable diesel refineries redirect oil procurement toward canola with superior cetane properties and carbon intensity scores.
- Canola:Oil content reaches 40-45% by weight, enabling efficient mechanical pressing or solvent extraction yields. New South Wales and Victoria crushing clusters anchor supply security for domestic food oil production and renewable diesel feedstock contracts. FSANZ oil composition standards and Clean Energy Regulator biofuel certificates jointly determine grade premiums and offtake eligibility.
- Soybeans:Lower oil content at 18-20% positions this segment for protein meal specialization rather than oil yield optimization. Domestic feed compounders in Queensland and Western Australia drive demand where amino acid specifications matter more than oil extraction efficiency. Limited Australian production forces import dependency, exposing margins to currency and freight volatility.
- Sunflower Seeds:Niche high-oleic varieties serve premium packaged goods manufacturers seeking oil stability without hydrogenation.
- Cottonseed:Byproduct of fiber production with variable oil quality; ginning locations in Queensland determine regional supply availability.
Canola anchors the volume base while soybeans gain share at the steepest rate through protein meal demand from intensive livestock operations.
Application:
Cost tier stratification separates commodity oil production from certified biofuel feedstock, with carbon intensity scoring creating price spreads that did not exist five years ago.
- Food:High-oleic canola varieties command price premiums in margarine and frying oil categories where FSANZ labeling requirements force trans-fat reformulation. Victorian and New South Wales food processors accelerate substitution programs to preempt compliance costs. Shelf stability and health claim eligibility determine procurement decisions more than raw oil price.
- Biofuels:Renewable diesel production represents the fastest-expanding demand segment as refineries scale canola oil purchases. Clean Energy Regulator certificates directly influence crusher investment in dedicated feedstock supply chains. Origin verification and carbon intensity scoring systems determine offtake premiums and contract structures.
- Feed:Protein meal specifications drive soybean procurement for poultry and aquaculture compounders.
- Oil Production:Intermediate crushing output serves downstream refiners with specialized fractionation capabilities.
Food applications retain the largest revenue pool while biofuels climb the fastest as certificate schemes reconfigure crusher capital allocation.
End User:
Customer type concentration favors industrial buyers with long-term contracting power over fragmented retail channels.
- Food Processing:Packaged goods manufacturers in Victoria and New South Wales redraw procurement patterns toward high-oleic canola for stability and health positioning. FSANZ disclosure requirements accelerate reformulation timelines. Direct crusher relationships replace merchant trading for volume security.
- Industrial:Biofuel refineries in Queensland and Western Australia displace spot market purchases with dedicated farm contracting programs. Carbon intensity scoring and origin certification requirements concentrate procurement leverage with the largest renewable diesel producers.
- Agriculture:Livestock producers drive protein meal demand with specific amino acid requirements.
- Retail:Bottled oil sales through supermarkets face margin compression from private label expansion.
Industrial offtake commands the strongest growth trajectory while food processing retains the deepest value chain integration.
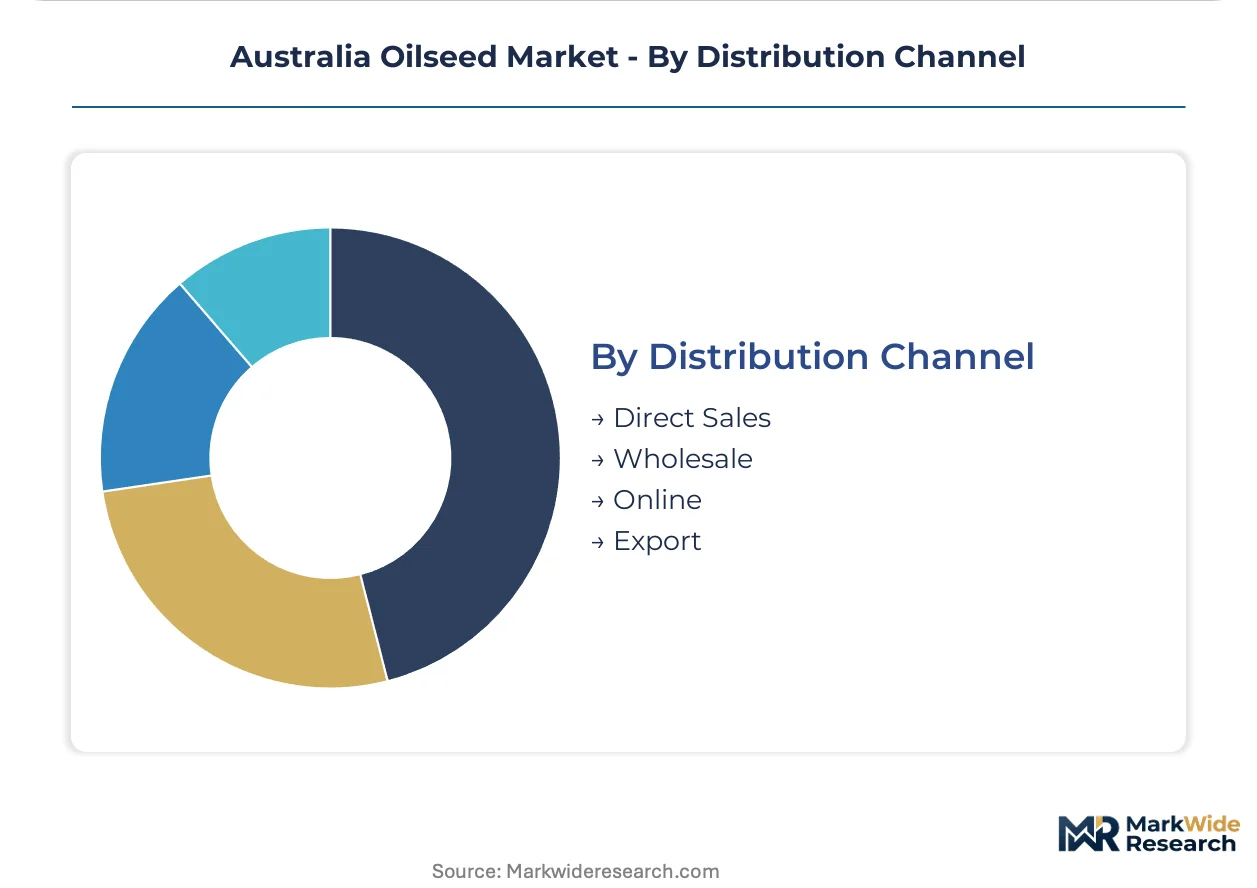
Distribution Channel:
Supply concentration in eastern Australia determines channel viability, with export infrastructure constraining options for western production zones.
- Direct Sales:Crush operators contract directly with biofuel refineries and food manufacturers, bypassing merchant intermediaries. Long-term supply agreements guarantee origin and carbon intensity scores. This channel concentrates volume with the largest processors possessing integrated storage and logistics networks.
- Export:Port terminal access in New South Wales and Victoria enables international oilseed and oil meal shipments. Quality certification and phytosanitary compliance determine market access. Asian feed compounders represent the primary destination for Australian protein meal.
- Wholesale:Aggregators serve smaller food processors and regional feed mills lacking direct crusher relationships.
- Online:Limited to specialty seed and small-scale oil purchases outside commodity flows.
Direct sales capture the expanding biofuel procurement volume while export channels retain strategic importance for protein meal surplus disposal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Newcastle's grain terminal infrastructure anchors New South Wales as the dominant oilseed export gateway, with dedicated storage and loading facilities connecting Riverina production zones to Asian protein meal markets. This logistical backbone underwrites Australia's position in regional oilseed trade flows.
New South Wales
Renewable diesel refineries in Queensland source canola crush from Newcastle-Gunnedah corridor facilities. The Clean Energy Regulator's biofuel certificate scheme pulls investment toward dedicated low-emission feedstock supply chains. GrainCorp's storage network along the Liverpool Plains secures origin-verified volumes for long-term industrial contracts.
Victoria
High-oleic canola breeding programs concentrate around Horsham and Wimmera research stations serving packaged goods reformulation needs. FSANZ labeling standards accelerate trans-fat substitution timelines for margarine manufacturers. Geelong crushing infrastructure supports farm-to-refinery integration with Melbourne-area biofuel processors.
Queensland
Protein meal demand from intensive poultry and aquaculture operations drives soybean procurement through Brisbane port terminals. The state's feed compounders rely on imported beans due to limited domestic production. APVMA residue regulations shape crop protection input availability for any future soybean expansion.
Western Australia
Albany and Esperance port terminals handle canola export surplus beyond domestic crush requirements. The state's grain handlers face freight cost disadvantages to eastern biofuel refineries. Carbon intensity scoring systems disadvantage longer supply chains to Queensland renewable diesel facilities.
Australia Oilseed Market Competitive Environment
Concentration sits with integrated grain handlers possessing captive storage networks and crushing assets. Three operator tiers structure competitive positioning: multinational traders with refining capabilities, domestic handlers with origination control, and specialist seed distributors with trait licensing relationships. Capacity expansion and backward integration into farm contracting represent the dominant competitive moves reshaping procurement leverage.
Among integrated handlers, GrainCorp exemplifies the domestic archetype with east coast infrastructure dominance, while Cargill Australia and Wilmar International occupy positions as multinational operators with specialized refining and export capabilities. These three anchors illustrate how scale in storage logistics translates to contract security with biofuel refineries and food manufacturers.
| Leading Market Players |
|---|
| GrainCorp |
| Cargill Australia |
| ADM Trading Australia Pty Ltd |
| Bunge Limited |
| Viterra |
| Ridley Corporation |
| Wilmar International |
| Louis Dreyfus Company |
| Syngenta Australia Pty Ltd |
| Others |
Value Chain & Pricing Dynamics
Clean Energy Regulator biofuel certificates gate both supply qualification and price differentiation simultaneously, forcing crushers to invest in origin-verification infrastructure that separates certified from uncertified crush streams. This dual-gating mechanism concentrates pricing power with handlers possessing integrated storage and carbon-tracking capabilities.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts between crush operators and renewable diesel refineries, with long-term offtake agreements commanding 15-20% price advantages over spot purchases. Price differentiation rests on carbon intensity scores and FSANZ oil composition grades, while cost compression in standard-grade food oil runs through energy-intensive solvent extraction. Biofuel refineries exhibit lowest price sensitivity due to certificate-driven feedstock scarcity, whereas regional feed compounders face acute margin pressure from import-dependent soybean meal sourcing.
Supply Chain Analysis
Strategic stockpile preferences dominate handler behavior given seasonal harvest concentration, with GrainCorp's Liverpool Plains storage network exemplifying the capital-intensive coordination required to maintain plant throughput. Geographic supply concentration centers on New South Wales and Victoria for canola crushing, while Queensland and Western Australia draw from international soybean origins. Raw material dependencies encompass hexane solvent, natural gas for thermal processing, and specialized high-oleic seed genetics. Single-source vulnerability runs through the Newcastle-Gunnedah corridor's dominance in export-terminal access. Distribution feeds from direct sales channels into biofuel refineries and food manufacturers, bypassing traditional merchant intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: Clean Energy Regulator certification requirements and FSANZ oil composition standards create switching costs that lock buyers into qualified supplier relationships.
For Market Incumbents: Consolidate crushing capacity along the Newcastle-Gunnedah corridor to capture biofuel certificate premiums before competitor handlers replicate carbon-tracking infrastructure. Backward integration into farm contracting secures origin-verified volumes against emerging grain traders. The threat of gene-edited seed distributors disintermediating trait licensing relationships demands captive breeding program investments or exclusive distribution partnerships with Syngenta Australia. For New Entrants and Emerging Players: Service-layer gaps in small-scale organic oilseed handling present white-space targets, as integrated majors under-serve boutique food manufacturers seeking non-GMO verification. Western Australia's Albany-Esperance production zones offer the most penetrable geography given freight disadvantages faced by eastern handlers. A go-to-market angle anchored in direct-to-food-processor relationships bypasses the storage-network moat that protects incumbent crush operators. For Investors and Strategic Acquirers: Gene Technology Regulator streamlined approval timelines reshape the acquisition landscape toward breeding specialists with CRISPR-derived trait pipelines. Long-term viability across the projection horizon favors handlers with demonstrated carbon intensity scoring capabilities and locked biofuel refinery contracts. The signal to watch is APVMA crop protection registration delays that could constrain farm-level production expansion and redirect crush margin pools toward chemical input distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm Contracting | Origin verification secures Clean Energy Regulator certificate eligibility for biofuel feedstock premiums. |
| High-Oleic Breeding Program Investment | FSANZ labeling compliance captures margarine reformulation demand from Victorian food processors. |
| Crushing Capacity Expansion | New South Wales infrastructure additions tighten supply security for Queensland renewable diesel refineries. |
| Carbon Intensity Tracking System Deployment | Certification infrastructure differentiates crush streams for industrial offtake contract eligibility. |
| Long-Term Supply Agreement Structuring | Dedicated farm contracting displaces spot market exposure for biofuel processor volume guarantees. |
Study Parameters
The analysis maps canola crush operations, soybean import flows, and high-oleic breeding programs, each validated through crusher operations managers, biofuel refinery procurement leads, seed distributor licensing specialists, and APVMA regulatory affairs officers. Primary interview findings triangulated against ABS agricultural census data, Clean Energy Regulator certificate issuance records, GrainCorp storage capacity disclosures, and FSANZ food standards determinations. Bottom-up volume builds from state-level crush capacity and farm output estimates cross-checked with top-down trade flow analysis.
Consistency checks against ABARES crop forecasts and customs export statistics validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, application, end user, and distribution channel dimensions alongside carbon intensity scoring tiers unique to biofuel feedstock qualification. CAGRs derived from regression analysis of historical crush margins, certificate price trajectories, and planted area expansion patterns, with scenario weighting for gene technology approval timelines and renewable diesel capacity buildouts.
Underlying assumptions cover APVMA crop protection registration continuity, Clean Energy Regulator certificate scheme stability, and FSANZ oil composition standard enforcement, with deviation risk concentrated in currency volatility affecting soybean import costs and natural gas price spikes impacting solvent extraction economics. Revision becomes warranted when biofuel refinery offtake growth crosses thresholds that exhaust available crush capacity or when gene technology licensing disputes disrupt trait commercialization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
South America Vegetable Seed Market
Seeds
Vietnam Vegetable Seed Market
Seeds
Wax Gourd Seed Market
Seeds
Buckwheat Seed Market
Seeds
Europe Amaranth Market
Seeds
Russia Forage Seed Market
Seeds
Asia-Pacific Onion Seed Market
Seeds
South and Southeast Asia Seed Market
Seeds
Africa Sorghum Seed Market
Seeds
Caraway Seeds Market
Seeds
Europe Vegetable Seed Market
Seeds
Africa Seed Market
Seeds
Organic Chia Seeds Market
Seeds
Asia-Pacific Chia Seed Market
Seeds
Chia Seeds Market
Seeds
South America Quinoa Seeds Market