
 Asia-Pacific Grain Seed Market | 2026-2036
Asia-Pacific Grain Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Grain Seed Market Outlook
Buyer concentration among large-scale agricultural cooperatives is decoupling from traditional village-level seed procurement patterns across the Asia-Pacific region. Bayer AG leverages its tropical corn germplasm libraries to anchor breeding programs in Thailand and Indonesia. Syngenta Group competes through integrated crop solution bundles that pair hybrid seeds with crop protection chemistry. Yuan Longping High-Tech Agriculture Co. Ltd dominates rice seed development through proprietary two-line hybrid systems optimized for subtropical water regimes.
Grain seed comprises genetically stable or hybridized reproductive material of cereal and coarse grain crops, typically conditioned to moisture content below 12% and treated with fungicidal or insecticidal coatings to ensure field emergence rates exceeding 85%. Its primary commercial purpose is to transmit yield potential, disease resistance, and abiotic stress tolerance from breeder genetics into farm-gate production systems. Hybrid seeds command premium positioning due to proprietary parent-line control and consistent heterosis expression in maize and rice rotations. Open-pollinated varieties sustain margin pools in marginal rainfall zones where farmers practice seed-saving across seasons. Organic seeds are gaining structural traction as export-facing cooperatives in Australia and Japan seek certified supply chain documentation for premium grain consignments.
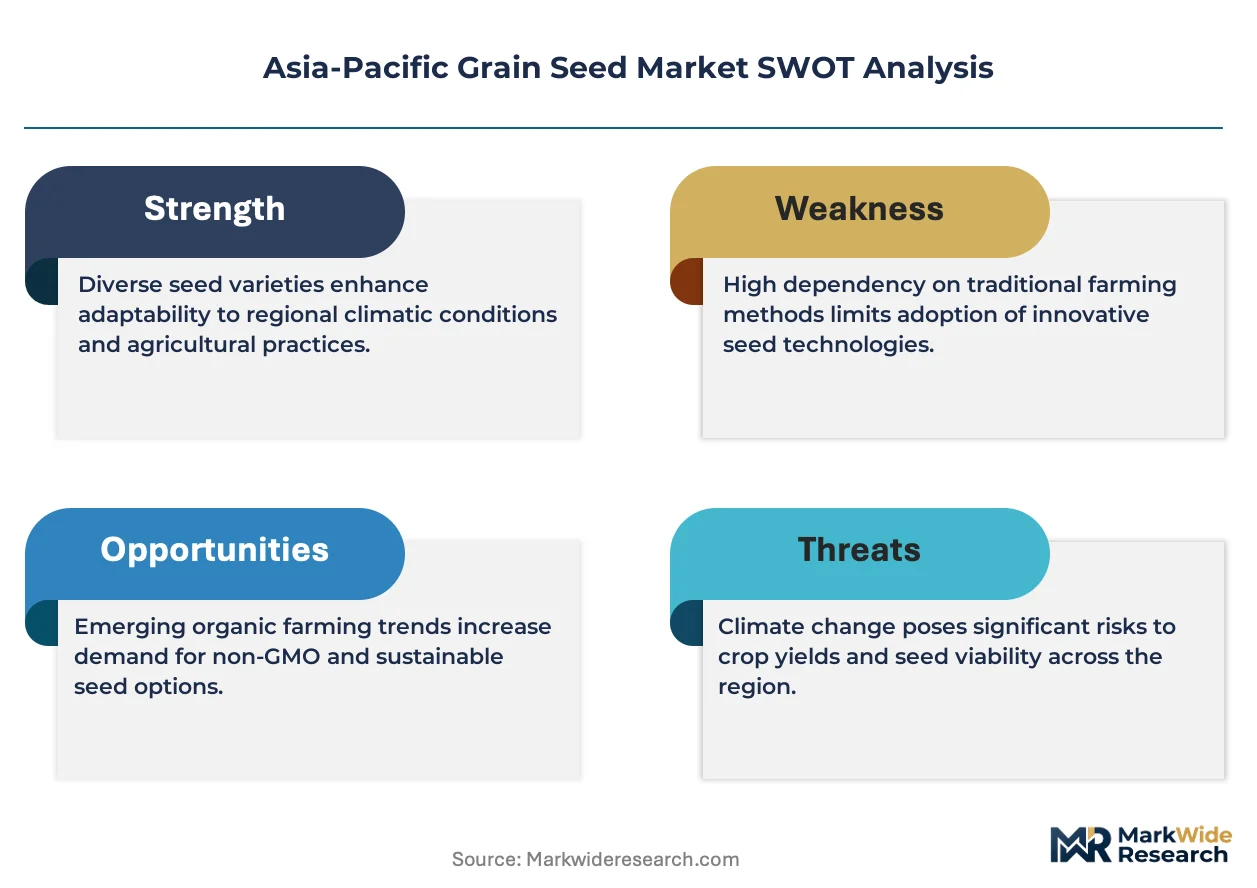
India's CEA and BIS enforce minimum seed certification standards that govern market access for domestic and imported genetic material, while China's NMPA and GB standards regulate transgenic trait approval and environmental release protocols for biotech corn. Australia's TGA and APVMA frameworks overlap with state-level quarantine restrictions on novel seed introductions. Stakeholders must monitor divergence between national biosafety approval timelines and the accelerating pace of gene-edited variety development.
Market Dynamics
Commercial feed millers across Southeast Asia are consolidating hybrid corn seed procurement volumes, decoupling purchasing authority from traditional village-level distribution networks and concentrating contract power with large-scale agricultural cooperatives.
Growth Catalysts
- India's PLI scheme for food processing:Breeder investment is redirecting toward high-yield wheat varieties as government incentives strengthen domestic value chains.
- Livestock operation scaling:Commercial feed millers across Thailand, Indonesia, and Vietnam are expanding hybrid corn seed procurement to match protein production growth.
- Gene-edited trait pipelines:Accelerating variety development timelines is compressing breeder-to-field release cycles for drought-tolerant rice germplasm.
Market Restraints
- Parent-line supply concentration:Tropical corn germplasm libraries remain concentrated among three multinational breeding programs, creating germplasm access bottlenecks for regional seed companies.
- Transgenic trait approval divergence:China's NMPA environmental release protocols and India's BIS certification standards operate on asynchronous timelines, delaying cross-border variety commercialization.
- Foundation seed multiplication capacity:State agricultural universities in eastern India's Indo-Gangetic Plain face infrastructure constraints limiting kharif rice foundation seed output.
Strategic Opportunities
- Organic certification documentation:Export-facing cooperatives in Australia and Japan are building certified supply chains for premium grain consignments, creating margin pools for organic seed producers.
- Two-line hybrid system licensing:Proprietary subtropical rice breeding platforms offer technology transfer potential to Southeast Asian national agricultural research systems.
- Integrated crop solution bundling:Pairing hybrid seeds with crop protection chemistry creates channel stickiness among large-scale cooperatives seeking input procurement simplification.
Industry Challenges
- Gene-edited variety classification:Divergence between national biosafety approval timelines and breeding program innovation cycles creates regulatory uncertainty for CRISPR-derived traits.
- Moisture conditioning infrastructure:Seed processing facilities require capital-intensive drying and treating equipment to achieve sub-12% moisture content and 85% field emergence standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Grain Seed Market |
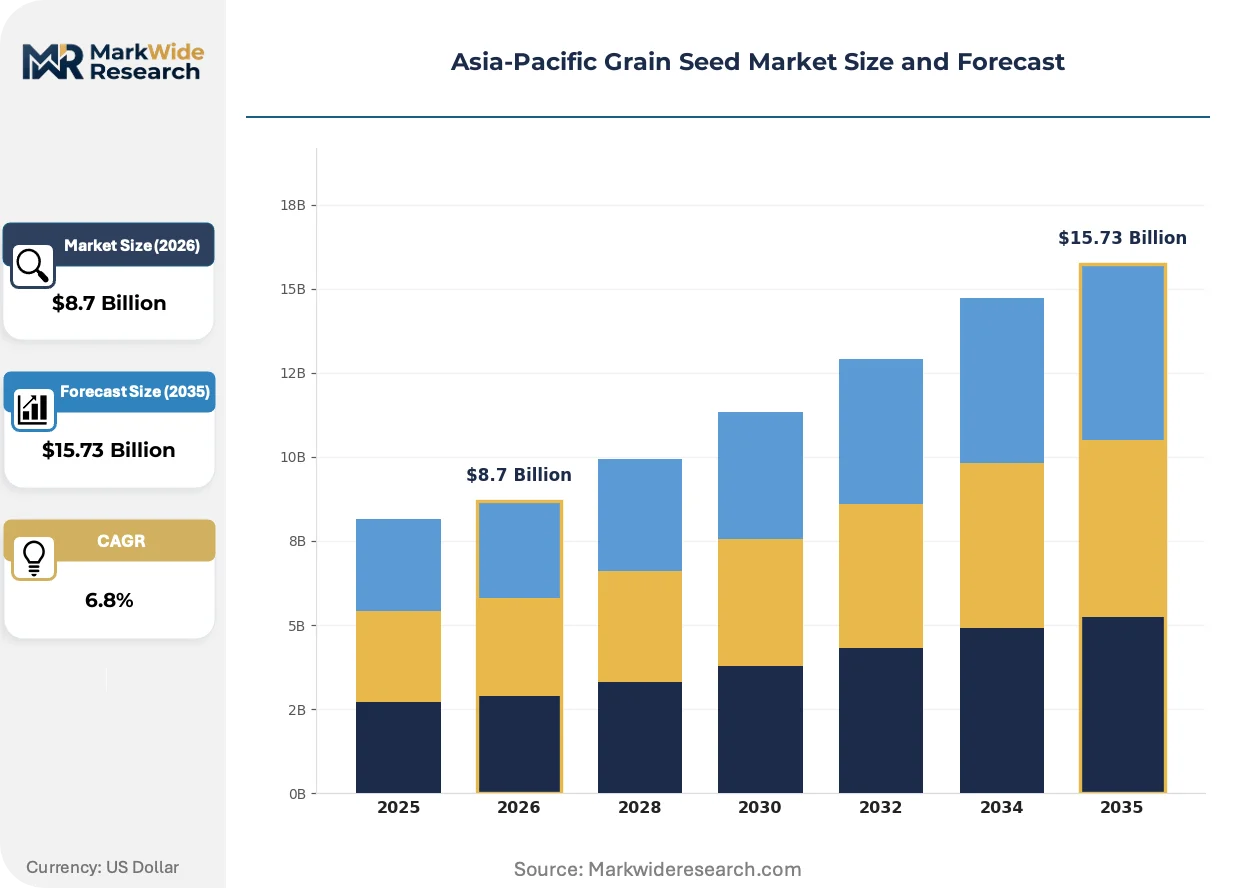
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetative Seeds, Hybrid Seeds, Open-Pollinated Seeds, Organic Seeds Cultivation Method: Conventional Farming, Organic Farming, Precision Agriculture, Sustainable Practices End User: Farmers, Agricultural Cooperatives, Seed Distributors, Government Agencies Market Channel: Direct Sales, Retail Outlets, Online Marketplaces, Wholesale Distribution |
| Companies Covered | Bayer AG, Syngenta Group, Corteva Agriscience, Yuan Longping High-Tech Agriculture Co. Ltd, Advanta Seeds - UPL, DCM Shriram Ltd (Bioseed), Groupe Limagrain, Kaveri Seeds, KWS SAAT SE & Co. KGaA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Grain Seed Market Strategic Shifts
Digital phenotyping platforms and molecular marker-assisted selection are compressing breeding cycles while regulatory frameworks scramble to classify gene-edited varieties separately from transgenic constructs.
CRISPR-Cas9 editing of drought-responsive transcription factors is automating trait introgression into elite rice and corn inbred lines. National agricultural research institutes in the Philippines and Vietnam are adopting these platforms to accelerate variety release. The technology is automating previously manual backcrossing programs that required six to eight generations for trait fixation.
China's NMPA is revising environmental release protocols to distinguish gene-edited crops from recombinant DNA transgenics, reducing field trial duration requirements for single-nucleotide edits. Seed companies with active China breeding stations are reclassifying pipeline candidates to capture streamlined approval pathways. The policy shift most affects maize trait development programs targeting water-use efficiency improvements.
Large-scale cooperatives in Thailand and Indonesia are consolidating input procurement through direct breeder contracts, bypassing traditional village-level seed dealer networks. Dealer margins are compressing as volume concentrates with fewer buyers wielding contract negotiation power. This channel restructuring is most visible in hybrid corn seed flows to commercial feed operations scaling beyond ten thousand head equivalent.
Asia-Pacific Grain Seed Market Segmentation
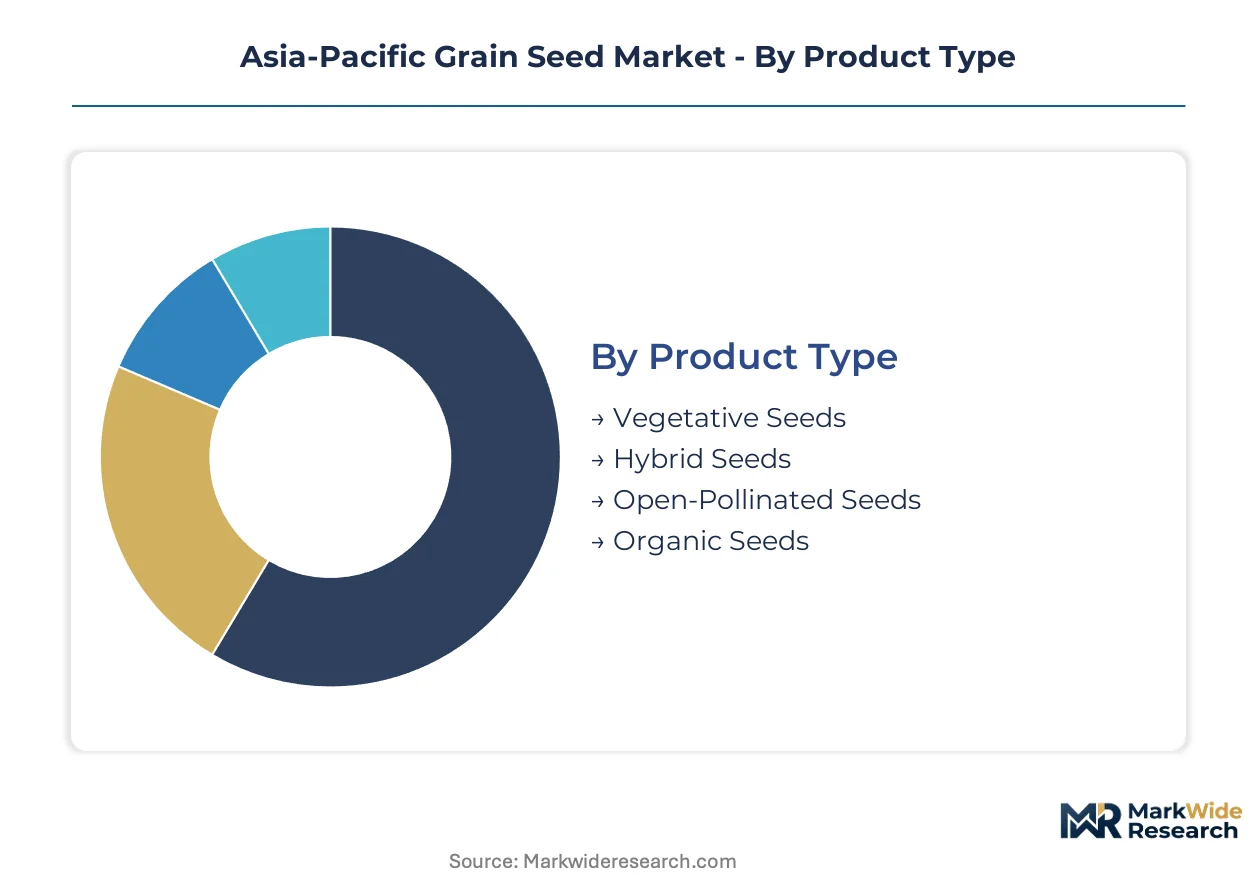
Grain seed purchasing in the Asia-Pacific region fragments across technical specifications, cultivation intensity, and procurement channel power. Breeders and distributors must align product portfolios with divergent farmer capabilities and cooperative buying consolidation.
Product Type:
Farmer willingness to pay premium prices hinges on yield stability guarantees and proprietary trait control rather than seed origin alone.
- Hybrid Seeds:Proprietary parent-line combinations deliver consistent heterosis expression in maize and rice rotations. Demand concentrates with commercial feed millers across Thailand and Indonesia who require uniform grain quality for protein production scaling.
- Open-Pollinated Seeds:Genetically stable varieties permit farmer seed-saving across seasons without yield degradation. Smallholder procurement in eastern India's marginal rainfall zones sustains volume as state agricultural universities multiply foundation stock.
- Vegetative Seeds:Asexually propagated planting material for vegetative-reproducing grain crops.
- Organic Seeds:Certified reproductive material meeting export documentation requirements for premium grain consignments.
Hybrid seeds lead on scale; organic seeds lead on momentum.
Cultivation Method:
Input intensity and certification requirements segment farmer investment capacity and seed specification demands.
- Conventional Farming:Synthetic input-dependent systems maximizing yield per hectare through intensive management. Procurement concentrates with large-scale cooperatives in Vietnam's Mekong Delta seeking volume-contracted hybrid corn for integrated feed supply chains.
- Precision Agriculture:Sensor-guided variable-rate input application optimizing seed placement and emergence timing. Australia's export-facing wheat operations adopt digital planting protocols to meet consignment uniformity standards for Japanese flour millers.
- Organic Farming:Prohibited-synthetic-input systems requiring certified seed and documented supply chain segregation.
- Sustainable Practices:Reduced-tillage and water-efficient cultivation methods preserving soil structure.
Conventional farming anchors current procurement volumes; precision agriculture climbs the fastest as digitization spreads.
End User:
Scale and technical sophistication determine seed specification complexity and contract negotiation leverage.
- Agricultural Cooperatives:Consolidated purchasing entities aggregating member demand for volume-based breeder contracts. Thailand's commercial feed-integrated cooperatives bypass village-level dealers to secure direct hybrid corn allocation.
- Farmers:Individual operators selecting varieties based on local adaptation and saved-seed compatibility. Eastern India's Indo-Gangetic Plain smallholders depend on state university foundation seed for kharif rice planting.
- Seed Distributors:Intermediary networks managing inventory logistics and credit extension to dispersed farm-gate buyers.
- Government Agencies:Public procurement bodies subsidizing seed access and regulating variety release protocols.
Agricultural cooperatives concentrate contract power; government agencies shape regulatory access.
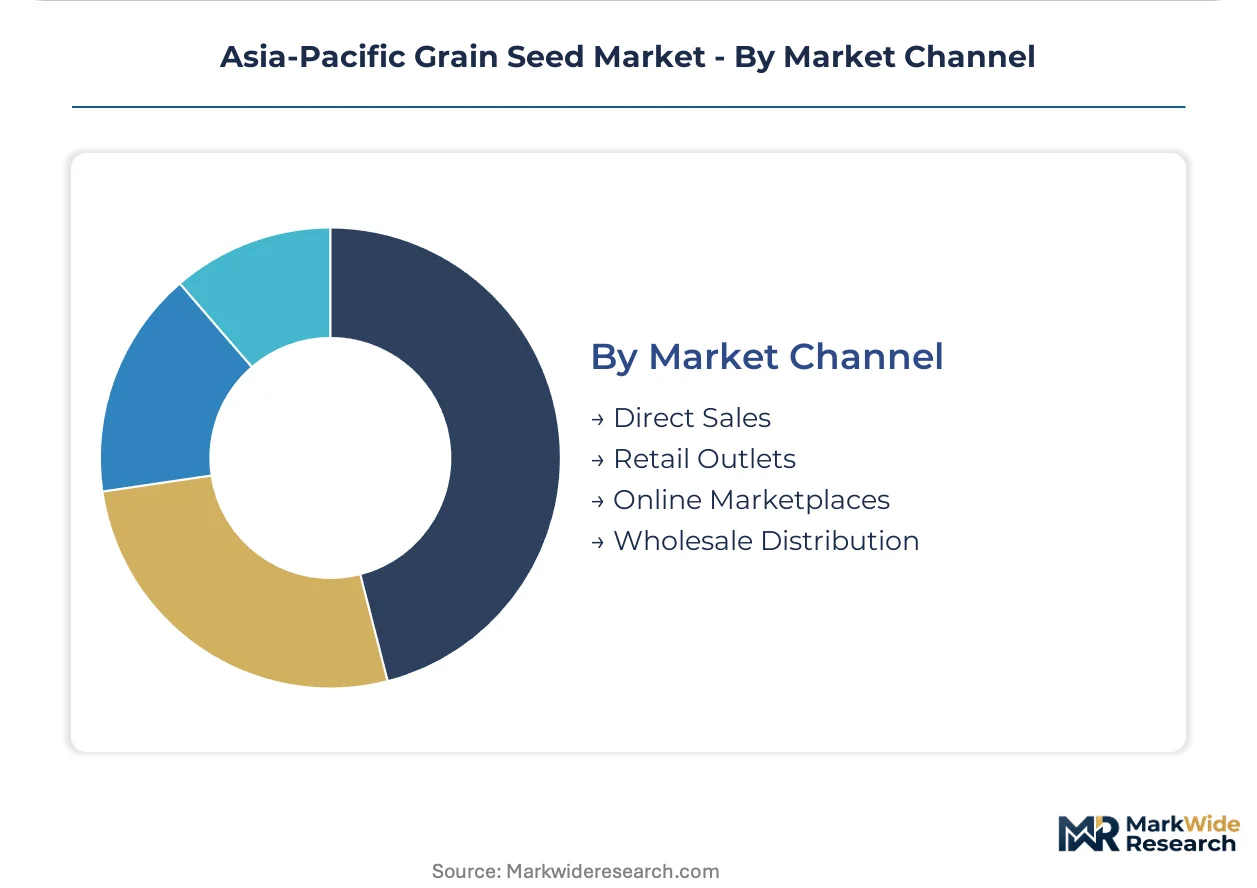
Market Channel:
Physical infrastructure and payment systems segment reach to farmer segments with divergent credit access and technical support needs.
- Wholesale Distribution:Bulk volume flows from breeder processing facilities to cooperative aggregation points. Indonesia's feed miller procurement networks rely on wholesale channels to coordinate just-in-time seed delivery across archipelago logistics.
- Direct Sales:Breeder-to-buyer contracts eliminating intermediary margins for large-volume purchasers. Bayer AG and Syngenta Group deploy technical agronomists to cooperative headquarters for variety selection consultation.
- Retail Outlets:Village-level dealer networks extending credit and small-package availability to smallholders.
- Online Marketplaces:Digital platforms aggregating variety information and enabling price comparison for informed selection.
Wholesale distribution dominates transaction value; online marketplaces gain share fastest among digitally connected younger farmers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for food processing is accelerating breeder investment toward high-yield wheat varieties, while Thailand's commercial feed millers expand hybrid corn procurement at a faster clip than Vietnam's state-coordinated distribution networks.
India
The Indo-Gangetic Plain concentrates kharif rice seed demand as state agricultural universities multiply foundation stock for smallholder distribution. India's CEA and BIS enforce minimum seed certification standards governing market access for domestic and imported genetic material. Eastern India's marginal rainfall zones sustain open-pollinated variety procurement where farmers practice seed-saving across seasons.
China
Gene-edited maize trait development is accelerating as NMPA revises environmental release protocols to distinguish single-nucleotide edits from recombinant DNA transgenics. China's GB standards regulate transgenic trait approval timelines that currently operate asynchronous to India's BIS certification. Water-use efficiency breeding programs in northern China are capturing streamlined field trial durations for drought-tolerant germplasm.
Thailand
Commercial feed-integrated cooperatives are consolidating hybrid corn seed procurement through direct breeder contracts, bypassing traditional village-level dealer networks. Thailand's tropical corn germplasm access depends on multinational breeding program licensing. The central plains region anchors large-scale cooperative aggregation points coordinating just-in-time seed delivery to protein production operations scaling beyond ten thousand head equivalent.
Indonesia
Archipelago logistics challenges are driving wholesale distribution channel concentration for hybrid corn flows to feed miller procurement networks. State agricultural research institutes are adopting CRISPR-Cas9 platforms to accelerate variety release timelines. Java's seed processing facilities require capital-intensive drying equipment to achieve sub-12% moisture content standards for field emergence rates exceeding 85%.
Australia
Export-facing wheat operations are adopting precision agriculture protocols to meet consignment uniformity standards for Japanese flour millers. Australia's TGA and APVMA frameworks overlap with state-level quarantine restrictions on novel seed introductions. Organic certification documentation is creating margin pools for certified supply chain segregation serving premium grain consignments to East Asian markets.
Asia-Pacific Grain Seed Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across breeding program ownership structures. The market exhibits tiered concentration with multinational germplasm libraries anchoring hybrid seed development and regional seed companies occupying open-pollinated variety niches. Three archetypes dominate: integrated crop solution bundlers, proprietary two-line hybrid system licensors, and foundation seed multiplication specialists. Competitive moves center on technology licensing agreements and direct cooperative contract negotiation bypassing traditional distribution layers.
Within the multinational germplasm tier, Bayer AG and Syngenta Group represent integrated crop solution approaches that pair hybrid seeds with crop protection chemistry. Yuan Longping High-Tech Agriculture Co. Ltd exemplifies the proprietary breeding platform archetype through its dominance of subtropical rice hybrid systems. These three entities occupy positions that reflect divergent strategic bets on channel control versus technology licensing across Southeast Asian and South Asian markets.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta Group |
| Corteva Agriscience |
| Yuan Longping High-Tech Agriculture Co. Ltd |
| Advanta Seeds - UPL |
| DCM Shriram Ltd (Bioseed) |
| Groupe Limagrain |
| Kaveri Seeds |
| KWS SAAT SE & Co. KGaA |
| Others |
Value Chain & Pricing Dynamics
CRISPR-Cas9 platform adoption across Southeast Asian national agricultural research institutes is compressing breeder-to-field timelines while concentrating germplasm licensing power among three multinational breeding programs with captive tropical corn libraries. This technological shift simultaneously reduces variety development costs for adopters and raises entry barriers for regional seed companies lacking parent-line access, reshaping margin distribution across hybrid seed tiers.
Pricing Analysis
Capacity additions in Indonesia and Vietnam are reshaping price floors for hybrid corn seed as state agricultural universities expand foundation seed multiplication facilities. Three-tier pricing structure across premium, standard, and economy levels reflects heterosis expression consistency and proprietary trait control, with commercial feed millers in Thailand showing lowest price sensitivity due to volume-contracted procurement. Cost compression in economy-tier open-pollinated varieties is intensifying because farmer seed-saving practices in eastern India's marginal rainfall zones reduce replacement demand.
Supply Chain Analysis
Single-source vulnerability sits with Thailand and Indonesia as archipelago logistics constraints concentrate hybrid corn germplasm flows through Java's seed processing facilities. Parent-line supply draws from multinational breeding stations in Thailand, proprietary two-line hybrid platforms in China, and state university multiplication networks in India. Tariff exposure on transgenic trait imports creates regulatory chokepoints at national biosafety approval interfaces. Distribution runs through wholesale channels coordinating just-in-time delivery to cooperative aggregation points, bypassing traditional village-level dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific grain seed market reads as a geographic-arbitrage play between India's PLI scheme incentives for food processing value chains and China's streamlined NMPA protocols for gene-edited variety approval, with cost differentials in regulatory compliance timelines exceeding those in physical production inputs.
For Market Incumbents: To counter germplasm access bottlenecks from concentrated parent-line supply, Bayer AG and Syngenta Group should deepen backward integration into tropical corn breeding stations across Thailand and Indonesia while securing certification investment in organic seed documentation for Australian export-facing cooperatives. For New Entrants and Emerging Players: Enter via organic seed multiplication partnerships with Japanese and Australian cooperatives seeking certified supply chain segregation, targeting the premium grain consignment segment where foundation seed infrastructure gaps in eastern India's Indo-Gangetic Plain create penetrable white space for certified organic producers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional seed companies with open-pollinated variety portfolios in marginal rainfall zones, where long-term viability hinges on gene-edited trait licensing agreements rather than proprietary germplasm ownership. Watch for NMPA-BIS regulatory convergence on environmental release protocols as the inflection signal for cross-border variety commercialization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Two-Line Hybrid System Licensing | Yuan Longping's proprietary platforms enable Southeast Asian NARS technology transfer without germplasm ownership. |
| Integrated Crop Solution Bundling | Syngenta's seed-crop protection pairings create channel stickiness among Thailand's consolidating cooperatives. |
| Gene-Edited Trait Pipeline Acceleration | Philippine and Vietnamese institutes adopting CRISPR-Cas9 compress breeding cycles for drought-tolerant rice. |
| Organic Certification Infrastructure | Australian export operations building documented segregation capture premium margins from Japanese flour millers. |
| Direct Cooperative Contract Negotiation | Bayer's technical agronomist deployment to cooperative headquarters bypasses dealer margin compression. |
Study Parameters
Bottom-up cooperative procurement modeling reconciled against top-down breeder shipment tracking forms the analytical core of this study. Primary interviews with seed processing facility managers, cooperative procurement officers, state agricultural university foundation seed directors, and crop protection distribution channel partners were validated against secondary sources including India's CEA certification databases, China's NMPA environmental release filings, Australia's APVMA quarantine records, and ASEAN customs trade statistics for hybrid corn seed flows.
Input-output matrices across product type, cultivation method, end user archetype, and market channel dimensions structured volume and value projections throughout the forecast period. CAGRs were derived from breeder pipeline candidate counts, foundation seed multiplication capacity expansions, and commercial feed miller procurement volume trajectories. Industry-specific inputs included kharif rice planting intention surveys from eastern India, tropical corn germplasm licensing fee structures, and gene-edited variety reclassification timelines under revised NMPA protocols.
Inputs from state agricultural university foundation seed programs were available through the study window; gaps in real-time cooperative inventory positioning introduce uncertainty bands around wholesale channel volume estimates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Pasture Seeds Market
Seeds
Myanmar Maize Seed Market
Seeds
India Rice Seed Market
Seeds
Global Packaged Chia Seeds Market
Seeds
Tomato Seed Market
Seeds
Asia-Pacific Quinoa Seeds Market
Seeds
Organic Chia Seeds Market
Seeds
China Vegetable Seed Market
Seeds
Apple Seed Oil Market
Seeds
Celery Seed Oil Market
Seeds
Garden Seeds Market
Seeds
Spain Forage Seed Market
Seeds
Global Seed Market
Seeds
Southeast Asia Seed Market
Seeds
Bangladesh Seed Market
Seeds
Philippines Rice Seed Market