
 Broadcast Infrastructure Market | 2026-2036
Broadcast Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Broadcast Infrastructure Market Analysis
The divergence between premium broadcast-grade infrastructure and commodity streaming hardware is hardening. Ross Video Ltd leverages its integrated production ecosystem to dominate high-end live broadcast environments. Cisco Systems, Inc. anchors enterprise and service provider networks with routing and IP transport portfolios. Grass Valley specializes in camera and playout systems for tier-one sports and news operations.
Broadcast infrastructure encompasses the physical and virtual systems enabling audio-visual content acquisition, processing, transmission, and distribution to mass audiences, typically operating at broadcast bitrates exceeding 1.5 Gbps for uncompressed HD signals and requiring sub-frame latency for live production. Its primary commercial purpose is ensuring reliable, synchronized delivery of content to viewers across terrestrial, satellite, cable, and internet protocols. IP-based technology leads capital deployment as broadcasters migrate from baseband SDI to SMPTE ST 2110 packetized workflows, while encoding equipment captures margin pools through software-defined and cloud-native compression architectures. Satellite transmission remains mature in remote and continental coverage scenarios where fiber lacks economic viability.
The Federal Communications Commission shapes spectrum allocation and station licensing requirements in the United States, while the European Telecommunications Standards Institute and EBU Technical Committee define interoperability frameworks for cross-border signal exchange. China's Ministry of Industry and Information Technology governs terrestrial broadcast standards and network equipment certification, directly affecting vendor market access. Stakeholders must monitor regulatory timelines for spectrum repacking and emission standards, as these dictate replacement cycles and compatibility investments across installed bases.
Market Dynamics
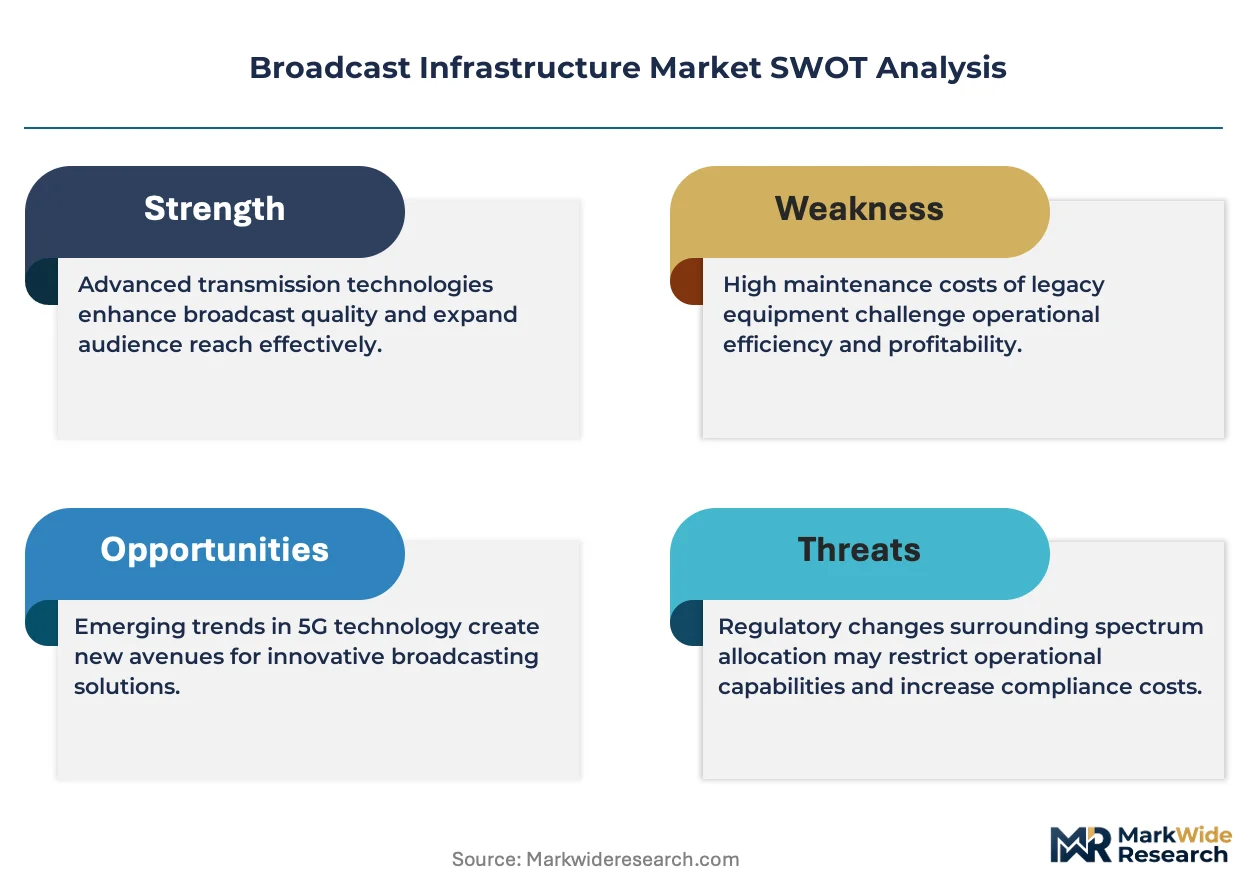
The migration from SDI baseband to IP-based SMPTE ST 2110 workflows is compressing equipment refresh cycles while fragmenting vendor ecosystems between specialized broadcast suppliers and IT-centric networking firms.
Growth Catalysts
- Streaming infrastructure expansion:OTT platforms are building dedicated broadcast-grade facilities for live sports and news, creating demand for synchronized multi-camera acquisition systems and low-latency encoding clusters.
- Spectrum repacking mandates:The Federal Communications Commission's incentive auction aftermath requires U.S. broadcasters to retune transmitters and replace RF chains, accelerating capital deployment in terrestrial transmission infrastructure.
- Cloud-native production:Software-defined playout and remote production architectures enable broadcasters to centralize operations and reduce physical facility footprints, driving virtualization investments.
Market Restraints
- Semiconductor supply concentration:FPGA and high-speed networking silicon dependencies on Taiwan-based foundries create vulnerability in professional video processing hardware procurement timelines.
- Capital intensity of IP transition:Complete facility overhauls require simultaneous investment in new cameras, routers, monitoring systems, and staff retraining, straining mid-market broadcaster budgets.
- Terrestrial broadcast substitution:Broadband internet delivery and mobile streaming applications erode addressable audiences for traditional over-the-air transmission infrastructure in urban markets.
Strategic Opportunities
- Remote production centralization:Sports leagues and concert promoters are adopting at-home production models where centralized facilities control distributed venue feeds, reducing on-site crew requirements.
- 5G broadcast trials:China's Ministry of Industry and Information Technology is licensing 5G New Radio broadcast modes for terrestrial television, opening spectrum-efficient distribution channels.
- AI-powered content automation:Machine learning for highlight clipping, automated camera tracking, and real-time graphics generation is converging with traditional production workflows to reduce labor costs.
Industry Challenges
- Hybrid skill scarcity:Broadcast engineering expertise in SDI timing and synchronization must merge with IP networking and cloud architecture competencies, creating recruitment friction.
- Interoperability certification delays:SMPTE ST 2110 implementation variations across vendors require extensive on-site integration testing before multi-brand deployments achieve frame-accurate performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Broadcast Infrastructure Market |
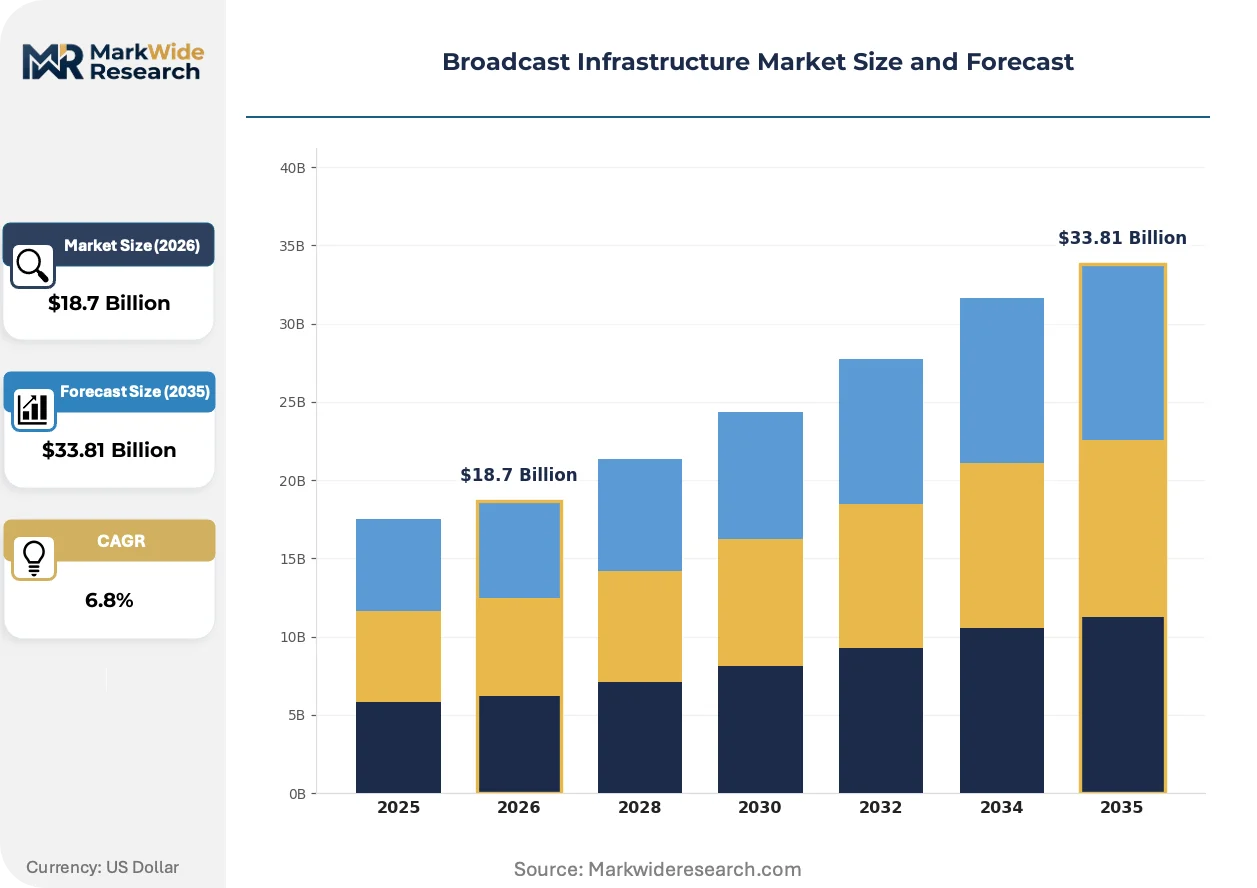
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
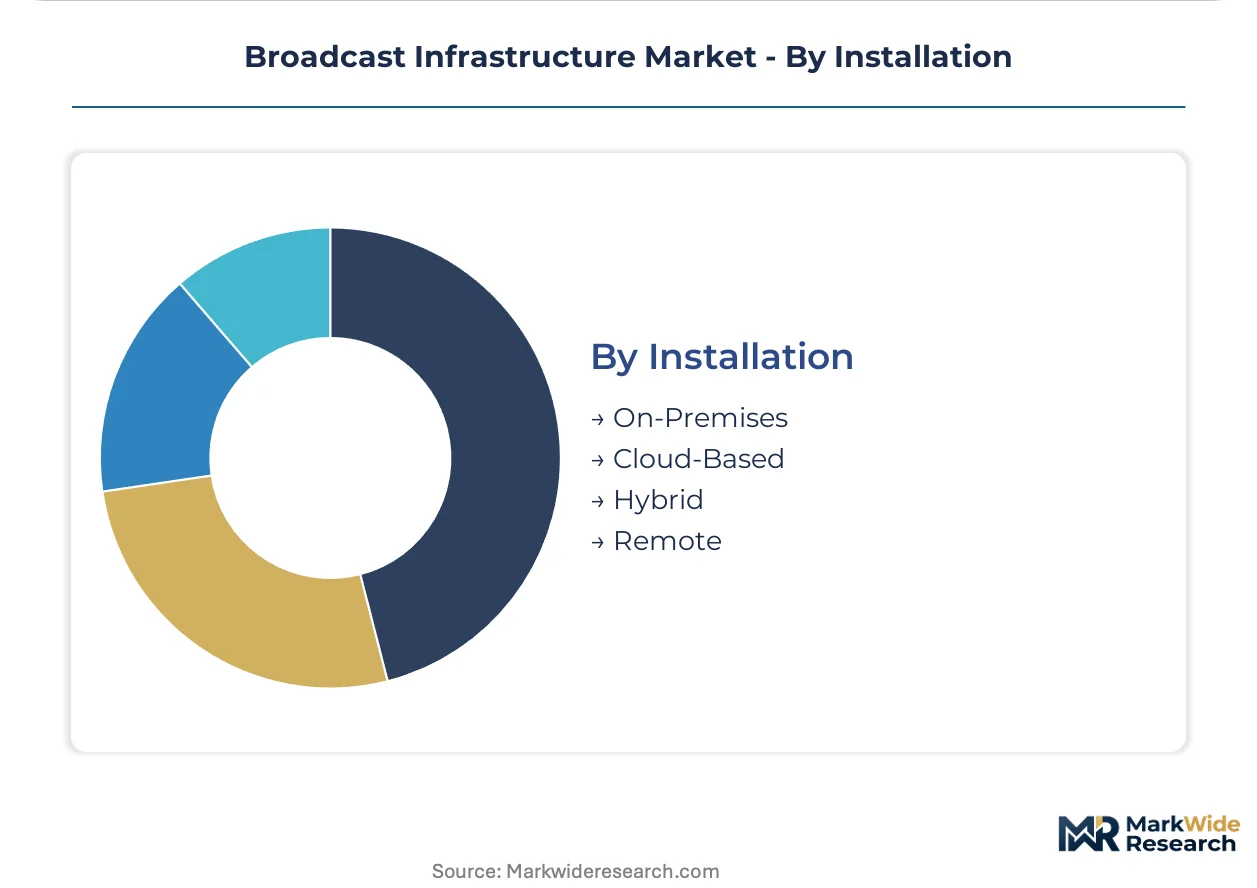
| Segmentation | Technology: Satellite Transmission, Fiber Optic, Terrestrial, IP-Based Product Type: Encoding Equipment, Modulators, Switchers, Routers End User: Broadcasters, Content Providers, Streaming Services, Network Operators Installation: On-Premises, Cloud-Based, Hybrid, Remote |
| Companies Covered | Ross Video Ltd, Kaltura, Cisco Systems, Inc., Clyde Broadcast Technology, Dacast Inc., EVS Broadcast Equipment SA, Nevion, Zixi, Grass Valley, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Broadcast Infrastructure Market Emerging Trajectories
Compression of production timelines and the unbundling of hardware from software licenses are restructuring how broadcast technology is procured, deployed, and upgraded across facility types.
Software-defined video processing is converging with commodity server hardware to displace dedicated appliance architectures. Tier-one sports networks are deploying CPU-based encoding farms for multi-format distribution, collapsing the traditional separation between production and delivery infrastructure. This convergence is enabling broadcasters to scale capacity through cloud bursting rather than fixed capital expenditure.
The European Telecommunications Standards Institute's work on media transport over managed IP networks is mandating interoperability testing for cross-border signal exchange. Broadcasters operating across Germany, France, and the Netherlands must now certify equipment against common timing and synchronization profiles. Regional network operators are consolidating vendor lists to reduce integration complexity.
Service-based commercial models are replacing perpetual license purchases in playout and master control. Broadcasters in the United States are adopting subscription pricing for channel origination software, shifting cost structures from capital to operating expenditure. This transition is most advanced among multicast network operators managing dozens of programmatic channels.
Broadcast Infrastructure Market Segmentation
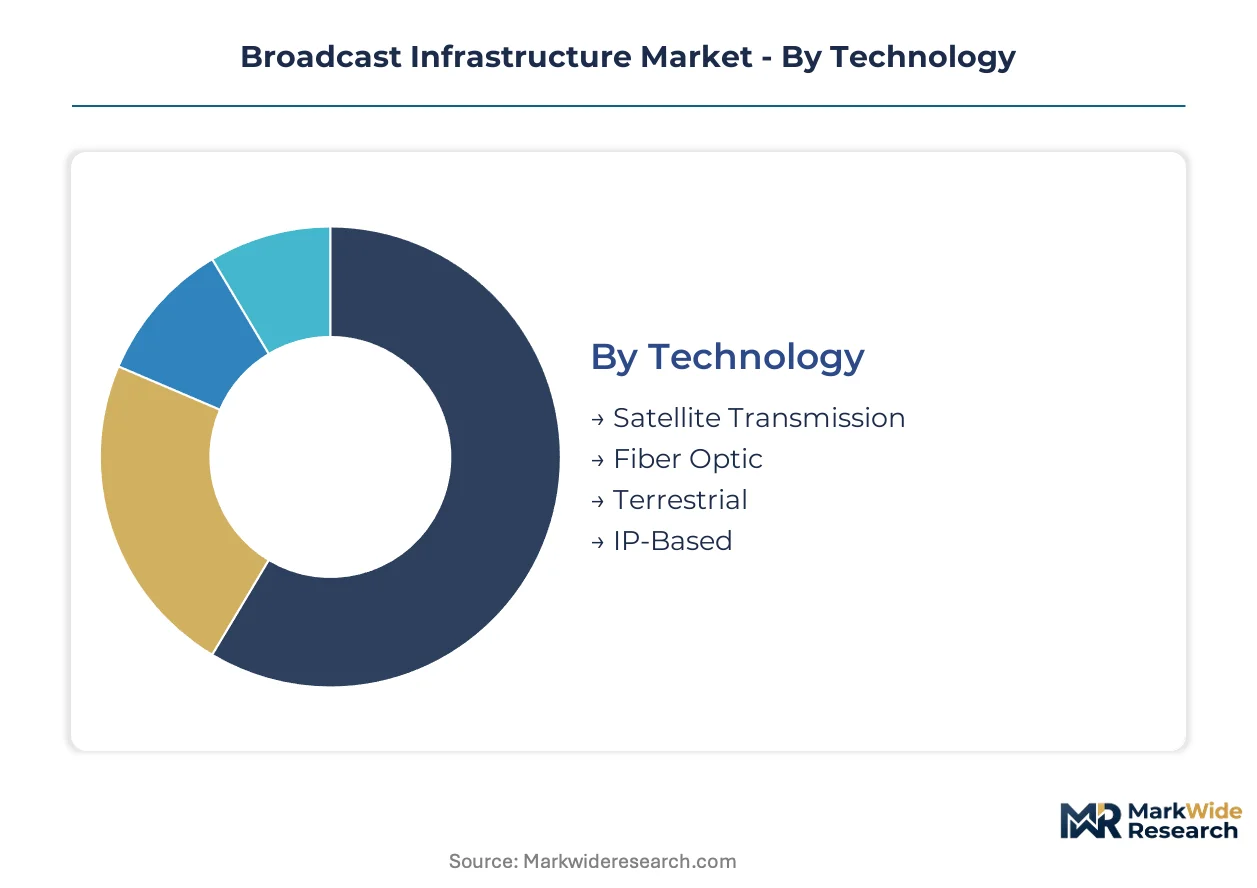
Broadcast infrastructure procurement diverges sharply across buyer archetypes. Sports networks prioritize sub-frame latency and 4K HDR capability, while multicast operators optimize for channel density and operational expenditure flexibility.
Technology:
Capital allocation decisions hinge on facility lifecycle position and geographic fiber availability.
- IP-Based:SMPTE ST 2110 packetized workflows displace SDI baseband in greenfield studios and major facility rebuilds. Tier-one sports networks in the United States and Germany are standardizing on software-defined routing with centralized timing distribution.
- Satellite Transmission:Ku-band and Ka-band systems dominate continental and maritime coverage where terrestrial fiber lacks economic viability. Remote production for international sports feeds and disaster recovery broadcasting sustain demand despite compression efficiency gaps versus fiber.
- Fiber Optic:Dense wavelength division multiplexing enables uncompressed multi-camera transport between venues and production centers. Stadium connectivity upgrades in China and Germany are driving dark fiber leasing and managed wavelength service contracts.
- Terrestrial:UHF and VHF transmission infrastructure faces capital constraints from spectrum repacking mandates and audience fragmentation. The FCC's post-incentive auction retuning requirements force transmitter replacement cycles in the United States.
Volume sits with terrestrial legacy systems; growth tilts toward IP-based infrastructure.
Product Type:
Margin concentration follows the boundary between hardware appliances and software licensure.
- Encoding Equipment:Software-defined and cloud-native compression architectures capture expanding margin pools. CPU-based encoding farms enable simultaneous multi-format distribution for streaming services building broadcast-grade facilities.
- Routers:IP routing platforms from IT-centric networking vendors compete with broadcast-specialized frame synchronization systems. Hybrid SDI-IP routers bridge migration timelines for mid-market broadcasters constrained by capital budgets.
- Switchers:Production switchers integrate AI-powered camera tracking and automated graphics generation. Remote production centralization reduces on-site hardware footprints while demanding higher-capacity studio-based switching systems.
- Modulators:COFDM and ATSC 3.0 modulators serve terrestrial transmission infrastructure replacement cycles. China's MIIT licensing of 5G New Radio broadcast modes creates adjacent demand for next-generation modulation platforms.
Encoding equipment commands premium pricing; switchers face the steepest competitive pressure from software alternatives.
End User:
Procurement scale and technical specification intensity vary dramatically across buyer categories.
- Streaming Services:OTT platforms are constructing dedicated broadcast-grade facilities for live sports and news, requiring synchronized multi-camera acquisition and low-latency encoding clusters. Cloud-native playout and subscription-based software licensing align with their operational expenditure preferences.
- Broadcasters:Traditional television networks manage hybrid SDI-IP environments through phased migration roadmaps. Spectrum repacking mandates and emission standard compliance dictate replacement cycles for terrestrial transmission chains.
- Content Providers:Sports leagues and concert promoters adopt at-home production models with centralized facility control over distributed venue feeds. Reduced on-site crew requirements drive investment in remote production infrastructure.
- Network Operators:Multicast and programmatic channel operators prioritize channel density and automated monitoring. Service-based commercial models for playout software shift cost structures from capital to operating expenditure.
Streaming services are expanding most quickly; broadcasters retain the largest installed base requiring maintenance and migration.
Installation:
Deployment architecture selection reflects workforce distribution, latency tolerance, and capital availability.
- Cloud-Based:Software-defined playout and master control enable broadcasters to centralize operations and reduce physical facility footprints. Virtualization investments align with multicast network operators managing dozens of programmatic channels.
- Hybrid:Split architectures locate real-time production functions on-premises while pushing distribution and archiving to cloud infrastructure. This configuration dominates sports and news operations requiring guaranteed sub-frame latency for live switching.
- On-Premises:Traditional facility-based infrastructure persists where regulatory compliance, security classification, or network reliability concerns restrict off-premises processing. Government and defense broadcasters maintain this preference.
- Remote:Distributed production models centralize technical direction while cameras and audio acquisition remain at venue locations. Dark fiber and managed IP network investments enable this architecture for concert and sports touring applications.
Hybrid deployments dominate current procurement; cloud-native architectures are gaining share fastest among new entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors broadcast infrastructure deployment through its concentration of streaming service headquarters and sports production facilities. The city's ecosystem of post-production houses and live event specialists drives continuous refresh cycles for IP-based routing and encoding systems.
United States
OTT platforms headquartered in Los Angeles and New York Metro are constructing dedicated broadcast-grade facilities for live sports acquisition. The Federal Communications Commission's post-incentive auction retuning mandates force transmitter replacement cycles across major metropolitan markets. Spectrum repacking requirements concentrate capital deployment in terrestrial transmission infrastructure throughout the Northeast Corridor and California.
China
State-backed broadcasters in Beijing and Shanghai are expanding 4K HDR production capacity ahead of international sporting events. The Ministry of Industry and Information Technology governs terrestrial broadcast standards and network equipment certification, directly affecting vendor market access. Dark fiber leasing between venues and production centers accelerates in the Yangtze River Delta region.
Germany
Public broadcasters in Munich and Cologne maintain Europe's most extensive terrestrial transmission networks requiring continuous modernization. The European Telecommunications Standards Institute mandates interoperability testing for cross-border signal exchange affecting equipment procurement. The Cologne-Bonn corridor hosts concentrated encoding and playout operations serving pan-European distribution.
Japan
Tokyo-based broadcasters lead 8K production infrastructure deployment for flagship sporting and cultural programming. METI coordinates national broadband and broadcast convergence policies shaping facility investment timelines. The Kanto region's dense fiber infrastructure enables remote production centralization for concert and esports applications.
United Kingdom
London's production services sector supplies remote production infrastructure for international sports leagues and concert tours. Ofcom regulates spectrum allocation and emission standards affecting terrestrial transmission replacement cycles. The Manchester MediaCityUK cluster anchors centralized playout operations for multicast network operators.
Broadcast Infrastructure Market Vendor Landscape
Premium-margin players sit above commodity-margin players across the live production versus software streaming divide. The vendor ecosystem fragments between specialized broadcast suppliers with deep timing synchronization expertise and IT-centric networking firms leveraging commodity silicon. Three archetypes dominate: integrated production ecosystem providers, enterprise networking incumbents, and cloud-native software specialists. Consolidation through strategic technology licensing and geographic distribution partnerships represents the dominant competitive trajectory.
Within the integrated production tier, Ross Video Ltd and Grass Valley exemplify vendors anchoring high-end live broadcast environments through tightly coupled hardware-software portfolios. Cisco Systems, Inc. occupies a distinct position leveraging enterprise routing and IP transport expertise to serve service provider and broadcaster network infrastructure requirements. These three entities represent the structural segmentation between broadcast-native specialization and IT-centric scale.
| Leading Market Players |
|---|
| Ross Video Ltd |
| Kaltura |
| Cisco Systems, Inc. |
| Clyde Broadcast Technology |
| Dacast Inc. |
| EVS Broadcast Equipment SA |
| Nevion |
| Zixi |
| Grass Valley |
| Others |
Supply Flow & Price Mechanics
China's dual carbon goals and associated green manufacturing mandates gate qualified supply for broadcast infrastructure vendors while stratifying pricing access across certification tiers. Equipment suppliers meeting MIIT energy-efficiency standards and ETSI environmental directives command premium positioning, whereas uncertified manufacturers face exclusion from tier-one broadcaster procurement lists.
Pricing Analysis
Value-based pricing anchored to guaranteed uptime and signal throughput dominates high-end live production contracts. Three-tier pricing structure across premium, standard, and economy levels separates broadcast-grade SMPTE ST 2110 systems from mid-market hybrid SDI-IP routers and commodity encoding appliances. Price differentiation hinges on certification level—EBU Technical Committee interoperability badges and FCC equipment authorization—and vertical integration depth in timing synchronization. Cost compression in the economy tier is intensifying because CPU-based software encoders displace FPGA-dependent hardware. Streaming services exhibit the lowest price sensitivity due to operational expenditure preferences, while multicast network operators prioritize per-channel economics.
Supply Chain Analysis
High-speed networking silicon and broadcast-specific FPGA supply rests on Taiwan-based foundries, Japanese specialty semiconductor houses, and select US fabless designers. Raw material dependencies span gallium nitride substrates for RF power amplifiers, precision crystal oscillators for timing distribution, and advanced organic substrates for high-density interconnect. Single-source vulnerability concentrates in 7nm and below process nodes for software-defined routing silicon. Distribution runs through authorized broadcast technology integrators in Los Angeles, London, and Beijing, with direct OEM relationships reserved for national broadcasters and multinational streaming platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Broadcast infrastructure is becoming a vertical-integration race where control over timing synchronization IP and encoding software stacks determines margin capture. Players are pursuing backward integration into FPGA firmware and cloud-native compression algorithms to escape commodity hardware pricing.
For Market Incumbents: Hedge against IT-centric networking vendors encroaching on routing and transport layers by deepening proprietary timing distribution ecosystems. Acquire specialized AI-powered camera tracking startups to defend production switcher margins from software alternatives. Prioritize certification investment for China's MIIT 5G broadcast standards to maintain vendor list eligibility. For New Entrants and Emerging Players: Enter via cloud-native playout and channel origination software serving multicast network operators managing programmatic channels. Target the remote production centralization segment where dark fiber leasing and managed IP services create service-revenue attach opportunities. Lead with subscription pricing models aligned with streaming service operational expenditure preferences. For Investors and Strategic Acquirers: The first major sports league adopting at-home production for an entire season is the leading indicator that centralized facility architectures have crossed the adoption threshold. Long-term viability favors vendors with software-defined portfolios decoupled from hardware refresh cycles. Acquisition focus should center on encoding software specialists with CPU-native compression stacks. Watch for 5G New Radio broadcast licensing decisions in additional national markets as spectrum policy inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| SMPTE ST 2110 Certification Investment | EBU Technical Committee interoperability badges unlock tier-one sports network procurement in Germany and the United States. |
| Cloud-Native Playout Platform Launch | Subscription pricing models align with multicast operators shifting capital expenditure to operational expenditure structures. |
| Backward Integration into Timing Silicon | In-house FPGA firmware development for PTP synchronization reduces dependency on Taiwan foundry allocation cycles. |
| Strategic Partnership with Dark Fiber Providers | Stadium connectivity contracts in China's Yangtze River Delta anchor remote production centralization deployments. |
| Acquisition of AI Camera Tracking Specialist | Automated production capabilities defend switcher margins against software-based alternatives entering from adjacent markets. |
Methodological Framework
SEC 10-K filings, ETSI technical specifications, and MIIT equipment certification databases formed the secondary backbone for market sizing and competitive positioning. Primary interviews with broadcast engineering directors, IP network architects at streaming services, and procurement leads at national broadcasters validated demand assumptions and technology transition timelines. Bottom-up and top-down triangulation reconciled facility-level capital expenditure patterns against aggregate vendor revenue disclosures.
Bottom-up modeling of equipment shipments by technology segment—IP-based, satellite, fiber optic, terrestrial—was cross-checked against top-down broadcaster capital expenditure surveys. Segmentation dimensions spanned deployment architecture, end-user category, and geographic regulatory cluster across the analysis window. CAGRs were derived from fitted adoption curves for SMPTE ST 2110 migration and software-defined encoding penetration, incorporating FCC spectrum repacking mandates and China's 5G broadcast licensing timeline as policy drivers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption scenarios or accelerated terrestrial broadcast substitution. Forecasts reflect assumptions regarding IP transition velocity and cloud-native adoption rates among mid-market broadcasters. A small set of named triggers—foundry allocation shocks, spectrum policy reversals, and major sports league production centralization decisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Slovenia Telecom Market
Telecommunications Infrastructure
Canada Telecom Towers Market
Telecommunications Infrastructure
Philippines Telecom Towers Market
Telecommunications Infrastructure
Session Initiation Protocol (SIP) Trunk Market
Telecommunications Infrastructure
Chile Telecom Tower Market
Telecommunications Infrastructure
Latin America Telecom Tower Market
Telecommunications Infrastructure
Telecom Network Infrastructure Market
Telecommunications Infrastructure
Global Optical Transport Network (OTN) Equipment Market
Telecommunications Infrastructure
Wireless Infrastructure Market
Telecommunications Infrastructure
UAE Telecom Towers Market
Telecommunications Infrastructure
Africa Telecom Towers and Allied Market
Telecommunications Infrastructure
Thailand Telecom Towers Market
Telecommunications Infrastructure
Global Cellular Networks Market
Telecommunications Infrastructure
Peru Telecom Tower Market
Telecommunications Infrastructure
Iraq Telecom Market
Telecommunications Infrastructure
Global Integrated Telecom Infrastructure Market