
 Meat Products Market | 2026-2036
Meat Products Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Products Market Foresight
Asset-light contract processing and third-party cold-chain leasing is rewriting competitive entry barriers in meat production. JBS leverages integrated feedlot-to-retail operations across multiple continents to sustain cost leadership in beef. Tyson Foods anchors its position through in-house rendering and value-added poultry capacity that controls margin capture at every stage.
Meat products encompass muscle tissue and edible offal from slaughtered livestock, processed through chilling, grinding, curing, smoking, or mechanical separation to achieve specified pH, moisture-protein ratios, and microbiological safety thresholds for human consumption. Fresh and frozen processing methods dominate volume throughput, though cured and smoked categories command higher margin pools due to extended shelf-life premiums and artisan positioning. Poultry leads product-type growth on feed-conversion efficiency, while beef occupies the highest absolute value tier in retail and food service channels.
The USDA Food Safety and Inspection Service enforces pathogen-reduction and hazard-analysis standards that shape plant design and operational costs, while FDA oversight of cell-cultured proteins and novel ingredients determines which technologies gain market access. EU REACH and EFSA frameworks restrict certain preservatives and processing aids, forcing reformulation for export-bound products. Stakeholders must monitor how divergent regulatory pathways for conventional and alternative proteins reshape capital allocation and facility certification requirements.
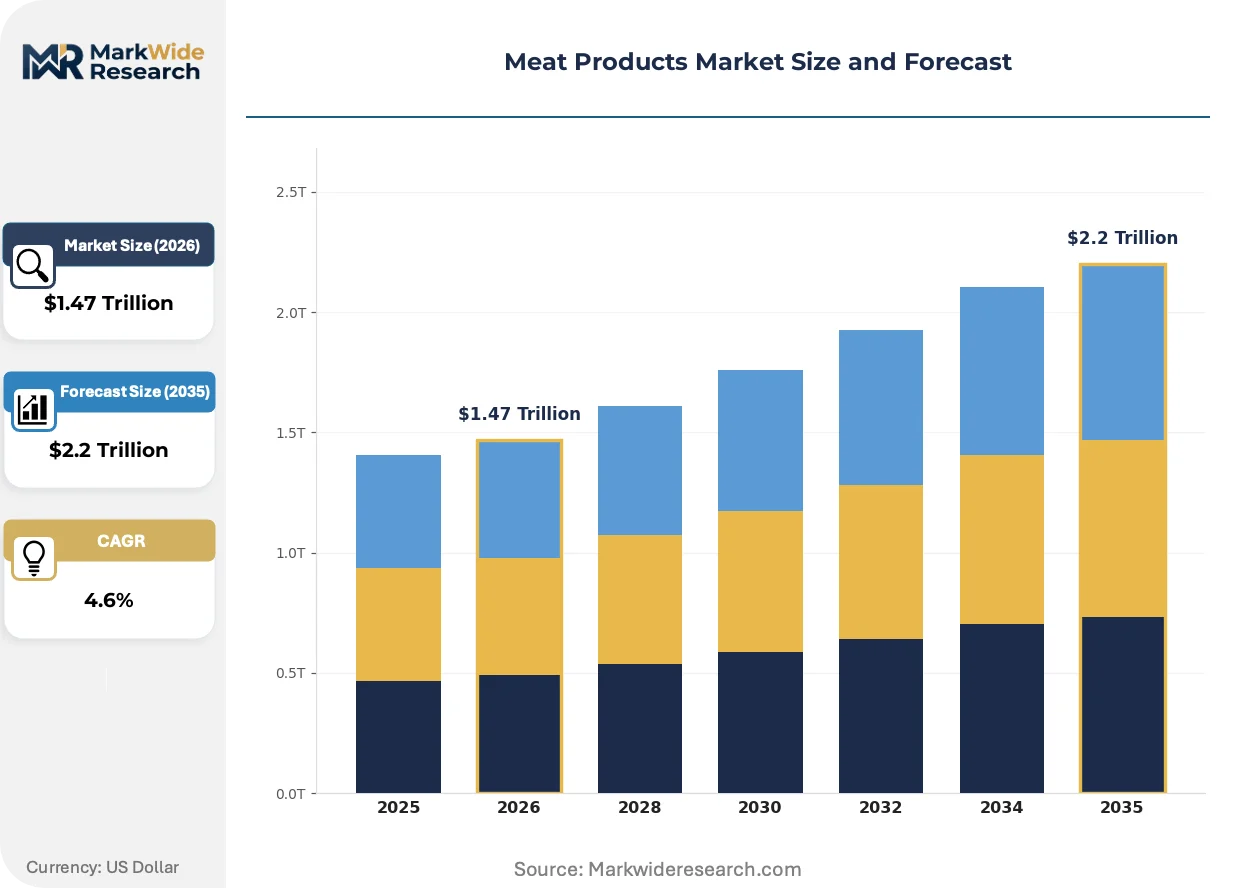
Market Dynamics
Asset-light contract processing and third-party cold-chain leasing are collapsing traditional capital barriers in meat production, enabling new entrants to scale without owning feedlots, slaughter facilities, or refrigerated logistics networks.
Growth Catalysts
- Cell-cultured protein frameworks:FDA and USDA joint oversight is creating clear pathways for novel protein commercialization, attracting venture capital into bioreactor-based manufacturing.
- Food service procurement expansion:Institutional buyers in Brazil are consolidating purchases of value-added processed meats, driving volume commitments that justify dedicated processing lines.
- Feed-conversion efficiency gains:Poultry production economics continue to outperform ruminant systems on input-to-output ratios, redirecting capacity investment toward broiler operations.
Market Restraints
- Feed grain price volatility:Corn and soybean meal input costs swing with weather patterns and biofuel policy, compressing processor margins without forward-contract coverage.
- Plant certification bottlenecks:USDA FSIS hazard-analysis compliance timelines stretch 18-24 months for new facilities, freezing capacity expansion in high-demand corridors.
- Plant-based substitution pressure:Pea and mycoprotein alternatives capture shelf space in European retail, forcing conventional meat into price-competitive positioning.
Strategic Opportunities
- Brazilian export corridor deepening:JBS and Marfrig infrastructure anchors untapped capacity for Middle Eastern and Asian halal-certified beef segments.
- Rendering co-product valorization:Tyson Foods demonstrates margin capture through in-house fat and protein recovery, a model replicable for mid-scale processors.
- EU Green Deal alignment:Methane-reduction incentives and carbon-border adjustment mechanisms reward low-emission supply chain investments with preferential market access.
Industry Challenges
- HACCP specialist scarcity:Qualified food safety system implementers command premium wages, delaying plant startups and audit readiness.
- Cold-chain integration complexity:Legacy refrigerated transport fleets lack real-time temperature monitoring compatibility with retailer traceability mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Products Market |
| Market Size in 2026 | $1.47 Trillion |
| Market Size in 2035 | $2.2 Trillion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Lamb Processing Method: Fresh, Frozen, Cured, Smoked Distribution Channel: Retail, Wholesale, Online, Food Service Packaging Type: Vacuum Pack, Tray Pack, Canned, Others |
| Companies Covered | Tyson Foods, JBS, Cargill, National Beef Packing Company, Hormel Foods, Smithfield Foods, Danish Crown, Marfrig, Pilgrim's Pride, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Products Market Shifts & Advancements
Processing technology and protein sourcing methods are diverging sharply, with conventional mechanical separation competing against cellular agriculture for capital and regulatory attention.
High-pressure processing is migrating from premium ready-to-eat deli categories into raw ground beef and poultry applications. Retail chains with private-label programs are adopting HPP for pathogen reduction without thermal degradation. This shift is compressing the shelf-life advantage traditionally held by cured and smoked products.
EU REACH restrictions on nitrite preservatives and EFSA evaluations of processed meat consumption are forcing reformulation of export-bound cured products. Manufacturers are substituting celery powder and fermentation-derived cultures for synthetic curing agents. German and Dutch processors face the steepest compliance costs, redirecting R&D spending toward clean-label alternatives.
Direct procurement from integrated packers is displacing traditional spot-market buying among large food service operators. Contract structures now specify origin verification and antibiotic-free protocols rather than commodity grades. This pattern concentrates most visibly in US institutional feeding programs and Brazilian quick-service restaurant supply chains.
Meat Products Market Segmentation
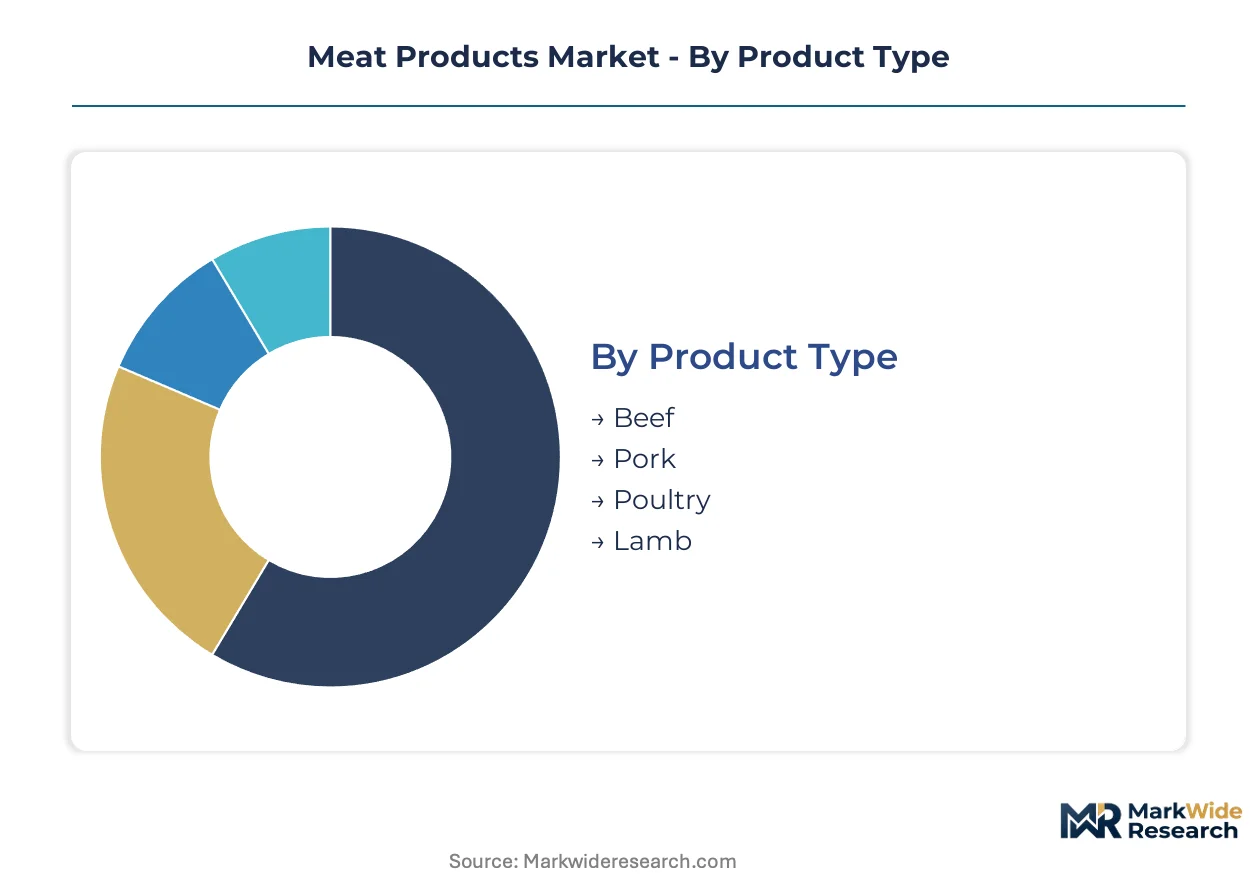
Meat product segmentation reveals how processing economics, channel requirements, and shelf-life specifications fragment procurement and pricing strategies. Understanding these divisions exposes where margin pools concentrate and where capital deployment faces technical or regulatory friction.
Product Type:
Fresh consumption patterns and feed-conversion economics split demand across species, with each protein type serving distinct cost tiers and culinary applications.
- Beef:Muscle tissue from cattle delivers the highest absolute value tier in retail and food service channels, commanding premium positioning in steakhouses and butcher counters. Demand concentrates in Brazil's export corridors, where integrated feedlot operations supply halal-certified cuts to Middle Eastern buyers despite methane-emission scrutiny under EU carbon-border mechanisms.
- Poultry:Broiler meat achieves superior feed-conversion ratios against ruminant systems, redirecting capacity investment toward vertically integrated operations. Food service operators in the United States consolidate procurement through antibiotic-free contract specifications that bypass traditional commodity spot markets.
- Pork:Versatile carcass utilization across fresh cuts and processed applications sustains volume throughput in European and Asian markets. Chinese domestic production and Danish export specialization anchor regional supply concentration.
- Lamb:Niche positioning in Middle Eastern, North African, and Australian markets depends on religious slaughter certification and seasonal consumption patterns. New Zealand's pasture-based systems supply premium chilled exports to high-income urban centers.
The dominant share belongs to poultry, while beef is closing the gap fastest through Brazilian export infrastructure expansion.
Processing Method:
Capital intensity and shelf-life extension capabilities create four distinct operational models with diverging margin structures and regulatory footprints.
- Fresh:Chilled muscle tissue maintains native pH and moisture-protein ratios for immediate consumption windows, dominating volume throughput in developed markets. Retail chains specify HACCP-verified cold-chain integrity from slaughter to display case.
- Frozen:Blast-freezing at minus 18 degrees Celsius enables intercontinental trade and inventory smoothing against feed-price volatility. Brazilian and Australian exporters leverage frozen bulk formats for Asian commodity procurement.
- Cured:Nitrite or fermentation-derived preservation extends shelf life while developing distinctive flavor profiles, though EU REACH restrictions on synthetic curing agents force costly reformulation for export-bound products. German and Dutch processors face steepest compliance burdens.
- Smoked:Thermal processing with wood-derived compounds creates artisan positioning in premium retail and food service channels, commanding extended shelf-life premiums against fresh alternatives.
Fresh processing retains volume leadership, though cured formats are gaining share fastest through clean-label reformulation investments.
Distribution Channel:
Customer scale and traceability requirements fragment logistics models, from pallet-scale institutional procurement to single-unit e-commerce fulfillment.
- Retail:Supermarket and hypermarket chains dominate developed-market volume, with private-label programs adopting high-pressure processing for pathogen reduction. Origin verification and antibiotic-free protocols now supersede traditional commodity grading in contract negotiations.
- Wholesale:Distributor intermediaries aggregate fragmented demand from independent butchers and small food service operators, concentrating purchasing power in regional hub markets.
- Online:Direct-to-consumer platforms require specialized insulated packaging and last-mile cold-chain investment, attracting venture capital into refrigerated logistics start-ups serving metropolitan concentrations.
- Food Service:Quick-service restaurant chains and institutional feeding programs in Brazil and the United States consolidate procurement through multi-year volume commitments that justify dedicated processing lines.
Food service channels are expanding most quickly, while retail maintains absolute value concentration.
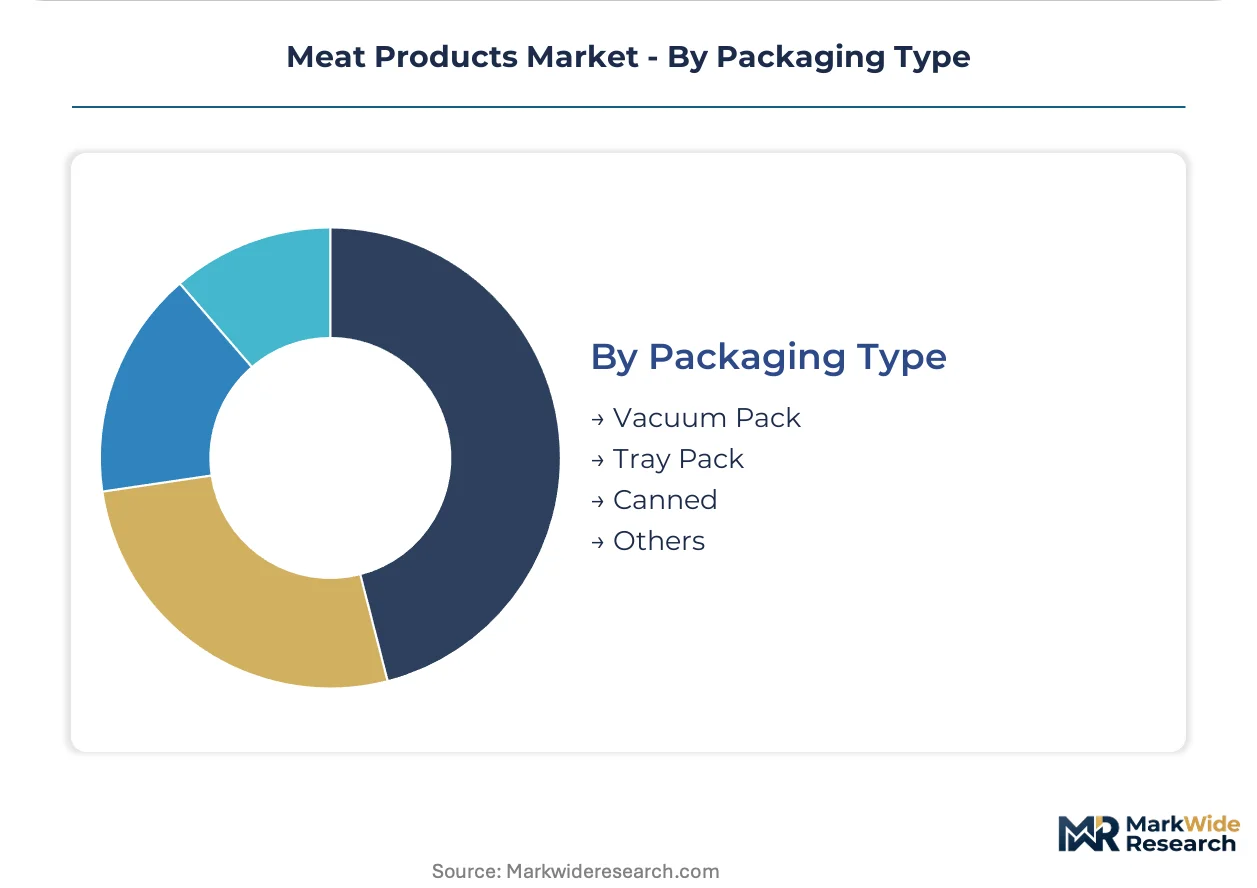
Packaging Type:
Barrier properties and shelf-life extension capabilities determine format selection across retail and export applications.
- Vacuum Pack:Oxygen exclusion extends chilled shelf life for premium cuts and processed meats, with modified-atmosphere variants gaining traction in European retail.
- Tray Pack:Overwrapped foam or fiber trays dominate fresh meat presentation in North American supermarkets, though sustainability pressures drive substitution toward recyclable substrates.
- Canned:Thermal sterilization in metal containers serves emergency stockpiling, military procurement, and emerging-market distribution where cold-chain infrastructure remains underdeveloped.
- Others:Emerging formats including compostable films and intelligent packaging with time-temperature indicators attract R&D investment from sustainability-focused processors.
Vacuum packaging holds the dominant position, though tray pack formats are climbing fastest through substrate innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon-border adjustment mechanisms and methane-reduction incentives are redirecting export flows toward low-emission supply chains. Brazil's integrated feedlot operations capture halal-certified beef demand from Middle Eastern buyers. USDA FSIS certification timelines shape capacity expansion decisions across North American processing corridors.
United States
Antibiotic-free procurement specifications from quick-service restaurant chains consolidate purchasing through direct contracts with integrated packers. USDA FSIS hazard-analysis compliance stretches 18-24 months for new facilities, freezing greenfield expansion. The Midwest processing belt—centered on Iowa, Nebraska, and Kansas—hosts the densest concentration of fed-cattle slaughter capacity.
Brazil
JBS and Marfrig infrastructure anchors large-scale beef and poultry export capacity serving Asian and Middle Eastern markets. ANVISA alignment with international halal certification standards unlocks preferential access to Saudi Arabian and UAE buyers. São Paulo state concentrates the nation's rendering and value-added processing capacity.
China
African swine fever recovery drives pork import dependence while domestic poultry integration accelerates. SAMR enforcement of traceability mandates compels cold-chain technology upgrades across distribution networks. Shandong Province hosts the largest concentration of poultry processing capacity serving domestic retail channels.
Germany
EFSA evaluations of processed meat consumption and EU REACH restrictions on nitrite preservatives force costly reformulation of cured products. The EU Green Deal's methane-reduction incentives reward pasture-based systems with preferential carbon accounting. Lower Saxony's dense livestock concentration faces steepest compliance burdens for emission-intensive operations.
Australia
New Zealand's pasture-based lamb systems supply premium chilled exports to high-income urban centers across Asia. DAWR biosecurity protocols and halal certification requirements shape export eligibility for Middle Eastern buyers. Victoria and New South Wales concentrate the nation's beef feedlot finishing capacity for grain-fed export segments.
Meat Products Market Competitive Landscape
On the supply side, the industry is consolidating around integrated packers with captive feedlot and rendering operations. Three strategic archetypes dominate: vertically integrated multinational protein conglomerates controlling feed-to-retail value chains; regional specialists with halal-certification advantages serving Middle Eastern export corridors; and asset-light contract processors leasing third-party cold-chain capacity. Competitive moves center on backward integration into rendering co-product valorization and multi-year procurement contracts locking in food service volume commitments.
Among North American protein conglomerates, Tyson Foods exemplifies margin capture through in-house rendering and value-added poultry capacity. JBS anchors the multinational archetype with feedlot-to-retail operations spanning multiple continents. Within the Brazilian export corridor, Marfrig occupies a position tied to halal-certified beef infrastructure serving Middle Eastern and Asian buyers.
| Leading Market Players |
|---|
| Tyson Foods |
| JBS |
| Cargill |
| National Beef Packing Company |
| Hormel Foods |
| Smithfield Foods |
| Danish Crown |
| Marfrig |
| Pilgrim's Pride |
| Others |
Supply & Pricing Matrix
The Santos-Paranaguá refrigerated corridor anchors Brazilian beef export economics, where bunker fuel and container slot premiums concentrate pricing power among JBS and Marfrig while forcing downstream buyers into contract structures that absorb cold-chain volatility through origin-verified premiums.
Pricing Analysis
Certification level—halal, USDA FSIS, or EU organic—creates the primary spread between commodity spot and contract premiums. Pricing stratifies across antibiotic-free, conventional, and economy tiers with feed-conversion efficiency as the secondary driver. Cost compression in poultry is intensifying because Brazilian integrators capture margin through captive feed milling. Quick-service restaurant chains show highest price sensitivity; premium retail channels absorb certification premiums with minimal volume elasticity.
Supply Chain Analysis
Upstream feedstock—corn and soybean meal from Iowa, Illinois, and Mato Grosso—feeds into integrated feedlot operations across Nebraska, Kansas, and São Paulo state. Raw material dependencies center on amino acid premixes, veterinary pharmaceuticals, and refrigeration equipment. Single-source vulnerability concentrates in Brazilian halal certification bodies that gate Middle Eastern market access. Distribution runs through pallet-scale institutional procurement contracts that bypass spot-market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment—USDA FSIS plant certification timelines stretching 18-24 months—erects structural barriers that protect incumbent returns from rapid competitive erosion.
For Market Incumbents: Harden feedlot-to-retail integration through captive rendering capacity that captures fat and protein recovery margins threatened by asset-light contract processors. Deepen cold-chain control through third-party logistics partnerships in Brazilian export corridors where ANVISA-halal alignment unlocks preferential Middle Eastern access. Prioritize HACCP specialist retention as qualified food safety implementers command premium wages that delay competitor plant startups. For New Entrants and Emerging Players: Establish a beachhead in cell-cultured protein segments where FDA-USDA joint oversight creates temporary regulatory clarity gaps before incumbent bioreactor scale-up. Target EU-bound cured product reformulation services where REACH nitrite restrictions force German and Dutch processors toward clean-label alternatives. Deploy direct-to-consumer platforms with intelligent packaging and last-mile cold-chain investment in metropolitan concentrations underserved by legacy refrigerated fleets. For Investors and Strategic Acquirers: FDA-USDA cell-cultured protein commercialization pathways reshape the acquisition landscape toward bioreactor manufacturing capabilities and novel protein IP portfolios. Long-term viability centers on supply chains with verified low-emission credentials that qualify for EU carbon-border adjustment preferential access. Monitor ANVISA halal certification expansion rates as the signal indicating Brazilian export corridor capacity absorption versus overbuild risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering | Tyson Foods demonstrates margin capture through in-house fat and protein recovery systems. |
| Halal Certification Infrastructure | Marfrig leverages ANVISA alignment to unlock Saudi Arabian and UAE buyer preferential access. |
| High-Pressure Processing Adoption | Retail private-label programs adopt HPP for pathogen reduction without thermal degradation. |
| Clean-Label Reformulation | German processors substitute celery powder for synthetic nitrites under EU REACH restrictions. |
| Direct Procurement Contracts | US quick-service chains consolidate purchasing through antibiotic-free specifications bypassing spot markets. |
Research Methodology
A standing panel of protein procurement directors, USDA FSIS compliance officers, feedlot operations managers, and cold-chain logistics specialists provided ongoing calibration against secondary validation from customs records, SEC 10-K protein segment disclosures, and ANVISA regulatory filings. Bottom-up volume estimates from plant-level capacity utilization triangulated against top-down trade flow analysis across Brazilian, US, and Australian export corridors.
Scenario-bracketing across feed grain price volatility bands, regulatory approval timelines for cell-cultured proteins, and carbon-border adjustment implementation intensity framed the projection horizon. Segmentation dimensions modeled include species type, processing method, distribution channel, and certification tier with CAGRs derived from elasticity-adjusted volume trajectory analysis. Industry-specific inputs incorporated broiler feed-conversion efficiency curves and halal certification throughput constraints.
Stress conditions across corn-soybean meal price spreads, USDA FSIS inspection backlog durations, and EU methane-reduction incentive calibration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Brazilian export infrastructure expansion rates and alternative protein technology cost curves. Quarterly review of ANVISA halal certification issuance volumes and FDA-USDA joint guidance publication cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Organic Chicken Market
Meat Products
North America Poultry Meat Market
Meat Products
Pork Flavors Market
Meat Products
North America Processed Meat Market
Meat Products
Pork Belly Meat Market
Meat Products
France Meat Products Market
Meat Products
Global Red Meat Market
Meat Products
United States Processed Pork Meat Market
Meat Products
Meat-Based FPP Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Saudi Arabia Goat Meat and Cheese Market
Meat Products
Chilled Meat Market
Meat Products
3D Printed Meat Market
Meat Products
Middle East Poultry Meat Market
Meat Products
North America Red Meat Market
Meat Products
Reconstituted Meat Market