
 North America Red Meat Market | 2026-2036
North America Red Meat Market Size, Share, and Industry Trends Forecast 2026-2036
North America Red Meat Market Analytics
Capital-intensity divergence between integrated packers and specialized processors is redrawing competitive boundaries in the North America red meat sector. Tyson Foods leverages captive cattle feeding operations to sustain margin control through volatile fed cattle markets. JBS S.A. anchors its North American position through large-scale beef and pork processing infrastructure across multiple US states. Cargill competes via diversified protein merchandising and grain origination synergies that buffer commodity price swings.
North America red meat encompasses muscle tissue from cattle, swine, sheep, and young bovines, processed under USDA-inspected facilities with mandatory HACCP protocols and maintained at sub-4°C for fresh distribution to preserve shelf stability and microbial safety. Beef dominates value generation across retail and foodservice channels given established consumer preference for marbled grain-fed product, while pork processing volumes lead in tonnage through integrated sow-to-shelf operations. The frozen process segment captures expanding export demand to Asian markets requiring extended shelf-life specifications, whereas fresh product retains premium positioning in domestic retail cases and quick-service restaurant supply chains.
USDA Agricultural Marketing Service grading standards and FDA Food Safety Modernization Act traceability mandates shape product differentiation and market access across US and Canadian supply chains. Canadian Food Inspection Agency regulations on antimicrobial residues and US EPA concentrated animal feeding operation permits constrain expansion timelines for large-scale feeding facilities. Stakeholders must monitor evolving labelling requirements for cell-cultured protein alternatives and carbon accounting disclosures that could redefine conventional red meat competitive positioning.
Market Dynamics
USDA Food Safety Modernization Act traceability mandates are compressing supply chain configurations across the United States and Canada, forcing packers to consolidate vendor networks and upgrade digital inventory systems ahead of compliance deadlines.
Growth Catalysts
- Texas-Oklahoma-Kansas feeding corridor concentration:Cattle finishing operations cluster in this tri-state zone, reducing transportation costs and enabling just-in-time harvest scheduling for major packers.
- FSMA Section 204 traceability rules:FDA mandates for electronic record-keeping are accelerating technology adoption across cold-chain logistics providers and retail distributors.
- Cell-cultured protein labelling frameworks:Emerging USDA-FSIS guidance on alternative protein nomenclature is clarifying competitive boundaries for conventional red meat positioning.
Market Restraints
- Fed cattle price volatility:Input cost swings for live cattle constrain margin predictability for non-integrated processors lacking captive feeding operations.
- EPA CAFO permitting delays:Concentrated animal feeding operation environmental approvals in the Iowa-Minnesota pork belt extend facility expansion timelines by 18-36 months.
- Plant-based protein substitution:Pea and soy protein isolates capture flexitarian trial in quick-service restaurant channels, pressuring ground beef volume.
Strategic Opportunities
- Canadian prairie province underpenetration:Manitoba and Saskatchewan cattle feeding infrastructure remains below optimal scale relative to US Corn Belt operations.
- Carbon accounting disclosure tailwinds:USDA Partnerships for Climate-Smart Commodities grants incentivize feedlot methane capture and regenerative grazing certification.
- Direct-to-processor digital procurement platforms:Blockchain-verified cattle sourcing apps enable rancher-packer contracting outside traditional auction channels.
Industry Challenges
- HACCP plan auditor scarcity:Qualified USDA-FSIS certification specialists command premium compensation, delaying facility approvals for mid-scale processors.
- Cold-chain capex intensity:Sub-4°C distribution infrastructure upgrades require substantial capital deployment across aging Midwest refrigerated warehouse networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Red Meat Market |
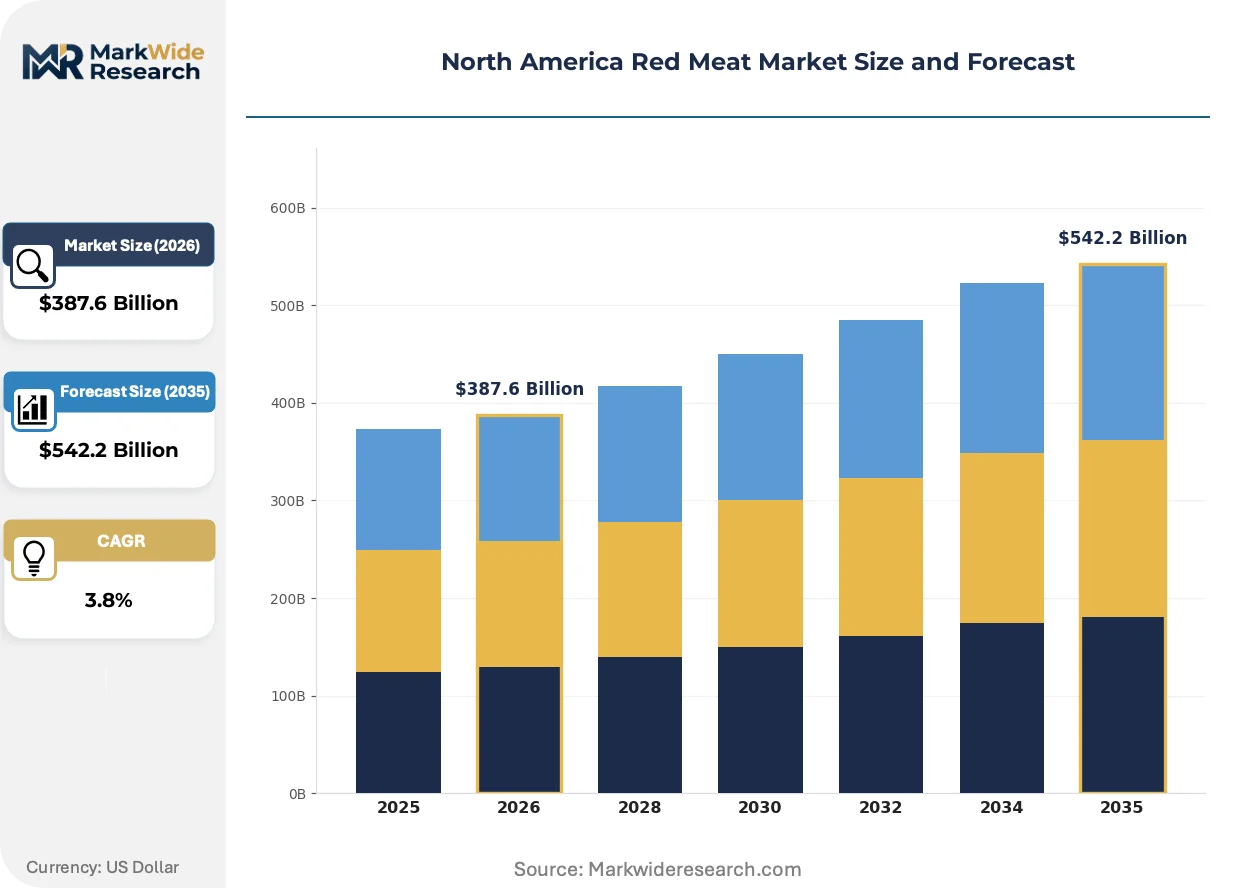
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $542.2 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Lamb, Veal Distribution Channel: Retail, Wholesale, Online, Foodservice Process Type: Fresh, Frozen, Canned, Processed Consumer Type: Direct Consumers, Restaurants, Retailers, Food Manufacturers |
| Companies Covered | Tyson Foods, Inc., JBS S.A., Hormel Foods Corporation, Maple Leaf Foods Inc., Cargill, National Beef Packing Company, Marfrig Global Foods S.A., Conagra Brands, Inc., WH Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Red Meat Market Evolving Landscape
Digital traceability infrastructure and alternative protein competitive pressure are forcing conventional red meat supply chains to differentiate through verified sourcing claims and operational transparency rather than commodity scale alone.
Blockchain-enabled cattle provenance systems are fragmenting traditional commodity beef marketing into source-verified premium tiers. Ranching cooperatives in Montana and Alberta are adopting distributed ledger platforms to document genetics, feed rations, and handling protocols. Foodservice buyers at white-tablecloth chains are contracting directly for single-origin product, bypassing conventional USDA Select-Choice-Prime grading pools.
USDA-FSIS cell-cultured protein labelling regulations are compressing competitive positioning frameworks for conventional packers. The agency's proposed standards of identity for "cell-cultured" versus "slaughtered" product terminology are forcing marketing department revisions. Beef industry trade associations are litigating to enforce stricter disclosure requirements on alternative protein packaging.
Quick-service restaurant procurement is consolidating around fewer, larger suppliers with integrated cold-chain capabilities. Chains are reducing approved vendor lists from twelve packers to four or five with national distribution reach. This concentration is most visible in the Texas-California corridor, where burger chains are signing multi-year supply agreements with packers owning captive feeding and refrigerated trucking assets.
North America Red Meat Market Segmentation
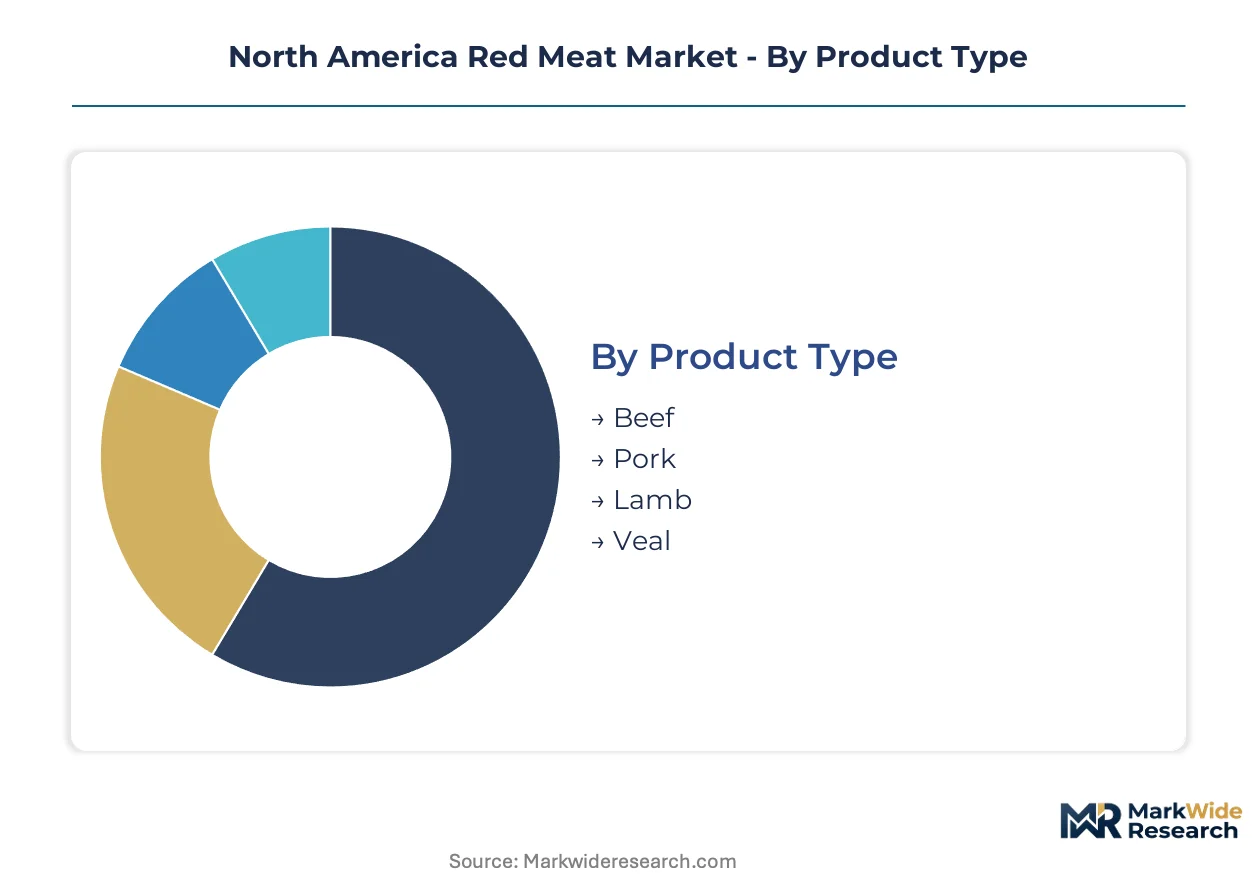
Segmentation in the North America red meat sector reveals how margin capture shifts across product grades, channel control, and processing sophistication. Understanding these divides exposes where integrated packers defend profitability and where specialized processors find openings.
Product Type:
Beef commands the widest margin spreads through USDA grading premiums, while pork dominates absolute tonnage via integrated sow-to-shelf operations.
- Beef:Grain-fed cattle finished in the Texas-Oklahoma-Kansas corridor yield marbled product graded Prime and Choice. White-tablecloth chains in Chicago and Dallas pay premiums for source-verified Angus and Wagyu lines. Fed cattle price volatility compresses margins for non-integrated processors during market swings.
- Pork:Iowa-Minnesota processing belt operations achieve cost leadership through vertical coordination from genetic selection to case-ready retail packaging. Sow herd consolidation into 5,000-head units drives efficiency gains. EPA CAFO permitting delays in the Corn Belt extend expansion timelines for new finishing barns.
- Lamb:Colorado and Texas panhandle feedlots supply ethnic retail channels and independent restaurants in metropolitan areas.
- Veal:Formula-fed dairy calf operations in Pennsylvania and Wisconsin serve specialty butcher counters and Italian-American restaurant suppliers.
The dominant share belongs to Beef, while Pork is closing the gap fastest through operational scale in the Corn Belt.
Distribution Channel:
Channel selection determines working capital intensity and price discovery mechanisms, with foodservice contracts offering volume certainty against retail's SKU proliferation costs.
- Retail:Supermarket meat cases in the United States and Canada demand case-ready packaging and sub-4°C cold-chain integrity. USDA-FSIS inspection protocols and country-of-origin labelling requirements add compliance layers. Chains are consolidating approved supplier lists from twelve packers to four with national refrigerated distribution.
- Foodservice:Quick-service burger chains in the Texas-California corridor sign multi-year agreements with packers owning captive feeding and trucking assets. White-tablecloth operators source single-origin product through direct rancher contracts outside commodity grading pools.
- Wholesale:Regional distributors in the Midwest and Southeast aggregate mixed loads for independent restaurants and institutional buyers.
- Online:Direct-to-consumer subscription boxes from Montana and Alberta ranching cooperatives leverage blockchain provenance claims for premium positioning.
Foodservice captures the steepest expansion trajectory through chain consolidation, though Retail retains the largest revenue base.
Process Type:
Processing method dictates shelf-life specifications and export market access, with frozen product opening Asian destinations that fresh distribution cannot reach.
- Fresh:Sub-4°C distribution from USDA-inspected facilities serves domestic retail cases and quick-service supply chains with seven-to-fourteen-day shelf windows. Cold-chain capex intensity pressures mid-scale processors upgrading aging Midwest refrigerated warehouse networks.
- Frozen:Blast-freezing at -18°C enables export to Japan and South Korea requiring extended transit times. Major packers in Nebraska and Kansas operate dedicated export fabrication lines with vacuum-sealed primal packaging.
- Processed:Cured and smoked products from Pennsylvania and Wisconsin plants serve deli counters and prepared food sections.
- Canned:Shelf-stable corned beef and hash products target institutional and emergency food supply channels.
Fresh holds the dominant position in value terms, while Frozen is gaining share fastest through Asian export demand.
Consumer Type:
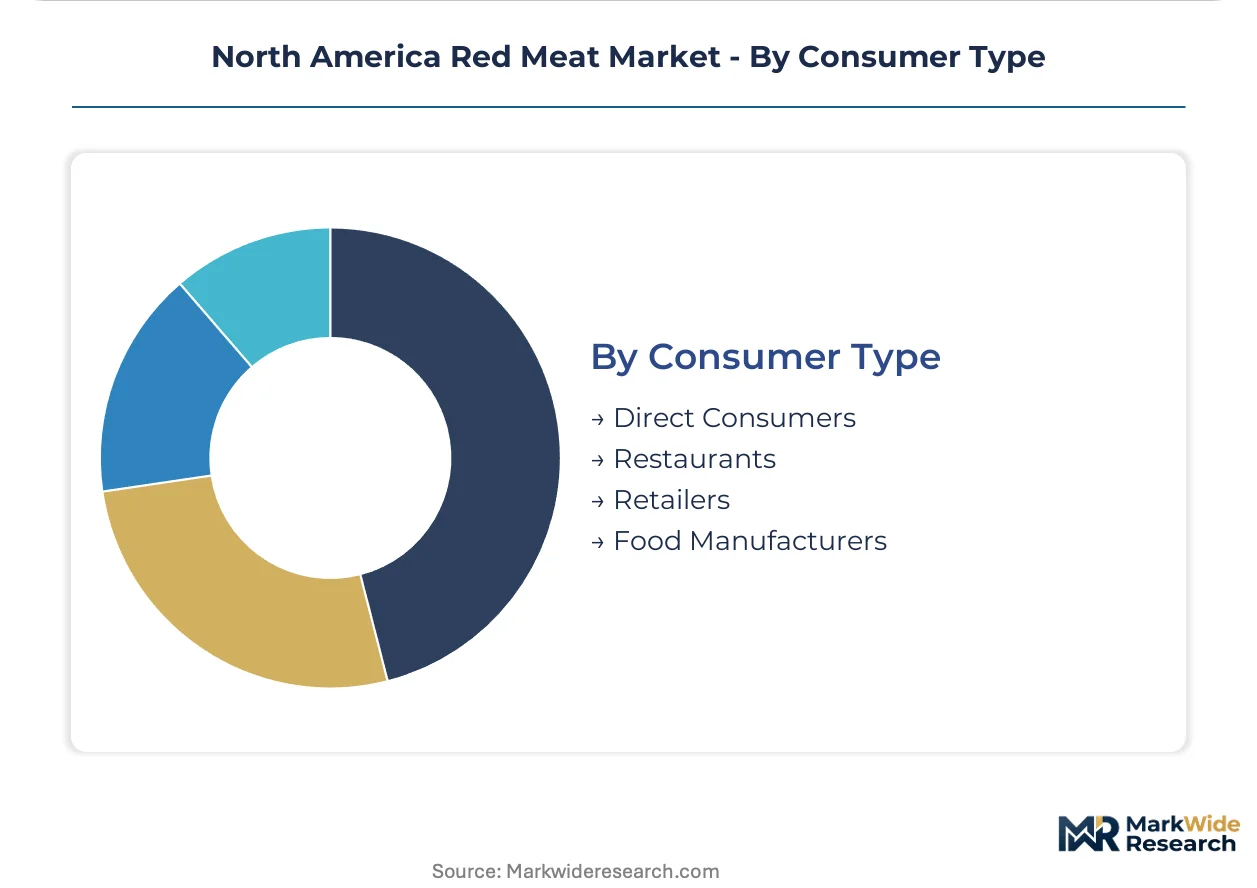
End-user concentration shapes procurement scale and specification complexity, with food manufacturers demanding consistent trim specifications that rancher-direct supply struggles to match.
- Restaurants:Burger chains and steakhouse groups contract for specified lean-to-fat ratios and portion-controlled cuts. USDA-FSIS HACCP plan requirements and third-party audit standards constrain vendor qualification to packers with documented food safety systems.
- Food Manufacturers:Prepared meal and frozen pizza producers in the Midwest purchase coarse ground beef and pork trim in truckload quantities. Specification tightness around microbiological limits excludes smaller processors lacking laboratory capabilities.
- Direct Consumers:Ranching cooperatives in Alberta and Montana sell quarter-beef and half-hog shares through subscription platforms with blockchain-verified handling documentation.
- Retailers:Supermarket meat departments source case-ready product with modified atmosphere packaging for extended color stability.
Restaurants command the largest procurement volumes, while Food Manufacturers are expanding specifications fastest through prepared meal growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Texas-Oklahoma-Kansas cattle feeding corridor, while Canadian prairie provinces trade at persistent discounts due to infrastructure gaps and regulatory lag. This asymmetry shapes cross-border investment flows and processor location decisions across North America.
United States
Quick-service restaurant chains and white-tablecloth operators drive differentiated procurement patterns, with the former demanding volume contracts and the latter seeking single-origin product. FDA Food Safety Modernization Act Section 204 mandates electronic traceability records from harvest through retail. The Iowa-Minnesota pork processing belt hosts vertically coordinated sow-to-shelf operations achieving cost leadership through genetic standardization and automated fabrication.
Canada
Manitoba and Saskatchewan cattle feeding infrastructure operates below optimal scale relative to US Corn Belt benchmarks, creating supply bottlenecks during peak harvest windows. Canadian Food Inspection Agency antimicrobial residue testing protocols exceed US baseline requirements, extending export certification timelines. Alberta ranching cooperatives deploy blockchain provenance platforms to access premium US foodservice channels outside commodity grading pools.
Mexico
Domestic consumption growth in Mexico City and Monterrey metro areas absorbs regional fed cattle supply that previously flowed northward. SADER sanitary inspection protocols align with USDA-FSIS equivalence standards to maintain export access. Northern border states concentrate feeder cattle operations supplying US packers under tariff-adjusted pricing mechanisms.
North America Red Meat Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated packers controlling margin capture through captive feeding operations while specialized processors compete on specification flexibility. The market structure consolidates around four major packers with national refrigerated distribution networks, leaving mid-scale processors dependent on regional wholesale channels. Strategic archetypes include vertically integrated protein conglomerates, diversified agricultural merchandisers, and focused beef or pork specialists. Dominant competitive moves center on backward integration into cattle feeding and cold-chain capacity expansion to secure quick-service restaurant contracts.
Among US-based protein conglomerates, Tyson Foods, Inc. and Cargill occupy positions exemplifying scale-driven supply chain control, while JBS S.A. represents the multinational archetype leveraging cross-border protein flows. These three anchors demonstrate how captive feeding operations and refrigerated distribution assets determine competitive positioning under volatile fed cattle markets.
| Leading Market Players |
|---|
| Tyson Foods, Inc. |
| JBS S.A. |
| Hormel Foods Corporation |
| Maple Leaf Foods Inc. |
| Cargill |
| National Beef Packing Company |
| Marfrig Global Foods S.A. |
| Conagra Brands, Inc. |
| WH Group Limited |
| Others |
Value Network & Pricing Analysis
Multi-year supply agreements with captive feeding operators lock in both protein access and margin visibility for quick-service restaurant chains across the Texas-California corridor. These contracts insulate buyers from fed cattle price swings while securing harvest scheduling priority at major packers.
Pricing Analysis
The customization-premium spread separates commodity USDA Select carcasses from source-verified Angus and Wagyu lines commanding significant markups at white-tablecloth chains. Pricing stratifies across premium, standard, and economy tiers driven by quality grade and geographic delivery cost. Cost compression in commodity beef is intensifying because plant-based protein isolates capture flexitarian trial in burger chains. Food manufacturers purchasing coarse ground trim in truckload quantities exhibit highest price sensitivity, while direct-to-consumer subscription buyers demonstrate lowest sensitivity due to provenance premiums.
Supply Chain Analysis
EPA CAFO permitting bottlenecks in the Iowa-Minnesota pork belt constrain expansion timelines and concentrate finishing capacity among incumbent operators with established environmental approvals. Geographic supply concentration centers on the United States, Canada, and Mexico with cross-border flows governed by tariff-adjusted mechanisms. The chain draws from live cattle, feed grain, and veterinary pharmaceutical inputs. Single-source vulnerability persists in refrigerated trucking capacity linking the Texas-Oklahoma-Kansas corridor to coastal export terminals. Distribution runs through integrated packer-owned cold-chain networks serving consolidated quick-service restaurant vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled provenance platforms are transforming this market into a platform-economics inflection where data interoperability between ranching cooperatives and foodservice buyers creates new value capture layers outside commodity exchanges.
For Market Incumbents: Secure captive feeding capacity in the Texas-Oklahoma-Kansas corridor to defend margin control against fed cattle price volatility. Invest in sub-4°C distribution infrastructure upgrades to maintain qualification on consolidated quick-service restaurant vendor lists. Plant-based protein substitution in burger chains represents the primary demand threat requiring premium positioning differentiation through verified sourcing claims. For New Entrants and Emerging Players: Direct-to-processor digital procurement platforms offer white-space opportunity where incumbent packers under-serve ranchers seeking transparent price discovery outside auction channels. Target Manitoba and Saskatchewan cattle feeding infrastructure gaps where Canadian prairie province underpenetration relative to US Corn Belt benchmarks creates supply bottlenecks. Deploy blockchain-verified cattle sourcing apps to establish rancher-packer contracting relationships as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-scale processors with USDA-FSIS certification capabilities and regional refrigerated distribution assets represent acquisition targets positioned for consolidation into national networks. Long-term viability framing favors operators with backward integration into feeding operations and climate-smart commodity certification access. Monitor EPA CAFO permitting velocity in the Iowa-Minnesota pork belt as the signal indicating expansion capacity release and competitive intensity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Capacity Expansion | Sub-4°C distribution infrastructure secures qualification on consolidated quick-service restaurant vendor lists nationwide. |
| Blockchain Provenance Integration | Distributed ledger platforms enable Montana and Alberta ranching cooperatives to bypass commodity grading pools for premium foodservice contracts. |
| Captive Feeding Operation Acquisition | Backward integration into Texas-Oklahoma-Kansas cattle finishing insulates packers from fed cattle price volatility. |
| Climate-Smart Certification Program | USDA Partnerships for Climate-Smart Commodities grants incentivize feedlot methane capture and regenerative grazing credentials. |
| Direct-to-Consumer Platform Launch | Subscription boxes from Alberta and Montana cooperatives leverage blockchain handling documentation for premium positioning. |
Research Methodology
Cross-validation between USDA Agricultural Marketing Service data and FDA Food Safety Modernization Act compliance records anchors the qualitative findings on traceability infrastructure investment. Primary interviews with cattle feeding operators, packer procurement executives, foodservice supply chain directors, and cold-chain logistics providers combine with secondary validation from USDA-FSIS inspection reports, EPA CAFO permitting databases, Canadian Food Inspection Agency antimicrobial residue protocols, and customs trade flow records. Bottom-up ranch-level production estimates and top-down channel consumption analysis enable triangulation across the North American protein complex.
Sensitivity analysis around fed cattle price volatility assumptions and EPA permitting timeline scenarios tests forecast robustness across the projection horizon. The analytical framework models segmentation dimensions including product type, process type, distribution channel, and consumer archetype alongside regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation adjusted for structural shifts in quick-service restaurant procurement consolidation and alternative protein competitive pressure. Industry-specific forecast inputs incorporate sow herd consolidation rates in the Iowa-Minnesota belt and blockchain platform adoption curves in Montana and Alberta cooperatives.
Forecasts assume regulatory continuity in USDA-FSIS inspection protocols and FDA Section 204 traceability mandates; material policy shifts on cell-cultured protein labelling or carbon accounting disclosure would require re-modeling. Specific risk factors that could revise projections include accelerated plant-based protein substitution in quick-service channels and extended EPA CAFO permitting delays constraining pork processing expansion. Practitioners should keep alternative scenarios live as FSMA compliance deadlines and climate-smart commodity grant allocations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Pork Flavors Market
Meat Products
Global Beef Market
Meat Products
India Edible Meat Market
Meat Products
Pork Belly Meat Market
Meat Products
Bacon Market
Meat Products
Western Europe Ready-To-Eat Meat Market
Meat Products
Reduced Fat Meat Market
Meat Products
Global Red Meat Market
Meat Products
Beef Fat Powder Market
Meat Products
Europe Poultry Meat Market
Meat Products
Hot Dog and Sausages Market
Meat Products
Pork Meat Market
Meat Products
Non-Veg Rte and Rtc Market
Meat Products
Organic Pork Market
Meat Products
Global Poultry Meat Market
Meat Products
United States Processed Pork Meat Market