
 Mouth Freshener Market | 2026-2036
Mouth Freshener Market Size, Share, and Industry Trends Forecast 2026-2036
Mouth Freshener Market Intelligence
Flavor chemist shortages across South Asia are redrawing where formulation R&D clusters locate. Perfetti Van Melle Group B.V. leverages its Dutch flavor-science heritage to sustain premium positioning in European mint segments. Dabur India Ltd. anchors Ayurvedic herbal lines through deep Ayurveda practitioner networks. Mars, Inc. competes on manufacturing scale across chewing gum facilities in multiple continents.
A mouth freshener denotes any orally administered product designed to mask or neutralize malodor through antimicrobial action, volatile flavor release, or mechanical cleansing, typically incorporating menthol, essential oils, xylitol, or zinc salts in pH-balanced matrices. These products serve commercial purposes spanning personal hygiene maintenance, social confidence enhancement, and adjunctive oral care between brushing. Chewing gums retain the largest revenue pool due to habitual purchase frequency and impulse-placement economics, while breath sprays represent the fastest-expanding format as urban commuters prioritize pocket-sized discretion. Herbal-flavored variants command widening shelf space as health-conscious consumers reject synthetic additives.
The US FDA oversees oral care product labeling and antimicrobial claim substantiation, while India's FSSAI enforces ingredient disclosure and sugar-content thresholds that directly shape permissible formulations. The EU's EFSA evaluates health claims for xylitol and probiotic breath-freshening ingredients, creating divergent approval pathways across Atlantic markets. Stakeholders must monitor evolving natural-claim standards and distribution-channel consolidation to align portfolio priorities with shifting regulatory and retail landscapes.
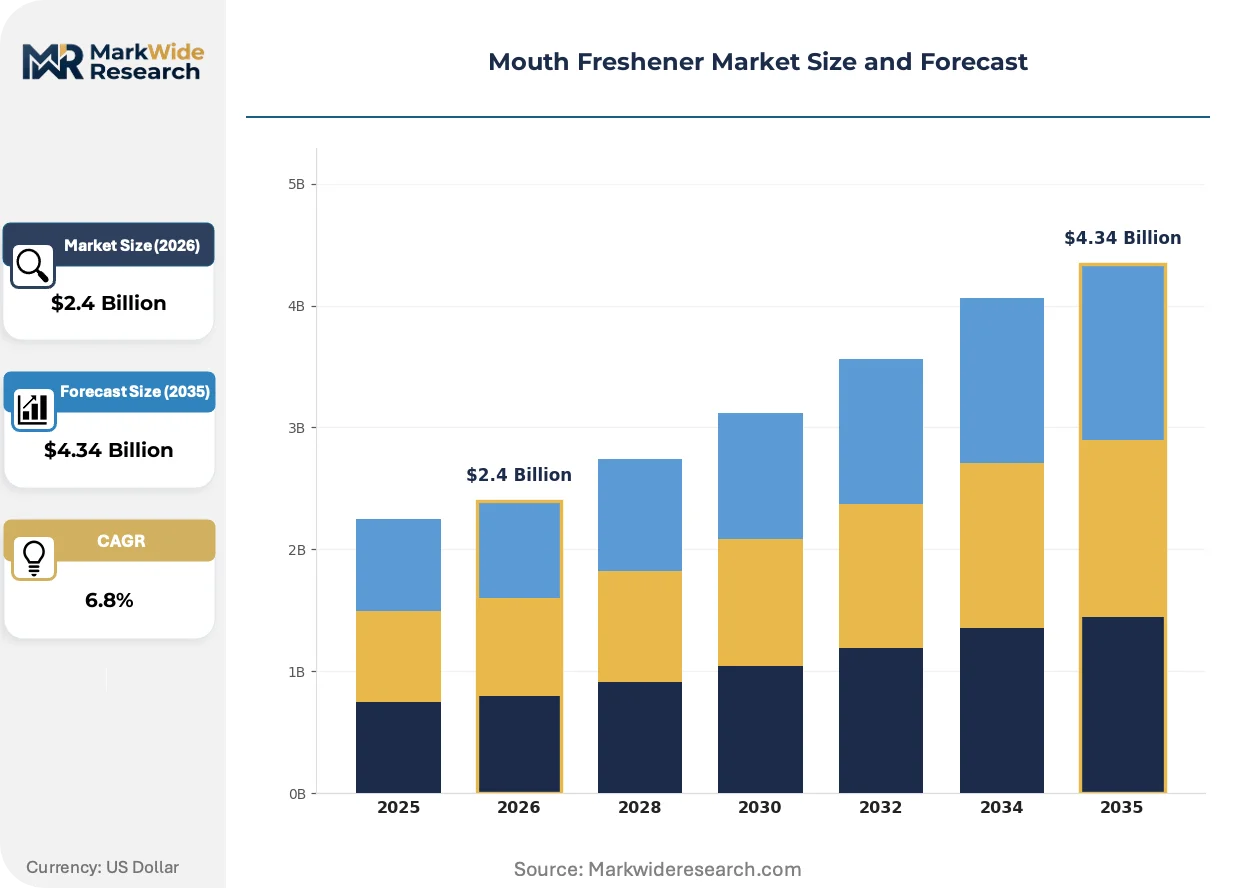
Market Dynamics
Portable format preferences are compressing chewing gum shelf space while expanding spray and dissolvable strip placements in Southeast Asian convenience chains. India's FSSAI sugar-free labeling tightening is forcing wholesale reformulation across oral care portfolios.
Growth Catalysts
- Urban Commuter Behavior:Young professionals in Indonesia's Jakarta-Bandung corridor prioritize pocket-sized discretion over traditional gum formats, accelerating spray and mint strip adoption in transit retail.
- FSSAI Reformulation Mandate:India's tightened sugar-free claim requirements push manufacturers toward xylitol, stevia, and monk fruit natural sweetener systems in pH-balanced matrices.
- Essential Oil Extraction Advances:Cold-press and CO2 extraction methods for menthol and herbal actives are improving volatile compound retention in Ayurvedic-flavored product lines.
Market Restraints
- Menthol Input Volatility:Synthetic menthol production concentrates in Chinese and Indian chemical corridors, exposing margins to feedstock price swings and environmental compliance costs.
- Flavor Chemist Scarcity:South Asia's shortage of trained flavor scientists restricts in-house formulation capabilities, forcing reliance on European and North American R&D outsourcing.
- Antimicrobial Claim Friction:The US FDA's substantiation requirements for zinc salt and essential oil efficacy claims create multi-year validation timelines that delay product launches.
Strategic Opportunities
- Probiotic Breath-Freshening:EFSA evaluation pathways for oral microbiome claims create first-mover advantage for strains with documented Streptococcus salivarius colonization data.
- Vietnam Convenience Expansion:Underpenetrated urban retail in Ho Chi Minh City and Hanoi offers format innovation space before competitor shelf saturation.
- Dual-Function Positioning:Zinc salt matrices with documented volatile sulfur compound neutralization are converging with cosmetic whitening claims in premium tier development.
Industry Challenges
- Cross-Border Formulation Harmonization:Divergent EFSA, FDA, and FSSAI approval timelines for novel sweeteners and probiotic strains force parallel development tracks that strain R&D budgets.
- Cold Chain Integrity for Probiotic Formats:Viable culture maintenance through Southeast Asian ambient distribution networks requires packaging innovation and last-mile temperature monitoring investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mouth Freshener Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mints, Breath Sprays, Chewing Gums, Mouthwashes Flavor: Mint, Cinnamon, Fruit, Herbal Distribution Channel: Online, Supermarkets, Convenience Stores, Pharmacies Target Audience: Teens, Adults, Seniors, Health-Conscious Consumers |
| Companies Covered | Johnson & Johnson Services, Inc., DS Group, Perfetti Van Melle Group B.V., The Hershey Company, Ferrero International S.A., Mars, Inc., Dabur India Ltd., Colgate-Palmolive Co., Mondelez International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mouth Freshener Market Strategic Shifts & Innovations
Active ingredient delivery systems are fragmenting as manufacturers compete on onset speed, duration, and sensory experience. Regulatory divergence between Atlantic and Asia-Pacific markets is forcing parallel certification strategies.
Water-soluble film strips containing encapsulated essential oils are supplanting traditional lozenges in premium urban segments. Transit retailers in Singapore and Bangkok are expanding facings for these formats. The technology is compressing manufacturing asset utilization for legacy hard-candy production lines.
The EU's EFSA health claim evaluation framework for xylitol caries-reduction benefits is reshaping permissible marketing language across European mint and gum portfolios. Manufacturers must reformulate or retract dental benefit claims pending positive opinions. Breath spray segments in Germany and France face the tightest claim substantiation requirements.
Subscription and auto-replenishment models through e-commerce platforms are capturing habitual purchasers who previously bought through impulse retail. Direct-to-consumer channels in India's tier-1 cities are displacing traditional kirana store loyalty. This pattern concentrates in Mumbai and Delhi NCR where delivery infrastructure supports same-day replenishment cycles.
Mouth Freshener Market Segmentation
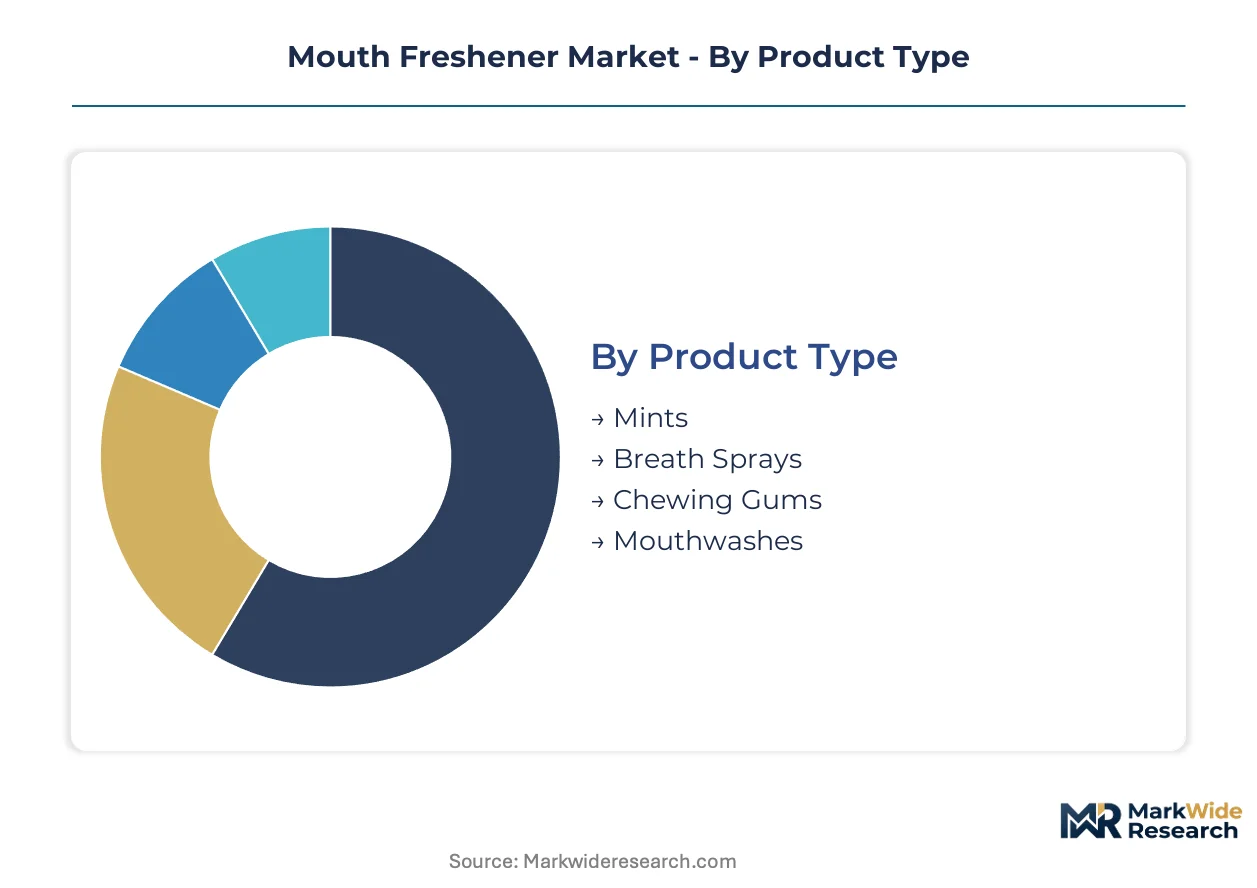
Format fragmentation across the mouth freshener category demands granular portfolio mapping. Regulatory claim substantiation varies sharply by product matrix, while distribution economics favor distinct channel strategies for impulse versus planned purchase occasions.
Product Type:
FSSAI sugar-free labeling mandates and FDA antimicrobial claim requirements create divergent compliance burdens across physical formats.
- Chewing Gums:Polyol-based matrices with sustained-release flavor encapsulation dominate habitual purchase occasions. Indonesia's Jakarta-Bandung corridor and India's tier-1 cities concentrate volume through transit retail placement, though shelf space compression is accelerating as convenience chains prioritize smaller formats.
- Breath Sprays:Alcohol-free aqueous solutions with rapid-onset volatile compounds address pocket-sized discretion priorities. Urban commuters in Singapore and Bangkok are displacing gum habits with spray adoption in premium transit retail, where facings are expanding fastest.
- Mints:Compressed tablet and lozenge formats with hard-candy processing economics serve impulse checkout placement.
- Mouthwashes:Larger-volume aqueous formulations with cetylpyridinium chloride or essential oil actives target adjunctive oral care positioning.
Established volume favors chewing gums; emerging adoption favors breath sprays.
Flavor:
Extraction technology maturity and natural-claim substantiation costs stratify margin profiles across taste profiles.
- Mint:Menthol and peppermint oil formulations leverage the most advanced cold-press and CO2 extraction infrastructure. Synthetic menthol concentration in Chinese and Indian chemical corridors exposes pricing to feedstock volatility, while natural mint sourcing from India's Uttar Pradesh and Madhya Pradesh commands premium positioning.
- Herbal:Ayurvedic ingredient systems with documented antimicrobial properties are gaining shelf space as FSSAI disclosure requirements push rejection of synthetic additives. Dabur India's practitioner network anchoring demonstrates distribution advantages for traditional medicine positioning.
- Fruit:Encapsulated ester and aldehyde flavor systems target younger demographics with sweetness-forward profiles.
- Cinnamon:Cinnamaldehyde-based formulations with warming sensory cues serve niche premium positioning.
Cost concentration sits with mint; health-claim differentiation favors herbal.
Distribution Channel:
Last-mile infrastructure investment and auto-replenishment algorithm deployment are redrawing channel economics.
- Convenience Stores:Transit-adjacent facings in Southeast Asian urban corridors prioritize portable formats with high impulse conversion. Vietnam's Ho Chi Minh City and Hanoi expansion offers underpenetrated placement opportunity before competitor saturation.
- Online:Subscription models through e-commerce platforms capture habitual purchasers in India's Mumbai and Delhi NCR, where same-day delivery infrastructure displaces traditional kirana loyalty.
- Supermarkets:Mass-market volume concentration with promotional calendar dependency.
- Pharmacies:Clinical positioning with probiotic and zinc salt formulations requiring EFSA or FDA claim substantiation.
Physical infrastructure favors convenience stores; data-capture economics favor online.
Target Audience:
Social confidence use cases and oral health literacy levels shape format and claim priorities.
- Adults:Working-age professionals across Indonesia's urban corridor and India's metropolitan zones drive spray and strip format innovation. Discretion priorities in workplace and transit contexts compress traditional gum purchase frequency.
- Health-Conscious Consumers:Sugar-free and natural-claim rejection of synthetic additives concentrates in India's tier-1 cities with highest FSSAI awareness. Xylitol and stevia reformulation investments target this segment's willingness to pay premium pricing.
- Teens:Flavor-forward and packaging-driven purchase with social sharing dynamics.
- Seniors:Dry-mouth symptom relief and denture-compatible formats with softer texture requirements.
Habitual volume anchors adults; margin expansion targets health-conscious consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's urban corridor consumes mouth fresheners through spray and strip formats at rates diverging sharply from India's gum-dominant habits, while European markets prioritize claim-substantiated functional positioning over impulse convenience.
United States
Transit retail and workplace discretion priorities drive spray format adoption in New York and Chicago metro areas. The FDA's antimicrobial claim substantiation requirements for zinc salt and essential oil formulations create multi-year validation timelines that delay product launches. Manufacturing scale concentrates around Mars, Inc.'s chewing gum facilities across multiple states.
Germany
Health-conscious consumers in Berlin and Munich reject synthetic additives, expanding shelf space for herbal-flavored variants. EFSA's health claim evaluation framework for xylitol caries-reduction benefits reshapes permissible marketing language across mint and gum portfolios. Breath spray segments face the tightest claim substantiation requirements in Frankfurt's pharmacy-dominant distribution.
India
FSSAI's tightened sugar-free labeling requirements push manufacturers toward xylitol, stevia, and monk fruit natural sweetener systems in pH-balanced matrices. Dabur India Ltd. anchors Ayurvedic herbal lines through deep practitioner networks in Maharashtra and Gujarat. Mumbai and Delhi NCR subscription models through e-commerce platforms displace traditional kirana store loyalty.
Indonesia
Young professionals in the Jakarta-Bandung corridor prioritize pocket-sized discretion over traditional gum formats, accelerating spray and mint strip adoption in transit retail. Convenience store chains expand shelf space for portable breath-freshening formats across urban corridors. Local flavor preferences drive demand for fruit and herbal variants beyond standard mint positioning.
Vietnam
Underpenetrated urban retail in Ho Chi Minh City and Hanoi offers format innovation space before competitor shelf saturation. Young adult demographics in emerging middle-class districts show rising awareness of oral hygiene maintenance as social confidence enhancement. Transit-adjacent convenience placement remains limited compared to Singapore and Bangkok benchmarks.
Mouth Freshener Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the mouth freshener market. Multinational confectionery conglomerates leverage manufacturing scale across chewing gum facilities on multiple continents, while Ayurvedic heritage specialists anchor traditional medicine positioning through practitioner networks. Three archetypes dominate: scale-driven confectionery multinationals, heritage-rooted herbal specialists, and oral care incumbents extending into breath-freshening adjacencies. Competitive moves concentrate on portfolio diversification into natural-claim formats and geographic expansion through Southeast Asian convenience retail partnerships.
Among heritage-rooted specialists, Dabur India Ltd. exemplifies the Ayurvedic practitioner-network archetype, while Perfetti Van Melle Group B.V. occupies a position reflecting Dutch flavor-science heritage in European mint segments. Mars, Inc. sits within the scale-driven multinational tier, representing manufacturing footprint advantages across multiple continents.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| DS Group |
| Perfetti Van Melle Group B.V. |
| The Hershey Company |
| Ferrero International S.A. |
| Mars, Inc. |
| Dabur India Ltd. |
| Colgate-Palmolive Co. |
| Mondelez International, Inc. |
| Others |
Cost & Logistics Intelligence
Natural sweetener substitution for synthetic polyols is redrawing procurement geography toward Indian stevia and monk fruit suppliers while compressing margin structures for legacy formulation tiers. This input transition simultaneously elevates working capital requirements for cold-chain probiotic cultures and fragments pricing power across regional regulatory clusters.
Pricing Analysis
Long-term offtake contracts for menthol and essential oil feedstocks dominate procurement in the chewing gum segment, while spot-market purchasing prevails for herbal extract inputs with volatile harvest cycles. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-substantiated probiotic formulations from conventional mint portfolios and unbranded private-label strips. Cost compression in economy tiers is intensifying because of FSSAI-mandated reformulation expenses and flavor chemist outsourcing premiums. Health-conscious consumers in India's tier-1 cities exhibit lowest price sensitivity for Ayurvedic-positioned products, while transit retail gum purchasers in Southeast Asian convenience chains remain most responsive to promotional discounting.
Supply Chain Analysis
Strategic stockpiling of synthetic menthol concentrates in Chinese and Indian chemical corridors offsets harvest volatility for natural peppermint sourcing from Uttar Pradesh and Madhya Pradesh. Formulation R&D draws from Dutch flavor-science heritage clusters, while finished goods manufacturing rests on Mars, Inc.'s multi-continent chewing gum facilities and Dabur India's Ayurvedic processing plants. Single-source vulnerability concentrates in South Asian flavor chemist talent pools, forcing European and North American R&D outsourcing. Distribution runs through Southeast Asian convenience store chains expanding shelf space for portable formats, with direct-to-consumer channels displacing traditional kirana loyalty in Mumbai and Delhi NCR.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Auto-replenishment algorithm deployment across India's e-commerce platforms signals a platform-economics inflection where subscription models capture habitual purchasers previously anchored to impulse retail. Interoperability between last-mile delivery infrastructure and oral care brand apps is reshaping customer lifetime value calculations.
For Market Incumbents: Consolidate manufacturing scale advantages through backward integration into natural sweetener supply chains in India and Indonesia, securing pH-balanced matrix production against FSSAI reformulation volatility. Deepen practitioner network control in Maharashtra and Gujarat to defend Ayurvedic heritage positioning against emerging herbal entrants. Channel control through exclusive transit retail partnerships in Jakarta-Bandung corridor represents the critical defensive lever against spray format commoditization. For New Entrants and Emerging Players: Subscription service-layer gaps in Vietnam's Ho Chi Minh City and Hanoi convenience infrastructure offer white-space entry before competitor shelf saturation. Underpenetrated probiotic breath-freshening segments with EFSA evaluation pathways represent the most penetrable application, given multi-year validation timelines that delay incumbent launches. Direct-to-consumer sampling campaigns through fitness and wellness platforms provide the specific go-to-market angle to bypass established retail gatekeepers. For Investors and Strategic Acquirers: FSSAI's tightened sugar-free labeling requirements reshape the acquisition landscape toward targets with demonstrated natural sweetener formulation capabilities and existing pH-balanced matrix portfolios. Long-term viability over the five-to-ten year horizon favors heritage-rooted specialists with captive Ayurvedic practitioner networks over pure-play confectionery scale operators. The acquisition target archetype combines regional brand equity in Southeast Asia with cold-chain packaging innovation for probiotic culture viability. Monitor EFSA positive opinion timelines for oral microbiome claims as the signal to watch for category premiumization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Sweetener Reformulation | FSSAI compliance in India mandates xylitol, stevia, and monk fruit substitution for legacy polyol systems. |
| Probiotic Format Cold-Chain Investment | Ambient distribution networks in Southeast Asia require packaging innovation for viable culture maintenance. |
| Ayurvedic Practitioner Network Expansion | Dabur India's Maharashtra and Gujarat anchoring demonstrates distribution advantages for traditional medicine positioning. |
| Transit Retail Format Innovation | Jakarta-Bandung corridor young professionals prioritize pocket-sized spray and strip discretion over gum habits. |
| Direct-to-Consumer Subscription Launch | Mumbai and Delhi NCR same-day delivery infrastructure displaces kirana store loyalty through auto-replenishment algorithms. |
Research Approach
Initial hypotheses were tested against primary input from flavor chemists, category buyers at Southeast Asian convenience chains, Ayurvedic practitioner network coordinators, and oral care regulatory affairs specialists, then refined through secondary validation against FSSAI disclosure filings, EFSA health claim evaluation registers, Nielsen retail audit data for transit-adjacent facings, and customs records for menthol and essential oil trade flows. Bottom-up demand modeling across format, flavor, and channel segments was triangulated with top-down market sizing from manufacturer capacity disclosures.
Variance decomposition across the projection horizon isolates volume drivers by urban commuter behavior shifts, regulatory reformulation mandates, and cold-chain infrastructure penetration. Segmentation dimensions modeled include physical format, flavor extraction technology tier, distribution channel type, and target audience oral health literacy level. CAGRs were derived from cohort analysis of adoption curves for spray and strip formats against chewing gum habit persistence. Industry-specific forecast inputs incorporate flavor chemist pipeline graduation rates and EFSA evaluation queue timelines for novel probiotic strains.
Forecasts assume regulatory continuity in FSSAI, FDA, and EFSA regimes; material policy shifts would require re-modeling of claim substantiation timelines and permissible formulation matrices. Specific risks that could revise projections include menthol feedstock price volatility from environmental compliance costs in Chinese chemical corridors, and cold-chain integrity failures in Southeast Asian ambient distribution networks. Revision becomes warranted when EFSA positive opinion issuance for oral microbiome claims crosses thresholds that trigger competitor portfolio repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
Orange Peel Extract Market
Flavorings and Food Additives
Winter Melon Peel Extract Market
Flavorings and Food Additives
Lemon Essential Oil Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Nature Identical Flavorings Market
Flavorings and Food Additives
Poria Cocos Extract Market
Flavorings and Food Additives
Global Chicory Market
Flavorings and Food Additives
Salts and Flavored Salts Market
Flavorings and Food Additives
Valencene Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market
Flavorings and Food Additives
Neotame Market
Flavorings and Food Additives
Ginkgo Biloba Extract Market
Flavorings and Food Additives
Europe Food Flavor Market
Flavorings and Food Additives
All-Natural Flavors System Market
Flavorings and Food Additives
Global Sterols Market