
 Vanilla Bean Market | 2026-2036
Vanilla Bean Market Size, Share, and Industry Trends Forecast 2026-2036
Vanilla Bean Market Outlook
Traceability technology is narrowing the gap between plantation origin and finished goods labeling. Givaudan SA leverages blockchain-verified sourcing platforms to secure premium Madagascar lots. McCormick & Company, Inc. anchors North American retail distribution through direct farmer partnerships in Papua New Guinea. Symrise AG specializes in controlled fermentation protocols that standardize vanillin concentration across harvest seasons.
Vanilla beans comprise the cured seed pods of orchid species Vanilla planifolia and V. tahitensis, containing 1.0–2.5% vanillin by dry weight alongside glucovanillin, resin, and volatile oil fractions; curing involves killing, sweating, drying, and conditioning stages over four to six months to develop aromatic complexity for flavor extraction. The extract segment dominates value capture due to concentration efficiency and extended shelf stability in industrial formulations. Powder applications compete on dispersion uniformity in dry bakery mixes and instant beverage bases. Food & Beverage applications sustain the largest volume pull, while Cosmetics and Fragrances segments concentrate margin in supercritical CO2-extracted absolute grades.
The FDA enforces identity standards for vanilla extract under 21 CFR 169.175, distinguishing pure extracts from vanillin-enhanced or artificial alternatives. The EU Deforestation Regulation and EUDR due diligence framework reshape import compliance for tropical origin commodities. Organic certification under USDA National Organic Program and EU Organic Regulation gates premium channel access. Stakeholders must monitor geospatial traceability mandates and fermentation-derived vanillin cost curves to calibrate sourcing strategies against shifting authenticity premiums.
Market Dynamics
The EU Deforestation Regulation is forcing a structural reconfiguration of vanilla bean procurement, compelling importers to deploy geospatial traceability systems and sever ties with non-compliant curing cooperatives.
Growth Catalysts
- Artisanal bakery premiumization:European and North American craft bakeries now specify origin-labeled vanilla extract in formulations, creating price premiums for traceable Madagascar and Ugandan lots.
- FDA identity standards enforcement:The agency's 21 CFR 169.175 compliance actions against vanillin-adulterated products are redirecting industrial buyers toward certified pure extract suppliers.
- Blockchain verification platforms:Distributed ledger systems now authenticate curing-stage provenance, reducing fraud incidence in high-value Tahitian vanilla transactions.
Market Restraints
- Madagascar supply concentration:Over seventy percent of Bourbon vanilla originates from the Sava region, exposing buyers to cyclone-related crop failure and port congestion.
- Fermentation-derived vanillin cost curves:Synthetic biology production from ferulic acid and glucose substrates is compressing price floors for natural extract alternatives.
- EUDR due diligence burden:The regulation's geospatial plotting requirements and supplier audit obligations are extending lead times by four to eight weeks for EU-bound shipments.
Strategic Opportunities
- Papua New Guinea expansion:The country's underdeveloped curing infrastructure offers first-mover advantages for vertically integrated processors establishing direct farmer networks.
- Supercritical CO2 extraction for cosmetics:Absolute-grade vanilla oil commands three to five times food-grade pricing in fragrance and skincare formulations.
- Organic certification arbitrage:USDA National Organic Program and EU Organic Regulation dual certification opens premium channel access in both North American and European retail.
Industry Challenges
- Skilled curer scarcity:Traditional sweating and sun-drying expertise is contracting as younger labor migrates to urban centers, threatening aromatic quality consistency.
- EUDR compliance system integration:Legacy ERP platforms lack polygon mapping capabilities, forcing expensive middleware deployments or full system replacements.
- Climate adaptation capex:Shade house construction and irrigation infrastructure require upfront investment that smallholder cooperatives cannot self-finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vanilla Bean Market |
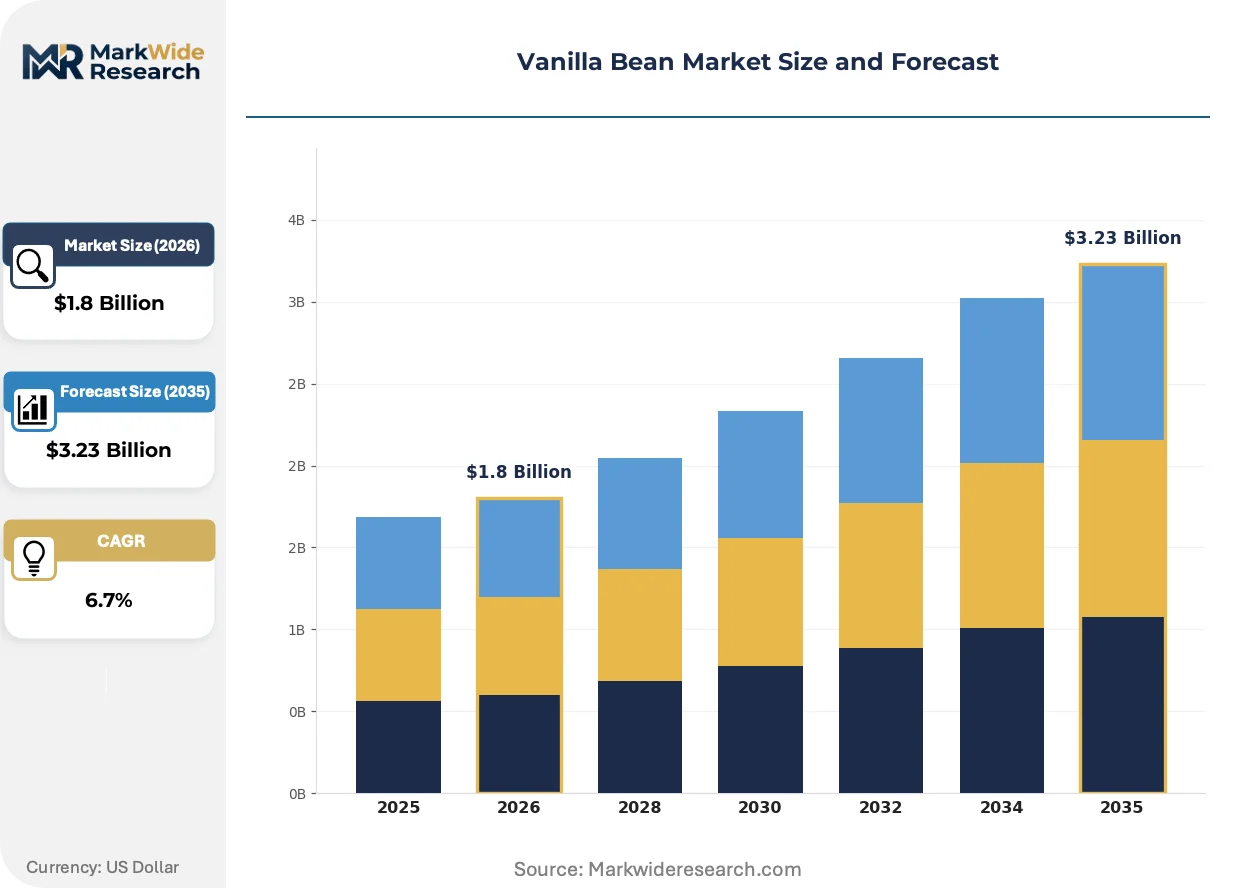
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Beans, Powder, Extract, Paste Application: Food & Beverage, Cosmetics, Pharmaceuticals, Fragrances End User: Retail, Food Service, Home Cooking, Industrial Distribution Channel: Online, Specialty Stores, Supermarkets, Distributors |
| Companies Covered | Symrise AG, Givaudan SA, Firmenich SA, McCormick & Company, Inc., Nielsen-Massey Vanillas, Inc., Sensient Technologies Corporation, International Flavors & Fragrances, Synthite Industries Ltd, Takasago International Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vanilla Bean Market Strategic Shifts
Digital traceability infrastructure and biotechnological alternatives are bifurcating the vanilla value chain into authenticated premium segments and cost-optimized functional substitutes.
Near-infrared spectroscopy coupled with blockchain timestamping is rendering obsolete paper-based chain-of-custody documentation. Multinational flavor houses now require spectroscopic vanillin fingerprinting for every lot, compressing authentication cycles from weeks to hours. This convergence is eliminating arbitrage opportunities for fraudulent origin claims in spot markets.
The EU Deforestation Regulation's geospatial mandate is restructuring import compliance workflows. Operators must now submit polygon coordinates for every production plot, triggering software procurement cycles across European importers. Small and mid-size trading houses are responding by consolidating volumes through larger compliant intermediaries rather than building in-house capabilities.
Buyer consolidation among North American ice cream manufacturers is compressing supplier rosters and extending contract durations. Three major processors now account for the majority of industrial extract offtake, shifting negotiation leverage toward volume-commitment frameworks. This concentration is most visible in Wisconsin and Vermont production clusters, where procurement teams now demand multi-year fixed-price agreements with inflation collars.
Vanilla Bean Market Segmentation
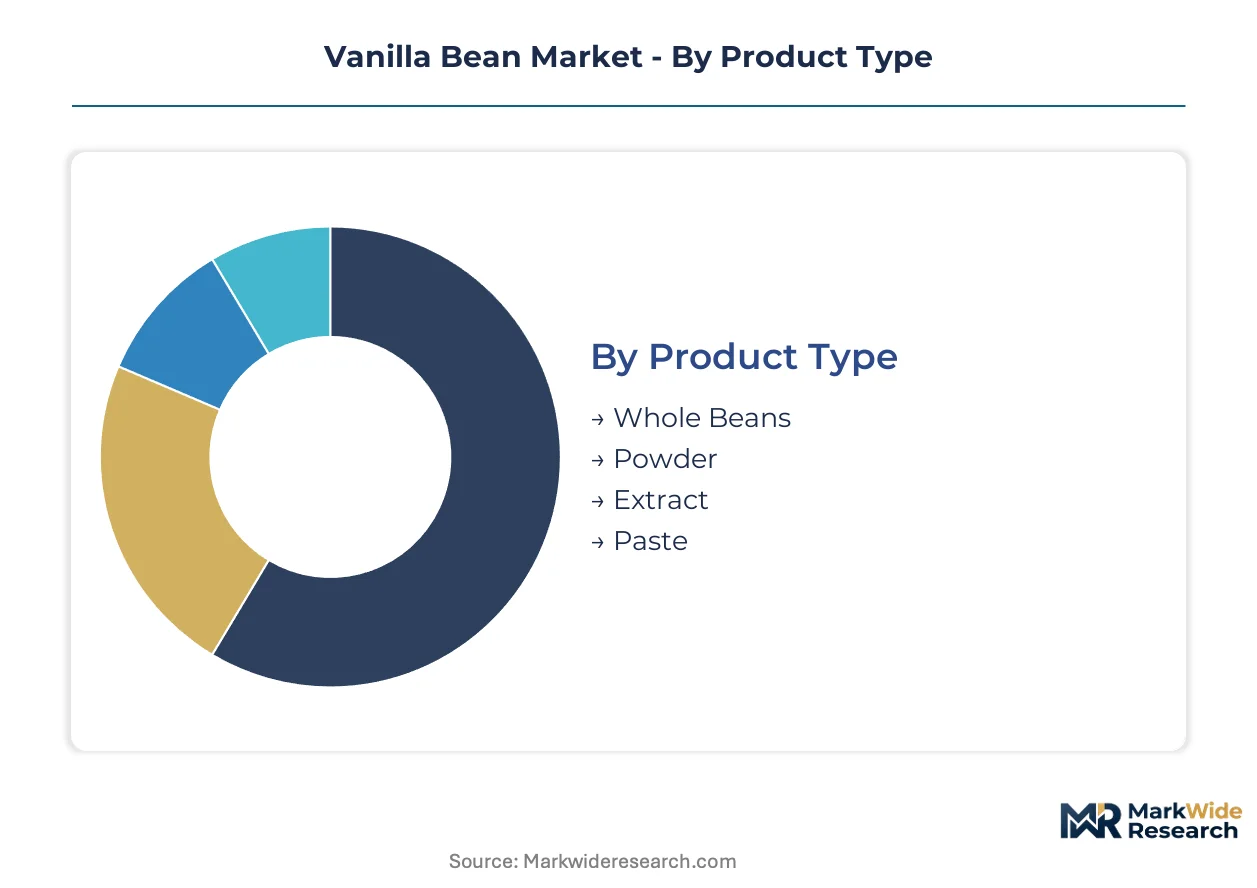
Vanilla bean procurement strategies diverge sharply across product formats and customer tiers. Industrial buyers prioritize concentration efficiency and batch consistency, while artisanal channels reward origin transparency and aromatic complexity.
Product Type:
Cost tier differentiation separates commodity-grade inputs from value-added preparations requiring curing expertise and extraction infrastructure.
- Whole Beans:Cured seed pods of Vanilla planifolia and V. tahitensis retain 1.0–2.5% vanillin by dry weight. Madagascar Bourbon lots command premium positioning in European artisanal bakery channels where origin labeling supports price realization.
- Extract:Alcohol-based solutions concentrate aromatic compounds for industrial scale deployment. North American ice cream manufacturers anchor volume offtake through multi-year fixed-price agreements with inflation collars.
- Powder:Spray-dried formulations deliver dispersion uniformity in dry bakery mixes and instant beverage bases. Convenience-driven home cooking segments in Germany and France absorb mid-tier volumes.
- Paste:Concentrated suspensions with visible seed specks signal authenticity in premium patisserie applications. Specialty stores in Tokyo and Paris stock super-premium Tahitian variants for chef clientele.
Extract commands the established base. The steepest expansion runs through paste formats in high-end food service.
Application:
End-use margin profiles range from volume-driven commodity formulations to supercritical CO2-extracted absolute grades capturing cosmetics premiums.
- Food & Beverage:Ice cream, baked goods, and beverage formulations absorb the majority of industrial extract volumes. FDA 21 CFR 169.175 identity standards enforcement redirects adulterated product buyers toward certified pure suppliers.
- Cosmetics:Supercritical CO2 extraction yields absolute-grade vanilla oil for fragrance and skincare. Three to five times food-grade pricing justifies dedicated processing lines in Swiss and French facilities.
- Fragrances:Volatile oil fractions supply fine perfume compounding houses. Grasse-based laboratories specify vanillin fingerprinting for every lot to compress authentication cycles.
- Pharmaceuticals:Standardized vanillin concentrations serve as excipients and masking agents. Regulatory filings with EMA and FDA require documented supply chain provenance.
Food & Beverage anchors volume throughput. Cosmetics and Fragrances concentrate margin capture.
End User:
Customer type stratification reflects procurement sophistication, contract scale, and specification stringency across channel tiers.
- Industrial:Flavor houses and processed food manufacturers purchase in container quantities. Wisconsin and Vermont production clusters now demand geospatial traceability documentation under EU Deforestation Regulation compliance frameworks.
- Food Service:Restaurant groups and catering operations specify origin-labeled extracts for menu differentiation. Paris and London chef-driven procurement teams audit curing cooperatives directly.
- Retail:Supermarket and specialty store channels stock branded extracts and whole beans. German and Austrian organic certification arbitrage opens premium shelf positioning.
- Home Cooking:Small-format retail packs serve enthusiast bakers. Online channels in the United States and United Kingdom aggregate long-tail demand for rare Tahitian and Ugandan varietals.
Industrial buyers lock in contract coverage. Home cooking channels expand most quickly through direct-to-consumer platforms.
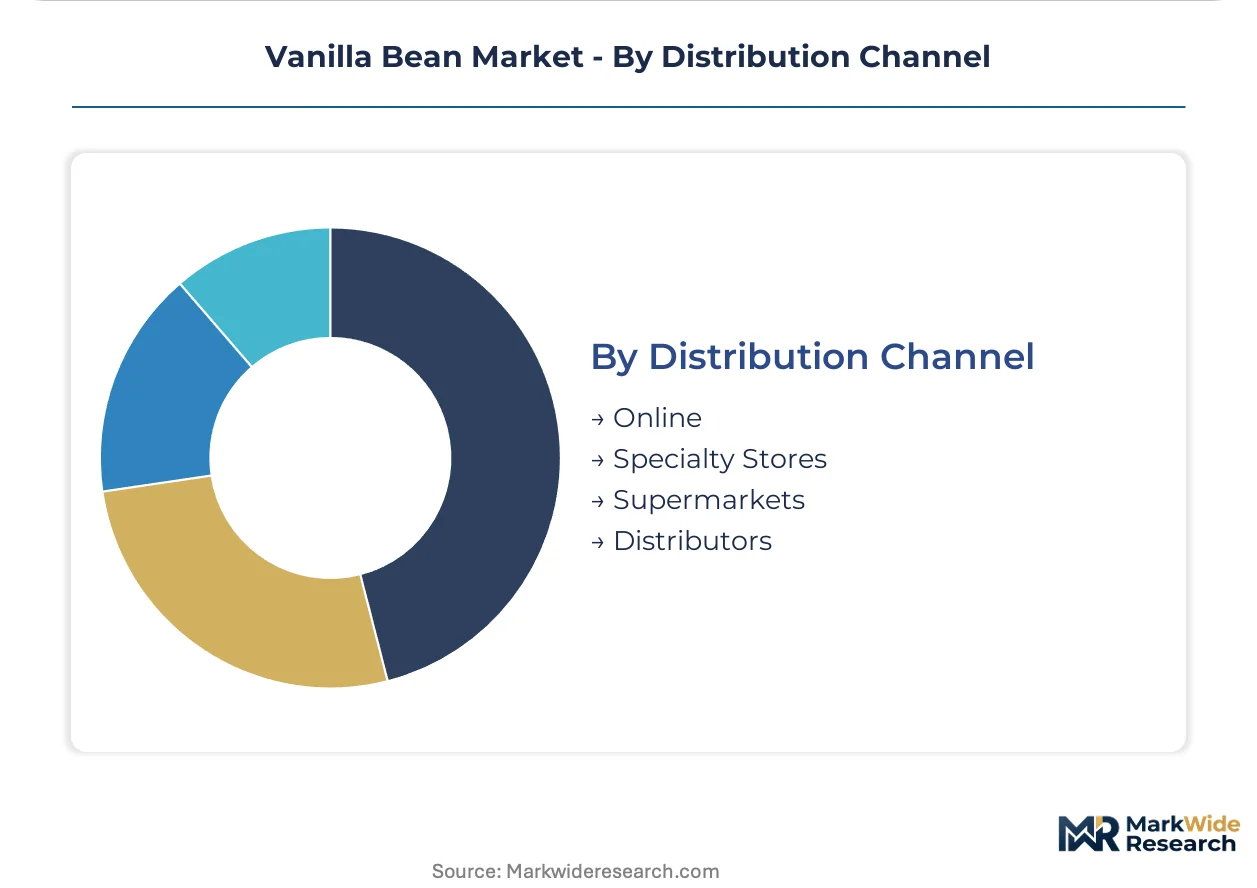
Distribution Channel:
Channel configuration determines authentication burden, margin retention, and geographic reach for vanilla bean suppliers.
- Distributors:Consolidated intermediaries manage EUDR compliance for small and mid-size European importers lacking polygon mapping capabilities. Extended lead times of four to eight weeks now apply to EU-bound shipments.
- Supermarkets:Mass retail placement requires volume commitments and promotional support. North American chains specify dual USDA National Organic Program and EU Organic Regulation certification for premium private label lines.
- Specialty Stores:Curated assortments emphasize origin stories and curing craftsmanship. Tokyo depachika food halls and Parisian épicerie fine stock limited Madagascar Grand Cru lots.
- Online:Direct platforms bypass intermediary margins and enable blockchain-verified provenance storytelling. Papua New Guinea-sourced beans gain visibility through specialty e-commerce without traditional curing infrastructure investment.
Distributors retain the largest volume throughput. Online channels gain share fastest through traceability transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Madagascar exports the majority of cured Bourbon vanilla to European flavor houses and North American ice cream manufacturers, creating a trade corridor vulnerable to cyclone disruption and port congestion at Toamasina.
United States
Artisanal ice cream manufacturers in Wisconsin and Vermont now specify origin-labeled Madagascar extract for premium positioning. FDA enforcement of 21 CFR 169.175 identity standards redirects industrial buyers toward certified pure extract suppliers. The Pacific Northwest hosts specialty roasters and craft chocolatiers driving small-batch vanilla paste procurement.
Germany
Organic certification arbitrage under EU Organic Regulation gates premium retail channel access for dual-certified Ugandan and Papua New Guinean lots. The country's national food safety regulator enforces strict contaminant thresholds for imported agricultural commodities. Cologne and Hamburg anchor continental distribution hubs managing EUDR geospatial documentation for EU-bound shipments.
France
Grasse-based fragrance laboratories specify vanillin fingerprinting for every lot of supercritical CO2-extracted vanilla absolute. ANSM and CNIL oversight extends to cosmetic ingredient traceability requirements. Parisian épicerie fine stock limited Madagascar Grand Cru lots for chef-driven procurement teams auditing curing cooperatives directly.
Indonesia
Planifolia cultivation in Java and Sulawesi supplies mid-tier industrial extract volumes to Asian processed food manufacturers. The country's national agricultural quarantine agency enforces phytosanitary certification for export lots. Surabaya and Makassar serve as consolidation points for shipments bound to flavor houses in Japan and South Korea.
Uganda
Organic-certified vanilla from the Rwenzori Mountains captures price premiums in German and Austrian retail channels. The Uganda National Bureau of Standards governs export quality grading for cured bean lots. Kampala-based cooperatives deploy blockchain-verified sourcing platforms to secure direct contracts with European artisanal bakery suppliers.
Vanilla Bean Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered procurement segments. The vendor base concentrates among multinational flavor houses with captive extraction infrastructure and regional trading houses managing EUDR compliance for smaller importers. Three strategic archetypes dominate: vertically integrated processors with direct farmer networks, specialty extractors serving cosmetics-grade absolute markets, and distributor-intermediaries consolidating volumes for compliance-heavy EU channels. Competitive moves center on backward integration into curing infrastructure and multi-year fixed-price contracting with inflation collars.
Among Swiss and German flavor houses, Givaudan SA and Symrise AG occupy positions anchoring premium Madagascar sourcing through blockchain-verified platforms. McCormick & Company, Inc. represents the North American retail distribution archetype, securing direct farmer partnerships in Papua New Guinea. These three exemplify the divergence between geospatial traceability investment and volume-scale retail penetration.
| Leading Market Players |
|---|
| Symrise AG |
| Givaudan SA |
| Firmenich SA |
| McCormick & Company, Inc. |
| Nielsen-Massey Vanillas, Inc. |
| Sensient Technologies Corporation |
| International Flavors & Fragrances |
| Synthite Industries Ltd |
| Takasago International Corp. |
| Others |
Value Chain & Pricing Dynamics
Madagascar supply concentration determines both the spread between Bourbon vanilla grades and the shape of procurement networks. Cyclone exposure in the Sava region amplifies price volatility across Madagascar-origin lots while compressing margins for non-traceable alternatives.
Pricing Analysis
Extraction-technology pricing gaps separate supercritical CO2 absolute grades from conventional alcohol-based extracts and commodity whole beans. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale as primary differentiation drivers. Cost compression in mid-tier extracts is intensifying because fermentation-derived vanillin alternatives are gaining industrial acceptance. Industrial ice cream manufacturers exhibit highest price sensitivity through multi-year fixed-price contracting, while cosmetics formulators show lowest sensitivity for absolute-grade materials.
Supply Chain Analysis
Curing cooperative concentration in Madagascar, Indonesia, and Uganda anchors global vanilla bean processing capacity. The supply chain draws from orchid cultivation, traditional sweating infrastructure, and alcohol-based extraction equipment as core inputs. Single-source vulnerability runs through the Sava region's seventy-percent share of Bourbon vanilla output, exposing buyers to weather-related disruption. Distribution runs through flavor house direct procurement for industrial volumes and specialty distributors for artisanal channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical low points as EUDR compliance investments force supplier consolidation and restore pricing discipline to traceable origin segments.
For Market Incumbents: Build blockchain-verified traceability moats by deploying geospatial mapping platforms that satisfy EU Deforestation Regulation polygon requirements. Secure backward integration into Papua New Guinea curing infrastructure to diversify beyond Madagascar concentration risk. Anchor multi-year fixed-price agreements with inflation collars to lock in volume commitments from Wisconsin and Vermont ice cream manufacturers.
For New Entrants and Emerging Players: Establish a beachhead in organic-certified Ugandan vanilla by leveraging dual USDA National Organic Program and EU Organic Regulation arbitrage for German and Austrian retail channels. Target home cooking segments through direct-to-consumer platforms that bypass traditional distributor margins. Lead with blockchain-verified provenance storytelling to differentiate against established commodity suppliers.
For Investors and Strategic Acquirers: EUDR full enforcement reshapes the acquisition landscape by rendering non-compliant trading houses acquisition targets for larger intermediaries with polygon mapping capabilities. Long-term viability favors vertically integrated processors with captive curing infrastructure and direct farmer networks. Monitor fermentation-derived vanillin cost curves as the signal indicating when natural extract premiums compress.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | Givaudan SA and Symrise AG leverage distributed ledger platforms to authenticate Madagascar curing-stage provenance. |
| Papua New Guinea Farmer Network Expansion | McCormick & Company, Inc. secures direct partnerships that bypass traditional curing cooperative intermediaries. |
| Supercritical CO2 Extraction Capacity Addition | Swiss and French facilities capture three-to-five times food-grade pricing in cosmetics absolute markets. |
| Organic Dual Certification Investment | Ugandan cooperatives unlock premium German and Austrian retail channels through USDA and EU Organic Regulation compliance. |
| EUDR Compliance System Integration | European importers deploy polygon mapping middleware to satisfy geospatial documentation requirements for EU-bound shipments. |
Study Parameters
The analysis maps whole bean, extract, powder, and paste sub-sectors, each validated through curing cooperative managers, flavor house procurement directors, cosmetics formulators, and specialty distributor channel heads. Primary interviews with Madagascar-based exporters and Ugandan cooperative leaders combined with secondary validation from customs trade records, FDA 21 CFR 169.175 enforcement actions, and EU Deforestation Regulation implementation guidance. Bottom-up volume triangulation across product formats and top-down value reconciliation anchored the sizing framework.
Assumptions held fixed include EUDR geospatial compliance timelines and fermentation-derived vanillin production cost curves, while vanilla planifolia yield volatility and cyclone frequency were modeled as scenario variables across the analysis window. Segmentation dimensions covered product type, application tier, end-user sophistication, and distribution channel configuration. CAGRs derived from compound growth trajectory modeling against historical price realization patterns and certified organic premium capture rates.
Macroeconomic conditions sit as an overlay; deviation in euro-dollar exchange rates or EU agricultural import tariff schedules would shift the trajectory. Forecasts reflect documented assumptions regarding EUDR enforcement stringency and synthetic biology substitution rates. Quarterly review of Madagascar meteorological indicators and fermentation vanillin capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Flavor Oil Market
Flavorings and Food Additives
Chicory Products Market
Flavorings and Food Additives
Water-Soluble Flavors Market
Flavorings and Food Additives
Food Grade Menthol Crystal Market
Flavorings and Food Additives
Natural Flavors and Fragrances Market
Flavorings and Food Additives
Neotame Market
Flavorings and Food Additives
Caralluma Extract Market
Flavorings and Food Additives
Cholic Acid Market
Flavorings and Food Additives
Australia Vanilla Flavor Market
Flavorings and Food Additives
United States Food Flavor and Enhancer Market
Flavorings and Food Additives
Ginkgo Biloba Extract Market
Flavorings and Food Additives
Global Flavors Market
Flavorings and Food Additives
Orange Extract Market
Flavorings and Food Additives
Nature Identical Flavorings Market
Flavorings and Food Additives
North America Food Colorants Market
Flavorings and Food Additives
Betanin Food Color Market