
 Brazil Agricultural Biologicals Market | 2026-2036
Brazil Agricultural Biologicals Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Agricultural Biologicals Market Insights
Microbial formulation technology is fragmenting the traditional crop input stack as live-cell delivery systems displace conventional chemistry-dependent protocols. Bioceres Crop Solutions anchors its position through proprietary strain development for drought-stressed environments. Novonesis A/S leverages fermentation scale to supply compatible microbial consortia across multiple crop systems. FMC Corporation competes by extending its biological portfolio through specialized distribution partnerships in Brazil's interior states.
Agricultural biologicals comprise living organisms, derived metabolites, and organic substrates formulated for crop enhancement, with microbial inoculants typically containing colony-forming units exceeding 10^9 per gram to ensure rhizosphere colonization. These inputs serve commercial agriculture by reducing synthetic chemical dependency while maintaining yield thresholds. Biopesticides command expanding shelf space as residue-conscious export markets tighten maximum residue limits for conventional agrochemicals. Biofertilizers occupy the volume leadership position in soybean-corn rotations where nitrogen-fixing bacteria replace top-dressed urea applications. Seed treatment represents the fastest-growing application vector as coating equipment upgrades enable uniform microbial deposition at planting.
ANVISA governs biological product registration through streamlined equivalence pathways for microbial pesticides, while MAPA oversees fertilizer claims and quality standards under federal agricultural input legislation. The country's national environmental regulator, IBAMA, imposes biodiversity access requirements on foreign-sourced microbial strains, creating compliance complexity for imported formulations. Stakeholders must monitor evolving equivalence protocols between Brazilian and Mercosur registration standards to anticipate competitive entry timing and portfolio localization requirements.
Market Dynamics
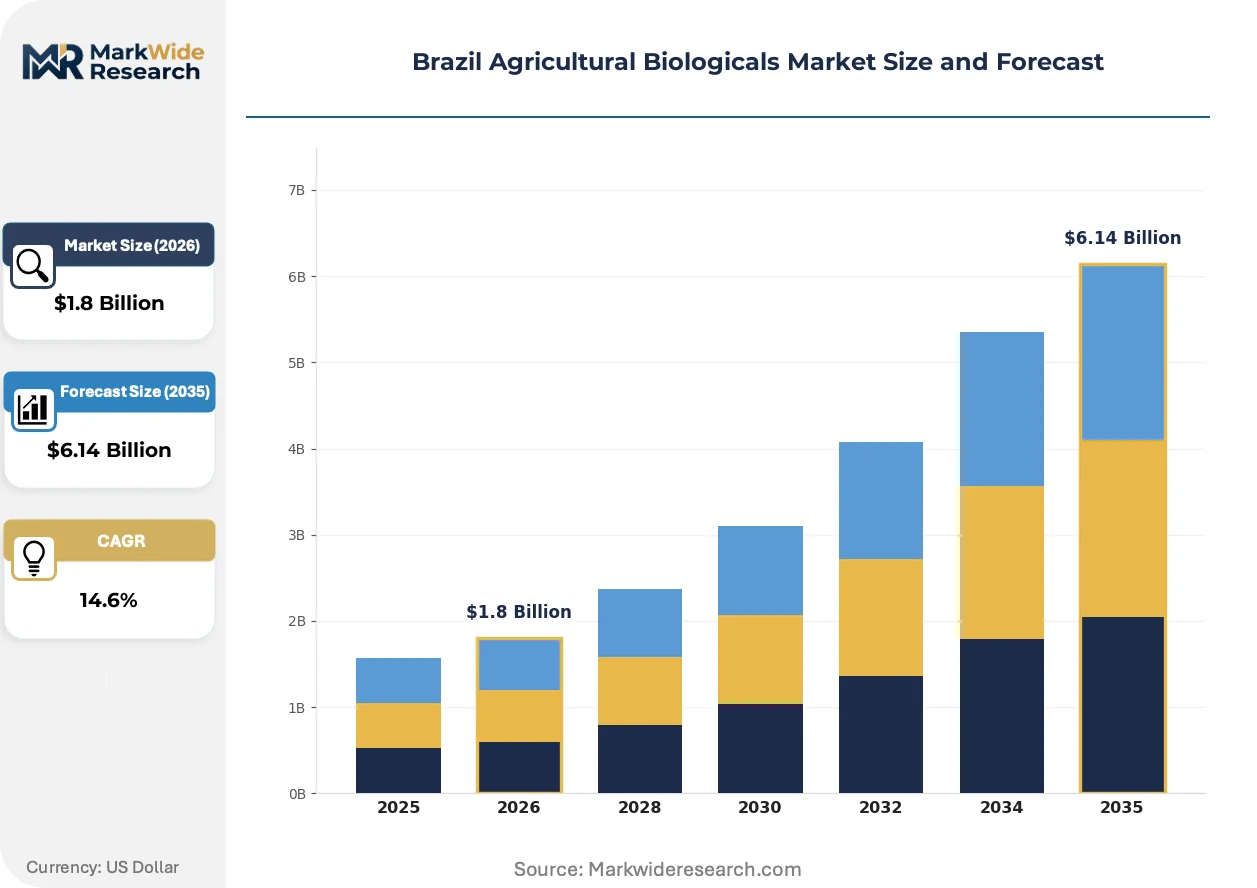
Microbial formulation advances are collapsing the traditional input hierarchy as live-cell delivery systems replace chemistry-dependent protocols across Brazil's Cerrado corridor. ANVISA's streamlined equivalence pathways for biopesticide registration accelerate this structural shift toward biological crop protection.
Growth Catalysts
- ANVISA Equivalence Pathways:Streamlined microbial pesticide registration reduces time-to-market for imported and domestic biological formulations, compressing competitive entry cycles for new entrants.
- Soybean Export Residue Limits:EU and Chinese maximum residue limits for synthetic agrochemicals drive Mato Grosso growers toward biopesticide seed treatments to maintain market access.
- Precision Planting Equipment:Upgraded coating systems enable uniform microbial deposition at planting, converting biological inoculants from foliar sprays to pre-plant protocols.
Market Restraints
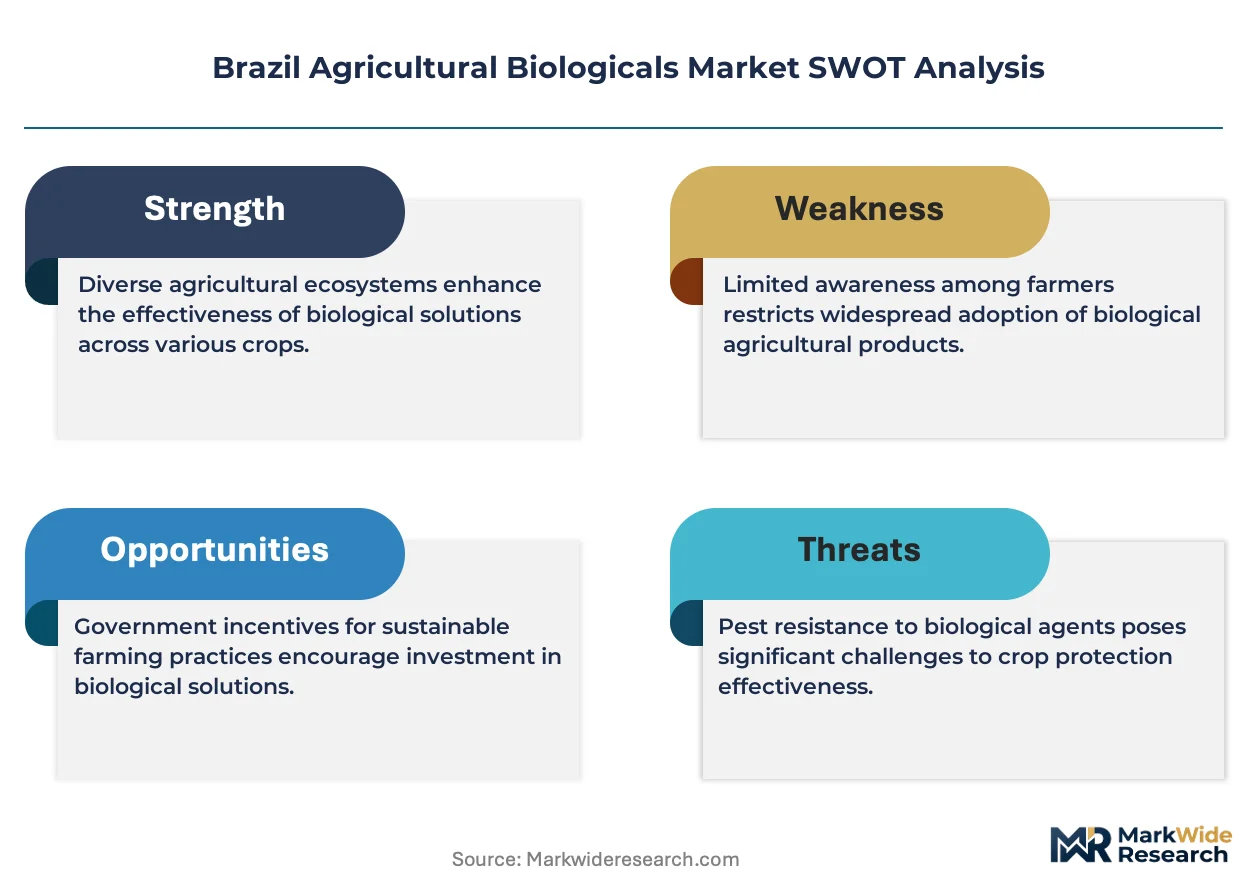
- IBAMA Biodiversity Access Requirements:Foreign-sourced microbial strains face compliance complexity for imported formulations, creating localization barriers for multinational suppliers.
- Live-Cell Shelf Stability:Microbial products containing colony-forming units exceeding 10^9 per gram require cold chain infrastructure absent in Brazil's interior distribution networks.
- Top-Dressed Urea Substitution Economics:Nitrogen-fixing bacteria face price competition from subsidized synthetic fertilizers in corn-soybean rotations, limiting penetration in cost-sensitive growing regions.
Strategic Opportunities
- MATOPIBA Expansion Corridor:Underdeveloped agricultural frontiers in Maranhão, Tocantins, Piauí, and Bahia present greenfield adoption potential for integrated biological protocols without legacy chemical dependency.
- MAPA Biofertilizer Quality Standards:Federal agricultural input legislation creates certification pathways that differentiate compliant products from unregistered competitors, enabling premium positioning.
- Digital Agriculture Convergence:Integration of microbial inoculants with variable-rate planting equipment and soil sensor networks enables outcome-based agronomic recommendations tied to biological performance.
Industry Challenges
- Microbial Strain Stewardship Expertise:Shortage of fermentation technologists and rhizosphere microbiologists limits domestic R&D capacity for proprietary strain development.
- MAPA-ANVISA Jurisdictional Overlap:Dual regulatory oversight for products spanning pesticide and fertilizer claims creates classification disputes and registration timeline uncertainty.
- Mercosur Equivalence Harmonization:Divergent registration standards across Brazil, Argentina, Paraguay, and Uruguay complicate regional portfolio strategies and manufacturing location decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Agricultural Biologicals Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Inoculants, Biopesticides, Biofertilizers, Amino Acids Application: Crop Protection, Soil Health, Seed Treatment, Organic Farming End Use Industry: Crops, Horticulture, Turf Management, Forestry Formulation: Liquid, Granular, Powder, Tablet |
| Companies Covered | Vittia Fertilizantes e Biológicos S.A., Microquimica Tradecorp Brazil S.A., Bioceres Crop Solutions Corp., FMC Corporation, Novonesis A/S, BIOMAX, Symborg, Lallemand, BASF, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Agricultural Biologicals Market Trends and Innovations
Formulation chemistry and regulatory architecture are converging to redefine competitive advantage in Brazil's agricultural biologicals sector. Three developments are compressing traditional market boundaries and creating new entry points for technology providers.
Encapsulation technology is collapsing the viability gap between laboratory strain performance and field efficacy. Polymer-based microencapsulation of nitrogen-fixing bacteria enables extended shelf life without refrigerated distribution. Large-scale row-crop operations in Mato Grosso are adopting these formulations for pre-plant seed treatment, replacing foliar application windows with single-pass planting protocols.
MAPA's implementation of federal biofertilizer quality standards under agricultural input legislation is compressing the competitive set by mandating minimum colony-forming unit counts and strain identification requirements. This regulatory tightening eliminates unregistered products from formal distribution channels. Domestic manufacturers with in-house fermentation capacity are expanding production to capture shelf space vacated by non-compliant imports.
Export-market residue protocols are collapsing procurement preferences toward certified biological inputs among integrated grain traders. Chinese and European buyers now require documentation of pre-harvest interval compliance for all crop protection applications. This certification-driven preference shift concentrates demand among biological suppliers with ANVISA-registered products and traceable supply chains, particularly in soybean-exporting cooperatives across the Cerrado corridor.
Brazil Agricultural Biologicals Market Segmentation
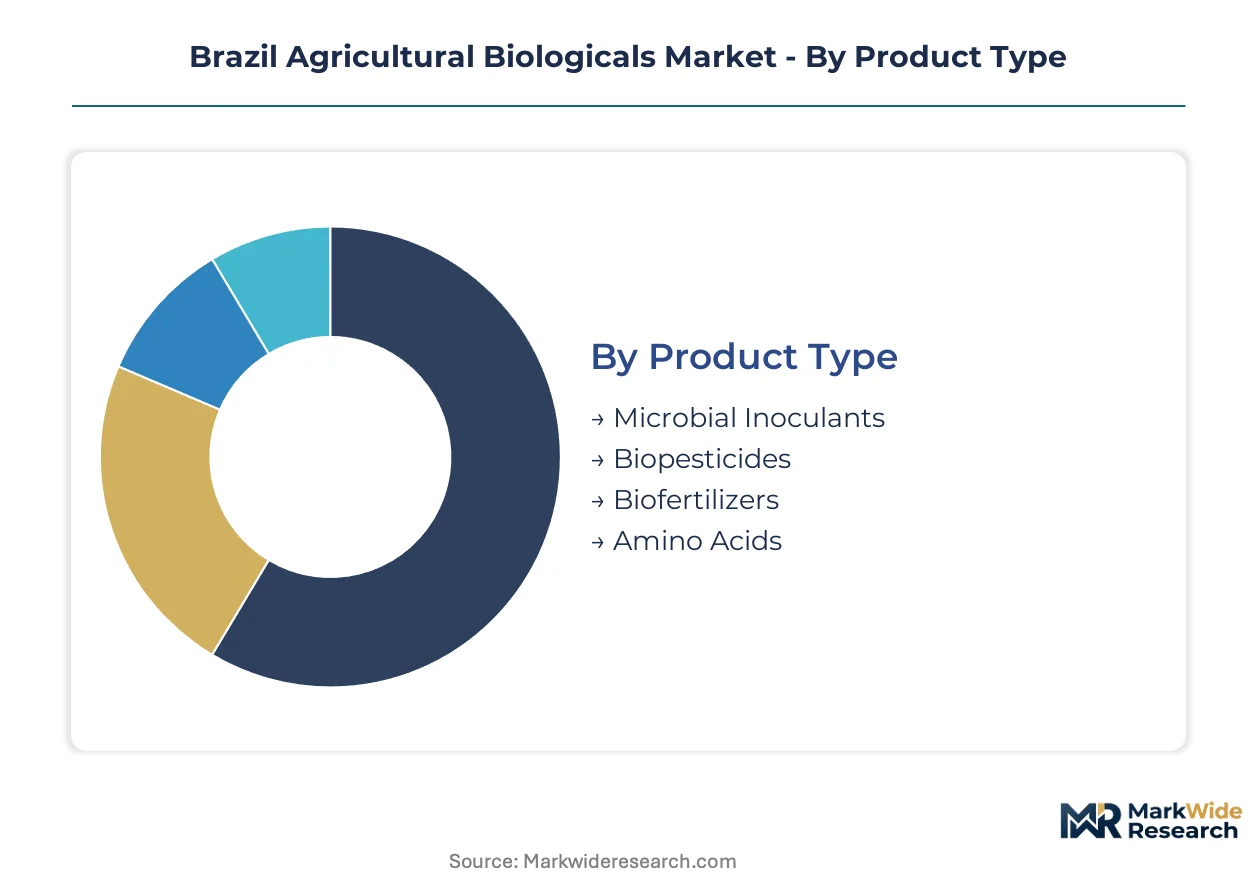
Segmentation in Brazil's agricultural biologicals market reveals how product chemistry, application timing, and end-use requirements create distinct competitive arenas. Each dimension carries unique regulatory footprints and technical specifications that shape supplier positioning.
Product Type:
Microbial products span the full use-case spectrum from rhizosphere colonization to foliar protection, with formulation stability determining field efficacy across Brazil's climate zones.
- Microbial Inoculants:Contain live bacteria or fungi exceeding 10^9 colony-forming units per gram, formulated for nitrogen fixation or phosphate solubilization. Demand concentrates in Mato Grosso soybean operations where Bradyrhizobium strains displace top-dressed urea, though cold chain gaps in interior distribution networks constrain penetration.
- Biopesticides:Derived from microbial fermentation or botanical extraction, targeting specific pest spectra with narrow modes of action. Mato Grosso growers are expanding adoption as ANVISA equivalence pathways compress registration timelines and EU export residue limits tighten.
- Biofertilizers:Organic substrates and metabolites enhancing nutrient availability without live-cell requirements.
- Amino Acids:Biostimulant compounds derived from protein hydrolysis, applied foliar or through fertigation systems.
Established volume favors microbial inoculants; emerging adoption favors biopesticides.
Application:
Application timing determines equipment compatibility and labor economics, with pre-plant protocols gaining share as precision planting infrastructure spreads.
- Crop Protection:Biological pest and disease management applied foliar or through chemigation, requiring live-cell viability through application windows. Demand clusters in Cerrado soybean operations where export residue documentation requirements concentrate procurement among ANVISA-registered suppliers.
- Seed Treatment:Microbial coating applied at planting, converting biological inputs from spray schedules to single-pass protocols. Mato Grosso operations with upgraded coating equipment are driving adoption as uniform deposition technology matures.
- Soil Health:Amendments targeting microbiome diversity and structure, applied pre-plant or between rotations.
- Organic Farming:Certified biological inputs meeting organic standard requirements for prohibited substance exclusion.
Seed treatment is climbing the fastest as equipment upgrades enable uniform microbial deposition; crop protection retains volume leadership through established spray infrastructure.
End Use Industry:
Customer scale and technical sophistication create divergent service requirements, from precision protocols for row-crop operations to maintenance schedules for perennial systems.
- Crops:Large-scale soybean-corn rotations dominating biological input consumption, with nitrogen-fixing bacteria and biopesticide seed treatments as core applications. MATOPIBA frontier expansion in Maranhão, Tocantins, Piauí, and Bahia presents greenfield adoption without legacy chemical dependency.
- Horticulture:High-value fruit and vegetable production with intensive input schedules and export quality requirements.
- Turf Management:Golf courses and sports fields requiring aesthetic performance and rapid recovery protocols.
- Forestry:Eucalyptus and pine plantations with multi-year rotation cycles and mechanized application constraints.
Crops command absolute volume; horticulture offers premium positioning through quality-sensitive procurement.
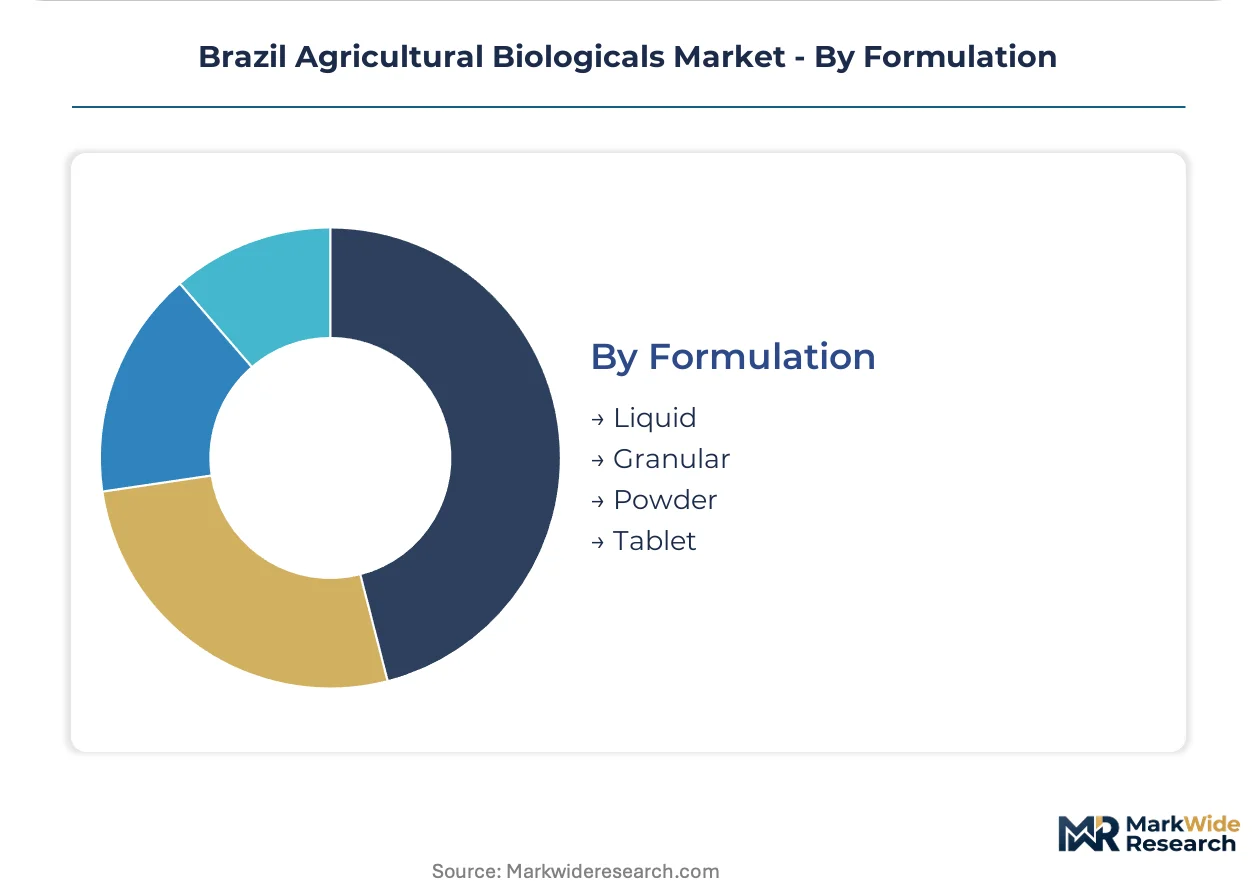
Formulation:
Physical form factor determines shelf stability, application equipment compatibility, and distribution economics across Brazil's interior logistics networks.
- Liquid:Aqueous suspensions of live cells or soluble metabolites, requiring calibrated spray equipment and often cold chain maintenance. Cerrado corridor operations prefer liquid for foliar application flexibility, though refrigerated transport gaps in remote areas constrain reach.
- Granular:Carrier-based formulations enabling dry application with standard planting equipment, extending shelf life through reduced moisture exposure.
- Powder:Concentrated dry formulations for reconstitution or direct soil incorporation, common in smallholder segments with limited mechanization.
- Tablet:Compressed formulations for specific application rates, niche in precision horticulture and research applications.
Liquid formulations dominate commercial row-crop volume; granular alternatives are gaining share fastest through shelf-stability advantages in interior distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's agricultural biologicals flow primarily toward European and Chinese export markets, with residue compliance requirements at destination ports reshaping input procurement across the Cerrado corridor.
Mato Grosso
Soybean growers in Mato Grosso dominate biological seed treatment consumption, driven by EU maximum residue limits on synthetic agrochemicals. ANVISA's streamlined equivalence pathways for microbial pesticide registration accelerate product availability for export-oriented operations. Rondonópolis and Lucas do Rio Verde anchor the adoption cluster, where precision planting equipment enables uniform microbial deposition at planting.
São Paulo
São Paulo's sugarcane and citrus sectors generate concentrated demand for biofertilizers and biostimulants, with processors requiring residue documentation for juice and ethanol exports. MAPA's federal biofertilizer quality standards under agricultural input legislation filter non-compliant products from formal distribution channels. Piracicaba and Ribeirão Preto host fermentation facilities supplying microbial consortia to adjacent growing regions.
Minas Gerais
Minas Gerais coffee and dairy operations deploy biological inputs for soil health management in high-altitude production zones. IBAMA's biodiversity access requirements on foreign-sourced microbial strains complicate import pathways for multinational suppliers. The Triângulo Mineiro region concentrates adoption of nitrogen-fixing bacteria in corn-soybean rotations replacing top-dressed urea.
Paraná
Paraná's diversified crop matrix—soybeans, corn, wheat, and poultry integration—creates year-round biological input demand across multiple application windows. State-level agricultural extension programs promote microbial inoculant adoption through technical assistance networks. Londrina and Maringá serve as distribution hubs connecting southern producers to domestic fermentation capacity.
Bahia
Bahia's MATOPIBA frontier expansion presents greenfield adoption potential for integrated biological protocols without legacy chemical dependency. Cotton and soybean operations in western Bahia require cold chain infrastructure for live-cell products that remains underdeveloped in interior distribution networks. Barreiras anchors the emerging demand cluster as large-scale row-crop operations establish precision planting infrastructure.
Brazil Agricultural Biologicals Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: domestic fermentation specialists with proprietary strain libraries, multinational agricultural input companies extending biological portfolios through distribution partnerships, and microbial technology platforms leveraging scale to supply compatible consortia across crop systems. Competitive moves concentrate on MAPA certification acquisition to differentiate compliant products and ANVISA registration timing to capture equivalence pathway advantages.
Among Brazil-based specialists, Vittia Fertilizantes e Biológicos S.A. and Microquimica Tradecorp Brazil S.A. occupy positions within the domestic manufacturing tier, exemplifying fermentation capacity anchored to regional distribution networks. Bioceres Crop Solutions Corp. represents the proprietary strain development archetype, while Novonesis A/S and FMC Corporation sit within the multinational technology platform tier. BIOMAX, Symborg, and Lallemand exemplify microbial consortium specialists, with BASF representing diversified agricultural input conglomerates extending biological coverage.
| Leading Market Players |
|---|
| Vittia Fertilizantes e Biológicos S.A. |
| Microquimica Tradecorp Brazil S.A. |
| Bioceres Crop Solutions Corp. |
| FMC Corporation |
| Novonesis A/S |
| BIOMAX |
| Symborg |
| Lallemand |
| BASF |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in domestic fermentation facilities across Brazil's interior drives supplier consolidation and amplifies pricing leverage for MAPA-certified manufacturers. Cold chain gaps in live-cell distribution compress margins for imported formulations while elevating premiums for shelf-stable alternatives.
Pricing Analysis
Next-generation encapsulation technology commands substantial premiums over conventional liquid formulations, while prior-generation powder products face cost compression from subsidized synthetic fertilizer competition. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale. Pricing pressure stems from nitrogen-fixing bacteria competing with subsidized urea in corn-soybean rotations. Large-scale cooperatives in Mato Grosso exhibit lowest price sensitivity due to export residue compliance requirements; smallholder segments in frontier regions show highest sensitivity.
Supply Chain Analysis
Extended payment terms from multinational distributors strain working capital for domestic fermentation specialists competing with subsidized imports. Manufacturing concentrates in Brazil, Denmark, and the United States, with strain development anchored in proprietary laboratories and toll fermentation distributed across regional hubs. Supply chains draw from molasses substrates, polymer encapsulants, and specialized packaging films. Single-source vulnerability in cold chain logistics for live-cell products creates distribution risk. Distribution runs through agricultural cooperatives and specialized biological input retailers serving the Cerrado corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's equivalence pathway acceleration constitutes a regulatory inflection compressing competitive entry cycles and amplifying returns for early-certified suppliers.
For Market Incumbents: Pre-empt emerging competition by acquiring domestic fermentation capacity in Minas Gerais or Goiás to secure MAPA certification advantages. Anchor proprietary strain libraries through IBAMA-compliant biodiversity access agreements before foreign entrants navigate compliance complexity. Defensive consolidation around cold chain infrastructure in MATOPIBA frontier zones neutralizes shelf-stability threats from encapsulation specialists. For New Entrants and Emerging Players: Western Bahia's underdeveloped cold chain infrastructure presents white-space opportunity for granular formulation specialists bypassing live-cell distribution constraints. Seed treatment application timing offers the most penetrable entry vector as precision planting equipment upgrades accelerate across Barreiras operations. Go-to-market positioning through agricultural machinery dealerships captures equipment-bundled biological adoption. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across microbial consortia manufacturing as fermentation scale economies mature. Long-term viability favors platform plays with multi-crop strain compatibility rather than single-product specialists. Acquisition targets should demonstrate ANVISA registration momentum and MAPA quality certification. Watch ANVISA-MAPA jurisdictional harmonization progress as the signal for regulatory clarity enabling portfolio consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| MAPA Certification Investment | Federal quality standards eliminate unregistered competitors from formal distribution channels. |
| Encapsulation Technology Licensing | Polymer-based microencapsulation extends shelf life without refrigerated infrastructure. |
| MATOPIBA Distribution Partnership | Frontier expansion corridors offer greenfield adoption without legacy chemical dependency. |
| Strain Stewardship Acquisition | Proprietary rhizosphere microbiology capabilities differentiate drought-stress formulations. |
| Digital Agriculture Integration | Variable-rate planting equipment convergence enables outcome-based agronomic recommendations. |
Research Methodology
Cross-validation between primary interviews with fermentation technologists and secondary validation through ANVISA registration databases anchors the qualitative findings. Primary sources include MAPA compliance officers, agricultural cooperative procurement managers, precision planting equipment distributors, and rhizosphere microbiology researchers. Secondary sources encompass IBAMA biodiversity access filings, federal biofertilizer quality standards documentation, customs import records for microbial formulations, and agricultural extension program reports. Bottom-up strain-level demand estimates triangulate against top-down regional crop acreage projections.
Calibration against historical adoption curves in comparable biological input markets shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, application timing, end-use crop system, and formulation stability class. CAGRs derive from fitted growth curves incorporating regulatory pathway acceleration effects and equipment upgrade cycles. Industry-specific forecast inputs include precision planting equipment penetration rates and EU-China residue limit tightening trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by multinational fermentation platforms would shift outcomes. Macroeconomic deviation in soybean export pricing, regulatory fragmentation between ANVISA and MAPA jurisdictions, or breakthroughs in synthetic nitrogen fixation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Poultry Manure Biofertilizers Market
Bio-Agriculture
China Biostimulants Market
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
Vietnam Biopesticides Market
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
Biorational Pesticides Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
Biochar Machine Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
US Biochar Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
South America Biological Organic Fertilizers Market
Bio-Agriculture
Biological Seed Treatment Market
Bio-Agriculture
United States Biopesticides Market
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
India Feed Probiotics Market