
 Brazil Biofertilizers Market | 2026-2036
Brazil Biofertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Biofertilizers Market Insights
The agricultural cooperative channel is fragmenting as digital platforms and specialty agronomy retailers capture share from traditional union-led purchasing. Rizobacter leverages its Rhizobium strain library to anchor premium positioning in soybean inoculants across southern Brazil. Vittia Group competes through phosphate-solubilizing formulations tailored to Cerrado acidity profiles. Novonesis A/S extends its Brazilian fermentation footprint to supply bulk active ingredients for downstream blenders.
Brazil biofertilizers comprise living microbial inoculants—primarily nitrogen-fixing bacteria, phosphate-solubilizing fungi, and plant-growth-promoting rhizobacteria—formulated in liquid suspensions or granular carriers with minimum viable cell counts exceeding 10⁸ CFU per gram, designed to enhance nutrient availability and reduce synthetic fertilizer dependency in commercial cropping systems. Liquid biofertilizers lead volume due to compatibility with existing spray infrastructure, while seed treatment application commands margin premiums through precise placement and reduced field passes. Granular formulations sustain growth in forestry and landscaping where mechanized broadcast spreading dominates operational protocols.
ANVISA registers microbial agricultural inputs under pesticide-equivalent safety protocols, while MAPA enforces quality standards through its national fertilizer laboratory network, creating dual compliance burdens that favor established producers with in-house toxicology and stability testing capabilities. The EU Green Deal's deforestation-free supply chain requirements, transmitted through Brazilian export certification bodies, redirect demand toward biological inputs with traceable carbon footprints. Stakeholders must monitor pending revisions to Brazil's Biosafety Law and state-level pesticide restriction statutes that could accelerate or constrain microbial product registrations.
Market Dynamics
ANVISA and MAPA's dual registration requirements are compressing the supplier base, favoring producers with in-house toxicology and fermentation capabilities while marginalizing blenders dependent on third-party active ingredients.
Growth Catalysts
- EU Green Deal deforestation regulations:Export certification bodies now mandate traceable biological inputs, redirecting Cerrado soybean operations toward certified biofertilizer suppliers.
- Phosphate-solubilizing microbial consortia:These formulations address Cerrado acidity constraints without lime amendments, accelerating adoption in no-till corn-soy rotations.
- Mato Grosso state environmental codes:Tightened synthetic input restrictions create compliance-driven substitution toward nitrogen-fixing inoculants in frontier agricultural zones.
Market Restraints
- ANVISA pesticide-equivalent safety protocols:Microbial agricultural inputs face toxicology testing burdens that extend registration timelines and elevate fixed costs for smaller blenders.
- Active ingredient supply concentration:Bulk fermentation capacity clusters with specialized biotech firms, creating dependency risks for downstream formulators lacking captive production.
- Synthetic fertilizer price volatility:Urea and phosphate commodity swings distort biofertilizer value propositions during low-price cycles in conventional inputs.
Strategic Opportunities
- Paraná specialty crop corridor:Vegetable and fruit producers in southern Brazil remain underpenetrated by microbial solutions optimized for high-value horticulture.
- Digital agronomy platforms:Remote sensing and prescription agriculture integration enables direct-to-farmer biofertilizer recommendations, bypassing cooperative purchasing structures.
- Pending Biosafety Law revisions:Streamlined microbial product registration pathways would accelerate market entry for novel strain combinations.
Industry Challenges
- Microbial viability management:Maintaining 10⁸ CFU per gram through storage, transport, and field application requires cold chain infrastructure absent in remote Cerrado municipalities.
- Strain intellectual property:Proprietary Rhizobium and Azospirillum libraries face licensing disputes that complicate consortium formulation development.
- Legacy synthetic fertilizer integration:Compatibility testing between biological inoculants and residual chemical programs demands field trial investment that stretches R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Biofertilizers Market |
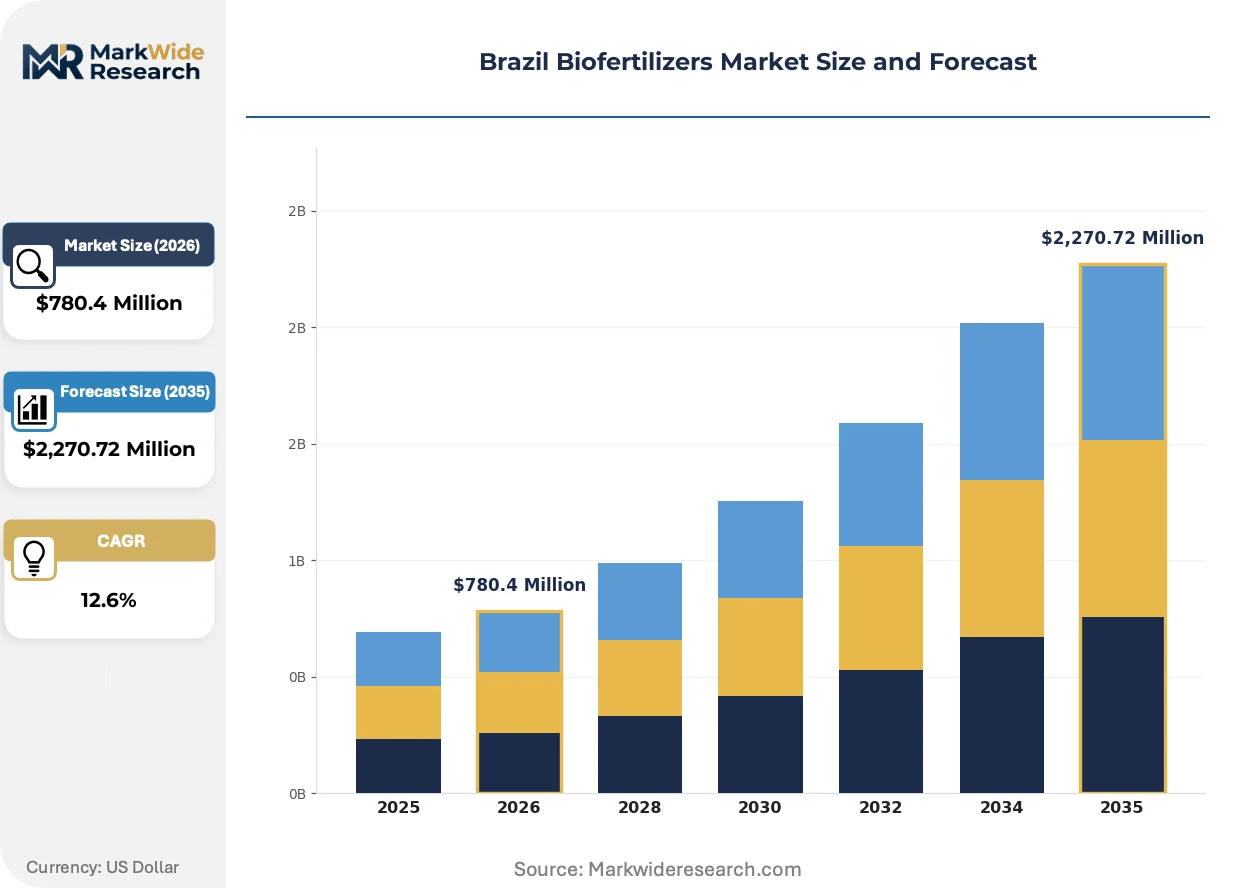
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $2,270.72 Million |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Biofertilizers, Granular Biofertilizers, Biofungicides, Bioherbicides End Use: Agriculture, Horticulture, Forestry, Landscaping Distribution Channel: Online Retail, Agricultural Cooperatives, Specialty Stores, Distributors Application Method: Soil Application, Seed Treatment, Foliar Spray, Hydroponics |
| Companies Covered | Vittia Group, Rizobacter, Novonesis A/S, Biolchim SpA, Lallemand Inc., Valagro, Bioceres Crop Solutions Corp, Novo Holdings, National Fertilizers Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Biofertilizers Market Trends and Innovations
Formulation science and regulatory traceability requirements are restructuring how microbial inputs reach Brazilian farms. Three developments dominate the innovation landscape.
Consortia-based multi-strain inoculants combining nitrogen-fixing bacteria, phosphate-solubilizing fungi, and plant-growth-promoting rhizobacteria in single formulations are rendering obsolete single-organism products. Large-scale no-till operators in Mato Grosso and Goiás are adopting these at accelerated rates. This compression collapses application passes and reduces tank-mix complexity for commercial spraying contractors.
MAPA's national fertilizer laboratory network is enforcing quality standards through expanded CFU verification and contaminant screening. This industrial consequence elevates compliance costs for smaller blenders while creating certification premiums for validated producers. Southern Brazil's cooperative purchasing channels are responding by consolidating supplier lists toward MAPA-certified facilities with documented stability testing.
Specialty agronomy retailers are capturing share from union-led cooperative purchasing through technical service bundling. These independent channels displace traditional volume-based procurement with strain-specific recommendations and application timing optimization. This shift concentrates in Paraná and Rio Grande do Sul where smaller landholdings demand customized biological programs rather than commodity inoculant packages.
Brazil Biofertilizers Market Segmentation
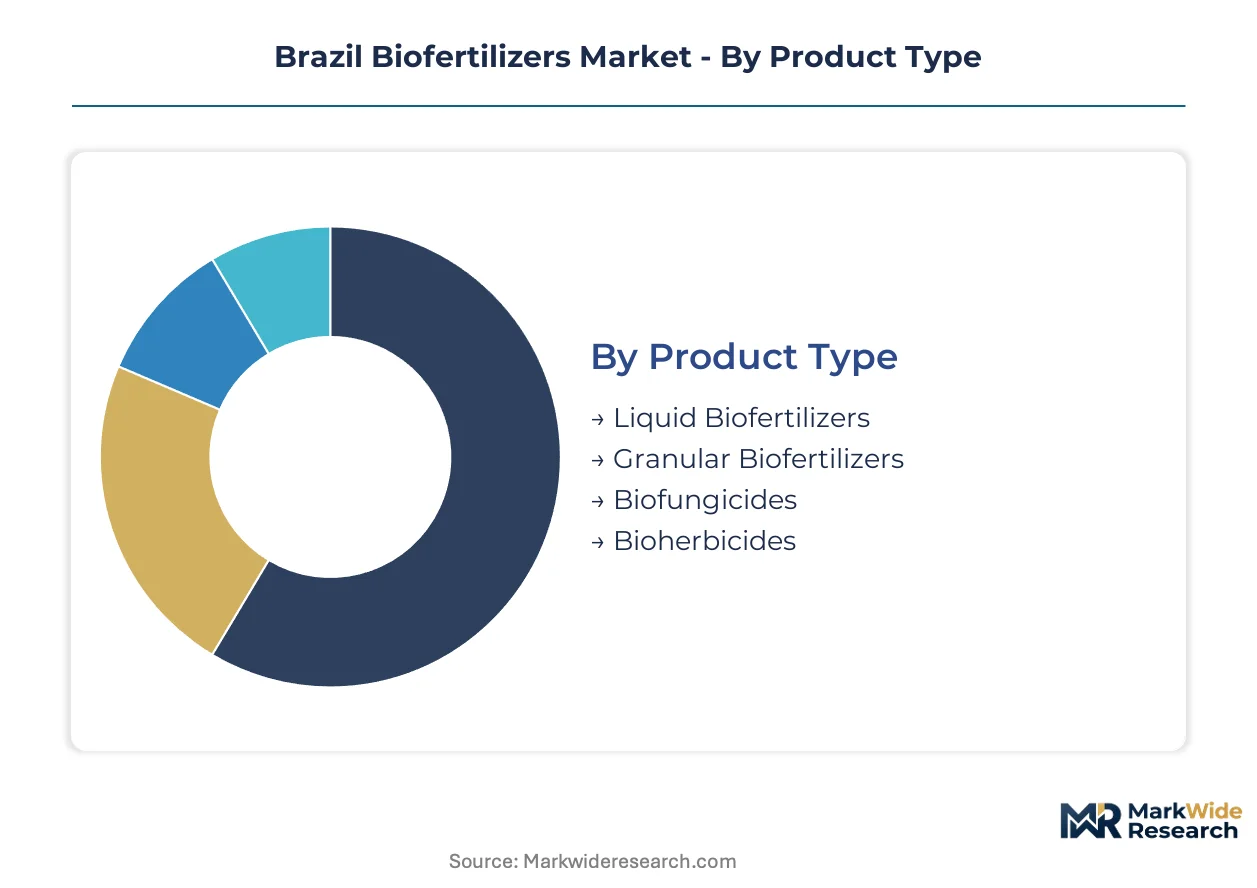
Brazil's biofertilizer segmentation reflects divergent operational rhythms across farming systems. Product formulations and application methods vary dramatically in inventory velocity and technical service intensity.
Product Type:
Liquid formulations turn inventory fastest through existing spray infrastructure, while granular products move slowly through bulk handling systems requiring specialized equipment.
- Liquid Biofertilizers:Microbial suspensions with minimum 10⁸ CFU per gram formulated for tank-mix compatibility with conventional crop protection. Mato Grosso no-till contractors favor these for single-pass application efficiency during narrow planting windows.
- Granular Biofertilizers:Carried-based inoculants with extended shelf stability designed for mechanized broadcast spreading. Forestry operations in Minas Gerais absorb volume despite higher per-hectare logistics costs versus liquid alternatives.
- Biofungicides:Microbial antagonists targeting soilborne pathogens through competitive exclusion mechanisms.
- Bioherbicides:Plant-pathogenic fungi formulated for targeted weed suppression in organic certification systems.
Liquid biofertilizers anchor the volume base while biofungicides gain share at the steepest rate as residue-conscious exporters seek dual-action biological inputs.
End Use:
Customer archetypes separate by purchase frequency and technical sophistication, with commodity row crops cycling inputs seasonally versus perennial systems demanding multi-year biological programs.
- Agriculture:Large-scale soybean-corn rotations across Cerrado states where ANVISA-registered nitrogen-fixing inoculants substitute for synthetic urea under tightening environmental codes.
- Horticulture:High-value vegetable producers in Paraná requiring strain-specific formulations with documented organic certification for EU export compliance.
- Forestry:Eucalyptus and pine plantation operators deploying phosphate-solubilizing consortia for multi-rotation nutrient management.
- Landscaping:Municipal and commercial turf managers utilizing granular carriers for mechanized establishment of biological soil amendments.
Agriculture commands absolute volume while horticulture expands most quickly as specialty crop corridors professionalize biological input procurement.
Distribution Channel:
Channel economics diverge sharply between high-touch advisory models and transaction-efficient platforms, with working capital requirements dictating participant scale.
- Agricultural Cooperatives:Union-led purchasing structures consolidating procurement for member farms across southern Brazil, though losing share to digitally-enabled competitors.
- Specialty Stores:Independent agronomy retailers bundling strain-specific recommendations with application timing optimization for smaller landholdings.
- Distributors:Regional logistics networks warehousing bulk liquid formulations for contractor delivery during compressed planting seasons.
- Online Retail:Direct-to-farmer platforms leveraging remote sensing data to prescribe biofertilizer rates without cooperative intermediation.
Agricultural cooperatives retain the volume base while online retail climbs the fastest as digital agronomy platforms capture younger producer cohorts.
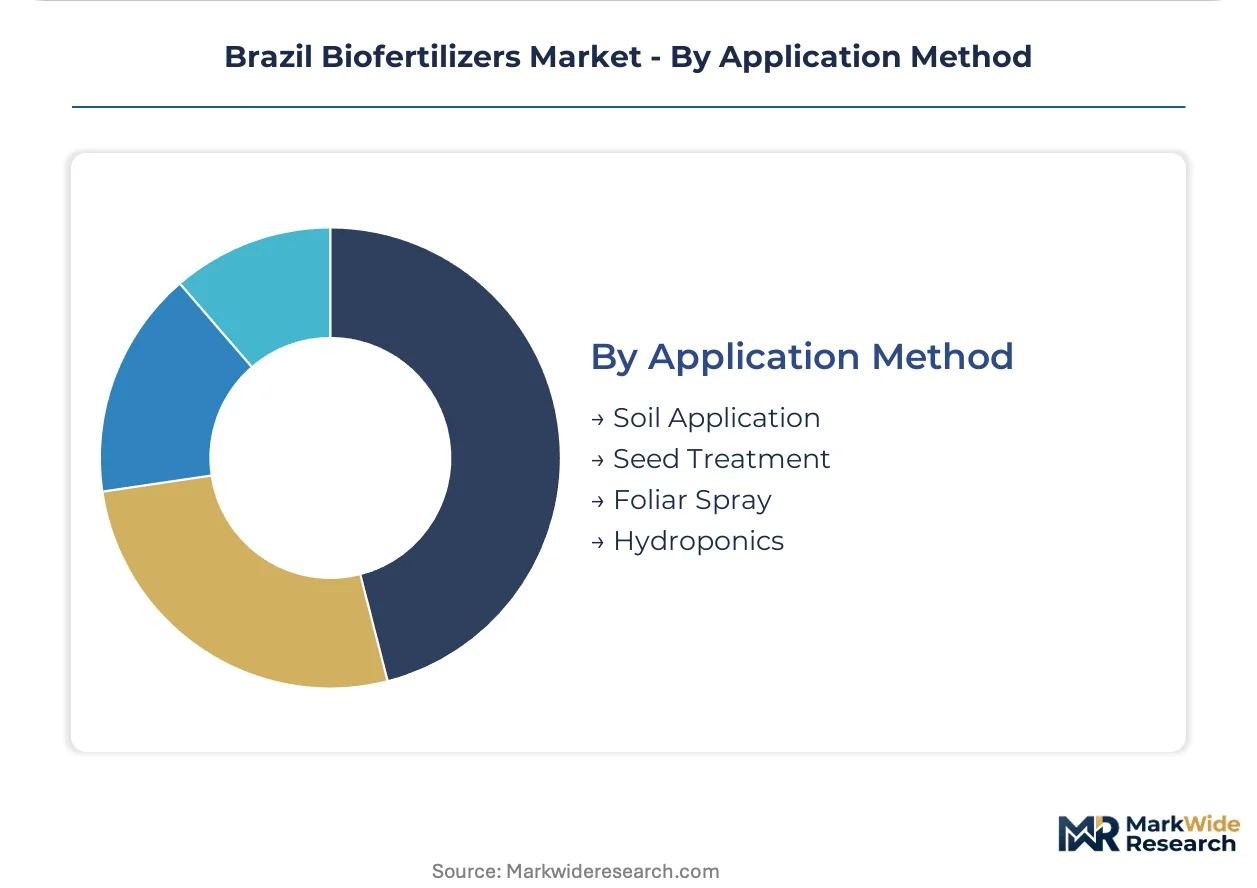
Application Method:
Placement precision directly correlates with biological efficacy and input cost recovery, separating premium positioning from commodity alternatives.
- Seed Treatment:Precision placement of Rhizobium inoculants onto soybean seed achieving maximum rhizosphere colonization with minimal field passes. Paraná farmers pay margin premiums for pre-applied formulations reducing planter box handling.
- Soil Application:Broadcast or banded delivery of phosphate-solubilizing consortia addressing Cerrado acidity constraints without lime amendments.
- Foliar Spray:Tank-mixed microbial suspensions applied during vegetative growth stages for supplemental plant-growth-promoting rhizobacteria delivery.
- Hydroponics:Recirculating system integration of nitrogen-fixing bacteria for protected cultivation operations in São Paulo's urban periphery.
Seed treatment anchors the volume base while hydroponics gains share at the steepest rate as protected cultivation expands for year-round vegetable supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA and MAPA's dual registration framework anchors regulatory oversight across Brazil's biofertilizer value chain, with state-level environmental codes creating differentiated compliance pressures across agricultural zones.
Mato Grosso
Soybean-corn rotations across the Cerrado frontier drive nitrogen-fixing inoculant consumption as state environmental codes tighten synthetic urea restrictions. MAPA's national fertilizer laboratory network enforces CFU verification standards that favor registered suppliers with documented stability testing. Rondonópolis and Lucas do Rio Verde anchor distribution logistics for liquid formulation deliveries during compressed planting windows.
Paraná
Specialty crop corridors cultivating vegetables and fruits for EU export compliance generate demand for certified organic biofertilizers with traceable carbon footprints. ANVISA's pesticide-equivalent safety protocols extend registration timelines for microbial inputs targeting high-value horticulture. Londrina and Maringá concentrate independent agronomy retailers bundling strain-specific recommendations with application timing optimization.
Rio Grande do Sul
Smaller landholdings across southern Brazil's cooperative heartland shift procurement toward digital platforms bypassing traditional union-led purchasing structures. State-level pesticide restriction statutes under pending Biosafety Law revisions redirect demand toward biological alternatives. Passo Fundo and Santa Maria host specialty stores capturing share through technical service bundling.
Minas Gerais
Eucalyptus and pine plantation operators deploy phosphate-solubilizing consortia for multi-rotation nutrient management across forestry zones. EU Green Deal deforestation-free supply chain requirements transmitted through Brazilian export certification bodies mandate traceable biological inputs. Belo Horizonte's logistics networks warehouse granular formulations for mechanized broadcast spreading in remote municipalities.
São Paulo
Protected cultivation operations in the urban periphery integrate nitrogen-fixing bacteria into recirculating hydroponic systems for year-round vegetable supply. ANVISA registers microbial agricultural inputs under toxicology testing burdens that elevate fixed costs for smaller blenders. Piracicaba and Campinas anchor fermentation capacity expansion serving downstream formulators with bulk active ingredients.
Brazil Biofertilizers Market Competitive Landscape
Strain-technology specialists and fermentation-scale operators split the market between premium proprietary formulations and commodity active ingredient supply. The supplier base compresses under dual registration burdens that favor in-house toxicology and stability testing capabilities. Three archetypes dominate: Rhizobium strain library holders, phosphate-solubilizing formulation developers, and bulk fermentation capacity operators. Competitive positioning hardens through MAPA certification premiums and backward integration into captive production.
Within the strain-technology tier, Rizobacter and Vittia Group exemplify divergent positioning strategies. Rizobacter anchors premium soybean inoculant positioning through its Rhizobium strain library across southern Brazil. Vittia Group occupies a position tailored to Cerrado acidity profiles with phosphate-solubilizing formulations. Novonesis A/S sits within the fermentation-scale archetype, extending Brazilian production footprint to supply bulk active ingredients for downstream blenders lacking captive manufacturing.
| Leading Market Players |
|---|
| Vittia Group |
| Rizobacter |
| Novonesis A/S |
| Biolchim SpA |
| Lallemand Inc. |
| Valagro |
| Bioceres Crop Solutions Corp |
| Novo Holdings |
| National Fertilizers Limited |
| Others |
Pricing and Supply Chain Analysis
Fermentation capacity underutilization in São Paulo's industrial corridor is compressing margins for bulk active ingredient suppliers while elevating pricing leverage for MAPA-certified formulators with captive strain libraries. This utilization asymmetry rewards backward-integrated producers and penalizes blenders dependent on third-party microbial concentrates.
Pricing Analysis
Price spreads between Mato Grosso no-till contractors and Paraná specialty crop producers exceed fifty percent on equivalent nitrogen-fixing inoculants, reflecting divergent certification requirements and technical service bundling. Three-tier pricing structure across premium MAPA-validated, standard registered, and economy unbranded tiers stratifies the market. Cost compression in the economy tier is intensifying because synthetic urea price volatility erodes biofertilizer value propositions during low-price cycles. Cooperative purchasing channels exhibit highest price sensitivity; export-certified horticulture operations demonstrate lowest sensitivity due to EU Green Deal compliance premiums.
Supply Chain Analysis
Upstream feedstock concentration in Brazilian sugarcane bagasse and corn steep liquor processing anchors domestic fermentation substrate availability, though phosphate-solubilizing fungi cultures draw from specialized Cerrado soil bank collections. Active ingredient production clusters with Novonesis A/S and captive biotech facilities in São Paulo and Minas Gerais, while carrier materials for granular formulations source from Minas Gerais mining byproducts. Single-source vulnerability concentrates in Rhizobium strain libraries held by incumbent specialists. Distribution runs through agricultural cooperatives in southern Brazil and specialty retailers in Paraná, with digital platforms emerging as direct-to-farmer alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of in-house toxicology and stability testing capabilities is consolidating supplier power toward MAPA-certified producers, marginalizing blenders lacking fermentation infrastructure or regulatory compliance depth.
For Market Incumbents: Pre-empt regulatory compression by accelerating backward integration into captive fermentation capacity before pending Biosafety Law revisions tighten registration pathways. Defend margin position through exclusive Rhizobium strain licensing agreements that block competitor consortium formulations. Prioritize cold chain infrastructure investment in remote Cerrado municipalities where microbial viability management failures create service differentiation opportunities. For New Entrants and Emerging Players: Paraná's vegetable and fruit corridors remain underpenetrated by microbial solutions optimized for high-value horticulture, offering white-space entry below incumbent radar. Rio Grande do Sul's digitally-native producer cohorts bypassing cooperative purchasing structures present direct-to-farmer platform opportunities without legacy channel conflict. Enter through prescription agriculture partnerships leveraging remote sensing data to demonstrate biofertilizer ROI without cooperative intermediation. For Investors and Strategic Acquirers: Capital is best deployed toward fermentation-scale operators with MAPA certification and documented stability testing capabilities, as dual registration burdens compress the supplier base and elevate acquisition premiums for compliant assets. Long-term viability hinges on exposure to Cerrado frontier expansion and EU export certification growth rather than commodity soybean inoculant volume. Monitor ANVISA registration timeline announcements as inflection indicators for regulatory arbitrage windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive active ingredient production insulates against supply concentration risks and elevates MAPA certification premiums. |
| Cold Chain Infrastructure Expansion | Municipal-level storage and transport networks address microbial viability failures in remote Cerrado planting zones. |
| Digital Agronomy Platform Partnership | Remote sensing integration enables direct-to-farmer recommendations bypassing cooperative purchasing structures. |
| Strain Library Licensing Agreements | Exclusive Rhizobium and Azospirillum access blocks competitor multi-strain consortium development. |
| EU Export Certification Investment | Traceable carbon footprint documentation captures Green Deal compliance premiums from deforestation-conscious buyers. |
Research Methodology
A spread of perspectives from fermentation plant managers, MAPA laboratory directors, cooperative procurement leads, specialty retailer agronomists, and Cerrado no-till contractors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through ANVISA registration databases, MAPA quality standard bulletins, and EU export certification body disclosures. Customs records tracking microbial concentrate imports and sugarcane bagasse processing volumes anchored bottom-up demand estimation, while top-down triangulation cross-checked against agricultural input expenditure surveys.
Demand-supply-balance framing structured the analytical approach across the projection horizon, modeling volume trajectories by product formulation, application method, end-use segment, and regional adoption cluster. Segmentation dimensions included liquid versus granular carrier systems, seed treatment versus soil application placement, agriculture versus horticulture versus forestry end uses, and cooperative versus digital channel penetration. CAGRs derived from fitted adoption curves calibrated to historical synthetic fertilizer substitution elasticities and regulatory enforcement intensity indices.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, EU agricultural import demand, and global urea price cycles would shift the trajectory materially. Forecasts embed assumptions regarding ANVISA registration timeline stability and MAPA laboratory network enforcement consistency. Cross-checking against agricultural cooperative purchasing data and export certification body transaction records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
Canada Biofertilizers Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
Plant-Based Biologics Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market
Bio-Agriculture
Global Biofortification Market
Bio-Agriculture
India Agricultural Biologicals Market
Bio-Agriculture
China Biostimulants Market
Bio-Agriculture
Europe Biofertilizer Market
Bio-Agriculture
United States Biocontrol Agents Market
Bio-Agriculture
GCC Biofertilizer Market
Bio-Agriculture
Bio-Seeds Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
North America Biofertilizer Market
Bio-Agriculture
Bio-Insecticide Market