
 North America Biostimulants Market | 2026-2036
North America Biostimulants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biostimulants Market Analytics
The capital-intensity divergence between microbial fermentation facilities and seaweed extraction operations is rotating competitive advantage toward players with in-house biological processing. Valagro USA leverages its Mediterranean-derived extraction expertise to sustain premium positioning in humic substance formulations. Koppert Biological Systems Inc. anchors its North American footprint through integrated biological crop protection distribution networks. Hello Nature USA Inc. competes by specializing in bacterial consortia tailored to corn and soybean rhizospheres.
Biostimulants comprise organic and inorganic substances applied to plants or soil to stimulate natural processes that enhance nutrient uptake efficiency, stress tolerance, and crop quality without direct pesticidal action; active constituents include amino acid profiles exceeding 80% purity, laminarin-rich seaweed polysaccharides, and spore-forming Bacillus species exceeding 10^9 CFU per gram. The primary commercial purpose centers on reducing grower dependency on synthetic nitrogen while maintaining yield trajectories amid volatile fertilizer pricing. Seaweed extracts command established margin pools due to decades of grower familiarity and consistent field performance documentation. Microbial products represent the fastest-expanding category as gene sequencing advances enable strain-specific inoculant development for targeted soil microbiome modulation. Amino acids occupy mature positioning in foliar application protocols across high-value vegetable and permanent crop systems.
The EPA regulates biostimulant products falling within biopesticide or plant regulator definitions, while state departments of agriculture in California and Florida enforce additional efficacy and residue testing protocols that shape market access timelines. The USDA National Organic Program standards create demand pull by permitting biostimulant use in certified organic operations where synthetic inputs face prohibition. Stakeholders must monitor emerging state-level fertilizer regulatory reclassifications that could subject historically unregulated biostimulant products to new registration burdens and efficacy substantiation requirements.
Market Dynamics
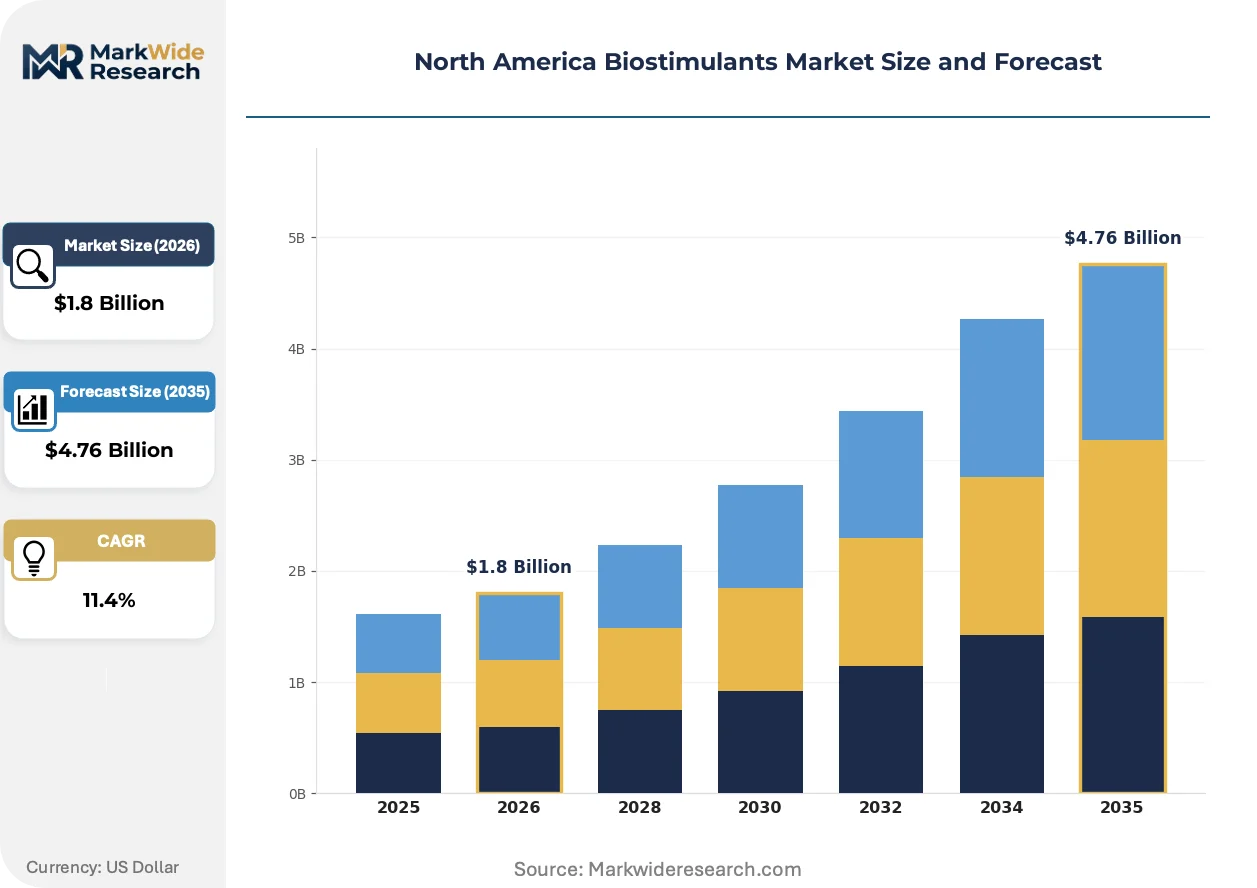
Specialty crop growers across California's Central Valley and Florida's citrus belt are accelerating biostimulant adoption to reduce synthetic nitrogen dependency amid volatile fertilizer pricing cycles. This demand pull is restructuring competitive positioning toward players with captive biological processing capabilities and strain-specific microbial development pipelines.
Growth Catalysts
- USDA Organic Certification Pathway:Certified organic operations face synthetic input prohibitions, creating mandatory demand for biostimulant alternatives in vegetable and permanent crop systems across the Corn Belt.
- Gene Sequencing Advances:Strain-specific inoculant development now enables targeted soil microbiome modulation for corn and soybean rhizospheres, accelerating microbial product category expansion.
- EPA Biopesticide Registration Frameworks:Accelerated commercialization timelines for products meeting plant regulator definitions are compressing market access barriers for novel biological formulations.
Market Restraints
- Seaweed Raw Material Concentration:Laminarin-rich polysaccharide supply chains concentrate in Mediterranean and North Atlantic extraction operations, exposing formulators to maritime harvest volatility and transport cost spikes.
- State-Level Fertilizer Reclassification Risk:California and Florida departments of agriculture enforce additional efficacy and residue testing protocols that extend registration timelines and inflate compliance expenditures.
- Amino Acid Input Cost Pressure:Foliar application protocols rely on amino acid profiles exceeding 80% purity, where fermentation feedstock costs track volatile agricultural commodity indices.
Strategic Opportunities
- Mississippi Delta Row Crop Penetration:Large-scale agricultural producers in this sub-region remain underpenetrated relative to specialty crop systems, offering volume expansion potential for bacterial consortia tailored to cotton and rice rotations.
- Integrated Biological Distribution Networks:Crop protection distributors with established agronomist relationships can capture biostimulant shelf space without dedicated capital deployment.
- Humic Substance Premium Positioning:Mediterranean-derived extraction expertise supports margin retention in specialty formulations for high-value permanent crops where grower familiarity commands price premiums.
Industry Challenges
- Microbial Strain Stability Expertise Gap:Spore-forming Bacillus species exceeding 10^9 CFU per gram require specialized fermentation and formulation capabilities scarce among regional distributors.
- Legacy Synthetic Fertilizer Integration Complexity:Agronomic protocols and application equipment across Corn Belt operations require retrofitting to accommodate biological product handling and timing requirements.
- Efficacy Substantiation Timeline Compression:Emerging state-level registration burdens demand field trial documentation that strains development budgets for early-stage product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biostimulants Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Seaweed Extracts, Microbial Products, Humic Substances Application: Crop Enhancement, Soil Health, Nutrient Management, Plant Growth Regulation End User: Agricultural Producers, Horticulturists, Landscape Professionals, Research Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Agrochemical Dealers |
| Companies Covered | Koppert Biological Systems Inc., Agrinos, Actagro LLC, Agrocare Canada Inc., Agriculture Solutions Inc., Valagro USA, Hello Nature USA Inc., Sigma Agriscience LLC, Humic Growth Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biostimulants Market Evolving Landscape
Biological crop input development is pivoting from broad-spectrum formulations toward precision microbiome engineering, with gene sequencing and fermentation advances converging to reshape product architecture and competitive differentiation.
Microbial consortia developed through marker-assisted strain selection is supplanting generic multi-strain blends in premium product tiers. Large-scale corn and soybean producers across Iowa and Illinois are adopting these targeted inoculants at accelerating pace. This precision approach is compressing margin pools for undifferentiated biological suppliers while rewarding players with in-house sequencing and fermentation infrastructure.
The EPA's evolving biopesticide registration pathways are creating regulatory clarity for plant biostimulant products previously caught between fertilizer and pesticide classification frameworks. This policy refinement reduces commercialization uncertainty for microbial and seaweed-derived formulations. California's Department of Pesticide Regulation is responding with parallel efficacy substantiation requirements that extend state-level approval timelines.
Agronomist-led technical recommendation models are displacing traditional distributor rebate structures as the primary purchase influence channel. Specialty crop growers in Florida's citrus and vegetable operations now expect field-specific application protocols bundled with product supply. This service integration is most visible in California's Central Valley, where independent crop consultants command growing input specification authority.
North America Biostimulants Market Segmentation
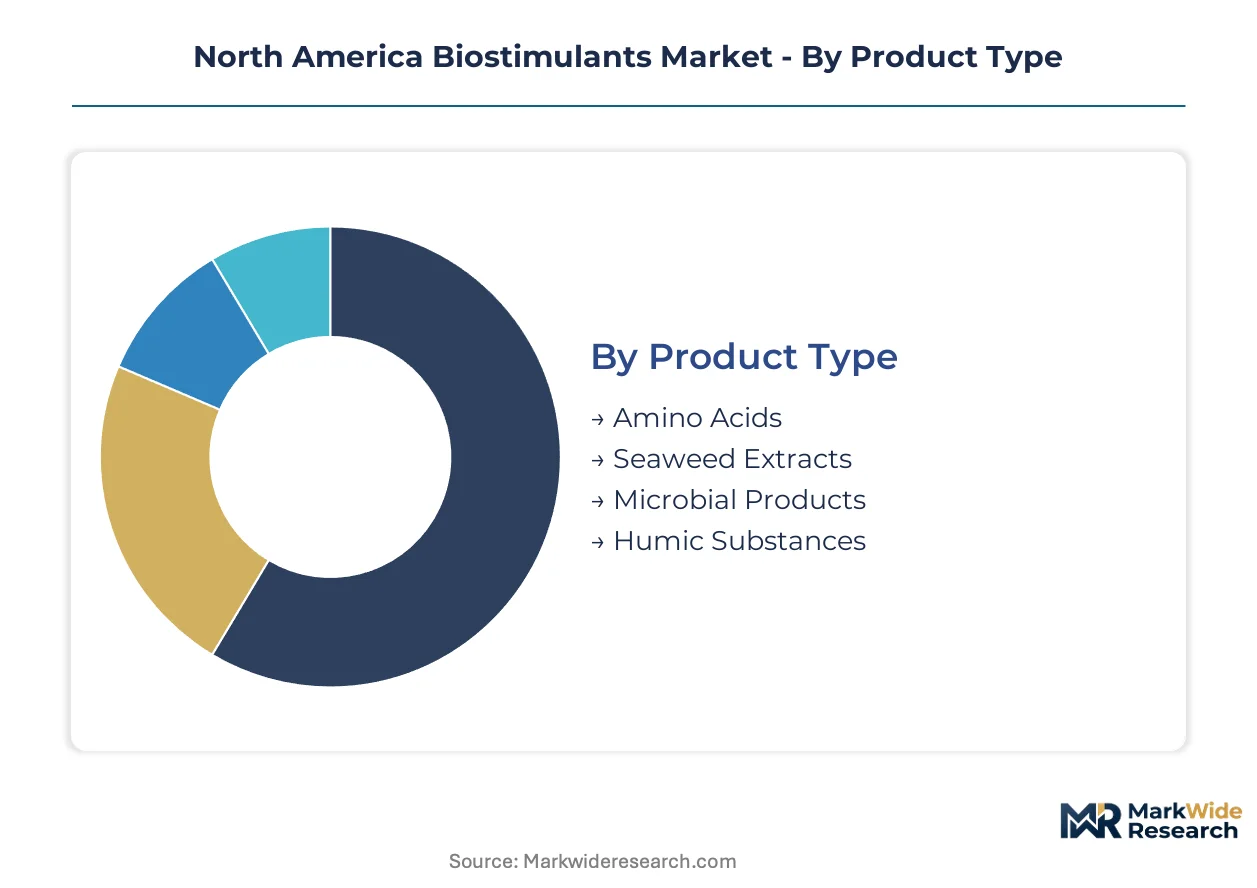
Biostimulant purchasing patterns diverge sharply between commodity row crop operations and high-value specialty systems, with product architecture and channel economics calibrated to these distinct agronomic requirements. The segmentation reveals where substitution pressure from synthetic inputs concentrates and where biological alternatives command structural advantage.
Product Type:
Seaweed extracts and amino acids face the most acute substitution threat from conventional foliar fertilizers, while microbial products operate in a less contested functional space.
- Seaweed Extracts:Laminarin-rich polysaccharides derived from Ascophyllum nodosum and Laminaria species constitute the formulation base. Demand clusters in Florida's citrus belt and California's Central Valley vegetable operations where decades of field documentation support grower confidence. EPA biopesticide registration pathways have compressed approval timelines for novel extraction protocols.
- Microbial Products:Spore-forming Bacillus species exceeding 10^9 CFU per gram and targeted bacterial consortia dominate this category. Corn and soybean producers across Iowa and Illinois are adopting strain-specific inoculants at the steepest rate as gene sequencing enables rhizosphere-tailored formulations. USDA Organic certification prohibitions on synthetic nitrogen accelerate demand pull in certified operations.
- Amino Acids:Fermentation-derived profiles exceeding 80% purity serve foliar application protocols in high-value permanent crops. Input cost volatility tracks agricultural commodity indices.
- Humic Substances:Mediterranean-sourced leonardite and peat derivatives command premium positioning in specialty crop systems where extraction provenance influences purchasing decisions.
Seaweed extracts anchor the volume base while microbial products gain share at the steepest rate.
Application:
Margin structures vary by functional claim complexity, with soil health applications requiring the most extensive field substantiation investment.
- Crop Enhancement:Yield protection and quality improvement claims dominate high-value fruit and vegetable systems. California specialty crop growers prioritize harvest index improvements in almond and grape operations.
- Soil Health:Microbiome modulation and aggregate stability applications target long-term productivity maintenance. Mississippi Delta cotton producers are expanding adoption to reduce synthetic input dependency in degraded soils.
- Nutrient Management:Nitrogen use efficiency and phosphorus solubilization claims concentrate in Corn Belt row crop rotations where fertilizer cost volatility drives biological substitution.
- Plant Growth Regulation:Stress tolerance and hormonal modulation applications serve Florida citrus operations facing HLB disease pressure and climate variability.
Nutrient management commands the largest addressable acreage while soil health applications show the steepest expansion trajectory.
End User:
Technical sophistication thresholds separate segments, with research institutions serving as validation gatekeepers for broader commercial adoption.
- Agricultural Producers:Large-scale Corn Belt and Mississippi Delta operations drive volume procurement through distributor networks. Equipment retrofit requirements and application timing protocols create switching costs from legacy synthetic programs.
- Horticulturists:Greenhouse and nursery operations in Florida and California demand precision formulation and field-specific technical support. Independent crop consultants command growing input specification authority in this segment.
- Landscape Professionals:Turf and ornamental applications in municipal and commercial settings prioritize aesthetic outcome consistency.
- Research Institutions:University extension services and USDA ARS facilities generate efficacy documentation that shapes regulatory and commercial acceptance timelines.
Agricultural producers generate the dominant revenue base while horticulturists deliver the highest margin per treated acre.
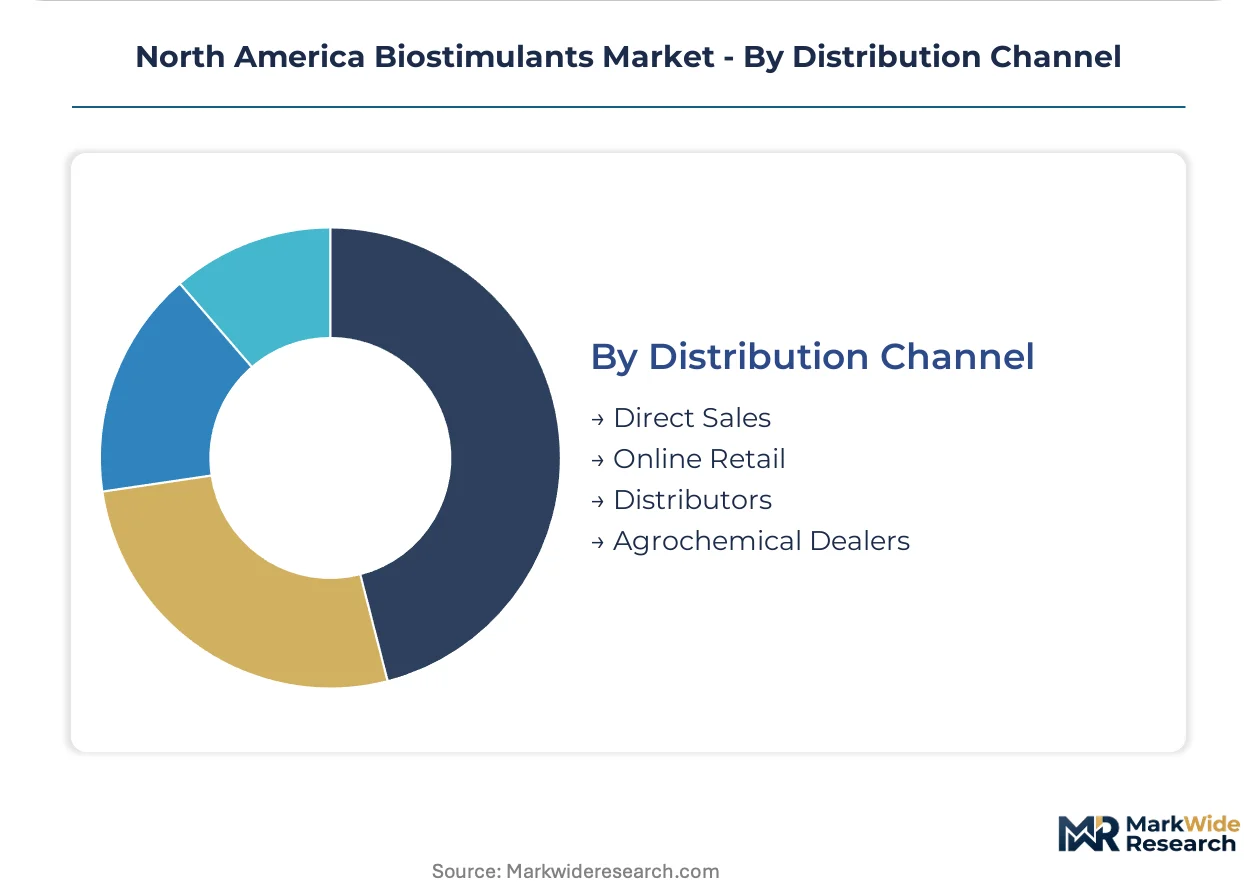
Distribution Channel:
Channel selection reflects customer scale and technical service requirements, with integrated biological networks displacing traditional rebate-driven structures.
- Distributors:Regional crop protection distributors with established agronomist relationships capture biostimulant shelf space without dedicated capital deployment. Koppert Biological Systems anchors North American presence through this channel architecture.
- Agrochemical Dealers:Legacy synthetic fertilizer retail networks require product training and equipment compatibility protocols to accommodate biological handling requirements.
- Direct Sales:Large-scale producers in Iowa and Illinois negotiate volume contracts with technical service bundling. Valagro USA leverages Mediterranean extraction expertise to sustain premium positioning in direct channels.
- Online Retail:Small-scale horticulture and landscape customers access standardized formulations through digital procurement platforms with limited technical support.
Distributors retain the volume base while direct sales channels climb the fastest as large producers consolidate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American biostimulant trade flows reflect divergent agricultural specialization patterns across the continent. The United States dominates regional consumption through its Corn Belt and specialty crop concentrations, while Canada supplies peat-derived humic substrates and Mexico contributes tropical seaweed extraction capacity. Cross-border regulatory alignment remains incomplete, with EPA biopesticide pathways operating independently from Health Canada and Mexican SADER protocols.
United States
California's Central Valley and Florida's citrus belt drive specialty crop demand for laminarin-rich seaweed extracts and amino acid formulations. The EPA's plant regulator registration framework accelerates commercialization timelines for microbial products meeting biopesticide definitions. Iowa and Illinois corn-soybean rotations anchor volume procurement for bacterial consortia tailored to rhizosphere modulation.
Canada
Prairie province canola and wheat producers are expanding biological input adoption to reduce synthetic nitrogen dependency amid carbon pricing pressures. Health Canada's Pest Management Regulatory Agency maintains parallel efficacy substantiation requirements that extend product registration timelines versus EPA pathways. Ontario's greenhouse vegetable clusters around Leamington and Kingsville generate concentrated demand for precision foliar formulations.
Mexico
Sinaloa and Baja California vegetable export operations face EU and US buyer sustainability protocols that mandate biological input documentation. The Secretariat of Agriculture and Rural Development (SADER) is developing fertilizer reclassification standards that could subject imported biostimulants to new registration burdens. Pacific coast seaweed harvesting operations in Guerrero and Oaxaca supply raw laminarin polysaccharides to North American formulators.
North America Biostimulants Market Competitive Landscape
Concentration sits with integrated biological processing specialists and Mediterranean extraction heritage players. The vendor base fragments between microbial fermentation capacity owners, seaweed extraction operators, and regional distribution networks with agronomist relationships. Three archetypes dominate: captive biological processors with strain development pipelines, extraction specialists leveraging geographic raw material access, and crop protection distributors capturing shelf space through technical service bundling. Portfolio diversification toward precision microbiome engineering and backward integration into fermentation capacity represent the dominant competitive vectors.
Within the extraction heritage tier, Valagro USA occupies a position reflecting Mediterranean-derived humic substance expertise. Koppert Biological Systems Inc. exemplifies the distribution-anchored archetype through integrated biological crop protection networks. Hello Nature USA Inc. represents the microbial specialization vector with bacterial consortia development capabilities. These three players illustrate how competitive advantage rotates toward in-house biological processing and strain-specific formulation expertise.
| Leading Market Players |
|---|
| Koppert Biological Systems Inc. |
| Agrinos |
| Actagro LLC |
| Agrocare Canada Inc. |
| Agriculture Solutions Inc. |
| Valagro USA |
| Hello Nature USA Inc. |
| Sigma Agriscience LLC |
| Humic Growth Solutions Inc. |
| Others |
Value Network & Pricing Analysis
Synthetic nitrogen displacement by microbial inoculants and seaweed extracts is redrawing raw material sourcing maps from Gulf Coast petrochemical corridors toward Mediterranean extraction facilities and domestic fermentation centers, compressing margin pools for undifferentiated commodity suppliers while rewarding captive biological processors with upstream cost control.
Pricing Analysis
Large-scale agricultural producers across Iowa and Illinois anchor North American biostimulant pricing through volume contract negotiations that bundle technical agronomic services with product supply. Three-tier pricing structure across premium, standard, and economy levels separates Mediterranean-derived humic formulations from domestic microbial consortia and generic seaweed extracts, with price differentiation resting on extraction provenance documentation and strain-specific efficacy data. Cost compression in economy-tier amino acid formulations is intensifying because fermentation feedstock costs track volatile agricultural commodity indices. Horticulturists in Florida and California exhibit the lowest price sensitivity, prioritizing harvest index improvements over per-acre input costs, while Mississippi Delta row crop operators remain highly price-sensitive due to thin cotton and rice margins.
Supply Chain Analysis
Container availability constraints on Mediterranean-to-Charleston shipping lanes and Pacific Northwest port congestion are elevating inbound logistics costs for laminarin-rich seaweed polysaccharides and European-sourced humic substrates. Manufacturing gravity centers on Italy and Spain for extraction expertise, the United States for microbial fermentation capacity, and Canada for peat-derived humic substrates, with raw material dependencies spanning Ascophyllum nodosum harvest operations, leonardite mining, and spore-forming Bacillus culture media. Single-source vulnerability concentrates in Mediterranean seaweed extraction operations exposed to maritime harvest volatility and climate-driven biomass fluctuations. Distribution runs through regional crop protection distributors with established agronomist relationships, supplemented by direct sales channels for large-scale Corn Belt producers consolidating procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarce fermentation infrastructure and strain-specific formulation expertise are concentrating competitive advantage among players with captive biological processing capabilities, leaving commodity distributors exposed to margin compression from integrated suppliers.
For Market Incumbents: Consolidate microbial fermentation capacity through targeted facility acquisitions or joint ventures with university extension programs to secure strain development pipelines. Lock in long-term offtake agreements with Mediterranean seaweed extraction operators to defend raw material access against emerging Asian competitors. Prioritize backward integration into spore-forming Bacillus culture production to reduce dependency on third-party fermentation contractors. For New Entrants and Emerging Players: Differentiate on precision microbiome engineering capabilities by partnering with gene sequencing service providers to develop rhizosphere-tailored bacterial consortia for underpenetrated Mississippi Delta cotton and rice rotations. Target direct sales relationships with large-scale producers in Iowa and Illinois who are consolidating procurement authority away from traditional distributor networks. Pursue white-space positioning in greenhouse vegetable clusters around Leamington, Ontario, where Health Canada registration timelines have deterred incumbent investment. For Investors and Strategic Acquirers: Emerging state-level fertilizer reclassification standards in California and Florida reshape the acquisition landscape by elevating regulatory compliance capabilities to primary valuation criteria. Target microbial fermentation specialists with existing EPA biopesticide registrations and documented field trial portfolios, as these assets compress commercialization timelines for acquirers. Watch for SADER regulatory developments in Mexico as a signal for North American harmonization pressure that would advantage players with multi-jurisdictional registration expertise.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive Bacillus culture production reduces third-party dependency and secures margin control. |
| Precision Microbiome Product Development | Gene sequencing partnerships enable strain-specific formulations that command premium positioning. |
| EPA Biopesticide Registration Investment | Accelerated approval pathways compress commercialization timelines for novel microbial formulations. |
| Integrated Agronomist Service Bundling | Field-specific application protocols displace rebate-driven distributor structures in specialty crop segments. |
| Mediterranean Extraction Supply Agreements | Long-term laminarin polysaccharide offtake secures raw material access against maritime harvest volatility. |
Research Methodology
Operator-level perspectives from specialty crop growers, crop protection distributors, microbial fermentation facility managers, and EPA regulatory affairs specialists anchored the qualitative base for this analysis. Primary interviews with these stakeholders combined with secondary validation from USDA National Organic Program standards documentation, EPA biopesticide registration databases, state department of agriculture efficacy testing protocols, and customs trade data for seaweed extract imports. Bottom-up acreage and application rate estimates triangulated against top-down manufacturer shipment data.
Sensitivity analysis around fertilizer price volatility scenarios and regulatory reclassification probabilities informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application function, end-user technical sophistication, and distribution channel structure, with additional granularity on organic certification status and row crop versus specialty crop system differentiation. CAGRs derived from trend extrapolation of historical adoption curves adjusted for gene sequencing technology diffusion rates and EPA registration pathway efficiency improvements.
Material uncertainties — state-level fertilizer reclassification timing, maritime seaweed harvest yields, and synthetic nitrogen price trajectory shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and technology adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Microphytes Market
Bio-Agriculture
Europe Biofertilizer Market
Bio-Agriculture
Bovine Tuberculosis Diagnosis Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Bacterial Biopesticides Market
Bio-Agriculture
Bloodroot Market
Bio-Agriculture
Indonesia Biopesticides Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
United States Biofertilizer Market
Bio-Agriculture
Bio-Insecticide Market
Bio-Agriculture
Mycelium Market
Bio-Agriculture
North America Bioherbicides Market
Bio-Agriculture
Plant-Based Biologics Market
Bio-Agriculture
Middle East and Africa Animal Genetics Market
Bio-Agriculture
India Biomass Market