
 ABS Sensors Market | 2026-2036
ABS Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
ABS Sensors Market Analytics
A shortage of mechatronics engineers is unwinding production timelines at several sensor manufacturers. Robert Bosch GmbH leverages captive semiconductor fabrication to secure chip supply for active sensor modules. Continental AG anchors its European market position through integrated braking system architectures. DENSO Corporation specializes in Hall-effect magnetic sensing for compact motorcycle ABS applications.
ABS sensors detect wheel deceleration rates via variable reluctance or Hall-effect principles, transmitting pulse signals to electronic control units at frequencies up to 15 kHz for real-time slip detection. These components prevent wheel lockup during emergency braking, maintaining vehicle steerability and reducing stopping distances on low-friction surfaces. Active sensor architectures now lead the technology dimension due to their digital output precision and immunity to electromagnetic interference from hybrid drivetrains. The OEM end-user channel captures the dominant margin pool as vehicle assemblers consolidate braking system procurement under platform-sharing agreements.
The US NHTSA mandates electronic stability control on all light vehicles, embedding ABS sensor demand within federal safety compliance. Europe's ECE R13 braking regulation and UN Regulation 78 for motorcycles enforce minimum ABS performance thresholds across type approvals. India's BIS certification and mandatory ABS fitment for two-wheelers above 125cc are reshaping supplier qualification requirements. Stakeholders must monitor how software-defined braking architectures redefine sensor hardware specifications and supplier value capture.
Market Dynamics
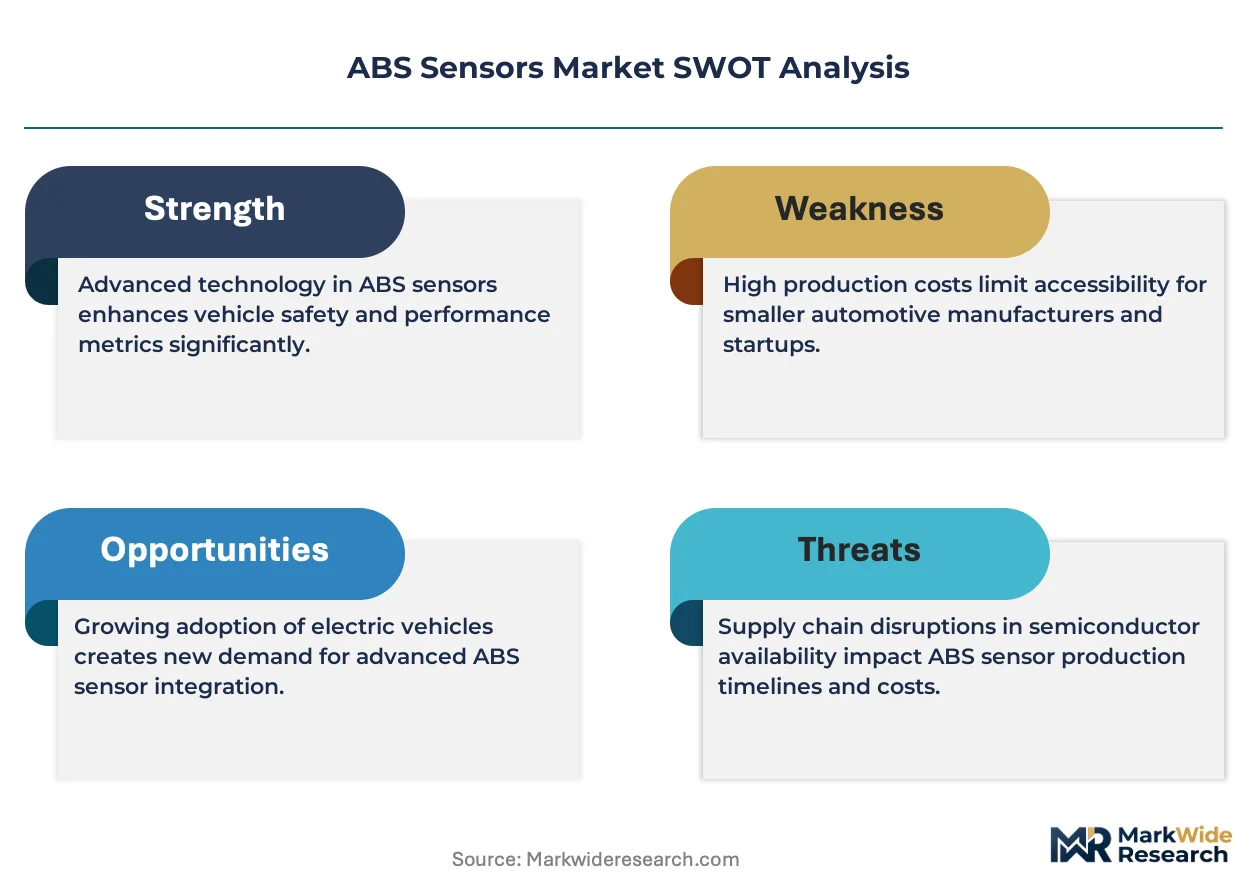
Active sensor architectures with digital output precision are compressing margins for legacy variable reluctance producers while embedding ABS sensor demand deeper into electronic stability control platforms. OEM platform-sharing agreements now consolidate braking system procurement, concentrating supplier qualification power with vehicle assemblers.
Growth Catalysts
- Electronic Stability Control Mandates:NHTSA requirements embed ABS sensors within federal safety compliance for all light vehicles sold in the United States.
- Hall-Effect Sensing:Motorcycle OEMs adopt magnetic sensing technologies for compact ABS modules targeting two-wheeler platforms above 125cc displacement.
- India's BIS Standards:Mandatory ABS fitment rules for domestic two-wheeler production are tightening product compliance requirements and reshaping supplier qualification.
Market Restraints
- Semiconductor Supply Concentration:Captive chip fabrication at Robert Bosch GmbH leaves independent sensor manufacturers exposed to foundry allocation volatility.
- Mechatronics Talent Scarcity:Production timeline extensions at multiple manufacturers trace directly to engineer shortages in electromechanical system design.
- Platform Consolidation Risk:OEM braking system procurement centralization under shared vehicle architectures reduces supplier diversification opportunities.
Strategic Opportunities
- Software-Defined Braking:Sensor hardware specification redefinition through algorithm-dependent control architectures creates value capture potential for firmware-capable suppliers.
- Hybrid Drivetrain EMI Immunity:Active sensor digital output precision addresses electromagnetic interference challenges in electrified powertrain platforms.
- Aftermarket Channel Expansion:Service bay sensor replacement demand concentrates in Germany's automotive component manufacturing corridor.
Industry Challenges
- Mechatronics Engineering Pipeline:Universities produce insufficient graduates with combined mechanical, electronic, and software competencies for sensor module development.
- Type Approval Timeline Compression:ECE R13 braking regulation and UN Regulation 78 certification cycles strain R&D resource allocation across multiple regulatory jurisdictions.
- Legacy System Integration:Backward compatibility requirements with analog ECU architectures constrain active sensor feature deployment in cost-sensitive vehicle segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ABS Sensors Market |
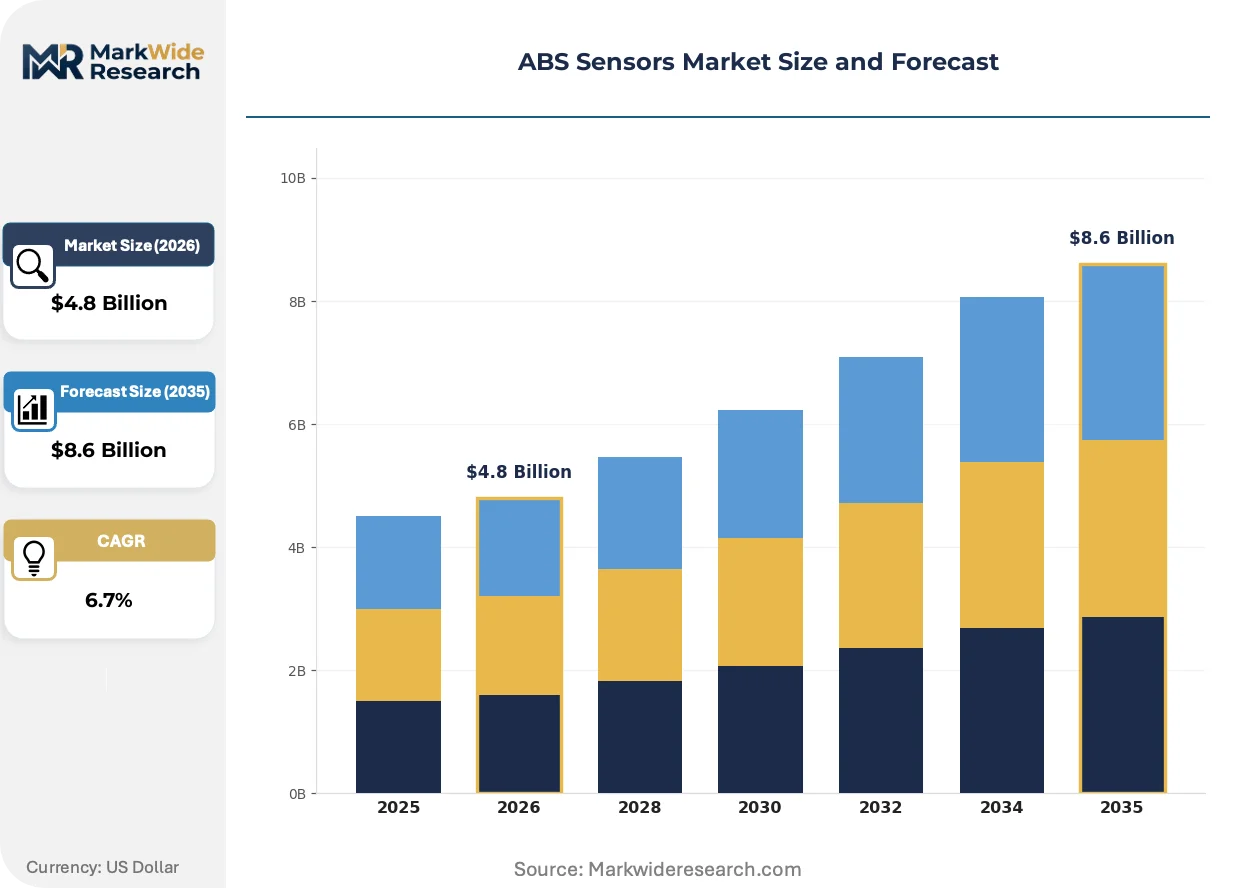
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
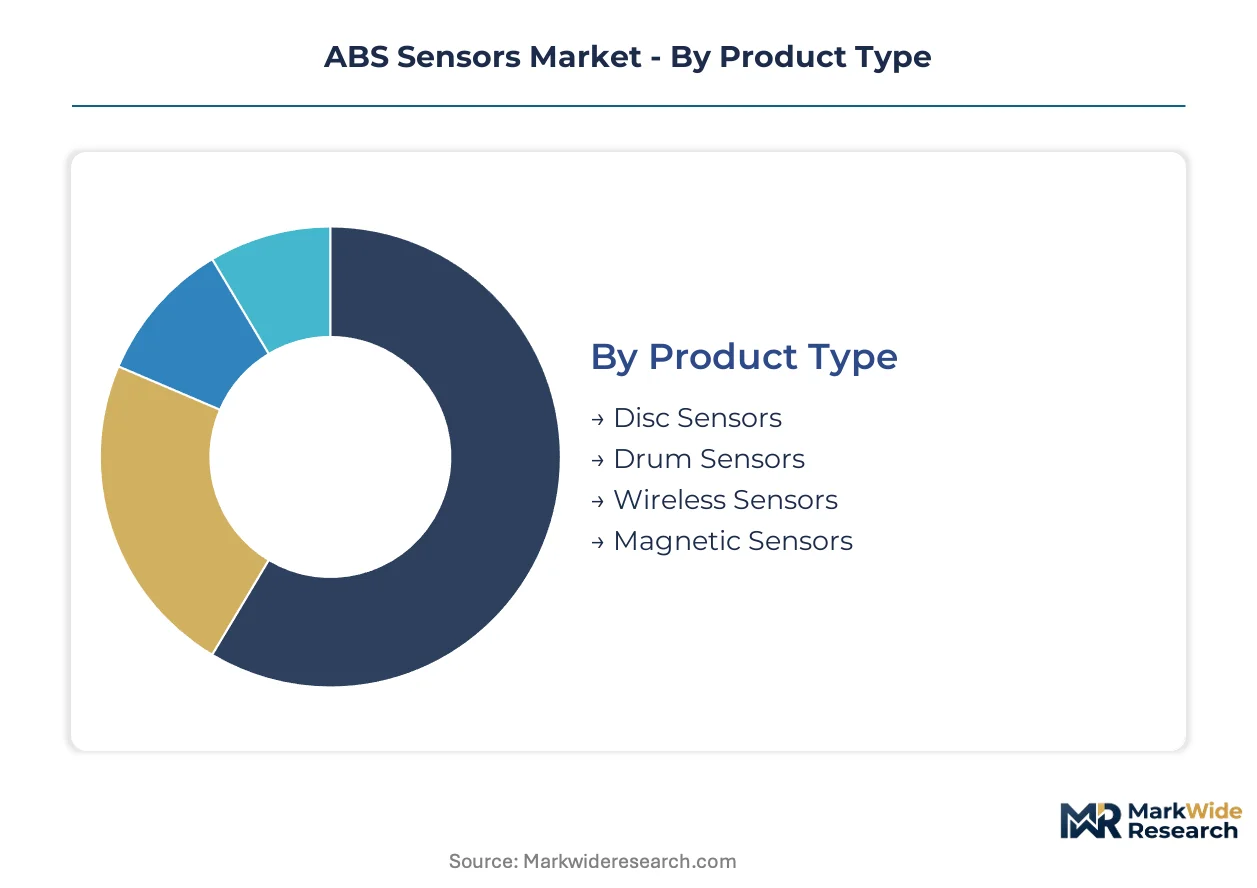
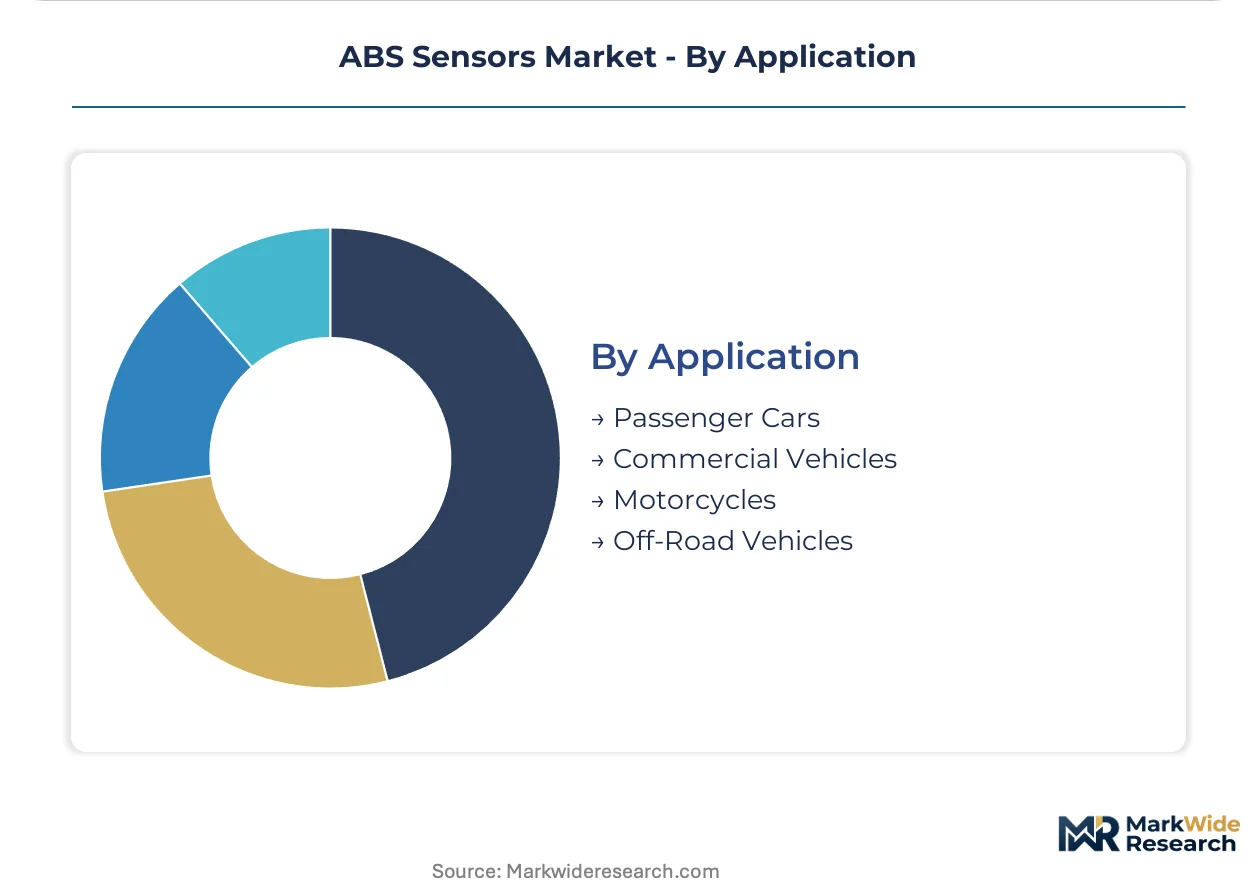
| Segmentation | Product Type: Disc Sensors, Drum Sensors, Wireless Sensors, Magnetic Sensors Technology: Active Sensors, Passive Sensors, Inductive Sensors, Capacitive Sensors End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Cars, Commercial Vehicles, Motorcycles, Off-Road Vehicles |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, ZF Friedrichshafen AG, HELLA GmbH & Co. KGaA, NXP Semiconductors, Delphi Technologies, Hitachi Automotive Systems, WABCO Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ABS Sensors Market Evolving Landscape
Digital output architectures are rewriting hardware specifications while regulatory mandates harden performance thresholds across type approvals. Supplier value capture increasingly depends on firmware integration capabilities alongside physical sensing components.
Active sensor modules with integrated signal conditioning circuits are supplanting passive variable reluctance designs in passenger car braking systems. OEM assemblers specify digital protocols for electromagnetic immunity in hybrid and electric platforms. The transition compresses revenue pools for analog-only component suppliers while elevating qualification barriers to entry.
ECE R13 braking regulation and UN Regulation 78 for motorcycles enforce minimum ABS performance thresholds across European and global type approvals. Tier-1 system integrators must demonstrate wheel slip detection accuracy under standardized test protocols. Motorcycle manufacturers above 125cc displacement face compressed redesign cycles to meet escalating certification requirements.
Vehicle assemblers now unbundle braking system procurement from chassis component sourcing, consolidating sensor purchasing under platform engineering teams. Tier-1 suppliers respond with integrated braking system architectures spanning hydraulic actuation and wheel speed sensing. Germany's automotive component manufacturing corridor hosts the densest concentration of these consolidated procurement functions.
ABS Sensors Market Segmentation
ABS sensor procurement patterns diverge sharply across vehicle platforms and supply chain tiers. Understanding these divisions reveals where specification power concentrates and which channels command margin premiums.
Product Type:
Domestic production concentrates on disc and drum variants for captive OEM supply, while wireless and magnetic architectures draw heavier export orientation toward motorcycle and commercial vehicle markets.
- Disc Sensors:These wheel-mounted units employ Hall-effect or variable reluctance principles to detect rotational speed on disc brake configurations. Passenger car OEMs in Germany's manufacturing corridor specify these for platform-sharing agreements spanning multiple nameplates. Disc sensors dominate value capture in electronic stability control integration.
- Drum Sensors:Designed for rear axle applications on light commercial vehicles and economy passenger cars, these sensors tolerate higher contamination exposure. Demand clusters in India's domestic two-wheeler and three-wheeler production under BIS mandatory fitment rules. Drum architectures face margin compression as disc brakes penetrate downstream vehicle segments.
- Wireless Sensors:Eliminating physical wiring harnesses, these modules transmit speed data via RF protocols to central receivers. Export demand from European commercial vehicle assemblers drives volume for trailer and heavy-duty platforms.
- Magnetic Sensors:Compact Hall-effect designs target motorcycle ABS modules above 125cc displacement. Japanese and Indian OEMs specify these for space-constrained fork-mounted installations.
Disc sensors hold the largest share; momentum sits with wireless architectures as commercial vehicle electrification accelerates.
Technology:
Cost tiers separate legacy analog designs from digital-output premium specifications, with active sensor architectures commanding qualification advantages in hybrid drivetrain applications.
- Active Sensors:Integrated signal conditioning circuits deliver digital output with electromagnetic immunity against hybrid powertrain interference. OEM platform engineering teams specify these for electronic stability control mandates under US NHTSA regulations. Active architectures embed suppliers deeper into firmware-dependent braking systems.
- Passive Sensors:Variable reluctance designs generate analog voltage signals without external power, serving cost-sensitive vehicle segments and legacy ECU architectures. Production concentrates in Eastern European and Mexican plants serving regional vehicle assemblers. Passive sensor margins compress as digital protocols become standard.
- Inductive Sensors:Proximity-detection variants suit off-road and construction equipment where environmental sealing exceeds passenger car requirements. German and Japanese construction machinery OEMs drive specification authority.
- Capacitive Sensors:Emerging architectures for non-contact speed detection in specialized high-temperature brake environments. Limited volume concentrates in motorsport and premium performance vehicle programs.
Active sensors dominate revenue; inductive designs are climbing the fastest in commercial vehicle expansion.
End User:
Volume concentration favors direct OEM relationships, though aftermarket channels in mature automotive corridors sustain replacement demand with different margin structures.
- OEMs:Vehicle assemblers consolidate braking system procurement under platform engineering teams, qualifying sensors alongside hydraulic actuation modules. German and US passenger car manufacturers specify active sensor architectures for electronic stability control compliance. OEM contracts span multi-year platform lifecycles with stringent change-control protocols.
- Tier-1 Suppliers:Integrated braking system architects like Continental AG and Robert Bosch GmbH source sensor modules for assembly into complete hydraulic control units. These suppliers anchor European market position through captive semiconductor fabrication and firmware integration capabilities.
- Aftermarket Providers:Service bay replacement demand concentrates in Germany's automotive component manufacturing corridor and US independent repair networks. Aftermarket sensors face price pressure from unbranded Asian imports.
- Vehicle Assemblers:Motorcycle and off-road equipment manufacturers represent a distinct procurement tier with specialized compact sensor requirements. Indian two-wheeler assemblers drive volume under mandatory ABS fitment rules.
OEMs command the largest share; aftermarket providers are gaining share fastest as vehicle parc ages in European and North American markets.
Application:
Maturity gradients separate established passenger car fitment from emerging motorcycle mandates and specialized off-road requirements.
- Passenger Cars:Electronic stability control mandates in the US and Europe embed ABS sensors as standard equipment across all light vehicle platforms. OEM platform-sharing agreements concentrate specification power with German and Japanese vehicle assemblers. Sensor counts multiply with all-wheel-drive architectures requiring four-channel monitoring.
- Commercial Vehicles:Heavy-duty braking regulations and trailer stability requirements drive multi-axle sensor configurations. European Union ECE R13 enforcement and US FMVSS 121 compliance sustain replacement demand in fleet operations.
- Motorcycles:India's BIS mandatory ABS fitment for two-wheelers above 125cc displacement has compressed redesign cycles. Japanese and Indian OEMs specify compact Hall-effect magnetic sensors for fork and swingarm mounting.
- Off-Road Vehicles:Agricultural and construction equipment manufacturers specify sealed inductive sensors for contamination-intensive environments. German and Japanese construction machinery OEMs maintain specialized qualification requirements.
Passenger cars hold the largest share; motorcycles are expanding most quickly as Asian markets tighten safety regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA electronic stability control mandates anchor United States demand, embedding ABS sensors within federal safety compliance for all light vehicle platforms. Vehicle assemblers in Michigan and Ohio consolidate braking system procurement under platform engineering teams. This regulatory foundation shapes how suppliers qualify across North American and export markets.
United States
Passenger car OEMs in Detroit and Ohio specify active sensor architectures for electronic stability control integration. NHTSA mandates embed ABS sensor demand within federal compliance frameworks for light vehicles. Michigan's automotive engineering corridor hosts concentrated procurement functions for domestic and export programs.
Germany
Continental AG and Robert Bosch GmbH anchor European market position through integrated braking system architectures. ECE R13 braking regulation enforces minimum ABS performance thresholds across type approvals. Stuttgart and Wolfsburg manufacturing corridors concentrate Tier-1 system integrator headquarters and R&D facilities.
India
Domestic two-wheeler assemblers drive volume under BIS mandatory ABS fitment rules for motorcycles above 125cc displacement. CDSCO and BIS certification requirements reshape supplier qualification timelines. Tamil Nadu and Maharashtra production clusters host motorcycle OEMs compressing redesign cycles for compliance.
Japan
DENSO Corporation specializes in Hall-effect magnetic sensing for compact motorcycle ABS applications. METI industrial standards and JIS certification frameworks govern sensor module specifications. Aichi Prefecture automotive component manufacturing maintains dense supplier ecosystems for domestic and ASEAN export markets.
China
Domestic passenger car OEMs accelerate electronic stability control adoption under MIIT automotive safety guidance. GB standards and SAMR quality supervision tighten product compliance for braking system components. Yangtze River Delta manufacturing zones concentrate sensor module assembly for local vehicle platforms.
ABS Sensors Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in ABS sensor supply. Tier-1 system integrators consolidate braking system procurement under platform-sharing agreements, compressing qualification opportunities for independent component suppliers. Two strategic archetypes dominate: captive semiconductor fabricators securing chip supply for active modules, and firmware-integrated braking system architects. Competitive moves concentrate on backward integration into semiconductor supply and technology licensing for electromagnetic immunity.
Among German-based integrated suppliers, Robert Bosch GmbH and Continental AG exemplify the captive-fabrication archetype, while DENSO Corporation represents Japanese specialization in compact magnetic sensing architectures. These three anchors occupy positions spanning European platform engineering, North American federal compliance, and Asian two-wheeler mandates. Their collective positioning illustrates how regional regulatory divergence rewards multi-jurisdictional qualification capabilities.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| ZF Friedrichshafen AG |
| HELLA GmbH & Co. KGaA |
| NXP Semiconductors |
| Delphi Technologies |
| Hitachi Automotive Systems |
| WABCO Holdings Inc. |
| Others |
Value Network & Pricing Analysis
US NHTSA electronic stability control mandates gate both supplier qualification timelines and price differentiation between active digital architectures and legacy analog modules. Tier-1 system integrators extract premium positioning through firmware-integrated braking platforms while independent sensor manufacturers face compressed margins on standardized passive designs.
Pricing Analysis
Long-term offtake contracts dominate OEM procurement, with vehicle assemblers locking in multi-year platform agreements that embed sensor specifications alongside hydraulic control units. Price differentiation rests on electromagnetic immunity certification tier and firmware integration depth, with active sensor architectures commanding substantial premiums over variable reluctance alternatives. Cost compression in passive sensor tiers is intensifying because Indian and Southeast Asian motorcycle OEMs prioritize BIS-compliant economy modules. Tier-1 braking system integrators exhibit lowest price sensitivity due to captive semiconductor fabrication, while aftermarket distributors face acute pressure from unbranded Asian imports.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific trade lanes into Germany's automotive corridor fluctuate with container availability at Rotterdam and Hamburg ports, compressing landed cost predictability for Hall-effect magnetic sensing components. Semiconductor wafer supply concentrates in Taiwan, South Korea, and Japan, while sensor module assembly clusters in Germany, China, and Mexico. Raw material dependencies span rare-earth magnets for Hall-effect elements, specialized epoxy resins for environmental sealing, and precision-machined ferromagnetic targets. Single-source vulnerability in automotive-grade microcontroller supply creates qualification bottlenecks for firmware-integrated active sensors. Distribution runs through Tier-1 braking system integrators who consolidate wheel speed sensing with hydraulic actuation under platform engineering contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service bay calibration and diagnostic software subscriptions expand faster than hardware replacement cycles as vehicle parc electrification multiplies sensor complexity. Firmware-dependent braking architectures create recurring revenue attachment opportunities beyond physical component supply.
For Market Incumbents: Consolidate semiconductor supply security through captive fabrication or long-term foundry offtake agreements as active sensor demand accelerates under hybrid drivetrain EMI requirements. Deepen backward integration into signal conditioning ASIC design to defend margin position against modular competitors. Lock in multi-year platform engineering contracts with German and Japanese OEMs before regulatory mandates tighten qualification windows further. For New Entrants and Emerging Players: Differentiate on motorcycle ABS module miniaturization for Indian and Southeast Asian two-wheeler OEMs facing compressed BIS redesign timelines. Target the aftermarket diagnostic equipment layer where service bay software subscriptions command recurring revenue with lower capital barriers than Tier-1 braking system integration. Pursue direct qualification with Indian domestic assemblers in Tamil Nadu and Maharashtra production clusters as platform-sharing agreements consolidate European supplier relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across firmware-integrated active sensor sub-segments as semiconductor content per module escalates. Long-term viability favors suppliers with demonstrated multi-jurisdictional type approval capabilities spanning NHTSA, ECE R13, and BIS certification frameworks. Acquisition target archetype: mid-cap specialists with captive Hall-effect magnetic sensing IP and existing Indian OEM relationships. Signal to watch: OEM unbundling of braking system procurement from chassis component sourcing as platform engineering teams consolidate specification authority.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Fabrication | Robert Bosch GmbH secures chip supply for active sensor modules against foundry allocation volatility. |
| Firmware Integration Investment | Suppliers embed signal conditioning algorithms to capture value from software-defined braking architectures. |
| Indian OEM Direct Qualification | Specialists bypass Tier-1 integrators to supply BIS-compliant motorcycle ABS modules under mandatory fitment rules. |
| Aftermarket Diagnostic Platform Launch | Service bay software subscriptions create recurring revenue attachment beyond hardware replacement cycles. |
| Multi-Jurisdictional Type Approval | Suppliers demonstrate NHTSA, ECE R13, and BIS certification capabilities to qualify for global platform engineering contracts. |
Research Methodology
Desk research of vehicle production databases, regulatory filing repositories, and Tier-1 supplier annual disclosures preceded structured interviews with OEM platform engineers, braking system procurement leads, aftermarket distributor operations heads, and semiconductor supply chain managers. Primary fieldwork combined telephone and video interviews across Germany, the United States, India, and Japan with secondary validation against IHS Markit registration data, customs trade records, and NHTSA compliance documentation. Bottom-up sensor unit demand estimates triangulated against top-down braking system market value allocations.
Variance decomposition across technology adoption curves, regulatory mandate implementation schedules, and platform-sharing agreement penetration shaped the analytical framework over the projection horizon. Segmentation dimensions modeled encompass product architecture, sensing technology, end-user channel, vehicle application, and regional production cluster. CAGRs derived from logistic diffusion curves fitted to electronic stability control mandate compliance trajectories and hybrid drivetrain penetration assumptions. Industry-specific forecast inputs included mechatronics engineering graduate pipeline data and semiconductor foundry capacity expansion announcements.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of electronic stability control mandates and continued OEM platform consolidation would require recalibration. Forecasts reflect assumptions regarding BIS implementation timelines for Indian two-wheeler ABS fitment and ECE R13 type approval cycle durations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Active Safety System Market
Automotive Safety and Security Systems
Two Wheeler Crash Guard Market
Automotive Safety and Security Systems
Road Speed Limiter Market
Automotive Safety and Security Systems
United States Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Automotive Smart Security Device Market
Automotive Safety and Security Systems
Automotive Airbag and Seat Belt Market
Automotive Safety and Security Systems
Automotive Pedestrian Protection System Market
Automotive Safety and Security Systems
Brake Override System Market
Automotive Safety and Security Systems
Seat Belt Pretensioner and Load Limiter Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
South Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Global Motorcycle Advanced Driver Assistance System (ADAS) Market
Automotive Safety and Security Systems
Global Automotive Electronic Stability Control Systems Market
Automotive Safety and Security Systems
Active Spoiler Market
Automotive Safety and Security Systems
Automotive Fire Suppression System Market
Automotive Safety and Security Systems
Motorcycle Anti-Lock Braking System Market