
 Automotive Inspection Tunnels Market | 2026-2036
Automotive Inspection Tunnels Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Inspection Tunnels Market Outlook
Consolidation among vehicle manufacturers is repositioning procurement leverage toward fewer, larger inspection-tunnel contracts. EISENMANN leverages its paint-system integration heritage to bundle tunnel installations with finishing-line overhauls. UVeye specializes in AI-driven optical architectures that compress cycle times for high-throughput OEM gates.
Automotive inspection tunnels are enclosed conveyor systems integrating multi-sensor arrays—laser profilometers, high-resolution optical cameras, and ultrasonic thickness gauges—to detect surface defects, dimensional deviations, and coating inconsistencies on moving vehicle bodies. The equipment operates at line speeds up to 120 units per hour with sub-millimeter resolution, serving quality-assurance mandates in paint shops and final-assembly areas. Optical technology leads installed base due to maturity in visible-spectrum defect recognition, while laser systems represent the fastest-expanding segment as OEMs adopt 3D surface mapping for electric-vehicle battery-tray verification. Permanent installations anchor margin pools through long-term service contracts, though portable configurations are gaining share among fleet operators seeking decentralized inspection capacity.
FDA guidelines for automotive-adjacent manufacturing equipment, EPA emissions-testing protocols, and CE marking under the EU Machinery Directive collectively shape tunnel design standards and cross-border market access. NHTSA safety-certification requirements in the United States further condition sensor calibration and data-retention specifications for equipment deployed at regulatory inspection stations. Stakeholders must weigh sensor-modularity investments against the risk of stranded assets as OEMs migrate toward solid-state battery platforms with altered chassis-metrology requirements.
Market Dynamics
Automotive inspection tunnels face structural recalibration as OEMs consolidate assembly-line footprints and demand sensor-agnostic platforms capable of serving both legacy internal-combustion chassis and emerging electric-vehicle architectures without full replacement.
Growth Catalysts
- EU Green Deal emissions protocols:CE marking requirements under the EU Machinery Directive now mandate inline verification of coating thickness and volatile-organic-compound containment, forcing paint-shop retrofits that bundle tunnel installations with environmental compliance upgrades.
- Stuttgart-Wolfsburg production clusters:Germany's concentrated automotive manufacturing geography generates procurement scale effects, with regional equipment vendors securing multi-year service contracts tied to precision-metrology specifications.
- AI-driven optical architectures:Machine-vision systems compress defect-detection cycle times while maintaining sub-millimeter resolution, enabling throughput gains at gates processing up to 120 units per hour.
Market Restraints
- Specialized sensor supply concentration:Laser profilometer and ultrasonic thickness-gauge components source predominantly from German and Japanese precision-optics suppliers, creating vulnerability to regional logistics disruptions.
- Substrate volatility in coating materials:Price instability in specialty polymers and ceramic-based paint formulations elevates total cost of ownership for tunnel operators maintaining calibration standards.
- Technical limitation in solid-state battery compatibility:Existing dimensional-verification algorithms optimized for stamped-steel chassis require redevelopment for aluminum-intensive battery-tray geometries.
Strategic Opportunities
- Fleet-operator decentralized inspection:Portable tunnel configurations address commercial-vehicle maintenance depots seeking autonomous quality-assurance capacity outside OEM-controlled paint-shop environments.
- Dual carbon goals in China:NMPA and MIIT emissions-verification mandates for domestic EV production create demand for inspection tunnels integrating real-time carbon-footprint telemetry.
- 3D surface-mapping convergence:Integration of laser profilometry with photogrammetric reconstruction enables single-pass verification of complex curvature geometries previously requiring multiple stations.
Industry Challenges
- Mechatronics-engineering talent scarcity:Shortage of specialists capable of calibrating multi-sensor arrays across optical, laser, and ultrasonic modalities extends commissioning timelines for new installations.
- NHTSA data-retention certification:Safety-certification requirements for equipment deployed at regulatory inspection stations impose documentation burdens that delay market entry for non-domestic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Inspection Tunnels Market |
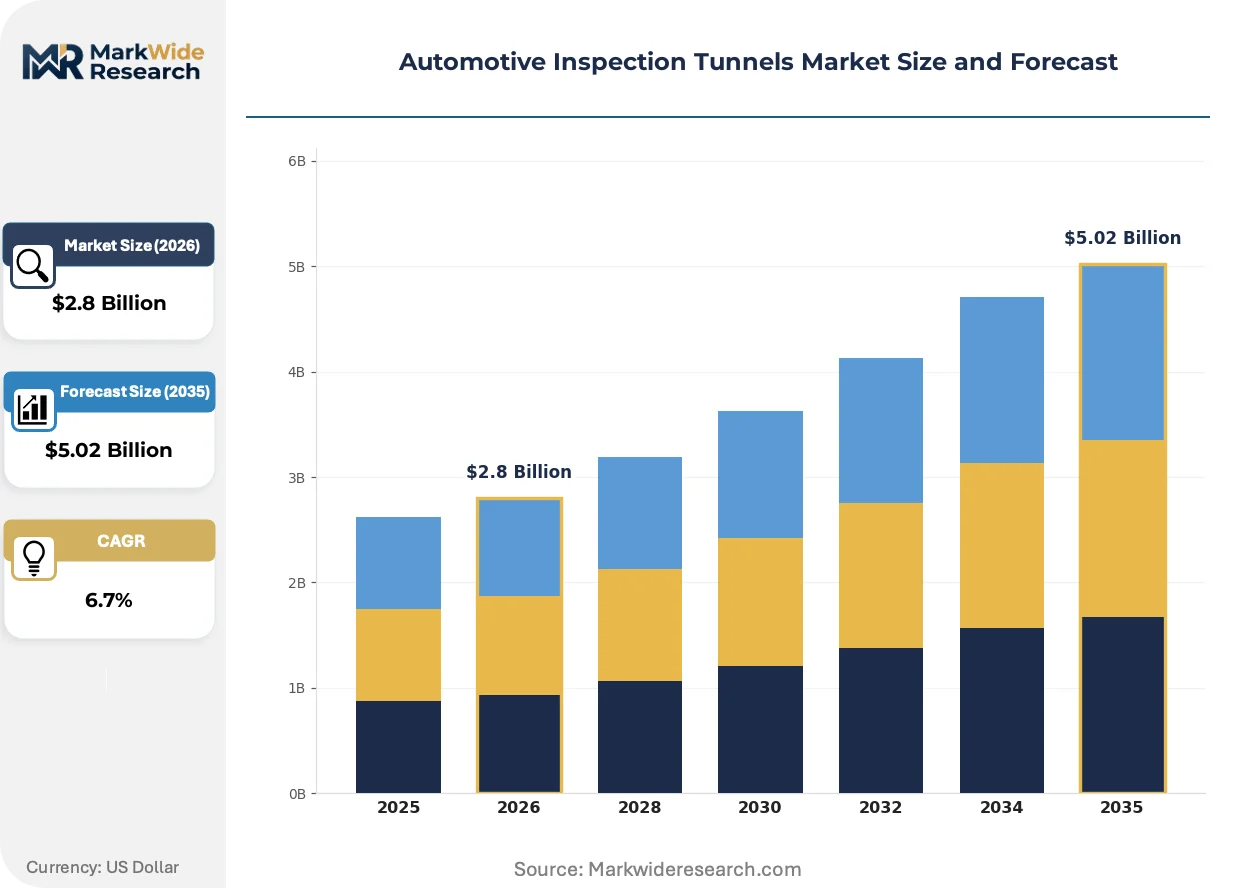
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Laser, Ultrasonic, Optical, Magnetic End User: Fleet Operators, Vehicle Manufacturers, Inspection Stations, Aftermarket Providers Installation Type: Permanent, Portable, Semi-Permanent, Integrated Maintenance Type: Routine, Predictive, Corrective, Preventive |
| Companies Covered | EISENMANN, GigaTera, Wenker, LDPI, DRB Tunnel Solutions, UVeye, Snap-on, Hunter Engineering Company, BendPak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Inspection Tunnels Market Strategic Shifts
Inspection tunnel architecture is pivoting from fixed-configuration installations toward reconfigurable platforms that accommodate evolving vehicle-form-factor requirements without structural overhaul.
Sensor-agnostic tunnel frames are modularizing to accept interchangeable laser, optical, and ultrasonic arrays through standardized mechanical interfaces and unified data buses. Tier-1 suppliers in Germany and Japan are adopting these platforms to reduce commissioning cycles for mixed-model production lines. This modularity is compressing capital-deployment timelines and extending equipment useful life across product-generation transitions.
CE marking under the EU Machinery Directive now explicitly addresses AI-enabled defect-classification systems, requiring documented algorithm-training datasets and inference-traceability for optical-inspection modules. Equipment manufacturers must maintain version-controlled software pipelines to satisfy conformity-assessment body scrutiny. Paint-shop operators in France and Italy are responding by demanding vendor-provided algorithm-audit trails as standard contract terms.
Service-contract unbundling is fragmenting traditional bundled-maintenance arrangements, with fleet operators and smaller OEMs negotiating à-la-carte sensor-calibration and software-update subscriptions. Tier-2 suppliers and independent service providers are capturing portions of aftermarket revenue previously retained by original tunnel manufacturers. This pattern is most pronounced in North American commercial-vehicle segments where third-party inspection networks operate outside captive OEM service structures.
Automotive Inspection Tunnels Market Segmentation
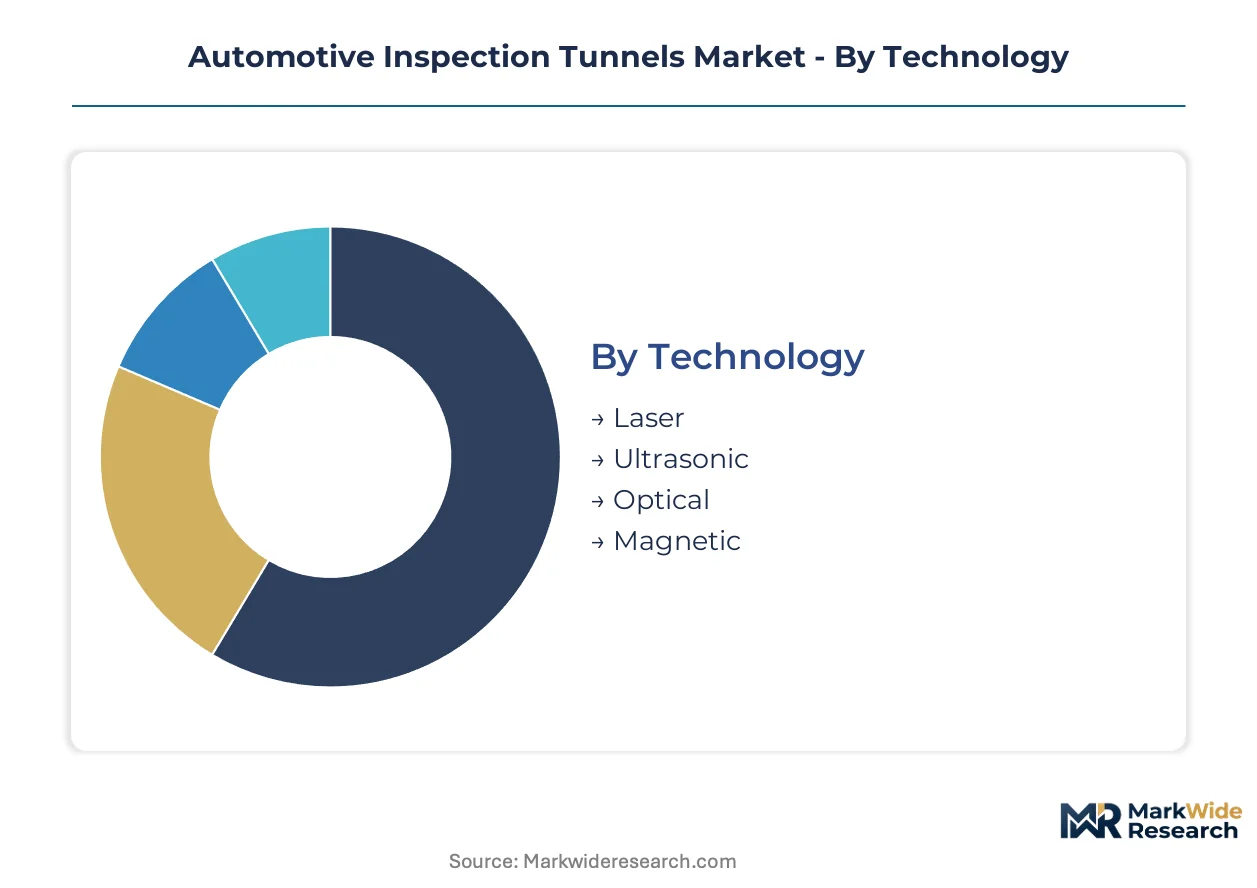
Technology choices determine resolution thresholds and throughput ceilings for automotive inspection tunnels. End-user procurement patterns diverge sharply between captive OEM installations and third-party service networks.
Technology:
Resolution requirements and chassis-material evolution differentiate buyer technology selection.
- Optical:Visible-spectrum camera arrays with sub-millimeter defect recognition dominate installed base in Stuttgart and Wolfsburg paint-shop retrofits. CE marking mandates for coating-thickness verification sustain procurement volumes as EU Green Deal protocols tighten.
- Laser:3D profilometry enables single-pass surface mapping for aluminum-intensive battery trays. OEMs in Germany adopt laser architectures fastest where electric-vehicle platforms demand geometric verification beyond optical capabilities.
- Ultrasonic:Thickness-gauge arrays penetrate multi-layer coatings for substrate integrity assessment.
- Magnetic:Eddy-current detection targets ferrous-body applications in legacy internal-combustion chassis inspection.
Volume sits with optical systems; growth tilts toward laser architectures.
End User:
Control over quality-assurance workflows shapes capital-deployment timing and service-contract structures.
- Vehicle Manufacturers:OEMs at Stuttgart-Wolfsburg clusters specify precision-metrology equipment with multi-year calibration contracts. NHTSA data-retention requirements for US regulatory gates extend procurement cycles for tunnel deployments.
- Fleet Operators:Commercial-vehicle maintenance depots outside OEM paint shops drive portable-configuration demand. Decentralized inspection capacity addresses autonomous quality-assurance needs without captive service dependencies.
- Inspection Stations:Government-mandated safety-certification facilities require sensor calibration traceability.
- Aftermarket Providers:Independent service networks negotiate à-la-carte maintenance subscriptions.
Revenue concentrates with vehicle manufacturers; fleet-operator deployments expand most quickly.
Installation Type:
Asset mobility and commissioning timelines separate procurement strategies across user categories.
- Permanent:Fixed conveyor systems anchor paint-shop infrastructure with 120-units-per-hour throughput. Long-term service contracts sustain margin pools for equipment vendors in German automotive clusters.
- Portable:Reconfigurable frames with standardized sensor interfaces address fleet-operator decentralized requirements. Modular mechanical mounts reduce commissioning cycles for mixed-model production lines.
- Semi-Permanent:Relocatable foundations serve multi-site OEM programs with shifting assembly footprints.
- Integrated:Bundled installations with finishing-line overhauls leverage paint-system vendor relationships.
Permanent installations capture capital expenditure share; portable configurations gain aftermarket traction.
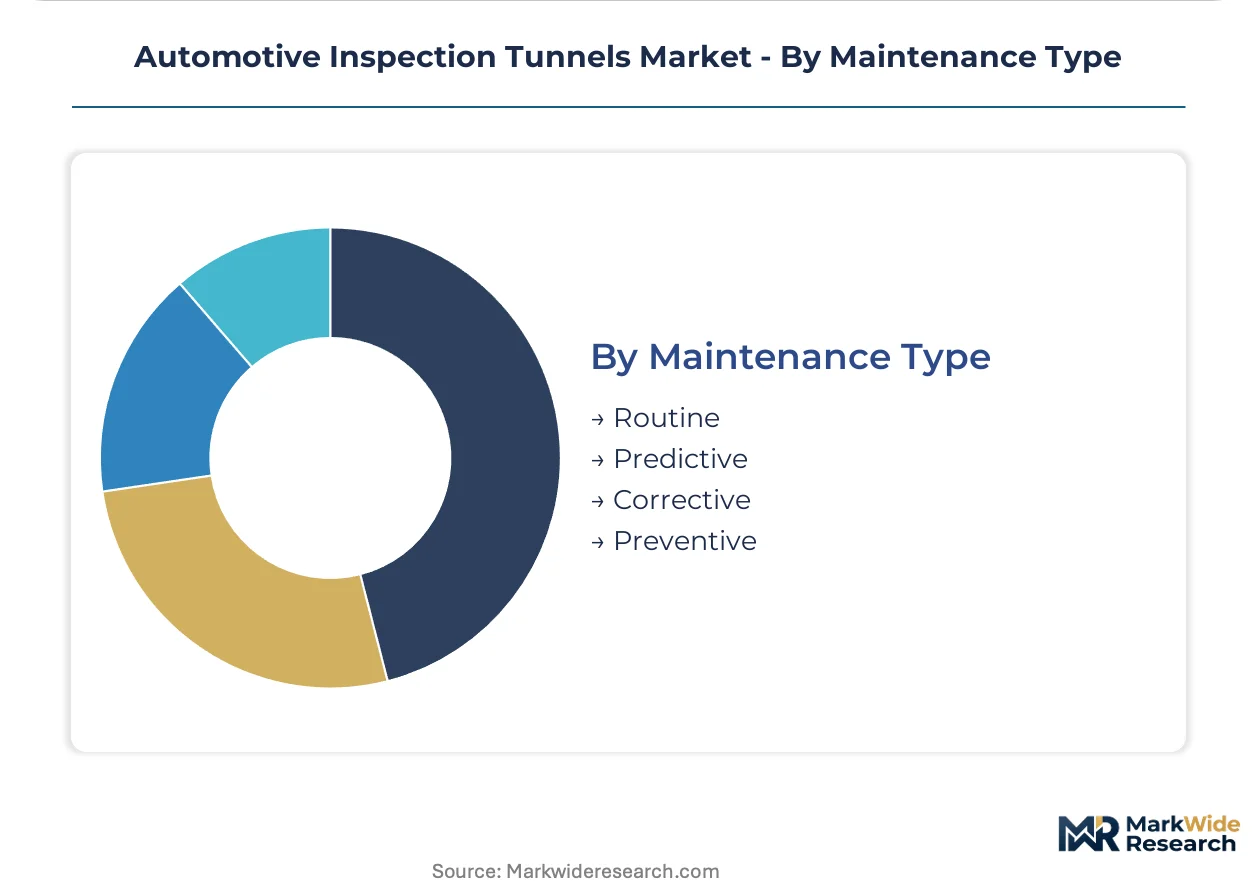
Maintenance Type:
Service-contract unbundling fragments traditional bundled arrangements across user segments.
- Routine:Scheduled calibration cycles preserve sub-millimeter resolution specifications. Tier-1 suppliers in Germany secure multi-year agreements tied to precision-metrology standards.
- Predictive:Algorithm-driven sensor-health monitoring extends equipment useful life across product-generation transitions. AI-enabled defect-classification systems require version-controlled software pipelines for CE marking compliance.
- Corrective:Failure-response protocols address unplanned downtime in high-throughput OEM gates.
- Preventive:Component-replacement schedules mitigate stranded-asset risk from solid-state battery platform migrations.
Revenue stability flows from routine contracts; predictive services climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty steel and precision-optics feedstock localities in Germany, Japan, and the United States anchor equipment manufacturing capacity for automotive inspection tunnels. These material concentrations shape regional procurement patterns and vendor-customer proximity advantages.
United States
NHTSA safety-certification requirements drive sensor calibration and data-retention specifications at regulatory inspection stations. EPA emissions-testing protocols condition tunnel design standards for cross-border market access. Detroit-Hamtramck automotive clusters generate precision-metrology equipment procurement tied to paint-shop retrofits and final-assembly quality assurance.
Germany
Stuttgart-Wolfsburg production clusters concentrate demand for sub-millimeter resolution systems processing up to 120 units per hour. CE marking under the EU Machinery Directive mandates inline verification of coating thickness and volatile-organic-compound containment. Baden-Württemberg equipment vendors secure multi-year service contracts through regional automotive manufacturing geography.
China
NMPA and MIIT emissions-verification mandates for domestic EV production create demand for inspection tunnels integrating real-time carbon-footprint telemetry. Dual carbon goals accelerate adoption of 3D surface-mapping architectures for aluminum-intensive battery-tray verification. Yangtze River Delta manufacturing hubs concentrate procurement for mixed-model production lines serving export and domestic OEM programs.
Japan
METI industrial standards and JIS certification requirements shape sensor-modularity investments and algorithm-training documentation for AI-enabled defect-classification systems. Precision-optics suppliers in Nagoya-Chubu corridors dominate laser profilometer component sourcing. Toyota City and surrounding Aichi Prefecture clusters sustain demand for optical technology with visible-spectrum defect recognition maturity.
South Korea
MFDS-equivalent automotive manufacturing equipment guidelines and domestic OEM quality protocols drive adoption of reconfigurable tunnel platforms. Seoul Capital Area production facilities require sensor-agnostic architectures capable of serving both legacy internal-combustion chassis and emerging electric-vehicle geometries. Busan-Ulsan shipbuilding-to-automotive supplier networks extend precision-metrology capabilities into commercial-vehicle inspection applications.
Automotive Inspection Tunnels Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue AI-driven optical architectures and portable configuration segments. The vendor base stratifies across paint-system integrators, precision-metrology specialists, and aftermarket service providers. Three archetypes dominate: heritage finishing-line bundlers, AI-native inspection technologists, and decentralized fleet-service enablers. Competitive positioning hinges on multi-year service contract capture and sensor-modularity roadmaps that extend equipment useful life across platform transitions.
Within the heritage integration tier, EISENMANN occupies a position exemplifying paint-system vendor relationships leveraged for bundled tunnel installations. UVeye represents the AI-native archetype through machine-vision specialization compressing cycle times at high-throughput OEM gates. Among diversified equipment fabricators, Snap-on and Hunter Engineering Company sit within aftermarket and fleet-operator service structures, anchoring portable configuration demand outside captive OEM paint-shop environments.
| Leading Market Players |
|---|
| EISENMANN |
| GigaTera |
| Wenker |
| LDPI |
| DRB Tunnel Solutions |
| UVeye |
| Snap-on |
| Hunter Engineering Company |
| BendPak |
| Others |
Value Chain & Pricing Dynamics
Laser profilometer components sourced from German and Japanese precision-optics suppliers cascade through three distinct pricing tiers downstream. OEM assembly-line contracts absorb premium calibration-included bundles, while fleet operators negotiate unbundled hardware with à-la-carte service subscriptions.
Pricing Analysis
Warranty and multi-year calibration bundling separate premium OEM installations from economy-tier portable configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service depth. Cost compression in the economy tier is intensifying because third-party service providers fragment traditional vendor maintenance revenue. Fleet operators exhibit highest price sensitivity due to decentralized capital constraints, whereas Stuttgart-Wolfsburg OEM clusters prioritize precision-metrology specifications over unit cost.
Supply Chain Analysis
Ocean freight and specialized handling for precision-optics components elevate landed costs for non-regional buyers. Manufacturing capacity concentrates in Germany, Japan, and the United States where specialty steel and sensor-component feedstocks anchor production. Laser profilometers, ultrasonic thickness gauges, and high-resolution optical cameras draw from concentrated precision-optics corridors. Single-source vulnerability in German-Japanese sensor-component supply creates exposure to regional logistics disruptions. Distribution runs through captive OEM procurement channels and independent aftermarket networks serving fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive inspection tunnel vendors face a consolidation play as sensor-agnostic platform requirements force out specialists lacking modular architecture roadmaps.
For Market Incumbents: Deepen sensor-modularity investments to extend equipment useful life across solid-state battery platform transitions. Capture multi-year calibration contracts in Stuttgart-Wolfsburg clusters before third-party service providers fragment aftermarket revenue. Threat from AI-native inspection technologists compressing cycle times demands accelerated machine-vision R&D spending. For New Entrants and Emerging Players: Fleet-operator channel partners offer the most penetrable entry point outside captive OEM paint-shop procurement structures. Target portable-configuration demand in North American commercial-vehicle segments where decentralized inspection capacity gaps persist. White-space exists in predictive maintenance software subscriptions unbundled from hardware sales. For Investors and Strategic Acquirers: NHTSA data-retention certification delays for non-domestic suppliers is the leading indicator that regulatory moats are widening for established players with compliance infrastructure. Five-to-ten year viability favors precision-metrology specialists with algorithm-audit-trail capabilities for CE marking conformity. Watch for OEM consolidation announcements reducing qualified vendor pools as acquisition timing signals.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Modularity Platform Development | Extends equipment useful life across ICE-to-EV platform transitions without full replacement. |
| Algorithm-Audit-Trail Infrastructure | Satisfies CE marking conformity-assessment scrutiny for AI-enabled defect-classification systems. |
| Predictive Maintenance Software Launch | Captures aftermarket revenue fragmentation from traditional bundled service contracts. |
| Fleet-Operator Channel Partnership | Penetrates decentralized inspection demand outside captive OEM paint-shop environments. |
| Precision-Optics Supplier Integration | Mitigates single-source vulnerability in German-Japanese laser profilometer component supply. |
Study Parameters
SEC filings, OEM production databases, and EU Machinery Directive regulatory archives formed the secondary backbone of this analysis. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket service heads, and precision-metrology equipment vendors combined with secondary validation. Bottom-up and top-down triangulation reconciled installation-unit estimates with revenue aggregation across technology and end-user segments.
Bottom-up modeling tracked individual contract values and installation timelines across permanent, portable, and semi-permanent configurations. Top-down validation cross-referenced precision-metrology equipment procurement patterns in Stuttgart-Wolfsburg and Detroit-Hamtramck clusters. Segmentation dimensions included technology type, end-user category, installation mobility, and maintenance contract structure. CAGRs derived from regression analysis of historical procurement cycles and projected EV platform transition timelines. Forecast inputs incorporated coating-material substrate volatility and solid-state battery chassis-metrology requirement shifts.
Caveats apply where NHTSA certification timeline extensions or solid-state battery platform acceleration could materially shift the outlook. Forecasts reflect assumptions about OEM consolidation pace and sensor-modularity adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market
Automotive Safety and Security Systems
Europe Airbag Systems Market
Automotive Safety and Security Systems
India Airbag Systems Market
Automotive Safety and Security Systems
Africa Vehicle Tracking System Market
Automotive Safety and Security Systems
In-Cabin Monitoring System (ICMS) Market
Automotive Safety and Security Systems
Automotive Anti Lock Braking System and Electronic Stability Control Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
Automotive Black Boxes Market
Automotive Safety and Security Systems
Engine Braking System Market
Automotive Safety and Security Systems
Automotive Shielding Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market
Automotive Safety and Security Systems
Automotive Vacuumless Braking Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Crane Collision Avoidance Devices Market
Automotive Safety and Security Systems
Automotive Brake Override System Market
Automotive Safety and Security Systems
Driving Armor Market