
 Bottle-Capping Equipment Market | 2026-2036
Bottle-Capping Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Bottle-Capping Equipment Market Outlook
ISO 9001 quality management certification is bifurcating the competitive landscape into qualified system integrators and non-certified assemblers. Krones AG leverages its integrated filling-capping lines to dominate high-speed beverage installations across Europe. Syntegon sustains R&D intensity in pharmaceutical-grade containment systems, while Accutek Packaging Equipment Companies specializes in compact bench-top units for craft producers and regional contract packers.
Bottle-capping equipment comprises machinery designed to apply, torque, and seal closures onto containers with precision tolerances typically ranging from 0.5 to 5 Nm, ensuring hermetic integrity across carbonated, still, and sensitive product categories. Fully automatic cappers command the largest installed base in high-volume beverage plants where throughput exceeds 60,000 bottles per hour, though rotary capping technology is displacing mechanical cam systems in premium pharmaceutical lines due to servo-driven torque repeatability. Electric capping segments attract margin pools from cosmetic manufacturers seeking programmable force profiles for fragile glass packaging.
FDA Title 21 CFR Part 11 and EMA Annex 15 guidelines shape validation documentation burdens for pharmaceutical end users, while EU Machinery Directive 2006/42/EC mandates CE-marked safety interlocks on all exported European equipment. China's SAMR enforces GB standards for food-contact materials that cascade into capping component specifications. Stakeholders must weigh regional certification portfolios against modular upgrade architectures as sustainability mandates tighten material traceability requirements.
Market Dynamics
Servo-driven torque control is rewriting equipment specifications as pharmaceutical bottlers abandon mechanical cam systems for repeatable force profiling at 0.1 Nm tolerances. This precision imperative cascades from FDA validation requirements through to component supplier selection, compressing margins for assemblers lacking metrology capabilities.
Growth Catalysts
- EMA Annex 15 validation protocols:European pharmaceutical manufacturers are retrofitting lines with audit-trail-capable cappers to satisfy documentation burdens for sterile liquid packaging.
- Carbonated soft drink bottlers in Mexico:Export-oriented production hubs are installing high-speed rotary systems to serve North American private-label contracts.
- Electric torque motors:Cosmetic glass packers are specifying programmable force curves to eliminate stress fractures on premium fragrance bottles.
Market Restraints
- Stainless steel alloy volatility:316L grade price swings directly compress margins for European equipment fabricators locked into fixed-price contracts.
- Control system supplier concentration:German and Japanese PLC manufacturers command 70% of motion-control architectures for precision capping lines.
- REACH substance restrictions:EU lubricant formulations face reformulation timelines that delay CE-marked equipment deliveries.
Strategic Opportunities
- India's PLI scheme for food processing:Domestic beverage bottlers qualify for equipment depreciation incentives that favor automated capping investments.
- Aseptic containment convergence:Isolator-integrated capping systems combine barrier technology with servo torque control for biologic vial filling.
- Direct-to-contract-packer sales channels:Equipment vendors are bypassing distributor networks to capture margin from regional craft distillers.
Industry Challenges
- Servo tuning expertise scarcity:Field service engineers capable of calibrating multi-axis torque profiles command premium compensation in tight labor markets.
- Legacy mechanical line integration:Retrofitting 1990s cam-driven bottling halls with electric cappers requires custom adapter fabrications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottle-Capping Equipment Market |
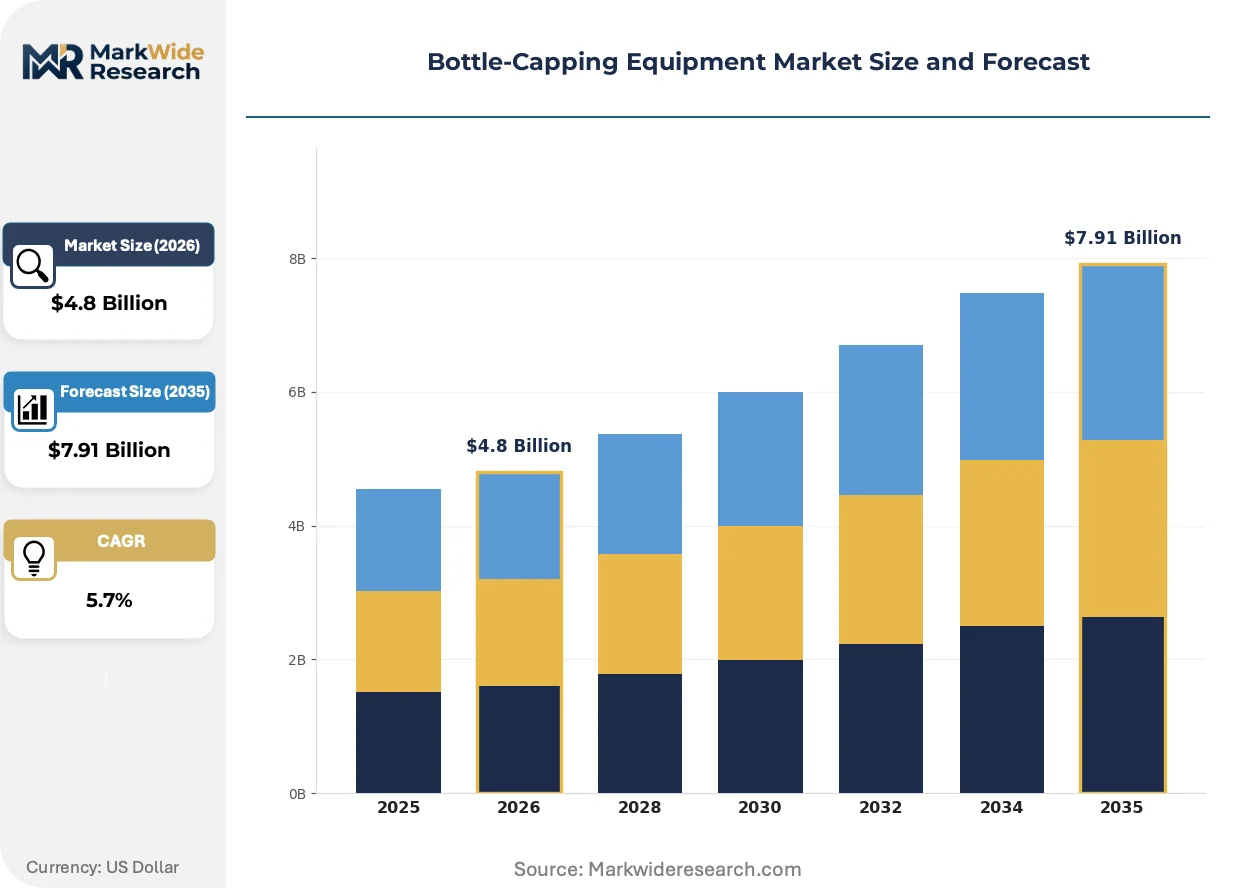
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Cappers, Semi-Automatic Cappers, Fully Automatic Cappers, Bench-Top Cappers End User: Beverage Industry, Pharmaceutical Companies, Food Processing, Cosmetic Manufacturers Technology: Mechanical Capping, Pneumatic Capping, Electric Capping, Rotary Capping Application: Glass Bottles, Plastic Bottles, Metal Containers, Specialty Packaging |
| Companies Covered | Krones AG, Closure Systems International, Accutek Packaging Equipment Companies, Sidel Group, Syntegon, ProMach, Coesia, Barry-Wehmiller Group, Arol Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottle-Capping Equipment Market Strategic Shifts
Digital torque traceability is becoming the non-negotiable specification as pharmaceutical auditors demand millisecond-level force logging for every sealed container.
Brushless DC servo motors with integrated encoders are supplanting pneumatic torque tools in pharmaceutical cleanroom installations. Pfizer and Moderna contract manufacturers specify these systems for mRNA vaccine vial capping where 0.5 Nm repeatability prevents aluminum seal deformation. The technology is compressing acceptance testing timelines from six weeks to ten days.
FDA Title 21 CFR Part 11 electronic record requirements now extend to capping equipment software revisions. Pharmaceutical end users must revalidate entire lines when vendors issue firmware updates, creating documentation backlogs. Aseptic liquid manufacturers in New Jersey and North Carolina are demanding locked software configurations to minimize requalification cycles.
Equipment-as-a-service contracts are displacing capital purchase models among mid-sized contract packers. Monthly payments covering maintenance and calibration appeal to craft beverage producers in Colorado and Oregon with constrained balance sheets. This financing structure concentrates vendor risk on uptime guarantees rather than hardware margins.
Bottle-Capping Equipment Market Segmentation
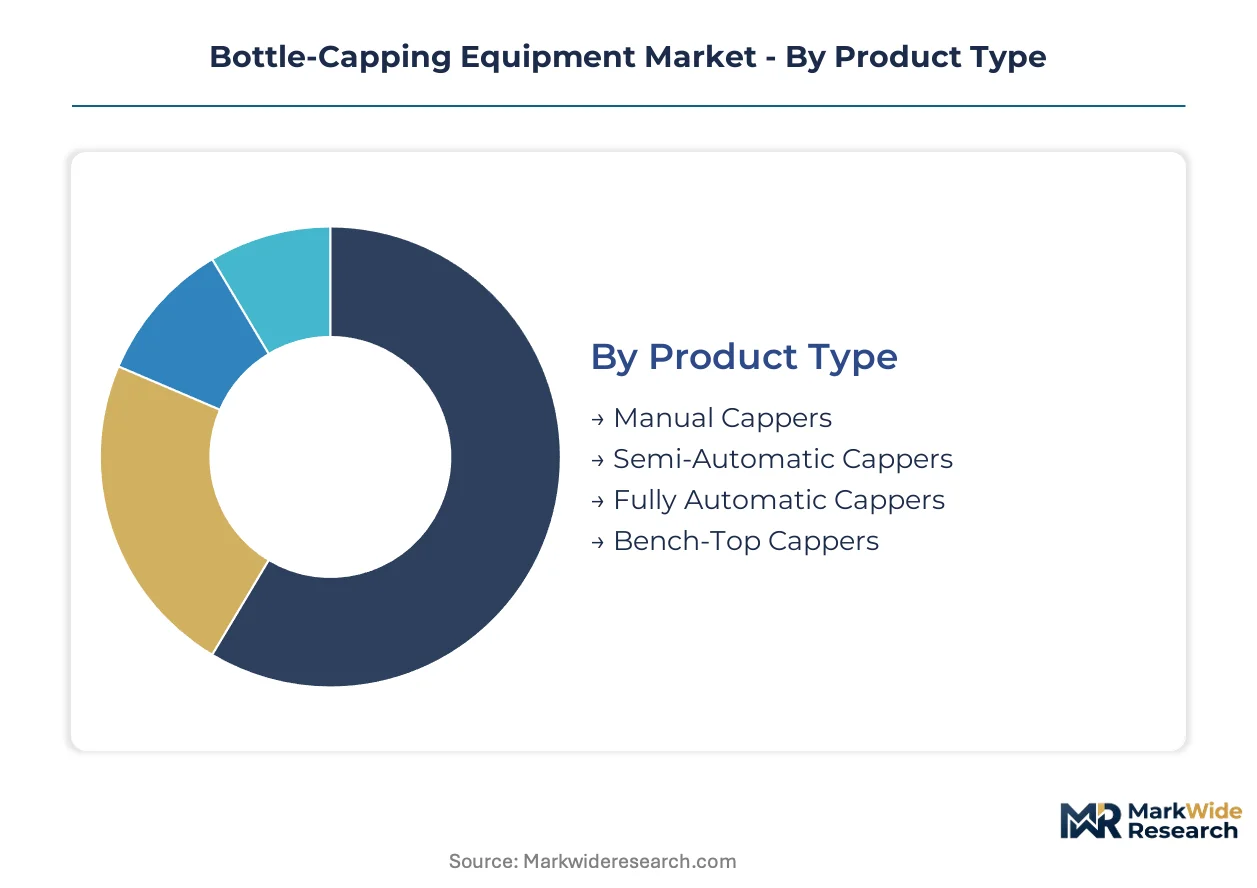
Segmentation in bottle-capping equipment reflects divergent validation burdens and throughput requirements across regulated industries. Equipment specifications bifurcate sharply between pharmaceutical-grade servo systems and beverage-grade mechanical lines.
Product Type:
FDA Title 21 CFR Part 11 and EMA Annex 15 validation protocols create tiered entry barriers that separate audit-trail-capable systems from basic mechanical units.
- Fully Automatic Cappers:High-speed rotary systems with integrated torque monitoring and reject stations process 60,000+ bottles hourly in carbonated beverage plants. German export-oriented facilities specify these for North American private-label contracts where throughput guarantees dominate procurement.
- Semi-Automatic Cappers:Intermediate systems with operator-fed infeed and automated torque application serve regional contract packers in Colorado and Oregon. Equipment-as-a-service financing concentrates here among craft distillers with constrained capital budgets.
- Manual Cappers:Hand-operated bench units for micro-batch pharmaceutical compounding and artisan food producers.
- Bench-Top Cappers:Compact electric units for R&D laboratories and pilot-scale cosmetic formulation.
Fully Automatic Cappers handles the majority of throughput; Bench-Top Cappers is expanding most quickly among craft producers.
End User:
Customer procurement authority varies by scale, with multinational beverage bottlers centralizing specifications while pharmaceutical quality units retain veto power over validation documentation.
- Beverage Industry:Carbonated soft drink and bottled water bottlers in Mexico deploy high-speed rotary systems for export production. FDA food-contact material rules cascade into stainless steel 316L specifications for all North American-bound equipment.
- Pharmaceutical Companies:mRNA vaccine manufacturers specify brushless DC servo motors with 0.1 Nm torque repeatability for aluminum seal integrity on glass vials. Pfizer and Moderna contract manufacturers in New Jersey and North Carolina demand locked software configurations to minimize requalification cycles.
- Food Processing:Sauce and condiment packers prioritize washdown-rated enclosures for sanitary compliance.
- Cosmetic Manufacturers:Premium fragrance houses specify programmable force curves to prevent stress fractures on decorative glass packaging.
Beverage Industry commands the largest installed base; Pharmaceutical Companies shows the steepest specification escalation on torque precision.
Technology:
Motion control architectures concentrate supply risk among German and Japanese PLC manufacturers, shaping vendor selection for precision applications.
- Electric Capping:Servo-driven torque systems with integrated encoders deliver programmable force profiles for fragile glass and aluminum containers. Cosmetic manufacturers in premium fragrance segments specify these for deformation prevention on high-value packaging.
- Rotary Capping:Continuous-motion turret designs with multi-head configurations maximize throughput in high-volume beverage installations. Mexico's export hubs favor these for private-label contract efficiency.
- Mechanical Capping:Cam-driven legacy systems still serving low-margin regional bottlers with minimal validation requirements.
- Pneumatic Capping:Compressed-air torque tools being displaced by electric alternatives in pharmaceutical cleanrooms due to oil contamination risks.
Electric Capping captures the specification upgrade cycle; Rotary Capping retains volume leadership in emerging economy beverage investments.
Application:
Container material properties dictate sealing mechanics, with thermal expansion coefficients and thread geometry driving head design specialization.
- Glass Bottles:Rigid containers requiring precise torque control to prevent thread cracking or seal deformation. Pharmaceutical vial capping demands 0.5 Nm repeatability for aluminum seal integrity on mRNA vaccine products.
- Plastic Bottles:PET and HDPE containers with molded threads tolerating wider torque variance in carbonated beverage applications. China's SAMR GB standards for food-contact materials cascade into capping component specifications for domestic production.
- Metal Containers:Aluminum and steel cans with rolled threads for industrial chemical and aerosol packaging.
- Specialty Packaging:Biodegradable and composite containers for sustainability-focused cosmetic and food brands.
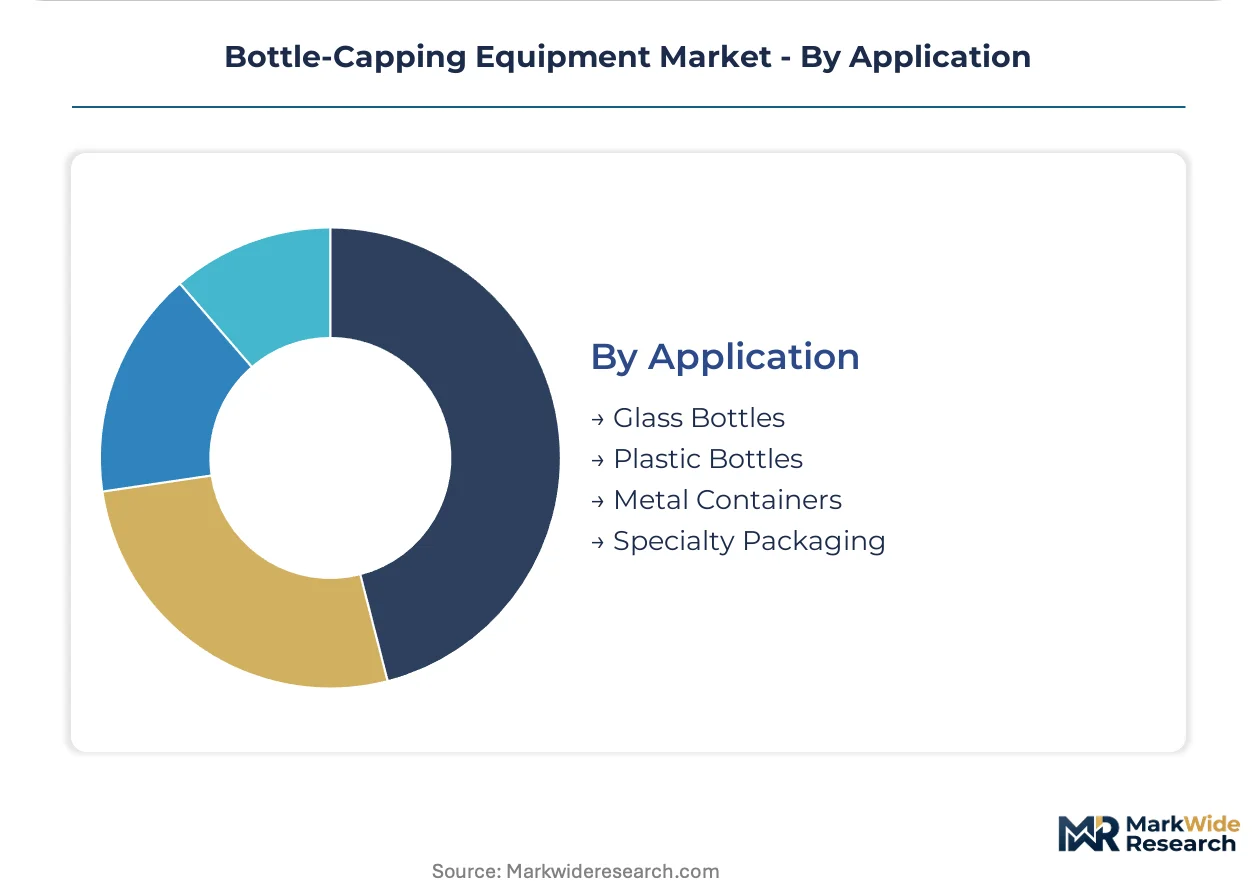
Glass Bottles imposes the tightest torque tolerances; Plastic Bottles accounts for the largest unit volume in emerging market beverage expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturers in New Jersey and North Carolina concentrate demand for servo-driven validation-capable systems, while export-oriented beverage bottlers in Mexico and Germany drive high-speed rotary installations. China's domestic production hubs and India's food processing incentives round out the geographic buyer mix.
United States
mRNA vaccine manufacturers in New Jersey and North Carolina specify brushless DC servo motors with locked software configurations to minimize FDA requalification cycles. FDA Title 21 CFR Part 11 mandates electronic record-keeping for all pharmaceutical capping equipment. The Research Triangle and Boston-Worcester corridor host contract manufacturers demanding 0.1 Nm torque repeatability for sterile vial sealing.
Germany
Export-oriented beverage facilities specify high-speed rotary systems for North American private-label contracts where throughput guarantees dominate procurement. EU Machinery Directive 2006/42/EC mandates CE-marked safety interlocks on all exported equipment. The Baden-Württemberg and Bavaria industrial corridors concentrate precision equipment fabricators serving pharmaceutical and cosmetic end users.
China
Domestic beverage bottlers deploy rotary capping technology for carbonated soft drink production serving internal market expansion. SAMR enforces GB standards for food-contact materials that cascade into capping component specifications. The Yangtze River Delta and Pearl River Delta clusters concentrate equipment demand from export-oriented producers.
Mexico
Carbonated soft drink bottlers install high-speed rotary systems to serve North American private-label export contracts. NAFTA-origin content rules influence equipment sourcing decisions for US-bound production. The Bajío Region and Nuevo León host concentrated beverage manufacturing investments with automated capping requirements.
India
Domestic beverage bottlers qualify for equipment depreciation incentives under the PLI scheme for food processing that favor automated capping investments. BIS certification requirements shape component specifications for food-contact equipment. Maharashtra and Gujarat industrial corridors concentrate demand from regional contract packers upgrading from manual systems.
Bottle-Capping Equipment Market Competitive Environment
Player mix skews toward diversified industrial conglomerates with filling-line integration capabilities alongside specialized precision equipment fabricators. Tiered competitive structure separates audit-trail-capable pharmaceutical-grade system integrators from beverage-focused throughput specialists. Dominant archetypes include integrated line providers, servo-precision specialists, and regional bench-top equipment assemblers. Competitive moves concentrate on vertical integration into filling-capping line integration and geographic expansion through distributor bypass strategies.
Within the integrated line provider tier, Krones AG and Sidel Group exemplify scale-driven positions spanning high-speed beverage installations across European export hubs. Syntegon occupies a position within the pharmaceutical-grade containment specialist archetype, while Accutek Packaging Equipment Companies represents the compact bench-top segment serving craft producers and regional contract packers with constrained capital budgets. Closure Systems International and ProMach anchor mid-market positions across North American beverage and food processing applications.
| Leading Market Players |
|---|
| Krones AG |
| Closure Systems International |
| Accutek Packaging Equipment Companies |
| Sidel Group |
| Syntegon |
| ProMach |
| Coesia |
| Barry-Wehmiller Group |
| Arol Group |
| Others |
Value Chain & Pricing Dynamics
Ninety-day stainless steel 316L inventory cycles at German fabricators concentrate pricing power among CE-certified system integrators while compressing margins for non-qualified assemblers locked into fixed-price contracts. This lead-time band feeds directly into cost-plus contract structures where alloy indexation clauses determine quarterly adjustment mechanics.
Pricing Analysis
Cost-plus contracts with London Metal Exchange stainless steel indexation dominate procurement between European equipment fabricators and beverage bottlers in Mexico. Three-tier pricing structure across FDA-validated pharmaceutical systems, CE-marked food-grade lines, and non-certified mechanical units separates audit-trail-capable integrators from regional assemblers. Pricing pressure stems from 316L alloy volatility that squeezes fixed-contract margins. Craft distillers in Colorado and Oregon exhibit highest price sensitivity through equipment-as-a-service uptake, while mRNA vaccine manufacturers in New Jersey accept premium positioning for locked software configurations.
Supply Chain Analysis
Forty-five day component lead times for brushless DC servo motors from Japanese and German PLC manufacturers anchor supply risk in precision capping architectures. Manufacturing concentrates in Germany, China, and Italy for turret fabrication, with Taiwan and South Korea supplying motion-control electronics. Stainless steel 316L from European mills, servo encoders from Japanese manufacturers, and CE-marked safety interlocks constitute critical input dependencies. Single-source vulnerability in PLC architectures threatens delivery timelines. Distribution runs through direct-to-contract-packer channels that bypass traditional distributor networks for regional craft producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where FDA Title 21 CFR Part 11 validation entrenchment creates switching costs that lock pharmaceutical end users into multi-year requalification cycles.
For Market Incumbents: Consolidate servo-tuning expertise through captive training academies in Baden-Württemberg and Bavaria to offset field engineer scarcity threatening service revenue. Deepen backward integration into brushless DC motor production to reduce dependency on Japanese PLC suppliers. EMA Annex 15 documentation burdens and firmware revalidation cycles reinforce installed base stickiness against emerging electric capping specialists. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for bench-top capping units offer lowest regulatory barrier to entry among pharmaceutical-grade segments. Target India's PLI scheme beneficiaries in Maharashtra and Gujarat industrial corridors where depreciation incentives accelerate automation investments. Pursue equipment-as-a-service financing structures for craft beverage producers in Colorado and Oregon with constrained capital budgets. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because validation documentation burdens and locked software configurations create decade-long customer relationships resistant to displacement. Acquire mid-cap servo-precision specialists with existing FDA master files and EMA technical dossiers. Monitor India's PLI scheme expansion announcements as inflection signal for automated capping demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Production | Captive supply of brushless DC motors reduces dependency on Japanese PLC manufacturers for pharmaceutical lines. |
| FDA Master File Acquisition | Pre-submitted validation documentation accelerates pharmaceutical customer qualification timelines versus de novo submissions. |
| Equipment-as-a-Service Launch | Monthly payment structures unlock craft distiller segments in Colorado and Oregon with constrained balance sheets. |
| CE Marking Fast-Track Investment | EU Machinery Directive 2006/42/EC pre-certification opens German export-oriented beverage facilities to North American contracts. |
| Isolator-Integrated Capping Development | Aseptic containment convergence with servo torque control captures biologic vial filling demand from Pfizer and Moderna contract manufacturers. |
Study Parameters
A spread of perspectives from equipment procurement managers at beverage bottlers, pharmaceutical quality assurance directors, contract packer operations heads, and servo motor component suppliers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA technical dossiers, SEC 10-K equipment vendor disclosures, and EU customs trade data. Bottom-up unit economics triangulated against top-down market sizing across the projection horizon.
Segmentation dimensions modeled include automation level, end-use industry, torque control technology, container material, and regional regulatory cluster. CAGRs derived from installed base turnover rates, replacement cycle analysis, and greenfield capacity announcements across the analysis window. Industry-specific forecast inputs incorporated PLI scheme incentive trajectories in India and mRNA vaccine manufacturing capacity expansion in New Jersey and North Carolina.
Decision-makers should treat outputs as directional under assumptions of sustained FDA validation stringency and stable stainless steel alloy pricing; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Heat Sealing Equipment Market
Packaging Equipment
Laser Coding Equipment Market
Packaging Equipment
Packaging Tensioner Market
Packaging Equipment
Hot Melt Equipment Market
Packaging Equipment
Strapping and Banding Equipment Market
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
Powder Filling Equipment Market
Packaging Equipment
Shrink Sleeve Labeling Equipment Market
Packaging Equipment
Vacuum Fillers Market
Packaging Equipment
Hand Sealers Market
Packaging Equipment
Thermal Impulse Sealers Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Bespoke Dispenser Market
Packaging Equipment
Beverage Packaging Equipment Market
Packaging Equipment
Global End-Of-Line Packaging Market
Packaging Equipment
Dispensing Booth Market