
 Hand Sealers Market | 2026-2036
Hand Sealers Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Sealers Market Insights
Buyer concentration among packaging service providers is hardening as mid-sized contract packers consolidate purchasing volumes to secure equipment discounts and technical support packages. IMPAK Corporation leverages its specialization in vacuum sealing systems to serve pharmaceutical and electronics clients with cleanroom-compatible configurations. Syntegon Technology GmbH anchors its position through extensive R&D investment in automated band sealing lines for high-throughput food operations. PAC Machinery differentiates by controlling distribution channels across North American industrial supply networks.
Hand sealers are electromechanical devices that apply controlled heat and pressure to thermoplastic films or laminates to create hermetic closures, typically operating at temperatures between 100°C and 300°C depending on material composition. Their primary purpose is to preserve product integrity, extend shelf stability, and prevent contamination across packaged goods supply chains. Impulse sealers dominate the installed base due to lower energy consumption and reduced burn risk in manual operations, while vacuum sealers capture expanding margin pools in food and pharmaceutical applications where oxygen exclusion determines product validity. Band sealers sustain growth in continuous-flow manufacturing environments where conveyor-integrated throughput outweighs unit flexibility.
FDA compliance requirements for pharmaceutical packaging integrity and USDA sanitation standards for food-contact equipment shape product design specifications and validation protocols for manufacturers serving regulated industries. The EU Machinery Directive and CE marking obligations additionally govern electrical safety and electromagnetic compatibility for equipment imported into European markets. Stakeholders must monitor evolving extended producer responsibility frameworks and material traceability mandates that will determine which sealing technologies qualify for sustainable packaging certifications.
Market Dynamics
Contract packaging consolidation across Southeast Asian manufacturing clusters is concentrating procurement volumes and reshaping equipment vendor relationships, while EU Packaging and Packaging Waste Regulation compliance deadlines compress material qualification timelines for flexible sealing applications.
Growth Catalysts
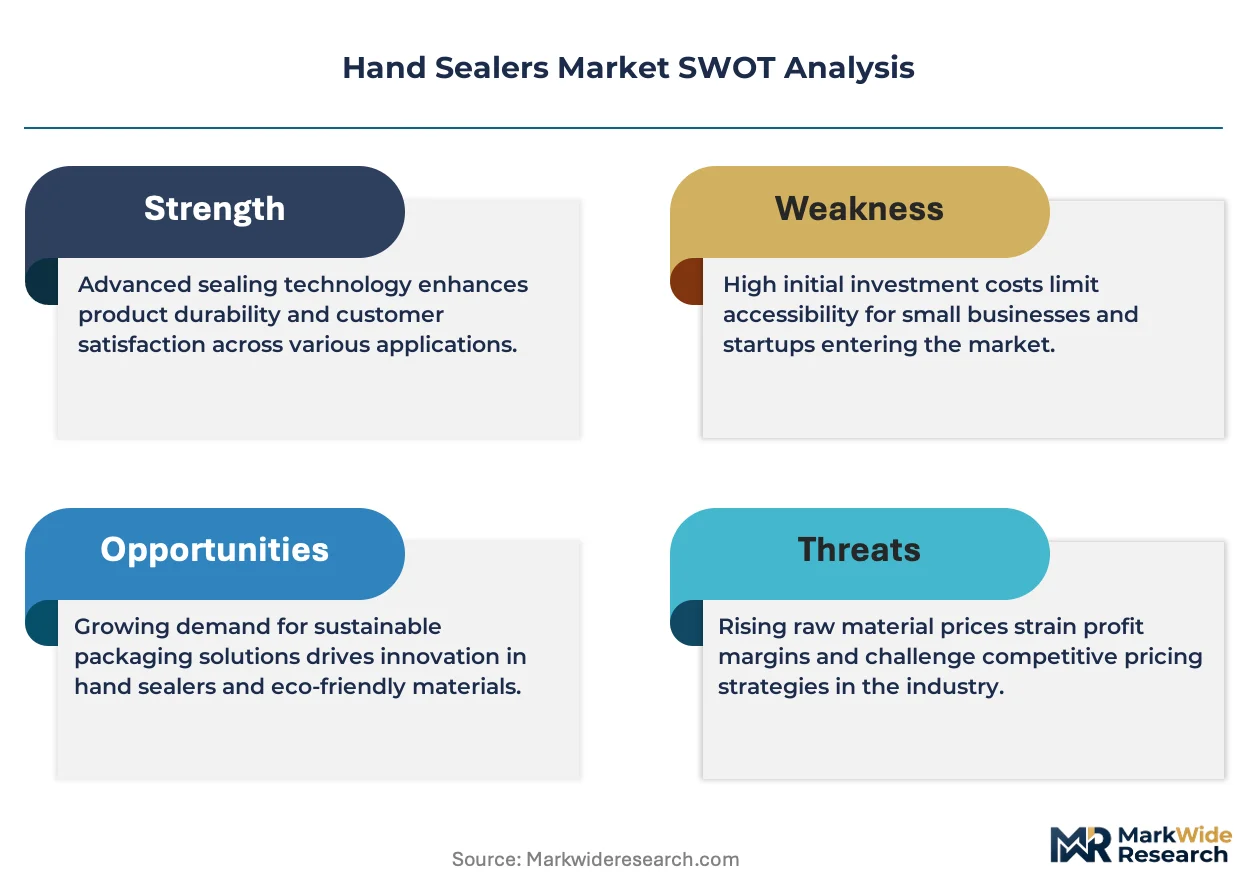
- EU Packaging and Packaging Waste Regulation:Material traceability mandates for flexible packaging closures are accelerating equipment replacement cycles among European food processors seeking certification-ready sealing systems.
- Contract packaging services:Rapid scaling of third-party packaging operations in Vietnam and Indonesia is generating concentrated demand for portable impulse sealers with rapid heat recovery specifications.
- Cleanroom-compatible configurations:Pharmaceutical and electronics manufacturers are specifying vacuum sealing systems with validated contamination control for hermetic packaging of sensitive components.
Market Restraints
- Heating element supply concentration:Nichrome alloy sourcing remains concentrated among East Asian metallurgical suppliers, exposing equipment manufacturers to input cost volatility and lead time extensions.
- Thermoplastic film thickness limitations:Impulse sealers face technical constraints sealing multilayer laminates exceeding 500 microns, restricting adoption in heavy-duty industrial packaging segments.
- CE marking electromagnetic compatibility testing:EU Machinery Directive compliance requirements impose extended validation timelines and third-party certification costs for imported equipment.
Strategic Opportunities
- Indonesian contract packaging expansion:Underpenetrated mid-tier packaging service providers in Surabaya and Bandung manufacturing corridors present equipment financing and technical support partnership openings.
- Band sealer-conveyor integration:Convergence of continuous sealing technology with automated material handling systems enables throughput optimization for high-volume food processing lines.
- USDA sanitation standard certification:Equipment validation protocols aligned with food-contact surface requirements create differentiation premiums for vendors serving North American protein packaging operations.
Industry Challenges
- Thermoplastic welding technician scarcity:Qualified service technicians capable of calibrating temperature-pressure profiles across diverse film substrates remain concentrated in industrialized packaging hubs.
- Legacy ERP integration complexity:Retrofitting automated band sealers with existing manufacturing execution systems requires custom middleware development and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Sealers Market |
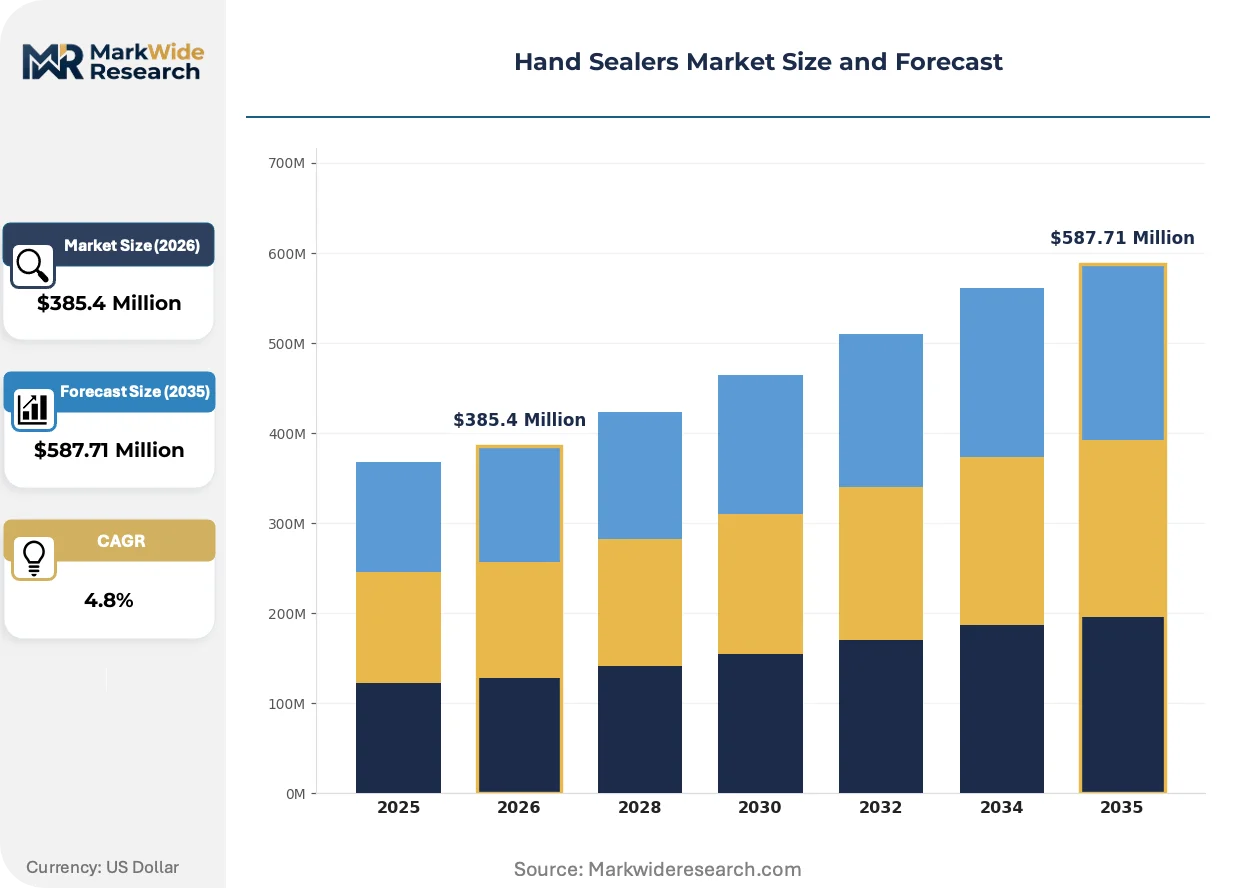
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Impulse Sealers, Constant Heat Sealers, Vacuum Sealers, Band Sealers, Heat Induction Sealers Application: Food Packaging, Pharmaceutical Packing, Electronics Protection, Textile Packaging, Cosmetic Sealing End User: Manufacturers, Packaging Service Providers, Distributors, Retailers, Small Businesses Power Source: Electric, Battery Operated, Pneumatic, Manual, Solar Powered |
| Companies Covered | IMPAK Corporation, Syntegon Technology GmbH, Aline Heat Seal Corporation, PAC Machinery, Accu-Seal Corporation, ZHEJIANG HONGZHAN PACKING MACHINERY, Audion Elektro, Vijay Packaging System, JORESTECH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Sealers Market Trends and Innovations
Sealing equipment architecture is pivoting toward energy-efficient impulse systems and modular vacuum configurations, while regulatory material compliance and buyer procurement consolidation reshape competitive requirements across food and pharmaceutical packaging verticals.
Impulse sealing technology with rapid heat recovery ceramic elements is absorbing market share from constant-heat alternatives in manual packaging operations. Small and mid-sized food enterprises across Southeast Asian manufacturing clusters are specifying these units for reduced energy consumption and lower burn risk. The technology is absorbing price-sensitive demand segments previously served by entry-level constant-heat equipment, compressing margin structures for basic sealing system vendors.
REACH substance restrictions on persistent organic pollutants in food-contact materials are forcing reformulation of PTFE-coated sealing bars and release surfaces. Equipment manufacturers serving European markets must validate alternative coating chemistries or ceramic surface treatments to maintain CE marking eligibility. Pharmaceutical packaging operations with pan-European distribution networks are accelerating qualification of compliant sealing systems ahead of enforcement phase-in timelines.
Mid-sized contract packers are consolidating equipment purchasing through preferred vendor agreements bundling technical support, spare parts availability, and operator training. This procurement model shift is displacing transactional spot purchasing through industrial distributors in North American and European markets. Food packaging service providers in Vietnam and Indonesia are negotiating volume-based service contracts with sealing equipment specialists to secure localized maintenance response capabilities.
Hand Sealers Market Segmentation
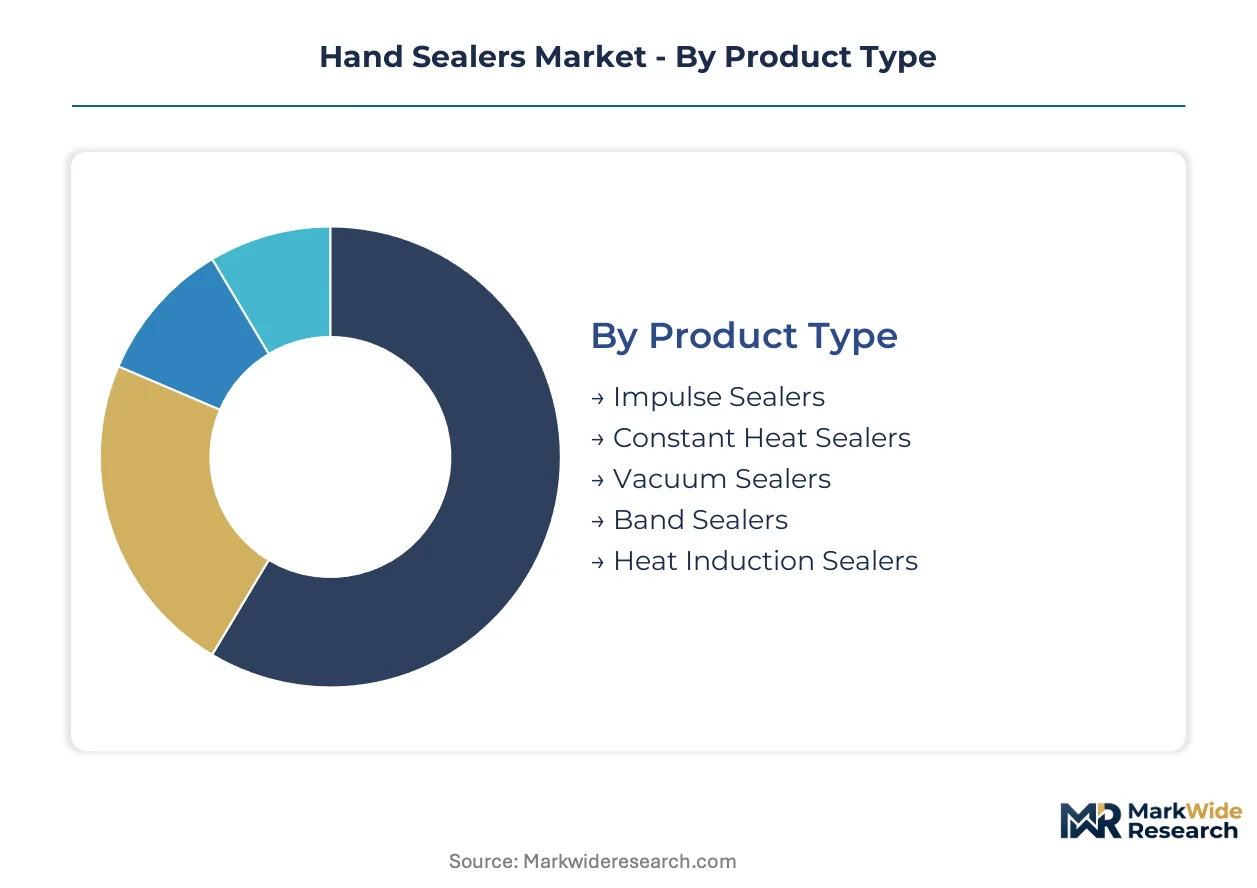
Hand sealer segmentation reveals distinct technology clusters serving divergent operational requirements across packaging verticals. Equipment selection hinges on throughput demands, material compatibility, and integration depth with existing production infrastructure.
Product Type:
Impulse and constant heat configurations dominate standalone manual operations, while vacuum and band systems embed into automated production lines with varying degrees of conveyor integration.
- Impulse Sealers:Ceramic heating elements deliver rapid thermal cycling with energy consumption 40% below constant-heat alternatives. Small food enterprises in Vietnam and Indonesia specify these units for intermittent sealing tasks where operator safety and power efficiency outweigh continuous throughput requirements.
- Vacuum Sealers:Chamber and external suction configurations extract atmospheric oxygen prior to heat sealing, extending shelf stability for oxygen-sensitive pharmaceuticals and protein products. Cleanroom-compatible stainless steel variants serve electronics manufacturers in South Korea and pharmaceutical operations under FDA validation protocols.
- Constant Heat Sealers:Maintained temperature bars suit thick laminates and continuous sealing cycles in high-volume textile packaging.
- Band Sealers:Conveyor-integrated continuous sealing enables throughput exceeding 1,000 packages hourly in automated food processing lines.
- Heat Induction Sealers:Non-contact electromagnetic field generation bonds foil liners to container rims for tamper-evident pharmaceutical closures.
Impulse sealers lead volumes today; vacuum sealers are gaining share fastest.
Application:
End-use concentration varies sharply by regulatory exposure and margin structure, with food and pharmaceutical packaging commanding premium equipment specifications.
- Food Packaging:USDA sanitation standards mandate stainless steel construction and tool-free disassembly for protein packaging operations. Southeast Asian contract packers in Surabaya and Bandung corridors drive demand for portable impulse units with rapid heat recovery.
- Pharmaceutical Packing:FDA 21 CFR Part 11 compliance requirements enforce validated sealing parameters with electronic batch records. Vacuum sealing with oxygen exclusion below 0.5% preserves API stability in moisture-sensitive dosage forms distributed across pan-European networks.
- Electronics Protection:ESD-safe vacuum configurations prevent static discharge damage to semiconductor components during hermetic packaging.
- Textile Packaging:Constant heat band sealers accommodate bulky fabric compression prior to closure in garment export operations.
- Cosmetic Sealing:Precision temperature control prevents thermal degradation of volatile fragrance compounds in premium skincare packaging.
Food packaging anchors current demand; pharmaceutical applications command the steepest expansion trajectory.
End User:
Procurement sophistication diverges dramatically between integrated manufacturers and third-party service providers, reshaping vendor relationship structures.
- Manufacturers:In-house packaging operations at food processors and pharmaceutical firms specify validated equipment with preventive maintenance contracts. These buyers prioritize technical documentation and spare parts availability over upfront capital expenditure minimization.
- Packaging Service Providers:Mid-sized contract packers consolidate purchasing volumes through preferred vendor agreements bundling equipment, training, and localized service response. Vietnamese and Indonesian third-party operators negotiate volume-based technical support packages to secure uptime guarantees.
- Distributors:Industrial supply intermediaries stock entry-level impulse sealers for spot purchasing by occasional-use customers.
- Retailers:In-store packaging stations at specialty food merchants specify compact countertop units with minimal footprint requirements.
- Small Businesses:Artisan food producers and boutique cosmetic makers prioritize price-accessible manual sealers with simplified operation.
Packaging service providers represent the fastest-expanding customer category; manufacturers retain the largest installed base.
Power Source:
Energy infrastructure availability and mobility requirements dictate power configuration selection across operating environments.
- Electric:Grid-connected 110V and 220V configurations deliver consistent thermal performance in fixed manufacturing locations. European food processors specify these units for compliance with EU Machinery Directive electrical safety requirements.
- Battery Operated:Lithium-ion powered portable sealers enable field packaging operations in agricultural collection points and remote logistics hubs lacking reliable grid access. Indonesian palm oil cooperatives deploy these units for on-site kernel packaging.
- Pneumatic:Compressed air actuation delivers precise pressure control for delicate medical device packaging in cleanroom environments.
- Manual:Hand-lever mechanical sealers serve off-grid emergency relief operations and ultra-low-volume artisan production.
- Solar Powered:Photovoltaic-battery hybrid systems support sustainable packaging initiatives in renewable energy demonstration projects.
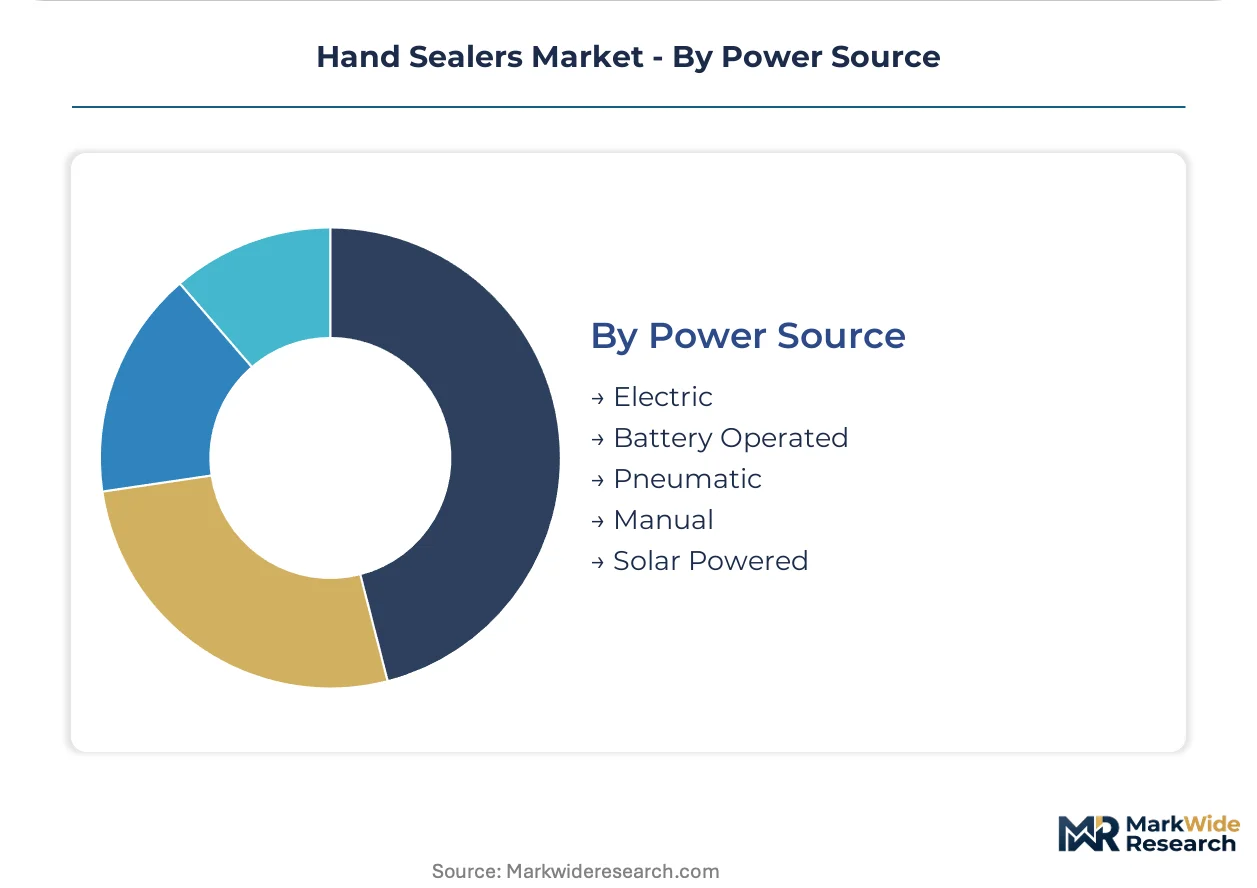
Electric configurations dominate installed capacity; battery operated systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam and Indonesia are outpacing mature European markets in equipment procurement velocity, while the United States and Germany sustain demand through regulatory-driven replacement cycles.
United States
Protein packaging operations in the Midwest and Southeast are driving demand for USDA-validated stainless steel impulse sealers with tool-free disassembly. FDA enforcement of pharmaceutical packaging integrity standards accelerates vacuum sealer replacement among generic drug manufacturers. Dallas-Fort Worth and Atlanta manufacturing corridors concentrate contract packaging services scaling automated band sealing lines.
Germany
Food processors in Bavaria and North Rhine-Westphalia are retrofitting facilities to meet EU Packaging and Packaging Waste Regulation material traceability deadlines. CE marking obligations under the EU Machinery Directive extend validation timelines for imported equipment. Stuttgart industrial cluster hosts precision engineering firms developing ceramic-element impulse systems for energy-conscious mid-sized enterprises.
Vietnam
Ho Chi Minh City and Hanoi manufacturing belts are absorbing portable impulse sealers with rapid heat recovery specifications as contract packaging services scale. Domestic food exporters face tightening EU import compliance requirements for flexible packaging closures. Binh Duong and Dong Nai provinces concentrate third-party packers negotiating volume-based technical support contracts with equipment specialists.
Indonesia
Palm oil cooperatives in Sumatra deploy battery-operated field sealers for on-site kernel packaging where grid access remains unreliable. The national pharmaceutical regulator enforces packaging integrity standards for domestic generic drug distribution. Surabaya and Bandung manufacturing corridors present underpenetrated mid-tier contract packaging service providers seeking equipment financing partnerships.
China
Electronics manufacturers in Shenzhen and Dongguan specify ESD-safe vacuum configurations for semiconductor component hermetic packaging. GB standards for food-contact equipment shape domestic supplier product specifications. Yangtze River Delta pharmaceutical clusters are qualifying cleanroom-compatible sealing systems for API export operations.
Hand Sealers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated vendor landscape. The installed base concentrates among established European and North American equipment fabricators with validated regulatory compliance histories. Three archetypes dominate: integrated packaging machinery conglomerates with broad portfolio coverage, specialized sealing technology pure-plays with deep application expertise, and regional fabricators competing on price-accessible configurations. Consolidation pressure intensifies through preferred vendor agreement expansion and geographic market entry partnerships.
Among North American specialists, IMPAK Corporation and PAC Machinery occupy positions within the cleanroom-compatible and distribution-intensive archetypes respectively. Syntegon Technology GmbH represents the European integrated machinery tier with extensive R&D footprints. ZHEJIANG HONGZHAN PACKING MACHINERY exemplifies Chinese regional fabricators scaling export-oriented production. These three anchors illustrate competitive positioning across regulatory compliance depth, geographic reach, and cost structure differentiation.
| Leading Market Players |
|---|
| IMPAK Corporation |
| Syntegon Technology GmbH |
| Aline Heat Seal Corporation |
| PAC Machinery |
| Accu-Seal Corporation |
| ZHEJIANG HONGZHAN PACKING MACHINERY |
| Audion Elektro |
| Vijay Packaging System |
| JORESTECH |
| Others |
Pricing and Supply Chain Analysis
Qualified thermoplastic welding technicians concentrated in Stuttgart and Bavaria industrial clusters drive labor-cost differentials that widen pricing-tier spreads between premium CE-validated equipment and entry-level configurations. These regional skill premiums cascade into three-tier pricing structures where certification-grade impulse sealers command substantial premiums over basic constant-heat alternatives.
Pricing Analysis
Capacity additions in Zhejiang and Guangdong provinces are reshaping price floors for standard-grade impulse sealers, compressing margins for mid-tier European fabricators. Three-tier pricing structure across premium, standard, and economy levels segments buyers by validation requirements and after-sales bundling intensity. Pricing pressure stems from Chinese regional fabricators scaling export-oriented production of ceramic-element systems. Small food enterprises in Vietnam and Indonesia represent the most price-sensitive segment, while pharmaceutical manufacturers under FDA validation protocols show minimal elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for automated band sealing lines, while industrial distributors stock entry-level units for spot purchasing. Component supply concentrates in China for ceramic heating elements, Germany for precision pressure-control assemblies, and Japan for nichrome alloy feedstock. Raw material dependencies include PTFE-coated sealing bars facing REACH reformulation mandates, lithium-ion cells for portable configurations, and stainless steel food-contact surfaces. Single-source vulnerability in East Asian metallurgical suppliers for heating element alloys exposes equipment manufacturers to input cost volatility. Distribution runs through preferred vendor agreements bundling technical support and spare parts availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in hand sealers rests on ceramic-element cost curves flattening and pharmaceutical-grade vacuum configurations capturing premium-tier demand. Energy-efficient impulse systems with rapid heat recovery specifications absorb share from constant-heat alternatives, validating R&D concentration in this architecture.
For Market Incumbents: Extend preventive maintenance contract penetration among mid-sized contract packers to lock in recurring revenue streams and defend against emerging Chinese regional fabricators. Deepen backward integration into ceramic heating element production to reduce exposure to East Asian nichrome alloy supply volatility. CE marking validation capabilities represent a critical lever for sustaining premium positioning in European food processing markets. For New Entrants and Emerging Players: Mid-tier contract packaging service providers in Surabaya and Bandung manufacturing corridors present accessible entry points with unconsolidated procurement and limited localized technical support. Equipment financing partnerships bundled with operator training programs offer a differentiated go-to-market angle against established distributors. Indonesian palm oil cooperatives deploying battery-operated field sealers represent an adjacent white-space target with minimal incumbent presence. For Investors and Strategic Acquirers: Packaging machinery conglomerates seeking sealing technology tuck-ins are the most active acquirer in this space, prioritizing validated regulatory compliance histories and installed base density. Cleanroom-compatible vacuum system specialists with FDA 21 CFR Part 11 documentation represent the most defensible acquisition target archetype. Watch for REACH enforcement phase-in timelines accelerating qualification of compliant sealing systems as an inflection indicator for premium-tier demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Heating Element R&D Scale-Up | Energy-efficient impulse systems absorb share from constant-heat alternatives in Southeast Asian food operations. |
| REACH-Compliant Coating Qualification | Alternative surface treatments preserve CE marking eligibility for European pharmaceutical packaging networks. |
| Preferred Vendor Agreement Expansion | Mid-sized contract packers in Vietnam consolidate procurement volumes to secure technical support packages. |
| Battery-Operated Product Line Extension | Indonesian palm oil cooperatives deploy portable sealers for on-site kernel packaging without grid access. |
| USDA Sanitation Standard Certification | Stainless steel construction with tool-free disassembly opens North American protein packaging operations. |
Research Methodology
Bottom-up food and pharmaceutical packaging modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with maintenance directors at contract packaging facilities, plant engineers at integrated food processors, OEM procurement teams at pharmaceutical manufacturers, and aftermarket service heads at equipment distributors were validated against secondary sources including FDA 21 CFR Part 11 guidance documents, EU Machinery Directive technical standards, USDA sanitation equipment listings, and customs trade data for sealing machinery classifications.
Input-output matrices map installed base by product type, application vertical, end-user category, and power configuration across the projection horizon. Segmentation dimensions modeled include sealing technology architecture, regulatory compliance tier, geographic manufacturing cluster, and integration depth with automated material handling systems. CAGRs were derived from slope analysis of replacement cycle timing, regulatory deadline compression effects, and contract packaging capacity expansion trajectories. Forecast inputs incorporate EU Packaging and Packaging Waste Regulation material traceability mandates and Southeast Asian manufacturing cluster growth rates.
Underlying measurement precision varies by segment; pharmaceutical and food packaging applications carry tighter precision than textile and cosmetic sealing due to regulatory validation documentation density. Forecasts reflect assumptions regarding ceramic-element cost reduction curves, REACH enforcement timelines, and contract packaging consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Dispensing Booth Market
Packaging Equipment
Rotary Tray Sealers Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
Bag Re-Sealer Market
Packaging Equipment
Heat Sealing Equipment Market
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
Bagging Equipment Market
Packaging Equipment
Hang Tag Applicators Market
Packaging Equipment
Blow Molding Tools Market
Packaging Equipment
Strap Dispenser Market
Packaging Equipment
Hydrapulper Market
Packaging Equipment
Clip Applicator Market
Packaging Equipment
PIR Blow Molding Market
Packaging Equipment
Flexible End-Load Cartoner Market
Packaging Equipment
Loading Spout Market
Packaging Equipment
Global End-Of-Line Packaging Market