
 APAC Insulin Market | 2026-2036
APAC Insulin Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Insulin Market Insights
CE marking under the EU MDR is collapsing as a relevant gate for APAC-bound manufacturers, since the region relies on its own conformity pathways. Novo Nordisk A/S leverages its biosimilar portfolio to sustain pricing power across Southeast Asian tender markets. Sanofi anchors its position through backward integration into insulin glargine API production. Eli Lilly and Company differentiates via concentrated R&D on next-generation delivery devices.
Insulin encompasses peptide hormone formulations—human recombinant, analog, and biosimilar variants—typically supplied at concentrations of 100 IU/mL, manufactured through microbial or mammalian cell fermentation, and prescribed to regulate blood glucose in diabetic patients. Long-acting insulin analogs occupy the dominant margin pool due to patent-protected formulations and premium positioning in hospital formularies. Biosimilar insulin represents the fastest-expanding product type as cost-containment policies in China and India accelerate tender switching. Delivery method segmentation shows insulin pens capturing volume leadership while insulin pumps concentrate value in urban Japanese and Australian markets.
India's CDSCO and China's NMPA enforce divergent bioequivalence standards that fragment registration timelines and shape local partnership requirements for multinational suppliers. Japan's PMDA maintains stringent immunogenicity surveillance protocols that limit biosimilar interchangeability and preserve originator pricing tiers. Australia's TGA alignment with European pharmacovigilance frameworks offers a streamlined secondary pathway for companies already holding EMA approvals. Stakeholders must monitor evolving national essential medicine list revisions and tender aggregation mechanisms across Indonesia, Vietnam, and the Philippines to anticipate volume allocation shifts.
Market Dynamics
Hospital procurement consolidation across China, India, and Japan is restructuring insulin distribution economics, with tender aggregation mechanisms favoring suppliers capable of delivering biosimilar volumes at scale.
Growth Catalysts
- India's PLI scheme for APIs:Production-linked incentives for active pharmaceutical ingredients are attracting fermentation capacity investments and reducing import dependency for insulin glargine precursors.
- Japan's aging diabetes burden:PMDA's streamlined biosimilar pathways for established molecules are accelerating hospital formulary switches toward cost-controlled analogs.
- Continuous glucose monitoring integration:Closed-loop algorithm advancement is driving pump-compatible insulin demand in Australian and South Korean urban centers.
Market Restraints
- API supply concentration:Fermentation-derived insulin precursors depend on a limited set of microbial cell line suppliers concentrated in China and Denmark.
- Bioequivalence standard divergence:CDSCO's immunogenicity testing requirements differ materially from NMPA protocols, fragmenting registration timelines for multinational sponsors.
- Cold chain infrastructure gaps:Last-mile temperature control failures in Indonesian and Philippine archipelago regions limit analog insulin shelf stability.
Strategic Opportunities
- Vietnam's essential medicines list expansion:Ministry of Health revisions are creating tender entry points for biosimilar basal insulin categories previously restricted to originator supply.
- Pre-filled pen device localization:Partnerships with Malaysian and Thai precision molders offer pathway to bypass import duties on delivery mechanism components.
- Digital therapeutics convergence:Integration of dose-optimization algorithms with smartphone-connected pens is opening subscription revenue models in Japanese retail pharmacy channels.
Industry Challenges
- Fermentation scale-up talent scarcity:Mammalian cell culture expertise for analog insulin production concentrates in legacy biologics hubs, constraining greenfield facility staffing.
- Multi-jurisdiction pharmacovigilance burden:Divergent adverse event reporting timelines across TGA, PMDA, and NMPA create compliance overhead for portfolio-wide safety surveillance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Insulin Market |
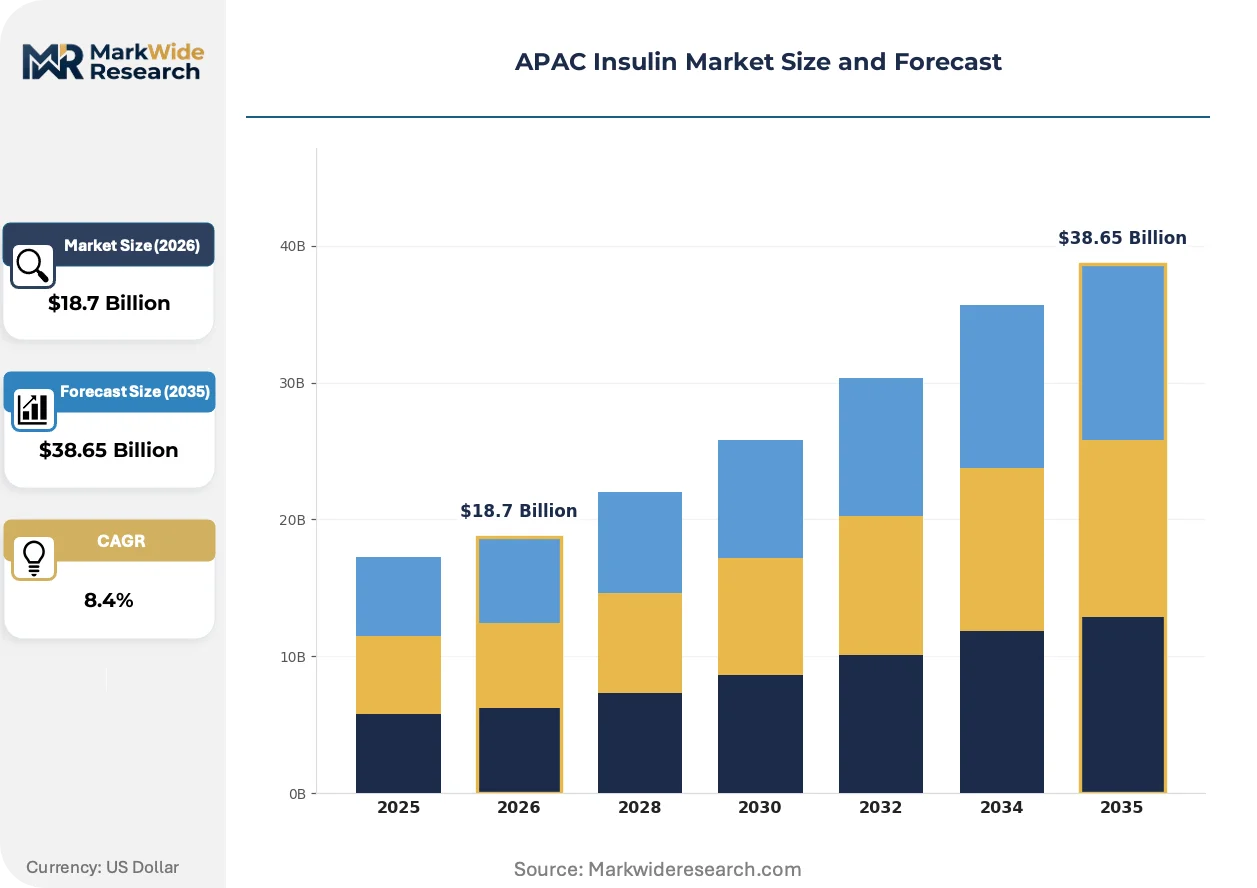
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid-Acting Insulin, Long-Acting Insulin, Premixed Insulin, Biosimilar Insulin Delivery Method: Insulin Pen, Insulin Pump, Syringe, Inhalable Insulin Patient Type: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Adolescent Patients End User: Hospitals, Clinics, Homecare, Diabetes Educators |
| Companies Covered | Novo Nordisk A/S, Sanofi, Eli Lilly and Company, Biocon, Wockhardt, Gan & Lee Pharmaceuticals, Tonghua Dongbao Pharmaceutical Co., Ltd., Eris Lifesciences Ltd, The United Laboratories International Holdings Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Insulin Market Trends and Innovations
Biosimilar manufacturing process innovation and connected delivery device development are compressing traditional insulin market segmentation. Competitive advantage now flows from vertical control over fermentation economics and data-capture capabilities in patient administration.
Next-generation basal insulin formulations incorporating albumin-binding fatty acid acylation are decomposing the traditional pharmacokinetic trade-off between duration of action and variability of absorption. Hospital formularies in Shanghai and Tokyo are adopting these molecules for type 2 diabetes intensification protocols. The technology is decomposing premium pricing power for first-generation glargine and detemir products by delivering flatter glucose profiles with reduced nocturnal hypoglycemia risk.
China's NMPA implementation of ICH Q5E comparability guidelines is harmonizing biosimilar insulin technical requirements with FDA and EMA precedent. This convergence reduces redundant clinical trial obligations for sponsors holding existing major-market approvals. Southeast Asian regulators in Indonesia and Vietnam are referencing NMPA determinations to accelerate their own biosimilar evaluation timelines.
Japanese retail pharmacies are deploying subscription-based insulin pen replenishment models integrated with municipal diabetes registry data. This channel innovation displaces traditional hospital-centric dispensing for stable type 2 patients. Australian community pharmacy chains are piloting comparable programs in Melbourne and Sydney metropolitan zones.
APAC Insulin Market Segmentation
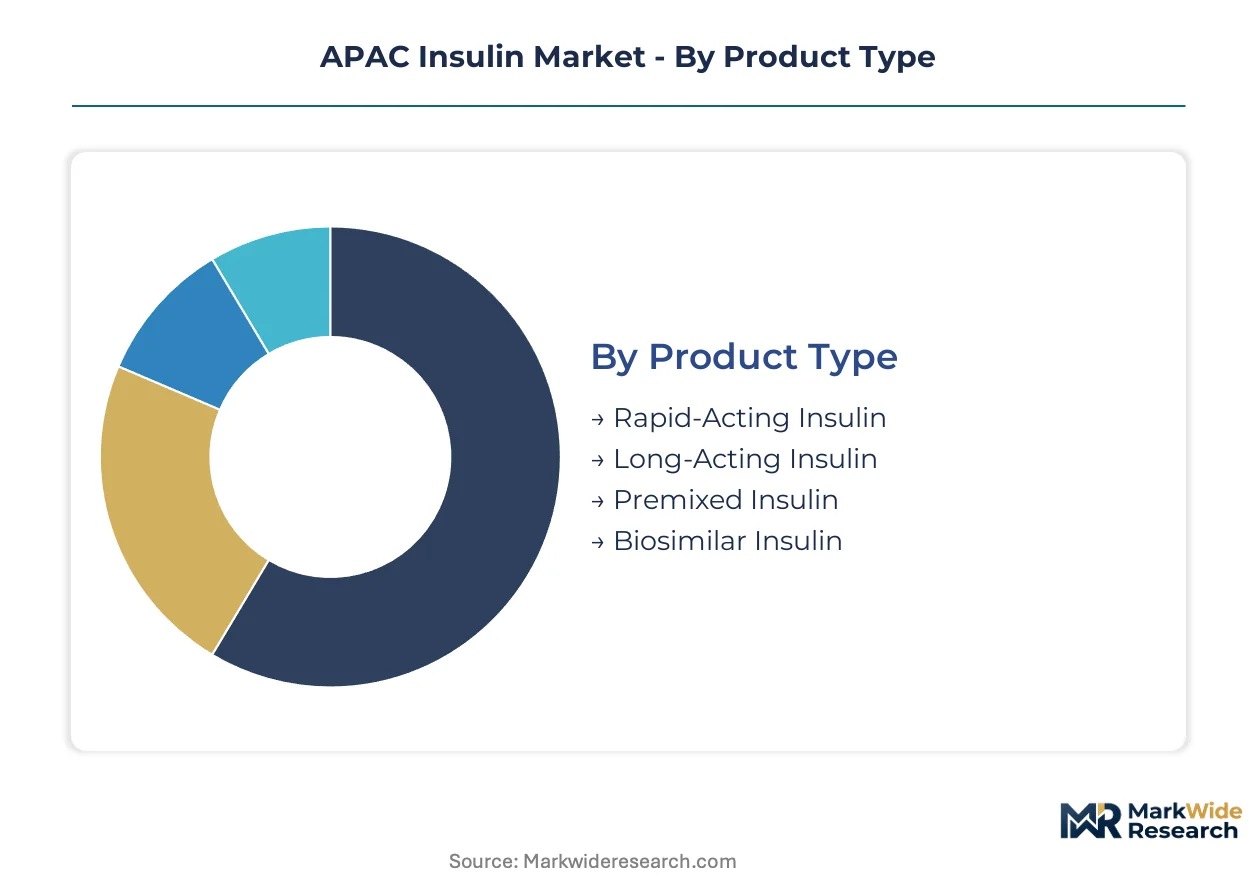
Insulin segmentation across Asia-Pacific reflects divergent clinical protocols and procurement economics. Hospital formularies in China and India drive category prioritization, while patient access programs reshape volume distribution across delivery formats.
Product Type:
Substitution pressure concentrates on first-generation analogs as next-generation basal formulations and biosimilars erode incumbent pricing tiers.
- Long-Acting Insulin:Albumin-binding fatty acid acylation technologies deliver flatter pharmacokinetic profiles with reduced nocturnal hypoglycemia risk. Shanghai and Tokyo hospital formularies are adopting these molecules for type 2 diabetes intensification protocols, displacing older glargine and detemir products.
- Biosimilar Insulin:Fermentation-derived equivalents to originator analogs are capturing tender volume as China's NMPA and India's CDSCO harmonize bioequivalence standards with ICH Q5E guidelines. Cost-containment policies in both countries accelerate hospital switching toward these categories.
- Rapid-Acting Insulin:Prandial glucose control formulations face compression from closed-loop pump algorithms that reduce bolus frequency requirements.
- Premixed Insulin:Fixed-ratio basal-bolus combinations retain utility in rural Indian and Indonesian clinics with limited monitoring infrastructure.
Long-acting insulin retains volume leadership; biosimilar insulin holds the steepest expansion curve.
Delivery Method:
Cost tier stratification separates premium-connected devices from commodity injection formats across urban and rural patient populations.
- Insulin Pen:Pre-filled and reusable cartridge systems dominate ambulatory dispensing in Japan and South Korea. Malaysian and Thai precision molders are attracting localization partnerships to bypass import duties on device components.
- Insulin Pump:Closed-loop systems with continuous glucose monitoring integration concentrate value in Australian and South Korean metropolitan diabetes centers. Algorithm advancement is driving pump-compatible insulin demand in these urban markets.
- Syringe:Vial-and-syringe formats persist in price-sensitive Indian and Vietnamese public procurement channels.
- Inhalable Insulin:Pulmonary delivery mechanisms face limited adoption due to PMDA immunogenicity surveillance requirements and hospital formulary conservatism in Japan.
Insulin pens retain volume leadership; insulin pumps hold the steepest expansion curve.
Patient Type:
Application urgency varies across autoimmune, metabolic, and gestational indications with divergent treatment intensification pathways.
- Type 2 Diabetes:Metabolic disease patients requiring insulin intensification represent the dominant addressable population across China and India. Hospital procurement consolidation favors basal insulin analogs for this cohort.
- Type 1 Diabetes:Autoimmune insulin dependence drives pump adoption and premium analog demand in Australian pediatric and adolescent clinics.
- Gestational Diabetes:Pregnancy-specific glucose management protocols in Japanese obstetric networks favor human recombinant insulin over analogs due to limited teratogenicity data.
- Adolescent Patients:Pediatric endocrinology centers in Melbourne and Sydney are piloting smartphone-connected pen subscription models for this transition-age cohort.
Type 2 diabetes retains volume leadership; type 1 diabetes holds the steepest expansion curve.
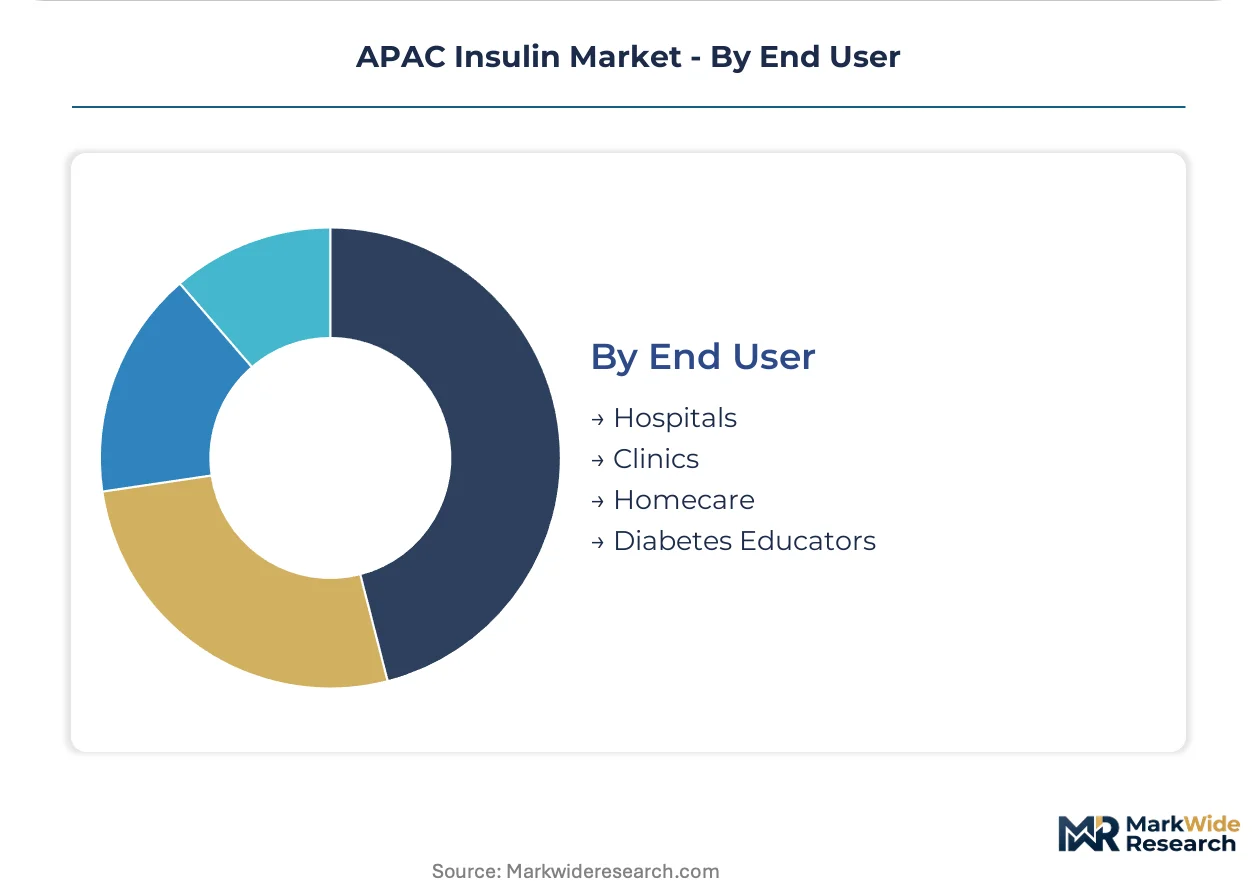
End User:
Customer type determines channel economics and regulatory exposure across institutional and retail dispensing environments.
- Hospitals:Tender aggregation mechanisms in China, India, and Japan favor suppliers capable of delivering biosimilar volumes at scale. Procurement consolidation is restructuring distribution economics across the region.
- Homecare:Self-administration growth in Australian and Japanese retail pharmacy channels is displacing traditional hospital-centric dispensing for stable patients.
- Clinics:Primary care facilities in Indonesian and Philippine archipelago regions face cold chain infrastructure gaps that limit analog insulin shelf stability.
- Diabetes Educators:Certified training professionals in Vietnam and the Philippines influence device selection and injection technique adherence.
Hospitals retain volume leadership; homecare holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for active pharmaceutical ingredients is attracting fermentation capacity investments across the region. China's NMPA harmonization with ICH Q5E guidelines is accelerating biosimilar registration timelines. Japan's PMDA maintains distinct immunogenicity surveillance protocols that preserve originator pricing tiers.
China
Hospital procurement consolidation in Shanghai and Beijing is restructuring insulin distribution economics toward biosimilar volume suppliers. NMPA's ICH Q5E comparability guideline implementation reduces redundant clinical trial obligations for sponsors holding FDA or EMA approvals. The Yangtze River Delta biologics cluster is expanding microbial cell fermentation capacity for insulin glargine precursors.
India
Type 2 diabetes intensification protocols in Mumbai and Delhi hospital networks are driving basal insulin analog demand among metabolic disease patients. CDSCO enforces divergent bioequivalence standards from NMPA protocols, fragmenting registration timelines for multinational sponsors. Maharashtra and Gujarat pharmaceutical corridors are attracting PLI-linked investments in recombinant insulin API manufacturing.
Japan
Aging diabetes burden in Tokyo and Osaka metropolitan areas is accelerating hospital formulary switches toward cost-controlled analogs. PMDA's streamlined biosimilar pathways for established molecules coexist with stringent immunogenicity surveillance that limits interchangeability. The Kanto region's retail pharmacy networks are deploying subscription-based insulin pen replenishment models integrated with municipal diabetes registries.
Australia
Closed-loop pump algorithm advancement is driving pump-compatible insulin demand in Melbourne and Sydney metropolitan diabetes centers. TGA alignment with European pharmacovigilance frameworks offers streamlined secondary pathways for companies already holding EMA approvals. Community pharmacy chains in New South Wales and Victoria are piloting smartphone-connected pen subscription programs for stable type 2 patients.
South Korea
Urban diabetes centers in Seoul are adopting continuous glucose monitoring integration for intensified glycemic management. MFDS maintains regulatory pathways that reference both FDA and EMA precedent for biosimilar insulin evaluation. The Seoul Capital Area's medical device ecosystem is attracting partnerships for precision pen component manufacturing.
APAC Insulin Market Competitive Landscape
Player mix skews toward integrated biologics manufacturers with captive fermentation capacity and originator multinational subsidiaries with established hospital formulary relationships. Market structure concentrates around three strategic tiers: patent-protected analog originators commanding premium positioning, biosimilar specialists competing on tender aggregation scale, and emerging domestic API-integrated players leveraging local regulatory familiarity. Dominant competitive moves include backward integration into insulin glargine precursor production and localization partnerships for pre-filled pen device manufacturing.
Among Nordic and European-origin biologics leaders, Novo Nordisk A/S and Sanofi exemplify the integrated originator archetype with established hospital procurement relationships across China, India, and Japan. Eli Lilly and Company occupies a position within the innovation-focused tier, differentiated by concentrated R&D on next-generation delivery devices. Within the emerging domestic specialist tier, Biocon and Wockhardt represent Indian API-integrated manufacturers capturing PLI-linked capacity expansion benefits. Gan & Lee Pharmaceuticals and Tonghua Dongbao Pharmaceutical Co., Ltd. anchor the Chinese domestic biosimilar segment, leveraging NMPA pathway familiarity and regional fermentation infrastructure.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Sanofi |
| Eli Lilly and Company |
| Biocon |
| Wockhardt |
| Gan & Lee Pharmaceuticals |
| Tonghua Dongbao Pharmaceutical Co., Ltd. |
| Eris Lifesciences Ltd |
| The United Laboratories International Holdings Limited |
| Others |
Pricing and Supply Chain Analysis
Fermentation scale economies in microbial cell line production anchor both supply concentration and price floors across the region. CDSCO and NMPA bioequivalence divergence fragments registration economics, forcing multinational sponsors to absorb redundant clinical trial costs that transmit into originator pricing tiers while domestic API-integrated players capture PLI-linked cost advantages.
Pricing Analysis
Certification level (ICH Q5E/FDA-grade vs. domestic pathway) creates the primary spread between originator and biosimilar insulin tiers. Three-tier pricing structure across patent-protected analogs, approved biosimilars, and unbranded vial formats stratifies hospital procurement channels. Cost compression in basal insulin intensifies as China's NMPA harmonization accelerates tender switching toward fermentation-derived equivalents. Public procurement managers in India and Indonesia exhibit highest price sensitivity; Japanese hospital formulary directors maintain lowest sensitivity due to PMDA immunogenicity protocols that preserve interchangeability barriers.
Supply Chain Analysis
Just-in-time inventory preferences dominate insulin distribution to Australian and Japanese retail pharmacies, while strategic stockpiling characterizes Chinese and Indian hospital procurement given tender aggregation cycles. Microbial cell line supply concentrates in Denmark and China; recombinant insulin API production clusters in Maharashtra, Gujarat, and the Yangtze River Delta. Cold chain infrastructure gaps in Indonesian and Philippine archipelago regions create single-source vulnerability for analog shelf stability. Distribution runs through hospital-centric procurement platforms in China and India, shifting toward pharmacy subscription models in Tokyo and Melbourne metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through divergent bioequivalence standards constructs formidable defensive moats for established players. PMDA immunogenicity surveillance protocols and CDSCO-NMPA pathway fragmentation embed switching costs that protect incumbent positioning.
For Market Incumbents: Fortify hospital formulary relationships through backward integration into insulin glargine precursor production, capturing PLI-linked capacity economics in Maharashtra and Gujarat corridors. Deepen data-capture capabilities in connected pen ecosystems to raise switching costs for stable type 2 patients migrating toward Australian and Japanese retail pharmacy channels. Counter biosimilar tender pressure by emphasizing next-generation albumin-binding formulations with demonstrated nocturnal hypoglycemia reduction.
For New Entrants and Emerging Players: Lead with pre-filled pen device localization partnerships in Malaysian and Thai precision molding clusters, bypassing import duties that erode margin viability in Southeast Asian tender markets. Target Vietnam's essential medicines list expansion as the most penetrable regulatory entry point, where Ministry of Health revisions are creating first-mover advantages in biosimilar basal categories previously restricted to originator supply. Anchor go-to-market strategy around municipal diabetes registry integration for subscription-based replenishment models.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors API-integrated domestic specialists with captive fermentation capacity and established CDSCO/NMPA regulatory familiarity. Long-term viability hinges on vertical control over microbial cell line supply and algorithm-enabled dose optimization platforms. Acquisition target archetype: Indian or Chinese biosimilar manufacturers with PLI-linked capacity expansion and hospital tender aggregation scale. Signal to watch: NMPA determination timelines for next-generation basal insulin formulations as inflection indicator for premium pricing erosion velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Insulin Glargine API Production | Captures PLI scheme benefits and reduces import dependency for precursors in Indian manufacturing corridors. |
| Pre-filled Pen Device Localization Partnerships | Bypasses Malaysian and Thai import duties on delivery mechanism components for Southeast Asian tender access. |
| Connected Pen Algorithm Development | Enables subscription revenue models integrated with municipal diabetes registries in Japanese retail pharmacy channels. |
| ICH Q5E Bioequivalence Harmonization | Reduces redundant clinical trial obligations for sponsors holding existing FDA or EMA approvals via NMPA convergence. |
| Closed-loop Pump Compatibility Certification | Concentrates value capture in Australian and South Korean urban diabetes centers with algorithm advancement. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors across China, India, Japan, and Australia; and secondary validation against NMPA filings, CDSCO submissions, ClinicalTrials.gov records, hospital procurement databases, and GPO contracts. Bottom-up patient population modeling triangulated with top-down fermentation capacity assessments across Maharashtra, Gujarat, and Yangtze River Delta biologics clusters.
Across the analysis window, value outputs reflect segmented modeling across product type (long-acting, biosimilar, rapid-acting, premixed), delivery method (pen, pump, syringe, inhalable), patient type, and end user dimensions. CAGRs derived from hospital procurement volume trajectories, tender aggregation mechanism evolution, and continuous glucose monitoring adoption curves in Melbourne, Sydney, and Seoul metropolitan zones.
Underlying assumptions cover regulatory pathway stability, cold chain infrastructure investment continuity, and PLI scheme extension, with deviation risk concentrated in NMPA-CDSCO standard divergence and Indonesian archipelago distribution reliability. Revision becomes warranted when biosimilar interchangeability determination timelines or next-generation basal insulin adoption rates cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Coagulation Factor IX Market
Biopharmaceuticals
Global Anti-Infective Drugs Market
Biopharmaceuticals
North America Generic Oncology Drug Market
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
Mefentrifluconazole Market
Biopharmaceuticals
Spain Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Macrolide Drugs Market
Biopharmaceuticals
Chronic Phase Markers Market
Biopharmaceuticals
North America and Europe Pegylated Drugs Market
Biopharmaceuticals
Drug Resistant Pulmonary Tuberculosis Market
Biopharmaceuticals
Vaccine Adjuvants Market
Biopharmaceuticals
US Generic Injectables Market
Biopharmaceuticals
Cancer Drug Market
Biopharmaceuticals
Paediatric Oncology Therapeutics Market
Biopharmaceuticals
Penicillin G Acylase Market
Biopharmaceuticals
Biologics Contract Development Market