
 Lupus Nephritis Market | 2026-2036
Lupus Nephritis Market Size, Share, and Industry Trends Forecast 2026-2036
Lupus Nephritis Market Outlook
China is narrowing its gap in lupus nephritis clinical trial infrastructure through expanded biologics manufacturing capacity and indigenous CRO networks. AstraZeneca leverages its SLE franchise to extend nephrology indications, while F. Hoffmann-La Roche Ltd anchors its position through IL-6 pathway investments. Aurinia Pharmaceuticals differentiates via selective immunomodulator specialization, and Novartis AG competes through broad immunology portfolio breadth.
Lupus nephritis constitutes immune-complex-mediated glomerular inflammation driven by autoantibody deposition, with disease severity graded by ISN/RPS histological class and proteinuria thresholds guiding therapeutic intensity. The condition serves as the primary cause of morbidity in systemic lupus erythematosus, demanding staged immunosuppression from corticosteroid induction to biologic maintenance. Biologics command the fastest expansion trajectory as B-cell and interferon pathway inhibitors displace conventional immunosuppressants in refractory populations. Hospital pharmacies retain dominant distribution share due to infusion center requirements for intravenous biologics, though specialty clinics absorb growing subcutaneous administration volumes.
FDA accelerated approval and EMA conditional marketing authorization frameworks compress development timelines for lupus nephritis therapies, while China's NMPA reform track expedites innovative biologics review. These pathways reshape investment prioritization toward registrational-ready assets with surrogate endpoint strategies. Stakeholders must monitor payer evidence requirements for full approvals, as conditional labels demand confirmatory outcomes data that determines sustained market access and pricing durability.
Market Dynamics
FDA accelerated approval and EMA conditional marketing authorization frameworks are compressing development timelines for lupus nephritis therapies, forcing sponsors to prioritize registrational-ready assets with surrogate endpoint strategies while building confirmatory trial infrastructure simultaneously.
Growth Catalysts
- Accelerated Approval Pathways:FDA's accelerated approval framework enables earlier market entry for biologics demonstrating proteinuria reduction, compressing traditional Phase III timelines by 18-24 months.
- Refractory Population Concentration:United States nephrology specialty clinics are expanding infusion center capacity to capture biologic-eligible patients failing cyclophosphamide or mycophenolate mofetil induction.
- Interferon Pathway Science:Type I interferon signature stratification is rendering conventional immunosuppressant selection obsolete in Class III/IV lupus nephritis, directing biologic allocation.
Market Restraints
- Confirmatory Trial Burden:Conditional marketing authorizations from EMA mandate renal function preservation endpoints that extend post-approval commitment timelines and inflate total development costs.
- Infusion Infrastructure Concentration:Hospital pharmacy dominance in intravenous biologic distribution limits patient access in rural catchment areas lacking nephrology subspecialty presence.
- Corticosteroid Taper Complexity:Histological response heterogeneity across ISN/RPS classes prolongs steroid exposure duration, complicating safety profiles for novel agents.
Strategic Opportunities
- Subcutaneous Administration Expansion:Self-injection biologics are penetrating community nephrology clinics, reducing hospital infusion dependency and expanding prescriber base beyond academic medical centers.
- China NMPA Reform Track:Priority review pathways for innovative biologics are compressing regulatory lag versus FDA approval, enabling near-synchronous launches in the world's second-largest pharmaceutical market.
- Maintenance Phase Specialization:B-cell depleting agents are capturing post-induction maintenance share from azathioprine and mycophenolate mofetil in steroid-minimization protocols.
Industry Challenges
- Renal Pathology Talent Scarcity:ISN/RPS classification expertise concentrates in tertiary academic centers, creating diagnostic bottlenecks that delay treatment initiation and trial enrollment.
- Biomarker Validation Complexity:Proteinuria surrogate acceptance varies across regulatory jurisdictions, forcing sponsors to design divergent evidentiary packages for FDA versus EMA submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lupus Nephritis Market |
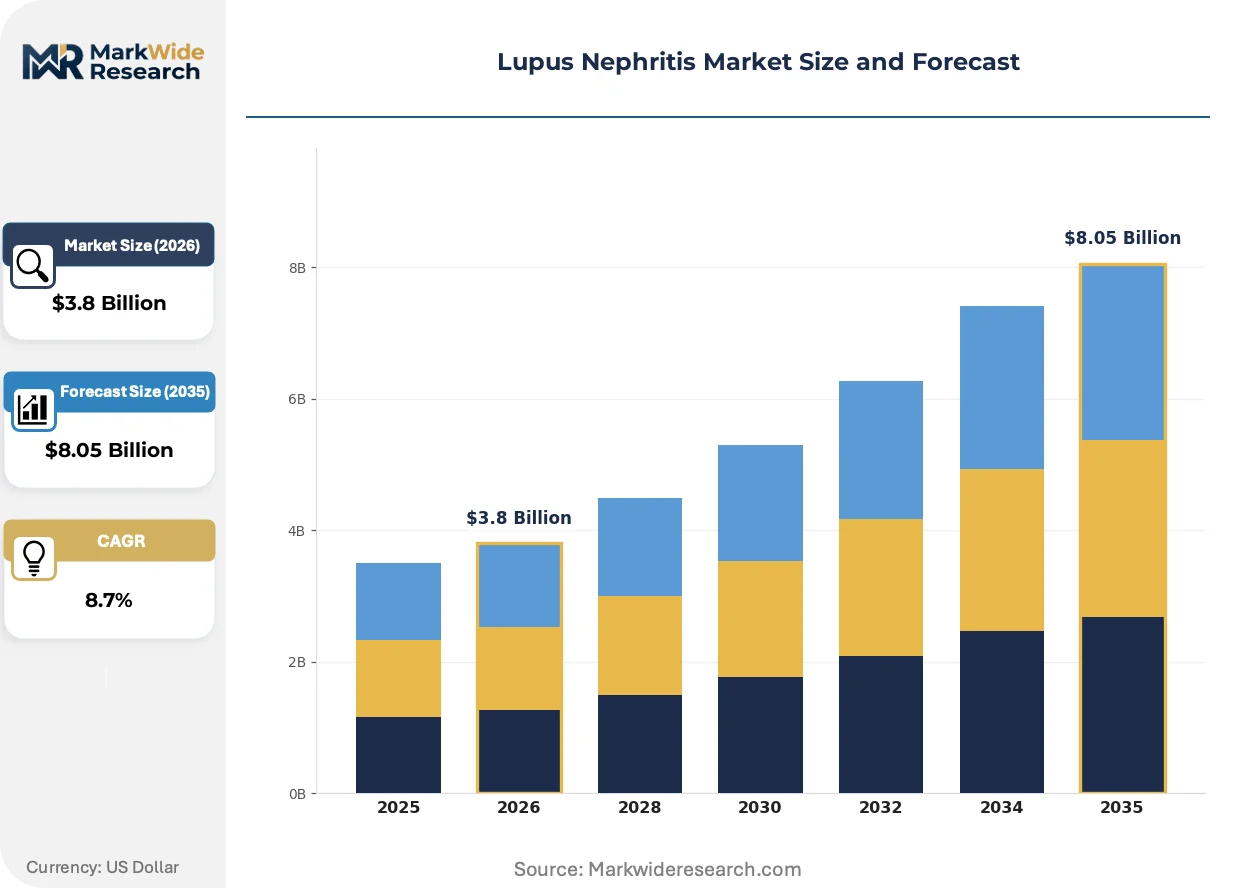
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunosuppressants, Biologics, Supportive Care End User: Hospitals, Specialty Clinics, Homecare Settings, Rehabilitation Centers Administration Route: Oral, Intravenous, Subcutaneous, Topical Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | AstraZeneca, Aurinia Pharmaceuticals, F. Hoffmann-La Roche Ltd, GlaxoSmithKline plc, Novartis AG, Bristol-Myers Squibb Company, Johnson & Johnson, Eli Lilly and Company, Merck & Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lupus Nephritis Market Strategic Shifts
Precision immunology is displacing empirical immunosuppression in lupus nephritis, with molecular stratification directing therapy selection and compressing trial-and-error treatment cycles that previously dominated nephrology practice.
Biosensors and digital biomarkers are rendering obsolete traditional in-clinic proteinuria monitoring, enabling remote disease activity tracking through home-based albumin-to-creatinine ratio testing integrated with electronic health record systems. Nephrology practices in integrated delivery networks are piloting these platforms fastest. The shift is compressing inter-visit assessment gaps and enabling earlier intervention for disease flares.
EMA's conditional marketing authorization framework is forcing sponsors to design adaptive confirmatory trials with renal hard endpoints while maintaining commercial access during evidence generation. This regulatory architecture is reshaping investment prioritization toward assets with clear biomarker-defined responder populations. European payers are demanding outcomes-based agreements that tie continued reimbursement to sustained renal function preservation.
Specialty pharmacy channels are capturing subcutaneous biologic dispensing from hospital outpatient departments, driven by payer preference for limited distribution networks with enhanced adherence monitoring. United States commercial insurers are mandating specialty pharmacy fulfillment for non-infused immunosuppressants. The channel migration is fragmenting prescriber control over medication access and introducing new prior authorization friction points.
Lupus Nephritis Market Segmentation
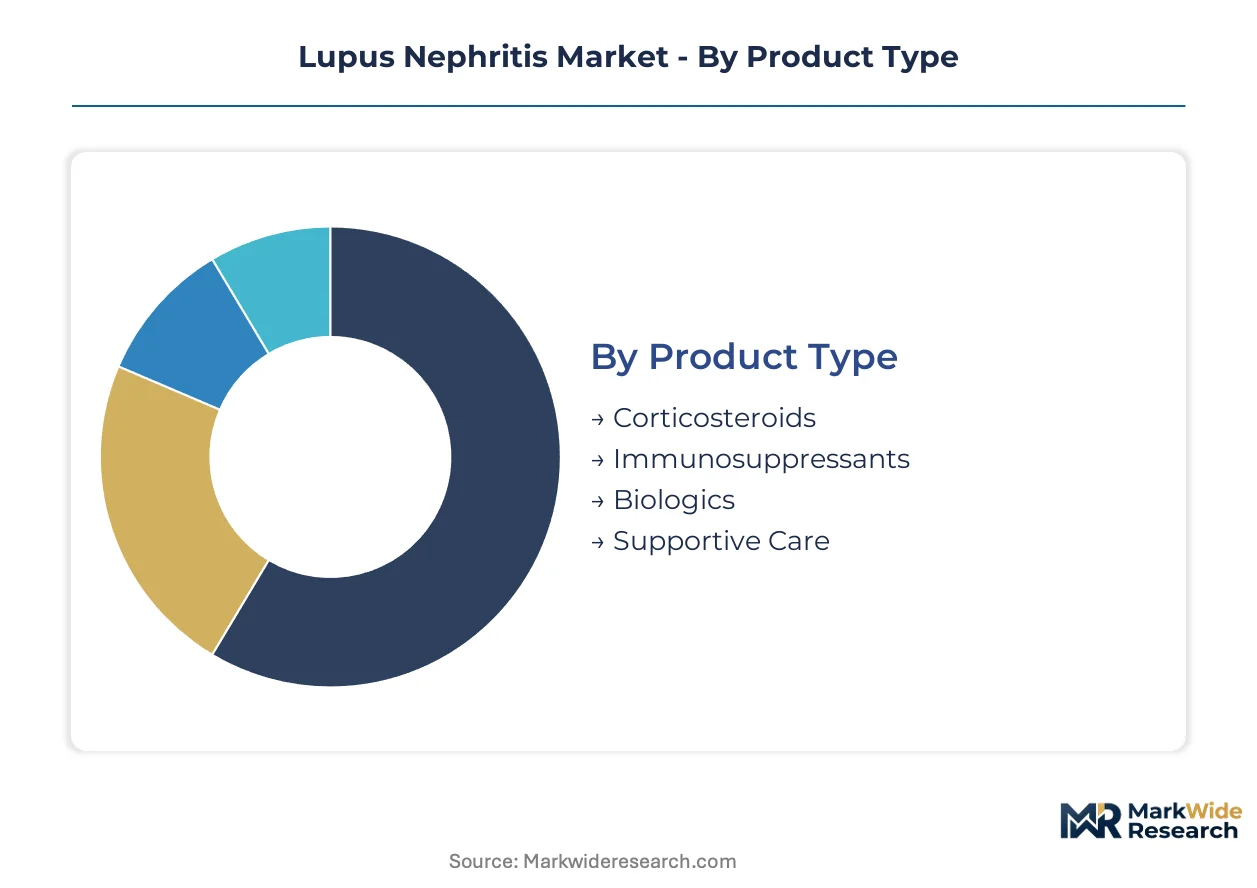
Lupus nephritis treatment selection hinges on ISN/RPS histological class, proteinuria severity, and prior therapy failure history. Segmentation reveals how biologics are displacing conventional immunosuppressants in refractory populations while administration innovation expands care settings.
Product Type:
Clinical decision-making spans induction intensity through maintenance durability, with molecular targeting now superseding empirical immunosuppression protocols.
- Biologics:B-cell depleting agents and interferon pathway inhibitors deliver selective immunomodulation for Class III/IV refractory cases. United States nephrology specialty clinics are expanding infusion capacity to capture patients failing cyclophosphamide induction, with FDA accelerated approval enabling earlier proteinuria-based market entry.
- Immunosuppressants:Mycophenolate mofetil and cyclophosphamide remain foundational for induction, though steroid-sparing protocols are narrowing their maintenance role. EMA conditional marketing authorizations mandate renal function preservation endpoints that extend post-approval commitments for combination regimens.
- Corticosteroids:Histological response heterogeneity across ISN/RPS classes prolongs exposure duration.
- Supportive Care:Antihypertensives and antiproteinuric agents address comorbidity management in stable disease.
Established volume favors immunosuppressants; emerging adoption favors biologics.
End User:
Care delivery fragmentation reflects therapy complexity, with site-of-service economics reshaping prescriber affiliations.
- Hospitals:Tertiary academic medical centers concentrate ISN/RPS classification expertise and intravenous biologic administration. China's NMPA reform track is compressing regulatory lag for innovative biologics, enabling near-synchronous hospital formulary adoption.
- Specialty Clinics:Community nephrology practices are absorbing subcutaneous biologic volumes as self-injection protocols reduce infusion dependency. United States commercial insurers mandate specialty pharmacy fulfillment, fragmenting prescriber control over medication access.
- Homecare Settings:Biosensor-integrated albumin-to-creatinine monitoring enables remote disease activity tracking.
- Rehabilitation Centers:Post-acute facilities manage steroid-induced myopathy and functional recovery.
Academic concentration favors hospitals; prescriber base expansion favors specialty clinics.
Administration Route:
Formulation innovation is compressing site-of-care requirements and enabling patient self-management.
- Intravenous:Infusion center administration dominates B-cell depleting agent delivery, with hospital pharmacy retention of distribution share. Rural catchment areas lacking nephrology subspecialty presence face access constraints.
- Subcutaneous:Self-injection biologics penetrate community clinics, reducing hospital dependency and expanding prescriber reach beyond academic centers. Specialty pharmacy channels capture dispensing from hospital outpatient departments.
- Oral:Mycophenolate mofetil and corticosteroids sustain convenience-driven preference for stable maintenance.
- Topical:Cutaneous lupus manifestations in overlap populations receive localized therapy.
Infusion infrastructure favors intravenous; patient autonomy and payer preference favor subcutaneous.
Distribution Channel:
Channel migration reflects payer cost containment and adherence monitoring requirements.
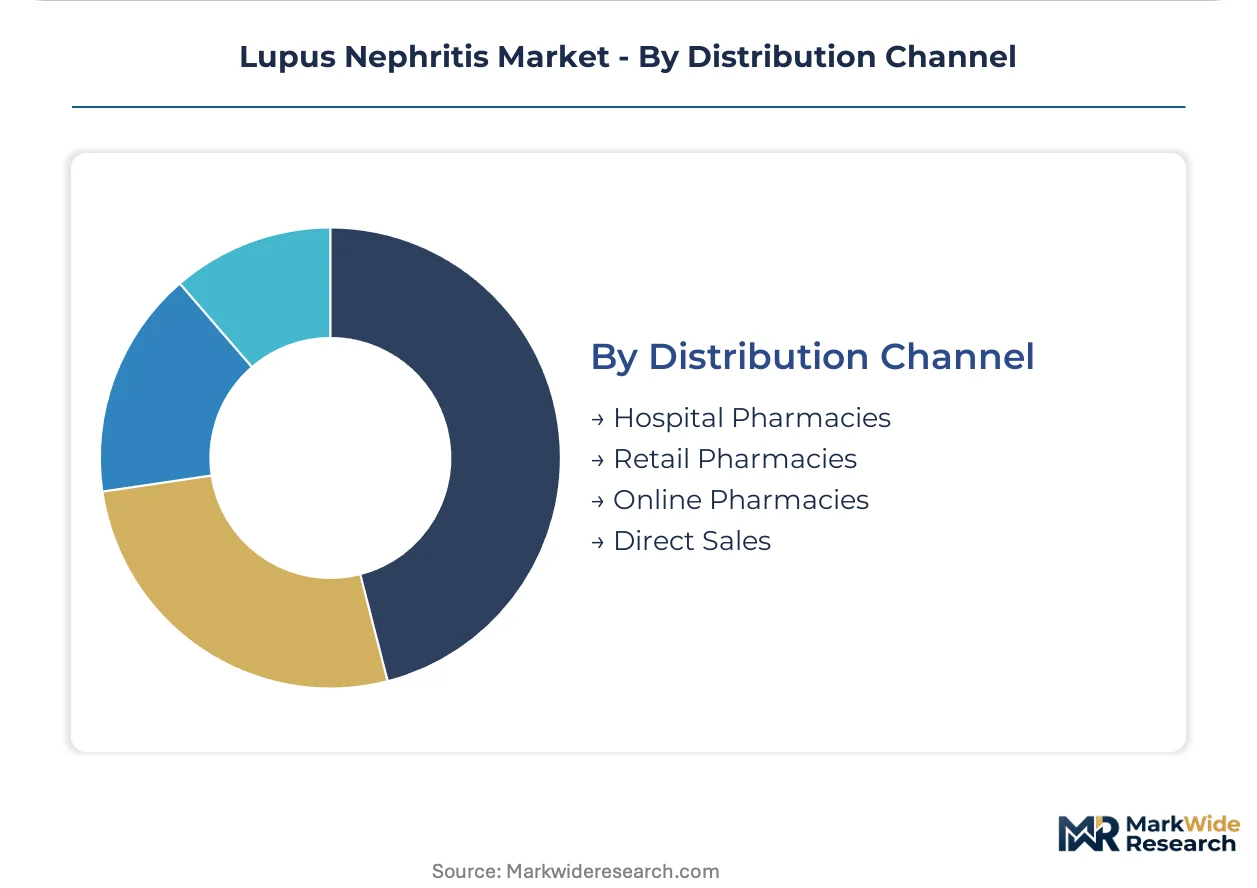
- Hospital Pharmacies:Retain dominant share for intravenous biologics requiring cold-chain handling and infusion center coordination. EMA conditional marketing authorization frameworks demand outcomes-based agreements tying reimbursement to renal function preservation.
- Specialty Pharmacies:Limited distribution networks with enhanced adherence monitoring capture subcutaneous biologic dispensing. United States commercial insurers mandate this channel for non-infused immunosuppressants, introducing prior authorization friction.
- Retail Pharmacies:Oral generic immunosuppressants flow through community dispensing.
- Online Pharmacies:Emerging for supportive care agents and patient convenience.
Payer control favors specialty pharmacies; acute care integration favors hospital pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in tertiary academic medical centers with ISN/RPS classification expertise, concentrating biologic infusion capacity and clinical trial infrastructure in specific national markets. Regulatory pathway differentiation across FDA, EMA, and NMPA frameworks is reshaping launch sequencing and investment allocation.
United States
Refractory patient populations and commercial payer willingness for novel immunosuppressants support premium biologic positioning. FDA accelerated approval enables proteinuria-based market entry, compressing Phase III timelines. Nephrology specialty clinics in Boston, New York, and San Francisco are expanding infusion center capacity to capture cyclophosphamide-failure cases.
China
Indigenous CRO networks and expanded biologics manufacturing capacity are narrowing clinical trial infrastructure gaps. NMPA priority review pathways compress regulatory lag versus FDA approval. Shanghai and Beijing hospital systems are piloting biosensor-integrated albumin-to-creatinine monitoring for remote disease tracking.
Germany
EMA conditional marketing authorization frameworks mandate renal function preservation endpoints that extend post-approval commitments. Outcomes-based agreements tie reimbursement to sustained renal function. Munich and Heidelberg academic centers concentrate ISN/RPS classification expertise and adaptive confirmatory trial design.
Japan
PMDA review timelines for innovative biologics are converging with FDA and EMA standards through harmonization initiatives. Steroid-minimization protocols in maintenance-phase treatment are gaining traction. Tokyo and Osaka nephrology departments are expanding subcutaneous biologic administration in community clinic networks.
United Kingdom
NHS specialized commissioning frameworks concentrate biologic access in designated renal units with outcome monitoring requirements. MHRA post-Brexit regulatory autonomy is enabling accelerated access pathways for lupus nephritis therapies. London and Manchester academic medical centers anchor clinical trial enrollment and histopathology expertise.
Lupus Nephritis Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in targeted pathway modulation. The vendor base stratifies across broad immunology portfolio players, selective immunomodulator specialists, and SLE franchise extenders. Three archetypes dominate: biologic platform developers with nephrology indication expansion, precision immunology specialists with biomarker-defined positioning, and large-cap pharmaceutical companies with portfolio breadth advantages. M&A activity targets registrational-ready assets with surrogate endpoint strategies, while capacity expansion concentrates in infusion center networks and subcutaneous formulation manufacturing.
Within the biologic platform tier, AstraZeneca and F. Hoffmann-La Roche Ltd occupy positions anchored by SLE franchise extension and IL-6 pathway investment respectively. Aurinia Pharmaceuticals exemplifies the selective immunomodulator specialist archetype. These three entities represent contrasting strategic postures: portfolio breadth, pathway-specific science, and indication-focused development.
| Leading Market Players |
|---|
| AstraZeneca |
| Aurinia Pharmaceuticals |
| F. Hoffmann-La Roche Ltd |
| GlaxoSmithKline plc |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Johnson & Johnson |
| Eli Lilly and Company |
| Merck & Co |
| Others |
Value Chain & Pricing Dynamics
FDA accelerated approval pathway dependency concentrates pricing power among sponsors with registrational-ready assets, compressing development timelines while simultaneously fragmenting supply chain control between hospital pharmacies and emerging specialty pharmacy channels. This regulatory chokepoint determines both the premium positioning of biologics in refractory populations and the geographic concentration of infusion infrastructure in tertiary academic centers.
Pricing Analysis
FDA accelerated approval dictates the pricing tier structure for lupus nephritis therapeutics, with proteinuria-based surrogate endpoints enabling premium positioning for B-cell depleting agents and interferon pathway inhibitors. Pricing stratifies across premium biologics, standard immunosuppressant combinations, and economy corticosteroid protocols, with differentiation driven by ISN/RPS histological class certification and steroid-sparing efficacy profiles. Cost compression in maintenance-phase immunosuppressants is intensifying because biologics are capturing post-induction share from azathioprine and mycophenolate mofetil. Community nephrology clinics exhibit highest price sensitivity due to payer prior authorization friction, while academic medical centers demonstrate lowest sensitivity given formulary control and research funding offsets.
Supply Chain Analysis
Export-control regime limitations on biologics manufacturing technology constrain capacity expansion outside established pharmaceutical hubs, tethering active pharmaceutical ingredient production to the United States, Switzerland, and Ireland. Cold-chain handling requirements for monoclonal antibodies rest on specialized logistics networks and infusion center coordination, with distribution running through hospital pharmacies for intravenous formulations and specialty pharmacies for subcutaneous alternatives. Single-source vulnerability concentrates in B-cell depleting agent supply, where limited qualified manufacturing sites face capacity constraints. Distribution downstream fragments between academic medical centers with ISN/RPS classification expertise and community specialty clinics absorbing self-injection volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lupus nephritis therapeutics sit at a platform-economics inflection where biosensor-integrated remote monitoring creates interoperability between pharmaceutical sponsors and integrated delivery networks, shifting value capture toward data-enabled care coordination.
For Market Incumbents: Pre-empt biosensor platform integration by embedding albumin-to-creatinine monitoring capabilities into biologic value propositions before digital health competitors capture patient touchpoints. Defend infusion center relationships through subcutaneous formulation development that reduces hospital dependency while maintaining prescriber loyalty. Channel fragmentation from mandated specialty pharmacy fulfillment threatens direct physician influence over medication access. For New Entrants and Emerging Players: Pursue maintenance-phase specialization with steroid-minimization protocols, as B-cell depleting agents displace conventional immunosuppressants in post-induction populations. Community nephrology clinics in the United States represent the most penetrable segment given expanding subcutaneous administration capacity and prior authorization expertise gaps. Position through outcomes-based contracting that ties reimbursement to renal function preservation metrics. For Investors and Strategic Acquirers: FDA confirmatory trial outcome requirements reshape the acquisition landscape toward assets with adaptive trial infrastructure already deployed. Long-term viability centers on sponsors capable of bridging accelerated approval proteinuria endpoints to sustained renal function preservation across the analysis window. Target acquisition archetypes include selective immunomodulator specialists with biomarker-defined responder populations. Watch for EMA conditional marketing authorization withdrawal signals as inflection indicators for pricing durability risk.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Reduces hospital infusion dependency and expands prescriber base to community nephrology practices. |
| Biosensor Platform Integration | Enables remote albumin-to-creatinine monitoring that compresses inter-visit assessment gaps for disease flares. |
| Adaptive Confirmatory Trial Design | Satisfies EMA conditional marketing authorization renal hard endpoint requirements while maintaining commercial access. |
| Specialty Pharmacy Partnership | Navigates United States commercial insurer mandated fulfillment for non-infused immunosuppressants. |
| China NMPA Priority Review Track | Compresses regulatory lag versus FDA approval for near-synchronous launch in the second-largest pharmaceutical market. |
Study Parameters
The analysis maps biologics, immunosuppressants, corticosteroids, and supportive care segments, each validated through nephrology practice administrators, formulary directors at academic medical centers, payer access specialists, and specialty pharmacy operations managers. Primary interviews with drug development executives and regulatory affairs leads combined with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored volume estimates.
Assumptions held fixed include ISN/RPS classification expertise concentration in tertiary centers and biologics manufacturing capacity constraints across the projection horizon. Segmentation dimensions modeled encompass product type, administration route, end user setting, and regional regulatory cluster. CAGRs derived from patient population epidemiology, treatment penetration curves, and pricing trajectory analysis. Forecast inputs incorporated infusion center capacity expansion rates and NMPA reform track implementation pace.
Sensitivities concentrate around FDA confirmatory trial failure rates and EMA conditional marketing authorization withdrawal triggers. Forecasts reflect assumptions regarding sustained payer willingness for novel immunosuppressants and biologics manufacturing capacity scaling. Material shifts in accelerated approval evidentiary requirements or biosimilar entry timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global CIS Insulin Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
Anti-Neprilysin Market
Biopharmaceuticals
Octreotide Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Global Hairy Cell Leukemia Drugs Market
Biopharmaceuticals
Conjugated Estrogen Market
Biopharmaceuticals
Global Kinase Inhibitors Market
Biopharmaceuticals
Plasmid DNA Manufacturing Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Mefentrifluconazole Market
Biopharmaceuticals
Biotherapeutics Cell Line Development Market
Biopharmaceuticals
Olaparib API Market
Biopharmaceuticals
Anti-Tumor Drugs Market