
 Platinum Nanoparticles Market | 2026-2036
Platinum Nanoparticles Market Size, Share, and Industry Trends Forecast 2026-2036
Platinum Nanoparticles Market Outlook
Japan is narrowing the geographic gap in high-purity platinum nanoparticle output through METI-backed nanomaterial initiatives. TANAKA HOLDINGS Co., Ltd. leverages its precious metals heritage to dominate electrochemical catalyst grades. Johnson Matthey sustains long-term supply relationships with European automotive emissions-system integrators. NanoComposix differentiates through aqueous suspension formulations tailored for biomedical research laboratories.
Platinum nanoparticles are metallic platinum structures typically ranging from 1 to 100 nanometers in diameter, synthesized via chemical reduction, thermal decomposition, or electrochemical methods, and valued for their exceptional catalytic surface area and electron-transfer kinetics. Their primary commercial purpose centers on accelerating chemical reactions in automotive catalytic converters, enabling targeted drug delivery in oncology, and enhancing sensitivity in electrochemical sensors. Colloidal platinum formulations command premium positioning in pharmaceutical applications where batch-to-batch consistency determines regulatory approval timelines. Supported platinum variants anchor the catalysts segment through fixed-bed reactor deployments in chemical processing. Core-shell architectures represent the fastest-growing structural category as manufacturers engineer platinum-ruthenium and platinum-palladium interfaces for enhanced durability in proton-exchange membrane fuel cells.
FDA guidelines govern platinum-based therapeutic nanoparticles under combination product frameworks, while EPA emissions standards directly scale automotive catalyst demand. REACH registration requirements in Europe impose full toxicological dossiers on nanoparticle importers, creating compliance moats for established suppliers. ISO 80004 nanotechnology terminology standards and OECD test guidelines for manufactured nanomaterials shape cross-border trade protocols. Stakeholders must monitor evolving MDR classification for implantable platinum devices and assess how dual carbon goals in China redirect state funding toward hydrogen economy catalysts.
Market Dynamics
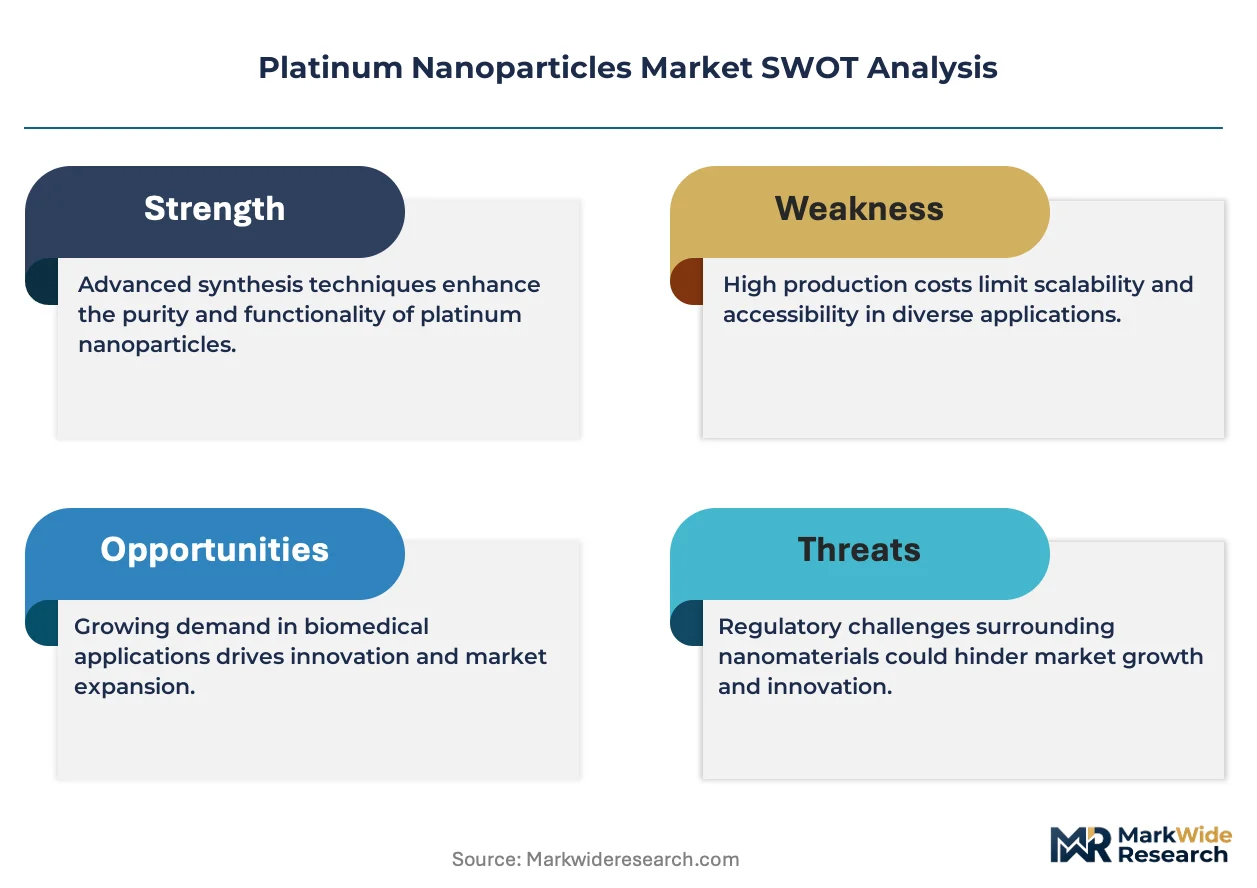
Automotive emissions regulations are compressing platinum loading requirements while hydrogen fuel cell deployment is expanding catalyst surface area specifications, creating divergent demand vectors across the same supplier base.
Growth Catalysts
- REACH registration dossiers:Full toxicological disclosure mandates in Europe erect compliance barriers that favor established nanomaterial importers with existing ECHA filings.
- Proton-exchange membrane fuel cells:Core-shell platinum-ruthenium architectures are gaining specification in heavy-duty transport applications requiring enhanced durability under load cycling.
- Oncology drug delivery:Nanoscale platinum carriers are securing FDA combination product approvals for targeted therapeutics, extending pharmaceutical application pipelines.
Market Restraints
- Platinum group metal volatility:Spot price fluctuations in rhodium and palladium feed directly into nanoparticle synthesis cost structures, compressing margin predictability for batch producers.
- South African supply concentration:Primary platinum mining geography concentrates in the Bushveld Complex, exposing downstream processors to single-region geopolitical and labor disruption risks.
- Colloidal stability limitations:Aqueous suspension shelf life constraints restrict distribution radius for biomedical-grade formulations, necessitating localized production infrastructure.
Strategic Opportunities
- India's PLI scheme for hydrogen:Production-linked incentives for electrolyzer manufacturing are creating domestic catalyst demand that local nanomaterial suppliers can capture.
- Electrochemical sensor miniaturization:Glucose monitoring and environmental detection devices are specifying sub-50-nanometer platinum deposits for enhanced electron-transfer kinetics.
- EU Green Deal hydrogen targets:Renewable hydrogen production mandates are scaling electrolyzer deployments that require platinum-coated titanium electrodes.
Industry Challenges
- ISO 80004 terminology alignment:Cross-border nanomaterial classification inconsistencies are delaying customs clearance and creating batch rejection risks at import.
- Cleanroom synthesis capex:Pharmaceutical-grade nanoparticle production requires ISO 14644 Class 7 facilities that demand seven-figure capital commitments for greenfield entrants.
- OECD test guideline implementation:Standardized nanotoxicology protocols remain unevenly adopted, forcing redundant safety studies for multi-jurisdictional product registrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platinum Nanoparticles Market |
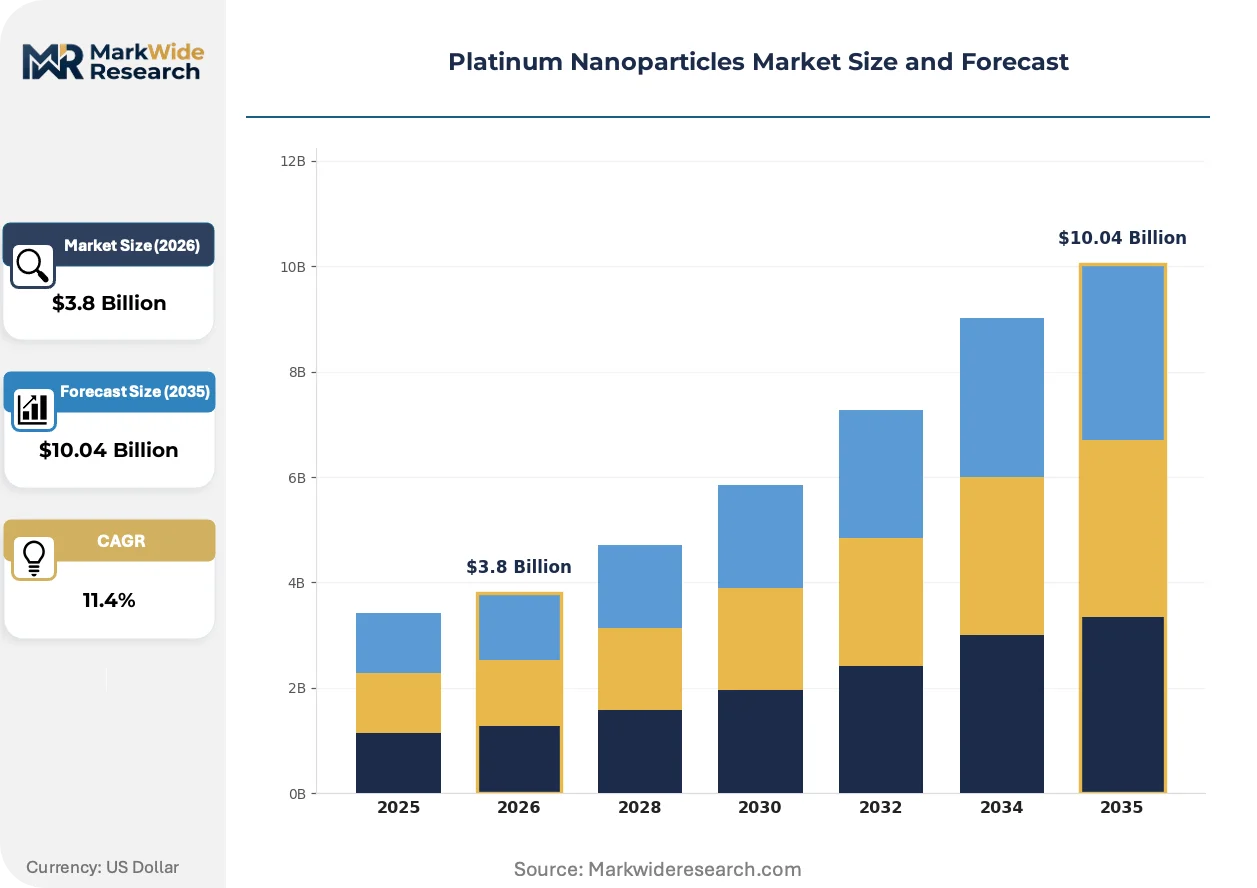
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colloidal Platinum, Supported Platinum, Platonic Nanoparticles, Core-Shell Nanoparticles Application: Catalysts, Drug Delivery, Sensors, Coatings End User: Pharmaceuticals, Electronics, Energy, Chemical Processing Form: Aqueous Suspension, Powder, Solid, Liquid Dispersion |
| Companies Covered | American Elements, TANAKA HOLDINGS Co., Ltd., NanoComposix, Strem Chemicals, Inc., Nanoshel LLC, Johnson Matthey, BASF, Tanaka Precious Metals, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platinum Nanoparticles Market Strategic Shifts
Synthesis methodology is bifurcating between legacy chemical reduction and precision electrochemical deposition, with quality specifications diverging sharply between automotive commodity grades and pharmaceutical custom batches.
Core-shell nanoparticle architecture is migrating from laboratory-scale demonstration to commercial fuel cell membrane-electrode assembly specifications. Heavy-duty truck manufacturers are qualifying platinum-cobalt and platinum-nickel surface layers for improved oxygen reduction reaction durability. This migration from homogeneous spherical particles to engineered heterostructures is compressing acceptable particle size distribution tolerances from ±15% to ±5%.
EPA Tier 4 and Euro 7 emissions standards are tightening particulate matter limits that indirectly affect platinum nanoparticle dispersion requirements in diesel oxidation catalysts. Catalyst coaters must now demonstrate sub-10-nanometer agglomeration control to maintain conversion efficiency at reduced metal loadings. Aftertreatment system integrators in Germany and the US are responding by specifying surfactant-stabilized colloidal feedstocks rather than conventional wet impregnation salts.
Research procurement patterns are fragmenting from centralized bulk purchasing to project-specific small-batch ordering with accelerated delivery requirements. University laboratories and CROs are displacing standing purchase agreements with on-demand aqueous suspension shipments from specialized nanomaterial distributors. This behavioral shift is most visible in the Boston-Cambridge biotech corridor and Basel pharmaceutical research cluster, where 48-hour delivery specifications are becoming standard tender requirements.
Platinum Nanoparticles Market Segmentation
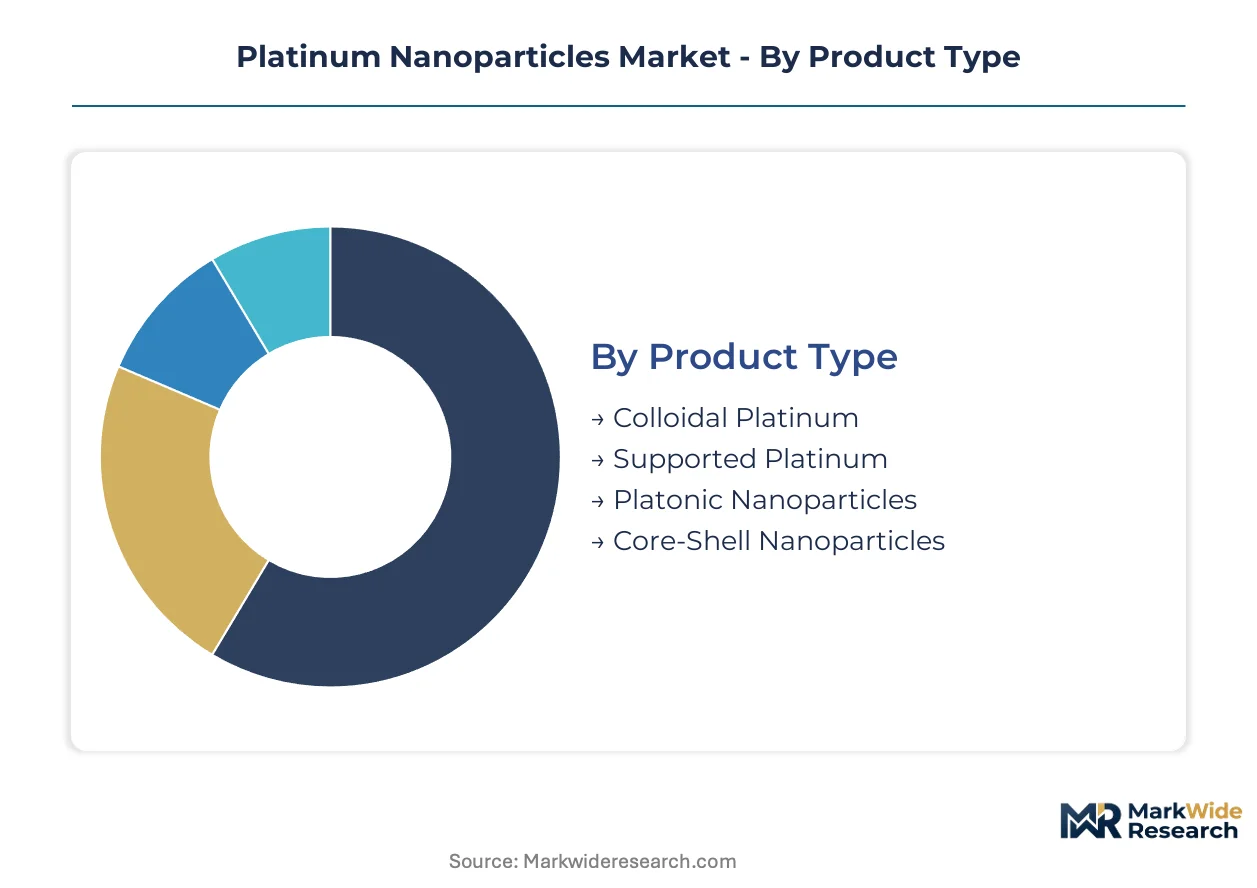
Segmentation in the platinum nanoparticles market reflects divergent purity specifications and regulatory pathways across end-use verticals. Pharmaceutical and automotive catalyst applications operate under incompatible quality frameworks, forcing suppliers to maintain distinct production lines and certification dossiers.
Product Type:
After-sales service intensity varies sharply across product types, with pharmaceutical-grade colloidal formulations requiring batch-specific stability monitoring and technical support that commodity catalyst grades do not demand.
- Colloidal Platinum:Aqueous suspensions stabilized by organic surfactants or polymer capping agents, typically specified at 99.95% purity for parenteral drug delivery. Demand concentrates in FDA-regulated oncology therapeutics where batch-to-batch consistency determines IND approval timelines.
- Supported Platinum:Nanoparticles dispersed on alumina, silica, or carbon carriers for fixed-bed catalytic reactors. German automotive catalyst coaters specify these for diesel oxidation applications under tightening Euro 7 particulate standards.
- Platonic Nanoparticles:Geometrically defined nanocrystals with controlled facet exposure for surface-sensitive catalysis. Research laboratories in the Boston-Cambridge corridor drive procurement for fundamental electrochemistry studies.
- Core-Shell Nanoparticles:Heterostructured architectures such as platinum-ruthenium or platinum-cobalt interfaces engineered for proton-exchange membrane fuel cell durability. Heavy-duty transport OEMs in Japan and South Korea are qualifying these for membrane-electrode assemblies.
Supported platinum holds the largest share; momentum sits with core-shell nanoparticles.
Application:
Application segmentation tracks divergent margin structures, with pharmaceutical drug delivery commanding price multiples over commodity catalyst uses due to regulatory compliance burdens and smaller batch scales.
- Catalysts:Automotive exhaust treatment and chemical process acceleration represent the volume anchor. EPA Tier 4 and Euro 7 emissions standards are compressing platinum loading requirements while demanding finer dispersion control.
- Drug Delivery:Nanoscale platinum carriers enable targeted oncology therapeutics through enhanced permeability and retention effects. FDA combination product frameworks govern these applications with extended approval timelines.
- Sensors:Electrochemical detection devices specify sub-50-nanometer platinum deposits for glucose monitoring and environmental contaminant detection. Miniaturization trends in point-of-care diagnostics are expanding specifications.
- Coatings:Antimicrobial and conductive surface treatments for medical devices and electronics substrates. REACH registration requirements in Europe restrict import of uncertified nanoparticle formulations.
Catalyst applications dominate volume; drug delivery is climbing the fastest.
End User:
End user segmentation reveals distinct procurement patterns, with pharmaceutical and energy sector buyers operating under opposing inventory strategies—just-in-time for drugs, long-term contracting for hydrogen infrastructure.
- Pharmaceuticals:CDMOs and innovator companies purchase colloidal platinum under master service agreements with audited quality protocols. FDA 21 CFR Part 11 compliance drives supplier qualification costs.
- Electronics:Semiconductor and sensor manufacturers specify narrow particle size distributions for printed electronics and MEMS fabrication. South Korean display panel producers are emerging as volume purchasers.
- Energy:Electrolyzer and fuel cell stack manufacturers source platinum-coated titanium electrodes. India's PLI scheme for hydrogen production is catalyzing domestic procurement.
- Chemical Processing:Petrochemical and fine chemical producers deploy supported platinum in hydrogenation and oxidation reactors. German chemical processing corridor concentration shapes regional supply relationships.
Chemical processing anchors historical demand; energy sector procurement is expanding most quickly.
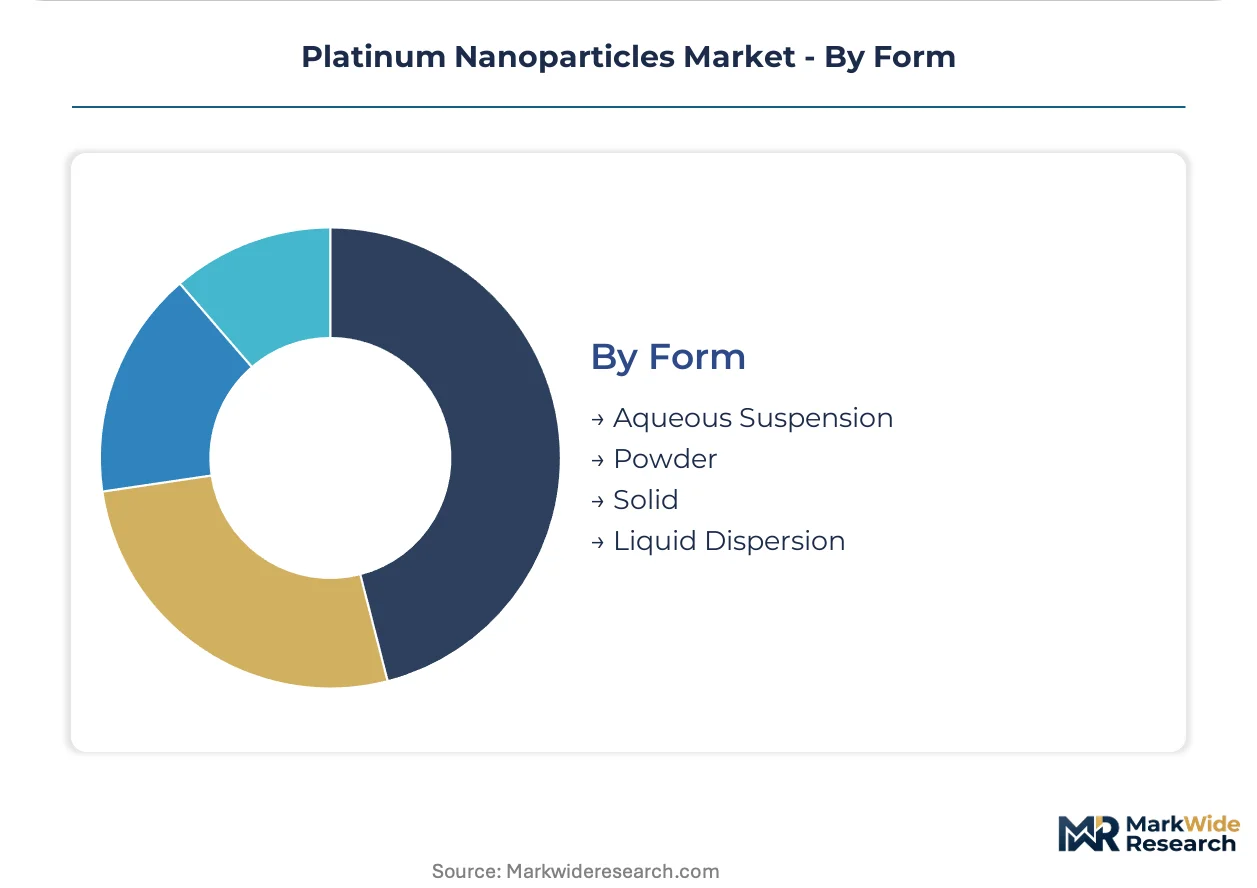
Form:
Form factor selection determines distribution economics and shelf-life constraints, with aqueous suspensions requiring cold-chain logistics that powder formulations avoid.
- Aqueous Suspension:Colloidal dispersions in deionized water with stabilizing agents for biomedical and research applications. NanoComposix and specialized distributors serve fragmented academic and CRO demand with 48-hour delivery specifications.
- Powder:Dried nanoparticle aggregates for catalyst manufacturing and materials research. Automotive catalyst coaters prefer spray-dried powders for wet impregnation processes.
- Solid:Compacted or embedded platinum nanoparticles in polymer or ceramic matrices for implantable devices. ISO 14644 cleanroom handling requirements restrict supplier base.
- Liquid Dispersion:Non-aqueous solvent-based formulations for organic-phase reactions and coating applications. Electronics manufacturers specify these for inkjet and screen-printing processes.
Powder forms command the largest volume; aqueous suspensions show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary platinum mining in South Africa's Bushveld Complex concentrates feedstock supply, while downstream nanoparticle synthesis clusters in Germany, Japan, the United States, and India reflect end-use demand patterns and regulatory proximity.
Germany
Automotive catalyst coaters and chemical processors drive colloidal platinum consumption for diesel oxidation and hydrogenation applications. REACH registration requirements through ECHA impose full toxicological dossiers on nanoparticle importers. The Rhine-Ruhr chemical corridor hosts BASF and Johnson Matthey integrated production networks serving European emissions-system integrators.
Japan
METI-backed nanomaterial initiatives are narrowing the geographic gap in high-purity platinum nanoparticle output for fuel cell and electrochemical applications. PMDA oversight governs pharmaceutical-grade formulations entering oncology therapeutic pipelines. TANAKA HOLDINGS leverages its precious metals heritage to dominate electrochemical catalyst grades from Tokyo-Osaka industrial centers.
United States
EPA Tier 4 emissions standards compress platinum loading requirements while expanding specifications for finer dispersion control in aftertreatment systems. FDA combination product frameworks govern nanoscale platinum carriers in targeted drug delivery. The Boston-Cambridge biotech corridor drives 48-hour delivery specifications for aqueous suspension procurement from specialized distributors.
India
The PLI scheme for hydrogen production is catalyzing domestic catalyst demand for electrolyzer manufacturing. BIS standards and CDSCO oversight create dual regulatory pathways for industrial and pharmaceutical grades. Gujarat and Maharashtra chemical processing clusters are emerging as localized production hubs to serve South Asian hydrogen economy deployments.
South Korea
Heavy-duty transport OEMs are qualifying core-shell platinum-ruthenium architectures for membrane-electrode assemblies in proton-exchange membrane fuel cells. MFDS regulates therapeutic nanoparticles while KBA emissions standards align with Euro 7 particulate limits. Display panel producers in Gyeonggi-do are expanding specifications for narrow particle size distributions in printed electronics applications.
Platinum Nanoparticles Market Competitive Environment
Integrated precious metals refiners and specialized nanomaterial distributors split the market along purity-grade lines. The structure concentrates around three archetypes: diversified chemical conglomerates with captive platinum group metal supply, dedicated nanomaterial synthesis houses serving research and pharmaceutical markets, and automotive catalyst coaters with backward integration into nanoparticle production. Competitive moves center on cleanroom synthesis capacity expansion for pharmaceutical-grade certification and strategic partnerships with fuel cell stack manufacturers for core-shell architecture qualification.
Among diversified chemical conglomerates, BASF and Johnson Matthey exemplify the integrated refiner-to-catalyst supply chain archetype. TANAKA HOLDINGS occupies a position within the precious metals heritage specialist tier, while NanoComposix represents the research-focused aqueous suspension distributor archetype serving fragmented academic and CRO demand with accelerated delivery specifications.
| Leading Market Players |
|---|
| American Elements |
| TANAKA HOLDINGS Co., Ltd. |
| NanoComposix |
| Strem Chemicals, Inc. |
| Nanoshel LLC |
| Johnson Matthey |
| BASF |
| Tanaka Precious Metals |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
The Bushveld Complex in South Africa concentrates primary platinum mining capacity, creating asymmetric pricing power for downstream processors in Germany and Japan who command premium positioning through ECHA REACH dossiers and METI-backed nanomaterial certifications. This geographic disconnect between raw material extraction and value-added synthesis shapes margin distribution across the supply chain.
Pricing Analysis
REACH registration requirements dictate the pricing tier structure across European pharmaceutical and catalyst applications. Three-tier pricing structure across pharmaceutical-grade colloidal, industrial catalyst, and research-standard suspensions separates batch-specific stability guarantees from commodity wet impregnation salts. Cost compression in automotive catalyst grades is intensifying because EPA Tier 4 and Euro 7 standards demand finer dispersion control at reduced metal loadings. Chemical processing buyers exhibit highest price sensitivity due to volume contracting norms, while oncology drug delivery sponsors accept substantial premiums for FDA-audited quality protocols.
Supply Chain Analysis
Primary platinum sponge and salt feedstock draws from South African mining operations, with secondary refining concentrated in the United States and Germany. Nanoparticle synthesis rests on sodium borohydride reducing agents, polymer capping agents, and ISO 14644 Class 7 cleanroom infrastructure. Single-source vulnerability runs through the Bushveld Complex labor and geopolitical exposure. Distribution runs through integrated precious metals refiners for catalyst grades and specialized nanomaterial distributors for aqueous suspension research orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platinum nanoparticle markets reward service-attach strategies where batch-specific stability monitoring and regulatory compliance consulting expand faster than commodity particle sales. Technical support contracts for pharmaceutical-grade formulations now represent the fastest-growing revenue layer.
For Market Incumbents: Insulate core catalyst relationships through backward integration into South African feedstock offtake agreements and ECHA REACH registration maintenance that creates compliance moats against Asian entrants. Capacity addition in Gujarat and Maharashtra chemical clusters captures India's PLI-scheme electrolyzer demand before local synthesis scale-up. Defensive patent positioning around core-shell platinum-ruthenium architectures protects fuel cell membrane-electrode assembly specifications from Korean and Japanese challengers. For New Entrants and Emerging Players: Establish a beachhead in aqueous suspension distribution for Boston-Cambridge and Basel research corridors where 48-hour delivery specifications and project-specific small-batch ordering fragment incumbent standing purchase agreements. India's hydrogen economy catalyst demand offers the most penetrable geography given PLI scheme timing and nascent local production. A specialized distributor model with cold-chain logistics partnerships bypasses the seven-figure cleanroom capex barrier that protects pharmaceutical-grade incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to monetize non-core nanomaterial divisions lacking pharmaceutical-grade certification pathways. Long-term viability centers on hydrogen economy catalyst demand durability and oncology therapeutic pipeline expansion. The signal to watch is heavy-duty transport OEM qualification timelines for core-shell architectures in membrane-electrode assemblies.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Synthesis Certification | ISO 14644 Class 7 qualification opens FDA-regulated pharmaceutical supply relationships. |
| Core-Shell Architecture Patenting | Platinum-ruthenium interface protection secures fuel cell durability specifications from Japanese OEMs. |
| REACH Dossier Maintenance | ECHA registration continuity preserves European catalyst and drug delivery market access. |
| Localized Production in India | Gujarat and Maharashtra hubs capture PLI-scheme electrolyzer catalyst demand before import substitution. |
| Aqueous Suspension Distribution | 48-hour delivery capabilities serve fragmented Boston-Cambridge and Basel research procurement. |
Study Parameters
A standing panel of nanoparticle synthesis chemists, pharmaceutical regulatory affairs leads, automotive catalyst procurement managers, and fuel cell stack engineering directors provided ongoing calibration against secondary validation from ECHA registration databases, EPA emissions compliance filings, METI nanomaterial initiative disclosures, and India PLI scheme administrative records. Bottom-up demand modeling across end-use verticals triangulated with top-down precious metals flow analysis.
Scenario-bracketing framed projections across the analysis window using segmented demand curves for pharmaceutical drug delivery, automotive catalyst, and hydrogen economy applications. Modeled dimensions included purity grade tier, particle architecture type, form factor, and regional regulatory cluster. CAGRs derived from historical precious metals price elasticity and end-use adoption curve fitting, with hydrogen deployment rates and oncology therapeutic approval timelines as key variable inputs.
Stress conditions across platinum group metal spot volatility, South African supply disruption, and REACH registration timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against IEA hydrogen project databases and FDA combination product approval records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Nanocatalysts Market
Nanomaterials
Metal Nitride Nanoparticles Market
Nanomaterials
Global Nanoclay Reinforcement Market
Nanomaterials
Boron Nitride Nanotubes Market
Nanomaterials
Nano Fillers Market
Nanomaterials
Nanotools Market
Nanomaterials
Carbon Nanotubes (Cnts) Market
Nanomaterials
Nanochemicals Market
Nanomaterials
Nanocomposites Market
Nanomaterials
Global Gold Nanorods Market
Nanomaterials
Nanomaterials Market
Nanomaterials
Metal Nanoparticles Market
Nanomaterials
Polymeric Nanoparticles Market
Nanomaterials
Asia-Pacific Nanocellulose Materials Market
Nanomaterials
Nanoparticle Titanium Dioxide (Tio2) Market
Nanomaterials
United States Gold Nanoparticles Market