
 Blood Processing and Storage Equipment Market | 2026-2036
Blood Processing and Storage Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Processing and Storage Equipment Market Intelligence
Revenue from automated system consumables and software licensing is rewriting the traditional margin structure once dominated by capital equipment sales. This shift favors companies with strong installed bases and service networks. Terumo Corporation leverages its extensive portfolio of collection and processing disposables. Haemonetics Corporation specializes in automated plasma and platelet collection systems, anchoring its position in specialized donation centers.
Blood processing and storage equipment encompasses devices for separating, preserving, and managing whole blood and its components. These systems, including centrifuges operating at specific g-forces and refrigerators maintaining a 2-6°C range, ensure the viability of blood products for transfusion medicine. While centrifuges and refrigerators remain core products, automated systems are displacing manual processing technologies due to superior efficiency. In application segments, blood banks and hospitals represent the largest consumers, driven by constant transfusion needs.
Market access is governed by stringent medical device regulations, including FDA clearance in the United States and CE marking under the MDR in Europe. China's NMPA imposes its own rigorous standards, shaping product design and quality management systems globally. These frameworks mandate strict traceability for all equipment. Future competitive advantage will hinge on navigating these divergent regulatory pathways while investing in technology that meets evolving clinical standards.
Market Dynamics
The fundamental dynamic shaping this market is the industry-wide migration from manual blood processing to fully automated systems. This transition is driven by demands for higher throughput, improved safety through reduced manual error, and enhanced component yield from each donation.
Growth Catalysts
- Automated Systems:The adoption of automated equipment for blood component separation enhances throughput and safety in high-volume blood banks, directly supporting the needs of transfusion medicine.
- Public Health Investment:China's substantial investment in its public health infrastructure, combined with demographic shifts toward an older population, creates concentrated demand for blood products and related equipment.
- Hospital Transfusion Needs:Large hospitals are increasing their utilization of sophisticated processing and storage equipment to manage complex transfusion requirements for surgery, oncology, and chronic disease treatment.
Market Restraints
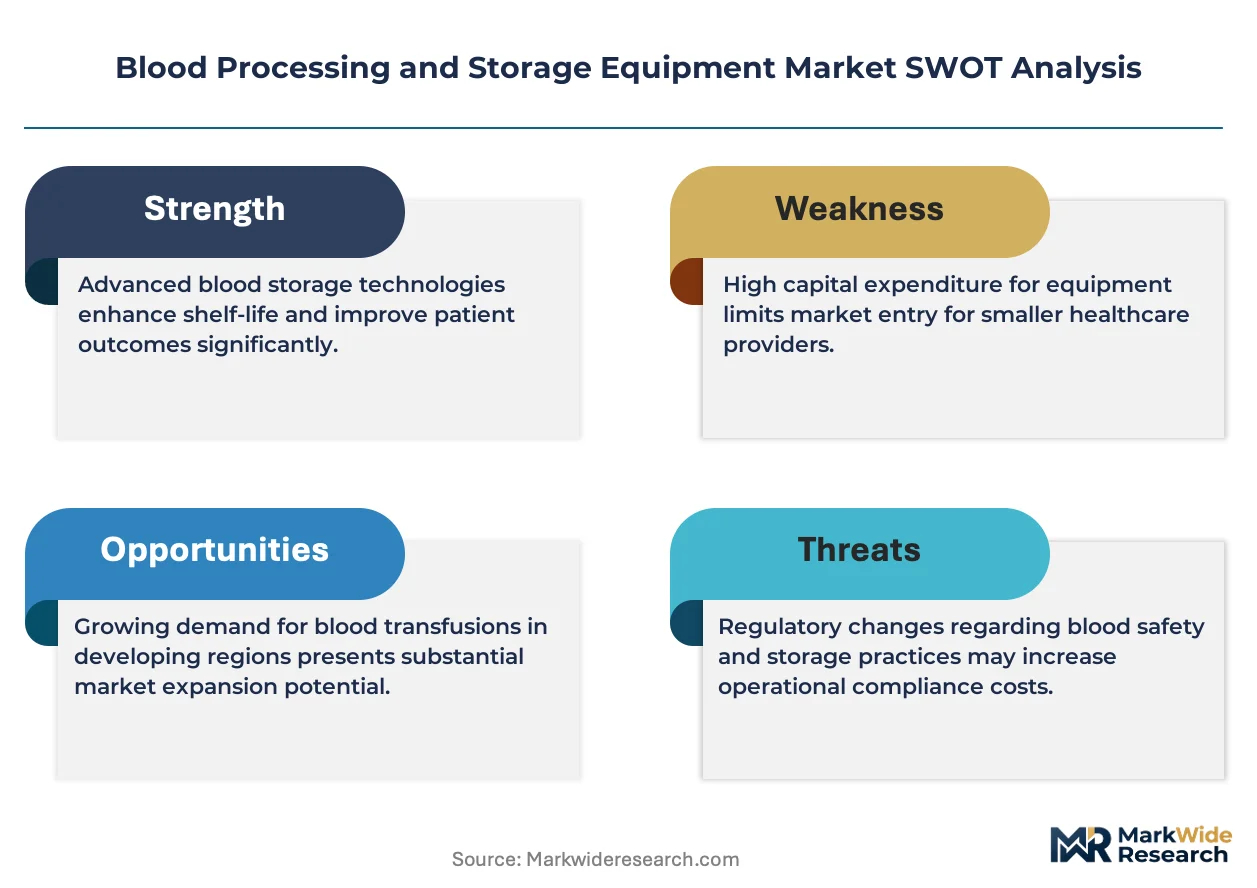
- High Capital Costs:The significant upfront investment required for fully automated blood processing and storage systems presents a substantial barrier for smaller blood banks and hospitals in developing regions.
- Regulatory Complexity:Navigating divergent and stringent regulatory frameworks, such as FDA clearance, European MDR, and China's NMPA standards, increases compliance costs and extends product development timelines.
- Cold Chain Dependency:The strict requirement for a 2-6°C temperature range for blood product storage makes the supply chain vulnerable to disruptions, particularly in regions with unreliable power infrastructure.
Strategic Opportunities
- Point-of-Care Technology:Developing portable, smaller-footprint blood processing units creates opportunities to serve military field hospitals, disaster response teams, and rural clinics that lack centralized laboratory facilities.
- Software and Data Analytics:Offering subscription-based software for inventory management, donor tracking, and equipment performance analytics provides a recurring revenue stream beyond capital equipment sales.
- Emerging Market Modernization:Targeting national health systems in Southeast Asia and Latin America that are actively upgrading their blood banking infrastructure from manual methods to semi-automated or automated platforms.
Industry Challenges
- Skilled Personnel Shortage:A lack of technicians and clinical laboratory scientists trained to operate, calibrate, and maintain advanced automated blood processing systems limits optimal equipment utilization.
- System Interoperability:Integrating new automated equipment with existing, often proprietary, Laboratory Information Systems (LIS) and Hospital Information Systems (HIS) presents significant technical and data-flow challenges.
- Consumable Lock-In:The dependence on proprietary disposables and reagents specific to one manufacturer's equipment creates supply chain vulnerabilities and limits procurement flexibility for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Processing and Storage Equipment Market |
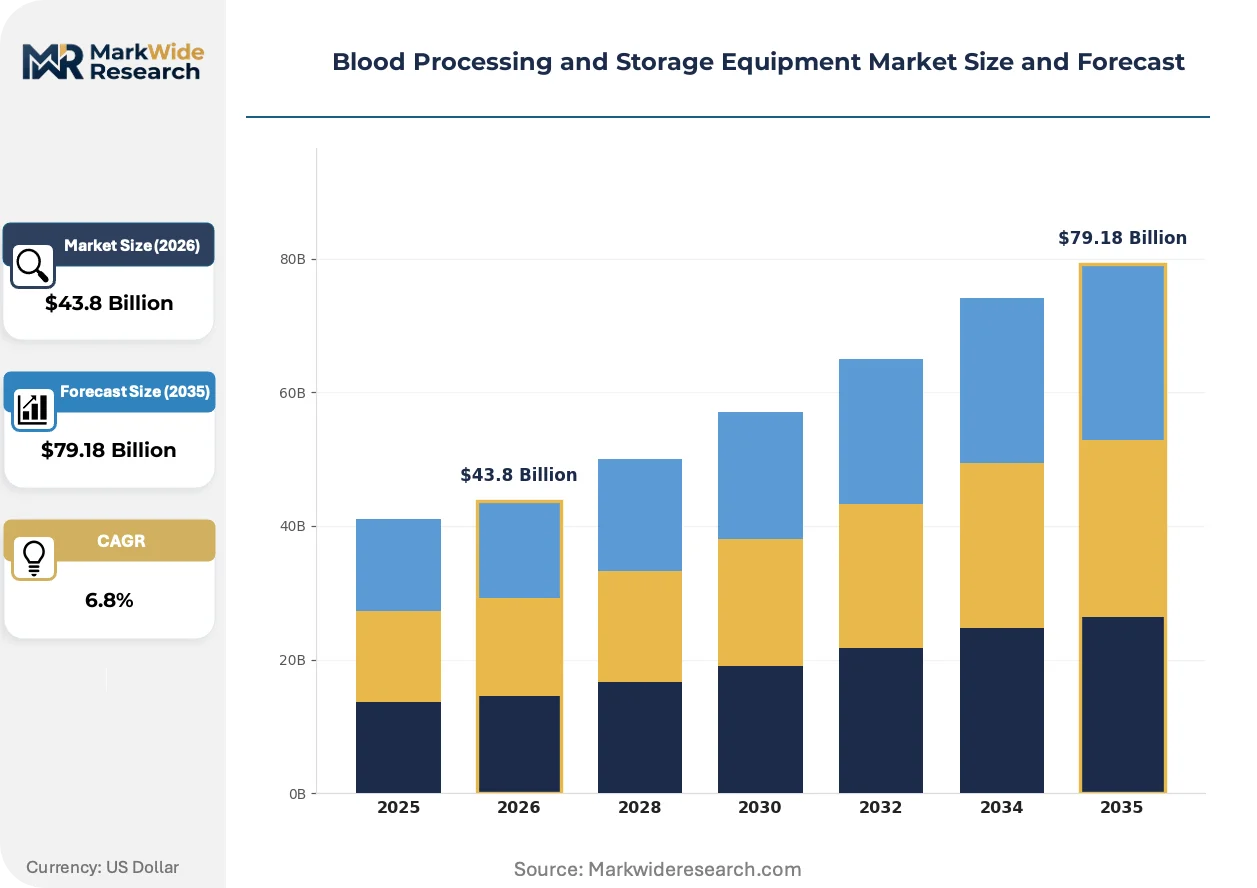
| Market Size in 2026 | $43.8 Billion |
| Market Size in 2035 | $79.18 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collection Bags, Centrifuges, Refrigerators, Freezers Technology: Automated Systems, Manual Processing, Cold Storage, Blood Warmers Application: Transfusion Medicine, Research Laboratories, Blood Banks, Hospitals End User: Clinics, Blood Donation Centers, Healthcare Facilities, Rehabilitation Centers |
| Companies Covered | Terumo Corporation, Grifols, Becton, Dickinson and Company, Abbott Laboratories, Haemonetics Corporation, F. Hoffmann-La Roche Ltd, Bio-Rad Laboratories, Inc., Thermo Fisher Scientific, Beckman Coulter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Processing and Storage Equipment Market Strategic Shifts & Innovations
The market's evolution is defined by the integration of data management into physical hardware and a business model shift toward consumables and services. This pivot redefines value away from the initial capital sale toward the entire lifecycle of the installed base.
Pathogen reduction technology (PRT) uses photochemical processes to inactivate a broad spectrum of infectious agents in plasma and platelets. Major blood centers and hospital systems are progressively implementing PRT to add a layer of safety beyond nucleic acid testing. The adoption of PRT is collapsing the perceived risk difference between screened and treated components, establishing a higher universal standard for transfusion safety.
Stringent traceability requirements embedded within regulations like the FDA's Unique Device Identification (UDI) system and Europe's Medical Device Regulation (MDR) are now standard. These rules compel manufacturers to serialize equipment and key consumables, enabling full lifecycle tracking. This regulatory pressure most acutely impacts software and disposables, which must now integrate seamlessly into digital traceability ecosystems within hospitals and blood banks.
A clear behavioral change is evident as end-users move from capital expenditures to operational expenditures through reagent rental and leasing agreements. This model disrupts traditional sales by bundling equipment, service, and proprietary consumables into a single, predictable cost-per-test or monthly payment. The shift is most pronounced in high-volume plasma collection centers and consolidated hospital laboratory networks across North America and Western Europe.
Blood Processing and Storage Equipment Market Segmentation
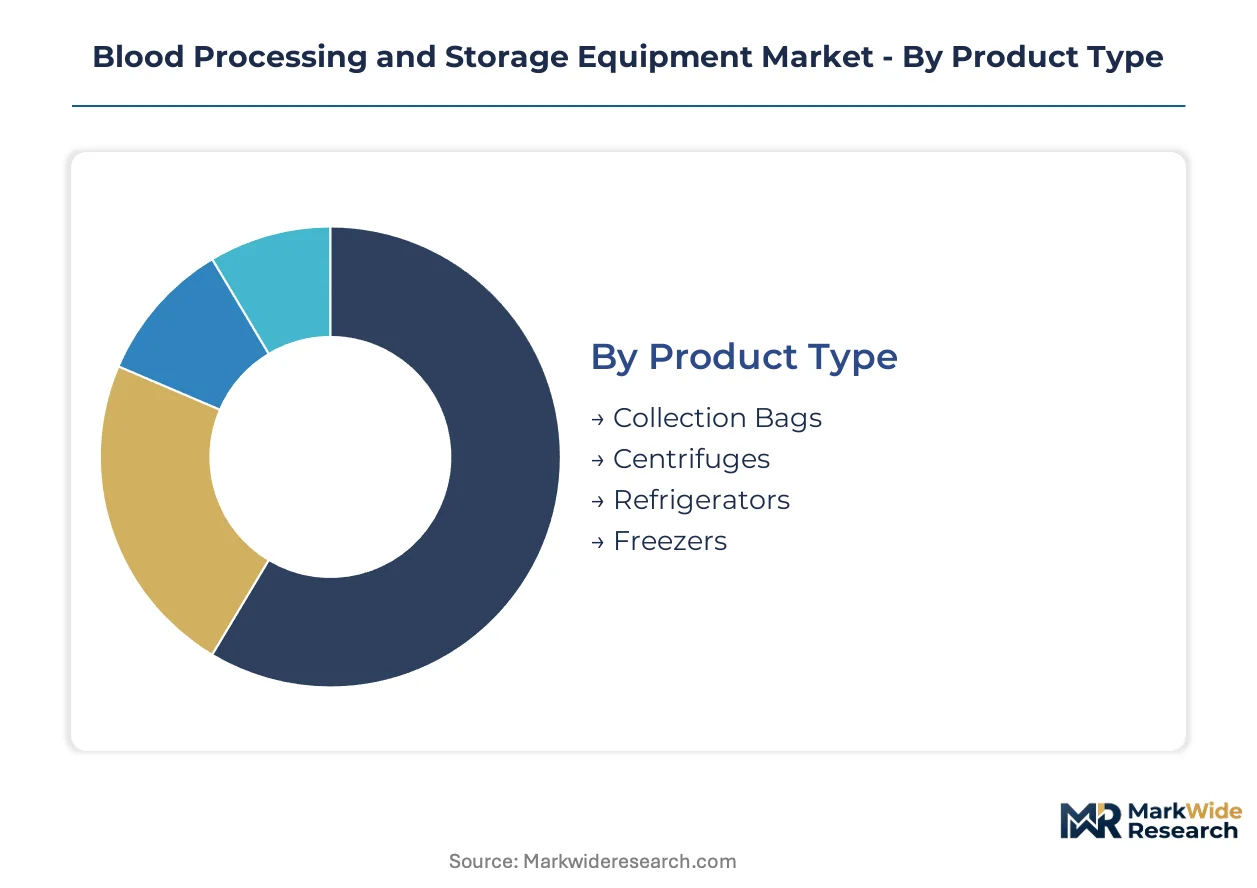
Segmentation within the blood processing and storage equipment market reveals how different product types, technologies, applications, and end-users contribute to market dynamics. Understanding these distinct segments helps identify specific demand patterns and areas of technological investment across the industry.
Product Type:
The product type segment illustrates differing procurement cycles, with consumables like collection bags having high turnover and capital equipment such as centrifuges representing longer investment horizons.
- Centrifuges:These devices separate whole blood into components like plasma, platelets, and red blood cells using specific g-forces. Demand concentrates in large hospital transfusion departments and regional blood processing centers due to the need for efficient component preparation.
- Refrigerators:Specialized refrigerators maintain blood products within a narrow 2-6°C temperature range, critical for preserving viability. Hospitals and blood banks across China and Europe require these systems for secure, long-term storage of transfusable units.
- Collection Bags:These sterile, single-use containers are essential for drawing and temporarily storing whole blood from donors. Blood donation centers and mobile collection units drive constant demand for these high-volume consumables.
- Freezers:Ultra-low temperature freezers are used for extended preservation of plasma, cryoprecipitate, and rare blood types, often requiring temperatures below -30°C. Specialized reference laboratories and research facilities utilize these units.
Collection Bags anchor the volume base while Centrifuges gain share at the steepest rate.
Technology:
Technological segments show varied cost implications, with automated systems demanding higher initial capital but offering long-term operational savings and improved safety.
- Automated Systems:These integrated platforms perform blood component separation, processing, and sometimes pathogen reduction with minimal human intervention. Large consolidated blood centers in North America and Western Europe adopt automated systems for enhanced safety and throughput efficiency.
- Cold Storage:This technology encompasses specialized refrigeration and freezing units essential for maintaining the viability and integrity of blood products. Hospitals and blood banks globally depend on reliable cold storage infrastructure to meet stringent regulatory requirements.
- Manual Processing:Traditional manual methods involve hands-on separation and handling of blood components, often requiring significant technician time. Smaller blood banks and clinics in developing regions still utilize manual processing due to lower upfront costs.
- Blood Warmers:Devices that safely warm refrigerated or frozen blood products to body temperature before transfusion, preventing hypothermia in patients. Emergency rooms and surgical suites frequently employ blood warmers for rapid patient care.
Automated Systems are expanding most quickly, driven by efficiency and safety demands across the industry.
Application:
Application segments demonstrate differing volume requirements, with transfusion medicine driving consistent, high-volume demand for processed blood products.
- Blood Banks:These facilities collect, process, test, and store blood donations, supplying hospitals with various blood components. Blood banks represent a primary consumer of processing and storage equipment, especially automated platforms.
- Hospitals:Hospitals utilize blood processing and storage equipment for direct patient care, including surgeries, emergency transfusions, and chronic disease management. Large hospital networks in urban centers maintain extensive inventories and processing capabilities.
- Transfusion Medicine:This broad field encompasses all aspects of blood collection, processing, testing, storage, and administration for therapeutic purposes. Regulatory bodies like the FDA and Europe's MDR significantly influence equipment standards within transfusion medicine.
- Research Laboratories:Academic and commercial research laboratories use specialized equipment for blood component analysis, drug development, and disease research. These labs often require high-precision centrifuges and advanced storage solutions.
Blood Banks and Hospitals collectively represent the largest volume consumers of blood processing equipment.
End User:
End user segments reflect distinct customer types, ranging from centralized processing facilities to direct patient care environments with varying equipment needs.
- Blood Donation Centers:These specialized facilities focus on collecting whole blood and apheresis donations from volunteers. They primarily procure collection bags and initial processing equipment before transferring blood to central processing.
- Healthcare Facilities:This broad category includes hospitals, clinics, and specialized medical centers that utilize blood products for patient treatment. Healthcare facilities require robust storage and processing capabilities for diverse clinical needs.
- Clinics:Smaller outpatient clinics and specialized treatment centers may have limited blood storage needs, often relying on external blood banks for supply. They typically require basic refrigeration units and blood warmers.
- Rehabilitation Centers:These centers rarely perform direct blood transfusions but may require minimal storage for emergency use or for patients receiving specific blood-derived therapies. Their equipment needs are generally low volume.
Blood Donation Centers and Healthcare Facilities exert the most significant purchasing influence within the market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for blood processing and storage equipment differs significantly across major global markets. While developed nations prioritize automated systems and advanced cold chain solutions, emerging economies often balance cost-effectiveness with modernization efforts. This dynamic influences investment patterns in critical infrastructure.
United States
United States demand for advanced blood processing equipment stems from large hospital networks and specialized transfusion medicine centers. The FDA's stringent regulatory framework, including Unique Device Identification (UDI) requirements, governs product design and traceability. Major medical technology hubs like Boston and San Diego drive innovation in automated systems and software integration.
Germany
German hospitals and blood banks require sophisticated processing and storage solutions to serve an aging population and maintain high clinical standards. European MDR regulations mandate rigorous safety and performance criteria for all medical devices. The Rhine-Main region, with its strong biotech presence, fosters development in cold storage and automated platforms.
China
China's substantial public health infrastructure investments and demographic shifts create immense demand for blood products and related equipment. The NMPA imposes rigorous standards for medical devices, influencing global product design. Major urban centers like Shanghai and Beijing are hubs for large-scale blood processing and storage facilities.
India
India's expanding healthcare sector and initiatives to modernize blood banking infrastructure are driving the need for semi-automated and automated platforms. The CDSCO regulates medical devices, pushing for improved quality and safety standards. Cities such as Mumbai and Bangalore see growing investment in advanced blood processing centers.
Japan
Japan's advanced medical system and rapidly aging population necessitate efficient blood processing and long-term storage capabilities. The PMDA ensures strict regulatory compliance for all blood-related equipment and consumables. Tokyo and Osaka remain key centers for the adoption of cutting-edge pathogen reduction technologies.
Blood Processing and Storage Equipment Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered market structure. The industry features a mix of multinational medical device conglomerates and specialized blood processing technology providers. Key strategic archetypes include broad-portfolio suppliers, niche technology innovators, and regional service providers. Companies pursue portfolio diversification and strategic partnerships to expand their market reach.
Specialized technology providers, such as Haemonetics Corporation, anchor positions in automated plasma and platelet collection systems for specialized donation centers. Terumo Corporation, a Japan-based medical device company, exemplifies the broad-portfolio approach with extensive collection and processing disposables. Grifols, S.A., a Spanish multinational pharmaceutical and chemical manufacturer, represents a vertically integrated player with significant presence in plasma collection and fractionation. These entities collectively demonstrate the varied strategies employed to meet the diverse needs of blood banks and hospitals globally, ranging from high-volume consumables to specialized automation.
| Leading Market Players |
|---|
| Terumo Corporation |
| Grifols |
| Becton, Dickinson and Company |
| Abbott Laboratories |
| Haemonetics Corporation |
| F. Hoffmann-La Roche Ltd |
| Bio-Rad Laboratories, Inc. |
| Thermo Fisher Scientific |
| Beckman Coulter |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes' cost dynamics directly influence the pricing of advanced blood processing equipment and consumables, linking supply concentration in Asia to downstream price differentiation in Western markets. This connection shapes procurement strategies for hospitals and blood banks globally.
Pricing Analysis
Long-term contract agreements dominate the procurement of automated blood processing systems, bundling equipment, service, and consumables into predictable operational costs. Price differentiation stems from the level of regulatory clearance (e.g., FDA vs. CE marking) and the breadth of after-sales technical support. Pricing softness runs through high-volume consumables due to intense competition among numerous manufacturers. Smaller clinics and blood banks in developing regions exhibit the highest price sensitivity, often opting for manual or semi-automated, lower-cost solutions.
Supply Chain Analysis
US export controls on specialized medical device components limit the cross-border flow of advanced technologies, impacting manufacturing locations. Geographic supply concentration for blood processing equipment centers on China, Germany, and Japan, which produce critical electronic components and high-grade plastics. Raw material dependencies include medical-grade polymers for collection bags and precision-engineered electronic modules for automated systems. A structural risk involves single-source vulnerability for highly specialized pathogen reduction reagents. Distribution runs through direct sales teams to large hospital networks and medical device distributors serving smaller facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands a substitution defense as centralized processing faces threats from decentralized, point-of-care blood management solutions. Incumbents must navigate this shift by integrating new technologies and service models.
For Market Incumbents: Entrench existing installed bases by aggressively expanding subscription-based software and service contracts for automated systems. This counters the shift towards operational expenditures and reduces vulnerability to new entrants offering lower-cost alternatives. Invest in R&D for next-generation automation that integrates AI-driven analytics, reinforcing efficiency and safety standards against emerging pathogen reduction technologies.
For New Entrants and Emerging Players: Establish a beachhead in underserved markets like rural clinics and military field hospitals with portable, smaller-footprint processing units. Target national health systems in Southeast Asia and Latin America actively upgrading from manual methods. The most penetrable segment involves semi-automated solutions that balance cost-effectiveness with improved throughput. A go-to-market angle focusing on flexible leasing models with integrated training programs can accelerate adoption.
For Investors and Strategic Acquirers: European Medical Device Regulation (MDR) reshapes the acquisition landscape by prioritizing companies with robust regulatory compliance and traceability systems. The market exhibits long-term viability driven by constant transfusion needs and an aging global population. Acquisition targets should focus on niche technology innovators specializing in software integration or advanced pathogen reduction capabilities. A critical signal to watch is the increasing market share captured by companies leveraging consumable lock-in strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | Securing FDA or NMPA clearance enables access to major markets and validates product safety for blood products. |
| Manufacturing Scale-Up | Expanding production capacity for collection bags and disposables meets constant global demand and reduces unit costs. |
| Platform Integration | Seamlessly connecting automated systems with existing LIS/HIS improves data flow and operational efficiency for hospitals. |
| Geographic Expansion | Entering national health systems in Southeast Asia or Latin America captures modernization demand for blood banking. |
| Hospital System Partnership | Collaborating with large hospital networks ensures direct market access and tailored solutions for complex transfusion needs. |
Research Approach
Desk research of medical device filings, public health reports, and academic literature preceded structured interviews with blood bank directors, hospital procurement managers, and regulatory affairs specialists. This approach combined primary insights with secondary validation. Bottom-up data collection from key market players was triangulated with top-down market sizing estimates.
Assumptions regarding stable regulatory environments and sustained public health investment were held fixed, while technological adoption rates varied across regions over the projection horizon. The analytical framework modeled segmentation dimensions including Product Type, Technology, Application, End User, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected demand for blood products. Industry-specific inputs included projected blood donation volumes and demographic shifts impacting transfusion needs.
Sensitivities concentrate around unforeseen regulatory shifts or major geopolitical disruptions affecting medical device supply chains. Forecasts reflect a specific set of assumptions regarding market evolution and technological development. Material shifts in public health policy or the emergence of widespread blood substitutes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Multi-Cuvette Spectrophotometer Market
Laboratory Equipment
Global Blood Gas Analyzers Market
Laboratory Equipment
Latin America Laboratory Equipment and Disposables Market
Laboratory Equipment
Global Laboratory Equipment Services Market
Laboratory Equipment
Global Slide Stainer Market
Laboratory Equipment
Laboratory Fume Hoods Market
Laboratory Equipment
Life Sciences and Laboratory Equipment Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Muffle Laboratory Furnaces Market
Laboratory Equipment
Microplate Washer Market
Laboratory Equipment
Scalable Clinical Chemistry Analyzers Market
Laboratory Equipment
Absorbance Micro Plate Reader Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Cuvettes Market
Laboratory Equipment
Microplate Reader Market