
 Global Slide Stainer Market | 2026-2036
Global Slide Stainer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Slide Stainer Market Foresight
Multi-source procurement of staining reagents and consumables is expanding as hospital networks diversify vendor relationships beyond single-platform dependencies. Thermo Fisher Scientific leverages its broad life sciences portfolio to sustain integrated workflow sales across diagnostic laboratories. Agilent Technologies anchors its position through specialized chromogenic and fluorescent detection systems. Sakura Finetek competes aggressively on automated throughput metrics in high-volume pathology settings.
A slide stainer is an instrument that applies chemical dyes, antibodies, or fluorescent markers to prepared tissue or cell specimens mounted on glass slides, typically processing batches of 20 to 100 slides per run with programmable temperature and incubation parameters. Its primary purpose is to standardize histological and cytological visualization for cancer diagnosis, infectious disease identification, and research microscopy. Automated slide stainers now dominate capital expenditure budgets due to labor cost containment and reproducibility demands, while digital imaging-based technology segments capture premium pricing from telepathology integration. Manual slide stainers retain niche demand in resource-limited settings and specialized research protocols where protocol flexibility outweighs throughput requirements.
FDA 510(k) clearance pathways and the EU In Vitro Diagnostic Regulation reshape product development timelines and clinical evidence requirements for manufacturers seeking market access. ISO 15189 accreditation standards for medical laboratories drive recurring demand for validated staining protocols and quality-controlled consumables. Stakeholders must monitor evolving digital pathology reimbursement frameworks and interoperability standards that determine whether instrument investments translate into sustainable revenue streams.
Market Dynamics
Automated slide stainer deployment is accelerating as diagnostic laboratories face mounting pressure to process rising pathology caseloads while containing labor costs and ensuring reproducible staining quality across distributed networks.
Growth Catalysts
- FDA 510(k) clearance streamlining:Expedited regulatory pathways for automated in vitro diagnostic devices are compressing time-to-market for manufacturers targeting US diagnostic laboratories.
- Histopathology workload surge:Cancer screening program expansions in Germany and Japan are forcing centralized lab networks to upgrade batch-processing capacity.
- ISO 15189 accreditation mandates:Medical laboratory quality standards across Europe are institutionalizing demand for validated, traceable staining protocols.
Market Restraints
- Reagent supply concentration:Specialty antibody and chromogenic dye production clusters heavily in Switzerland and Massachusetts, creating single-source vulnerabilities.
- Capital intensity barriers:High-throughput platforms require substantial upfront investment, excluding resource-limited settings and small independent pathology practices.
- EU MDR compliance friction:The In Vitro Diagnostic Regulation's clinical evidence requirements are extending product development timelines and inflating regulatory costs.
Strategic Opportunities
- India diagnostic network buildout:Hospital chain consolidation and government health infrastructure programs are creating first-time automated staining demand outside traditional mature markets.
- Digital pathology convergence:Integration of whole-slide imaging with automated staining workflows is opening telepathology revenue streams for platform vendors.
- Consumables unbundling:Reagent rental and per-slide pricing models are penetrating price-sensitive segments previously locked out of capital purchase markets.
Industry Challenges
- Histotechnologist talent scarcity:Specialized technician shortages in the United States and United Kingdom are constraining lab operational scaling regardless of equipment availability.
- Legacy system integration complexity:Proprietary communication protocols between staining platforms and laboratory information systems are fragmenting workflow automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Slide Stainer Market |
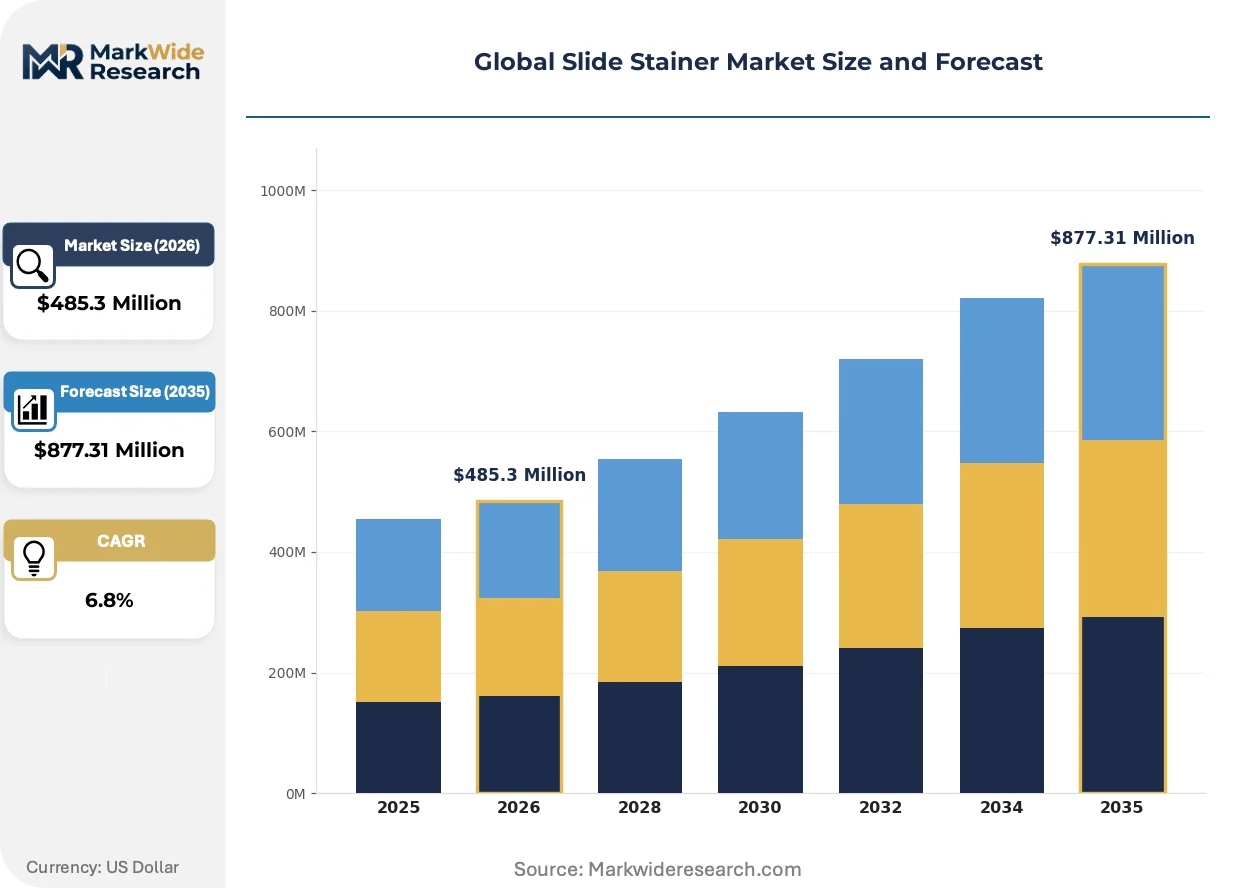
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $877.31 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
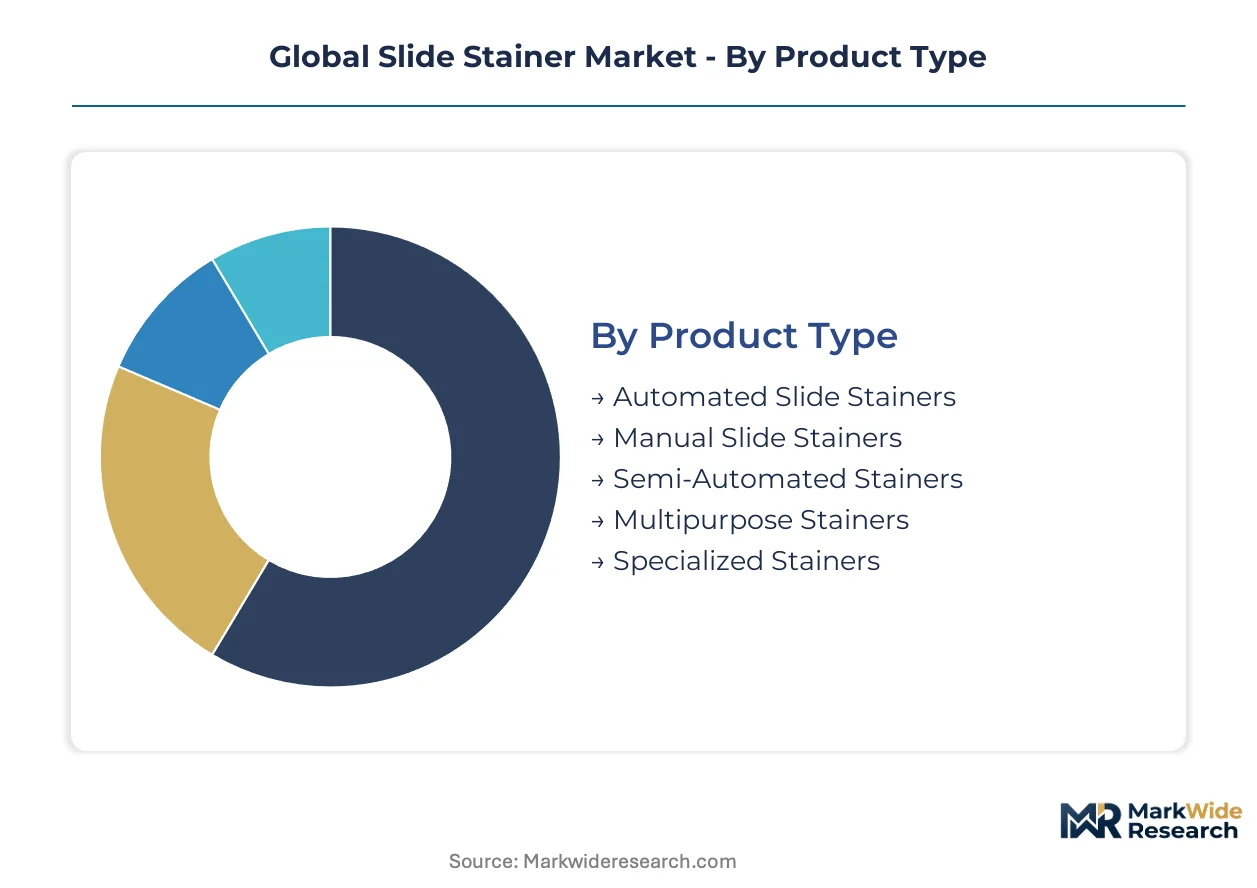
| Segmentation | Product Type: Automated Slide Stainers, Manual Slide Stainers, Semi-Automated Stainers, Multipurpose Stainers, Specialized Stainers Technology: Chromogenic, Fluorescent, Digital Imaging-Based, Immunohistochemistry, Cytochemical Application: Pathology Labs, Forensic Diagnostics, Tissue Engineering, Cytology, Veterinary Testing End User: Research Institutes, Diagnostic Laboratories, Pharmaceutical Companies, Academic Hospitals, Biotech Firms |
| Companies Covered | Agilent Technologies, Sakura Finetek, Thermo Fisher Scientific, Siemens Healthineers, Biocare Medical, F. Hoffmann-La Roche, Merck KGaA, BioGenex, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Slide Stainer Market Shifts & Advancements
Digital imaging capabilities are merging with automated liquid-handling precision to transform slide staining from isolated benchwork into integrated diagnostic production pipelines.
Multiplex immunohistochemistry platforms are expanding into high-complexity cancer profiling applications. Academic medical centers and reference laboratories in the United States are adopting these systems to reduce sequential staining rounds. The technology is expanding into companion diagnostic development pipelines, compressing biomarker validation timelines.
REACH chemical registration requirements are reshaping reagent formulation strategies across European supply chains. Manufacturers are reformulating chromogenic substrates and buffer systems to eliminate restricted substances. Germany's reference laboratories are absorbing compliance costs through consolidated procurement negotiations with preferred vendors.
Consolidated purchasing by hospital networks is displacing decentralized lab equipment decisions. Integrated delivery networks in the United States are mandating standardized staining platforms across affiliated pathology sites. This concentration is most visible in Florida and Texas, where multi-hospital systems are extracting volume-based service concessions from instrument suppliers.
Global Slide Stainer Market Segmentation
Slide stainer purchasing decisions hinge on throughput requirements, protocol complexity, and integration with existing laboratory infrastructure. Distinct segment boundaries reflect divergent capital allocation priorities across diagnostic workflows versus research applications.
Product Type:
Capital expenditure thresholds and labor cost containment drive platform selection across hospital networks and independent laboratories.
- Automated Slide Stainers:These systems process 20 to 100 slides per batch with programmable temperature, incubation, and reagent dispensing parameters. Demand concentrates in United States hospital networks and German reference laboratories where FDA 510(k) cleared platforms and CE-marked devices anchor centralized pathology operations. Labor scarcity and ISO 15189 accreditation mandates accelerate replacement of manual workflows.
- Manual Slide Stainers:Benchtop units requiring technician-mediated dye application and timing control dominate resource-limited settings in India and specialized research protocols at United States academic medical centers. Protocol flexibility outweighs throughput requirements where specimen volumes remain below automation breakeven thresholds.
- Semi-Automated Stainers:Hybrid platforms automate reagent delivery while retaining manual slide handling occupy mid-tier laboratories in Japan transitioning from manual protocols.
- Multipurpose Stainers:Modular systems supporting H&E, special stains, and immunohistochemistry on single platforms serve multi-site diagnostic networks in Texas and Florida seeking equipment standardization.
- Specialized Stainers:Purpose-built systems for cytology or frozen section applications target high-volume breast cancer screening centers in the United Kingdom.
Volume sits with Automated Slide Stainers; growth tilts toward Multipurpose Stainers.
Technology:
Detection chemistry selection tracks diagnostic specificity requirements and downstream imaging infrastructure.
- Chromogenic:Enzyme-mediated colorimetric detection using horseradish peroxidase or alkaline phosphatase substrates remains the workhorse for routine histopathology. German pathology networks and Japanese cancer screening programs absorb the bulk of chromogenic reagent consumption, with REACH compliance costs reshaping European supply chains.
- Fluorescent:Fluorophore-conjugated antibody detection enables multiplexed biomarker visualization on single tissue sections. Academic medical centers in the United States deploy these systems for companion diagnostic development and tumor microenvironment profiling.
- Digital Imaging-Based:Integrated staining and whole-slide imaging platforms capture premium pricing from telepathology networks in the United States and Netherlands requiring remote diagnostic capabilities.
- Immunohistochemistry:Antigen-specific antibody detection systems anchor oncology diagnostic workflows across diagnostic laboratories in Germany and Japan.
- Cytochemical:Cell-based staining protocols for hematological malignancy identification retain steady demand in United Kingdom reference laboratories.
Chromogenic technology commands installed base dominance; Digital Imaging-Based platforms are climbing the fastest on telepathology convergence.
Application:
Specimen throughput and reimbursement economics determine staining platform deployment across diagnostic settings.
- Pathology Labs:High-volume cancer diagnosis and infectious disease identification workflows process thousands of slides weekly. Centralized lab networks in the United States, Germany, and Japan drive automated platform procurement to manage rising caseloads from expanded screening programs.
- Forensic Diagnostics:Specialized tissue and DNA staining for criminal investigation and mass casualty identification operates at lower volumes with stringent chain-of-custody requirements. United States state crime laboratories and United Kingdom forensic pathology services sustain niche demand.
- Tissue Engineering:Quality control staining for regenerative medicine scaffold characterization serves biomanufacturing facilities in Massachusetts and Switzerland.
- Cytology:Pap smear and liquid-based cervical cancer screening applications concentrate in public health programs across Japan and Germany.
- Veterinary Testing:Companion animal and livestock pathology services in Texas and California utilize adapted human diagnostic platforms.
Pathology Labs absorb the majority of capital deployment; Forensic Diagnostics exhibits the steepest expansion trajectory on crime laboratory modernization funding.
End User:
Funding mechanisms and regulatory compliance obligations create distinct purchasing behaviors across institutional categories.
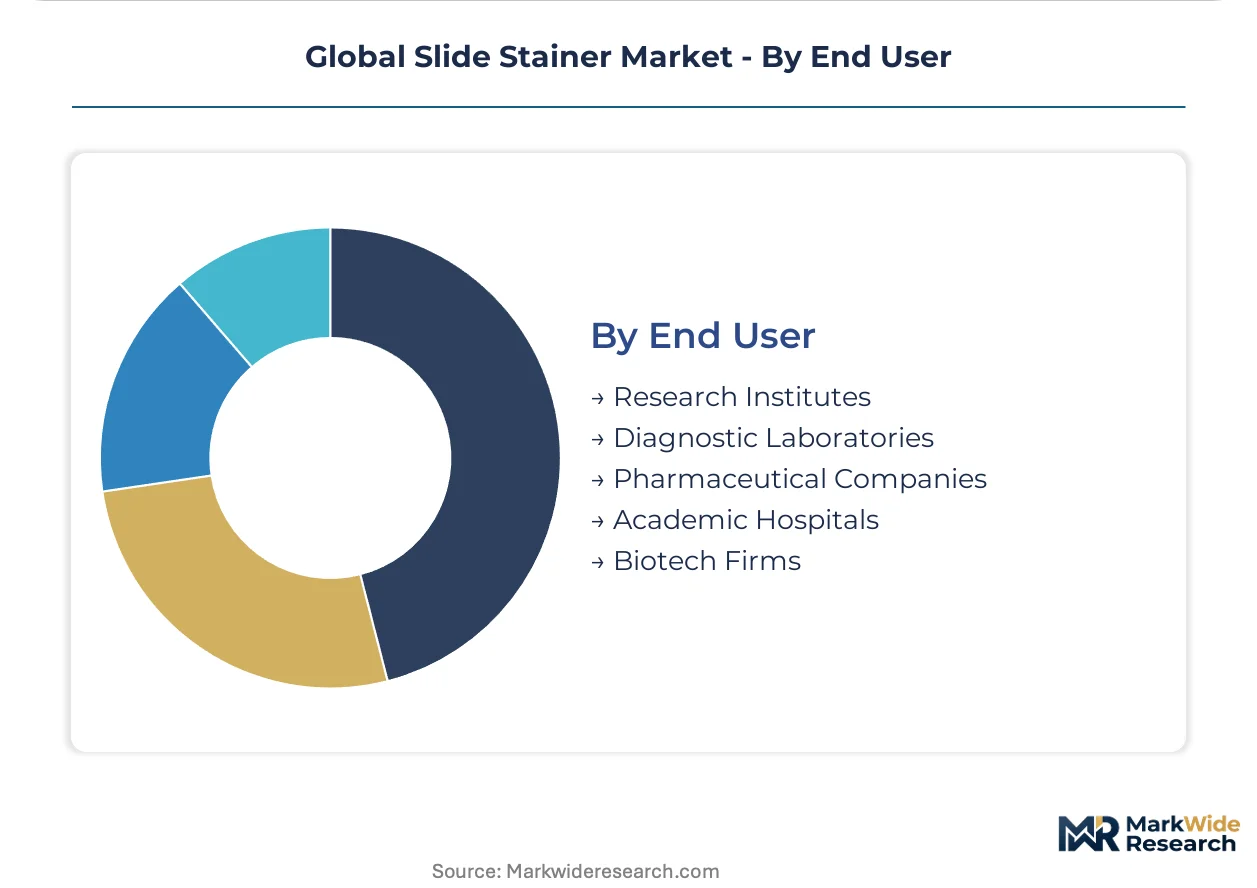
- Diagnostic Laboratories:Commercial and hospital-affiliated labs facing ISO 15189 accreditation and CAP proficiency testing requirements constitute the core revenue base. Integrated delivery networks in the United States and hospital chains in Germany consolidate procurement to extract volume concessions.
- Research Institutes:Basic science and translational research facilities prioritize protocol flexibility over throughput, sustaining manual and semi-automated platform demand at NIH-funded centers and Max Planck Institute facilities.
- Pharmaceutical Companies:Toxicology and biomarker validation groups at Roche and Novartis facilities in Switzerland deploy high-throughput systems for clinical trial support.
- Academic Hospitals:Teaching institutions in Boston and Heidelberg balance diagnostic service obligations with research training missions.
- Biotech Firms:Emerging companies in Cambridge, Massachusetts and South San Francisco utilize specialized staining for preclinical therapeutic development.
Diagnostic Laboratories anchor current revenue concentration; Biotech Firms are gaining share fastest on cell therapy pipeline expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland and Massachusetts concentrate specialty antibody and chromogenic dye production, creating supply dependencies that shape procurement strategies across diagnostic networks. FDA 510(k) clearance pathways in the United States and EU MDR compliance requirements in Europe are compressing product development timelines while extending regulatory costs for manufacturers seeking market access.
United States
Integrated delivery networks in Florida and Texas mandate standardized staining platforms across affiliated pathology sites, extracting volume-based service concessions from instrument suppliers. FDA 510(k) clearance streamlining expedites time-to-market for automated in vitro diagnostic devices targeting commercial laboratories. Histotechnologist talent scarcity in Massachusetts and California constrains operational scaling regardless of equipment availability.
Germany
Reference laboratories absorb REACH compliance costs through consolidated procurement negotiations with preferred reagent vendors. EU MDR clinical evidence requirements extend product development timelines while institutionalizing demand for validated staining protocols under ISO 15189 accreditation. Bavaria's centralized cancer screening programs force batch-processing capacity upgrades across hospital-affiliated diagnostic networks.
Japan
Expanded cancer screening programs drive centralized lab networks to upgrade automated staining capacity for rising pathology caseloads. PMDA regulatory frameworks align with international standards while maintaining distinct local approval requirements for imported diagnostic platforms. Tokyo and Osaka metropolitan areas concentrate high-volume pathology operations serving national health insurance reimbursement structures.
India
Hospital chain consolidation and government health infrastructure programs create first-time automated staining demand outside traditional mature markets. CDSCO medical device regulations are harmonizing with international standards while maintaining import substitution priorities for domestic manufacturing. Maharashtra and Karnataka host emerging diagnostic network buildouts serving tier-two city expansion.
United Kingdom
Forensic pathology services and state crime laboratories sustain niche demand for specialized tissue and DNA staining with stringent chain-of-custody protocols. NHS procurement frameworks favor multi-year service contracts over capital purchases, reshaping vendor pricing models. London and Southeast England concentrate reference laboratory capacity serving national screening programs.
Global Slide Stainer Market Competitive Landscape
Strategic partnerships dominate the current landscape as instrument manufacturers seek reagent supply security and laboratory information system interoperability. The vendor base organizes around three tiers: diversified life sciences conglomerates with integrated workflow portfolios, specialized histopathology equipment fabricators competing on throughput metrics, and regional consumables suppliers capturing service revenue through rental pricing models. Competitive positioning hinges on FDA 510(k) clearance velocity, CE marking breadth, and digital pathology integration capabilities. M&A activity targets reagent formulation capabilities and whole-slide imaging software assets.
Among diversified conglomerates, Thermo Fisher Scientific leverages its broad life sciences portfolio to sustain integrated workflow sales, while Agilent Technologies anchors its position through specialized detection systems. Sakura Finetek occupies a distinct tier competing aggressively on automated throughput metrics in high-volume pathology settings. These three entities exemplify divergent strategic archetypes: platform ecosystem integration, specialized chromogenic and fluorescent technology depth, and pure-play histopathology automation scale respectively.
| Leading Market Players |
|---|
| Agilent Technologies |
| Sakura Finetek |
| Thermo Fisher Scientific |
| Siemens Healthineers |
| Biocare Medical |
| F. Hoffmann-La Roche |
| Merck KGaA |
| BioGenex |
| Danaher Corporation |
| Others |
Supply & Pricing Matrix
Consolidated procurement by United States hospital networks and German reference laboratories is forcing reagent suppliers to unbundle consumables from capital equipment, compressing margins on standalone instrument sales while expanding recurring revenue streams through rental pricing models.
Pricing Analysis
Service bundling separates premium-tier vendors from mid-market competitors, with FDA 510(k) cleared platforms commanding annual maintenance contracts while economy-tier suppliers strip warranties to hit capital expenditure thresholds. Price differentiation hinges on ISO 15189 validation documentation and remote diagnostic capabilities. Cost compression in the manual stainer segment intensifies as Indian hospital chains negotiate volume-based reagent discounts. Academic medical centers exhibit lowest price sensitivity due to grant-funded procurement, while independent pathology practices in resource-limited settings prioritize upfront capital minimization over total cost of ownership.
Supply Chain Analysis
Direct-to-laboratory channels serve high-volume diagnostic networks in the United States and Germany, while distribution runs through regional medical device distributors for mid-tier laboratories in India and Japan. Specialty antibody production concentrates in Switzerland and Massachusetts, with chromogenic dye formulation anchored in German chemical clusters. Supply chains draw from optical-grade glass substrates in Japan, precision fluidics from German engineering suppliers, and electronic control modules from South Korean semiconductor fabricators. Single-source vulnerability in Swiss antibody production creates exposure to REACH chemical registration disruptions. Regional distribution hubs in Singapore and Rotterdam manage last-mile logistics for Asia-Pacific and European markets respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive reagent manufacturing is becoming the decisive competitive lever as platform vendors seek to lock in consumables revenue and insulate margins from supply concentration risks.
For Market Incumbents: Anchor market position through backward integration into antibody and chromogenic substrate production, eliminating dependency on Swiss and Massachusetts specialty suppliers. Secure ISO 15189 pre-validated protocol libraries to defend against emerging digital pathology entrants. Expand service infrastructure in Texas and Florida to capture multi-year contracts from consolidating hospital networks. For New Entrants and Emerging Players: Begin with reagent rental models targeting price-sensitive diagnostic networks in Maharashtra and Karnataka, bypassing capital purchase barriers that exclude resource-limited settings. Exploit white-space in multiplex immunohistochemistry platforms for companion diagnostic development pipelines at United States academic medical centers. Partner with regional distributors in India to establish service presence without direct sales infrastructure investment. For Investors and Strategic Acquirers: The window for entry favors reagent formulation specialists with REACH-compliant substrate libraries and established relationships with German reference laboratories. Long-term viability rests on convergence between automated staining and whole-slide imaging workflows. Monitor FDA 510(k) clearance velocity for digital-integrated platforms as the inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Manufacturing Integration | Captive antibody production insulates margins from Swiss supply concentration and REACH compliance disruptions. |
| Digital Pathway Partnership | Whole-slide imaging integration with staining workflows opens telepathology revenue streams in Netherlands and United States networks. |
| ISO 15189 Pre-Validation | Pre-certified protocol libraries accelerate hospital laboratory accreditation and reduce customer implementation timelines. |
| Per-Slide Pricing Models | Reagent rental penetration in Indian diagnostic networks converts capital-constrained buyers into recurring revenue accounts. |
| Regional Service Expansion | Dedicated field engineering in Florida and Texas captures multi-hospital system contracts through guaranteed uptime commitments. |
Research Methodology
Independent corroboration across primary interviews with histopathology laboratory directors, biomedical equipment procurement managers, and reagent supply chain specialists underwrites the qualitative findings, validated against FDA 510(k) clearance databases, EU MDR submission records, hospital GPO contract repositories, and ISO 15189 accreditation registries. Bottom-up instrument shipment tracking and top-down diagnostic laboratory capital expenditure surveys were reconciled to establish market sizing boundaries.
Rate-of-change decomposition across the analysis window isolates volume drivers from price mix effects, with segmentation modeling across product type, detection technology, application setting, and end-user category. CAGRs were derived from installed base replacement cycles, screening program expansion timelines, and digital pathology adoption curves. Forecast inputs incorporate PMDA regulatory approval timelines for Japanese market entry and CDSCO harmonization progress for Indian diagnostic network buildouts.
Underlying measurement precision varies by segment; automated slide stainer volumes carry tighter precision than manual stainer estimates due to concentrated vendor reporting. Forecasts reflect assumptions regarding histotechnologist labor scarcity persistence and digital pathology reimbursement framework evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Centrifuge Tubes Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Absorbance Micro Plate Reader Market
Laboratory Equipment
Middle East and Africa Laboratory Hoods and Enclosure Market
Laboratory Equipment
Albumin Analyzers Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
Laboratory Furnaces Market
Laboratory Equipment
Global Pipette Tips Market
Laboratory Equipment
Asia Pacific Cell Counting Market
Laboratory Equipment
Latin America Laboratory Equipment and Disposables Market
Laboratory Equipment
Blood Processing and Storage Equipment Market
Laboratory Equipment
Global Pipettes and Pipettors Market
Laboratory Equipment
Laboratory Rockers and Shakers Market
Laboratory Equipment
Laboratory Furniture Market
Laboratory Equipment
Scalable Clinical Chemistry Analyzers Market