
 South America Soy Protein Ingredients Market | 2026-2036
South America Soy Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
South America Soy Protein Ingredients Market Analytics
Ingredient formulation services revenue is narrowing as commodity soy processors build in-house technical capabilities. Bunge Global SA leverages its crushing footprint across Brazil and Argentina to backward-integrate into isolate production. Cargill anchors South American supply through its port-adjacent processing complexes in Santos and Rosario. CHS Inc. competes via farmer-linked origination contracts that secure non-GMO soybean streams for premium concentrate output.
Soy protein ingredients encompass protein fractions extracted from defatted soy flakes through aqueous or alcohol-washing processes, yielding isolates exceeding 90% protein content or concentrates retaining 65-70% protein with associated soluble carbohydrates. These ingredients function primarily as emulsifiers, gelling agents, and texturizers in formulated foods where animal protein displacement or cost reduction drives formulation decisions. Soy isolate commands the highest unit margins due to its functional purity in dairy analog applications, while textured soy protein records the fastest volume trajectory as Brazilian and Argentine meat-alternative startups scale extrusion capacity. Soy flour persists as a mature, price-driven category confined mainly to bakery and animal feed blending where protein functionality requirements remain less stringent.
ANVISA governs food additive approvals and protein content claims across Brazil, Argentina's national food safety authority enforces Mercosur-aligned labeling standards, and each country's respective agricultural ministry monitors genetically modified organism thresholds in export-bound ingredient streams. Compliance with these overlapping frameworks determines market access for both domestic processors and imported specialty isolates. Stakeholders must track evolving Mercosur harmonization negotiations and pending protein-source disclosure mandates that could restructure competitive positioning across the value chain.
Market Dynamics
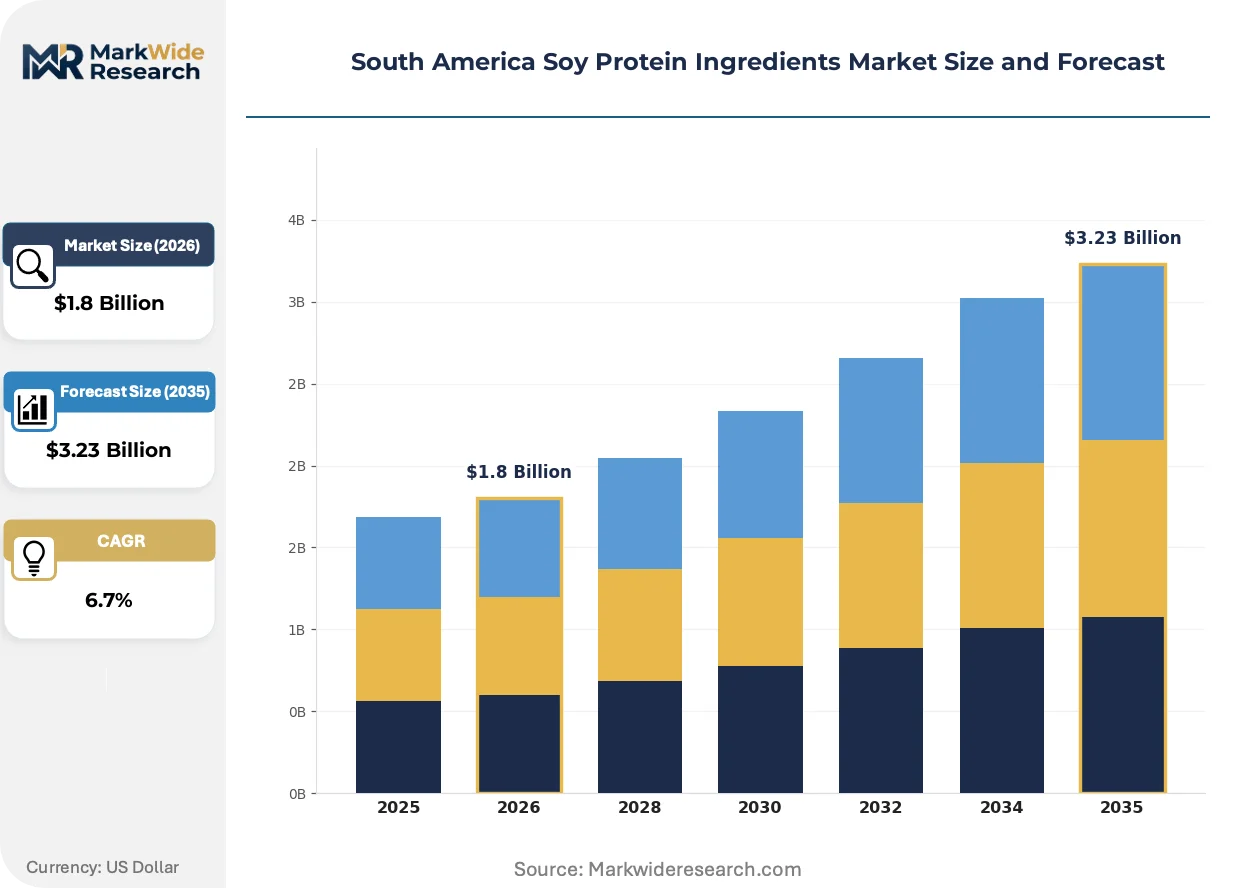
Backward integration by Brazilian commodity processors is compressing margins for independent isolate suppliers and reshaping competitive positioning across the value chain. São Paulo's manufacturing corridor concentrates extrusion capacity for textured soy protein, while ANVISA's tightened protein labeling rules force reformulation investments.
Growth Catalysts
- ANVISA fortification mandates:Brazil's updated protein content disclosure rules require verified amino acid profiles, driving demand for high-purity isolates in dairy analog applications.
- Textured soy protein absorption:Argentine and Brazilian meat-alternative startups scale extrusion capacity, consuming rising volumes of functional soy fractions for plant-based cutlet and ground formats.
- Southeastern corridor clustering:Minas Gerais and São Paulo host dense soy processing infrastructure, minimizing logistics costs for ingredient shipments to domestic food manufacturers.
Market Restraints
- Input cost volatility:Defatted soy flake prices fluctuate with Brazilian soybean export parity, compressing processor margins during harvest-season gluts.
- Supply concentration risk:Santos and Paranaguá port complexes handle over 80% of export-bound isolate volumes, creating single-point vulnerability for international shipments.
- Technical limitation:Alcohol-washed concentrates retain beany off-flavors that limit penetration into premium beverage applications, constraining price realization.
Strategic Opportunities
- Underpenetrated Andean markets:Peru and Colombia lack domestic isolate production, creating import substitution openings for Brazilian processors with Mercosur tariff advantages.
- Regulatory tailwind:Pending Mercosur harmonization on protein-source disclosure could standardize labeling across Argentina, Brazil, Paraguay and Uruguay, reducing compliance fragmentation.
- Technology convergence:Precision fermentation partnerships with domestic yeast suppliers enable hybrid protein formulations that differentiate isolate offerings in functional foods.
Industry Challenges
- Extrusion engineering talent gap:High-shear texturization expertise concentrates in southern Brazil, forcing Argentine processors to recruit internationally or accept yield penalties.
- Non-GMO certification timelines:IP traceback documentation for premium concentrate streams requires 18-24 month grower contract cycles, locking working capital ahead of sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Soy Protein Ingredients Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Isolate, Soy Concentrate, Textured Soy Protein, Soy Flour Application: Bakery, Dairy Alternatives, Meat Alternatives, Snacks End User: Food & Beverage Industry, Nutraceuticals, Animal Feed, Dietary Supplements Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Specialty Stores |
| Companies Covered | Ajinomoto, Kerry Group, Tate & Lyle, Dien Inc., Archer Daniels Midland Company, BRF Global, Bunge Global SA, Cargill, CHS Inc., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Soy Protein Ingredients Market Evolving Landscape
Digital process control systems are virtualizing quality assurance workflows across South American soy protein facilities, compressing batch release timelines and enabling real-time specification adjustments. Three developments dominate the innovation landscape.
Membrane filtration technology is virtualizing traditional acid-precipitation steps in isolate production. Brazilian processors in São Paulo state deploy ceramic microfiltration modules that reduce hexane residual detection times from hours to minutes. This shift enables just-in-time specification matching for dairy analog customers, compressing inventory carrying costs.
ANVISA's pending amino acid scoring methodology revision will mandate digestibility-corrected protein claims across all fortified food categories. Brazilian infant formula and sports nutrition manufacturers face 12-18 month reformulation cycles to meet PDCAAS disclosure requirements. Argentine exporters to Brazil must synchronize labeling systems or risk customs detention at border checkpoints.
Long-term offtake contracting is displacing spot purchasing among São Paulo-based meat-alternative manufacturers. Three-year volume commitments with fixed protein specifications now dominate textured soy protein procurement, locking processor capacity and squeezing smaller buyers into secondary supply tiers. This pattern concentrates most acutely in Brazil's alternative protein startup ecosystem.
South America Soy Protein Ingredients Market Segmentation
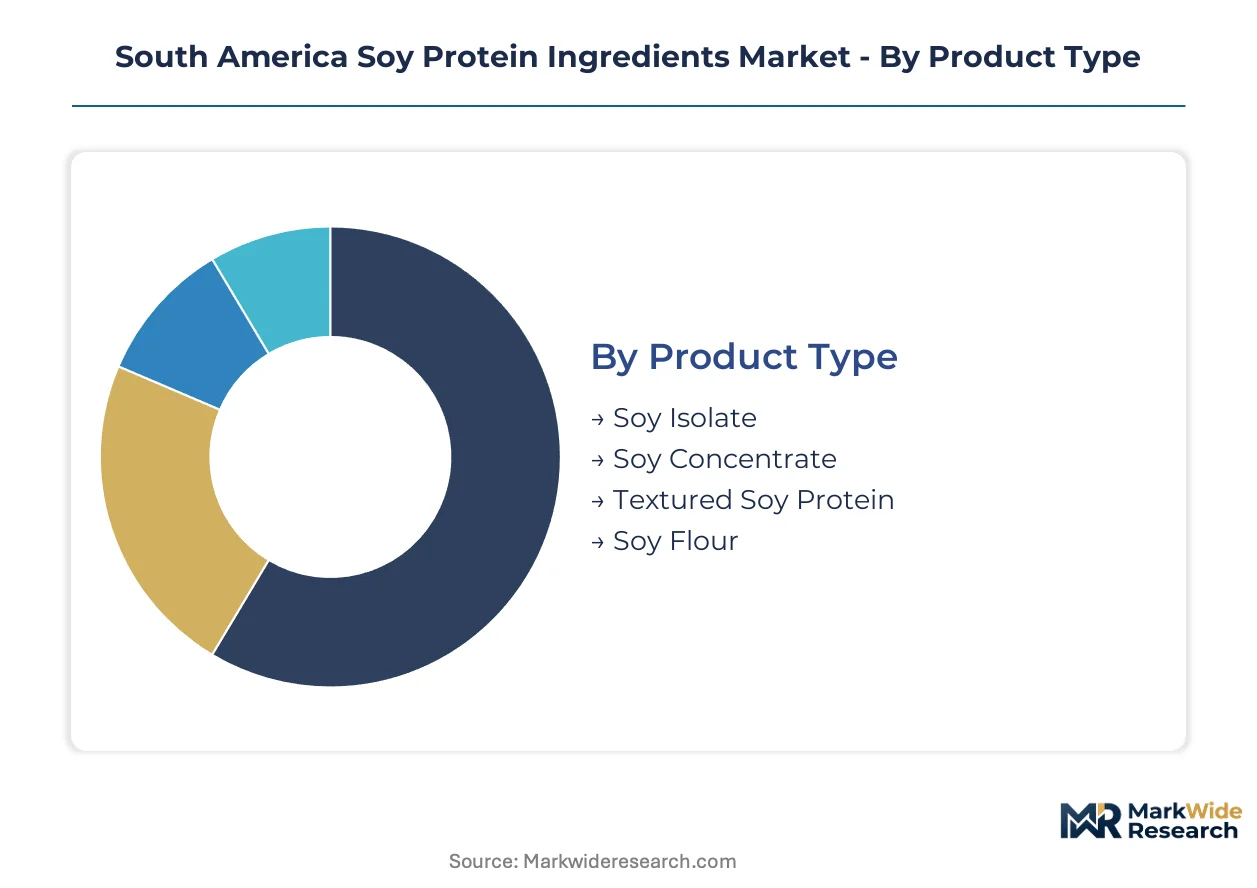
Segmentation in South America's soy protein market reveals divergent margin structures across product tiers and distribution modes. Technical specification requirements vary sharply between dairy analog formulators and meat-alternative extruders, driving distinct procurement behaviors among Brazilian and Argentine processors.
Product Type:
After-sales technical support intensity escalates with protein purity, as isolate customers demand ongoing formulation troubleshooting while flour buyers require minimal service intervention.
- Soy Isolate:Exceeding 90% protein content through aqueous extraction, this fraction delivers superior emulsification for dairy analog applications. São Paulo-based infant formula manufacturers absorb volumes under ANVISA's tightened amino acid disclosure mandates.
- Textured Soy Protein:High-shear extrusion transforms defatted flakes into fibrous matrices mimicking animal muscle structure. Brazilian meat-alternative startups in Minas Gais scale capacity fastest, consuming rising volumes for plant-based cutlet formats.
- Soy Concentrate:Alcohol-washed to 65-70% protein with retained soluble carbohydrates, serving cost-sensitive bakery and feed blending operations across Argentina's Pampas region.
- Soy Flour:Full-fat or defatted milled flakes, lowest processing intensity, confined to mature applications where protein functionality requirements remain minimal.
By volume, soy flour leads. By growth pace, textured soy protein is ahead.
Application:
Margin capture stratifies sharply across application tiers, with dairy alternatives commanding specification premiums and meat alternatives driving volume expansion through extrusion scale-up.
- Meat Alternatives:Extruded soy proteins form the structural backbone of plant-based burgers, sausages, and whole-cut analogs. Argentine and Brazilian startups deploy high-moisture extrusion lines, absorbing textured protein volumes at three-year offtake contract terms.
- Dairy Alternatives:Isolates enable foam stability and gelation in milk substitutes, yogurt analogs, and frozen desserts. ANVISA's pending PDCAAS scoring methodology forces reformulation investments among São Paulo-based infant nutrition manufacturers.
- Bakery:Concentrates and flours provide dough conditioning and shelf-life extension, price-driven procurement with limited technical service requirements.
- Snacks:Textured fractions fortify extruded cereals and protein bars, growing traction in Brazil's southeastern manufacturing corridor.
Meat alternatives absorb volume fastest; dairy alternatives extract the highest unit margins.
End User:
Procurement sophistication diverges between multinational food manufacturers and regional feed compounders, with nutraceutical buyers imposing certificate-of-analysis stringency that animal feed customers rarely match.
- Food & Beverage Industry:Dominant demand source spanning dairy analog, meat alternative, and bakery applications. Brazilian processors in São Paulo and Minas Gerais anchor continental supply relationships.
- Nutraceuticals:Sports nutrition and medical food manufacturers require isolates with documented amino acid profiles and low anti-nutrient residuals.
- Dietary Supplements:Powder and capsule formulators source non-GMO certified concentrates, with IP traceback documentation extending 18-24 months.
- Animal Feed:Price-sensitive poultry and aquaculture operations in southern Brazil blend soy flour and low-grade concentrates for protein supplementation.
Food and beverage commands absolute volume; nutraceuticals expand most quickly.
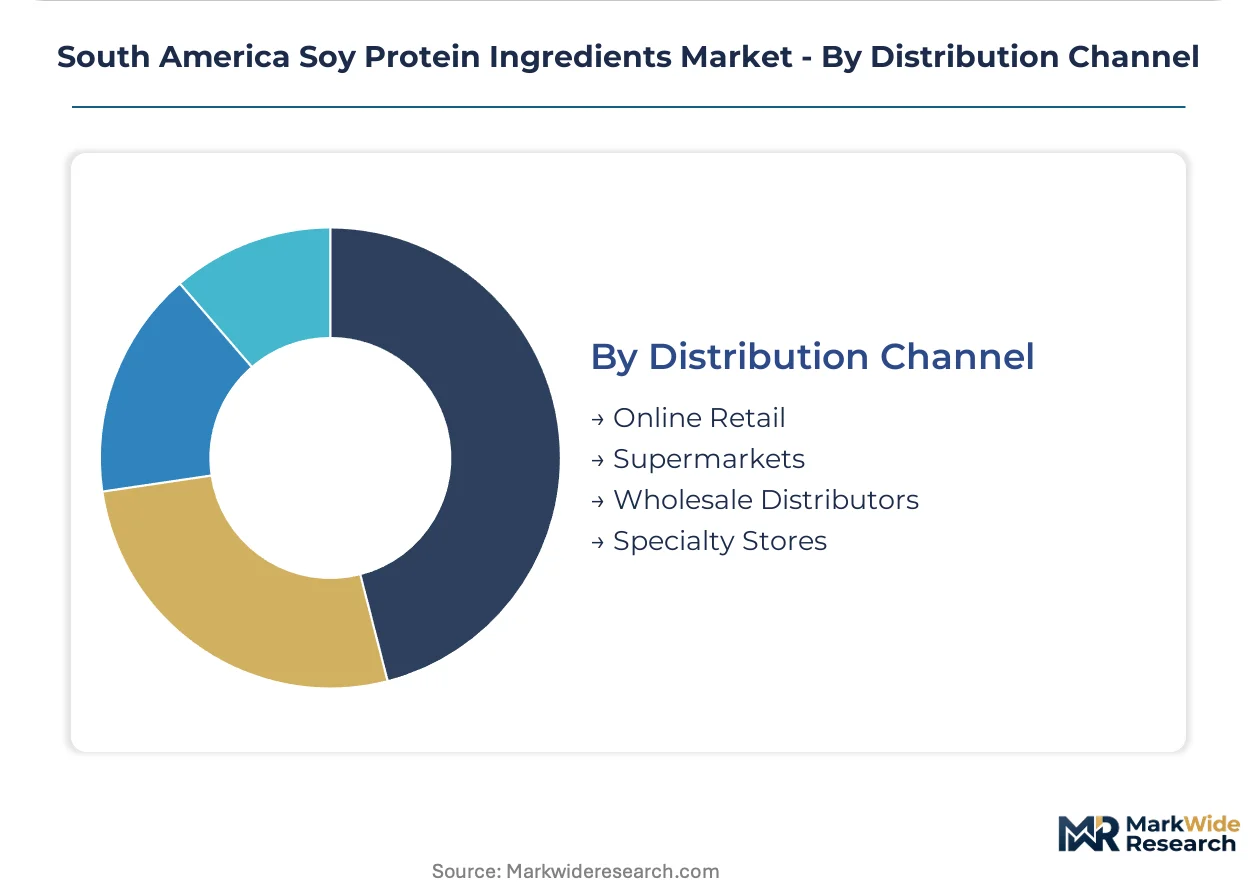
Distribution Channel:
Logistics configuration determines working capital intensity, with bulk rail shipments to wholesale distributors minimizing per-kilogram costs versus parcel-scale online retail.
- Wholesale Distributors:Santos and Rosario port-adjacent depots consolidate containerized isolate volumes for redistribution to Argentine and Brazilian food manufacturers.
- Supermarkets:Packaged retail formats target home bakers and small-scale foodservice in São Paulo's urban corridor.
- Specialty Stores:Health food retailers stock organic and non-GMO certified concentrates for consumer DIY plant-based cooking.
- Online Retail:Direct-to-consumer channels serve dispersed nutraceutical and supplement buyers across underpenetrated Andean markets.
Wholesale distributors handle volume dominance; online retail climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across South American soy protein demand centers. Brazilian food manufacturers absorb premium isolates with minimal volume contraction, while Argentine feed compounders and Andean importers exhibit acute sensitivity to defatted flake price swings.
Brazil
ANVISA's fortified food mandates drive isolate procurement from São Paulo infant formula manufacturers. The southeastern manufacturing corridor concentrates extrusion capacity for textured soy protein, with Minas Gerais processors scaling high-moisture lines for meat-alternative startups.
Argentina
Rosario port-adjacent crushing complexes anchor Mercosur-aligned supply chains. The national food safety authority enforces protein-source disclosure standards that synchronize with Brazilian import requirements, reducing customs friction for cross-border concentrate shipments.
Chile
Santiago-based nutraceutical formulators import isolates under strict digestibility-corrected protein specifications. The country's national pharmaceutical regulator monitors amino acid profile documentation for sports nutrition applications, creating certificate-of-analysis stringency unmatched by regional feed buyers.
Colombia
Bogotá food manufacturers rely on Brazilian Mercosur tariff advantages for concentrate supply. Domestic isolate production remains absent, forcing import dependency that exposes processors to Santos port congestion and currency volatility.
Peru
Lima's emerging plant-based foodservice sector sources textured soy protein through informal distribution channels. The absence of domestic crushing infrastructure leaves Peruvian buyers dependent on Brazilian wholesale distributors with extended lead times.
South America Soy Protein Ingredients Market Competitive Landscape
Capability concentration sits with multinational processors possessing port-adjacent infrastructure; scale advantage sits with commodity crushers backward-integrating into isolate production. The market structures around three tiers: integrated agribusiness conglomerates, regional concentrate specialists, and toll-processing extrusion operators. Dominant competitive moves include captive supply chain control over non-GMO soybean streams and three-year offtake contracting that locks processor capacity.
Among integrated agribusiness conglomerates, Bunge Global SA and Cargill exemplify the port-proximate processing archetype, leveraging Brazilian and Argentine crushing footprints to anchor continental supply relationships. CHS Inc. occupies a distinct position within the farmer-linked origination tier, securing identity-preserved soybean streams through contract agriculture structures that support premium concentrate output.
| Leading Market Players |
|---|
| Ajinomoto |
| Kerry Group |
| Tate & Lyle |
| Dien Inc. |
| Archer Daniels Midland Company |
| BRF Global |
| Bunge Global SA |
| Cargill |
| CHS Inc. |
| Others |
Value Network & Pricing Analysis
Overcapacity in São Paulo's extrusion corridor compresses spot pricing for textured soy protein while simultaneously forcing processors toward long-term offtake contracts that lock buyer-seller relationships. This utilization dynamic rewards backward-integrated crushers with captive flake supply while squeezing independent isolate suppliers into specification-based competition.
Pricing Analysis
After-sales technical service revenue drives lifetime value most acutely for isolate suppliers serving dairy analog formulators. Contract-based long-term offtake dominates procurement, with price differentiation resting on protein purity tiers and ANVISA certification status. Cost compression in standard-grade concentrates is intensifying as commodity processors absorb formulation functions internally. Feed compounders in Argentina's Pampas exhibit acute price sensitivity, while São Paulo infant formula manufacturers absorb premium isolates with minimal volume contraction.
Supply Chain Analysis
Export-control regimes on precision fermentation technology limit hybrid protein formulation partnerships between Brazilian isolate processors and domestic yeast suppliers. Supply concentrates in Brazil and Argentina, with raw material flows drawing from defatted soy flakes, identity-preserved non-GMO soybean streams, and hexane solvent inputs. Single-source vulnerability sits with Santos and Paranaguá port complexes handling bulk export volumes. Distribution runs through port-adjacent wholesale depots in Santos and Rosario that consolidate containerized shipments for Mercosur redistribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with ANVISA's pending amino acid scoring methodology, which forces reformulation cycles that niche suppliers can exploit before incumbents adapt.
For Market Incumbents: Harden formulation service revenue by embedding technical teams within São Paulo dairy analog operations before commodity processors complete in-house capability builds. Expand identity-preserved non-GMO contract agriculture structures in Minas Gerais to defend premium concentrate positioning against Argentine import competition.
For New Entrants and Emerging Players: Andean underpenetration in Peru and Colombia offers white-space entry through Brazilian wholesale distributor relationships that bypass port congestion exposure. Target Lima's emerging plant-based foodservice sector with textured soy protein shipments via informal distribution channels that incumbent processors underserve.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among toll-processing extrusion operators locked into three-year offtake contracts with meat-alternative startups. Long-term viability centers on processors with demonstrated ANVISA compliance infrastructure and Mercosur tariff-advantaged logistics. Monitor pending protein-source disclosure harmonization negotiations as inflection signal for cross-border consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isolate Production | Bunge Global SA leverages Brazilian crushing footprint to capture dairy analog margins previously lost to independent suppliers. |
| Long-term Supply Agreement | Three-year offtake contracts lock textured protein capacity for São Paulo meat-alternative startups, squeezing secondary buyers. |
| Geographic Expansion | Brazilian processors exploit Mercosur tariff advantages to displace imports in underpenetrated Colombian and Peruvian markets. |
| Regulatory Certification Investment | ANVISA amino acid scoring compliance separates premium isolate suppliers from concentrate-only competitors in infant nutrition. |
| Joint Venture | Precision fermentation partnerships with domestic yeast suppliers enable hybrid protein differentiation in functional food applications. |
Research Methodology
Cross-validation between regulatory filing analysis and processor production data anchors the qualitative findings in this study. Primary interviews with soy processing plant managers, dairy analog formulation chemists, ANVISA regulatory affairs specialists, and wholesale distribution channel partners combined with secondary validation from customs trade records, ANVISA disclosure databases, Mercosur harmonization documents, and SEC filings from listed agribusiness conglomerates. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Calibration against historical price realization data and capacity utilization rates across São Paulo and Minas Gerais processing facilities informs the analytical framework. Segmentation dimensions include product type tier, application category, end-user sophistication level, and distribution channel structure. CAGRs derive from slope analysis of observed adoption curves rather than extrapolation. Forecast inputs incorporate ANVISA regulatory timeline uncertainty and Mercosur tariff regime stability assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive backward-integration moves by commodity crushers would shift outcomes beyond modeled ranges. Material shifts in ANVISA protein disclosure mandates or Mercosur harmonization negotiations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Indonesia Edible Oil Market
Ingredients
Omega 6 Market
Ingredients
Baking Ingredients Market
Ingredients
Liquid Feed Market
Ingredients
Hops Market
Ingredients
South America Fats and Oil Market
Ingredients
Coconut Cream Powder Market
Ingredients
Salad Oil Market
Ingredients
Middle East and Africa Fruit and Vegetable Ingredients Market
Ingredients
Soy Hydrolysates Market
Ingredients
Asparagus Extract Market
Ingredients
Ben Oil Market
Ingredients
Germany Protein Market
Ingredients
Specialty Flours Market
Ingredients
Feed Premix Market
Ingredients
Africa Fats and Oil Market