
 Vietnam Cashew Market | 2026-2036
Vietnam Cashew Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Cashew Market Outlook
Direct procurement from farmer cooperatives is reshaping how Vietnamese cashew processors secure raw nut supplies. Cao Phat Co., Ltd. leverages backward integration into Binh Phuoc growing zones to stabilize input costs. Donafoods anchors southern Vietnam processing capacity with industrial-scale shelling and roasting lines. Long Son Joint Stock Company competes through specialty-grade W180 kernel exports to European confectionery buyers.
Vietnam cashew comprises the kernel, shell, and testa of Anacardium occidentale seeds, with kernels typically containing 47% fat and 21% protein by dry weight; mechanical shelling followed by steam or vacuum roasting separates edible portions from caustic shell liquid for safe consumption. Cashew kernels dominate export value, while cashew butter gains traction among North American snack manufacturers seeking plant-based spreads. Wholesale channels still handle the majority of raw nut volume, though online retail accelerates for packaged kernel sales to Asian diaspora consumers.
Vietnam's Ministry of Agriculture and Rural Development coordinates with the country's national food safety regulator to enforce maximum residue limits for aflatoxin and pesticide contaminants, compelling processors to adopt HACCP and ISO 22000 certification for EU and US market access. The EU Deforestation Regulation adds traceability obligations that favor large-scale operators with documented supply chain mapping. Stakeholders must weigh certification investments against margin compression from African competitor expansion.
Market Dynamics
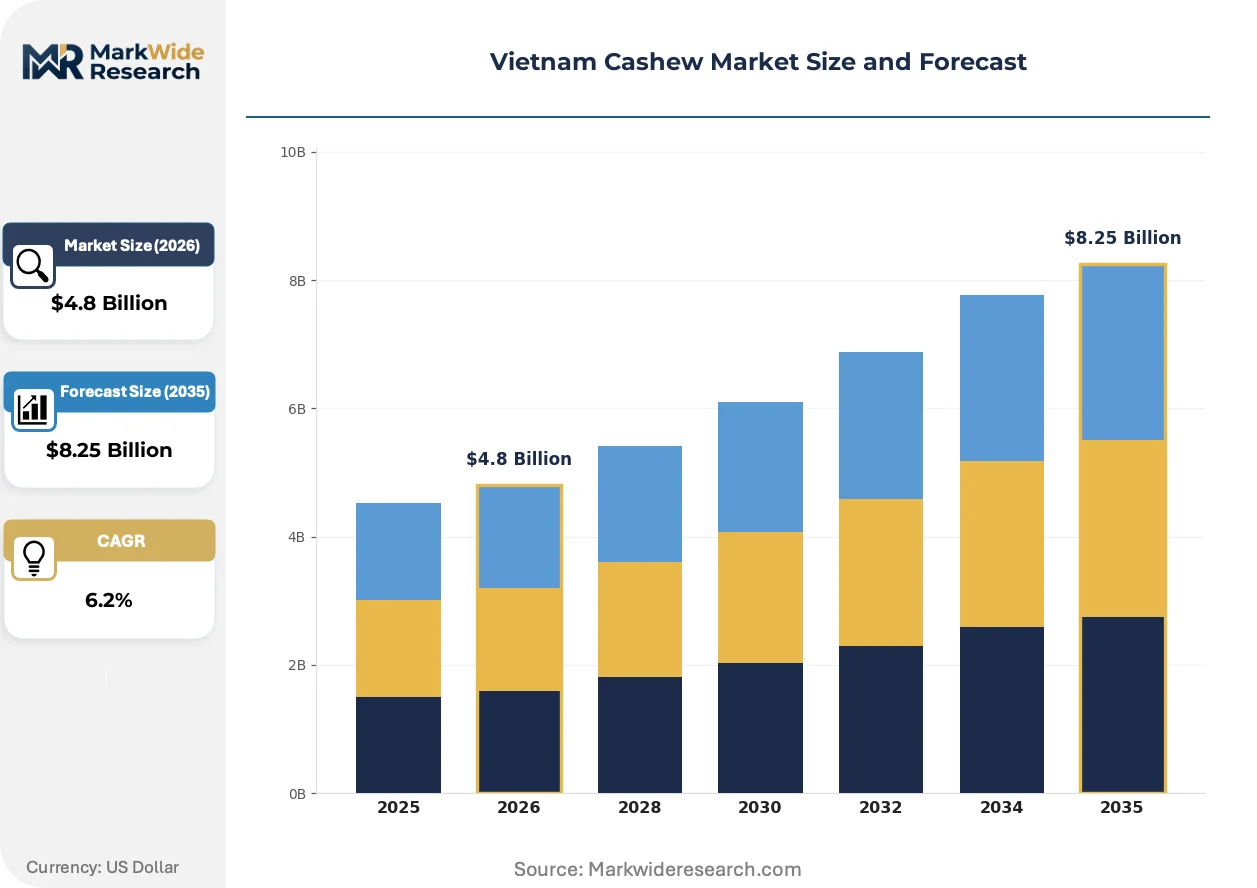
Binh Phuoc province's processing cluster dominance creates supply-side concentration that shapes competitive positioning across Vietnam's cashew value chain, while EU Deforestation Regulation traceability mandates force certification investments that favor scaled operators over fragmented processors.
Growth Catalysts
- Clean-label snack expansion:North American and European snack manufacturers drive kernel demand as plant-based protein alternatives displace conventional ingredients in retail formulations.
- Vietnam's food safety enforcement:The Ministry of Agriculture and Rural Development's stricter pesticide residue protocols under national standards push processors toward certified supply chains that unlock premium export channels.
- Mechanical shelling automation:Steam and vacuum roasting technologies reduce labor dependency while improving kernel grade consistency for specialty W180 exports to European confectionery buyers.
Market Restraints
- Raw nut import dependency:Vietnam processors source over half of raw cashew nuts from African origins, exposing margins to currency volatility and West African supply disruptions.
- Aflatoxin compliance costs:Maximum residue limits enforced by Vietnam's national food safety regulator require HACCP and ISO 22000 certification investments that compress returns for mid-scale operators.
- Caustic shell liquid handling:Mechanical shelling generates toxic byproduct requiring specialized waste management infrastructure that constrains greenfield processing expansion.
Strategic Opportunities
- Asian diaspora e-commerce channels:Online retail accelerates for packaged kernel sales to Vietnamese and broader Southeast Asian consumer communities in North America and Europe.
- Cashew butter formulation growth:North American snack manufacturers seek plant-based spreads as peanut butter alternatives, creating new application demand beyond whole kernel exports.
- Farmer cooperative direct sourcing:Backward integration into Binh Phuoc growing zones stabilizes input costs and builds traceability documentation required by EU Deforestation Regulation compliance.
Industry Challenges
- Skilled roasting technician scarcity:Steam and vacuum roasting operations require specialized operators capable of grade-specific temperature calibration, with training pipelines lagging capacity expansion.
- Certification timeline compression:HACCP and ISO 22000 audit scheduling creates 12-18 month compliance windows that delay EU market entry for new processing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Cashew Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Cashew Nuts, Cashew Kernels, Cashew Butter, Cashew Flour Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Household, Food Processing Industry, Snack Manufacturers, Exporters Quality Grade: W180, W210, W240, W320 |
| Companies Covered | Cao Phat Co., Ltd., Donafoods (Dong Nai Food Industrial Corporation), Long Son Joint Stock Company, An Viet Phat Holdings, Binh Phuoc Import Export Production Company, Tan Long Group, Phuc Thinh Cashew Processing Co., Ltd., Phu Vinh Trading Service Company Limited, Hoang Son 1 Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Cashew Market Strategic Shifts
Processing technology convergence with traceability systems is actively reshaping competitive differentiation in Vietnam's cashew sector, as automation investments intersect with regulatory documentation requirements.
Steam-vacuum hybrid roasting technology is hybridizing traditional thermal processing with precision moisture control systems. European confectionery buyers and North American snack manufacturers adopt these systems to secure consistent W180 and W320 grade outputs. The technology is compressing price spreads between commodity-grade and specialty-grade kernel categories by reducing human grading error.
Vietnam's Ministry of Agriculture and Rural Development coordinates with the national food safety regulator to enforce maximum residue limits for aflatoxin and pesticide contaminants. This regulatory framework compels processors to document supply chain mapping from farm gate to export port. Large-scale operators with captive Binh Phuoc sourcing zones respond fastest, while fragmented processors face exclusion from EU and US channels.
Buyer procurement patterns are consolidating around documented traceability rather than spot-price optimization. North American and European snack manufacturers now require batch-level farm origin data as a condition of contract renewal, displacing traditional wholesale channel anonymity. This shift concentrates contract volume with processors possessing integrated cooperative relationships in Vietnam's southeastern growing belt.
Vietnam Cashew Market Segmentation
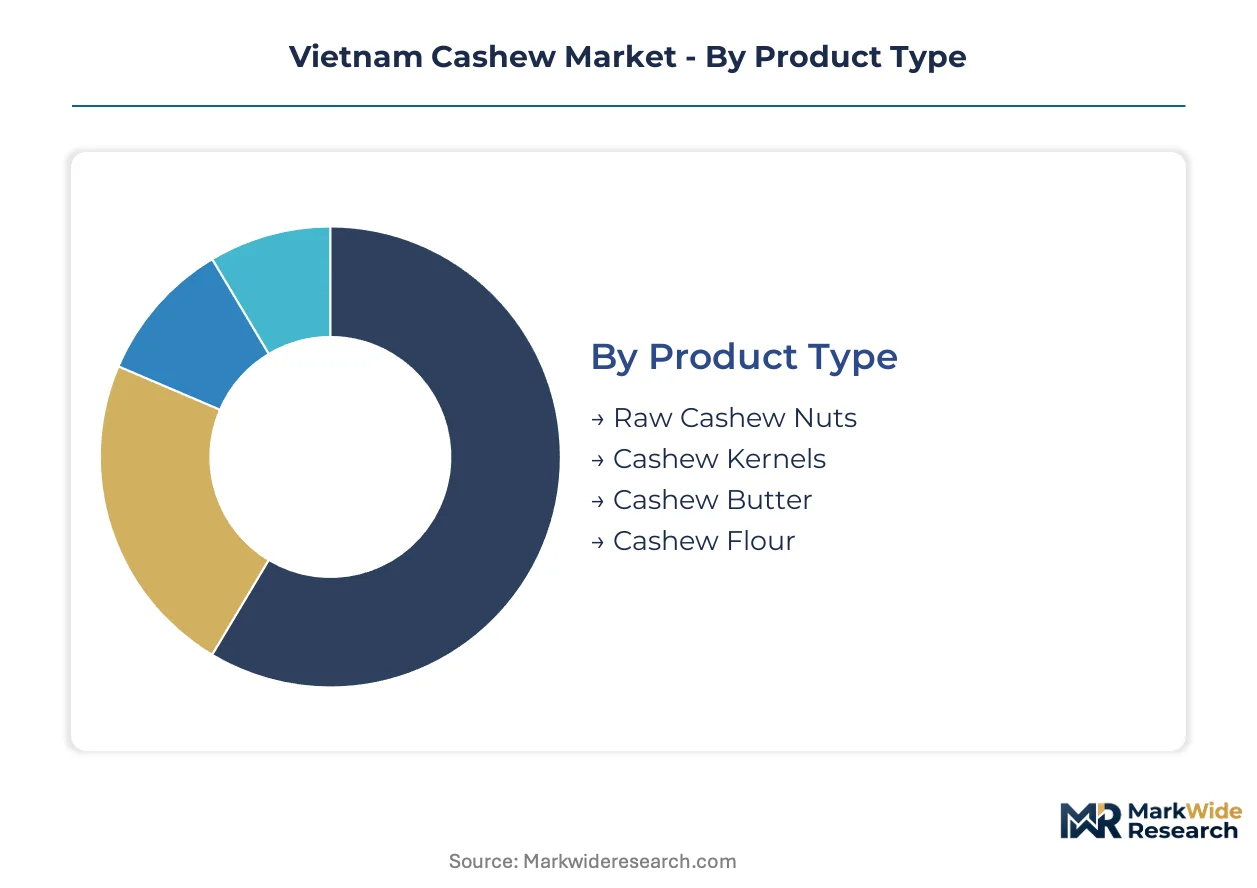
Vietnam's cashew value chain fragments across four distinct dimensions that shape procurement patterns and margin capture. Product type determines processing intensity and export eligibility. Distribution channel governs price realization and traceability documentation burden. These splits reveal where backward integration yields competitive advantage versus where commodity exposure dominates.
Product Type:
Cost tier stratification separates minimally processed inputs from value-added outputs with divergent capital requirements and certification thresholds.
- Cashew Kernels:Edible portions of Anacardium occidentale seeds containing 47% fat and 21% protein by dry weight, mechanically shelled and steam-roasted to separate from caustic shell liquid. European confectionery buyers and North American snack manufacturers concentrate demand around W180 and W320 grades as clean-label nut consumption displaces conventional ingredients.
- Raw Cashew Nuts:In-shell seeds sourced primarily from African origins and Binh Phuoc growing zones, representing the input layer where over half of national processing volume depends on West African supply. Currency volatility and aflatoxin compliance costs compress margins for processors lacking cooperative direct-sourcing relationships.
- Cashew Butter:Ground kernel paste gaining formulation share among North American snack manufacturers seeking plant-based peanut butter alternatives.
- Cashew Flour:Defatted kernel meal emerging in gluten-free baking applications with smaller current volume but expanding specialty channel presence.
Cashew kernels hold installed capacity. Cashew butter is rotating up the share rankings.
Distribution Channel:
Customer type and purchase scale dictate channel selection, with traceability requirements increasingly filtering options for export-oriented processors.
- Wholesale:Bulk volume transactions handling majority of raw nut throughput and commodity-grade kernel exports, characterized by spot-price negotiation and limited origin documentation. EU Deforestation Regulation traceability mandates are compressing wholesale channel viability for undocumented supply chains.
- Online Retail:Packaged kernel sales accelerating to Vietnamese and Southeast Asian diaspora communities in North America and Europe, where batch-level farm origin data now conditions repeat purchase behavior.
- Supermarkets:Branded packaged kernels reaching mass-market consumers with HACCP and ISO 22000 certification displayed as shelf differentiators.
- Specialty Stores:Premium-grade W180 and organic-certified kernels targeting health-conscious urban consumers willing to absorb price premiums for documented provenance.
Wholesale maintains throughput dominance. Online retail is climbing the fastest.
End User:
Application maturity varies across household consumption versus industrial formulation, with divergent specification stringency and contract duration.
- Snack Manufacturers:North American and European plant-based protein formulators driving specification-grade kernel demand with multi-year contracts requiring HACCP certification and aflatoxin testing protocols.
- Exporters:Re-export processors and trading houses consolidating volume for EU and US market access, where Vietnam's Ministry of Agriculture and Rural Development pesticide residue enforcement creates compliance gatekeeping.
- Food Processing Industry:Confectionery and bakery ingredient buyers seeking consistent W240 and W320 grades for recipe standardization.
- Household:Direct consumer purchases through retail channels, smaller individual transaction scale but expanding through e-commerce penetration.
Snack manufacturers command specification leadership. Exporters are expanding most quickly.
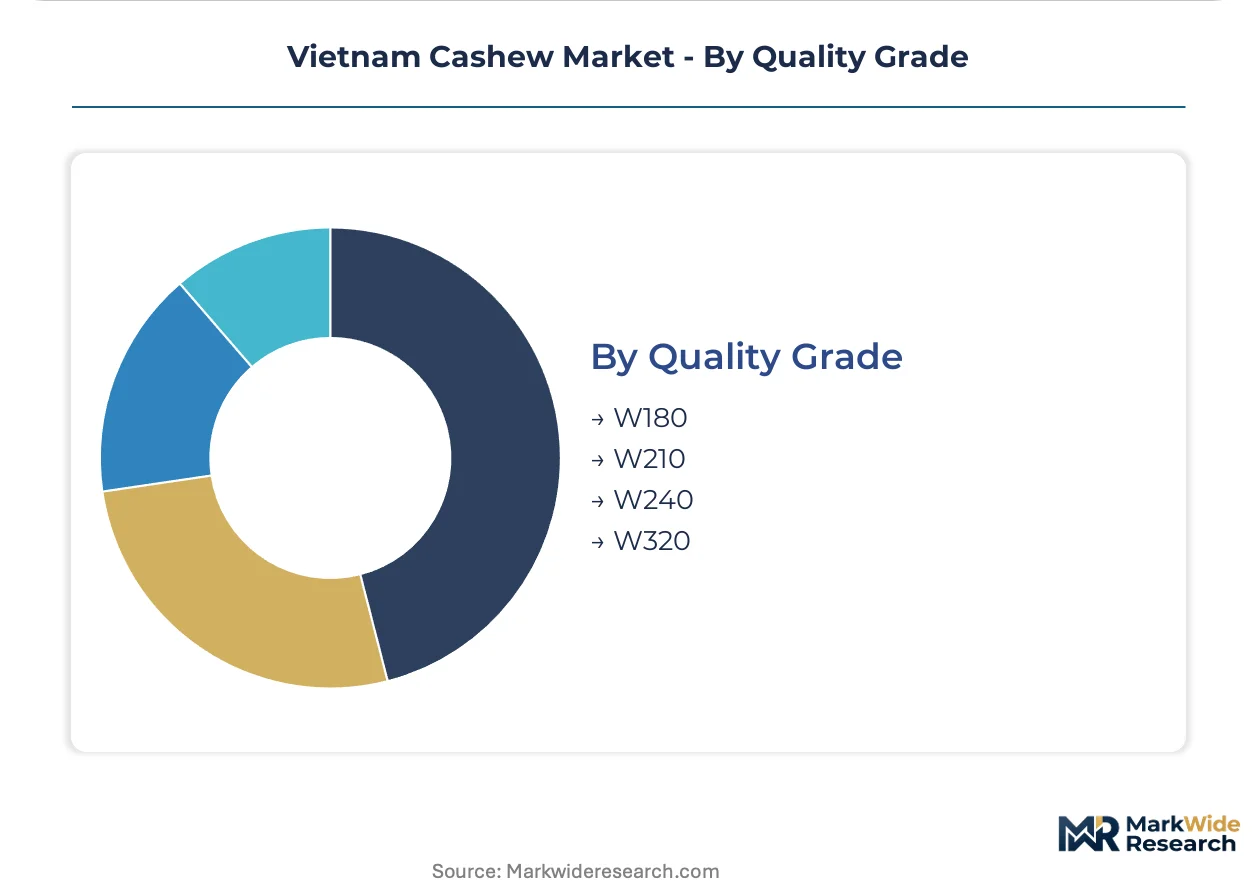
Quality Grade:
Kernel size and wholeness classification determines price tier placement and end-use suitability, with mechanical shelling automation compressing traditional grade spreads.
- W180:Largest whole kernels exceeding 18.0mm width, specialty-grade category commanding premium positioning from European confectionery buyers and gift-pack channels. Steam-vacuum hybrid roasting technology is reducing human grading error and stabilizing output consistency.
- W320:Standard whole kernels 15.9-17.0mm width, volume-grade workhorse of North American snack manufacturing and mainstream retail, where mechanical shelling automation has improved grade consistency for contract fulfillment.
- W210:Intermediate whole kernels 16.9-18.0mm width, bridging premium and standard tiers with flexible end-use application.
- W240:Mid-size whole kernels 14.0-15.9mm width, food processing industry preference for ingredient applications where visual presentation matters less than cost efficiency.
W320 holds installed capacity. W180 is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cat Lai-Cai Mep port complex underwrites Vietnam's cashew export dominance, handling over seventy percent of kernel container volume bound for EU and North American markets.
Binh Phuoc Province
Snack manufacturers in Germany and the Netherlands drive W180 grade demand from this southeastern growing belt. Vietnam's Ministry of Agriculture and Rural Development enforces pesticide residue protocols that favor processors with documented cooperative sourcing. The Chon Thanh industrial zone concentrates steam-vacuum hybrid roasting capacity for European confectionery contracts.
Dong Nai Province
North American cashew butter formulators source paste volumes from this southern processing hub. The national food safety regulator mandates HACCP certification for US market access, compressing timelines for new facility approvals. Bien Hoa city anchors industrial-scale shelling lines serving re-export traders.
Ho Chi Minh City Metro
Asian diaspora e-commerce channels accelerate packaged kernel sales through this logistics gateway. ISO 22000 audit requirements from Vietnam's agricultural coordination ministry delay smaller operator market entry. Thu Duc district warehouses consolidate traceability documentation for EU Deforestation Regulation compliance.
Ba Ria-Vung Tau Province
Cai Mep deep-water terminal throughput determines raw nut import velocity from West African origins. The country's national food safety standards compel aflatoxin testing infrastructure investment. Phu My industrial parks host caustic shell liquid waste management facilities constraining greenfield expansion.
Vietnam Cashew Market Competitive Environment
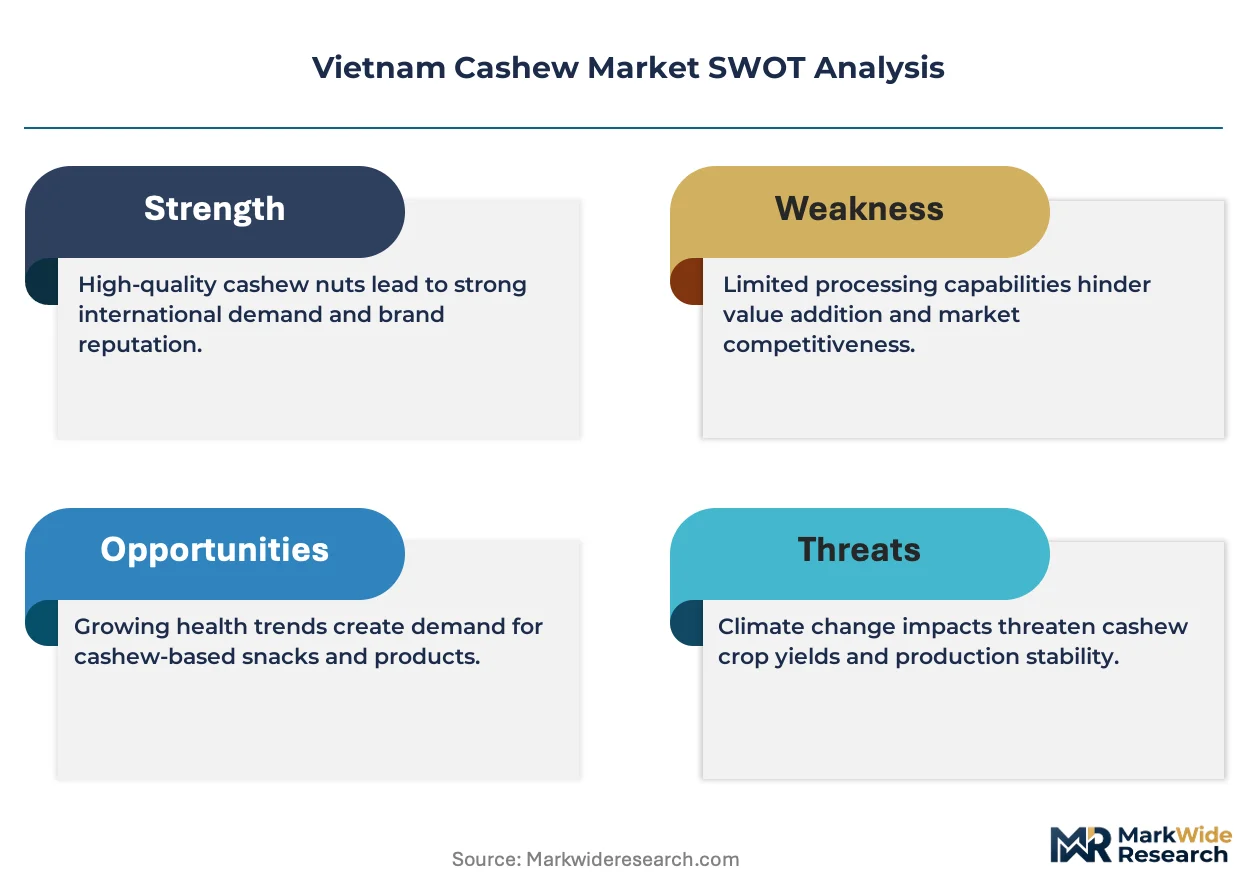
Platform integrators command the system tier; component specialists sit upstream in raw nut sourcing and specialty roasting. The Vietnam cashew sector exhibits tiered concentration around Binh Phuoc processing clusters and Dong Nai industrial corridors. Three archetypes dominate: cooperative-integrated processors with captive supply, export-trading houses with EU certification, and specialty-grade W180 specialists for European confectionery. Competitive moves center on backward integration into farmer cooperatives and HACCP-ISO 22000 certification acceleration for deforestation-regulation readiness.
Among Binh Phuoc-based processors, Cao Phat Co., Ltd. and Donafoods occupy positions exemplifying cooperative-sourcing archetypes, while Long Son Joint Stock Company represents the specialty-grade export tier. These entities anchor the competitive structure without exhaustive profiling, serving as reference points for strategic archetype analysis rather than operational specifics.
| Leading Market Players |
|---|
| Cao Phat Co., Ltd. |
| Donafoods (Dong Nai Food Industrial Corporation) |
| Long Son Joint Stock Company |
| An Viet Phat Holdings |
| Binh Phuoc Import Export Production Company |
| Tan Long Group |
| Phuc Thinh Cashew Processing Co., Ltd. |
| Phu Vinh Trading Service Company Limited |
| Hoang Son 1 Company Limited |
| Others |
Value Chain & Pricing Dynamics
Raw nut import dependency from West African origins compresses margin structures across all pricing tiers while simultaneously forcing supply chain reconfiguration toward documented cooperative sourcing. This dual pressure determines both the spread between commodity-grade and specialty-grade kernel quotations and the geographic routing of procurement investments.
Pricing Analysis
Volume-discount tiering structures dominate cashew kernel transactions, with W180 specialty grades commanding substantial premiums over W320 standard volumes due to European confectionery buyer specifications. Price differentiation rests on HACCP certification status and mechanical shelling automation levels, as steam-vacuum hybrid roasting capabilities separate contract-eligible processors from spot-market participants. Cost compression in mid-grade categories is intensifying because African competitor expansion erodes Vietnamese processor margins. Snack manufacturers in North America exhibit highest price sensitivity, while European gift-pack channels absorb premiums for documented provenance.
Supply Chain Analysis
EU Deforestation Regulation traceability mandates restrict market access for undocumented supply chains, compelling processors to map farm-gate origins. Geographic supply concentration centers on Binh Phuoc province for domestic raw material and Côte d'Ivoire, Ghana, and Nigeria for import dependency. Raw material flows draw from West African cooperative networks, Vietnamese farmer associations, and Cambodian border trade. Single-source vulnerability from West African political instability threatens input security. Distribution runs through Cat Lai-Cai Mep port complex consolidation for EU and North American container dispatch.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer procurement consolidation around North American and European snack manufacturers concentrates contract negotiation power, fragmenting processor margin capture across tiered certification requirements.
For Market Incumbents: Entrench cooperative-sourcing relationships in Binh Phuoc growing zones to secure traceability documentation required by EU Deforestation Regulation compliance. Accelerate HACCP-ISO 22000 certification timelines ahead of competitor capacity additions. African processor expansion represents the primary substitution threat; backward integration into farmer cooperatives provides the defensive lever. For New Entrants and Emerging Players: Establish a beachhead in cashew butter formulation supply to North American plant-based spread manufacturers, where application diversification lags kernel processing saturation. Asian diaspora e-commerce channels in Ho Chi Minh City Metro offer the most penetrable distribution entry point. Direct-to-consumer packaged kernel sales bypass wholesale channel consolidation. For Investors and Strategic Acquirers: The market sits at a certification-intensification phase that favors processors with completed HACCP-ISO 22000 audit cycles and documented Binh Phuoc cooperative networks. Long-term viability across the analysis window hinges on deforestation-regulation readiness rather than spot-price optimization capability. Acquisition targets should demonstrate integrated sourcing zones. The signal to watch is EU Deforestation Regulation enforcement timeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farmer Cooperatives | Captive supply from Binh Phuoc growing zones stabilizes input costs against West African currency volatility. |
| HACCP-ISO 22000 Certification Acceleration | Audit completion unlocks EU and North American snack manufacturer contract eligibility ahead of regulatory deadlines. |
| Steam-Vacuum Hybrid Roasting Capacity Addition | Mechanical shelling automation reduces human grading error for W180 specialty-grade European confectionery contracts. |
| Cashew Butter Formulation Partnership | Plant-based spread applications diversify revenue beyond commodity kernel exports to North American manufacturers. |
| Traceability Documentation System Deployment | Batch-level farm origin data satisfies EU Deforestation Regulation procurement conditions for contract renewal. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with cashew processing plant managers, European confectionery procurement leads, North American snack manufacturer R&D directors, and Vietnamese farmer cooperative representatives. Secondary validation drew from Vietnam Ministry of Agriculture and Rural Development food safety filings, EU Deforestation Regulation implementation guidance, customs export records, and ISO 22000 certification registries. Bottom-up processor capacity surveys and top-down export value triangulation cross-checked volume estimates.
Calibration against historical price spreads between W180 and W320 grades anchored growth trajectory assumptions across the projection horizon. Segmentation modeling captured product type stratification, distribution channel evolution, end-use application maturity, and quality grade tiering. CAGRs were derived from import dependency ratios, certification penetration curves, and mechanical automation adoption rates. Forecast inputs incorporated EU regulatory enforcement timelines and West African supply disruption probabilities.
Sensitivities concentrate around EU Deforestation Regulation implementation acceleration and West African raw nut export policy shifts. Forecasts reflect assumptions regarding certification cost absorption capacity and cooperative sourcing relationship durability. Material shifts in Vietnamese food safety enforcement stringency or African competitor processing capacity expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Tree Nut Allergy Market
Nuts and Seeds
Almond Butter Market
Nuts and Seeds
Almond Oil Market
Nuts and Seeds
Breadnut Market
Nuts and Seeds
Almond Extract Market
Nuts and Seeds
South America Nut-Based Spread Market
Nuts and Seeds
Pistachios Market
Nuts and Seeds
Horse Chestnut Seed Extract Market
Nuts and Seeds
Almond Market
Nuts and Seeds
Pecans Market
Nuts and Seeds
Maca Market
Nuts and Seeds
Walnut Oil Market
Nuts and Seeds
Germany Cashew Market
Nuts and Seeds
Passionfruit Seed Oil Market
Nuts and Seeds
Nuts Market
Nuts and Seeds
China Almond Market