
 Organic Almond Oil Market | 2026-2036
Organic Almond Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Almond Oil Market Analytics
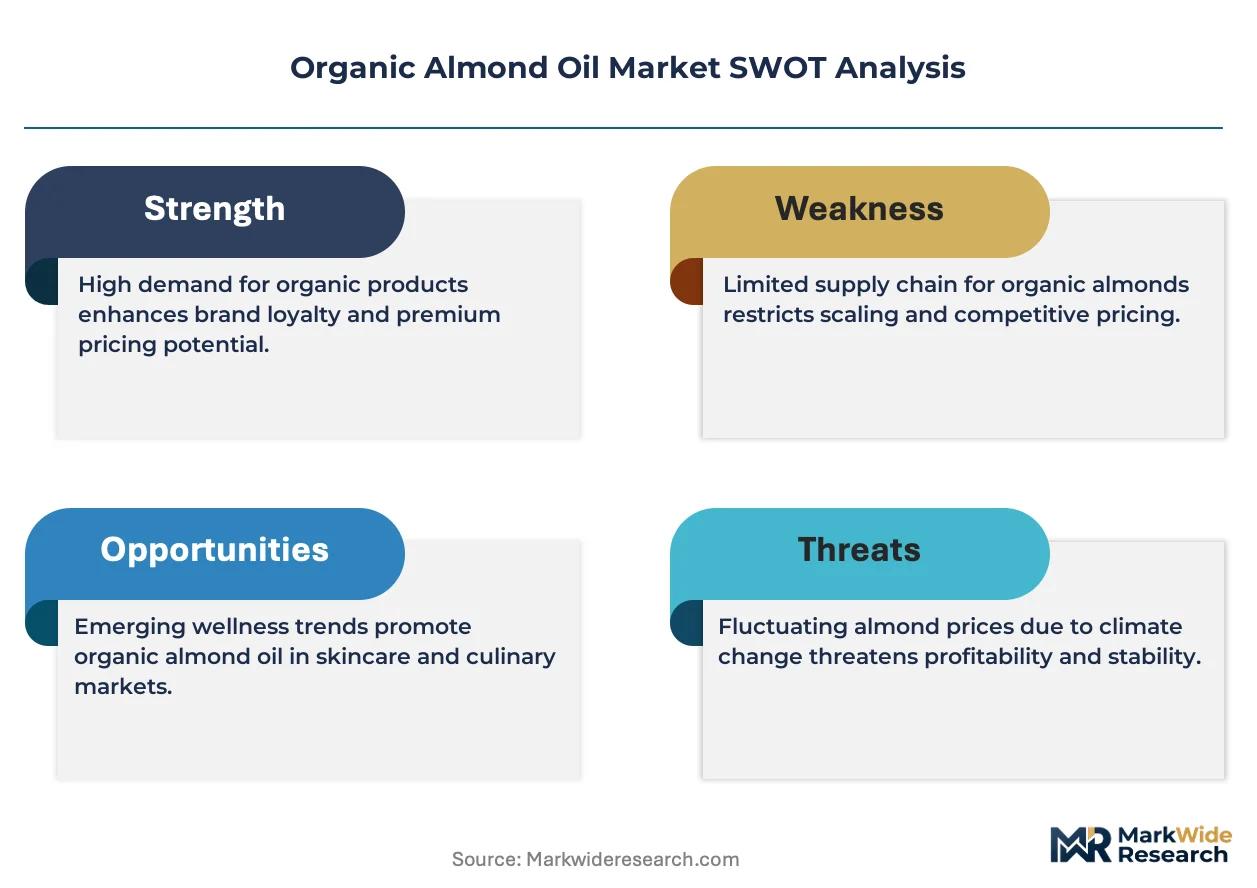
Fragmentation among indie beauty brands and direct-to-consumer wellness startups is repositioning procurement patterns across the organic almond oil value chain. AOS Products Pvt. Ltd leverages its India-based cold-press infrastructure to supply bulk cosmetic-grade oil to European formulators. Blue Diamond Global Ingredients Division anchors North American supply through its integrated almond orchards in California. NOW Foods competes via certified organic SKUs distributed through health stores and online retail channels.
Organic almond oil is a fixed oil extracted from Prunus dulcis kernels through cold-pressing or expeller methods, retaining oleic acid concentrations above 60% and vitamin E levels that deliver oxidative stability in topical and edible applications. Cosmetic oil leads product type demand due to premium positioning in anti-aging and sensitive-skin formulations, while edible oil sustains growth through clean-label cooking and nutraceutical applications. Specialty stores dominate distribution channel value capture, though online retail is accelerating as subscription beauty boxes and DTC wellness platforms expand.
EMA cosmetic ingredient guidelines, USDA National Organic Program standards, and REACH chemical safety frameworks collectively govern market access and product differentiation across producing and consuming regions. These regulators enforce extraction method disclosures, residue limits, and organic certification chain-of-custody requirements that directly shape supplier qualification costs. Stakeholders must monitor evolving EU Green Deal sustainability metrics and FDA cosmetic labeling modernization to anticipate compliance-driven sourcing shifts.
Market Dynamics
Clean-label cosmetics procurement is compressing extraction-to-shelf timelines while REACH compliance costs are restructuring supplier qualification tiers across European personal care value chains.
Growth Catalysts
- EU Green Deal sustainability metrics:Mandatory carbon footprint disclosures are redirecting procurement toward cold-press extraction methods with verified chain-of-custody documentation.
- Nutraceutical edible oil applications:Clean-label cooking oil demand in Germany and France is expanding food-grade organic almond oil volumes beyond traditional cosmetic uses.
- California almond orchard consolidation:Integrated growing and processing operations are stabilizing raw kernel supply for cosmetic-grade oil extraction.
Market Restraints
- Water-intensive cultivation:California almond production faces irrigation quota restrictions under state drought management frameworks.
- Single-origin supply concentration:Overreliance on Central Valley orchards creates climate vulnerability in kernel procurement.
- High oleic acid standardization:Batch-to-batch fatty acid profile variation complicates cosmetic formulation consistency.
Strategic Opportunities
- Spanish organic cultivation expansion:Andalusian orchard development offers EU-origin kernel supply with reduced transatlantic logistics exposure.
- Subscription beauty box channels:Direct-to-consumer wellness platforms are creating captive demand for small-format cosmetic oil SKUs.
- ISO 16128 natural origin certification:Harmonized cosmetic ingredient standards are enabling cross-border formulation portability.
Industry Challenges
- Cold-press technician scarcity:Specialized equipment operation and temperature-controlled extraction expertise gaps constrain capacity expansion.
- USDA-NOP organic certification timelines:Three-year conversion periods for conventional orchard transitions delay new supply entry.
- Legacy ERP integration:Batch traceability systems struggle to interface with emerging blockchain-based chain-of-custody platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Almond Oil Market |
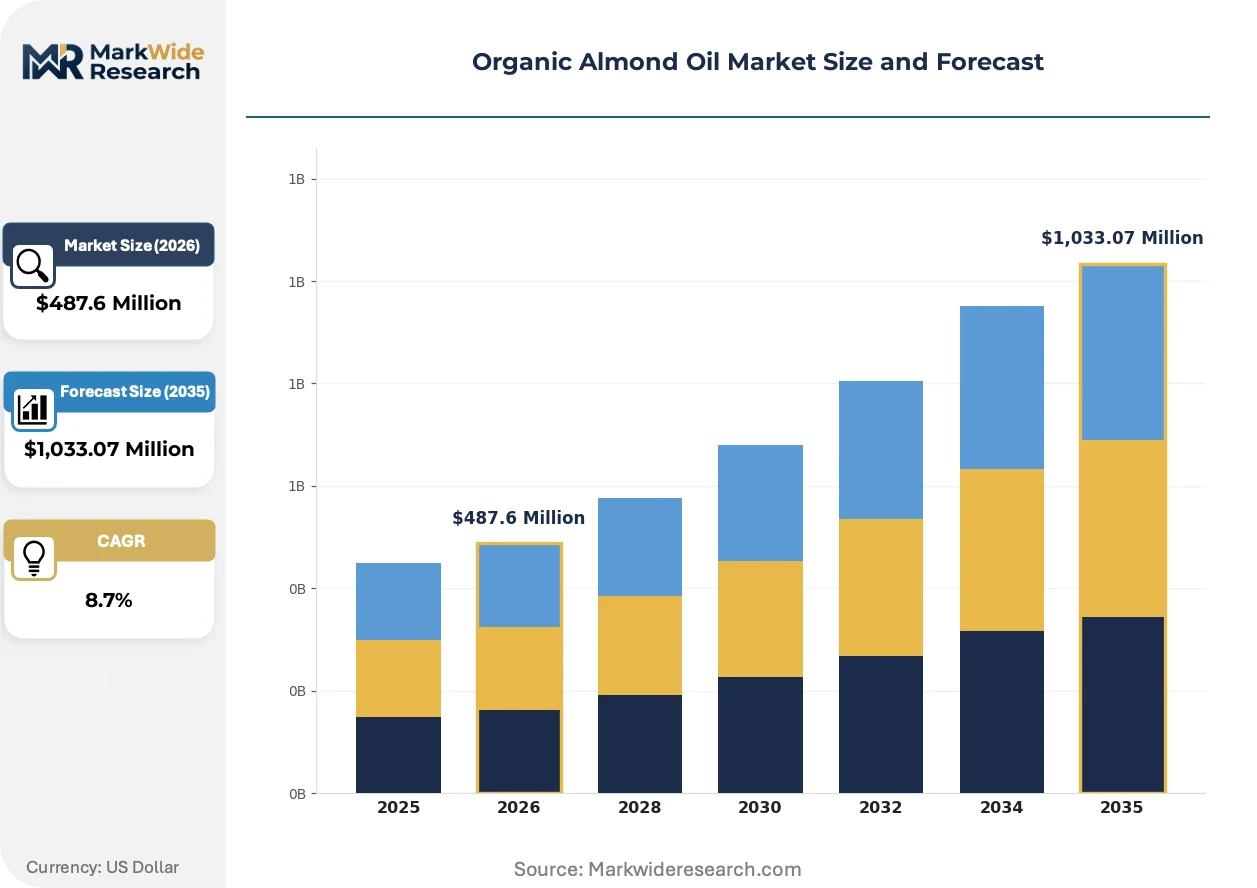
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carrier Oil, Cosmetic Oil, Edible Oil, Aromatherapy Oil Application: Cosmetics, Food Industry, Personal Care, Pharmaceuticals Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Stores Form: Liquid, Solid, Emulsified, Bulk Packaging |
| Companies Covered | AOS Products Pvt. Ltd, Ashwin Fine Chemicals & Pharmaceuticals, Blue Diamond Global Ingredients Division, Caloy Company, LP, NOW Foods, Frontier Co-op, Bajaj Consumer Care Ltd., Dabur India Ltd, Liberty Vegetable Oil Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Almond Oil Market Evolving Landscape
Supercritical CO2 extraction is advancing alongside blockchain traceability adoption, while regulatory disclosure requirements are tightening across multiple jurisdictions simultaneously.
Supercritical CO2 extraction technology is converging with cosmetic-grade oil production, replacing solvent-based methods in premium formulation supply chains. German and French skincare manufacturers are piloting these systems at pilot-plant scale. The technology is converging with existing cold-press infrastructure to create hybrid extraction facilities that serve both mass-market and luxury segments.
REACH chemical safety frameworks are expanding residue testing mandates for imported cosmetic ingredients. ECHA registration requirements now cover previously exempt low-volume substances in topical applications. European formulators are responding by demanding third-party extraction method certifications from Indian and Californian suppliers.
Beauty box subscription models are fragmenting bulk procurement into micro-lot orders with customized fatty acid specifications. Indie skincare brands are bypassing traditional distributors to source directly from cold-press facilities. This pattern is most visible in German urban markets where direct-to-consumer wellness platforms command growing shelf-space equivalent.
Organic Almond Oil Market Segmentation
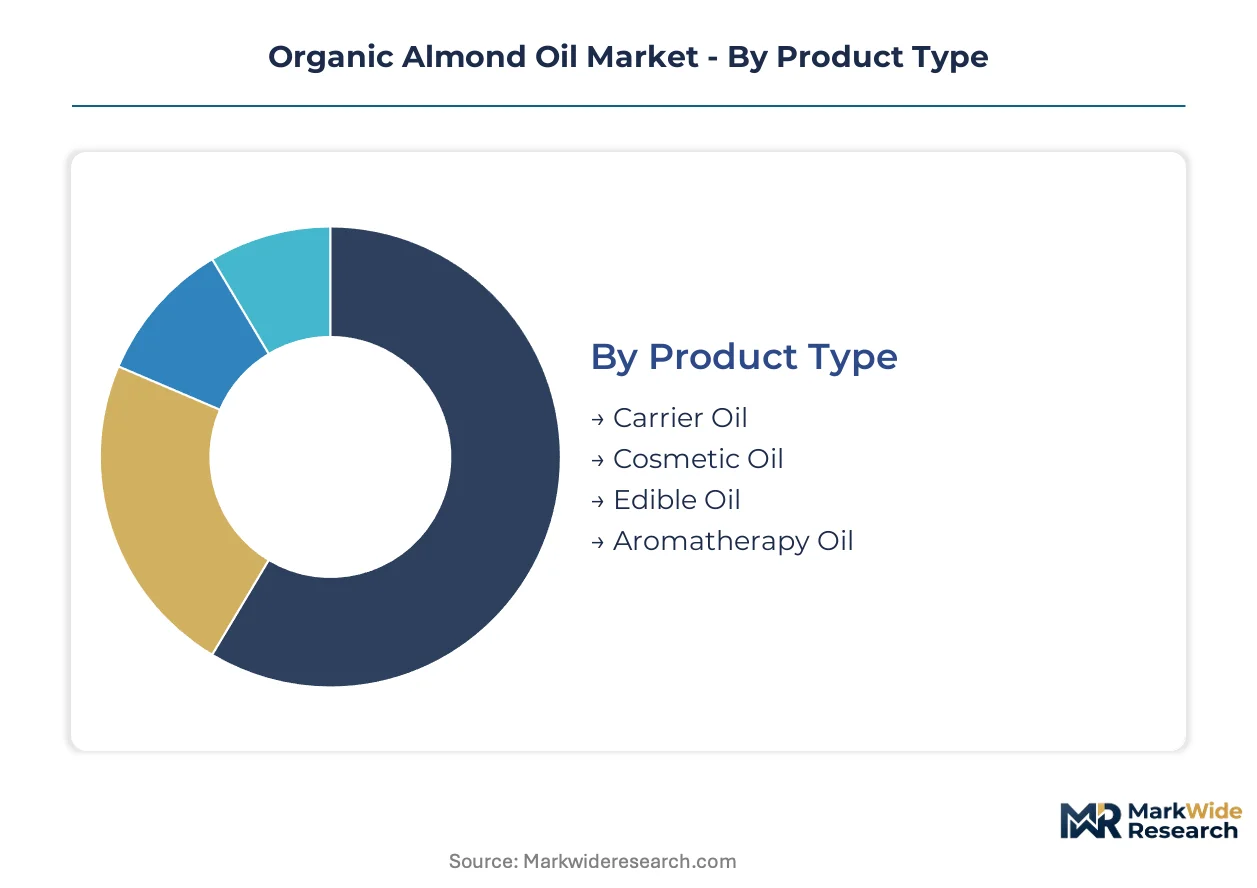
Segmentation in organic almond oil reveals how extraction specifications, end-use purity requirements, and channel logistics create distinct procurement ecosystems. Formulators select grades based on fatty acid profiles, while distribution strategies diverge between bulk industrial supply and precision-dosed consumer formats.
Product Type:
The customization-vs-standardization spectrum spans from bulk carrier formulations requiring minimal specification to cosmetic grades demanding batch-certified oleic acid thresholds and cold-press documentation.
- Cosmetic Oil:Cold-pressed grades with oleic acid concentrations above 60% and vitamin E retention serve anti-aging and sensitive-skin formulations. Demand concentrates in German and French skincare manufacturing where REACH compliance mandates extraction method disclosure and residue testing.
- Edible Oil:Food-grade organic certification under USDA National Organic Program standards supports clean-label cooking and nutraceutical applications. Clean-label cooking demand in Germany and France is expanding volumes beyond traditional cosmetic uses.
- Carrier Oil:Neutral-scent base oil for essential oil dilution in massage and aromatherapy blends.
- Aromatherapy Oil:Specially packaged small-format oil for wellness practitioners and home diffusion use.
Leading the category by volume: Cosmetic Oil. Growing fastest: Edible Oil.
Application:
End-use concentration tilts toward premium personal care, with pharmaceutical and food sectors imposing divergent purity and documentation burdens.
- Cosmetics:Facial serums, moisturizers, and hair treatments leverage oxidative stability from high vitamin E content. German and French formulators are piloting supercritical CO2 extraction systems at pilot-plant scale for premium supply chains.
- Personal Care:Body oils, cleansers, and baby care products require gentle extraction methods for sensitive-skin positioning.
- Food Industry:Salad dressings, finishing oils, and functional food formulations demand flavor-stable cold-press grades.
- Pharmaceuticals:Topical medicinal preparations and softgel encapsulation require pharmacopeia-compliant purity certification.
Cosmetics dominates revenue contribution. Pharmaceuticals climbs steepest as medicinal topical applications expand.
Distribution Channel:
Channel selection tracks order granularity, with bulk procurement consolidating through specialty intermediaries while micro-lot fragmentation accelerates through direct platforms.
- Specialty Stores:Premium positioning through curated beauty and wellness retailers with trained staff consultation. Indie skincare brands in German urban markets are bypassing traditional distributors to source directly from cold-press facilities.
- Online Retail:Subscription beauty boxes and direct-to-consumer wellness platforms are creating captive demand for small-format SKUs with customized fatty acid specifications.
- Health Stores:Certified organic SKUs distributed through natural products retailers with established organic certification trust.
- Supermarkets:Mass-market edible oil placement competing with conventional nut oils on shelf price positioning.
Specialty Stores capture highest value per liter. Online Retail expands most quickly as subscription models fragment bulk procurement.
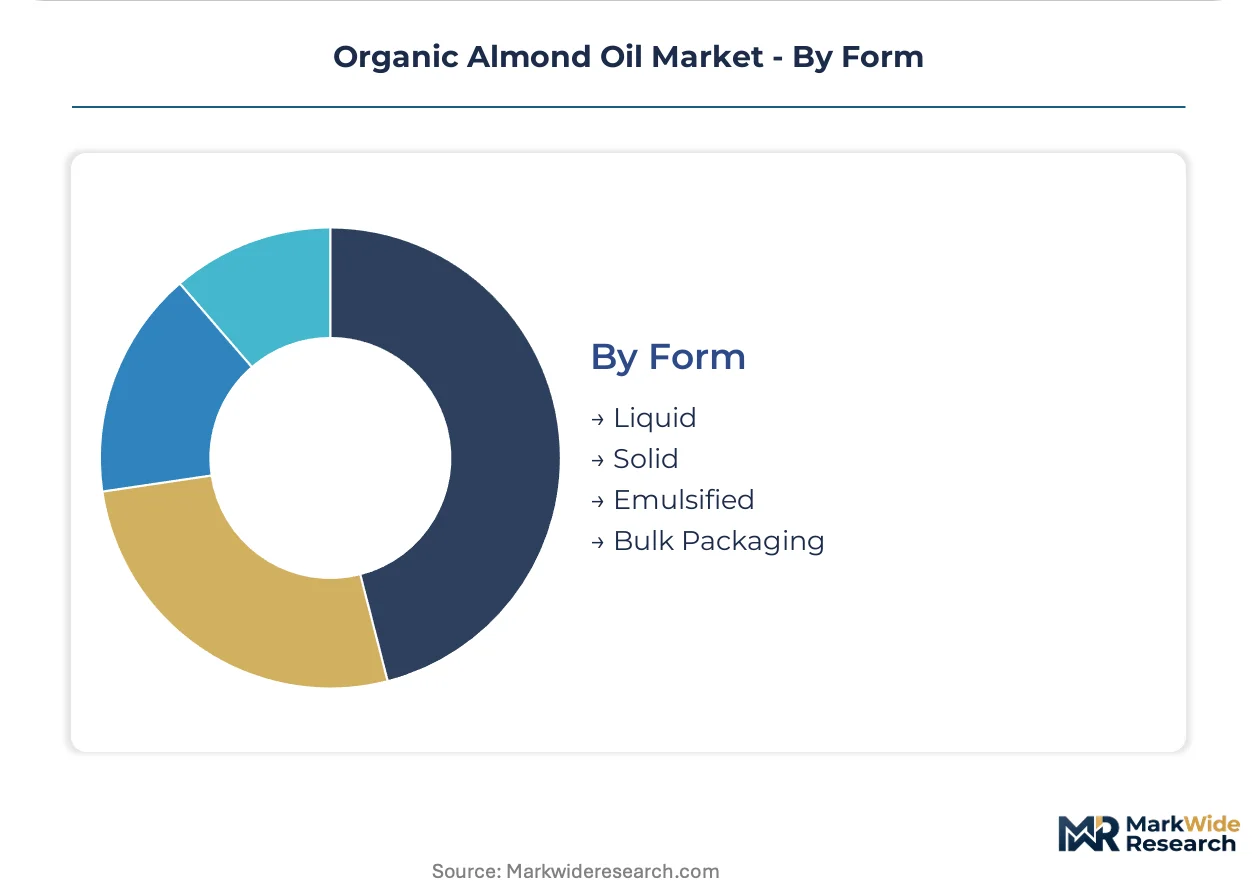
Form:
Physical state and packaging configuration determine shelf stability, dosing precision, and logistics cost structure across the value chain.
- Liquid:Standard pourable oil in glass or PET bottles for direct application and formulation feedstock.
- Bulk Packaging:Drum and tote quantities for cosmetic manufacturers and food processors with integrated filling operations.
- Emulsified:Pre-stabilized water-in-oil or oil-in-water preparations for ready-to-use cosmetic formulations.
- Solid:Hydrogenated or fractionated forms for balm bases and temperature-stable transport.
Liquid leads by volume throughput. Emulsified gains share fastest as formulators seek production efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic formulators in Germany, France, and Spain drive the bulk of European organic almond oil procurement, while California's integrated orchard operations anchor transatlantic supply chains for premium cold-pressed grades.
Germany
REACH compliance mandates extraction method disclosure and residue testing for cosmetic-grade imports. The EU Green Deal's carbon footprint requirements redirect procurement toward cold-press facilities with verified chain-of-custody documentation. Hamburg and Frankfurt host formulators piloting supercritical CO2 extraction at pilot-plant scale for premium skincare supply chains.
France
Clean-label cooking demand in Paris and Lyon expands food-grade organic almond oil volumes beyond traditional cosmetic applications. ANSM cosmetic ingredient guidelines enforce batch traceability for topical formulations. The Provence-Alpes-Côte d'Azur region concentrates indie beauty brands sourcing directly from cold-press facilities for sensitive-skin positioning.
Spain
Andalusian orchard development offers EU-origin kernel supply with reduced transatlantic logistics exposure. Spanish organic cultivation expansion attracts formulators seeking alternatives to California supply concentration. Seville and Granada host emerging cold-press operations serving both domestic cosmetic manufacturers and export markets.
United States
California almond orchard consolidation stabilizes raw kernel supply for cosmetic-grade oil extraction through integrated growing and processing operations. State drought management frameworks impose irrigation quota restrictions on Central Valley production. The Sacramento Valley concentrates Blue Diamond Global Ingredients Division's captive supply infrastructure.
India
AOS Products Pvt. Ltd leverages Rajasthan-based cold-press infrastructure to supply bulk cosmetic-grade oil to European formulators. FSSAI food safety standards and USDA National Organic Program certification requirements govern export qualification. Jaipur and Udaipur cluster traditional oil extraction operations upgrading to temperature-controlled systems for international compliance.
Organic Almond Oil Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer wellness platforms and subscription beauty box channels. The vendor base stratifies across integrated orchard operators, contract cold-press specialists, and certified organic distributors. Three archetypes dominate: California-based integrated growers controlling upstream kernel supply, Indian contract manufacturers serving European formulators, and North American certified organic brands distributing through health retail channels. Competitive moves concentrate on geographic expansion into Spanish cultivation zones and portfolio diversification into emulsified and small-format SKUs.
Within the integrated-grower tier, Blue Diamond Global Ingredients Division anchors North American supply through its California orchard base. Among contract manufacturing specialists, AOS Products Pvt. Ltd represents the India-to-Europe supply corridor. On the certified-organic retail vector, NOW Foods exemplifies health-store and online channel penetration. These three occupy positions spanning upstream agricultural control through downstream brand distribution.
| Leading Market Players |
|---|
| AOS Products Pvt. Ltd |
| Ashwin Fine Chemicals & Pharmaceuticals |
| Blue Diamond Global Ingredients Division |
| Caloy Company, LP |
| NOW Foods |
| Frontier Co-op |
| Bajaj Consumer Care Ltd. |
| Dabur India Ltd |
| Liberty Vegetable Oil Company |
| Others |
Value Network & Pricing Analysis
German and French cosmetic formulators concentrate procurement power through long-term offtake agreements, anchoring a contract-based pricing model that rewards verified cold-press documentation and REACH-compliant chain-of-custody certification.
Pricing Analysis
Volume procurement through integrated orchard operators captures margin stability, while indie beauty brands purchasing micro-lots face premium-mid-economy pricing differentiation based on fatty acid certification and batch traceability. Cold-press cosmetic grades command spreads over expeller-processed edible tiers due to vitamin E retention thresholds. Price erosion runs through bulk edible oil segments as California drought quotas compress kernel yields. Subscription beauty box channels exhibit lowest price sensitivity; supermarket edible oil placement faces highest.
Supply Chain Analysis
Kernel supply rests on California Central Valley orchards, Spanish Andalusian cultivation zones, and Rajasthan-based Indian processing clusters. Raw material flows draw from almond cultivation, cold-press equipment fabrication, and organic certification auditing services. Single-origin concentration in California exposes procurement to irrigation quota restrictions under state drought frameworks. Distribution runs through specialty chemical intermediaries for bulk cosmetic manufacturers and direct-to-consumer platforms for indie brand micro-lots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as players pursue captive control over cold-press extraction capacity to secure margin capture and REACH compliance documentation.
For Market Incumbents: Anticipate margin compression from Spanish orchard expansion and supercritical CO2 extraction pilots by securing backward integration into Andalusian cultivation zones. Prioritize ISO 16128 certification investment to defend formulation portability against emerging EU-origin suppliers. Cold-press technician scarcity represents the critical capacity constraint requiring apprenticeship pipeline development. For New Entrants and Emerging Players: Subscription beauty box channels offer the most penetrable route for small-format SKU entry with customized oleic acid specifications. Target German urban markets where direct-to-consumer wellness platforms fragment traditional distributor relationships. Emphasize blockchain-based chain-of-custody documentation as the differentiated go-to-market anchor against legacy ERP-dependent incumbents. For Investors and Strategic Acquirers: The window for entry favors Indian contract manufacturers with USDA-NOP certification and established European formulator relationships. Long-term viability hinges on irrigation-resilient supply geography diversification beyond California concentration. Watch Spanish organic cultivation conversion timelines as the inflection signal for EU-origin supply competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Operations | Captive kernel supply insulates margin capture from California drought quota volatility. |
| Cold-Press Capacity Expansion | Temperature-controlled extraction infrastructure addresses REACH disclosure mandates for German formulators. |
| Blockchain Traceability Implementation | Distributed ledger documentation satisfies EU Green Deal carbon footprint verification requirements. |
| Subscription Channel Partnership | Direct-to-consumer wellness platforms fragment bulk procurement into high-margin micro-lot demand. |
| Supercritical CO2 Pilot Investment | Hybrid extraction technology serves premium cosmetic segments alongside existing cold-press infrastructure. |
Research Methodology
Trade databases, ECHA registration filings, and USDA National Organic Program certification records formed the secondary backbone, cross-referenced with primary interviews involving cold-press facility operators, European cosmetic formulator procurement leads, and Indian export compliance officers. Bottom-up and top-down triangulation validated volume estimates across extraction method tiers and end-use applications.
Bottom-up modeling anchored projections, with top-down macro validation across product type, application, distribution channel, and geographic production hub dimensions. CAGRs were derived from segmented growth rate analysis incorporating kernel yield trajectories, regulatory compliance cost inflation, and channel shift velocities. Supercritical CO2 adoption curves and Spanish orchard conversion timelines served as industry-specific forecast inputs throughout the analysis window.
The model holds under stable California irrigation quota enforcement and REACH residue testing continuity; deviation in drought severity or ECHA low-volume substance reclassification would shift supply geography and pricing tier dynamics. A small set of named triggers—Spanish organic certification acceleration, blockchain traceability standardization, and cold-press technician training pipeline development—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
North America Peanut Butter Market
Nuts and Seeds
Edible Peanut Powder Market
Nuts and Seeds
Japan Fox Nuts Market
Nuts and Seeds
Bambara Beans Market
Nuts and Seeds
North America Moringa Products Market
Nuts and Seeds
Processed Walnuts Market
Nuts and Seeds
Nut Butters Market
Nuts and Seeds
Almond Extract Market
Nuts and Seeds
Almond Oil Market
Nuts and Seeds
Dry Fruits Market
Nuts and Seeds
Nuts Market
Nuts and Seeds
Germany Cashew Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Almond Butter Market
Nuts and Seeds
India Cashew Market
Nuts and Seeds
Blackcurrant Seed Oil Market