
 Nut Ingredients Market | 2026-2036
Nut Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Nut Ingredients Market Analysis
Food manufacturers are rotating procurement toward bakeries as the primary demand archetype for nut butters and flours. Olam Food Ingredients leverages integrated sourcing from origination markets to secure almond and cashew supply chains. Barry Callebaut AG differentiates through chocolate-confectionery grade nut paste specialization. Blue Diamond Growers dominates California almond ingredient production with vertical orchard-to-processing control.
Nut ingredients comprise processed or semi-processed forms of tree nuts and peanuts, including butters with specified particle size distributions below 50 microns, flours with fat contents ranging from 10% to 50%, and cold-pressed oils retaining tocopherol profiles above 200 ppm. These inputs deliver protein fortification, textural modification, and clean-label fat replacement across formulated foods. Whole nuts retain the largest volume share within product type segmentation, though nut flours are gaining traction as gluten-free bakery formulations expand. Confectionery application margins compress under cocoa butter price volatility, while breakfast cereals offer steadier contract structures for suppliers.
The FDA enforces strict aflatoxin action levels for peanut and tree nut products entering interstate commerce, forcing importers to deploy pre-shipment testing protocols. EU REACH and EFSA mycotoxin standards further constrain supplier eligibility for European food manufacturers. Stakeholders must monitor evolving allergen labeling mandates from Health Canada and emerging sustainability disclosure requirements under the EU Green Deal.
Market Dynamics
Plant-based bakery applications are displacing confectionery as the dominant demand archetype, forcing ingredient suppliers to reconfigure particle size specifications and fat content profiles for dough conditioning rather than chocolate suspension.
Growth Catalysts
- Clean-label bakery expansion:European snack manufacturers are scaling procurement of almond and cashew flours as gluten-free formulations capture shelf space from wheat-based alternatives.
- EU REACH mycotoxin thresholds:Tighter raw nut sourcing protocols are accelerating supplier consolidation toward vertically integrated processors capable of pre-shipment testing documentation.
- Germany's procurement concentration:Clean-label snack producers in Bavaria and Baden-Württemberg are establishing multi-year contracts that stabilize volume commitments for specialty nut butter suppliers.
Market Restraints
- California almond supply concentration:Orchard-to-processing control by dominant growers creates pricing power asymmetry for downstream ingredient purchasers.
- Cocoa butter price volatility:Confectionery application margins compress unpredictably, destabilizing contract structures for nut paste suppliers serving chocolate manufacturers.
- FDA aflatoxin action levels:Strict enforcement for peanut and tree nut products forces importers to deploy redundant testing protocols, elevating landed costs.
Strategic Opportunities
- Breakfast cereal contract structures:Steadier procurement patterns compared to confectionery offer suppliers predictable volume commitments and longer planning horizons.
- Cold-pressed oil tocopherol retention:Premium positioning above 200 ppm antioxidant profiles enables differentiation in functional food applications.
- EU Green Deal sustainability disclosure:Emerging requirements for supply chain transparency create first-mover advantage for processors with origination-level traceability systems.
Industry Challenges
- Allergen labeling mandate evolution:Health Canada's pending specification changes require reformulation documentation and packaging redesign cycles.
- Particle size distribution precision:Sub-50 micron specifications for nut butters demand capital-intensive milling equipment and quality control infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nut Ingredients Market |
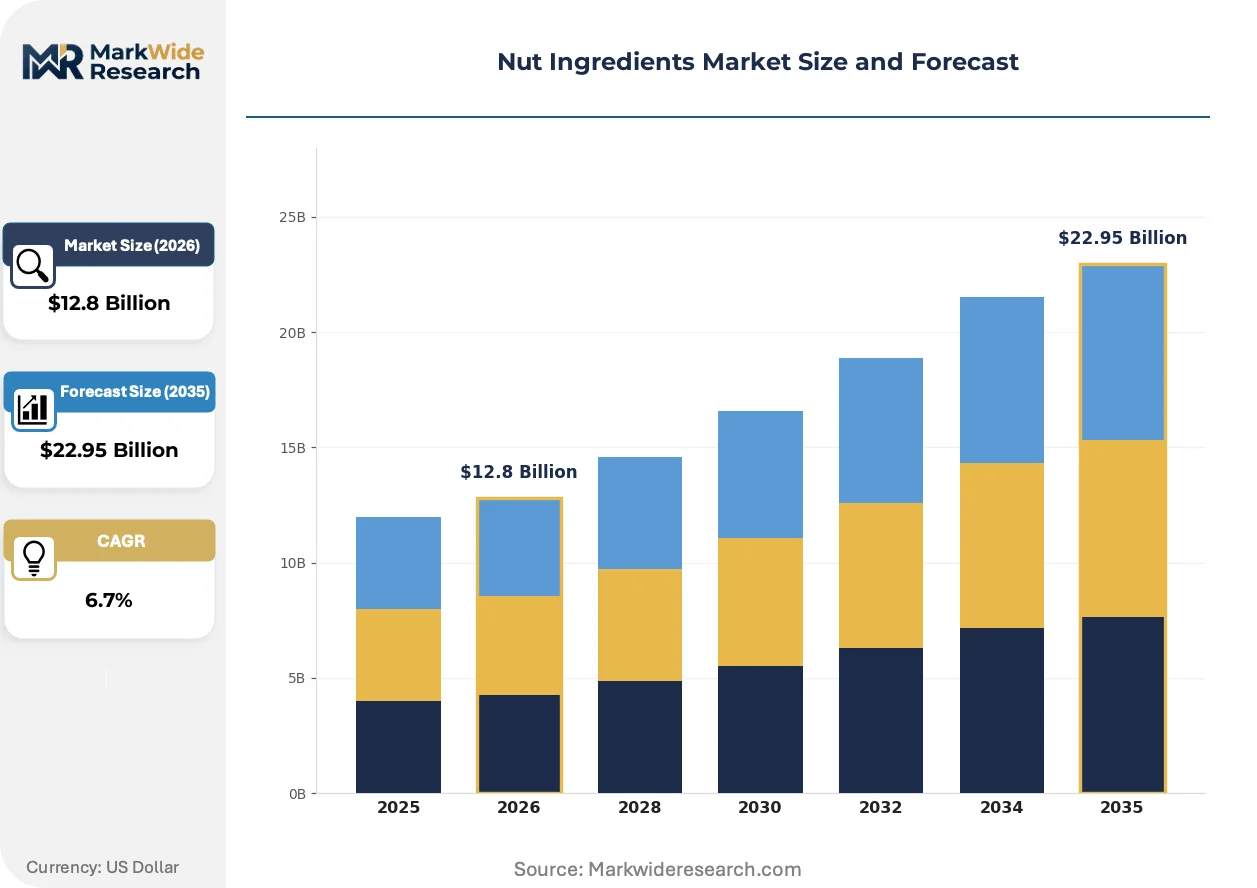
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Nuts, Nut Butters, Nut Flours, Nut Oils Application: Baking, Snacks, Confectionery, Breakfast Cereals End User: Food Manufacturers, Bakeries, Restaurants, Retailers Grade: Organic, Conventional, Premium, Natural |
| Companies Covered | Archer Daniels Midland Company, Olam Food Ingredients, Barry Callebaut AG, Blue Diamond Growers, John B. Sanfilippo & Son Inc., Kanegrade Limited, The Wonderful Company LLC, Royal Nut Company, Borges Agricultural & Industrial Nuts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nut Ingredients Market Emerging Trajectories
Processing technology and regulatory disclosure requirements are converging to reshape competitive positioning across ingredient tiers, with particle engineering and supply chain transparency emerging as primary differentiation vectors.
High-pressure processing for nut paste stabilization is fragmenting the microbiological safety landscape. Bakery manufacturers are adopting HPP-treated almond butters to eliminate thermal degradation of protein functionality. This technology is fragmenting the traditional pasteurization equipment market as cold-chain infrastructure investments displace conventional roasting lines.
EFSA mycotoxin standards are tightening maximum permissible levels for aflatoxin B1 in tree nut ingredients. European food manufacturers are responding by restricting supplier eligibility to processors with in-house ELISA testing capabilities. Almond paste and cashew butter categories face the steepest compliance costs, driving consolidation toward integrated origination processors.
Specification-driven procurement contracts are replacing commodity spot purchasing for premium nut flours. Snack manufacturers in Germany and France are demanding certified fat content ranges between 10% and 50% with batch-level certificates of analysis. This pattern concentrates purchasing power among buyers with technical staffing to audit supplier quality systems.
Nut Ingredients Market Segmentation
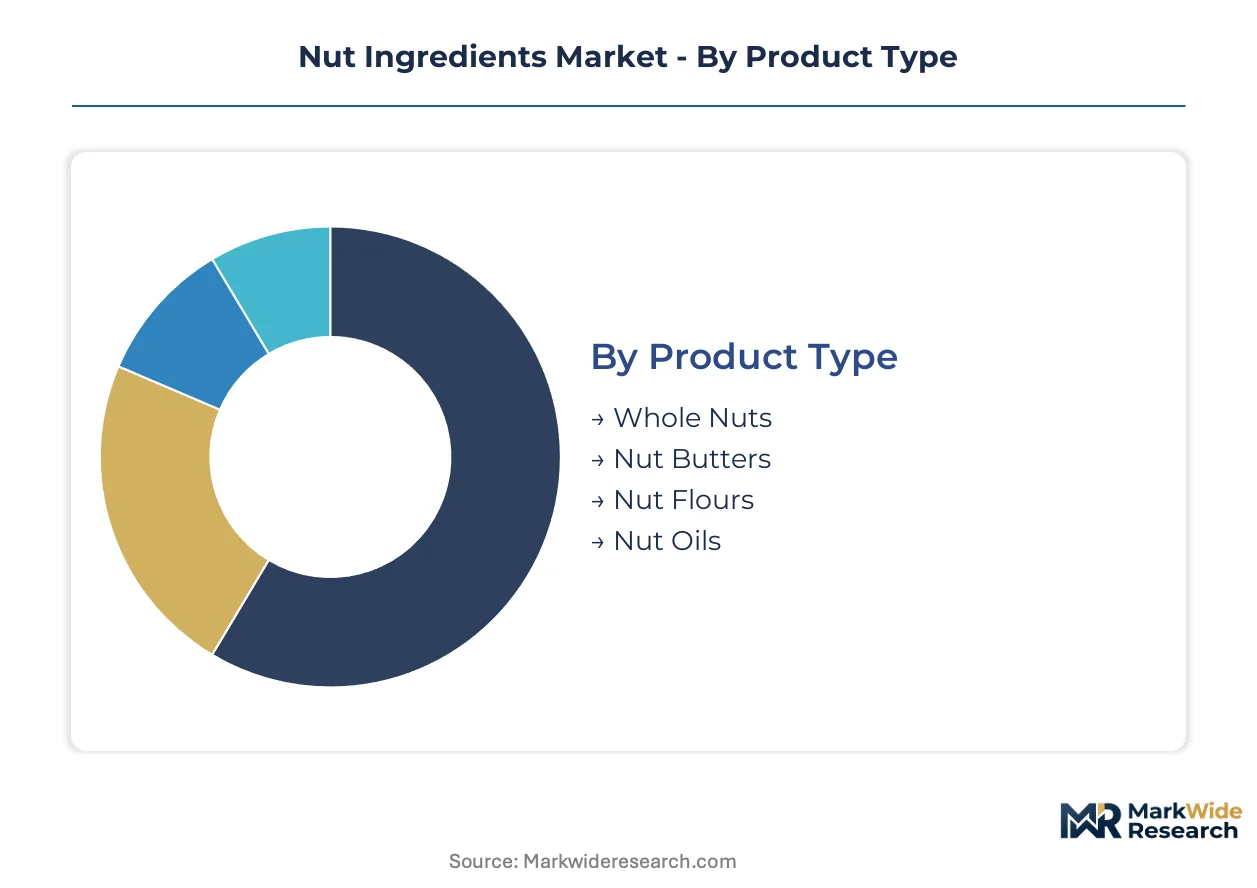
Nut ingredient procurement patterns diverge sharply across product formats and end-use specifications. Suppliers must calibrate milling precision, fat content profiles, and certification tiers to match distinct buyer requirements across bakery, confectionery, and retail channels.
Product Type:
Domestic processing capacity in California and Spain concentrates whole nut supply, while nut butters and flours flow through export-led trade corridors into European bakery clusters.
- Whole Nuts:Raw and roasted kernels retain intact cellular structures for texture-critical applications. Almond and cashew volumes concentrate in German clean-label snack manufacturing, driven by Bavarian producers scaling multi-year procurement contracts.
- Nut Butters:Paste specifications demand particle size distributions below 50 microns for dough conditioning and chocolate suspension. High-pressure processing adoption is fragmenting traditional pasteurization equipment markets as cold-chain infrastructure investments displace conventional roasting lines.
- Nut Flours:Defatted and partially defatted powders with fat contents ranging from 10% to 50% serve gluten-free bakery formulations.
- Nut Oils:Cold-pressed extraction retains tocopherol profiles above 200 ppm for functional food positioning.
Whole nuts hold the largest share; momentum sits with nut flours as gluten-free formulations capture shelf space from wheat-based alternatives.
Application:
Margin structures vary by application volatility, with breakfast cereals offering steadier contract terms than confectionery segments exposed to cocoa butter price swings.
- Baking:Almond and cashew flours provide protein fortification and textural modification for gluten-free bread, pastry, and cookie formulations. German and French manufacturers are demanding certified fat content ranges with batch-level certificates of analysis.
- Snacks:Whole nut inclusion in bars and trail mixes requires roasted flavor development without thermal degradation of protein functionality. Clean-label positioning drives procurement toward processors with origination-level traceability systems.
- Confectionery:Nut pastes and pralines face margin compression under cocoa butter price volatility, destabilizing contract structures for suppliers.
- Breakfast Cereals:Granola and muesli applications offer predictable volume commitments and longer planning horizons compared to confectionery procurement.
Baking commands the dominant volume position; snack applications are climbing the fastest as clean-label positioning accelerates.
End User:
Procurement sophistication tiers separate industrial-scale manufacturers from fragmented foodservice operators.
- Food Manufacturers:Formulated food producers deploy specification-driven contracts with technical staffing to audit supplier quality systems. FDA aflatoxin action levels and EU REACH mycotoxin thresholds force redundant testing protocols.
- Bakeries:Artisan and industrial bakeries rotate procurement toward almond and cashew flours as primary demand archetypes for dough conditioning applications.
- Restaurants:Foodservice operators prioritize cost-stable supply over specification precision for menu ingredient incorporation.
- Retailers:Private-label snack and baking ingredient assortments demand clean-label positioning with visible supply chain transparency.
Food manufacturers represent the largest procurement volume; bakeries are gaining share fastest as plant-based bakery applications displace traditional channels.
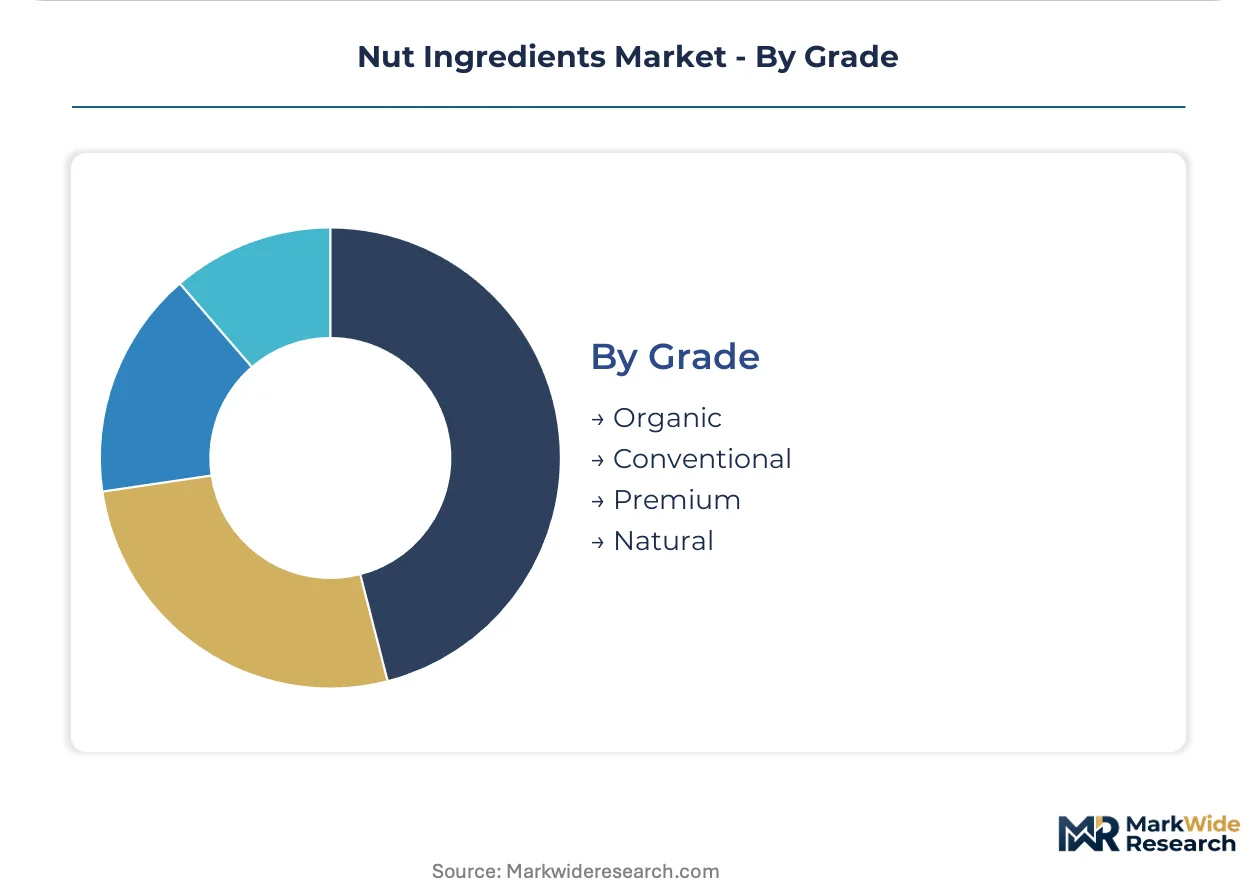
Grade:
Certification tier pricing stratifies across organic premium positioning, conventional commodity supply, and natural-label middle ground.
- Organic:Certified cultivation and processing command premium positioning in European and North American retail channels. EU Green Deal sustainability disclosure requirements create first-mover advantage for processors with documented origination traceability.
- Conventional:Standard agricultural practice supply serves cost-sensitive industrial applications with relaxed certification requirements.
- Premium:Superior size grading, flavor profiles, and defect tolerances target confectionery and gift nut applications.
- Natural:Minimal processing claims bridge clean-label positioning without full organic certification cost structures.
Conventional grade holds the largest share; organic certification is expanding most quickly under tightening EU regulatory disclosure mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Europe's dominance in nut ingredient import processing, while California's Central Valley irrigation networks anchor North American almond supply security.
Germany
Bavarian snack manufacturers in Munich and Augsburg are scaling multi-year procurement contracts for almond flours. EU REACH mycotoxin thresholds force redundant testing protocols on all inbound shipments. The Baden-Württemberg cluster around Stuttgart concentrates clean-label bakery innovation.
United States
California's San Joaquin Valley orchards supply 80% of global almond ingredient volumes through captive processing infrastructure. FDA aflatoxin action levels mandate pre-shipment ELISA documentation for interstate commerce. Modesto and Sacramento processing hubs dominate vertical orchard-to-ingredient production.
Spain
Catalonian processors in Tarragona and Lleida are expanding cold-pressed oil capacity for European functional food channels. EFSA standards on aflatoxin B1 restrict supplier eligibility to integrated origination processors. Valencia's port infrastructure handles Mediterranean transit for North African cashew supply.
India
Gujarat's Kutch district processors are scaling cashew butter output for Middle Eastern confectionery export. FSSAI allergen labeling mandates require reformulation documentation for packaged nut products. The Mumbai-Pune corridor concentrates technical staffing for supplier quality audits.
France
Île-de-France formulated food manufacturers are demanding certified fat content ranges with batch-level certificates of analysis. ANSM specifications on processing facility hygiene drive consolidation toward HPP-equipped suppliers. Lyon-based industrial bakeries anchor procurement for gluten-free pastry channels.
Nut Ingredients Market Vendor Landscape
Listed leaders compete with private specialists across origination control and processing technology dimensions. The vendor base separates into three tiers: integrated agricultural conglomerates with captive orchard assets, mid-scale processors with specification-driven milling capabilities, and regional traders serving cost-sensitive foodservice channels. Dominant competitive moves include backward integration into orchard ownership and strategic partnerships with cold-chain logistics providers.
Within the integrated agricultural tier, Olam Food Ingredients and Blue Diamond Growers exemplify origination-to-processing control architectures. Barry Callebaut AG occupies a position among confectionery-grade specialists. Archer Daniels Midland Company represents the diversified commodity processor archetype with multi-origin sourcing networks.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Olam Food Ingredients |
| Barry Callebaut AG |
| Blue Diamond Growers |
| John B. Sanfilippo & Son Inc. |
| Kanegrade Limited |
| The Wonderful Company LLC |
| Royal Nut Company |
| Borges Agricultural & Industrial Nuts |
| Others |
Supply Flow & Price Mechanics
Almond flour substitution for wheat-based alternatives in Bavarian clean-label bakeries simultaneously shifts procurement geography toward California's Central Valley orchards and compresses margin structures for European traders lacking origination-level control. This input displacement forces price discovery mechanisms to absorb trans-Pacific logistics premiums and FDA-mandated aflatoxin testing overhead.
Pricing Analysis
Volume-discount tiering structures dominate contract negotiations between German snack manufacturers and specialty nut butter suppliers. Pricing stratifies across organic certification premiums, EU REACH compliance documentation tiers, and particle size precision grades below 50 microns. Cost compression in conventional almond paste categories is intensifying because Blue Diamond Growers' captive orchard-to-processing control limits competitive sourcing alternatives. Industrial-scale food manufacturers exhibit lowest price sensitivity due to multi-year volume commitments, while fragmented foodservice operators drive spot-market volatility.
Supply Chain Analysis
Strait of Gibraltar transit underwrites Mediterranean cashew flows from West African origination points into Valencia's port infrastructure. Supply concentration in California, Spain, and Vietnam draws from orchard cultivation cycles, cold-pressed extraction equipment, and ELISA testing laboratory networks. Single-source vulnerability concentrates in California's San Joaquin Valley irrigation-dependent almond production. Distribution runs through Rotterdam's cold-chain hubs into Bavarian and Baden-Württemberg processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where HPP-treated paste stabilization contracts and batch-level certificate of analysis subscriptions expand faster than commodity nut ingredient hardware. Recurring technical auditing and compliance documentation layers now outpace raw volume growth in supplier margin structures.
For Market Incumbents: Consolidate backward integration into West African cashew origination networks before EU Green Deal traceability mandates harden supplier eligibility criteria. Capture cold-chain logistics partnerships serving Rotterdam-to-Stuttgart corridors to defend against specialty millers with specification-driven quality systems. Lock in multi-year procurement contracts with Île-de-France formulated food manufacturers before HPP equipment financing costs escalate. For New Entrants and Emerging Players: EU REACH pre-certification fast-tracks open procurement channels for Bavarian clean-label snack producers seeking redundant aflatoxin testing documentation. White-space concentrates in cold-pressed almond oil tocopherol retention above 200 ppm for French functional food channels. Target Lyon-based industrial bakeries with certified fat content range guarantees and batch-level digital traceability dashboards. For Investors and Strategic Acquirers: EFSA mycotoxin threshold reductions reshape the acquisition landscape toward integrated origination processors with in-house ELISA capabilities and documented orchard traceability. Long-term viability favors vertically controlled agricultural assets over trading-dependent intermediaries. Watch for Health Canada allergen labeling mandate finalization as signal for packaging redesign cycle demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Assets | Captive almond supply from California's Central Valley insulates against price volatility from dominant growers. |
| HPP Equipment Deployment | Cold-chain pasteurization adoption fragments traditional roasting line markets across German bakery supply chains. |
| EU REACH Compliance Certification | Pre-shipment testing documentation unlocks procurement eligibility with Bavarian multi-year contract manufacturers. |
| Traceability System Implementation | Origination-level digital tracking creates first-mover positioning under emerging EU Green Deal disclosure mandates. |
| Specialty Milling Capacity Expansion | Sub-50 micron particle precision captures specification-driven contracts from French gluten-free pastry channels. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA enforcement actions, EFSA scientific opinions, EU REACH substance databases, and California agricultural commission reports. Interviews with almond processor operations directors, German snack manufacturer procurement leads, Spanish cold-pressed oil technical directors, and Rotterdam cold-chain logistics operators were triangulated against customs trade data and food industry association filings. Bottom-up volume estimates from individual facility capacities were cross-checked against top-down market sizing from downstream application demand.
Segmentation dimensions modeled include product type hierarchy, application volatility tiers, end-user procurement sophistication levels, and certification grade stratification across the projection horizon. CAGRs were derived from trend extrapolation of bakery displacement patterns and regulatory compliance cost trajectories. Forecast inputs incorporated EU mycotoxin standard evolution timelines and California irrigation supply reliability assumptions.
Decision-makers should treat outputs as directional under sustained almond flour substitution momentum and stable FDA aflatoxin enforcement intensity; material deviation in cocoa butter price volatility or REACH threshold revisions would warrant model refresh. Practitioners should keep alternative scenarios live as EFSA scientific committee deliberations and Health Canada labeling mandate finalizations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Breadnut Market
Nuts and Seeds
Hazelnut Market
Nuts and Seeds
Almond with Shell Snack Market
Nuts and Seeds
Almond Products Market
Nuts and Seeds
Horse Chestnut Seed Extract Market
Nuts and Seeds
Nuts and Nutmeals Market
Nuts and Seeds
Europe Cashew Market
Nuts and Seeds
Nutmeg Market
Nuts and Seeds
Rubus Fructicosus (Blackberry) Seed Market
Nuts and Seeds
Saudi Arabia Nuts Market
Nuts and Seeds
Pistachios Market
Nuts and Seeds
Low Fat Nut Butter Market
Nuts and Seeds
Nut Butters Market
Nuts and Seeds
Edible Peanut Powder Market
Nuts and Seeds
Nut Based Spread Market
Nuts and Seeds
Walnut Oil Market