
 Breadnut Market | 2026-2036
Breadnut Market Size, Share, and Industry Trends Forecast 2026-2036
Breadnut Market Outlook
Small-scale milling technology is fragmenting traditional breadnut processing, enabling decentralized flour production closer to Caribbean source farms. Natural Caribbean Foods leverages island-wide farmer networks to secure raw supply. Organic Island Mills sustains premium positioning through certified organic channels. Caribbean Flour Mills competes on volume, supplying industrial bakeries across the Greater Antilles.
Breadnut refers to the seeded fruit of Brosimum alicastrum, a tropical tree whose starchy seeds contain approximately 40 percent carbohydrates and notable protein content when dried and milled. The seed requires boiling or roasting to eliminate latex compounds before commercial use in flour, oil extraction, or whole-food applications. Fresh breadnut dominates household consumption in producing regions, while breadnut flour captures the fastest expansion as gluten-free alternatives displace wheat in specialty baking. Breadnut oil occupies a narrow premium niche, constrained by low extraction yields and limited cold-press capacity.
Jamaica's Bureau of Standards enforces food safety labeling for breadnut derivatives under national processed food regulations. The FDA oversees import clearance for Caribbean breadnut products entering US retail channels, requiring hazard analysis and preventive controls compliance. Stakeholders must monitor evolving allergen classification debates, as breadnut's botanical proximity to mulberry family species triggers periodic regulatory review in major import jurisdictions.
Market Dynamics
Small-scale milling technology is fragmenting traditional breadnut processing, enabling decentralized flour production closer to Caribbean source farms. This structural shift redistributes value capture from centralized processors to farm-gate entrepreneurs and regional cooperatives.
Growth Catalysts
- Gluten-free bakery expansion:Specialty bakeries across North America and Europe are reformulating product lines with breadnut flour to capture celiac and clean-label consumer segments.
- Jamaica Bureau of Standards labeling protocols:Codified food safety frameworks for breadnut derivatives are accelerating formal channel development and export readiness.
- Caribbean agricultural export standards:Tightening quality protocols are differentiating compliant suppliers and creating entry barriers for informal producers.
Market Restraints
- Input cost volatility:Fresh breadnut spoilage rates and seasonal harvest fluctuations create raw material price instability for processors.
- Supply concentration risk:Processing hub dependence on Jamaica and the Dominican Republic concentrates geographic exposure to climate and logistics disruptions.
- Low oil extraction yields:Breadnut oil production remains constrained by technical limitations in cold-press capacity and recovery rates.
Strategic Opportunities
- Underpenetrated US retail channels:FDA import clearance pathways for Caribbean breadnut products remain underutilized relative to established tropical commodity flows.
- Organic certification premiums:Certified organic breadnut flour commands price differentiation in European and North American specialty food segments.
- Farmer network digitization:Island-wide coordination platforms are emerging to aggregate smallholder supply and standardize quality at source.
Industry Challenges
- Allergen classification uncertainty:Breadnut's botanical proximity to mulberry family species triggers periodic regulatory review in major import jurisdictions, creating compliance timeline risk.
- Legacy latex compound processing:Boiling and roasting requirements for seed detoxification demand capital-intensive equipment that constrains micro-processor scaling.
- Skill gaps in decentralized milling:Technical expertise for small-scale flour quality control remains scarce outside established processing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breadnut Market |
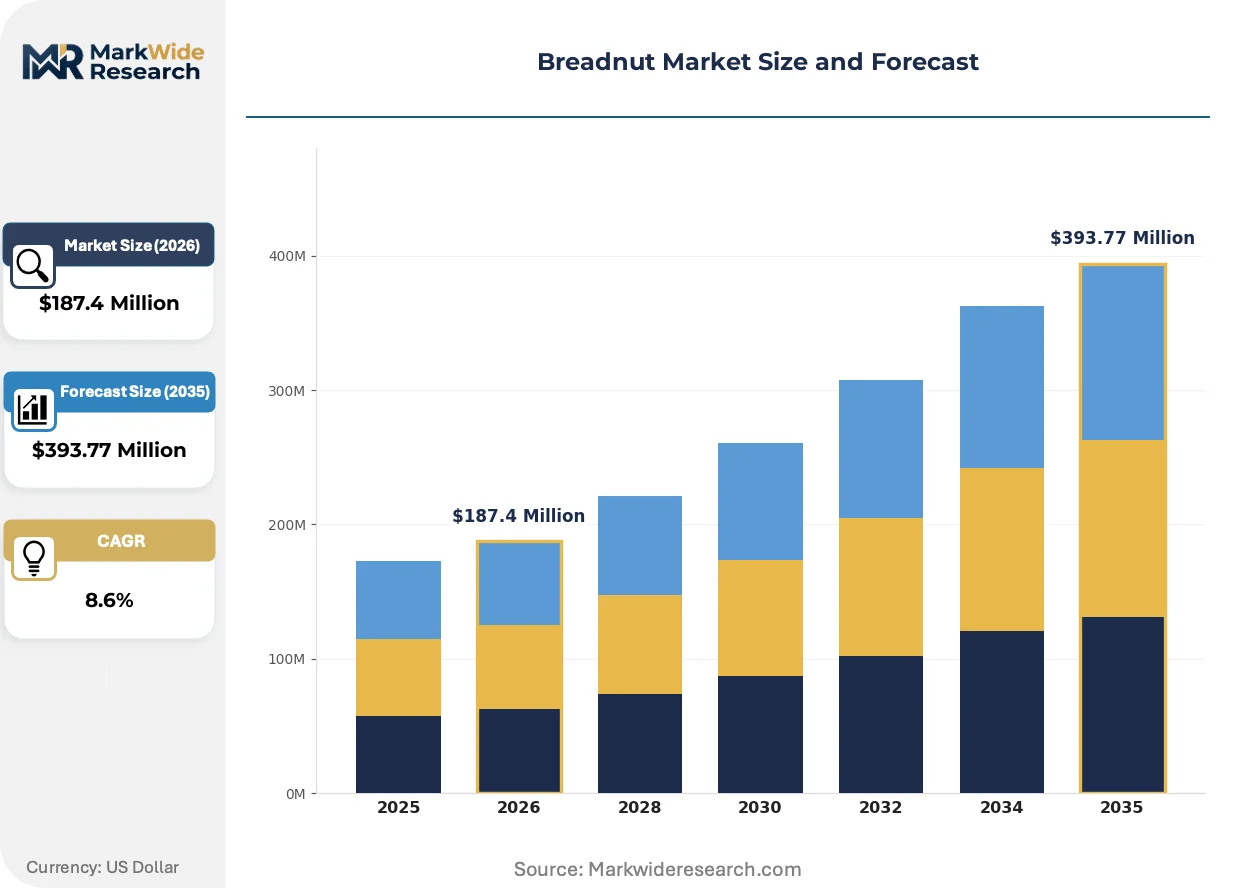
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Breadnut, Dried Breadnut, Breadnut Flour, Breadnut Oil End User: Households, Food Manufacturers, Restaurants, Health Food Stores Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Farmers Markets Application: Snack Foods, Meal Ingredients, Baking, Natural Remedies |
| Companies Covered | Natural Caribbean Foods, Organic Island Mills, Caribbean Flour Mills, Sustainable Island Products, Pure Tropical Flour, Tropical Flour Co., Breadnut Innovations, Premium Caribbean Ingredients, Island Products Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breadnut Market Strategic Shifts
Technology adoption and regulatory codification are converging to professionalize a historically informal supply chain. These developments are compressing the gap between farm-gate production and formal export channels.
Solar-powered micro-milling units are digitizing quality control protocols for small-batch breadnut flour. Caribbean cooperatives are deploying these systems to track moisture content, particle size, and contamination risk in real time. The technology is digitizing traceability documentation that export buyers require for hazard analysis compliance.
The FDA's hazard analysis and preventive controls framework is reshaping import clearance procedures for Caribbean breadnut derivatives. US retail channel entry now demands documented supply chain controls that informal exporters struggle to satisfy. Breadnut flour shipments are most affected, with compliant suppliers gaining preferential shelf placement in specialty grocery.
Direct procurement from farmer networks is replacing traditional commodity broker intermediation. Natural Caribbean Foods and similar aggregators are building island-wide supply relationships that bypass legacy export houses. Jamaica and the Dominican Republic exhibit the most advanced network development, with processing hubs contracting harvest volumes pre-season.
Breadnut Market Segmentation
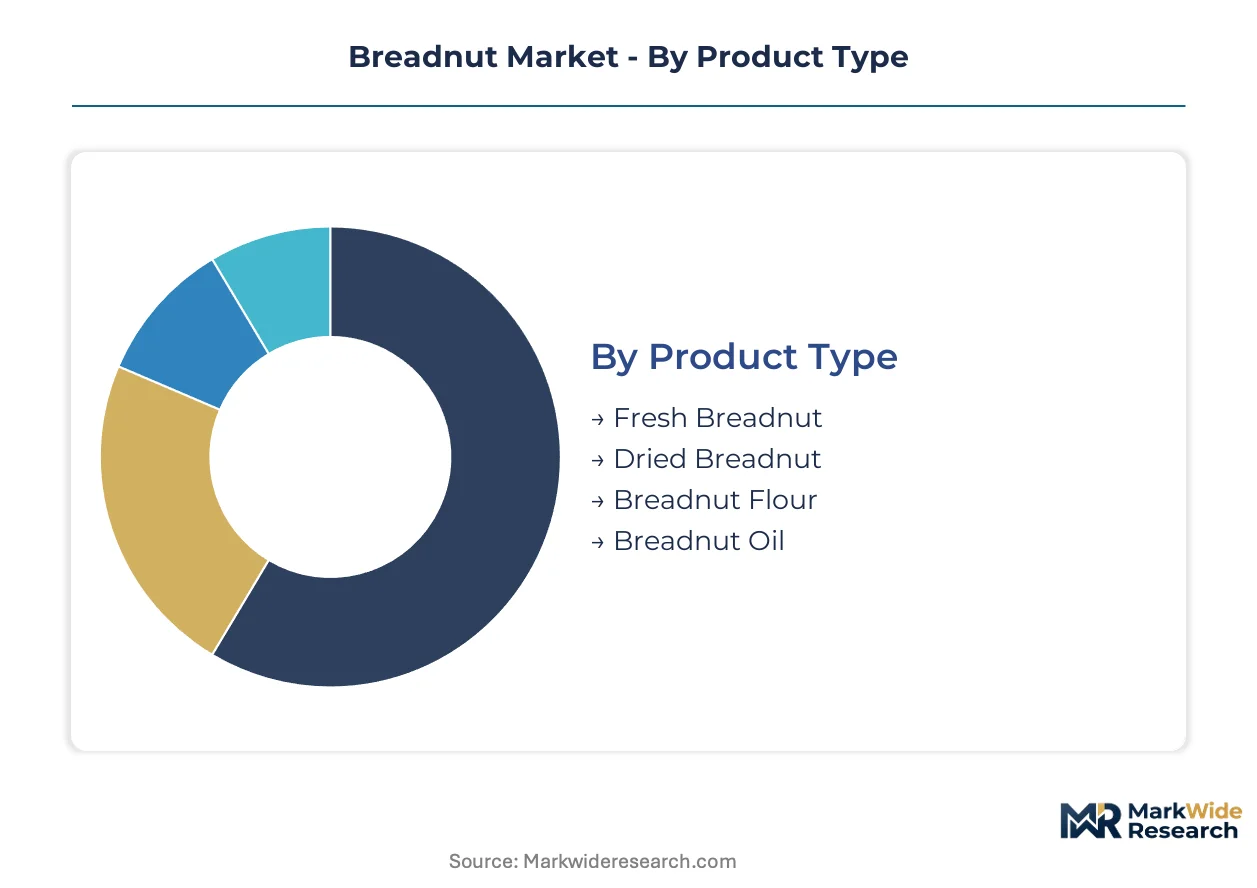
Breadnut market segmentation reveals how processing intensity and distribution sophistication determine value capture. Each category maps distinct pathways from Caribbean farm-gate to end-consumers across North America and Europe.
Product Type:
The use-case spectrum spans raw household consumption to industrial ingredient transformation, with processing depth directly correlating to export eligibility and margin structure.
- Fresh Breadnut:Unprocessed seeded fruit retains latex compounds requiring immediate boiling or roasting. Households across Jamaica and the Dominican Republic dominate demand, constrained by perishability and limited cold-chain reach into formal retail.
- Breadnut Flour:Milled from dried seeds containing approximately 40 percent carbohydrates, this gluten-free alternative is displacing wheat in specialty bakeries across North America. Celiac and clean-label consumer segments drive the steepest expansion trajectory.
- Dried Breadnut:Shelf-stable whole seeds serve regional food manufacturers seeking intermediate processing inputs. Seasonal harvest fluctuations create price volatility for processors dependent on this raw form.
- Breadnut Oil:Cold-pressed extraction yields remain technically constrained, limiting output to premium niche applications in natural cosmetics and high-end culinary segments.
The dominant share belongs to Fresh Breadnut, while Breadnut Flour is closing the gap fastest.
End User:
Customer sophistication tiers separate commodity bulk buyers from premium-channel specialists willing to pay for certified organic provenance.
- Food Manufacturers:Industrial bakeries across the Greater Antilles reformulate product lines with breadnut flour to capture gluten-free market share. FDA hazard analysis compliance requirements favor suppliers with documented supply chain controls.
- Households:Traditional consumers in producing regions consume fresh breadnut as a starchy staple, with preparation methods passed through generational knowledge rather than formal retail channels.
- Health Food Stores:North American specialty retailers curate certified organic breadnut flour for celiac and paleo diet adherents, commanding price premiums through traceability storytelling.
- Restaurants:Caribbean diaspora eateries and farm-to-table establishments in urban US markets incorporate breadnut into heritage cuisine and experimental tasting menus.
Food Manufacturers capture the highest volume throughput, whereas Health Food Stores deliver the strongest margin per kilogram.
Distribution Channel:
Channel selection determines regulatory exposure, with formal retail requiring Jamaica Bureau of Standards labeling compliance that informal pathways bypass.
- Specialty Stores:Curated independent grocers in Brooklyn, Toronto, and London stock breadnut flour for Caribbean diaspora communities and health-conscious experimenters alike.
- Supermarkets:Mainstream retail placement remains sparse outside ethnic food aisles, though gluten-free certification is unlocking shelf space in conventional grocery.
- Online Retail:Direct-to-consumer platforms enable island-based processors to reach North American buyers without intermediary markups, though FDA import documentation requirements filter out informal suppliers.
- Farmers Markets:Hyperlocal Caribbean sales of fresh breadnut sustain traditional consumption patterns with minimal regulatory overhead.
Specialty Stores anchor current revenue, yet Online Retail is expanding most quickly as digitized farmer networks streamline export logistics.
Application:
Functional use cases range from caloric subsistence to wellness positioning, with application innovation driving premiumization.
- Baking:Breadnut flour substitution in gluten-free bread, pastry, and pasta formulations represents the primary industrial demand driver, with specialty bakeries across North America and Europe leading adoption.
- Meal Ingredients:Boiled or roasted whole seeds serve as carbohydrate staples in traditional Caribbean cooking, with minimal processing preserving nutritional integrity.
- Snack Foods:Roasted breadnut seeds packaged for convenience consumption target health-conscious urban consumers seeking alternatives to processed grain snacks.
- Natural Remedies:Folk medicinal applications in producing regions claim digestive and anti-inflammatory properties, though clinical validation remains limited and regulatory classification uncertain.
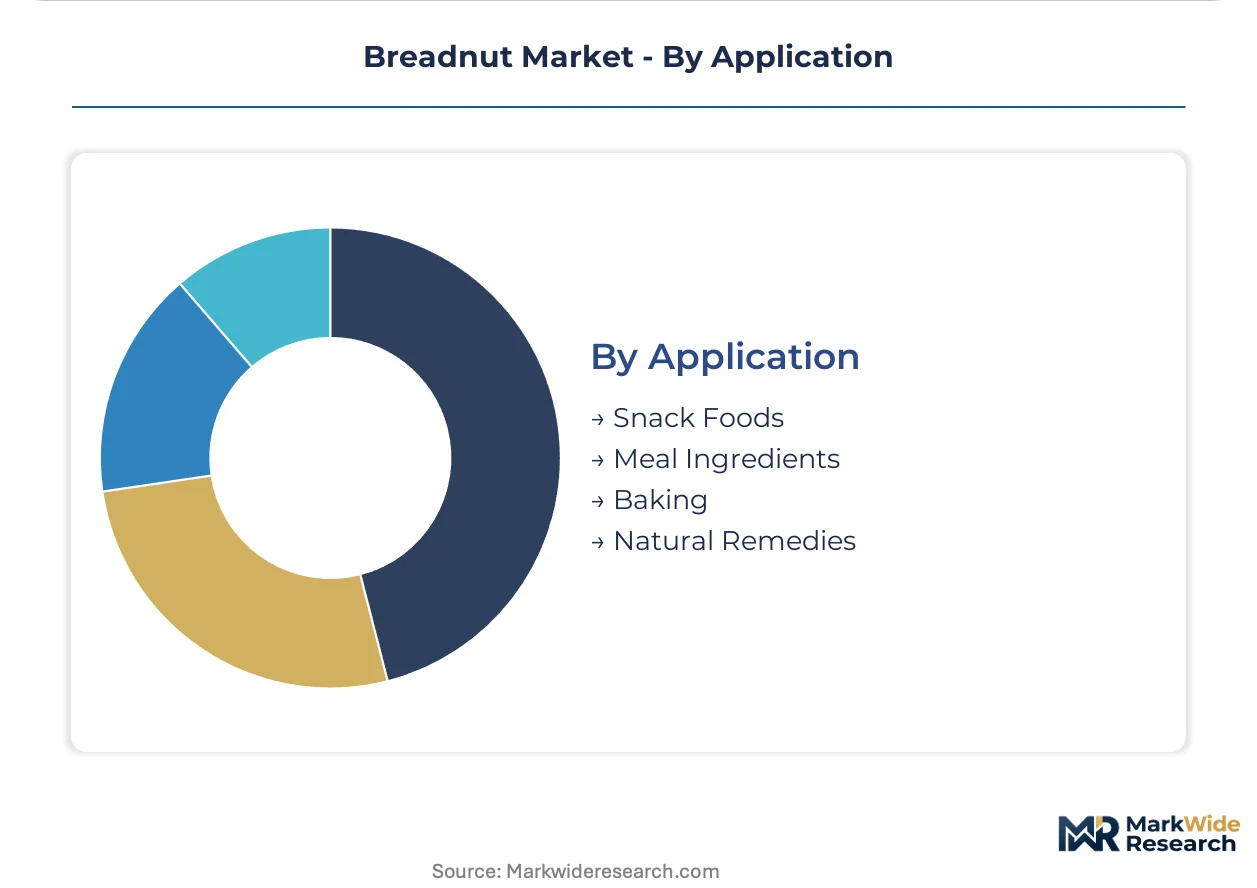
Baking commands the largest addressable market, while Snack Foods is gaining share fastest through convenience-oriented product development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gluten-free bakery buyers concentrate in North American and European metropolitan markets, while Caribbean processing infrastructure clusters around specific island economies with established agricultural export frameworks.
Jamaica
Kingston-based processors supply breadnut flour to specialty bakeries in Brooklyn and Toronto. The Jamaica Bureau of Standards enforces processed food labeling protocols that accelerate formal channel development. St. Elizabeth Parish farming cooperatives deploy solar-powered micro-milling units to aggregate smallholder harvests.
Dominican Republic
Santo Domingo industrial bakeries reformulate product lines to capture celiac consumer segments in Miami and Madrid. The national food safety regulator applies Codex Alimentarius standards for export-ready derivative production. Cibao Valley processing hubs contract pre-season harvest volumes from mountain farming networks.
United States
New York and Florida health food stores curate certified organic breadnut flour for Caribbean diaspora communities. The FDA requires hazard analysis and preventive controls documentation for Caribbean import clearance. Brooklyn specialty grocers anchor shelf placement for compliant suppliers.
United Kingdom
London independent retailers stock breadnut derivatives for clean-label experimenters and heritage cuisine enthusiasts. The Food Standards Agency monitors allergen classification debates affecting mulberry family proximity concerns. Brixton market vendors source through direct island procurement platforms.
Canada
Toronto-area Caribbean restaurants incorporate breadnut into tasting menus and traditional preparations. Health Canada oversees import safety assessments for tropical commodity derivatives. Scarborough ethnic food distributors bridge island-based processors with metropolitan retail channels.
Breadnut Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented processing tiers. The vendor base distributes between centralized industrial mills and decentralized farm-gate micro-processors. Three archetypes dominate: island-wide network aggregators, certified organic premium-positioned specialists, and volume-focused industrial suppliers. Competitive moves concentrate on farmer network digitization and organic certification acquisition.
Among Caribbean-based network aggregators, Natural Caribbean Foods exemplifies island-wide supply coordination, while Organic Island Mills occupies a position within certified organic premium channels. Caribbean Flour Mills represents the volume-driven industrial tier supplying formal bakery customers across the Greater Antilles.
| Leading Market Players |
|---|
| Natural Caribbean Foods |
| Organic Island Mills |
| Caribbean Flour Mills |
| Sustainable Island Products |
| Pure Tropical Flour |
| Tropical Flour Co. |
| Breadnut Innovations |
| Premium Caribbean Ingredients |
| Island Products Ltd. |
| Others |
Value Chain & Pricing Dynamics
Kingston-to-Miami freight corridors carry the majority of Caribbean breadnut flour exports, with container cost dynamics amplifying price differentiation between certified organic and conventional grades while compressing margins for informal suppliers lacking volume scale.
Pricing Analysis
Cost-plus contracts indexed to fresh breadnut spot prices in Jamaican and Dominican wholesale markets dominate processor-buyer agreements. Three-tier pricing structure across premium organic, standard commercial, and economy bulk levels separates certified suppliers from commodity traders. Pricing pressure stems from seasonal harvest volatility and rising cold-chain logistics costs. Food manufacturers exhibit highest price sensitivity due to reformulation volume requirements, while health food stores absorb premiums for traceability documentation.
Supply Chain Analysis
Extended payment terms from Kingston and Santo Domingo processors to St. Elizabeth and Cibao Valley farmer networks anchor working capital flows across the procurement tier. Supply concentrates in Jamaica, the Dominican Republic, and Haiti as source origins, with processing capacity clustering around Kingston and Santo Domingo. Raw material dependencies center on fresh breadnut harvests, diesel for off-grid milling units, and food-grade packaging for export eligibility. Single-source vulnerability runs through the Kingston-Miami shipping lane. Distribution runs through specialty grocers in Brooklyn, Toronto, and London, with online retail expanding fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified organic breadnut flour represents a service-attach opportunity, with traceability-as-a-service and farmer network digitization expanding faster than commodity flour sales alone.
For Market Incumbents: Harden supply security through backward integration into pre-season harvest contracting with St. Elizabeth and Cibao Valley cooperatives. Accelerate Jamaica Bureau of Standards and FDA hazard analysis compliance investments to widen the gap from informal competitors facing import documentation barriers. For New Entrants and Emerging Players: Mid-scale gluten-free bakeries in the US Southeast and Pacific Northwest represent the most penetrable entry point, with direct-to-procurement-manager outreach bypassing established distributor markups. Target certified organic positioning to capture price premiums unavailable to commodity entrants. For Investors and Strategic Acquirers: Island-wide network aggregators with digitized farmer relationships and existing organic certification infrastructure offer the strongest long-term viability profile across a 5-10 year holding window. Monitor FDA allergen classification rulings on mulberry family proximity as the critical regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Farmer Network Digitization | St. Elizabeth cooperatives deploy solar-powered micro-mills with real-time quality tracking for export compliance. |
| Organic Certification Acquisition | Jamaica Bureau of Standards protocols favor pre-certified suppliers in Brooklyn and Toronto specialty retail placement. |
| Backward Integration into Harvest Contracting | Pre-season volume agreements with Cibao Valley farming networks secure raw material priority during seasonal shortages. |
| Direct-to-Consumer Online Retail Launch | Island-based processors bypass legacy export house markups to reach celiac and paleo diet adherents directly. |
| Regulatory Compliance Infrastructure Investment | FDA hazard analysis documentation unlocks preferential shelf positioning in US specialty grocery channels. |
Study Parameters
Operator-level perspectives from breadnut flour procurement managers at North American specialty bakeries, Jamaica Bureau of Standards compliance officers, St. Elizabeth cooperative milling technicians, and Brooklyn ethnic grocery category buyers anchored the qualitative base. Secondary validation drew from FDA import clearance documentation, Jamaica processed food labeling regulations, Caribbean agricultural export trade data, and specialty food retail audit records. Bottom-up farmer network sizing and top-down gluten-free ingredient market triangulation cross-checked volume estimates.
Scenario-bracketing around harvest yield volatility and regulatory timeline uncertainty framed the projection methodology across the analysis window. Segmentation modeling incorporated product type, end-user sophistication tier, distribution channel formality, and geographic regulatory cluster. CAGRs derived from anchored base-year sizing and year-by-year growth step-downs reflecting market maturation. Industry-specific inputs included seasonal spoilage rates and cold-press oil extraction yield constraints.
Macroeconomic conditions sit as an overlay; deviation in Caribbean diesel costs, container shipping rates, or US specialty food consumer discretionary spending would shift the trajectory. Forecasts reflect documented assumptions on farmer network expansion rates and regulatory clearance timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Reduced Fat Peanut Butter Market
Nuts and Seeds
United States Nuts Market
Nuts and Seeds
Spain Fox Nuts Market
Nuts and Seeds
Europe Tahini Market
Nuts and Seeds
Walnut Oil Market
Nuts and Seeds
Flax Seed Meal Market
Nuts and Seeds
Europe Cashew Market
Nuts and Seeds
Packaged Sunflower Seeds Market
Nuts and Seeds
Tree Nuts Market
Nuts and Seeds
Almond Market
Nuts and Seeds
Fox Nuts Market
Nuts and Seeds
Hazelnut Market
Nuts and Seeds
Nut Oil Market
Nuts and Seeds
Nut Products Market
Nuts and Seeds
Brazil Nuts Market
Nuts and Seeds
Saudi Arabia Nuts Market