
 Dry Fruits Market | 2026-2036
Dry Fruits Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Fruits Market Analysis
Food manufacturers is realigning procurement toward premium almond and walnut inputs for functional snack bars and plant-based dairy alternatives. Olam International leverages integrated sourcing networks across Australia and the Middle East to secure year-round supply continuity. Sun-Maid Growers anchors its position through controlled cooperative farming and direct retail shelf presence in North American grocery channels. Graceland Fruit specializes in infused and individually quick-frozen dried cherry platforms for industrial bakery accounts.
Dry fruits comprise dehydrated or desiccated whole fruits, kernels, and seeds with moisture content typically reduced below 20 percent through sun-drying, mechanical dehydration, or osmotic processing to extend shelf stability and concentrate caloric and micronutrient density for food manufacturing, retail snacking, and ingredient applications. Almonds and cashews within the product type category command the widest margin pools due to protein positioning and premium pricing in health food shops, while raisins sustain volume leadership through bakery and confectionery offtake. The distribution channel structure tilts toward supermarkets for mass-market penetration, though online stores are capturing the fastest growth trajectory among direct-to-consumer premium and gift-format assortments.
FDA food safety modernization rules and USDA organic certification requirements shape product standards and market access for suppliers targeting United States retail and food service accounts, while EFSA nutrition and health claims regulation governs permissible functional marketing for European distribution. India's FSSAI fortification and labeling mandates are tightening compliance thresholds for imported and domestically processed dried fruit SKUs. Stakeholders must monitor evolving dehydration energy standards and origin traceability protocols as procurement criteria harden across institutional buyers.
Market Dynamics
Snack food manufacturers are expanding procurement of dried fruit inclusions for clean-label product lines, while the EU Green Deal and F-Gas Regulation tighten energy standards for dehydration and cold storage infrastructure across supplier networks.
Growth Catalysts
- Clean-label bakery demand:Industrial bakery accounts are scaling purchases of infused dried cherries and raisins to replace artificial preservatives in formulation pipelines.
- EU F-Gas Regulation:Cold storage infrastructure upgrades are accelerating replacement cycles for energy-efficient dehydration equipment in processing facilities.
- India urban household expansion:Quick-service restaurant chains in Mumbai, Delhi, and Bangalore are scaling packaged raisin and cashew procurement for menu standardization.
Market Restraints
- Almond input cost volatility:California water allocation restrictions and drought cycles create pricing instability for premium nut suppliers.
- Middle East sourcing concentration:Iranian pistachio and Turkish apricot supply corridors face geopolitical transit friction and currency fluctuation exposure.
- Substitution threat from fresh fruit:Cold chain improvements in Southeast Asia enable fresh blueberry and cranberry displacement of dried alternatives in yogurt applications.
Strategic Opportunities
- India FSSAI fortification mandates:Micronutrient enrichment requirements for dried fruit SKUs create premium positioning for compliant importers and domestic processors.
- Plant-based dairy alternatives:Almond and cashew milk ingredient demand opens industrial volume contracts for kernel suppliers with pasteurization capabilities.
- Direct-to-consumer online channels:Gift-format assortments bypass supermarket slotting fees and capture margin through subscription and seasonal gifting platforms.
Industry Challenges
- USDA organic certification timelines:Three-year conversion periods for conventional orchards delay supply response to premium price signals.
- Dehydration energy standard compliance:EU Green Deal efficiency benchmarks require capex-heavy equipment retrofits for small and mid-scale processors.
- Traceability protocol fragmentation:Blockchain and paper-based origin verification systems create reconciliation friction across multi-tier supplier networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Fruits Market |
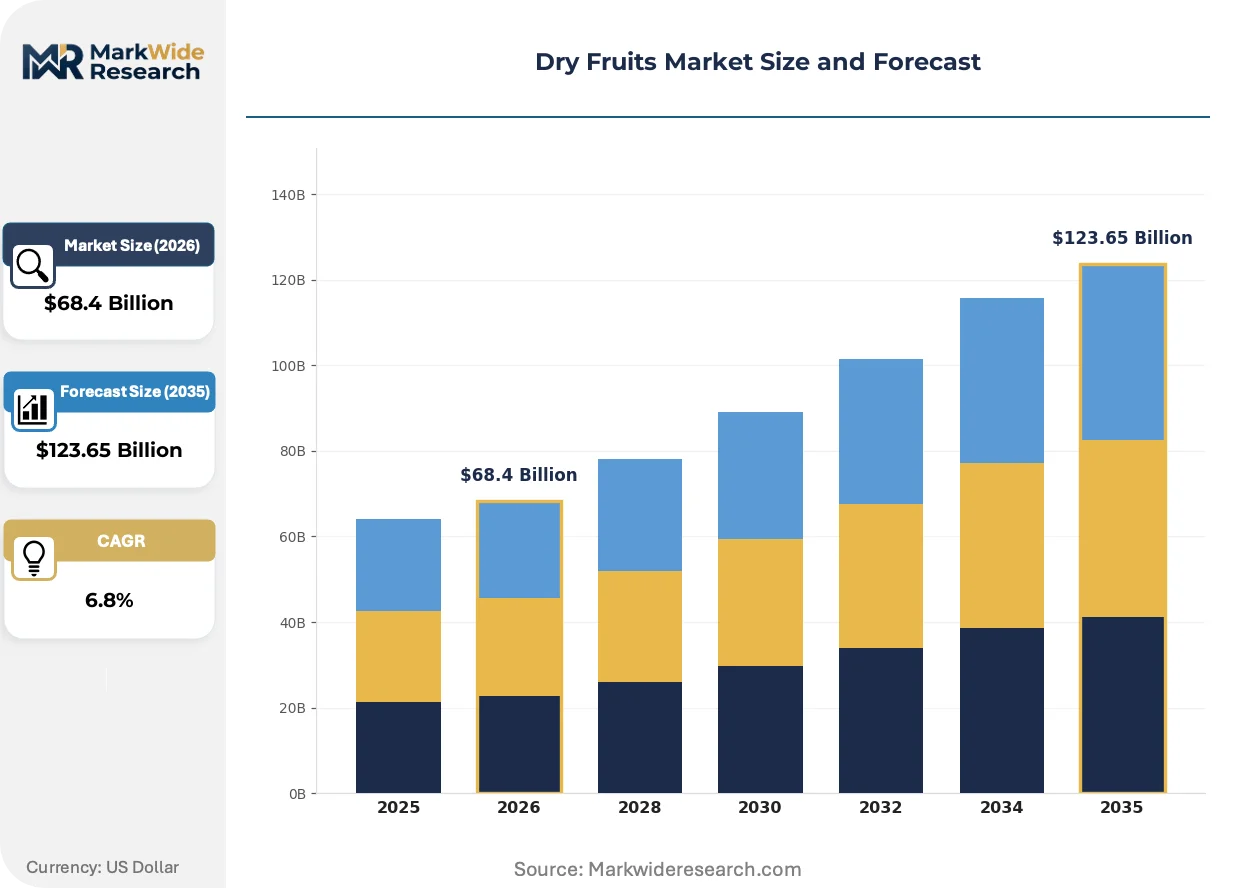
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almonds, Cashews, Walnuts, Raisins Packaging Type: Bags, Boxes, Jars, Pouches Distribution Channel: Supermarkets, Online Stores, Health Food Shops, Local Markets End User: Retail Consumers, Restaurants, Bakeries, Food Manufacturers |
| Companies Covered | Olam International, Sun-Maid Growers, Sunsweet Growers, Bergin Fruit and Nut Company, AL FOAH, Manassen Foods Australia Pty Ltd, Graceland Fruit, Angas Park Fruit Co., Agthia Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Fruits Market Emerging Trajectories
Processing technology and regulatory compliance are converging to reshape competitive positioning across dehydration, fortification, and distribution segments.
Smart dehydration systems with IoT-enabled moisture monitoring and automated temperature modulation are integrating into industrial processing lines. Mid-scale processors in Spain and Italy are adopting these platforms to reduce energy intensity and meet EU Green Deal benchmarks. The technology is integrating quality control and energy compliance into single workflow architectures, compressing capital payback periods.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in cold storage and transport refrigeration. Dried fruit warehouses in Germany and the Netherlands are retrofitting ammonia-based and transcritical CO2 systems to maintain temperature integrity. Almond and walnut storage facilities face the steepest compliance costs due to extended holding periods for premium grades.
Urban Indian households are rotating toward packaged formats over loose bulk purchases in traditional retail. Quick-service restaurant procurement teams are consolidating supplier bases to reduce origin variability in raisin and cashew specifications. This concentration is most visible in Mumbai and Bangalore, where chain bakery and cafe expansion outpaces traditional mithai shop growth.
Dry Fruits Market Segmentation
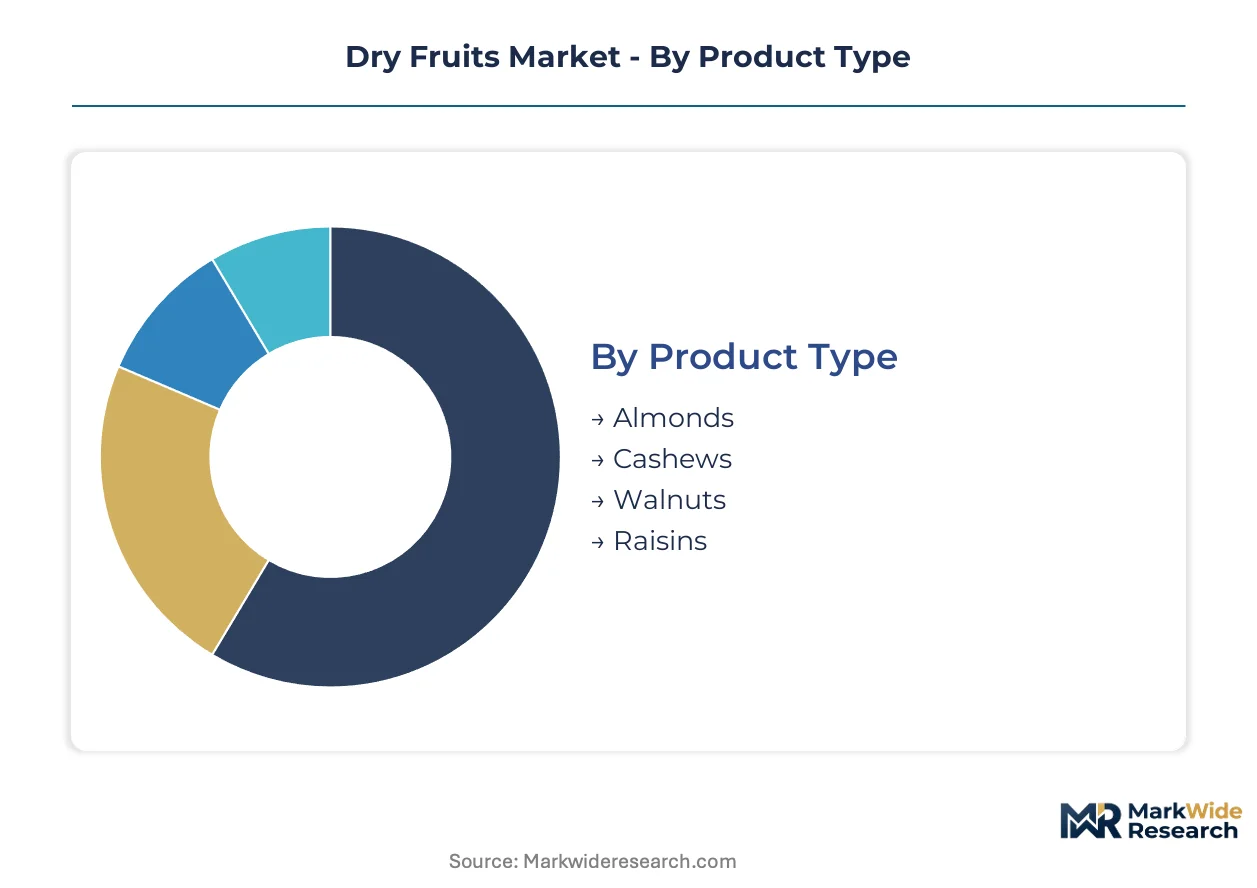
Segmentation in the dry fruits market reveals distinct procurement behaviors across buyer categories. Product specifications, packaging formats, and channel preferences create divergent margin structures that suppliers must navigate strategically.
Product Type:
Premium protein positioning separates health-focused buyers from commodity-driven accounts.
- Almonds:Kernels with protein density above 20% dominate functional snack bar formulations and plant-based dairy alternatives. California suppliers face water allocation constraints that tighten premium grade availability for health food shop channels.
- Cashews:Curved whole kernels with fat content near 47% anchor quick-service restaurant procurement in Mumbai and Bangalore for menu standardization. Indian urban households rotate toward packaged formats over loose bulk, concentrating demand in branded SKUs.
- Walnuts:Omega-3 positioning drives bakery and confectionery offtake in European industrial accounts.
- Raisins:Bakery and confectionery volume leadership sustains through industrial procurement pipelines.
Raisins lead volumes today; almonds are gaining share fastest.
Packaging Type:
Format selection tracks retail channel requirements and shelf-life demands.
- Bags:Flexible laminate structures with moisture barriers dominate supermarket mass-market penetration for everyday snacking occasions.
- Boxes:Rigid presentation formats capture gift-format assortments through direct-to-consumer online channels, bypassing slotting fees.
- Jars:Reclosable glass containers serve health food shop premium positioning with visible product quality.
- Pouches:Lightweight flexible formats align with quick-service restaurant back-of-house efficiency requirements for portion control.
Bags dominate current volume; pouches are expanding most quickly.
Distribution Channel:
Channel choice determines margin capture and customer relationship depth.
- Supermarkets:Mass-market penetration with slotting fee structures concentrates raisin and cashew volume through retail grocery networks.
- Online Stores:Direct-to-consumer premium and gift-format assortments capture fastest growth trajectory among subscription and seasonal gifting platforms.
- Health Food Shops:Premium almond and walnut positioning serves functional food consumers with clean-label requirements.
- Local Markets:Traditional loose bulk formats face displacement as urban Indian households rotate toward packaged alternatives.
Supermarkets anchor current volume; online stores show steepest expansion trajectory.
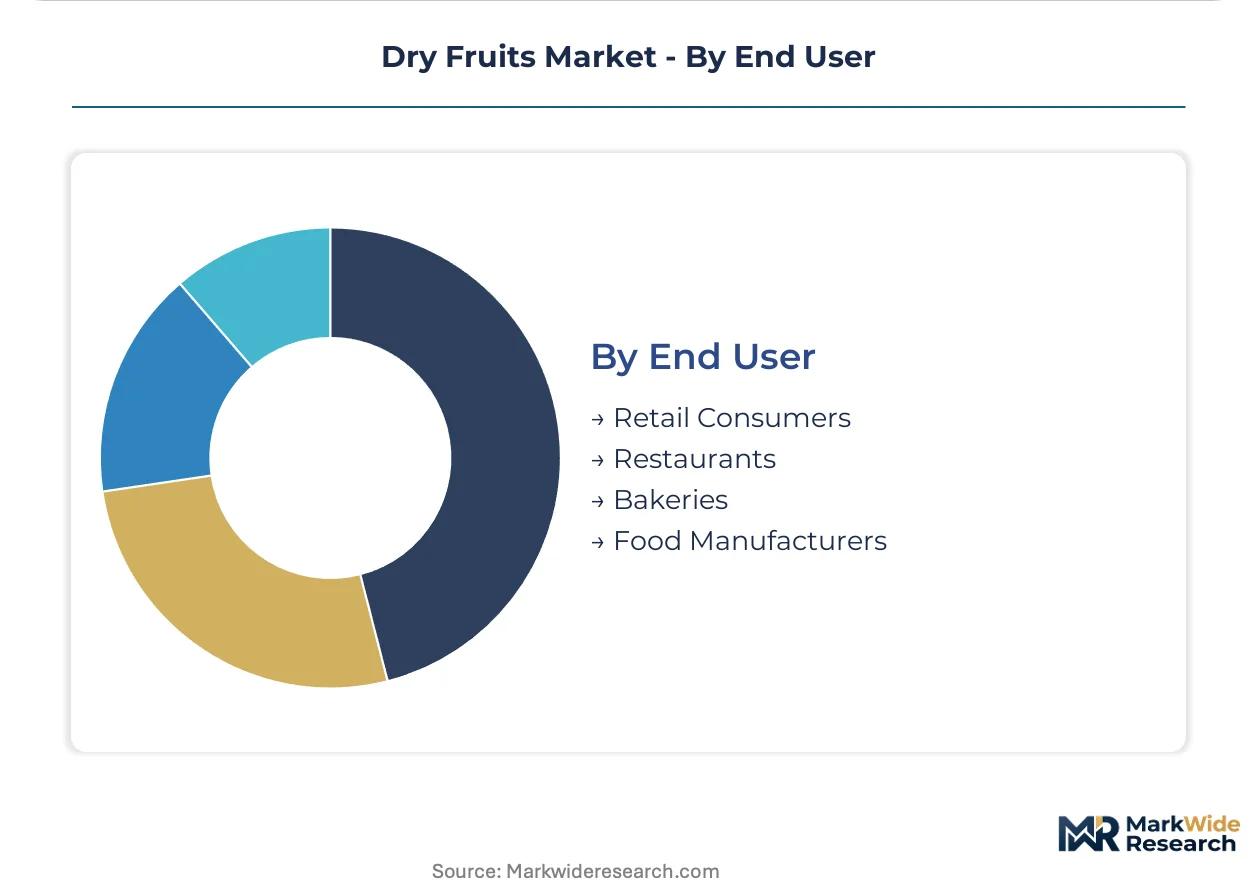
End User:
Application requirements drive specification granularity and supplier consolidation.
- Retail Consumers:Packaged format demand concentrates in urban Indian households seeking convenience and quality assurance over traditional loose bulk.
- Restaurants:Quick-service chains in Delhi and Mumbai standardize raisin and cashew specifications through consolidated supplier bases.
- Bakeries:Industrial accounts scale infused dried cherry and raisin procurement to replace artificial preservatives in clean-label pipelines.
- Food Manufacturers:Functional snack bar and plant-based dairy alternative producers realign procurement toward premium almond and walnut inputs.
Food manufacturers lead industrial volume; restaurants are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting dehydration capacity toward jurisdictions with lower energy compliance costs. The EU Green Deal and F-Gas Regulation have steepened operational expenses for European processors, while India's FSSAI fortification mandates and subsidized cold storage infrastructure attract sourcing migration. California water restrictions and Middle East transit friction compound this geographic rebalancing.
United States
California's Central Valley dominates almond kernel supply for functional snack bar and plant-based dairy ingredient contracts. FDA food safety modernization rules and USDA organic certification requirements shape compliance thresholds for retail and food service market access. Los Angeles and San Francisco Bay Area distribution clusters concentrate cold storage and reprocessing infrastructure for export-grade walnut and pistachio grades.
Germany
Industrial bakery accounts in Bavaria and North Rhine-Westphalia scale raisin and infused cherry procurement for clean-label formulation pipelines. EFSA nutrition and health claims regulation governs permissible functional marketing language for European distribution. Hamburg and Rotterdam-adjacent warehousing nodes retrofit ammonia-based refrigeration systems to meet EU F-Gas Regulation phase-down timelines for hydrofluorocarbon elimination.
India
Urban households in Mumbai, Delhi, and Bangalore rotate from loose bulk toward packaged raisin and cashew formats for convenience and quality assurance. FSSAI fortification and labeling mandates tighten compliance thresholds for imported and domestically processed dried fruit SKUs. Maharashtra and Gujarat processing corridors expand mechanical dehydration capacity to serve quick-service restaurant chain procurement consolidation.
Turkey
Aegean and Mediterranean growing regions anchor apricot and fig drying for European industrial bakery and confectionery offtake. Geopolitical transit friction through regional corridors creates currency fluctuation exposure for pistachio and dried fruit exporters. Izmir and Mersin port clusters concentrate grading, packaging, and cold storage infrastructure for Middle East and North African re-export flows.
Australia
Integrated sourcing networks across Riverina and Sunraysia districts secure year-round supply continuity for almond and sultana contracts. Energy efficiency benchmarks for dehydration equipment accelerate replacement cycles among mid-scale processors. Sydney and Melbourne distribution hubs coordinate direct retail shelf presence and industrial ingredient bulk shipments across Asia-Pacific channels.
Dry Fruits Market Vendor Landscape
Capacity expansion dominates the current landscape as dehydration infrastructure migrates toward lower-compliance-cost jurisdictions. The vendor base stratifies across integrated multinational traders, cooperative farming structures, and specialized industrial ingredient processors. Three archetypes define competitive positioning: scale-driven commodity handlers, premium-grade specialists with controlled origin networks, and technology-integrated mid-tier processors. M&A activity concentrates among Australian and Middle Eastern sourcing networks, while strategic partnerships link dehydration equipment vendors with energy compliance consultancies.
Among integrated sourcing specialists, Olam International and Sun-Maid Growers exemplify divergent structural approaches to supply security. Olam International occupies a position anchored across Australia and Middle East corridor networks, while Sun-Maid Growers represents cooperative-controlled farming with direct retail channel penetration. Graceland Fruit sits within the industrial ingredient specialization tier, serving bakery accounts with processing-format differentiation. These three entities collectively illustrate how scale, cooperative structure, and application-specific processing define competitive positioning in procurement consolidation environments.
| Leading Market Players |
|---|
| Olam International |
| Sun-Maid Growers |
| Sunsweet Growers |
| Bergin Fruit and Nut Company |
| AL FOAH |
| Manassen Foods Australia Pty Ltd |
| Graceland Fruit |
| Angas Park Fruit Co. |
| Agthia Group |
| Others |
Supply Flow & Price Mechanics
Quick-service restaurant procurement consolidation in Mumbai and Delhi anchors a contract-based long-term offtake model that compresses spot-market exposure for raisin and cashew suppliers. California almond handlers counter water allocation volatility with premium-grade pricing stratification that separates health food shop channels from industrial ingredient accounts.
Pricing Analysis
Retailer markup layers in European supermarket channels absorb EFSA compliance costs through shelf-positioning premiums for organic-certified SKUs. Three-tier pricing structure across premium, standard, and economy levels tracks moisture content thresholds and origin traceability depth. Cost compression in commodity raisin grades is intensifying because Indian FSSAI fortification mandates require micronutrient investment that erodes base-margin pools. Quick-service restaurant chains exhibit highest price sensitivity due to menu-cost rigidity, while health food shops accept premium positioning for protein-density certification.
Supply Chain Analysis
Regional distribution centers in Hamburg and Rotterdam-adjacent nodes retrofit ammonia-based refrigeration to maintain cold-chain integrity for walnut and pistachio grades. Geographic supply concentration centers on California for almonds, Turkey for apricots and figs, and India for cashew processing. Raw material dependencies draw from Iranian pistachio corridors, Australian sultana districts, and Middle Eastern date cultivation belts. Single-source vulnerability runs through California water-restricted acreage for premium almond grades. Distribution runs through cooperative-controlled farming structures with direct retail shelf presence in North American grocery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry fruit procurement is shifting toward premium protein positioning as food manufacturers reformulate functional snack bars and plant-based dairy alternatives, elevating specification granularity above commodity bulk purchasing.
For Market Incumbents: Cement supply security through backward integration into controlled origin networks across Australian and Middle East corridors. Invest in IoT-enabled dehydration equipment to compress EU Green Deal compliance payback periods. Olam International's integrated sourcing architecture demonstrates how geographic diversification neutralizes California water allocation volatility. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for gift-format assortments that bypass supermarket slotting fees. Target urban Indian households rotating from loose bulk toward packaged convenience formats. Anchor initial positioning through FSSAI-compliant micronutrient fortification that commands premium shelf positioning. For Investors and Strategic Acquirers: Food manufacturers with plant-based dairy alternative pipelines are the most active acquirer in this space, seeking kernel suppliers with pasteurization capabilities. Mid-scale dehydration processors with energy-efficient equipment retrofits represent the target archetype. Monitor California water tribunal rulings as the inflection indicator for almond input cost volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled Origin Networks | Australian and Middle East corridor access secures year-round supply continuity against drought cycles. |
| IoT-Enabled Dehydration Equipment Deployment | Smart moisture monitoring reduces energy intensity to meet EU Green Deal efficiency benchmarks. |
| FSSAI Fortification Compliance Investment | Micronutrient enrichment mandates create premium positioning for imported and domestic dried fruit SKUs. |
| Direct-to-Consumer Online Channel Launch | Subscription and seasonal gifting platforms capture margin through bypassed supermarket slotting fees. |
| Cold Storage Infrastructure Retrofit | Ammonia-based and transcritical CO2 systems maintain temperature integrity under EU F-Gas Regulation phase-down. |
Methodological Framework
Multiple input streams — primary interviews with dehydration equipment vendors and food manufacturer procurement leads, secondary validation through customs records and FSSAI filing databases, and trade flow analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder roles engaged included cooperative farming managers, quick-service restaurant supply chain directors, cold storage facility operators, and EFSA regulatory affairs consultants. Secondary sources encompassed EU Green Deal implementation documents, USDA organic certification registries, and India DGFT import-export statistics.
Cross-referencing historical shipment patterns against panel input from procurement executives anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, packaging format, distribution channel, and end-user application with regional regulatory cluster overlays. CAGRs were derived from reconciling volume trajectories with value-chain margin compression indicators. Industry-specific forecast inputs incorporated California water allocation tribunal projections and EU F-Gas Regulation equipment replacement cycle assumptions.
The model assumes a particular technology adoption path for smart dehydration systems; alternative pathways for conventional sun-drying expansion would alter the outlook for energy compliance cost structures. Forecasts reflect assumptions about FSSAI enforcement intensity and California drought recurrence frequency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Seed Butter Market
Nuts and Seeds
Apricot Kernel Market
Nuts and Seeds
Global Almond Powder Market
Nuts and Seeds
Rubus Fructicosus (Blackberry) Seed Market
Nuts and Seeds
United States Nuts Market
Nuts and Seeds
Saudi Arabia Nuts Market
Nuts and Seeds
Peanuts Market
Nuts and Seeds
Soy Nut Market
Nuts and Seeds
Walnut Oil Market
Nuts and Seeds
Nuts Market
Nuts and Seeds
Horse Chestnut Seed Extract Market
Nuts and Seeds
Nut Oil Market
Nuts and Seeds
Spain Fox Nuts Market
Nuts and Seeds
Germany Cashew Market
Nuts and Seeds
Breadnut Market
Nuts and Seeds
Processed Walnuts Market