
 Walnut Market | 2026-2036
Walnut Market Size, Share, and Industry Trends Forecast 2026-2036
Walnut Market Intelligence
Expertise in precision irrigation and integrated pest management is rotating from traditional farm management towards data-driven agronomy specialists. This shift impacts operational efficiency for major producers. Olam Group leverages its extensive global sourcing network to manage supply chain volatility. Diamond Foods, Inc. differentiates through strong brand recognition in the consumer snacking category, while Borges International Group specializes in value-added products for the European food manufacturing sector.
Walnuts are the edible seeds of trees from the Juglans genus, prized for their high concentration of alpha-linolenic acid (ALA), a vital omega-3 fatty acid. Their primary commercial purpose is as a nutrient-dense food ingredient. The market's value is heavily weighted towards shelled walnuts, which offer convenience for food manufacturers and bakery applications. While snacking remains a dominant application, ingredients for plant-based dairy alternatives represent the fastest-growing use case.
Market access and quality are governed by a matrix of international standards. In the United States, the USDA sets strict grading standards for size and color, while the EU's EFSA evaluates health claims associated with walnut consumption. China's GB standards for food safety impose further requirements on importers. Processors must navigate these disparate regulations to secure a position in high-value export markets.
Market Dynamics
The central tension shaping the walnut market is the collision between rising consumer demand for nutrient-dense, plant-based foods and the increasing climate volatility impacting key cultivation zones. This dynamic forces growers to balance production scale with resource management under tightening regulatory scrutiny.
Growth Catalysts
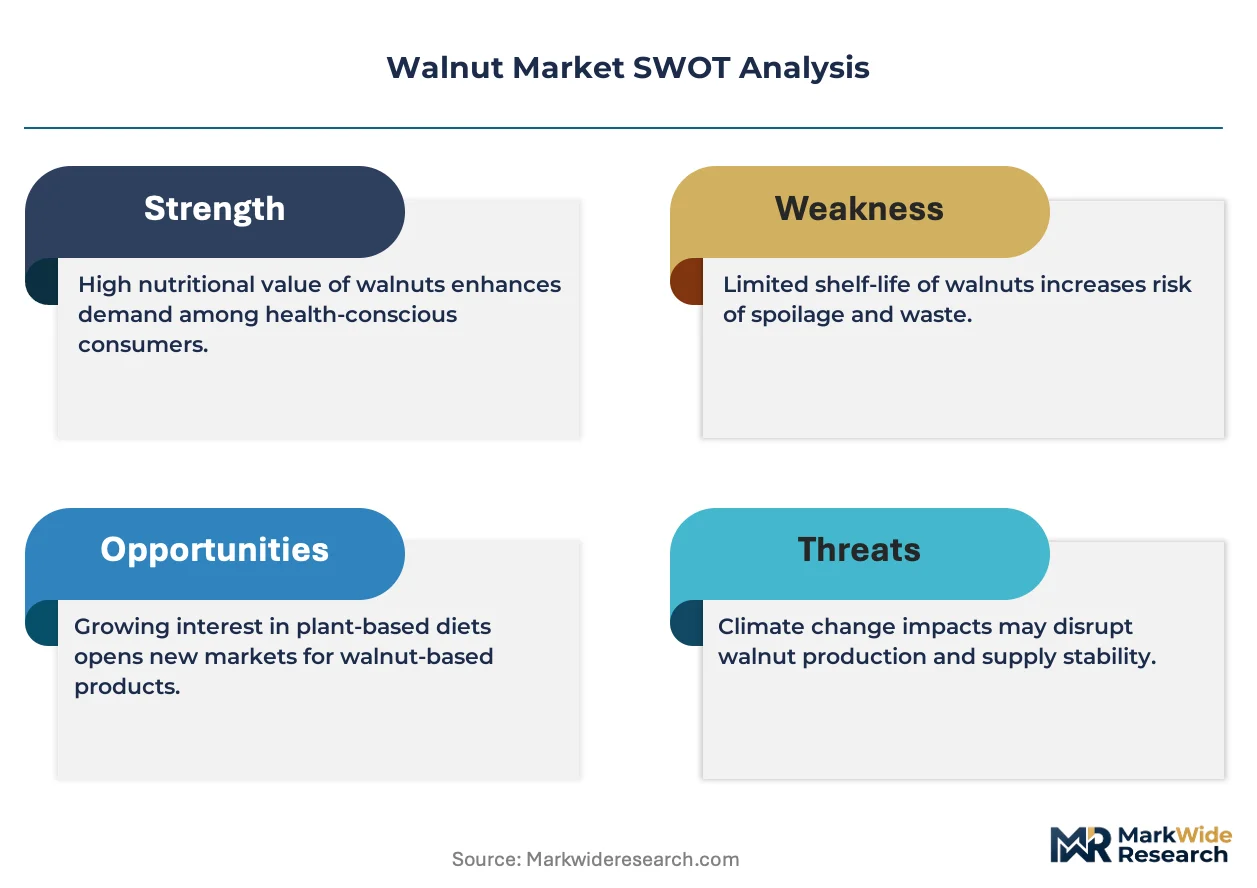
- Health Claim Validation:The European Food Safety Authority's (EFSA) scientific opinions on the health benefits of ALA omega-3s in walnuts bolster consumer trust, enabling food manufacturers to market products with specific health-oriented messaging.
- Plant-Based Dairy Expansion:Demand from the dairy alternatives segment is a primary catalyst, with walnuts being increasingly utilized as a creamy, nutrient-rich base for plant-based milks, yogurts, and cheeses.
- Snacking Culture in China:The continued growth of a middle class in China fuels demand for walnuts as a premium, healthy snack, often consumed as a standalone product or as an ingredient in traditional baked goods.
Market Restraints
- Geographic Production Risk:Heavy reliance on specific climates, particularly in California and parts of China, exposes the global supply to significant disruption from localized droughts, frosts, or other extreme weather events.
- Nut Ingredient Interchangeability:In industrial applications like bakeries and confectionery, food processors can substitute walnuts with almonds or pecans based on commodity price fluctuations, which caps the pricing power of walnut suppliers.
- Water Input Volatility:The water-intensive nature of walnut cultivation creates a structural cost vulnerability, especially in regions like the western United States where water rights and availability are under constant pressure.
Strategic Opportunities
- Walnut Oil for Cosmetics:Extracting and marketing cold-pressed walnut oil for use in natural skincare formulations presents a high-margin opportunity to valorize the nut's properties beyond the food sector.
- Direct-to-Consumer Channels:E-commerce platforms allow growers and cooperatives to market specialty, single-origin, or certified organic walnuts directly to consumers, capturing higher margins and building brand loyalty.
- Processed Foods in Brazil:Brazil's expanding food processing industry represents an underpenetrated market for walnut ingredients in value-added products like breakfast cereals, nutrition bars, and premium desserts.
Industry Challenges
- Navigating Disparate Food Standards:Exporters face significant operational hurdles in concurrently satisfying USDA grading rules, EU health claim regulations, and China's GB standards for food safety, demanding costly compliance and testing protocols.
- Pest Management Expertise Gap:The industry-wide pivot towards Integrated Pest Management (IPM) requires specialized agronomic knowledge, creating a challenge for growers to find and retain talent capable of managing these data-driven systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Walnut Market |
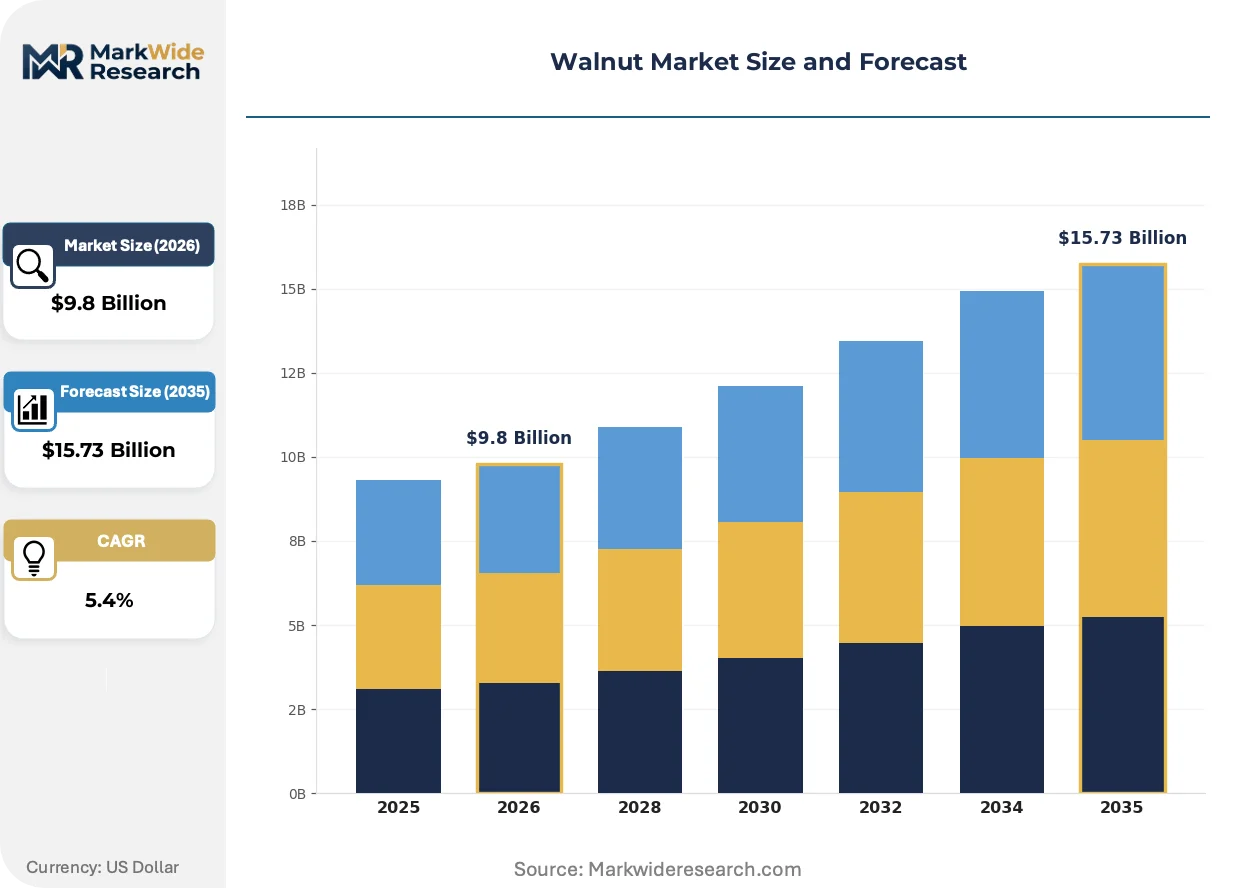
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shelled Walnuts, In-Shell Walnuts, Organic Walnuts, Black Walnuts, White Walnuts Application: Snacking, Bakery Ingredients, Confectionery, Dairy Alternatives, Cosmetic Ingredients End User: Food Manufacturers, Nut Roasters, Confectioners, Cosmetic Companies, Health Supplement Producers Packaging Type: Bulk Bags, Retail Packs, Vacuum Sealed Packs, Glass Jars, Paper Bags |
| Companies Covered | Sierra Cascade Nut Company, Select Harvests Limited, Olam Group, Diamond Foods, Inc., SunOpta Inc., John B. Sanfilippo & Son, Inc., Mariani Nut Company Inc., Archer-Daniels-Midland Company, Borges International Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Walnut Market Strategic Shifts & Innovations
Technological advancements in agronomy are intersecting with evolving consumer demands for transparency and sustainability. This convergence is pushing the industry beyond traditional cultivation and processing, creating new standards for efficiency and product differentiation.
Technology and Product Evolution
Precision irrigation and soil moisture sensor networks provide real-time data for optimizing water allocation in walnut orchards. Large-scale agricultural enterprises in California and Australia are rapidly adopting these systems to combat increasing water scarcity. This data-driven agronomy is supplanting traditional, calendar-based irrigation schedules, improving both resource efficiency and crop yield consistency.
Regulatory and Policy Shifts
The EU's Farm to Fork Strategy, a core component of the European Green Deal, establishes ambitious targets for reducing pesticide application and promoting organic agriculture. This policy directly incentivizes European growers and pressures importers to demonstrate more sustainable cultivation methods. Producers targeting the European market must provide enhanced documentation on farming practices, particularly affecting shelled walnuts destined for food manufacturing.
Demand-Side and Behavioral Shifts
A consumer preference for product provenance and clean-label ingredients is gaining significant traction, particularly in the health and wellness food categories. This behavioral shift favors suppliers that can offer certified organic or single-origin walnuts, disrupting the conventional commodity procurement model where price is the primary decision factor. This trend is most visible in North America and Western Europe, especially within the plant-based beverage and premium snacking segments.
Walnut Market Segmentation
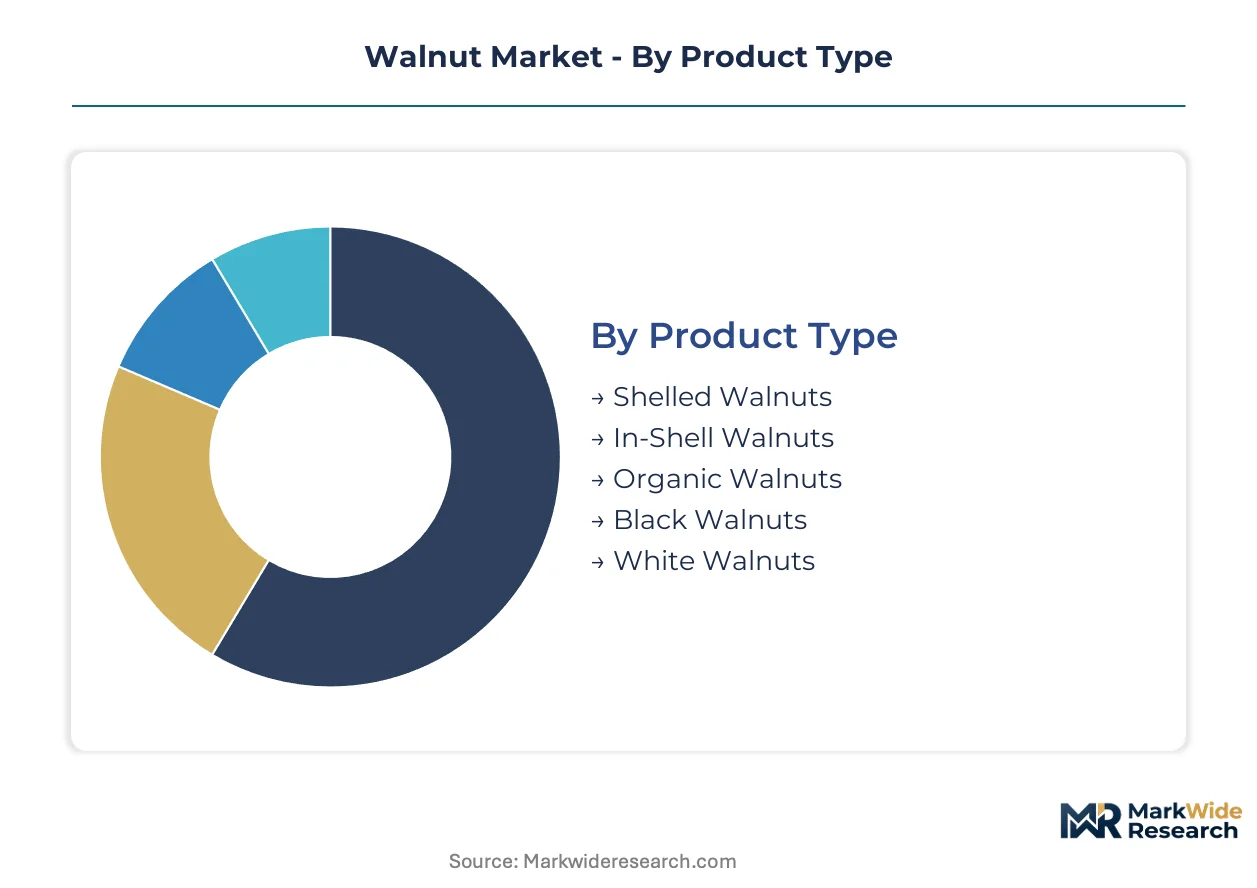
The walnut market segments delineate distinct consumption patterns and operational requirements, guiding strategic decisions for producers and processors. Understanding these divisions helps identify areas of concentrated demand and specific value chain pressures across the industry.
Product Type:
The product type segmentation highlights varying degrees of substitution pressure, particularly for commodity-grade walnuts.
- Shelled Walnuts:These are walnuts with their hard outer shell removed, providing immediate usability for culinary applications. Demand concentrates in the food manufacturing sector, driven by convenience and reduced processing costs for baked goods and snacks.
- In-Shell Walnuts:These are whole walnuts retaining their protective outer shell, primarily sold for direct consumer consumption.
- Organic Walnuts:These walnuts are cultivated without synthetic pesticides or fertilizers, adhering to strict organic certification standards like USDA organic. Demand is expanding in North America and Western Europe, driven by consumer preference for clean-label and sustainably produced foods.
- Black Walnuts:These walnuts are native to North America, known for their robust, earthy flavor profile and harder shell.
- White Walnuts:Also known as English walnuts, these are the most common commercial variety, prized for their milder flavor and lighter color.
Shelled Walnuts retain volume leadership; Organic Walnuts hold the steepest expansion curve.
Application:
The application segment reveals how walnuts are integrated into various consumer products.
- Snacking:Walnuts are consumed directly as a healthy, nutrient-dense snack, often roasted or flavored. Demand remains robust across all major markets, particularly in China, fueled by a growing middle-class preference for convenient healthy options.
- Bakery Ingredients:Walnuts are incorporated into breads, cakes, muffins, and pastries, providing texture and nutritional value.
- Confectionery:Walnuts are used in chocolates, pralines, and other sweet treats, contributing flavor and crunch.
- Dairy Alternatives:Walnuts are processed into plant-based milks, yogurts, and cheeses, leveraging their creamy texture and nutritional profile. Demand is surging in North America and Western Europe, driven by health trends and dietary preferences for plant-based foods.
- Cosmetic Ingredients:Walnut oil and extracts are utilized in skincare products for their emollient and antioxidant properties.
Snacking remains the dominant application, while plant-based dairy alternatives are expanding most quickly.
End User:
Customer type segmentation highlights distinct procurement needs and quality requirements.
- Food Manufacturers:These entities procure walnuts as raw ingredients for large-scale production of packaged foods, including cereals, snacks, and ready meals. Procurement decisions are heavily influenced by bulk pricing and consistent quality standards, particularly in the European food manufacturing sector.
- Nut Roasters:Specialized companies that roast and package walnuts for direct consumer sale or as ingredients for other food businesses.
- Confectioners:Businesses that use walnuts as an ingredient in chocolates, candies, and other sweet products.
- Cosmetic Companies:These companies source walnut oil or extracts for their formulations, prioritizing specific chemical profiles and purity. Demand in this sector is driven by the rise of natural and clean-beauty trends, especially in premium skincare markets.
- Health Supplement Producers:Manufacturers that process walnuts or their derivatives into capsules, powders, or functional food additives for health benefits.
Food Manufacturers represent the largest purchasing segment, with Health Supplement Producers showing significant value-add potential.
Packaging Type:
Volume considerations significantly influence packaging choices within the walnut market.
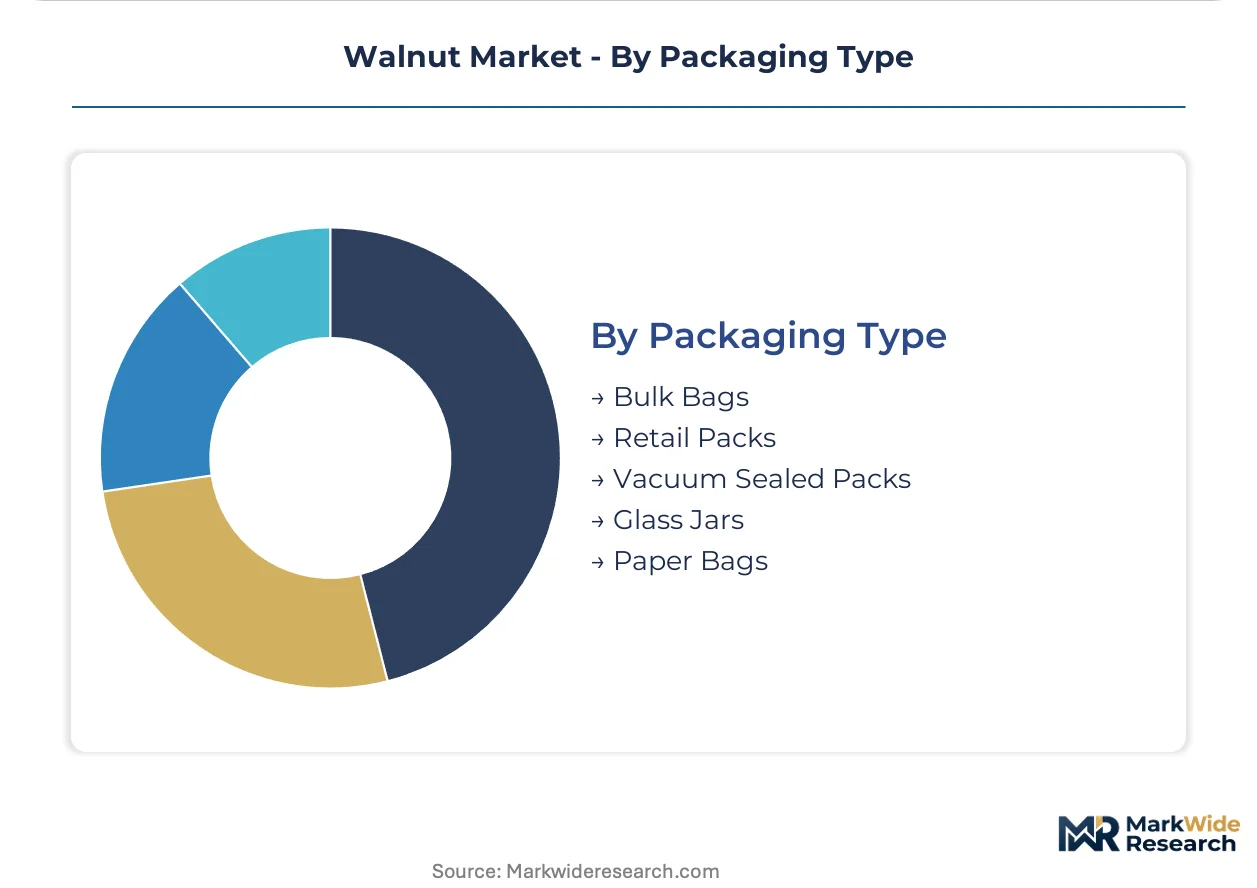
- Bulk Bags:Large-format packaging, typically 25kg or more, used for industrial-scale transport and storage of walnuts for food manufacturers and processors. These are critical for managing high-volume logistics and reducing per-unit packaging costs for large commercial buyers.
- Retail Packs:Smaller, consumer-friendly packaging, often 250g to 1kg, designed for direct sale in supermarkets and online channels. Demand is accelerating in North America and Western Europe, driven by convenience and brand differentiation for household consumers.
- Vacuum Sealed Packs:Packaging designed to remove air, extending shelf life and preserving freshness for both industrial and retail applications.
- Glass Jars:Premium packaging option, offering aesthetic appeal and product visibility, often used for specialty or organic walnuts.
- Paper Bags:Environmentally conscious packaging choice, increasingly favored for smaller retail quantities or farmers' market sales.
Bulk Bags dominate industrial supply chains, while Retail Packs are gaining share in direct-to-consumer sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The walnut market exhibits a pricing-power asymmetry, with cultivation hubs in the United States facing different market dynamics than the processing and consumption centers in China. This regional divergence impacts trade flows and influences investment in value-added product development.
United States
United States walnut producers focus on meeting increasing demand for plant-based dairy ingredients and organic snacking options. USDA organic standards influence cultivation practices, ensuring product integrity. California's Central Valley remains the primary cultivation region, where growers implement advanced irrigation techniques.
China
China's substantial consumer base drives demand for walnuts in traditional cuisine and as a popular healthy snack. The GB standards for food safety impose rigorous requirements on imported walnuts. Major urban centers like Shanghai serve as critical import gateways, facilitating distribution across the vast market.
Germany
Germany's advanced food manufacturing sector demands high-quality walnut ingredients for bakery and confectionery applications. The EU's Farm to Fork Strategy pressures importers to demonstrate sustainable cultivation methods. Food processing clusters in North Rhine-Westphalia integrate walnuts into value-added products for European distribution.
Brazil
Brazil's expanding food processing industry creates a growing market for walnut ingredients in breakfast cereals and nutrition bars. ANVISA food safety regulations govern the import and use of nuts, ensuring consumer protection. The industrial hub of São Paulo drives innovation in processed food development, incorporating walnuts into new consumer offerings.
Australia
Australia sees demand for walnuts in premium snacking and the expanding organic food segment. The TGA evaluates health claims for products containing nut derivatives, influencing marketing strategies. Cultivation in the Riverina region benefits from advanced irrigation, supporting consistent supply for domestic and export markets.
Walnut Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the walnut market. The industry exhibits a tiered structure, with large agricultural enterprises focusing on scale and efficiency, while specialized processors differentiate through value-added products. Key strategic archetypes include integrated global suppliers, consumer-facing brand owners, and ingredient specialists. Companies pursue strategic partnerships and geographic expansion to secure supply and penetrate new demand centers.
Integrated global suppliers such as Olam Group leverage extensive sourcing networks to manage supply chain volatility and ensure consistent raw material availability. Consumer-facing brand owners like Diamond Foods, Inc. occupy a position in the premium snacking category, differentiating through strong brand recognition and direct consumer appeal across various retail channels. Furthermore, Borges International Group, a European-based entity, exemplifies specialists focused on value-added products, catering to the European food manufacturing sector with customized walnut ingredients and diverse product offerings for industrial clients.
| Leading Market Players |
|---|
| Sierra Cascade Nut Company |
| Select Harvests Limited |
| Olam Group |
| Diamond Foods, Inc. |
| SunOpta Inc. |
| John B. Sanfilippo & Son, Inc. |
| Mariani Nut Company Inc. |
| Archer-Daniels-Midland Company |
| Borges International Group |
| Others |
Cost & Logistics Intelligence
USDA organic standards influence both cultivation practices and product labeling, directly impacting supply qualification and enabling price differentiation for premium walnut products. China's GB standards for food safety also impose strict requirements, affecting market access and pricing for imported walnuts.
Pricing Analysis
Configured-to-order pricing for specialized walnut ingredients allows suppliers to command premiums from European food manufacturers. Contract-based long-term offtake dominates for industrial buyers, while retail operates on per-unit transactional pricing. Quality grade, determined by USDA size and color standards, and certification level, such as USDA organic, are key price differentiation drivers. Pricing softness stems from nut ingredient interchangeability, particularly for commodity-grade walnuts in industrial applications. Food manufacturers are highly price-sensitive for bulk ingredients, while direct-to-consumer premium snacking segments show lower sensitivity.
Supply Chain Analysis
Inventory management for walnuts must account for seasonal harvest cycles and the need for controlled storage environments to preserve quality. Production concentrates in the United States, particularly California's Central Valley, China, and Australia. Water is a critical input, especially in arid cultivation zones, creating a structural cost vulnerability. Geographic production risk from climate volatility, such as droughts or frosts, poses a significant structural risk to global supply. Distribution runs through large-scale processors and aggregators for industrial use, and directly to retailers for consumer packs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The walnut market is experiencing a platform-economics inflection as data-driven agronomy and precision irrigation systems create an interoperable ecosystem for resource management. This shift enables new efficiencies and product differentiation across the supply chain.
For Market Incumbents: Shield market share against commodity price volatility by deepening vertical integration into value-added processing for plant-based dairy alternatives. Invest in advanced irrigation technologies and Integrated Pest Management (IPM) to mitigate climate volatility and rising water input costs. Secure long-term supply contracts with growers in diversified geographies to reduce geographic production risk. This strategy helps counter the threat of nut ingredient interchangeability.
For New Entrants and Emerging Players: USDA organic certification fast-tracks market entry for premium, clean-label walnuts, especially in North America and Western Europe. Target the underpenetrated Brazilian processed foods market with specialized walnut ingredients for breakfast cereals and nutrition bars. Develop direct-to-consumer e-commerce channels to capture higher margins for single-origin or certified organic products. This approach leverages consumer preference for provenance and health claims.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates seeking to divest non-core nut processing assets. Long-term viability rests on securing sustainable sourcing and processing capabilities for high-growth segments like plant-based dairy. Focus on mid-sized processors specializing in innovative value-added walnut ingredients for European food manufacturing. The signal to watch is increased M&A activity among ingredient specialists targeting specific health-claim validated product lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agronomy Adoption | Optimizes water usage and improves crop yield consistency for walnut growers. |
| Plant-Based Dairy Ingredient Development | Captures surging demand from health-conscious consumers in North America. |
| Direct-to-Consumer E-commerce Platform | Builds brand loyalty and secures higher margins for specialty walnut producers. |
| Global Sourcing Network Expansion | Mitigates supply chain volatility and ensures consistent raw material availability. |
| Cosmetic Walnut Oil Extraction | Valorizes byproducts and taps into the high-margin natural skincare market. |
Research Approach
The analysis maps walnut product types, applications, and end-user segments, each validated through primary interviews with food manufacturers, nut roasters, and agronomy specialists. This approach combines qualitative insights from industry stakeholders with quantitative data from USDA reports, EFSA scientific opinions, and China's customs data. Bottom-up data collection was triangulated with top-down market sizing.
Forecast outputs were consistently checked against historical market trends and external industry benchmarks over the projection horizon. The analytical framework modeled segmentation across product type, application, end-user, and packaging type, along with regional consumption patterns. Compound annual growth rates were derived from a multi-factor regression analysis. Key forecast inputs included consumer health trend adoption rates and climate volatility projections.
Decision-makers should treat outputs as directional under current climate stability and regulatory frameworks; material deviation would warrant model refresh. Forecasts reflect assumptions regarding agricultural policy shifts and consumer dietary preferences. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Apricot Kernel Market
Nuts and Seeds
Organic Almond Oil Market
Nuts and Seeds
China Almond Market
Nuts and Seeds
Breadnut Market
Nuts and Seeds
South America Nut-Based Spread Market
Nuts and Seeds
Reduced Fat Peanut Butter Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Hazelnut Market
Nuts and Seeds
Nut Ingredients Market
Nuts and Seeds
Tree Nuts Market
Nuts and Seeds
Thailand Fox Nuts Market
Nuts and Seeds
Tree Nut Allergy Market
Nuts and Seeds
Europe Nut-Based Spreads Market
Nuts and Seeds
Walnut Oil Market
Nuts and Seeds
Tiger Nuts Market
Nuts and Seeds
United States Nuts Market