
 Brazil Nuts Market | 2026-2036
Brazil Nuts Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Nuts Market Analysis
Almond paste is hardening as a cost-competitive substitute in European confectionery applications, pressuring Brazil nut pricing in premium praline segments. Select Harvest sustains its position through backward integration into Amazonian collection cooperatives. Archer Daniels Midland leverages its commodity trading infrastructure to control bulk export channels. Beraca specializes in cosmetic-grade oil extraction, occupying a defensible niche in personal care supply chains.
Brazil nuts are large seeds from Bertholletia excelsa trees, containing exceptionally high selenium content at approximately 96 micrograms per nut and lipid profiles dominated by unsaturated fatty acids around 67 percent. The nuts serve primarily as functional food ingredients and cosmetic oil feedstocks where trace mineral bioavailability matters. Raw product type leads volume due to clean-label demand from industrial buyers, while nutraceuticals end user represents the fastest-growing segment as selenium fortification gains regulatory traction in dietary supplements. Distribution through specialty stores captures the highest margin pool, though online channel expansion is accelerating as direct-to-consumer wellness brands proliferate.
ANVISA governs food supplement registration and selenium labeling thresholds in Brazil, directly influencing export-grade processing standards. The EU REACH framework and EFSA selenium intake guidelines shape market access for Brazilian processors selling into European nutraceutical channels. Organic certification under Brazilian federal programs and EU equivalence agreements creates bifurcated compliance costs that smaller collectors struggle to absorb. Stakeholders must monitor evolving selenium maximum-level debates in major import jurisdictions to anticipate reformulation requirements ahead of regulatory implementation.
Market Dynamics
EU REACH enforcement on food-contact selenium limits is compressing export windows for Brazilian processors, forcing rapid certification upgrades across the Amazonian collection network before the regulatory deadline.
Growth Catalysts
- EFSA selenium intake guidelines:European nutraceutical formulators now specify Brazil nut oil for fortified supplements, creating pull-through demand for traceable Amazonian sourcing.
- Clean-label industrial procurement:São Paulo snack manufacturers are specifying raw Brazil nuts over processed alternatives to meet retailer ingredient transparency mandates.
- Amazonian collection cooperatives:Backward integration into indigenous harvesting networks secures organic-certified volume for cosmetic-grade oil extraction.
Market Restraints
- Almond paste substitution:European confectionery buyers are reformulating praline recipes with lower-cost nut pastes, eroding premium pricing power for Brazil nut inclusions.
- Single-origin supply concentration:Ninety percent of commercial harvest originates from wild Amazonian stands in Brazil, Bolivia, and Peru, exposing buyers to climate-induced yield volatility.
- ANVISA registration timelines:Brazilian food supplement approval processes extend eighteen to twenty-four months, delaying export-grade product launches.
Strategic Opportunities
- Direct-to-consumer wellness channels:Online distribution bypasses specialty store markups, capturing margin pool for selenium-positioned brands targeting North American supplement buyers.
- Cosmetic oil microencapsulation:Personal care formulators are integrating Brazil nut oil into stable delivery systems for anti-aging topical applications.
- EU organic equivalence agreements:Brazilian federal certification programs now streamline access to European premium pricing tiers for compliant collectors.
Industry Challenges
- Wild harvest traceability systems:Mapping individual Brazil nut trees across dispersed Amazonian territories requires GPS-enabled cooperative management platforms that most collectors lack capital to deploy.
- Selenium testing laboratory capacity:Batch verification for export compliance bottlenecks at ANVISA-accredited facilities during peak harvest windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Nuts Market |
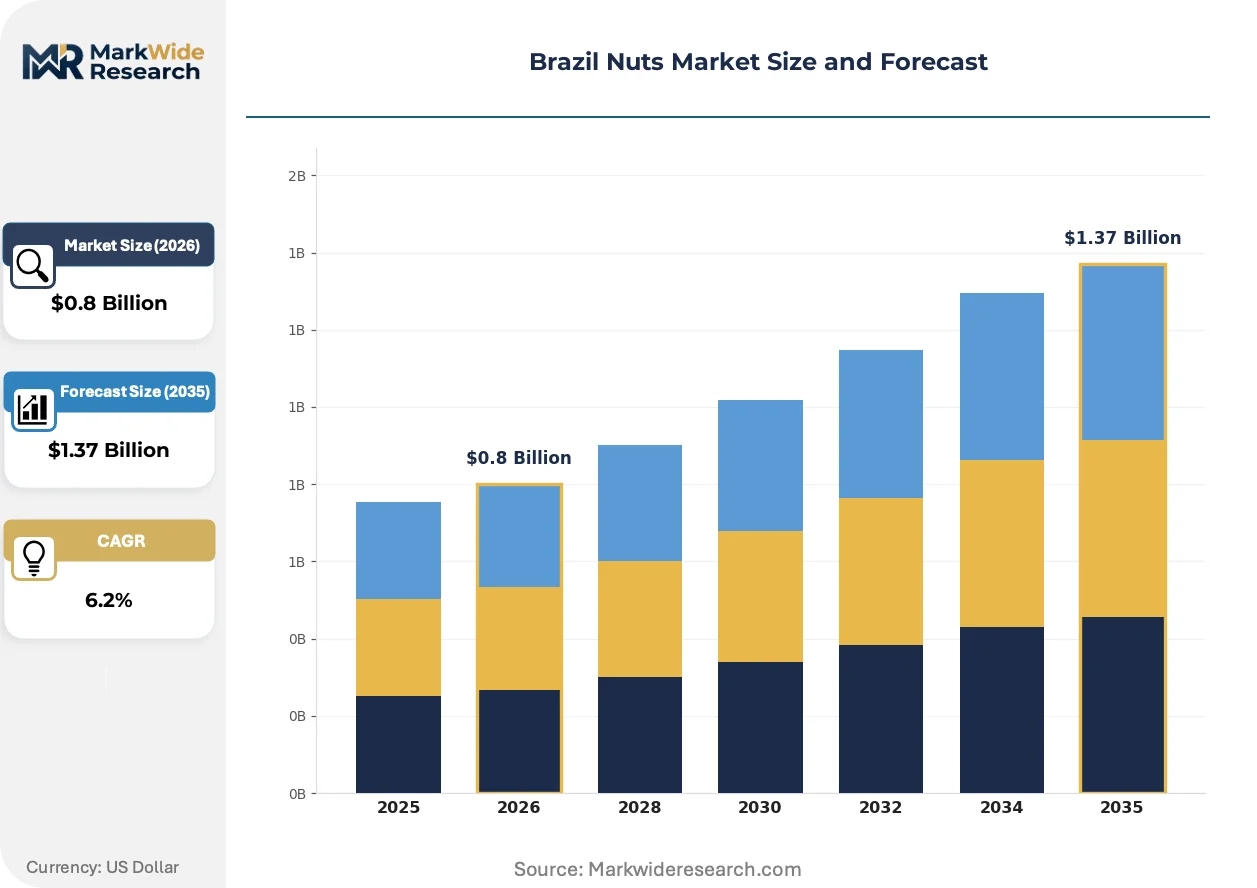
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.37 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw, Roasted, Flavored, Unsalted End User: Food Industry, Cosmetics, Nutraceuticals, Snacks Packaging Type: Bags, Tins, Boxes, Bulk Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Select Harvest, Food to Live, Archer Daniels Midland, Beraca, Sunfood, Basse Nuts, Terrasoul Superfoods, Agroindustria del Oriente S.A., Happilo International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Nuts Market Emerging Trajectories
Processing technology and regulatory compliance systems are converging to reshape how Brazil nut moves from wild harvest to formulated end-products, with traceability and selenium verification as the central technical battlegrounds.
Cold-press extraction equipment with inline selenium spectroscopy is integrating real-time mineral content verification into cosmetic oil production lines. European nutraceutical contract manufacturers are adopting these systems to pre-validate batches before EU customs entry. This technology compression is eliminating the rework costs that previously eroded margins on rejected shipments.
EU REACH substance restrictions on food-contact materials are tightening selenium migration limits for packaging films and processing equipment. Brazilian exporters must now certify that their supply chains exclude non-compliant polymer grades. The nutraceutical segment is responding by demanding chain-of-custody documentation from nut collection through final encapsulation.
Industrial buyers are consolidating procurement around vertically integrated suppliers who control both Amazonian collection and São Paulo processing infrastructure. This preference shift displaces spot-market traders who cannot guarantee organic certification continuity. The behavior is most pronounced among German and Dutch confectionery houses with published sustainability commitments.
Brazil Nuts Market Segmentation
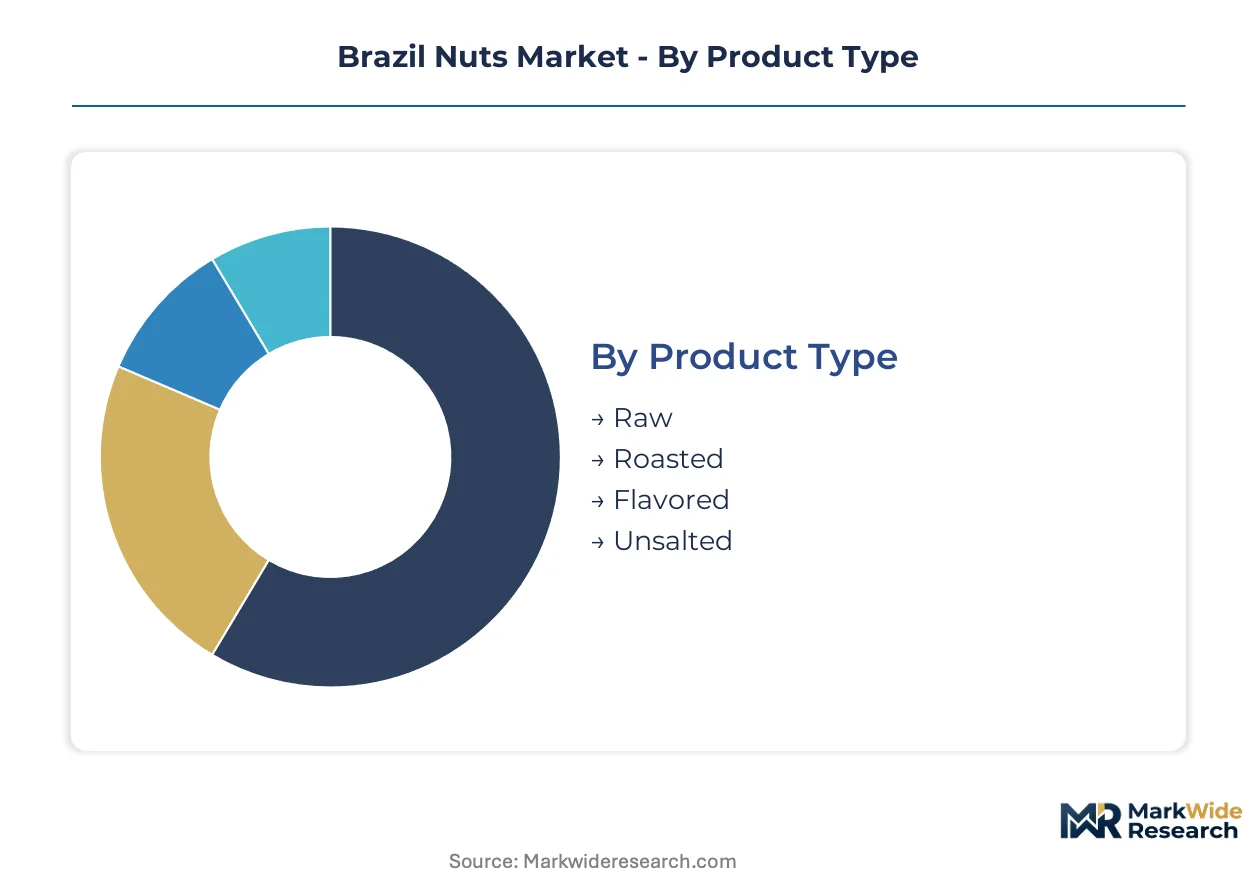
Brazil nut segmentation reflects divergent processing requirements across food-grade and cosmetic-grade applications. Each category carries distinct certification burdens and margin structures that reshape supplier selection criteria for industrial buyers.
Product Type:
Customization intensity varies sharply across this category, from commodity raw kernels to value-added flavor profiles requiring specialized roasting infrastructure.
- Raw:Unprocessed kernels retain full selenium bioavailability and lipid integrity for cosmetic oil extraction and premium food applications. São Paulo snack manufacturers specify raw product to satisfy retailer clean-label mandates and traceability requirements.
- Roasted:Thermal processing develops Maillard flavor compounds and extends shelf stability for direct consumption channels. European confectionery houses favor roasted grades for praline inclusions where moisture control determines texture consistency.
- Flavored:Salt, honey, and spice coatings target impulse purchase segments in airport retail and convenience channels.
- Unsalted:Sodium-free positioning serves cardiac-conscious demographics and ingredient buyers formulating controlled-sodium finished goods.
Leading the category by volume: Raw. Growing fastest: Flavored.
End User:
Application maturity spans from established food processing to emerging nutraceutical positioning where regulatory approval timelines create entry barriers.
- Nutraceuticals:Selenium-enriched supplements and functional foods command premium pricing contingent on ANVISA registration and EFSA compliance documentation. European formulators specify Brazil nut oil for traceable mineral fortification.
- Cosmetics:Cold-pressed oil delivers tocopherol and unsaturated fatty acid profiles for anti-aging topical formulations. Personal care manufacturers in Germany and France integrate microencapsulated Brazil nut oil into premium skincare lines.
- Food Industry:Ingredient buyers in confectionery and bakery segments specify kernel grades for texture and fat content consistency.
- Snacks:Roasted and packaged whole kernels serve direct consumption channels with lower certification requirements but compressed margins.
Dominating revenue contribution: Food Industry. Expanding most quickly: Nutraceuticals.
Packaging Type:
Volume scale and margin capture diverge between industrial bulk formats and consumer-facing premium presentations.
- Bulk:25-kilogram fiber drums and food-grade totes serve cosmetic oil extractors and confectionery processors with minimal handling costs. São Paulo processing corridors concentrate procurement around bulk shipments through Santos port infrastructure.
- Bags:Flexible pouches with nitrogen flush dominate snack retail positioning.
- Tins:Metal canisters signal gift-market premium positioning in European specialty retail.
- Boxes:Rigid packaging supports organic certification display requirements and shelf differentiation.
Highest throughput: Bulk. Steepest expansion trajectory: Bags.
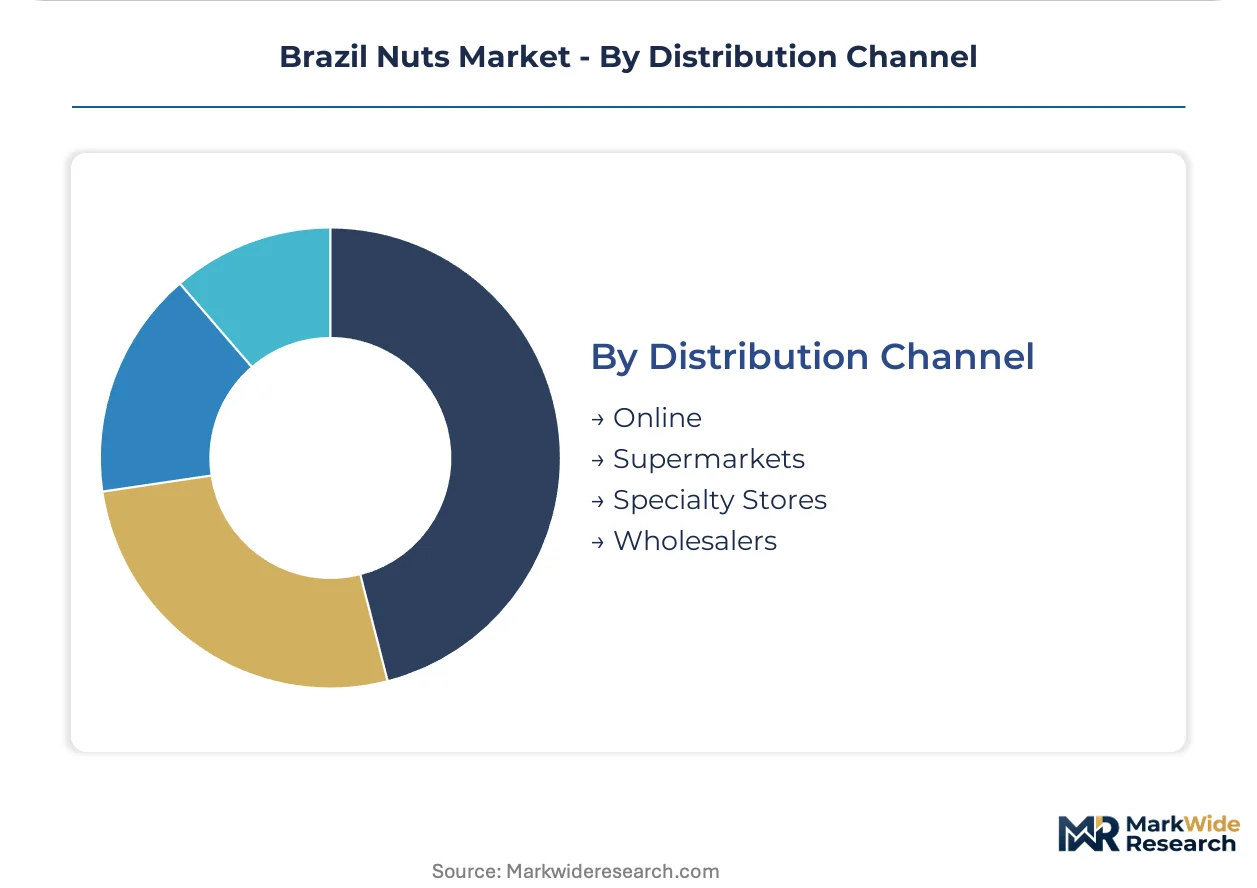
Distribution Channel:
Channel selection determines margin retention versus market access tradeoffs across geographically dispersed demand centers.
- Specialty Stores:Gourmet retailers and organic chains capture premium pricing for certified organic and fair-trade positioned product. German and Dutch confectionery houses with published sustainability commitments consolidate procurement through this channel.
- Online:Direct-to-consumer wellness brands bypass intermediary markups to target North American selenium supplement buyers with subscription models.
- Supermarkets:Mass retail placement requires scale supply commitments and promotional investment.
- Wholesalers:Traditional distributors serve fragmented food service and small processor demand.
Widest volume flow: Wholesalers. Gaining share fastest: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European nutraceutical formulators and São Paulo food processors concentrate import demand for traceable Amazonian Brazil nut supply. Regulatory pressure from EFSA selenium guidelines and EU REACH food-contact rules is reshaping procurement geography across importer nations. Processing infrastructure clusters near Santos port and Rotterdam distribution hubs.
Germany
EFSA selenium intake guidelines drive German supplement manufacturers to specify Brazil nut oil for fortified formulations. REACH substance restrictions on food-contact materials force importers to certify polymer-grade compliance across packaging supply chains. Cologne and Hamburg processing corridors concentrate cosmetic oil extraction for personal care brands.
United States
FDA dietary supplement regulations and selenium labeling requirements shape import specifications for wellness brands targeting direct-to-consumer channels. Amazonian collection cooperatives face pressure to demonstrate organic certification equivalence under USDA National Organic Program rules. California and New York wellness markets anchor North American demand for selenium-positioned supplements.
France
ANSM pharmaceutical oversight and cosmetic safety standards influence Brazil nut oil specifications for anti-aging topical formulations. EU organic equivalence agreements streamline access for Brazilian federal certified collectors. Paris and Lyon cosmetic laboratories drive microencapsulation demand for stable selenium delivery systems.
Netherlands
Rotterdam port infrastructure serves as the primary European entry point for bulk Brazil nut shipments from Santos. Dutch confectionery houses with published sustainability commitments consolidate procurement around traceable Amazonian sourcing. ECHA REACH enforcement creates compliance bottlenecks for non-certified processors during peak harvest windows.
Brazil
ANVISA food supplement registration timelines extend eighteen to twenty-four months, delaying export-grade product launches for domestic processors. São Paulo's food processing corridor clusters snack and confectionery manufacturers near port infrastructure. Amazonian collection cooperatives in Pará and Amapá states supply wild-harvested organic-certified volume for cosmetic oil extraction.
Brazil Nuts Market Vendor Landscape
Backward integration into Amazonian collection networks dominates the current landscape as processors secure organic-certified supply. The vendor base spans vertically integrated commodity traders, specialty oil extractors, and direct-to-consumer wellness brands. Three strategic archetypes prevail: bulk commodity exporters controlling Santos port channels, cosmetic-grade specialists with cold-press extraction capabilities, and subscription-model wellness brands bypassing retail markups. M&A activity targets indigenous cooperative partnerships, while certification upgrades absorb capital across the Amazonian collection network.
Among commodity-integrated processors, Archer Daniels Midland exemplifies scale-driven export infrastructure control, while Beraca occupies the cosmetic-grade specialization tier with personal care supply chain positioning. Select Harvest represents the cooperative-integration archetype through Amazonian sourcing networks. These three anchors illustrate how competitive positioning diverges across bulk commodity, cosmetic extraction, and traceable sourcing vectors.
| Leading Market Players |
|---|
| Select Harvest |
| Food to Live |
| Archer Daniels Midland |
| Beraca |
| Sunfood |
| Basse Nuts |
| Terrasoul Superfoods |
| Agroindustria del Oriente S.A. |
| Happilo International |
| Others |
Supply Flow & Price Mechanics
EU organic equivalence agreements gate qualified supply and premium-tier pricing access, forcing Brazilian collectors to absorb certification costs or surrender margin to compliant intermediaries. Buyers in German nutraceutical channels now pay demonstrable premiums for traceable Amazonian provenance.
Pricing Analysis
Volume-scale bulk shipments to Rotterdam capture commodity margins, while specialty store and direct-to-consumer channels retain premium capture. Three-tier pricing structure across organic-certified premium, conventional food-grade standard, and ungraded economy levels reflects certification burden and traceability depth. Cost compression in conventional grades intensifies because almond paste substitution in European confectionery erodes Brazil nut inclusion pricing power. Food industry buyers exhibit highest price sensitivity due to reformulation flexibility, whereas cosmetic-grade oil extractors show lowest sensitivity given selenium bioavailability requirements.
Supply Chain Analysis
Single-source vulnerability sits with wild Amazonian stands concentrated across Brazil, Bolivia, and Peru where climate-induced yield volatility exposes buyers to harvest shortfalls. The supply chain draws from dispersed indigenous collection cooperatives, São Paulo processing infrastructure, and Rotterdam distribution hubs. Regulatory restriction through EU REACH food-contact selenium limits creates compliance bottlenecks for non-certified processors. Distribution runs through vertically integrated commodity traders controlling Santos port export channels and bulk shipment consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wild harvest capacity constraints in Amazonian territories prop pricing, as ninety percent of commercial volume originates from non-cultivated stands with limited expansion potential. Supply scarcity favors incumbent processors with cooperative network control.
For Market Incumbents: Deploy certification infrastructure investment to defend organic-certified volume against spot-market traders who cannot guarantee compliance continuity. Anchor São Paulo processing capacity to lock in Santos port throughput allocation. Almond paste substitution in European praline segments threatens premium pricing power for conventional grades. For New Entrants and Emerging Players: Begin with direct-to-consumer wellness channels in North American markets where subscription models bypass specialty store markups and selenium positioning commands brand premium. Target nutraceutical microencapsulation applications where stable delivery system technology creates formulation stickiness. Partner with established Amazonian cooperatives rather than building collection networks from origin. For Investors and Strategic Acquirers: ANVISA registration backlog clearing is the leading indicator that export-grade processing capacity will tighten and qualified supply premiums will expand. Five-to-ten year viability rests on cooperative network control rather than spot-market trading positions. Acquisition targets should demonstrate GPS-enabled traceability platforms and existing EU organic equivalence documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperatives | Secures organic-certified volume for cosmetic oil extraction ahead of EU REACH deadlines. |
| Cold-Press Extraction Scale-Up | Enables real-time selenium spectroscopy integration for pre-validated EU customs entry. |
| Direct-to-Consumer Channel Launch | Captures margin pool from wellness brands targeting North American supplement buyers. |
| Microencapsulation R&D Partnership | Develops stable delivery systems for anti-aging topical applications in German cosmetic labs. |
| EU Organic Equivalence Program Enrollment | Streamlines access to premium pricing tiers for compliant Amazonian collectors. |
Methodological Framework
Trade databases, ANVISA registration filings, and EFSA guidance documents formed the secondary backbone, supplemented by customs records tracking Santos-Rotterdam shipment corridors. Primary interviews with Amazonian cooperative managers, São Paulo food processing procurement leads, and European nutraceutical formulators validated supply chain concentration assumptions. Bottom-up volume estimates from collection cooperative output triangulated against top-down import value flows.
Bottom-up modeling aggregated segment-level demand across raw, roasted, and flavored product types, while top-down analysis anchored total market value to disclosed import flows. Segmentation dimensions included product type, end user application, packaging format, and distribution channel complexity. CAGRs derived from historical volume trajectories adjusted for regulatory implementation timelines and certification adoption curves. Forecast inputs incorporated EU REACH enforcement schedules and ANVISA processing capacity constraints.
Climate-induced yield volatility, regulatory deadline acceleration, and cooperative certification failure are the dominant revision risks to modeled supply assumptions. Forecasts reflect documented assumptions about collection network stability and export infrastructure throughput. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Pecans Market
Nuts and Seeds
Macadamia Nut Market
Nuts and Seeds
Global Edible Nuts Market
Nuts and Seeds
United States Cashew Market
Nuts and Seeds
Peanuts Market
Nuts and Seeds
India Processed Cashew Market
Nuts and Seeds
Betel Nuts Market
Nuts and Seeds
Carob Extract Market
Nuts and Seeds
Europe Nut-Based Spreads Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
Nutmeg Market
Nuts and Seeds
Spain Fox Nuts Market
Nuts and Seeds
Macadamia Market
Nuts and Seeds
Nutmeg Butter Market
Nuts and Seeds
Pistachios Market
Nuts and Seeds
Fat Free Peanut Butter Market