
 Cyclopentasiloxane Market | 2026-2036
Cyclopentasiloxane Market Size, Share, and Industry Trends Forecast 2026-2036
Cyclopentasiloxane Market Analytics
Cosmetic-grade purity specifications above 99.5 percent is bifurcating the competitive landscape into premium and commodity supply tiers. Dow Chemical Company leverages backward integration into silane feedstocks to sustain margin control across volatile raw material cycles. Wacker Chemie AG anchors its position through specialized silicone manufacturing scale in Germany and Asia-Pacific operations. BASF SE differentiates via application-specific technical service for personal care formulators seeking rapid emulsion development support.
Cyclopentasiloxane is a volatile cyclic siloxane with molecular formula C10H30O5Si5, featuring a low surface tension of approximately 19 mN/m and rapid evaporation at skin temperature, which makes it functionally essential as a carrier solvent and sensory modifier in cosmetic formulations. Industrial-grade material serves surface treatment applications where film-forming speed and substrate compatibility determine process economics. Skin Care applications command the deepest margin pools due to formulation complexity and brand premiumization, while Hair Care competes on volume throughput with thinner technical specifications. The Direct Sales channel dominates bulk pharmaceutical and industrial procurement through long-term supply agreements, whereas Online Retail extends reach to indie cosmetic brands and regional formulators lacking established distributor relationships.
EPA scrutiny of cyclic siloxane bioaccumulation shapes product registration requirements for US-market personal care ingredients, while REACH authorization processes in Europe restrict D5 concentrations in leave-on cosmetics above 0.1 percent by weight. China's SAMR enforces GB standards for cosmetic raw material safety that implicate cyclopentasiloxane purity thresholds and residual monomer limits. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation timelines and inventory qualification costs.
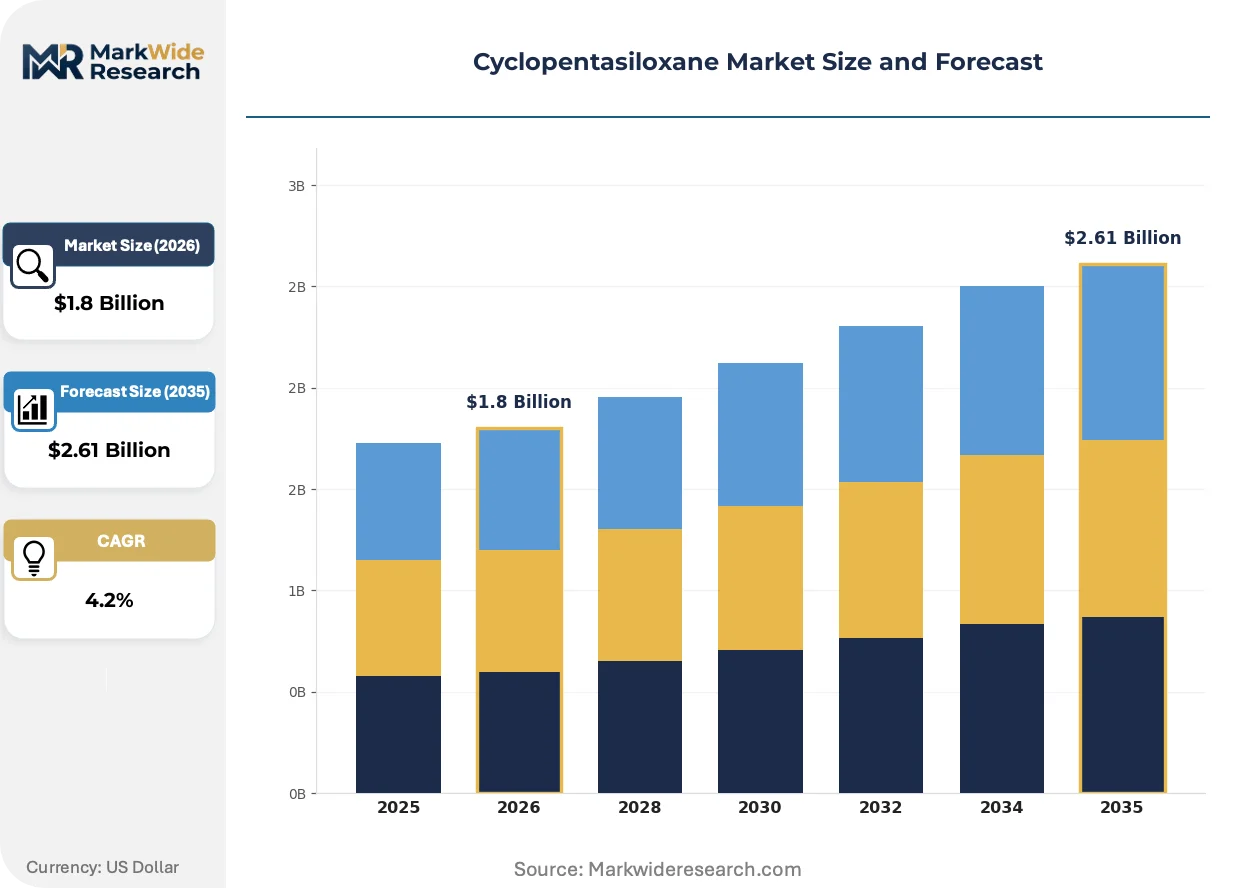
Market Dynamics
REACH authorization processes restricting D5 concentrations above 0.1 percent in leave-on cosmetics are forcing reformulation investments across European supply chains, while South Korean cosmetic formulators expand cyclopentasiloxane use in long-wear skin care products as volatile silicone demand rises.
Growth Catalysts
- Volatile silicone demand in K-beauty:South Korean cosmetic formulators are expanding cyclopentasiloxane use in long-wear skin care products, creating sustained pull for high-purity grades.
- REACH substitution mandates:European restrictions on cyclic siloxanes are pushing manufacturers toward D5 reformulation strategies that preserve functional performance.
- China personal care manufacturing scale:Domestic brands in Shanghai and Guangzhou manufacturing clusters are scaling rapidly, concentrating demand in coastal production zones.
Market Restraints
- Silane feedstock volatility:Raw material cost swings in silane chemistry constrain margin predictability for non-integrated producers.
- EPA bioaccumulation scrutiny:Product registration requirements for cyclic siloxanes in US-market personal care ingredients create compliance friction and timeline uncertainty.
- Dimethicone substitution pressure:Linear siloxanes compete on perceived environmental profile in clean beauty positioning.
Strategic Opportunities
- Underpenetrated ASEAN formulator base:Indonesian and Vietnamese cosmetic manufacturers lack established distributor relationships, creating channel innovation potential through direct technical service models.
- Pharmaceutical-grade qualification:Cyclopentasiloxane purity thresholds above 99.5 percent open transdermal drug delivery applications with distinct regulatory pathways.
- China SAMR GB standard alignment:Residual monomer limits and cosmetic raw material safety enforcement create first-mover advantage for qualified inventory holders.
Industry Challenges
- Reformulation timeline compression:Regulatory divergence between REACH, EPA, and SAMR jurisdictions forces simultaneous multi-standard qualification.
- Specialized silicone synthesis expertise scarcity:Cyclic siloxane manufacturing requires process chemistry capabilities concentrated in Germany and select Asia-Pacific facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyclopentasiloxane Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Personal Care, Industrial, Pharmaceuticals End User: Manufacturers, Retailers, Distributors, Researchers Application: Skin Care, Hair Care, Antiperspirants, Surface Treatments Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers |
| Companies Covered | KCC Beauty, BASF SE, Dow Chemical Company, Grant Industries Inc., Evonik Industries, Wacker Chemie AG, Momentive Performance Materials Inc., Kobo Products Inc., Shin-Etsu Silicones, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyclopentasiloxane Market Evolving Landscape
Formulation technology is actively compressing carrier solvent volumes while preserving sensory performance, with miniaturization of emulsion particle sizes and convergence of volatile and non-volatile silicone functionalities reshaping competitive positioning in cosmetic chemistry.
Microemulsion delivery systems incorporating cyclopentasiloxane as a volatile carrier are miniaturizing droplet sizes below 100 nanometers, enabling deeper active penetration without residual film. Premium skin care brands in South Korea and Japan are adopting these systems at accelerated pace. The structural consequence is compression of traditional two-phase formulation steps into single-process manufacturing, reducing batch cycle times and capital footprint for emulsion production.
REACH authorization restrictions on D5 concentrations in leave-on cosmetics above 0.1 percent by weight are forcing ingredient suppliers to develop alternative cyclic siloxane formulations or hybrid volatile systems. The industrial consequence is fragmentation of raw material qualification protocols across European and non-European supply chains. Personal care formulators serving dual markets are responding with geographic SKU differentiation that increases inventory complexity but preserves market access.
Indie cosmetic brands lacking established distributor relationships are migrating procurement toward online retail channels for raw material sourcing, bypassing traditional chemical distributor networks. This channel shift is most visible in North American and European markets where small-batch formulators prioritize speed over volume pricing. The disruption compresses minimum order quantities and forces suppliers to unbundle technical service from bulk procurement contracts.
Cyclopentasiloxane Market Segmentation
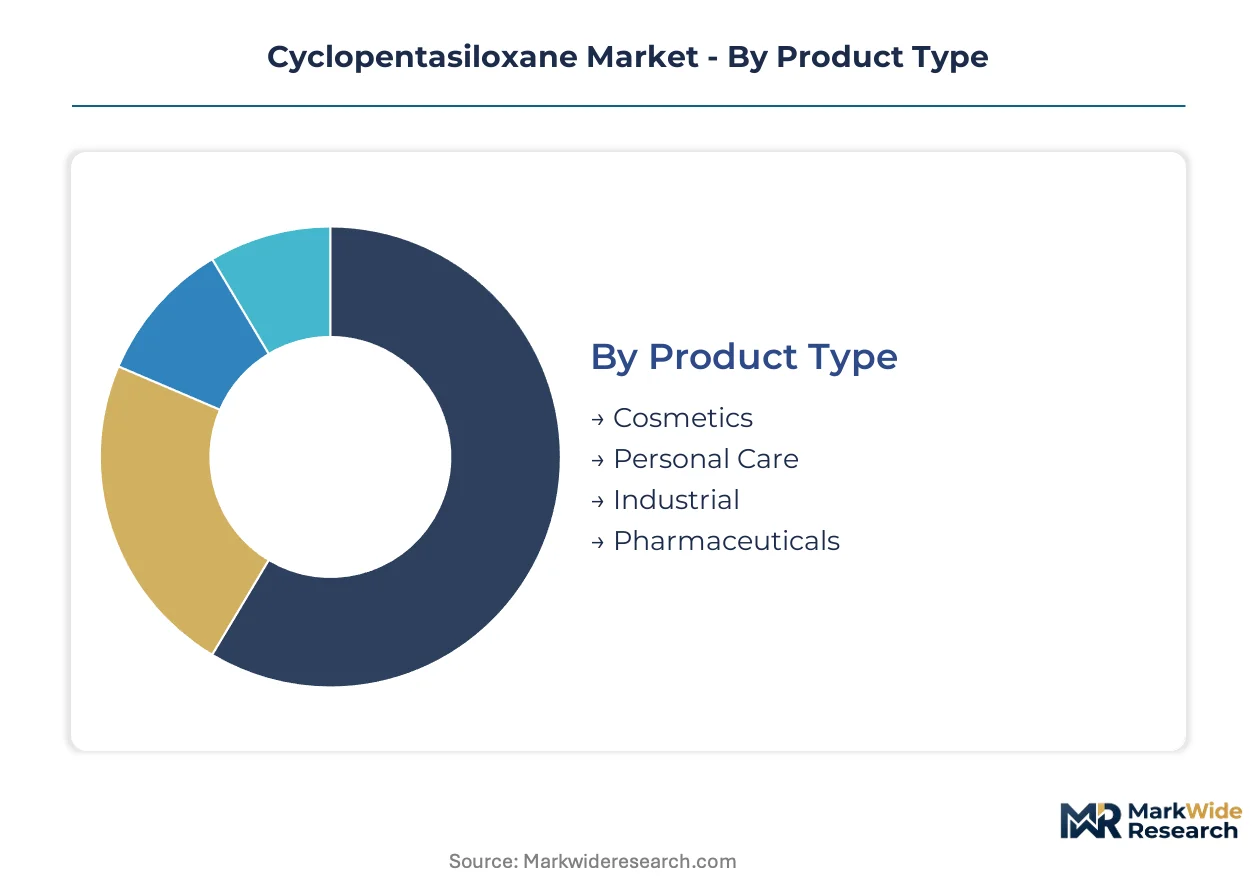
Cyclopentasiloxane procurement patterns diverge sharply by segment, with bulk industrial buyers negotiating long-term direct contracts while cosmetic formulators source through fragmented distributor networks. Channel selection directly determines margin capture and technical service intensity across each category.
Product Type:
Cosmetics-grade material flows predominantly through specialized chemical distributors with technical service capabilities, while industrial grades concentrate in direct sales channels with volume pricing structures.
- Cosmetics:Purity specifications above 99.5 percent define this tier, with residual monomer limits enforced under China's SAMR GB standards. South Korean formulators in Seoul and Busan drive demand for sensory-optimized grades in long-wear skin care formulations.
- Personal Care:REACH D5 concentration caps above 0.1 percent in leave-on products force European suppliers toward reformulated or hybrid volatile systems. This segment carries the steepest regulatory qualification burden across jurisdictions.
- Industrial:Film-forming speed and substrate compatibility determine process economics in surface treatment applications. Buyers prioritize consistent evaporation rates over cosmetic-grade purity thresholds.
- Pharmaceuticals:Transdermal drug delivery applications require qualification pathways distinct from cosmetic uses. Purity thresholds and documentation protocols exceed standard cosmetic specifications.
Cosmetics dominates installed base. Pharmaceuticals is where expansion concentrates.
End User:
Cost tier stratification separates integrated multinationals with captive technical teams from price-sensitive independents lacking formulation expertise.
- Manufacturers:Large-scale personal care producers in China's Shanghai and Guangzhou clusters negotiate directly with silicone suppliers, bypassing distributor markups. Their procurement volumes justify dedicated technical service attachments.
- Retailers:Indie cosmetic brands in North American markets source through online retail channels, prioritizing speed and small minimum order quantities over volume pricing. Technical service is typically unbundled from procurement.
- Distributors:Traditional chemical distribution networks retain relevance for mid-tier formulators requiring inventory management and just-in-time delivery across European and Asia-Pacific markets.
- Researchers:Academic and contract research organizations drive small-volume demand for experimental-grade material with specialized documentation requirements.
Manufacturers command volume concentration. Retailers represent the most rapidly diversifying procurement pattern.
Application:
Margin pools vary substantially by formulation complexity, with skin care commanding premium positioning and hair care competing on throughput scale.
- Skin Care:Microemulsion delivery systems miniaturizing droplet sizes below 100 nanometers enable deeper active penetration. Premium brands in South Korea and Japan adopt these systems at accelerated pace.
- Hair Care:Thinner technical specifications and higher volume throughput define this segment. Competition centers on cost efficiency rather than sensory differentiation.
- Antiperspirants:Volatile carrier functionality remains essential for dry-down performance. Regulatory scrutiny on cyclic siloxane bioaccumulation shapes product registration requirements in US markets under EPA oversight.
- Surface Treatments:Industrial applications prioritize film-forming speed and substrate compatibility. Process economics depend on consistent evaporation behavior rather than cosmetic-grade aesthetics.
Skin Care commands deepest margin pools. Surface Treatments is gaining share fastest in industrial procurement.
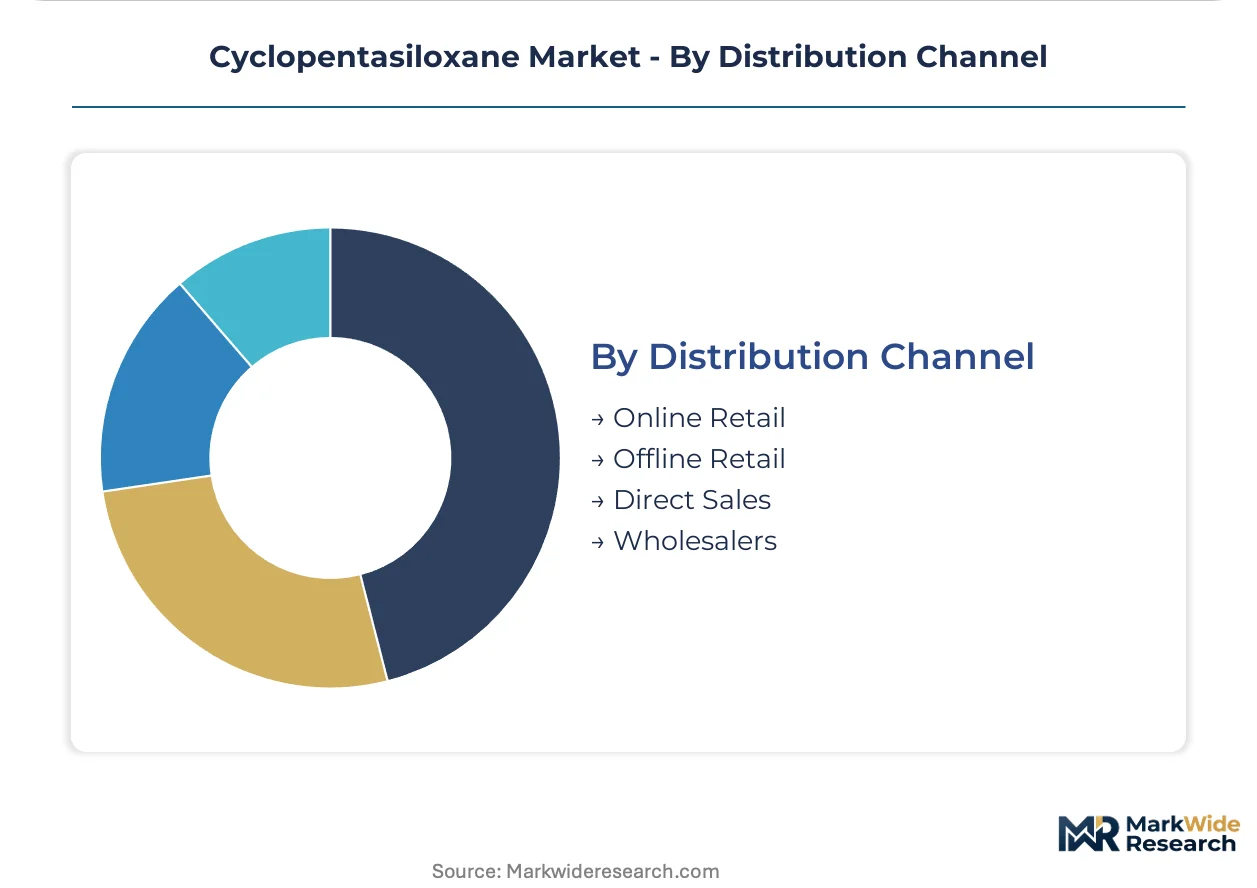
Distribution Channel:
Customer type and geography determine channel selection, with established formulators favoring direct relationships and emerging players seeking transactional flexibility.
- Online Retail:Indie cosmetic brands lacking established distributor relationships migrate procurement toward digital platforms. This shift compresses minimum order quantities and accelerates sourcing timelines.
- Offline Retail:Traditional chemical distributors retain relevance for mid-tier manufacturers requiring technical consultation and inventory management across European supply chains.
- Direct Sales:Bulk pharmaceutical and industrial procurement flows through long-term supply agreements with integrated silicone producers. Technical service is embedded in contract structures.
- Wholesalers:Regional formulators in underpenetrated ASEAN markets access material through wholesale networks bridging supply concentration in China with dispersed demand in Indonesia and Vietnam.
Direct Sales anchors volume throughput. Online Retail is where channel innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized silicone intermediates to South Korean cosmetic formulators, establishing a trans-Eurasian trade corridor that channels European chemical engineering into Asia-Pacific personal care manufacturing.
China
Domestic personal care brands in Shanghai and Guangzhou manufacturing clusters scale production capacity for long-wear skin care formulations. SAMR enforces GB standards for cosmetic raw material safety with residual monomer limits that qualified suppliers must meet. Coastal production zones concentrate demand as indigenous brands capture market share from multinational incumbents.
South Korea
Seoul and Busan formulators drive volatile silicone consumption in K-beauty export products targeting North American and Southeast Asian consumers. MFDS regulates cosmetic ingredient safety with purity thresholds that align with premium brand positioning. The Seoul Capital Area anchors formulation R&D while Busan-Ulsan handles bulk chemical processing.
Germany
Wacker Chemie AG maintains specialized silicone manufacturing scale serving European pharmaceutical and industrial customers. ECHA administers REACH authorization processes restricting D5 concentrations above 0.1 percent in leave-on cosmetics. The Bavaria and North Rhine-Westphalia chemical corridors concentrate cyclic siloxane synthesis expertise.
United States
Indie cosmetic brands migrate procurement toward online retail channels, bypassing traditional chemical distributor networks. EPA scrutiny of cyclic siloxane bioaccumulation shapes product registration requirements for personal care ingredients. The California personal care manufacturing base leads adoption of microemulsion delivery systems.
Japan
Premium skin care brands in Tokyo and Osaka accelerate adoption of sub-100 nanometer droplet microemulsion systems. METI oversees chemical substance management with standards that exceed baseline international requirements. The Kanto region concentrates formulation science capabilities while Kansai maintains historical silicone processing infrastructure.
Cyclopentasiloxane Market Competitive Landscape
Listed leaders compete with private specialists across capital access and technical service intensity. The vendor base consolidates around integrated chemical conglomerates with captive silane feedstock positions and independent formulators serving niche cosmetic applications. Three archetypes dominate: backward-integrated multinationals with global manufacturing footprints, regional specialists with application-specific technical service, and private-label suppliers competing on minimum order flexibility. Capacity expansion in Asia-Pacific manufacturing zones and portfolio diversification into hybrid volatile systems constitute the dominant competitive moves.
Within the integrated multinational tier, Dow Chemical Company and Wacker Chemie AG exemplify backward integration into silane feedstocks that sustains margin control across raw material cycles. BASF SE anchors the application-specific technical service archetype, occupying a position where rapid emulsion development support differentiates procurement relationships with personal care formulators. Shin-Etsu Silicones represents the Asia-Pacific manufacturing scale vector, sitting within a geographic concentration of demand growth.
| Leading Market Players |
|---|
| KCC Beauty |
| BASF SE |
| Dow Chemical Company |
| Grant Industries Inc. |
| Evonik Industries |
| Wacker Chemie AG |
| Momentive Performance Materials Inc. |
| Kobo Products Inc. |
| Shin-Etsu Silicones |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with take-or-pay provisions lock in silane feedstock access and price visibility for integrated producers, insulating margin positions against raw material volatility while constraining flexibility for non-integrated buyers facing spot market exposure.
Pricing Analysis
Cosmetic-grade versus industrial-grade purity thresholds generate a technology-generation pricing gap that separates premium specification holders from commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by purity certification, volume scale, and technical service bundling. Cost compression in standard grades is intensifying because Chinese domestic brands scale manufacturing and negotiate direct supplier relationships. Indie cosmetic formulators represent the most price-sensitive segment, while pharmaceutical transdermal developers accept premium positioning for qualification documentation.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows from German silicone synthesis facilities to Asia-Pacific formulation centers, creating logistical exposure for just-in-time cosmetic chemical procurement. Supply concentrates in Germany, China, and South Korea, with cyclic siloxane manufacturing expertise anchored in Bavarian chemical corridors and Busan-Ulsan industrial zones. The chain draws from silane monomer, methyl chloride, and copper catalyst feedstocks. Single-source vulnerability in specialized silicone intermediates threatens continuity for European formulators facing REACH substitution timelines. Distribution runs through direct sales for bulk pharmaceutical and industrial buyers, with specialized chemical distributors serving cosmetic formulators requiring technical consultation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cyclopentasiloxane demand is entering a cyclical recovery phase as K-beauty export momentum and pharmaceutical-grade qualification expansion restore volume growth after regulatory compression in European markets.
For Market Incumbents: Consolidate backward integration into silane feedstocks to defend margin positions against raw material volatility and dimethicone substitution pressure from clean beauty positioning. Prioritize capacity qualification under China's SAMR GB standards to capture first-mover advantage in Shanghai and Guangzhou manufacturing clusters. Lock in long-term offtake agreements with South Korean formulators to secure premium-grade volume commitments. For New Entrants and Emerging Players: Lead with pharmaceutical-grade purity qualification above 99.5 percent to access transdermal drug delivery applications with distinct regulatory pathways and limited incumbent presence. Target Indonesian and Vietnamese cosmetic manufacturers lacking established distributor relationships, deploying direct technical service models that bypass traditional chemical distribution networks. Emphasize rapid emulsion development support as the go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with application-specific technical service capabilities and qualified inventory positions under multiple regulatory jurisdictions. Long-term viability centers on hybrid volatile system development capacity and Asia-Pacific manufacturing footprint expansion. Watch for SAMR enforcement acceleration on residual monomer limits as the inflection signal indicating qualification-driven consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Feedstocks | Dow Chemical Company and Wacker Chemie AG sustain margin control across raw material cycles through captive supply positions. |
| Pharmaceutical-Grade Qualification Investment | Purity thresholds above 99.5 percent open transdermal drug delivery applications with distinct SAMR and FDA regulatory pathways. |
| Hybrid Volatile System Development | REACH D5 concentration caps force reformulation strategies that preserve functional performance in European leave-on cosmetics. |
| Direct Technical Service Model Deployment | Indonesian and Vietnamese formulators lack distributor relationships, creating channel innovation potential for qualified suppliers. |
| China SAMR GB Standard Alignment | Residual monomer limits and cosmetic raw material safety enforcement create first-mover advantage for qualified inventory holders in Shanghai and Guangzhou clusters. |
Research Methodology
Initial hypotheses were tested against primary input from silicone plant managers, cosmetic formulation R&D directors, personal care procurement leads, and chemical distribution channel partners and refined through secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and SAMR regulatory disclosure databases. Bottom-up volume modeling triangulated with top-down value chain analysis to ensure consistency across estimation approaches.
Variance decomposition across purity grade tier, end-use application, regional production hub, and distribution channel structure shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions calibrated to disclosed contract structures and spot market indicators. Silane feedstock price indices and REACH regulatory timeline scenarios constituted key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained K-beauty export momentum, SAMR enforcement acceleration, or REACH substitution compliance timelines would require recalibration. Forecasts reflect documented assumptions regarding regulatory divergence persistence and raw material cycle positioning. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Asia Pacific Surfactants Market
Surfactants
Coconut Derived Surfactants Market
Surfactants
Tetrabutylammonium Bromide Market
Surfactants
Trisiloxane Market
Surfactants
Benzyl Trimethyl Ammonium Chloride Market
Surfactants
Detergent Chemicals Market
Surfactants
Sodium Cumenesulfonate Market
Surfactants
Sodium Lauroyl Sarcosinate Market
Surfactants
Dioctyl Sulfosuccinates Components Market
Surfactants
Global Fluorosurfactants Market
Surfactants
Cationic Surfactants Market
Surfactants
Alcohol Ether Sulfates Market
Surfactants
Dispersant Market
Surfactants
Polysorbate 40 Market
Surfactants
Soy-Based Surfactants Market
Surfactants
Sodium Lauryl Sulphate Market