
 Gas Calorimeter Market | 2026-2036
Gas Calorimeter Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Calorimeter Market Foresight
End-use demand is shifting from laboratory-based fuel analysis toward continuous online monitoring at pipeline interconnection points and LNG regasification terminals. Yokogawa Electric Corporation dominates precision instrumentation for Asian energy infrastructure, leveraging decades of process automation integration. Emerson Electric Co. anchors North American market presence through distributed control system compatibility, while Honeywell International Inc. competes on embedded sensor platforms that reduce calibration frequency.
A gas calorimeter measures the heat of combustion or calorific value of gaseous fuels using thermal equilibrium, infrared absorption, or direct combustion methods, typically achieving measurement uncertainties below 0.1 percent for custody transfer applications. Stationary online systems lead installed base value due to permanent pipeline integration and regulatory mandate coverage, though portable units represent the fastest-growing category for field audit and spot-check deployment. Combustion technology occupies the premium tier where custody transfer accuracy is mandatory, while infrared segments attract replacement demand from facilities seeking lower maintenance overhead.
EPA greenhouse gas reporting rules and EU F-Gas Regulation shape product specifications by mandating traceable measurement uncertainty and restricting certain heat transfer fluid chemistries. Japan's METI enforces city gas interchangeability standards that require real-time calorific value adjustment at gate stations. Stakeholders must monitor evolving hydrogen blending specifications, as calorimeter manufacturers face redesign requirements for variable-Wobbe-index fuel streams.
Market Dynamics
Pipeline operators are replacing batch laboratory testing with continuous online calorimetry to satisfy real-time gas interchangeability mandates. This infrastructure upgrade cycle is compressing replacement timelines and elevating accuracy specifications across custody transfer points.
Growth Catalysts
- EPA Greenhouse Gas Reporting:Mandatory traceable measurement uncertainty for large combustion sources drives upgrades to combustion-technology calorimeters with certified accuracy below 0.1 percent.
- LNG Regasification Terminals:Terminal operators require real-time calorific value verification at unloading arms to manage Wobbe index variations during cargo blending operations.
- Hydrogen Blending Trials:Germany and Japan are testing variable-calorific fuel streams that force calorimeter redesign for dual-fuel compatibility at city gate stations.
Market Restraints
- Platinum Catalyst Supply:Combustion calorimeters depend on platinum-based sensors concentrated in South African and Russian supply chains, exposing manufacturers to price volatility and export restrictions.
- EU F-Gas Heat Transfer Fluids:Restrictions on fluorinated greenhouse gases used in thermal equilibrium instruments are forcing premature obsolescence of installed base units before full depreciation.
- Infrared Spectroscopy Substitution:Lower-maintenance infrared units are capturing replacement demand from facilities that previously specified combustion technology for non-custody applications.
Strategic Opportunities
- India City Gas Distribution:The country's Petroleum and Natural Gas Regulatory Board mandates calorific value monitoring at all CNG stations and domestic city gate points, creating greenfield demand.
- Embedded Sensor Convergence:Integration of MEMS thermal sensors with edge computing enables predictive calibration algorithms that reduce field service frequency.
- Portable Audit Segment:Pipeline integrity programs require spot-check verification at interconnection points, expanding the fastest-growing product category beyond permanent installations.
Industry Challenges
- Metrology Talent Scarcity:Custody transfer certification requires technicians trained in ISO 17025 uncertainty analysis, a skill set concentrated in aging specialist workforces across Germany and Japan.
- Legacy System Integration:Online calorimeters must interface with existing distributed control systems through proprietary protocols, extending commissioning timelines at brownfield sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Calorimeter Market |
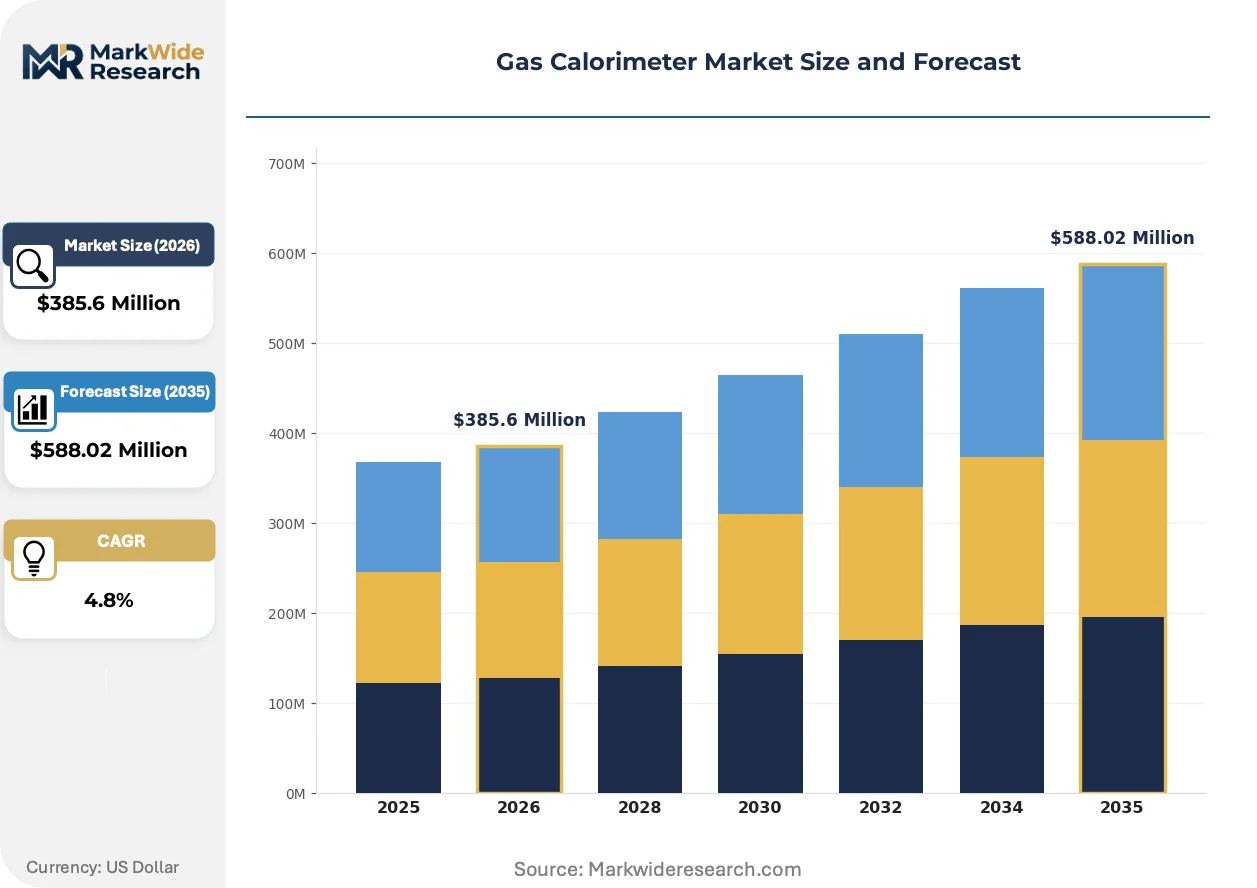
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Online, Laboratory Technology: Infrared, Thermal Conductivity, Electrical Resistance, Combustion End User: Industrial, Research Institutions, Environmental Agencies, Energy Providers Application: Fuel Analysis, Emissions Testing, Research, Quality Control |
| Companies Covered | Yokogawa Electric Corporation, Emerson Electric Co., Honeywell International Inc., Siemens AG, Azbil Corporation, RIKEN KEIKI Co., Ltd., ABB Ltd., AMETEK, Inc., Endress+Hauser AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Calorimeter Market Shifts & Advancements
Measurement hardware is converging with digital infrastructure to enable autonomous calibration and predictive maintenance. This shift is elevating software and service revenue streams relative to instrument sales alone.
Micro-electromechanical systems are integrating thermal conductivity sensors with on-chip temperature compensation. LNG terminal operators are adopting these compact modules for containerized measurement skids. The technology is integrating real-time drift correction that eliminates manual span adjustments, compressing total cost of ownership for unmanned facilities.
Japan's METI has tightened city gas interchangeability enforcement through revised technical standards requiring 15-minute rolling average calorific value reporting. Pipeline operators must now install redundant measurement chains with automatic failover. Gate stations in Tokyo and Osaka are responding by specifying dual-path combustion calorimeters with hot-standby redundancy.
Buying committees are unbundling hardware procurement from calibration service contracts. Energy majors now source instruments through capital budgets while contracting third-party metrology firms for traceability maintenance. This bifurcation is most visible in German municipal utilities, where separate tender processes for equipment and ISO 17025-accredited service are becoming standard practice.
Gas Calorimeter Market Segmentation
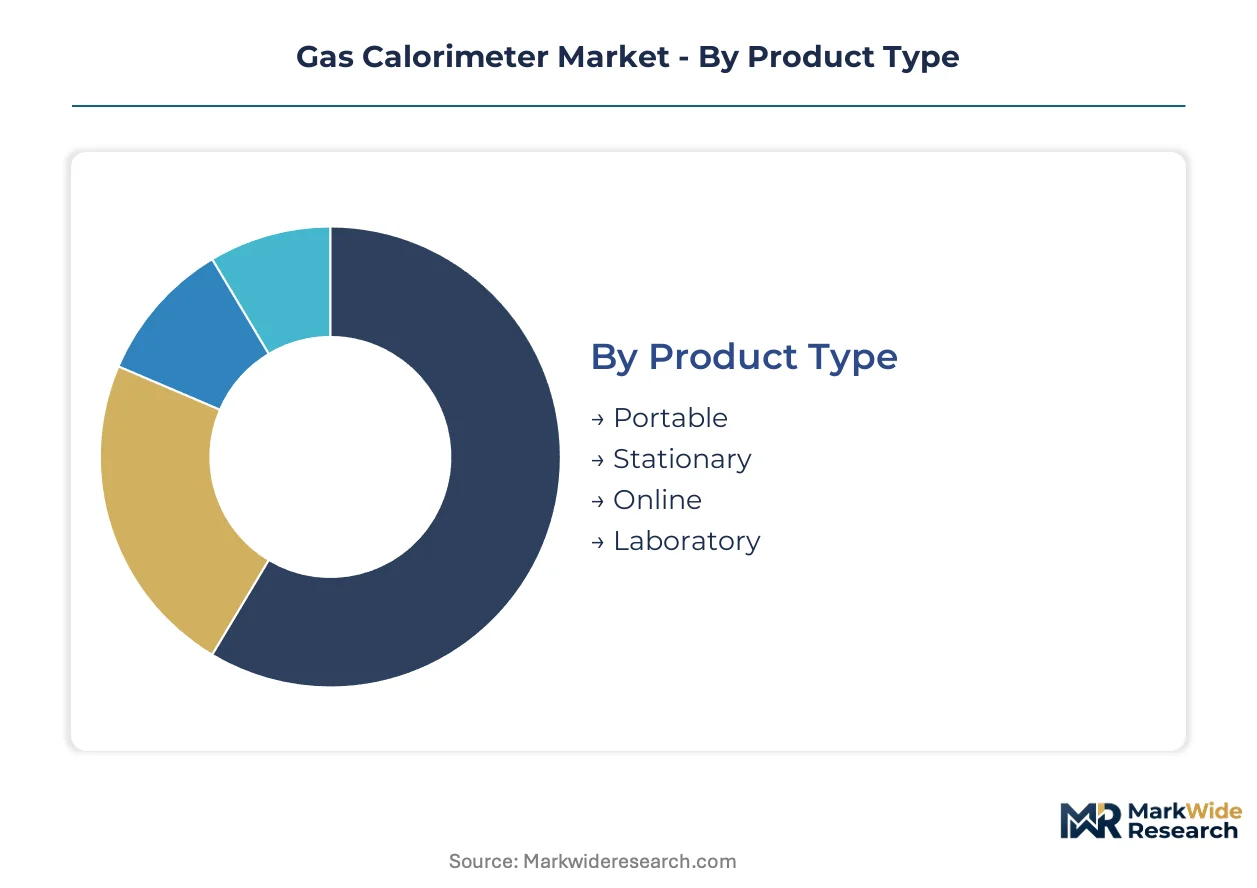
Gas calorimeter segmentation reflects competing demands for measurement precision, deployment flexibility, and regulatory compliance across custody transfer and non-custody applications. Technology choice and product architecture determine capital intensity, maintenance burden, and suitability for hydrogen-blended fuel streams.
Product Type:
Stationary and online systems anchor pipeline infrastructure investments, while portable units address emerging spot-check mandates.
- Stationary:Permanent installations at city gate stations and LNG terminals deliver continuous calorific value verification with hot-standby redundancy for regulatory failover. Demand concentrates in Germany and Japan where METI and network codes mandate 15-minute rolling average reporting.
- Online:Real-time measurement chains integrate directly with distributed control systems for automated Wobbe index adjustment during cargo blending operations. Energy providers in the United States deploy these at interstate pipeline interconnection points to satisfy FERC interchangeability standards.
- Portable:Field audit units enable pipeline integrity programs to verify custody transfer accuracy without permanent infrastructure.
- Laboratory:Batch analysis systems serve reference calibration and research applications with highest precision specifications.
Mature deployment sits with Stationary systems. Newer deployment is concentrated in Online configurations.
Technology:
Measurement principle selection trades accuracy against maintenance overhead and supply chain exposure.
- Combustion:Direct burning of sample gas achieves sub-0.1 percent uncertainty for custody transfer applications through platinum-catalyzed reaction chambers. EPA greenhouse gas reporting rules in the United States mandate this technology for large combustion sources requiring traceable measurement chains.
- Infrared:Absorption spectroscopy eliminates consumable catalysts and reduces field service frequency, attracting replacement demand from facilities that previously specified combustion units for non-custody applications.
- Thermal Conductivity:MEMS-integrated sensors with on-chip temperature compensation enable compact containerized skids for unmanned LNG terminals.
- Electrical Resistance:Resistance-based thermal equilibrium methods serve legacy installations facing EU F-Gas Regulation obsolescence pressures.
Premium-tier revenue concentrates with Combustion technology. Infrared configurations are gaining share fastest among replacement cycles.
End User:
Customer type determines specification stringency, procurement channel, and service contract structure.
- Energy Providers:Pipeline operators and LNG terminal owners drive volume through mandatory custody transfer infrastructure, unbundling hardware procurement from third-party metrology service contracts.
- Industrial:Manufacturing facilities with on-site power generation require calorific value monitoring for fuel optimization and emissions compliance.
- Environmental Agencies:Regulatory enforcement bodies specify reference-grade instrumentation for compliance auditing and standard-setting.
- Research Institutions:National metrology laboratories maintain primary standards for calibration traceability chains.
Capital deployment leadership sits with Energy Providers. Fastest expansion is appearing in Industrial captive power applications.
Application:
Use case segmentation maps to regulatory mandate intensity and measurement uncertainty requirements.
- Fuel Analysis:Calorific value determination for custody transfer and billing reconciliation demands highest accuracy tiers with ISO 17025-accredited traceability.
- Quality Control:Gate station monitoring for city gas interchangeability requires real-time Wobbe index verification to prevent appliance malfunction.
- Emissions Testing:Stationary source compliance monitoring under EPA rules links calorimeter data to greenhouse gas inventory calculations.
- Research:Hydrogen blending trials in Germany and Japan depend on variable-calorific fuel stream characterization for dual-fuel compatibility validation.
Established revenue sits with Fuel Analysis. Steepest expansion trajectory is emerging in Research applications tied to hydrogen infrastructure testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and Japan where precision instrumentation heritage meets pipeline infrastructure investment, while demand expansion accelerates in India and the United States driven by regulatory mandates and LNG terminal buildouts.
Germany
Pipeline operators at city gate stations drive combustion calorimeter deployment for hydrogen blending trials mandated under national energy transition policy. The EU F-Gas Regulation forces premature replacement of thermal equilibrium units using restricted heat transfer fluids. Industrial clusters in North Rhine-Westphalia and Bavaria anchor calorimeter integration into chemical plant fuel optimization systems.
United States
EPA greenhouse gas reporting rules mandate traceable measurement uncertainty below 0.1 percent for large combustion sources, elevating specification stringency at interstate pipeline interconnection points. FERC interchangeability standards require real-time calorific value verification. Gulf Coast LNG terminals deploy online systems for Wobbe index management during cargo blending operations.
Japan
METI enforces 15-minute rolling average calorific value reporting through revised city gas interchangeability technical standards. Pipeline operators in Tokyo and Osaka install redundant measurement chains with automatic failover capability. Yokohama and Chiba industrial zones drive demand for embedded sensor platforms in unmanned gate station configurations.
India
The Petroleum and Natural Gas Regulatory Board mandates calorific value monitoring at all CNG stations and domestic city gate points, creating greenfield infrastructure demand. City gas distribution expansion targets 100 new geographical areas under national pipeline connectivity programs. Gujarat and Maharashtra lead deployment with compressed commissioning timelines at brownfield industrial zones.
China
National pipeline operators accelerate online calorimeter adoption for custody transfer standardization across provincial natural gas networks. MIIT industrial fuel quality standards elevate measurement traceability requirements for steel and chemical sector emissions compliance. Yangtze River Delta LNG receiving terminals integrate real-time monitoring for spot cargo quality verification.
Gas Calorimeter Market Competitive Landscape
Top-tier vendors anchor custody transfer applications with certified accuracy below 0.1 percent, while mid-tier specialists compete on maintenance reduction and embedded sensor convergence. The vendor base stratifies across precision instrumentation conglomerates, process automation integrators, and MEMS sensor specialists. Three archetypes dominate: combustion technology purists, infrared spectroscopy converts, and MEMS-integrated platform builders. Competitive moves concentrate on backward integration into platinum catalyst supply chains and predictive calibration software licensing.
Within the precision instrumentation tier, Yokogawa Electric Corporation and Emerson Electric Co. occupy positions shaped by decades of process automation integration. Honeywell International Inc. exemplifies the embedded sensor convergence archetype. Siemens AG and ABB Ltd. represent European-based industrial conglomerates with distributed control system compatibility. Azbil Corporation and RIKEN KEIKI Co., Ltd. anchor Japanese specialist positioning. AMETEK, Inc. and Endress+Hauser AG sit within the metrology-focused instrumentation segment.
| Leading Market Players |
|---|
| Yokogawa Electric Corporation |
| Emerson Electric Co. |
| Honeywell International Inc. |
| Siemens AG |
| Azbil Corporation |
| RIKEN KEIKI Co., Ltd. |
| ABB Ltd. |
| AMETEK, Inc. |
| Endress+Hauser AG |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between ISO 17025-accredited custody transfer systems and non-certified process monitoring units manifests in both pricing power and supply chain sourcing strategies. Premium combustion calorimeters with platinum-catalyzed reaction chambers command sustained margins through South African and Russian platinum dependencies, while infrared alternatives compete on shorter lead times and reduced field service burden.
Pricing Analysis
Short lead time premiums dominate procurement negotiations, with emergency replacement orders for combustion calorimeters attracting significant markups over standard delivery schedules. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with EPA-mandated traceability tiers commanding highest price realization. Cost compression in mid-tier infrared segments is intensifying because MEMS thermal conductivity alternatives are displacing legacy thermal equilibrium units. Industrial captive power operators exhibit highest price sensitivity, while LNG terminal operators prioritize accuracy over unit economics.
Supply Chain Analysis
Freight cost escalation on platinum catalyst shipments from South African refineries and Russian export terminals is elevating landed costs for combustion technology manufacturers. Manufacturing concentrates in Germany and Japan where precision instrumentation heritage meets domestic pipeline infrastructure investment. Platinum catalyst supply, MEMS sensor wafers, and specialized heat transfer fluids constitute critical input dependencies. Single-source vulnerability in platinum supply chains exposes manufacturers to export restriction risk. Distribution runs through process automation integrators and third-party metrology service firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with captive platinum sourcing and predictive calibration software capabilities. EU F-Gas Regulation obsolescence pressures are forcing weaker thermal equilibrium specialists toward exit or acquisition.
For Market Incumbents: To counter infrared spectroscopy substitution in non-custody applications, deepen backward integration into platinum catalyst supply chains and accelerate embedded sensor convergence with edge computing platforms. Lock in long-term service contracts with German municipal utilities before third-party metrology firms capture calibration revenue streams. For New Entrants and Emerging Players: Distribution channel partners in India's city gas distribution expansion represent the most penetrable entry vector. Target brownfield industrial zones in Gujarat and Maharashtra where compressed commissioning timelines favor agile integrators over established incumbents. Lead with portable audit units for pipeline integrity programs where field service frequency requirements are lowest. For Investors and Strategic Acquirers: Re-rating potential sits with MEMS-integrated platform builders given hydrogen blending trial momentum across Germany and Japan. Five-to-ten-year viability favors vendors with dual-fuel combustion calorimeter architectures already validated in METI-supervised gate station deployments. Watch for 15-minute rolling average reporting mandate expansion beyond Tokyo and Osaka as the signal indicating accelerated replacement cycle onset.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Platinum Catalyst Supply | Captive sourcing from South African refineries insulates margin structure against export restriction volatility. |
| Predictive Calibration Software Licensing | MEMS thermal sensor integration with edge computing reduces field service frequency for unmanned LNG terminals. |
| Hydrogen Blending Compatibility Certification | Dual-fuel validation under METI technical standards positions vendors for Germany's energy transition infrastructure. |
| Third-Party Metrology Service Acquisition | ISO 17025-accredited calibration capability captures unbundled service contracts from German municipal utilities. |
| Portable Audit Unit Platform Development | Spot-check verification demand from pipeline integrity programs expands fastest-growing product category beyond permanent installations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with pipeline operations directors, LNG terminal instrumentation managers, third-party metrology service heads, and OEM procurement leads at distributed control system integrators. EPA greenhouse gas reporting databases, EU F-Gas Regulation implementation records, Japan METI technical standard revisions, and India Petroleum and Natural Gas Regulatory Board mandates provided regulatory traceability. Bottom-up unit deployment tracking across city gate stations and LNG terminals triangulated against top-down energy infrastructure investment forecasts.
Segment-level modeling addressed product architecture, measurement technology, end-user procurement channel, and application regulatory intensity across the analysis window. Technology choice parameters incorporated platinum catalyst supply constraints, MEMS sensor yield curves, and hydrogen blending trial expansion trajectories. CAGRs derived from infrastructure replacement cycle compression and regulatory mandate phase-in schedules. LNG regasification terminal buildout pipelines and city gas distribution geographical area allocations informed regional demand allocation.
Caveats apply where platinum export restrictions, EU F-Gas Regulation enforcement acceleration, or hydrogen blending standard revisions could materially shift the outlook. Forecasts reflect assumptions about regulatory mandate adherence timelines and infrastructure commissioning cadence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Lab Supplies Market
Testing Equipment
Supercritical Fluid Chromatography (SFC) System Market
Testing Equipment
Particle Size Analysis Market
Testing Equipment
Polymer Testing Equipment Market
Testing Equipment
Rheometer Market
Testing Equipment
Global Residue Testing Market
Testing Equipment
US Eddy-Current Testing Market
Testing Equipment
Chemical Testing Services Market
Testing Equipment
Water Test Kits Market
Testing Equipment
Membrane Osmometer Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
HPLC Market
Testing Equipment
Salt Spray Chamber Market
Testing Equipment
Elemental Analysis Market
Testing Equipment
Glass Testing Instruments Market
Testing Equipment
Water Analysis Instruments Market