
 Lactose Assay Kit Market | 2026-2036
Lactose Assay Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Lactose Assay Kit Market Foresight
Reagent subscription programs and annual calibration services are pivoting how vendors monetize lactose assay workflows. Thermo Fisher Scientific leverages its global distribution network to bundle consumables with instrument service contracts. Megazyme anchors its competitive stance through specialized enzyme formulations for dairy matrices. Bio-Rad Laboratories differentiates via integrated software platforms that automate absorbance data interpretation.
A lactose assay kit comprises enzyme-coupled reagent systems—typically beta-galactosidase and glucose oxidase formulations stabilized in phosphate buffer—designed to quantify lactose concentration in complex biological or food matrices through photometric endpoint detection. Enzymatic assay formats dominate routine quality control due to established AOAC validation and broad instrument compatibility, while fluorometric assay configurations capture the fastest growth trajectory among pharmaceutical developers seeking enhanced sensitivity for low-concentration lactose excipient verification. Colorimetric assay demand concentrates within academic institutions prioritizing cost-per-test economy over throughput.
FDA nutrition labeling enforcement and EU Regulation 1169/2011 allergen disclosure mandates compel food manufacturers to document lactose content with validated analytical methods. ISO 17025 laboratory accreditation requirements in major dairy-exporting nations further standardize kit performance claims and inter-laboratory comparability. Stakeholders must weigh the capital efficiency of open-platform reagent subscriptions against locked-in consumable ecosystems when selecting long-term assay partners.
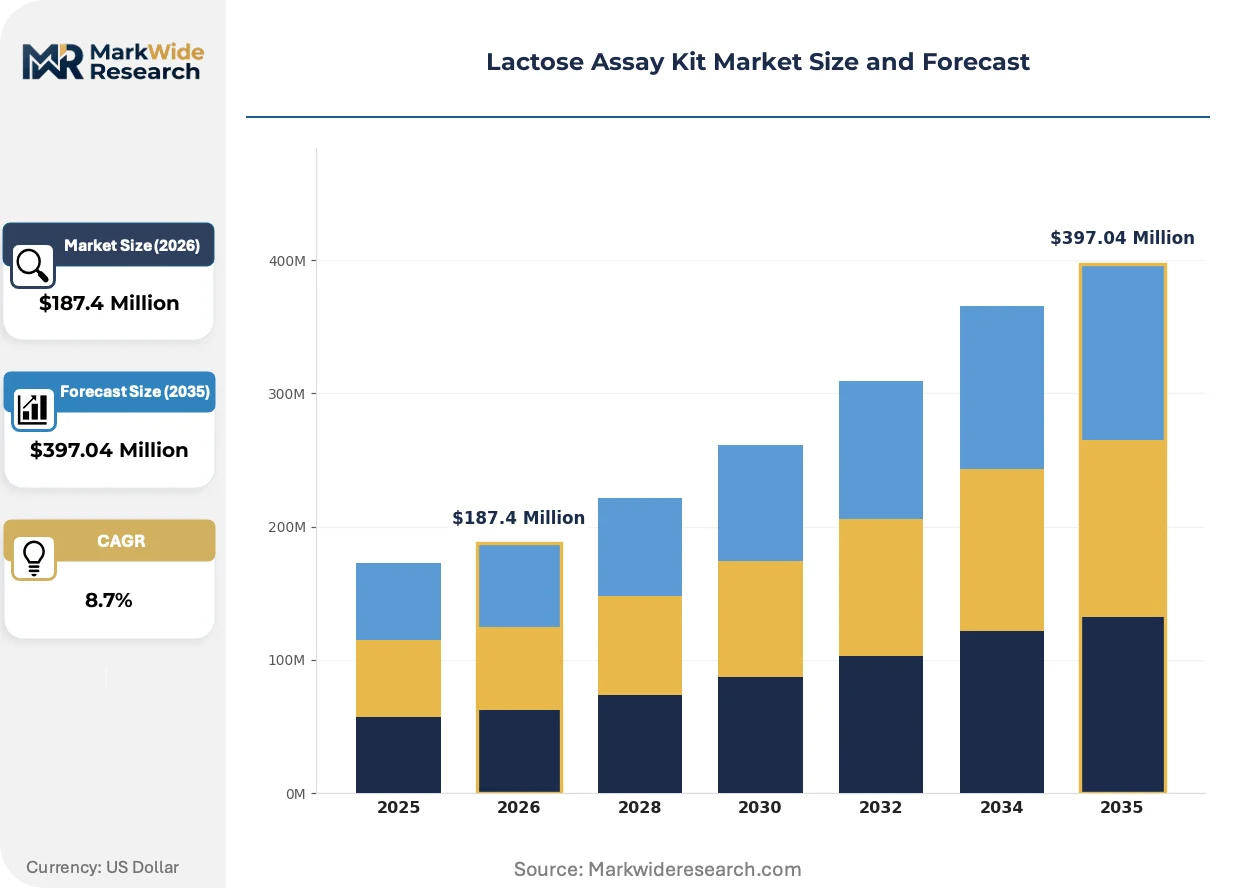
Market Dynamics
Enzymatic detection methods are systematically displacing gravimetric techniques across dairy quality control workflows, driven by AOAC validation requirements and ISO 17025 laboratory accreditation mandates that now govern procurement decisions at food manufacturers and contract testing laboratories worldwide.
Growth Catalysts
- FDA Nutrition Labeling Enforcement:Food manufacturers must document lactose content with validated analytical methods, creating mandatory kit replacement cycles at processing facilities across the United States.
- EU Regulation 1169/2011 Allergen Disclosure:Dairy exporters into European markets face compulsory lactose quantification, expanding addressable demand for standardized assay formats.
- Enzyme Stabilization Advances:Phosphate-buffered beta-galactosidase formulations now maintain activity across broader temperature ranges, reducing cold-chain dependency in emerging market deployments.
Market Restraints
- Specialized Enzyme Supply Concentration:High-purity glucose oxidase production concentrates among a limited supplier base, exposing kit manufacturers to input cost volatility and allocation risk.
- Fluorometric Instrument Capital Requirements:Pharmaceutical developers seeking enhanced sensitivity for lactose excipient verification face six-figure capital outlays for detection platforms, constraining adoption velocity.
- Gravimetric Method Persistence:Academic institutions and smaller dairy cooperatives continue leveraging legacy techniques where cost-per-test economy outweighs throughput requirements.
Strategic Opportunities
- Indian Dairy Processing Expansion:FSSAI implementation of stricter compositional standards for packaged milk products creates unmet demand for accredited assay workflows at mid-sized cooperatives.
- Plant-Based Dairy Analogue Testing:Oat, almond, and soy milk manufacturers require lactose verification to substantiate allergen-free claims, opening adjacent application verticals.
- Reagent Subscription Monetization:Annual calibration bundles and consumable auto-replenishment programs capture recurring revenue streams from instrument-installed bases.
Industry Challenges
- ISO 17025 Accreditation Timeline Compression:Contract laboratories face 12-18 month certification windows that delay kit vendor qualification and contract award cycles.
- Multi-Instrument Software Integration:Absorbance data interpretation platforms must interface with legacy LIMS architectures at food manufacturers, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactose Assay Kit Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymatic Assay, Colorimetric Assay, Fluorometric Assay, Conductometric Assay Application: Dairy Industry, Food & Beverage Testing, Clinical Diagnostics, Pharmaceutical Development End User: Food Manufacturers, Research Laboratories, Hospitals, Academic Institutions Distribution Channel: Online Stores, Direct Sales, Distributors, Retail Outlets |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Agilent Technologies, Megazyme, Bio-Rad Laboratories, BioAssay Systems, Abcam plc, R-Biopharm AG, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactose Assay Kit Market Shifts & Advancements
Photometric endpoint detection architectures are giving way to multiplexed assay configurations that simultaneously quantify lactose alongside other dairy carbohydrates, compressing per-sample analytical costs and turnaround times.
Fluorometric assay sensitivity thresholds are converging with pharmaceutical excipient verification requirements, enabling picomolar-level lactose detection in parenteral formulations. Biologics manufacturers at CDMO facilities adopt these platforms to satisfy USP monograph specifications. The technology is compressing the gap between food-grade and pharmaceutical-grade assay capabilities.
EU Regulation 1169/2011 enforcement is intensifying at member-state level, with food safety authorities in Germany, France, and Italy conducting unannounced lactose labeling audits at dairy import facilities. Processors serving multiple European markets now standardize on dual-validated enzymatic methods to preempt regulatory fragmentation. This policy pressure is accelerating kit replacement cycles among exporters.
Buying patterns among contract testing laboratories now favor outcome-based service contracts that bundle reagent supply with instrument uptime guarantees. Traditional consumable resale margins compress as vendors absorb calibration and maintenance obligations. This model shift concentrates procurement authority at multi-site laboratory networks in North America and Western Europe.
Lactose Assay Kit Market Segmentation
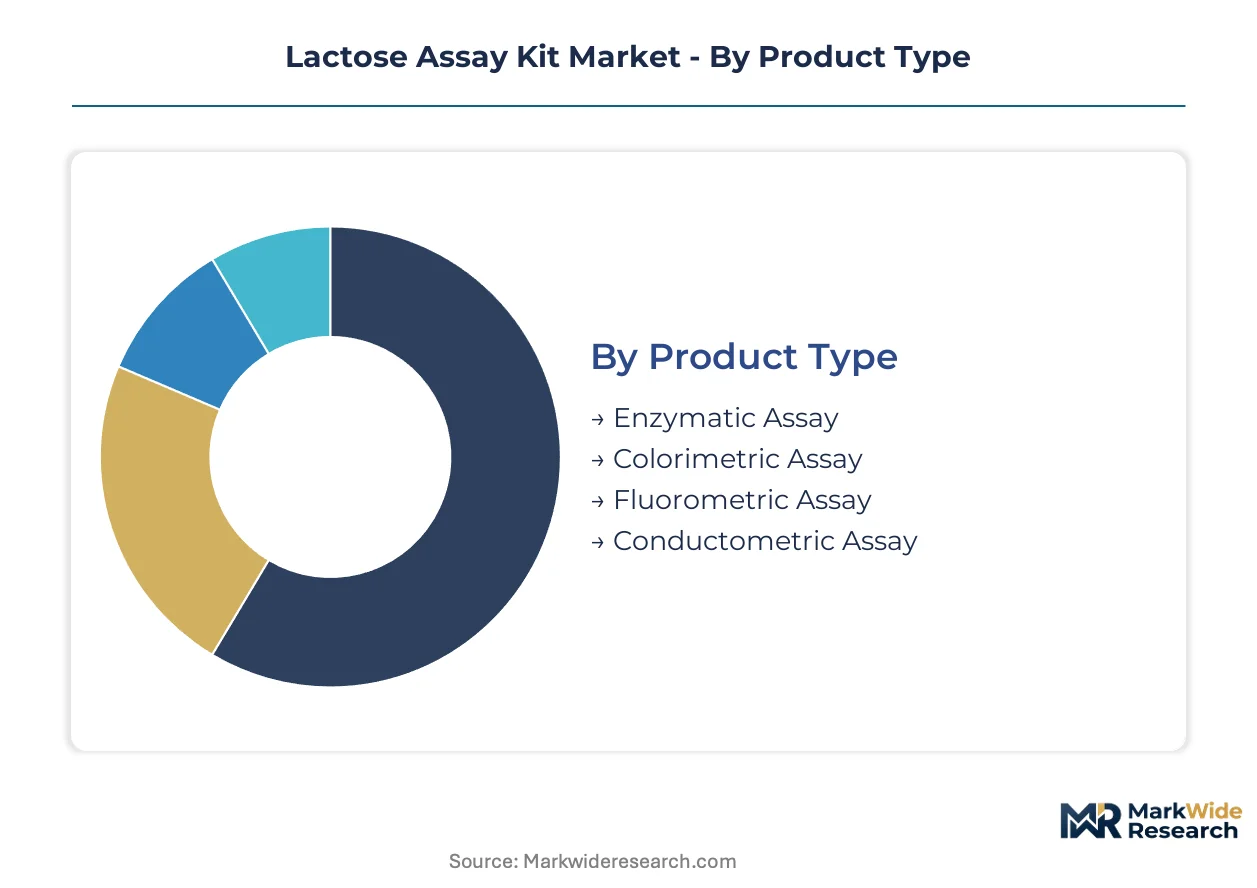
Lactose assay kit procurement varies sharply by detection sensitivity requirements and regulatory compliance burden. Dairy processors prioritize validated enzymatic formats for routine quality control, while pharmaceutical developers demand fluorometric sensitivity thresholds for excipient verification.
Product Type:
Enzymatic formats command the volume tier through AOAC-validated workflows, while fluorometric configurations capture premium pricing through pharmaceutical-grade specifications.
- Enzymatic Assay:Beta-galactosidase and glucose oxidase formulations stabilized in phosphate buffer deliver photometric endpoint detection for routine dairy quality control. Food manufacturers in Germany and France deploy these formats under EU Regulation 1169/2011 enforcement, replacing gravimetric methods to satisfy ISO 17025 accreditation timelines.
- Fluorometric Assay:Picomolar-level sensitivity configurations enable lactose excipient verification in parenteral biologics. CDMO facilities in Switzerland and the United States adopt these platforms to satisfy USP monograph specifications, though six-figure instrument capital requirements constrain adoption velocity at smaller pharmaceutical developers.
- Colorimetric Assay:Cost-per-test economy drives concentration at academic institutions prioritizing teaching budgets over throughput.
- Conductometric Assay:Emerging format leverages ionic conductivity changes for rapid screening in field-deployable configurations.
Mature deployment sits with Enzymatic Assay formats. Newer deployment is concentrated in Fluorometric Assay configurations.
Application:
Regulatory pressure intensity separates high-frequency testing environments from episodic validation requirements across end-use verticals.
- Dairy Industry:Processors at cooperatives and integrated facilities conduct compositional verification for packaged milk, cheese, and whey products. FSSAI implementation of stricter standards in India creates unmet demand at mid-sized operations lacking accredited workflows.
- Food & Beverage Testing:Plant-based dairy analogue manufacturers—oat, almond, and soy milk producers—require lactose verification to substantiate allergen-free claims, opening adjacent demand verticals beyond traditional dairy.
- Clinical Diagnostics:Lactose intolerance screening protocols at hospital laboratories employ standardized kits for hydrogen breath test correlation.
- Pharmaceutical Development:Biologics manufacturers validate excipient purity to prevent immunogenic responses in parenteral formulations.
Volume concentration rests with Dairy Industry applications. Steepest expansion trajectory belongs to Food & Beverage Testing as plant-based analogue production scales.
End User:
Procurement authority clusters where multi-site standardization and regulatory audit exposure intersect.
- Food Manufacturers:Integrated dairy processors and contract testing laboratories dominate kit consumption through outcome-based service contracts bundling reagent supply with instrument uptime guarantees.
- Research Laboratories:Method development and validation studies drive demand for multi-format flexibility and open-platform compatibility.
- Hospitals:Clinical chemistry departments deploy lactose assays for metabolic disorder screening and nutritional assessment protocols.
- Academic Institutions:Teaching laboratories prioritize cost-per-test economy, perpetuating gravimetric method persistence where throughput requirements remain minimal.
Contract consolidation favors Food Manufacturers. Grant-dependent purchasing characterizes Academic Institutions.
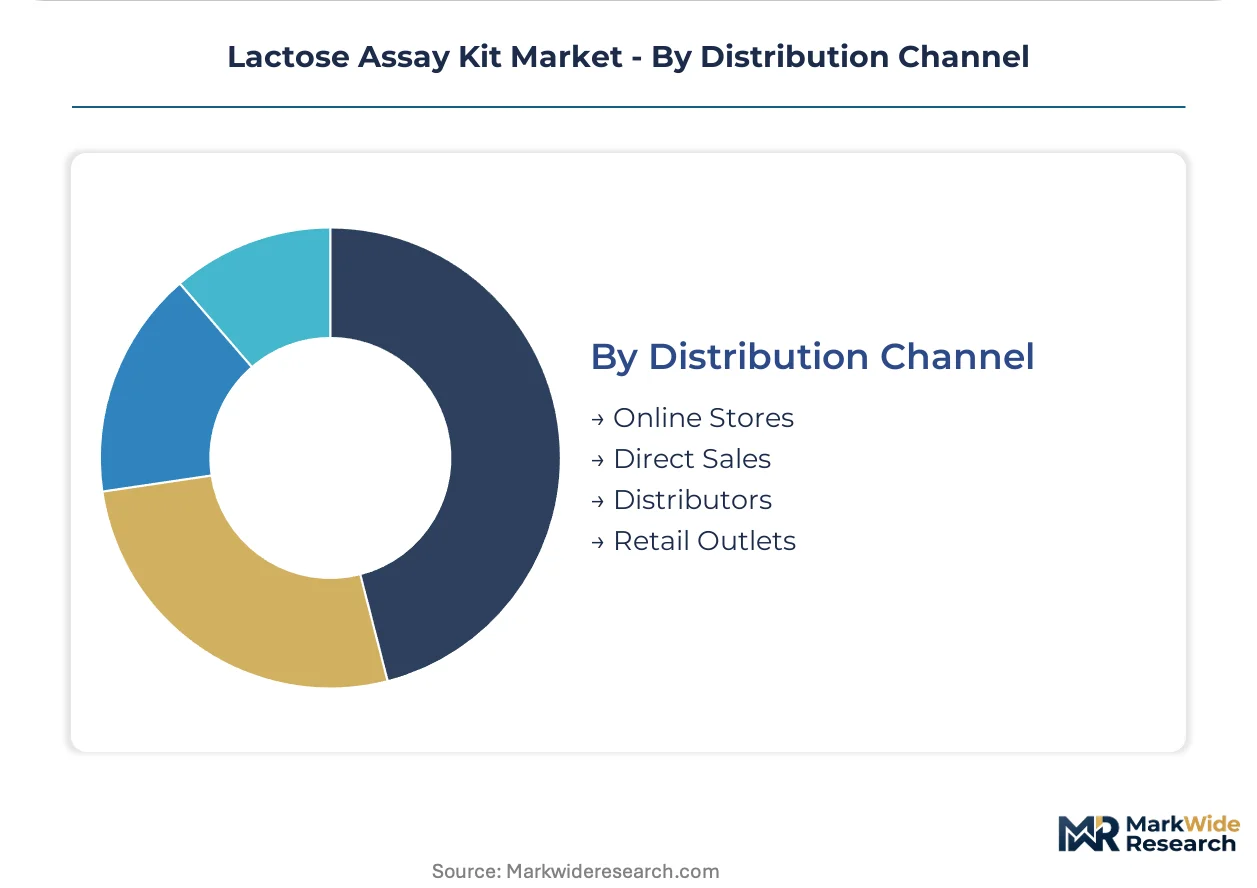
Distribution Channel:
Service integration requirements determine channel selection more than price transparency alone.
- Direct Sales:Instrument manufacturers leverage installed bases to bundle consumables with calibration and maintenance contracts, capturing recurring revenue streams from multi-site laboratory networks.
- Distributors:Regional specialists provide logistics coverage for mid-sized dairy cooperatives and emerging market deployments where cold-chain integrity remains critical.
- Online Stores:Academic and small research users favor catalog convenience for standard reagent replenishment.
- Retail Outlets:Limited penetration confined to basic educational kits and consumer-grade testing products.
Service bundling concentrates in Direct Sales. Geographic reach expansion belongs to Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Madison, Wisconsin anchors North American lactose assay demand through its concentration of dairy research institutions and food safety laboratories serving Upper Midwest processing cooperatives.
United States
FDA nutrition labeling enforcement compels dairy processors to replace gravimetric methods with validated enzymatic assays. The agency's 2023 guidance on added sugars disclosure intensified kit replacement cycles at yogurt and whey protein facilities. Chicago's contract testing laboratory corridor now standardizes on dual-validated formats to serve multi-state dairy cooperatives.
Germany
EU Regulation 1169/2011 allergen disclosure mandates drive kit procurement at dairy export facilities. The country's Federal Office of Consumer Protection and Food Safety conducts unannounced labeling audits at import checkpoints. Bavaria's dairy processing belt around Munich deploys accredited workflows to satisfy ISO 17025 timelines for cheese and infant formula exporters.
India
FSSAI implementation of stricter compositional standards for packaged milk creates unmet demand at mid-sized cooperatives lacking accredited testing infrastructure. The regulator's 2024 notification on adulteration detection mandates enzymatic verification for lactose content claims. Gujarat's Anand dairy cooperative cluster rapidly scales assay capacity to meet export qualification requirements.
Switzerland
Swissmedic pharmaceutical-grade specifications for biologics excipient verification attract fluorometric assay deployments. CDMO facilities around Basel adopt picomolar-sensitivity platforms to satisfy USP monograph requirements. The country's precision manufacturing heritage supports premium instrument calibration services bundled with reagent supply contracts.
China
SAMR dairy safety standards revision pressures domestic processors to upgrade from legacy methods. The regulator's 2024 draft on infant formula compositional testing specifies enzymatic detection for lactose quantification. Inner Mongolia's Hohhot dairy industrial zone consolidates testing capacity at three super-regional laboratories serving Mongolian and Russian export markets.
Lactose Assay Kit Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the lactose assay kit landscape. Instrument manufacturers with global distribution networks leverage installed bases to bundle consumables with service contracts, while specialized reagent formulators concentrate on enzyme stabilization intellectual property. Three archetypes dominate: diversified life science conglomerates with full workflow integration, boutique enzyme houses with matrix-specific formulations, and analytical instrument specialists with software-automated data interpretation. Competitive moves concentrate on reagent subscription monetization and annual calibration bundling to capture recurring revenue from multi-site laboratory networks.
Among diversified life science conglomerates, Thermo Fisher Scientific occupies a position exemplifying global distribution scale, while Merck KGaA anchors the European chemical reagent tradition. Megazyme represents the specialized enzyme house archetype with its focus on carbohydrate assay formulations. These three entities illustrate how competitive positioning separates through bundled service integration versus technical specialization in enzyme stability.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Agilent Technologies |
| Megazyme |
| Bio-Rad Laboratories |
| BioAssay Systems |
| Abcam plc |
| R-Biopharm AG |
| Promega Corporation |
| Others |
Supply & Pricing Matrix
Family-owned enzyme houses in Ireland and specialized reagent formulators in Germany anchor supply-side discipline through multi-generational technical expertise and conservative balance sheets, translating into stable pricing for beta-galactosidase formulations even as pharmaceutical-grade demand escalates. Their reluctance to pursue leveraged expansion preserves margin structures across the value chain.
Pricing Analysis
Value-based pricing anchored to ISO 17025 accreditation outcomes dominates contract negotiations between kit vendors and food manufacturers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and educational-grade tiers separates fluorometric configurations from enzymatic workhorses. Cost compression in food-grade segments is intensifying because contract laboratories now demand bundled calibration services. Academic institutions exhibit highest price sensitivity, while CDMO facilities absorb premium tiers without volume negotiation.
Supply Chain Analysis
High-purity glucose oxidase supply rests on specialty fermentation houses in Denmark, the Netherlands, and Japan, with phosphate buffer chemical feedstock drawing from industrial chemical producers in Germany and China. Lyophilized enzyme stability depends on specialized cold-chain logistics providers and hermetic packaging substrates. Single-source vulnerability concentrates in rare beta-galactosidase mutant strains protected by trade-secret fermentation protocols. Distribution runs through authorized distributors with temperature-validated warehousing for emerging market deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Lactose Assay Kit Market functions as a cost-of-compliance arena where EU Regulation 1169/2011 enforcement erects a barrier-to-entry moat favoring incumbents with pre-validated assay formats and established accreditation relationships.
For Market Incumbents: Anticipate margin compression from outcome-based service contracts by deepening captive supply of stabilized enzyme formulations and securing exclusive distribution partnerships with mid-sized dairy cooperatives in India. Consolidation of regional distributors in North America represents a defensive priority against price-transparent digital procurement platforms. For New Entrants and Emerging Players: FSSAI implementation in India opens a window for accredited assay workflows at mid-sized cooperatives lacking in-house laboratory infrastructure. Plant-based dairy analogue manufacturers in North America present the most penetrable vertical for specialized allergen-verification kits. A go-to-market angle emphasizing rapid deployment without legacy LIMS integration complexity accelerates initial reference customer acquisition. For Investors and Strategic Acquirers: Accelerating unannounced lactose labeling audits in Germany is the leading indicator that regulatory enforcement intensity is entering a sustained escalation phase. Over a multi-year horizon, acquisition targets should emphasize specialized enzyme houses with matrix-specific intellectual property and recurring revenue attachment rates above industry medians. Watch for FSSAI notification expansion beyond packaged milk into cheese and whey derivatives as the definitive inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme Stabilization Patent Acquisition | Secures proprietary buffer formulations that extend reagent shelf life beyond AOAC validation requirements. |
| Outcome-Based Service Contract Launch | Bundles instrument uptime guarantees with reagent auto-replenishment at multi-site dairy processors. |
| Indian Distribution Partnership | Establishes cold-chain-validated logistics coverage for FSSAI-mandated testing infrastructure expansion. |
| Fluorometric Platform Integration | Compresses pharmaceutical excipient verification timelines for CDMO facilities under USP monograph pressure. |
| Plant-Based Analogue Application Development | Opens adjacent revenue streams from oat and almond milk manufacturers requiring allergen-free certification. |
Research Methodology
Document review covered FDA guidance documents, EU Regulation 1169/2011 implementing acts, FSSAI notifications, and AOAC Official Methods, complemented by interviews with quality control directors at dairy processors, laboratory managers at contract testing facilities, procurement leads at food manufacturers, and regulatory affairs specialists at kit vendors. Secondary validation drew from ISO 17025 accreditation body records, trade customs data for enzyme imports, and SEC filings of publicly traded life science conglomerates. Bottom-up demand modeling triangulated against top-down market sizing from instrument installed base estimates.
Segment-level value projections across enzymatic, fluorometric, colorimetric, and conductometric formats were generated through adoption curve modeling for dairy industry, pharmaceutical development, and plant-based analogue applications. CAGRs were derived from regulatory mandate implementation timelines and replacement cycle analysis of gravimetric method displacement. Forecast inputs incorporated FSSAI enforcement intensity scenarios and pharmaceutical excipient verification requirement expansion under USP monograph revisions.
The model assumes a particular technology adoption path favoring enzymatic detection for routine quality control; alternative pathways involving rapid conductometric screening or biosensor miniaturization would alter the outlook for photometric endpoint architectures. Forecasts reflect assumptions about accreditation timeline compression and cold-chain infrastructure development in emerging markets. A small set of triggers—FSSAI scope expansion, Swissmedic specification tightening, and SAMR infant formula rule finalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Hydrogen Peroxide Measurement Market
Testing Equipment
Supercritical Fluid Chromatography Market
Testing Equipment
Heavy Metal Testing Market
Testing Equipment
Global Liquid Chromatography Systems Market
Testing Equipment
Hydrometer Market
Testing Equipment
Global Chromatography Columns Market
Testing Equipment
Polymer Testing Equipment Market
Testing Equipment
Global Laboratory Analytical Instruments and Consumables Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Global Circular Dichroism (CD) Spectrometers Market
Testing Equipment
Geochemical Services Market
Testing Equipment
Cone Calorimeter Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
High Performance Liquid Chromatography (HPLC) Market
Testing Equipment
Europe Process Analytics Market
Testing Equipment
2D Chromatography Market