
 Italy Food Flavor and Enhancer Market | 2026-2036
Italy Food Flavor and Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Food Flavor and Enhancer Market Foresight
Italian flavor compound production is pivoting toward fermentation-derived natural substrates as domestic biotech capacity expands. Givaudan SA leverages its Grasse-to-Milan supply chain to dominate premium natural flavor extraction. Firmenich anchors European citrus terpene sourcing through its southern Italian procurement networks. Kerry Group competes in savory taste modulation systems for pasta sauce and ready-meal manufacturers.
Food flavor and enhancer compounds comprise volatile aromatic molecules, nucleotide salts, and yeast-derived glutamates formulated to amplify sensory perception at threshold concentrations below one part per million. Manufacturers deploy solvent extraction, enzymatic biotransformation, and controlled Maillard reaction processes to achieve thermal stability in pasteurization environments. Natural flavors and extracts command margin premiums as EFSA clean-label guidance pressures reformulation away from artificial variants. Flavor enhancers gain traction in reduced-sodium meat applications where potassium chloride requires taste masking. Dairy applications represent a mature segment where vanilla and fermented dairy notes see stable replacement demand.
EFSA maintains maximum usage thresholds for glutamate-based enhancers under Regulation (EC) No 1333/2008, while Italy's Ministry of Health enforces additional national labeling protocols for flavor compounds in traditional protected-origin products. CSRD disclosure requirements will compel flavor houses to document supply chain emissions from agricultural feedstock through final formulation. Stakeholders must monitor how EU-wide harmonization of natural flavor definitions reshapes product classification and market access thresholds.
Market Dynamics
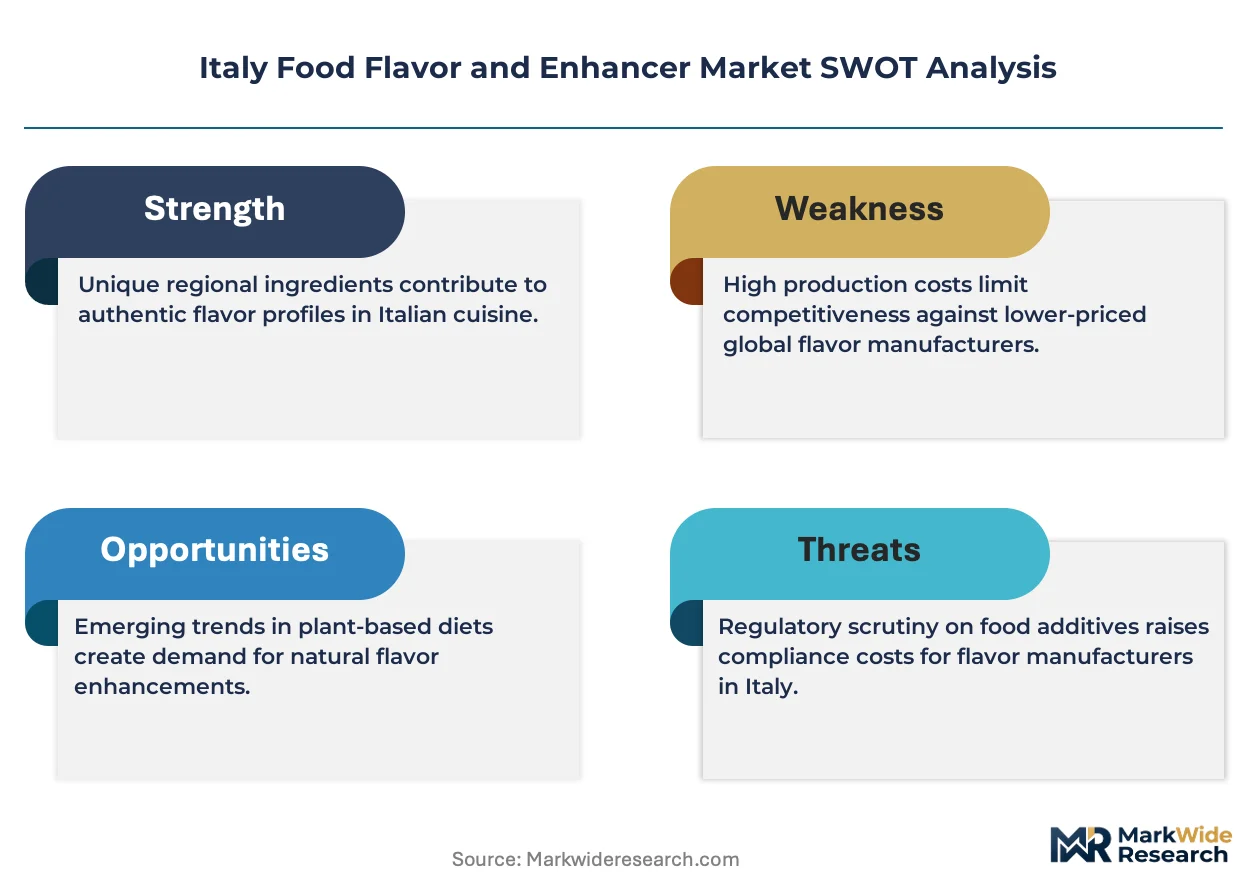
EFSA's tightening clean-label guidance under the EU Farm to Fork Strategy is forcing Italian flavor houses to eliminate synthetic additives from formulations targeting protected-origin products. This regulatory compression is accelerating capital redeployment toward fermentation-derived natural substrates and enzymatic biotransformation capabilities.
Growth Catalysts
- EFSA clean-label mandates:Regulation (EC) No 1333/2008 maximum thresholds for glutamate-based enhancers are compelling reformulation toward natural flavor extracts in ready-to-eat meal production across Lombardy.
- Biotechnology infrastructure expansion:Domestic fermentation capacity growth is enabling cost-competitive production of yeast-derived glutamates and nucleotide salts for savory taste modulation systems.
- Reduced-sodium meat applications:Potassium chloride taste-masking demand is pulling flavor enhancer procurement from Emilia-Romagna's cured meat processors seeking clean-label alternatives.
Market Restraints
- Agricultural feedstock volatility:Citrus terpene supply fluctuations from southern Italian groves create input cost instability for natural flavor extraction operations.
- Supply concentration risk:Premium natural flavor extraction capacity clusters around Milan and Grasse, creating geographic vulnerability in upstream aromatic molecule procurement.
- Technical thermal stability limitations:Natural flavor compounds exhibit degradation under pasteurization conditions that synthetic variants withstand, constraining application scope in shelf-stable products.
Strategic Opportunities
- Piedmont underpenetration:Turin's food manufacturing corridor offers expansion potential for savory taste modulation systems serving pasta sauce and ready-meal producers.
- CSRD disclosure tailwinds:Corporate Sustainability Reporting Directive requirements for supply chain emissions documentation are creating competitive differentiation for fermentation-derived natural substrate producers.
- Direct-to-manufacturer distribution:Digital procurement platforms are disintermediating traditional flavor compound distributors in Veneto's food processing clusters.
Industry Challenges
- Enzymatic biotransformation talent scarcity:Specialized biochemist recruitment lags capacity expansion timelines for domestic fermentation facilities.
- Traditional protected-origin labeling complexity:Italy's Ministry of Health national protocols for flavor compounds in DOP/IGP products create extended certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Food Flavor and Enhancer Market |
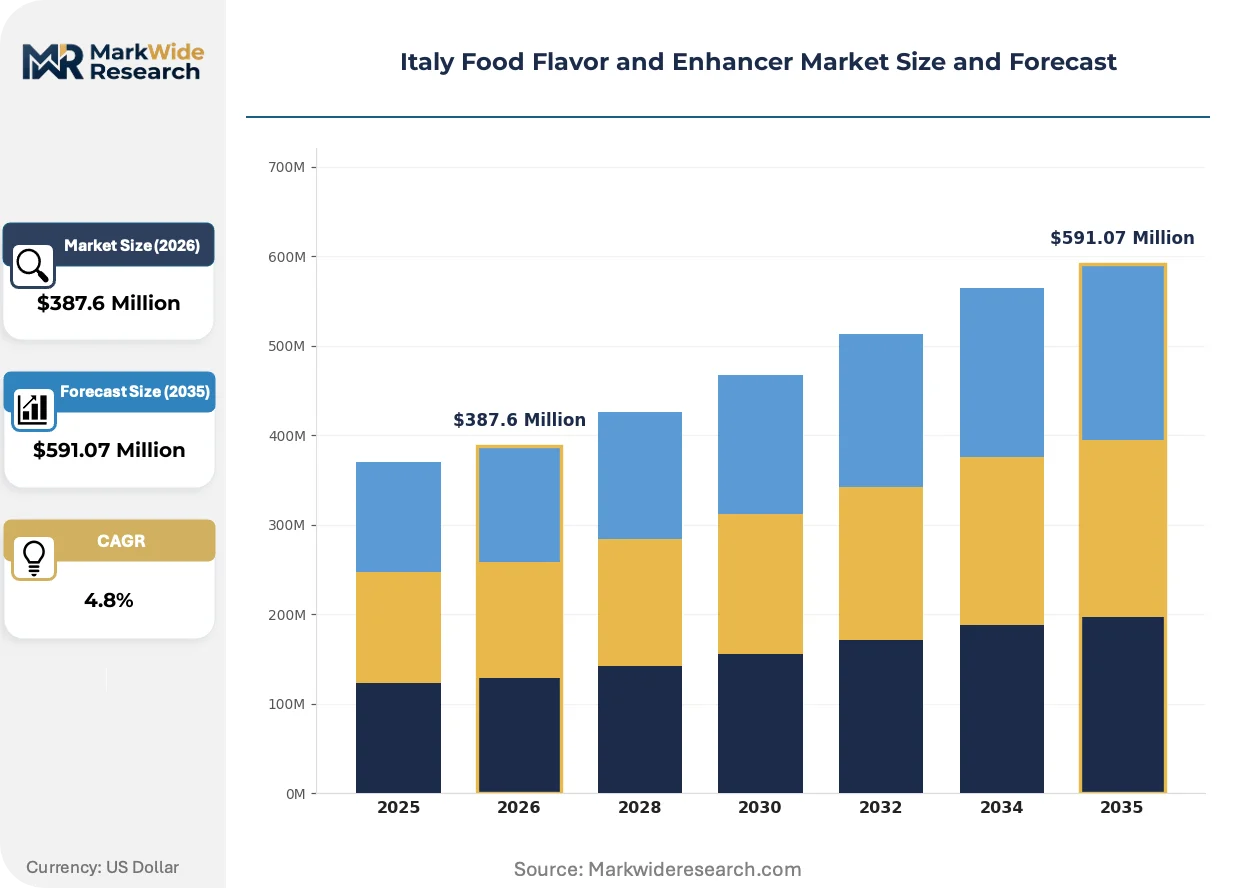
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Flavor Enhancers, Extracts Application: Bakery, Beverages, Dairy Products, Meat Products Distribution Channel: Online Retail, Hypermarkets, Supermarkets, Specialty Stores End User: Food Manufacturers, Restaurants, Catering Services, Households |
| Companies Covered | Givaudan SA, Firmenich, International Flavors & Fragrances Inc., Sensient Technologies, DuPont Danisco, Symrise AG, Kerry Group, Cargill Inc, Archer Daniels Midland, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Food Flavor and Enhancer Market Shifts & Advancements
Controlled Maillard reaction processes are rewriting thermal stability benchmarks for natural flavor compounds in pasteurized applications. This technological pivot is compressing the performance gap between synthetic and natural variants.
Enzymatic biotransformation is rewriting production economics for fermentation-derived natural substrates. Ready-to-eat meal manufacturers in Lombardy are adopting these compounds at accelerated procurement cycles. The technology is rewriting competitive positioning by enabling margin premiums previously captured by solvent-extracted natural flavors.
CSRD disclosure requirements are mandating granular supply chain emissions documentation from agricultural feedstock through final formulation. Flavor houses must now deploy carbon accounting systems across Grasse-to-Milan supply chains. Small and mid-sized Italian producers face compliance cost burdens that larger integrated players absorb through existing sustainability infrastructure.
Buyer concentration among northern Italy's ready-to-eat meal producers is compressing switching cycles for flavor compound procurement. Direct sourcing agreements are replacing distributor-mediated transactions in Milan's food manufacturing corridor. This pattern is most visible in savory taste modulation systems where volume commitments secure preferential capacity allocation.
Italy Food Flavor and Enhancer Market Segmentation
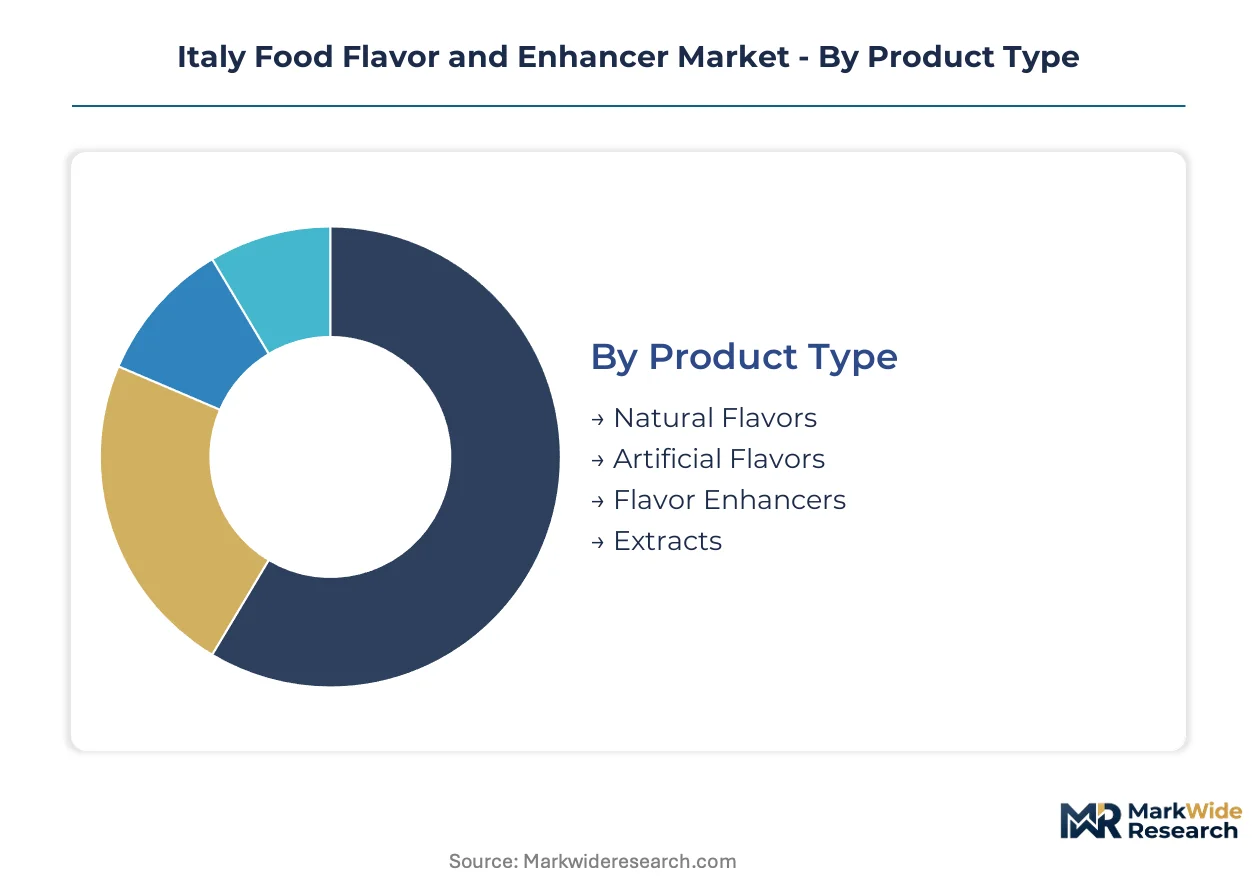
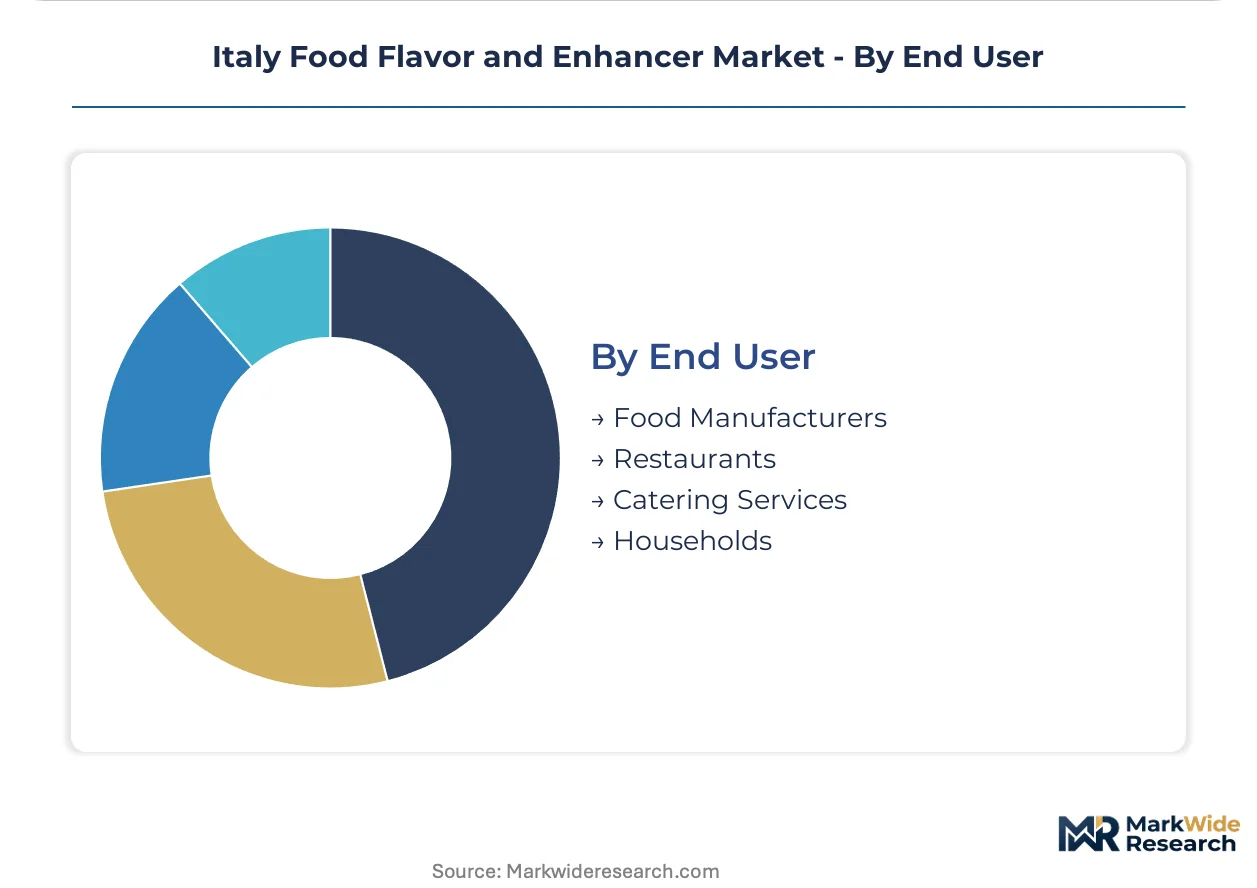
Italian flavor procurement patterns diverge sharply across product categories and end-use applications. Reformulation pressures from EFSA clean-label mandates are reshaping upgrade cycles differently across each segment dimension.
Product Type:
Replacement cycles accelerate where EFSA thresholds under Regulation (EC) No 1333/2008 force synthetic-to-natural transitions.
- Natural Flavors:Fermentation-derived aromatic molecules and solvent-extracted botanicals command margin premiums. Lombardy's ready-to-eat meal manufacturers are prioritizing these compounds to secure protected-origin product certifications under Ministry of Health protocols.
- Flavor Enhancers:Yeast-derived glutamates and nucleotide salts enable sodium reduction in cured meat applications. Emilia-Romagna processors source these for potassium chloride taste-masking in clean-label reformulations.
- Artificial Flavors:Synthetic aromatic molecules face declining procurement volumes as EFSA guidance tightens maximum usage thresholds.
- Extracts:Citrus terpenes from southern Italian groves supply beverage and confectionery manufacturers seeking geographic provenance claims.
Volume placements concentrate in Natural Flavors; the faster expansion belongs to Flavor Enhancers.
Application:
Cost tier differentiation separates commodity formulations from premium protected-origin products requiring extended certification timelines.
- Meat Products:Cured meat processors across Emilia-Romagna deploy flavor enhancers for sodium reduction without sensory degradation. Clean-label mandates from large retail buyers in northern Italy are accelerating procurement of yeast-derived glutamates.
- Dairy Products:Vanilla and fermented dairy notes see stable replacement demand in mature mozzarella and ricotta applications. Domestic extraction capacity around Milan serves formulators of premium fresh cheese varieties.
- Beverages:Citrus terpene procurement concentrates in southern Italian groves for carbonated and still drink applications.
- Bakery:Maillard-reaction flavors provide thermal stability for shelf-stable baked goods in Veneto's industrial baking clusters.
Procurement scale tilts toward Meat Products; margin premiums accrue fastest in Dairy Products.
Distribution Channel:
Customer type stratification separates institutional volume buyers from fragmented household procurement.
- Hypermarkets:Consolidated procurement of standard-grade flavor compounds for private-label ready-meal production. Milan's retail headquarters negotiate direct supply agreements bypassing traditional distributors.
- Online Retail:Specialty extracts and small-batch natural flavors reach artisanal producers in peripheral regions. Digital platforms disintermediate traditional distribution layers for Veneto food processing clusters.
- Supermarkets:Mid-tier flavor enhancers and artificial variants serve regional brand manufacturers.
- Specialty Stores:Premium natural extracts target traditional protected-origin producers seeking geographic differentiation.
Transaction volume clusters in Hypermarkets; the steepest expansion trajectory runs through Online Retail.
End User:
Supply concentration aligns with geographic clustering of Italy's food manufacturing infrastructure.
- Food Manufacturers:Large-scale savory taste modulation systems for pasta sauce and ready-meal production dominate procurement volumes. Lombardy's manufacturing corridor around Milan anchors demand for fermentation-derived substrates.
- Restaurants:Premium natural extracts and concentrated flavor systems support menu differentiation in northern Italy's hospitality sector.
- Catering Services:Cost-optimized flavor enhancers for high-volume meal production.
- Households:Retail-packaged extracts and seasoning blends through supermarket and online channels.
Capacity allocation prioritizes Food Manufacturers; penetration gains are climbing the fastest for Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Citrus terpenes from southern Italian groves supply beverage and confectionery manufacturers seeking geographic provenance claims. Northern Italy's manufacturing corridor concentrates flavor procurement for ready-to-eat meal production. The country's regulatory environment under EFSA oversight shapes regional competitive dynamics.
Lombardy
Milan anchors the densest concentration of flavor compound procurement in Italy. EFSA's Regulation (EC) No 1333/2008 thresholds compel reformulation toward natural extracts in ready-to-eat meal production. Food manufacturers across the manufacturing corridor deploy fermentation-derived substrates for savory taste modulation systems.
Emilia-Romagna
Cured meat processors drive demand for yeast-derived glutamates in sodium-reduction applications. Italy's Ministry of Health enforces additional labeling protocols for flavor compounds in traditional protected-origin products. Bologna and Parma host procurement clusters where potassium chloride taste-masking solutions gain traction.
Piedmont
Turin's food manufacturing corridor offers expansion potential for savory taste modulation systems serving pasta sauce producers. CSRD disclosure requirements create competitive differentiation for fermentation-derived substrate suppliers. Domestic biotech capacity expansion enables cost-competitive production of natural flavor compounds.
Veneto
Industrial baking clusters deploy Maillard-reaction flavors for thermal stability in shelf-stable products. Digital procurement platforms disintermediate traditional flavor compound distributors across the region. Verona and Padua anchor mid-tier procurement for standard-grade formulations.
Lazio
Rome's hospitality sector pulls premium natural extracts for menu differentiation applications. Online retail channels reach artisanal producers in peripheral regions with specialty extracts. The capital region exhibits slower procurement velocity compared to northern manufacturing corridors.
Italy Food Flavor and Enhancer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biotechnology-enabled natural substrate production. The vendor base stratifies across three tiers: integrated multinationals with Grasse-to-Milan supply chains, regional specialists in enzymatic biotransformation, and commodity distributors serving price-sensitive segments. Strategic archetypes include fermentation-capability builders, citrus terpene sourcing consolidators, and direct-to-manufacturer platform operators. Dominant competitive moves encompass backward integration into agricultural feedstock procurement and capacity expansion in controlled Maillard reaction processing.
Among Switzerland-based flavor houses, Givaudan SA and Firmenich occupy positions exemplifying integrated supply chain control from raw material through formulation. Kerry Group represents the savory taste modulation specialist archetype. These three anchors illustrate divergent strategic postures: Grasse-linked aromatic extraction dominance, European citrus terpene sourcing consolidation, and ready-meal manufacturer service orientation respectively.
| Leading Market Players |
|---|
| Givaudan SA |
| Firmenich |
| International Flavors & Fragrances Inc. |
| Sensient Technologies |
| DuPont Danisco |
| Symrise AG |
| Kerry Group |
| Cargill Inc |
| Archer Daniels Midland |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between Ministry of Health DOP/IGP-compliant natural extracts and standard-grade flavor compounds manifests in divergent margin structures and procurement network configurations. Premium-tier suppliers command captive relationships with Lombardy ready-to-eat meal producers while commodity-grade distributors face disintermediation pressure from digital platforms.
Pricing Analysis
Service-bundling separates formulation-technical-support-inclusive contracts from unbundled commodity transactions. Three-tier pricing structure across premium natural extracts, standard fermentation-derived substrates, and economy artificial variants reflects EFSA certification thresholds and thermal stability performance. Pricing pressure stems from agricultural feedstock volatility in southern Italian citrus terpene sourcing. Large food manufacturers in Milan's manufacturing corridor exhibit lowest price sensitivity due to volume-committed capacity allocation, while peripheral artisanal producers drive hardest bargain on specialty extracts.
Supply Chain Analysis
Freight cost differentials between Grasse-to-Milan aromatic extraction corridors and domestic southern Italian citrus terpene routes shape regional procurement economics. Supply concentration rests on France, Italy, and Switzerland for premium natural flavor extraction, with Spain and Morocco entering citrus botanical sourcing. Raw material dependencies include fermentation feedstocks, solvent-extracted botanical matrices, and yeast-derived nucleotide precursors. Single-source vulnerability concentrates in Milan-Grasse premium extraction capacity. Distribution runs through direct-to-manufacturer agreements displacing traditional distributor networks in northern Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity scarcity props pricing for natural substrate producers as EFSA clean-label mandates compress synthetic alternative viability. Supply constraints in enzymatic biotransformation talent extend capacity buildout timelines beyond demand absorption curves.
For Market Incumbents: Deepen backward integration into southern Italian citrus terpene procurement to secure feedstock against climate volatility threatening Grasse-linked supply chains. Expand controlled Maillard reaction processing capacity in Piedmont to capture Turin manufacturing corridor demand. Fortify formulation-technical-service bundling against emerging biotechnology-enabled competitors.
For New Entrants and Emerging Players: Begin with Veneto industrial baking clusters where digital procurement platform penetration has weakened incumbent distributor relationships. Target shelf-stable thermal stability applications where natural compound performance gaps persist. Pursue direct-to-manufacturer positioning with carbon-accounting-enabled CSRD compliance documentation.
For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-capability builders given EFSA threshold compression accelerating synthetic-to-natural substitution curves. Long-term viability favors integrated players with Grasse-to-Milan supply chain control spanning extraction through formulation. Monitor enzymatic biotransformation talent pipeline tightness as inflection signal for capacity expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Domestic biotech infrastructure growth enables cost-competitive yeast-derived glutamate production against solvent-extracted alternatives. |
| Backward Integration into Citrus Terpene Sourcing | Upstream control over southern Italian grove networks insulates margin from agricultural feedstock price volatility. |
| Controlled Maillard Reaction Processing Investment | In-house thermal stability capabilities close performance gap between natural and synthetic flavor compounds in pasteurized applications. |
| CSRD-Compliant Carbon Accounting Deployment | Granular emissions documentation from agricultural feedstock through formulation creates procurement preference among sustainability-mandated buyers. |
| Direct-to-Manufacturer Digital Platform Launch | Disintermediation of traditional distributors captures margin compression in Veneto and Lombardy food manufacturing clusters. |
Research Methodology
Document review covered EFSA regulatory filings, Ministry of Health DOP/IGP protocols, and CSRD disclosure frameworks, complemented by interviews with fermentation facility technical directors, Lombardy ready-to-eat meal procurement leads, Emilia-Romagna cured meat processor R&D heads, and southern Italian citrus cooperative managers. Secondary validation drew from EU customs trade data, agricultural commodity price indices, and biotech capacity expansion announcements. Bottom-up procurement volume modeling triangulated against top-down market sizing from flavor house revenue disclosures.
Segment-level value and volume trajectories across the projection horizon reflect product-type, application, and distribution-channel dimensional modeling. CAGRs were derived from regression analysis against EFSA regulatory phase-in schedules and biotechnology capacity buildout timelines. Industry-specific forecast inputs incorporated enzymatic biotransformation yield improvement curves and thermal stability performance benchmarking data.
Underlying measurement precision varies by segment; natural flavors and fermentation-derived enhancers carry tighter precision than artificial flavor categories facing demand collapse. Forecasts reflect assumptions around EFSA threshold enforcement consistency and domestic biotech talent pipeline development. Stakeholders should weight assumptions against their own operating context regarding regulatory compliance timelines and feedstock sourcing geography.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
North America Vanilla and Vanillin Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
Natural Food Colors Market
Flavorings and Food Additives
Lemon Essential Oil Market
Flavorings and Food Additives
United States Food Flavor and Enhancer Market
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
Grapefruit Oil Market
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
Orange Essential Oil Market
Flavorings and Food Additives
Natural Food Colors and Flavors Market
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
Citrus-Based Sugar-Reduction Flavor Modulators Market
Flavorings and Food Additives
Cocoa Extract Market
Flavorings and Food Additives
Flavor Compounds Market