
 Europe Food Flavor Market | 2026-2036
Europe Food Flavor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Flavor Market Foresight
Plant-based dairy is decoupling from traditional flavor profiles as oat and pea protein bases require entirely new masking and enhancement systems. Givaudan SA leverages its biotechnology platform to engineer yeast-derived dairy notes that perform in neutral pH environments. Symrise AG anchors its European position through captive botanical sourcing in Spain and Madagascar. Kerry Group Plc competes by extending its taste modulation portfolio into sodium-reduction synergies for clean-label savory applications.
Europe food flavors encompass volatile and non-volatile compounds—esters, aldehydes, terpenes, and Maillard reaction products—formulated at parts-per-million precision to survive thermal processing, shelf aging, and consumer palatability thresholds. Their primary function is to restore or enhance sensory identity lost during industrial scale-up, fat reduction, or sugar reformulation. Natural flavors now command premium positioning as EFSA scrutiny on artificial additive safety intensifies, while liquid formats dominate beverage and dairy injection systems due to dispersion efficiency. Powder segments retain margin strength in bakery dry mixes where shelf stability and flowability determine procurement decisions.
EFSA, the EU Green Deal framework, and REACH collectively constrain synthetic precursor availability while mandering disclosure thresholds that favor botanical extraction over petrochemical synthesis. The F-Gas Regulation indirectly pressures cryogenic extraction economics, pushing investment toward supercritical CO2 and enzyme-assisted methods. Stakeholders must monitor how the EU AI Act reshapes predictive flavor formulation tools and whether ECHA substance evaluations trigger further artificial flavor delistings.
Market Dynamics
EFSA's additive safety reassessments and the EU Green Deal's chemical footprint mandates are forcing European flavor houses to rebuild formulation pipelines around botanical extraction and fermentation-derived molecules rather than petrochemical precursors.
Growth Catalysts
- Plant-based protein expansion:Meat and dairy alternatives in Germany, France, and the Netherlands require entirely new masking and enhancement flavor systems as oat, pea, and fava bases replace animal proteins.
- REACH substance restrictions:The regulatory framework's tightening authorization lists for synthetic precursors accelerate investment in natural extraction capabilities and biotech-derived alternatives.
- Clean-label reformulation:Sugar reduction mandates across EU member states drive demand for taste modulation technologies that restore sensory satisfaction without caloric load.
Market Restraints
- Vanillin feedstock volatility:Guaiacol and lignin supply disruptions from Nordic pulp mills create price instability for natural vanilla alternatives.
- Cryogenic extraction cost pressure:The F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants raises operating costs for traditional cold-press botanical extraction in Southern Europe.
- Biotech capacity concentration:Precision fermentation infrastructure for yeast-derived dairy and meat notes clusters in Switzerland and Denmark, limiting supply diversification.
Strategic Opportunities
- Poland and Romania:Underpenetrated food manufacturing bases in Eastern Europe offer first-mover positioning as multinational brands regionalize supply chains post-pandemic.
- Upcycled botanicals:Citrus peel and grape pomace from Spanish and Italian wine industries provide low-cost, circular feedstocks for terpene and flavonoid extraction.
- EU AI Act alignment:Predictive flavor formulation tools that document training data provenance gain competitive preference as algorithmic transparency mandates take effect.
Industry Challenges
- Flavorist talent scarcity:European universities produce fewer than 150 qualified flavor chemists annually, creating recruitment bottlenecks for R&D expansion.
- Natural certification timelines:EFSA novel food and flavoring substance approvals average 18-24 months, delaying product launches and tying up regulatory affairs capacity.
- Legacy ERP integration:Batch-oriented manufacturing execution systems at mid-sized flavor houses resist real-time traceability upgrades required by the EU Digital Product Passport framework.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Flavor Market |
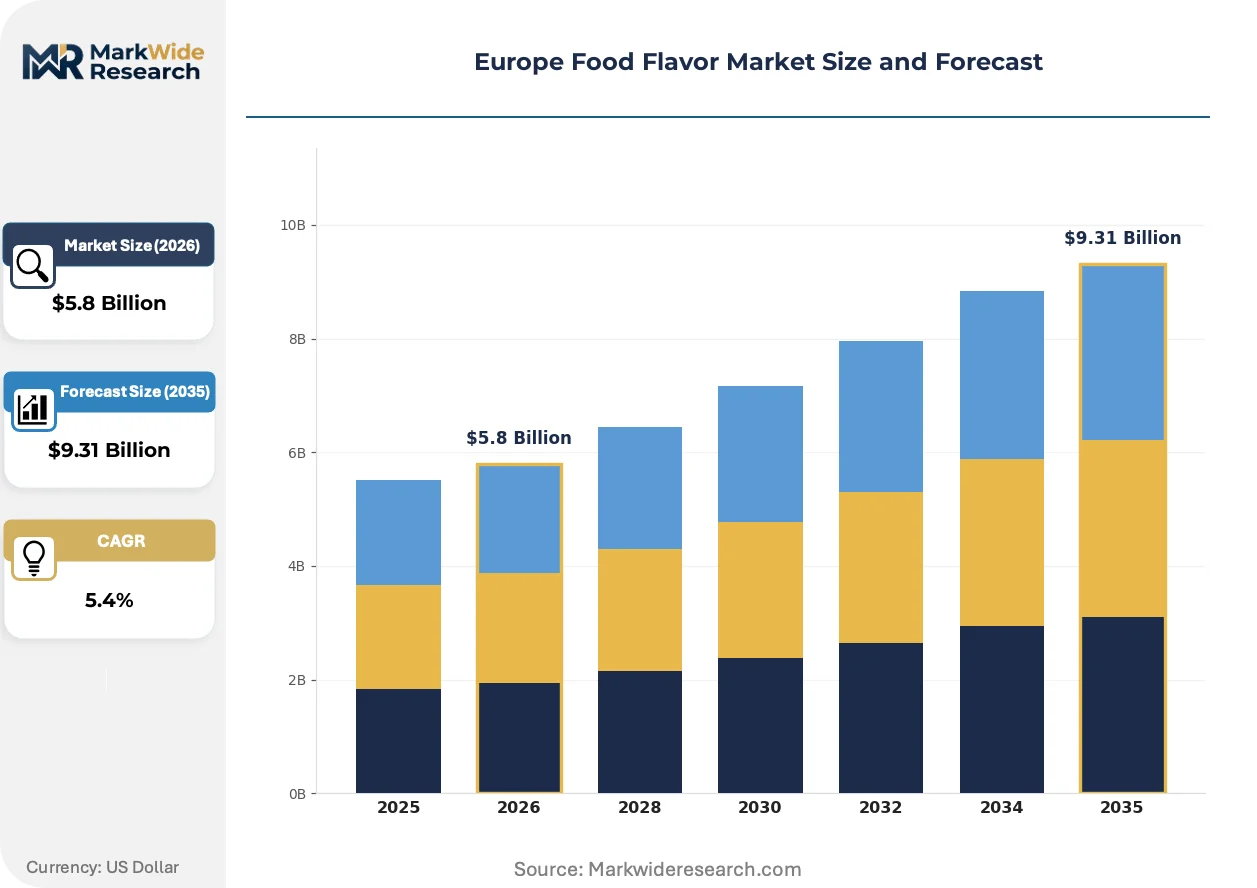
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.31 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Organic Flavors, Extracts Form: Liquid, Powder, Paste, Granules Application: Beverages, Bakery, Dairy, Confectionery End User: Food Manufacturers, Restaurants, Retailers, Catering Services |
| Companies Covered | International Flavors & Fragrances Inc., BASF SE, Givaudan SA, European Flavours and Fragrances, Firmenich SA, Symrise AG, Kerry Group Plc, Sensient Technologies Corporation, DSM-Firmenich, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Flavor Market Shifts & Advancements
Biotechnology platforms and regulatory disclosure requirements are converging to transform how European flavor houses source, formulate, and validate their ingredient portfolios.
Precision fermentation is rewriting the economics of high-value flavor molecules. Yeast strains engineered to express lactones, esters, and sulfur compounds now supply dairy and meat alternative manufacturers at scale previously reserved for petrochemical synthesis. Givaudan and smaller biotech specialists in Switzerland and Denmark are commissioning multi-thousand-liter bioreactors. This platform is compressing the cost gap between natural-labeled and artificial alternatives while eliminating agricultural land and climate dependencies.
The EU Green Deal's Farm to Fork strategy tightens chemical input tracking across flavor supply chains. EFSA's expanded transparency requirements now mandate publication of all safety study data supporting flavoring substance approvals, forcing reformulators to document botanical provenance and extraction solvent residues. Spanish citrus processors and Madagascar vanilla cooperatives face new due diligence obligations. The natural flavor segment bears the heaviest compliance burden as artificial additive delistings accelerate.
Direct procurement relationships between food manufacturers and botanical extractors are displacing traditional distributor intermediaries. Large German and French dairy and bakery groups now contract directly with Spanish rosemary and thyme extractors for clean-label antioxidant-flavor dual-function ingredients. This channel compression eliminates margin stacking but requires flavor houses to rebuild technical service capabilities around co-development partnerships rather than catalog sales. The shift is most visible in savory applications where sodium reduction synergies demand iterative formulation collaboration.
Europe Food Flavor Market Segmentation
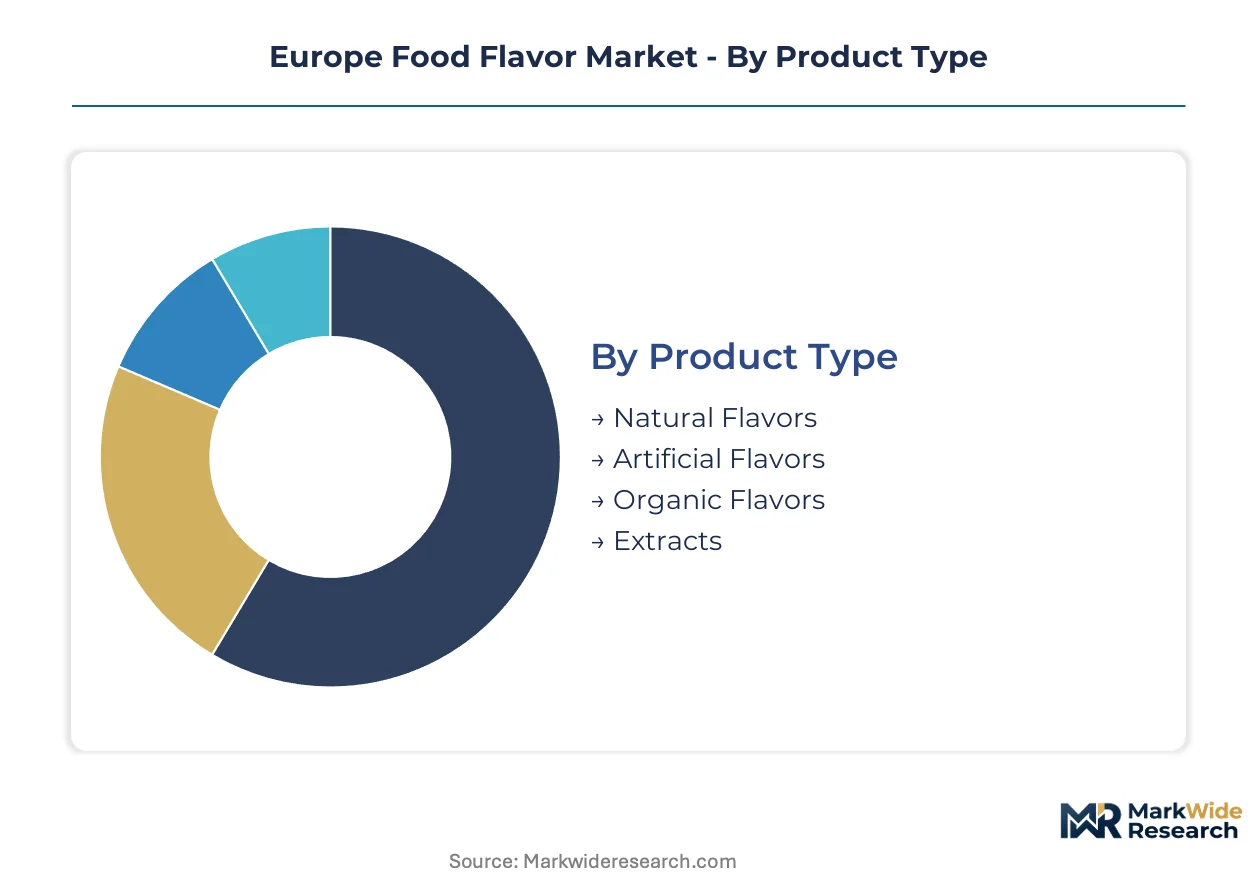
European flavor procurement patterns diverge sharply across certification tiers, with EFSA novel food approvals and EU organic labeling creating distinct compliance cost structures that reshape supplier selection. Formulation choices cascade through thermal stability requirements, clean-label positioning, and end-use processing constraints.
Product Type:
Natural flavors carry the heaviest EFSA novel substance approval burden, while artificial alternatives face REACH authorization restrictions and accelerating delisting pressure.
- Natural Flavors:Botanical and fermentation-derived molecules from Spanish citrus processors and Madagascar vanilla cooperatives require documented provenance and extraction solvent disclosure under expanded EFSA transparency mandates. German dairy and French bakery manufacturers absorb premium pricing to secure clean-label positioning for retail-facing products.
- Artificial Flavors:Petrochemical-derived esters, aldehydes, and sulfur compounds face REACH substance restrictions and EFSA safety reassessments that compress available precursor lists. Dutch and Belgian confectionery houses retain limited artificial portfolios where thermal stability demands exceed natural alternatives.
- Organic Flavors:EU organic certification mandates agricultural feedstock traceability and prohibits synthetic solvent extraction. Italian wine industry grape pomace supplies terpene feedstocks for certified organic citrus and berry notes.
- Extracts:Supercritical CO2 and enzyme-assisted concentrates from rosemary, thyme, and vanilla deliver dual antioxidant-flavor functionality for savory sodium reduction projects.
Leading the category by volume: Natural Flavors. Growing fastest: Organic Flavors.
Form:
Processing economics and dispersion requirements segment form selection, with liquid formats dominating high-throughput injection systems and powder commanding bakery dry mix margins.
- Liquid:Aqueous and oil-based solutions disperse efficiently in beverage carbonation lines and dairy HTST pasteurization systems. German beverage manufacturers specify liquid formats for parts-per-million precision in sugar-reduced formulations.
- Powder:Spray-dried and plated flavors with maltodextrin carriers deliver shelf stability and flowability for automated bakery premix operations. French industrial bakeries prioritize powder segments for clean-label dry goods.
- Paste:High-viscosity concentrates suit small-batch artisan applications and compound chocolate manufacturing where moisture control is critical.
- Granules:Agglomerated formats bridge solubility and handling properties for instant beverage and soup powder applications.
Highest margin capture: Powder. Fastest format expansion: Liquid.
Application:
End-use thermal processing intensity and shelf stability demands determine flavor system architecture, with sugar reduction mandates reshaping category priorities.
- Beverages:Carbonated soft drinks, functional waters, and alcohol-free alternatives require heat-stable, clear-label flavor systems that survive pasteurization and maintain clarity. Swedish and Finnish manufacturers drive demand for fermented botanical notes in low-sugar launches.
- Bakery:Yeast-raised and chemically leavened products demand Maillard-stable flavors that perform through oven profiles exceeding 200°C. Spanish and Italian industrial bakeries source dual-function antioxidant extracts for clean-label preservation.
- Dairy:Fermented and fresh dairy applications require pH-tolerant flavor systems that perform in acidic yogurt and neutral milk environments. Precision fermentation-derived dairy notes from Swiss bioreactors supply German plant-based alternatives.
- Confectionery:Hard candy, chocolate, and gum applications prioritize heat stability and fat compatibility for conching and depositing processes.
Deepest formulation collaboration: Dairy. Steepest expansion trajectory: Beverages.
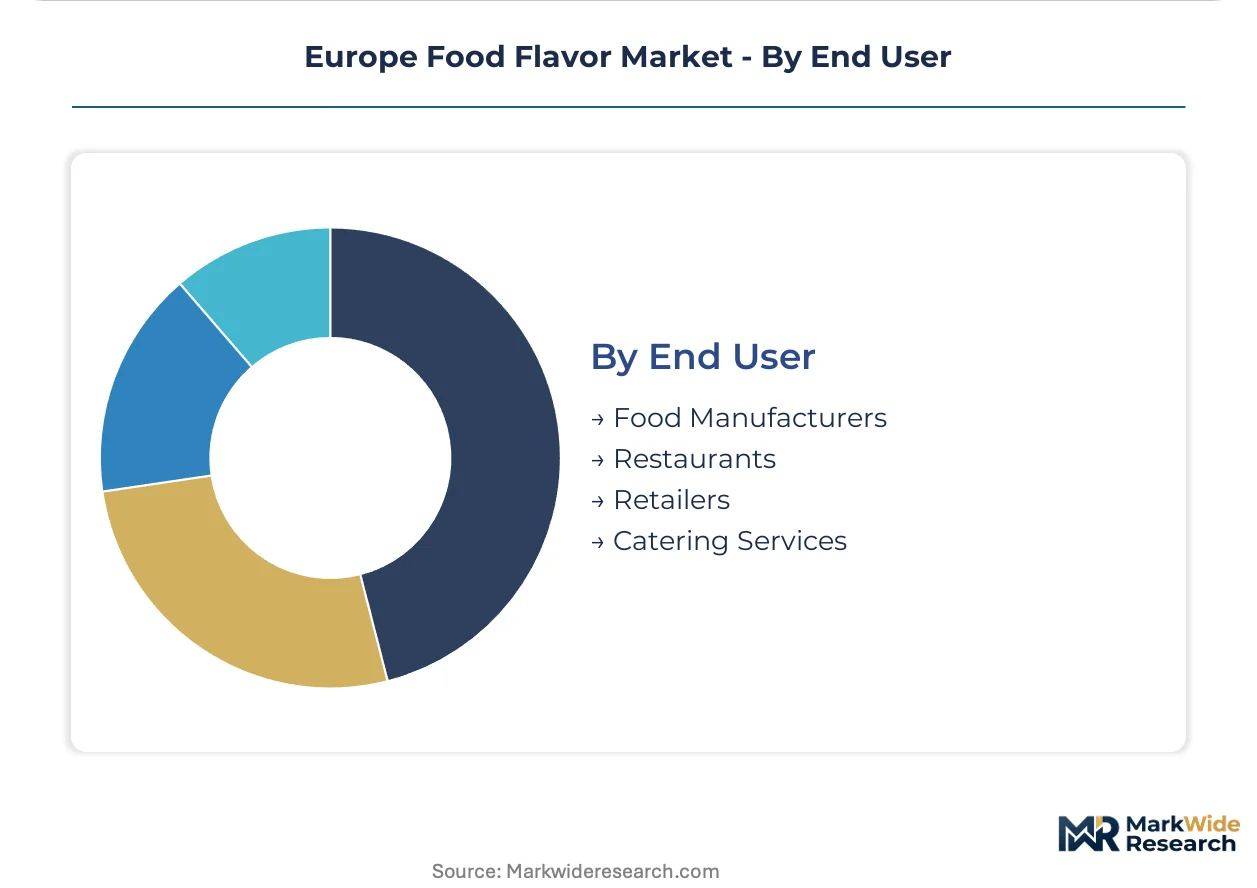
End User:
Procurement scale and technical service requirements separate institutional buyers, with co-development partnerships replacing catalog sales for complex reformulation projects.
- Food Manufacturers:Multinational dairy, bakery, and beverage groups in Germany and France contract directly with Spanish botanical extractors for captive supply of clean-label ingredients. These buyers demand iterative sodium reduction and sugar reformulation support.
- Restaurants:Chain and independent foodservice operators source standardized flavor systems through distributor networks for menu consistency across locations.
- Retailers:Private label grocery chains specify white-label flavor solutions for store-brand product lines, prioritizing cost position over technical partnership.
- Catering Services:Institutional and event catering buyers prioritize shelf-stable, high-volume formats with minimal handling complexity.
Dominant procurement volume: Food Manufacturers. Fastest channel growth: Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and Switzerland, while consumption spreads across Western and Eastern European manufacturing bases. German flavor houses supply reformulated systems to dairy and bakery processors. Eastern European markets absorb volume as supply chains regionalize post-pandemic.
Germany
Plant-based protein expansion drives flavor investment as oat and pea alternative manufacturers rebuild formulation pipelines. EFSA clean-label guidelines force disclosure of extraction solvents and botanical provenance. The Cologne-Düsseldorf corridor hosts captive botanical sourcing operations serving sodium-reduction projects for industrial bakeries.
France
Sugar reduction mandates in confectionery and dairy applications accelerate taste modulation procurement. REACH authorization lists compress synthetic precursor availability for traditional flavor houses. The Lyon-Grenoble axis concentrates supercritical CO2 extraction capacity for rosemary and thyme dual-function ingredients.
Netherlands
Precision fermentation infrastructure for yeast-derived dairy notes attracts biotech investment from Swiss and Danish specialists. The EU Green Deal's chemical footprint mandates reshape formulation priorities for export-oriented food manufacturers. Wageningen anchors research partnerships between flavor houses and agricultural universities.
Spain
Citrus peel and grape pomace from Valencia and Catalonia wine industries supply low-cost terpene feedstocks for circular extraction models. EFSA expanded transparency requirements impose due diligence obligations on botanical cooperatives. Barcelona hosts direct procurement relationships between extractors and French dairy groups.
Poland
Underpenetrated food manufacturing bases offer first-mover positioning as multinational brands regionalize supply chains. The F-Gas Regulation raises operating costs for cryogenic extraction, pushing investment toward enzyme-assisted methods. Warsaw and Łódź industrial zones attract flavor house technical service expansion for bakery and beverage clients.
Europe Food Flavor Market Competitive Landscape
Top-tier vendors anchor premium natural flavor supply, while mid-tier specialists compete on regional technical service and clean-label certification speed. The vendor base stratifies across biotechnology platforms, captive botanical networks, and taste modulation portfolios. Three archetypes dominate: Swiss-Danish precision fermentation operators, Spanish-Italian botanical extractors with circular feedstock access, and Irish-Dutch taste modulation specialists. Competitive moves concentrate on direct procurement relationships with food manufacturers and predictive formulation tool development under EU AI Act transparency mandates.
Among biotechnology-anchored operators, Givaudan SA and DSM-Firmenich exemplify the precision fermentation tier investing in multi-thousand-liter bioreactor capacity for yeast-derived dairy and meat notes. Symrise AG occupies a position within the captive sourcing archetype through controlled botanical networks in Spain and Madagascar. Kerry Group Plc represents the taste modulation specialist tier extending sodium-reduction synergies into clean-label savory applications.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. |
| BASF SE |
| Givaudan SA |
| European Flavours and Fragrances |
| Firmenich SA |
| Symrise AG |
| Kerry Group Plc |
| Sensient Technologies Corporation |
| DSM-Firmenich |
| Others |
Supply & Pricing Matrix
Natural-certification premiums over artificial alternatives bifurcate procurement economics across German dairy and French bakery supply chains, compressing margins for non-compliant extractors while rewarding Spanish botanical cooperatives with documented provenance. This tier divergence manifests in contract structures that tie price escalators to EFSA disclosure timelines and REACH authorization status, forcing buyers to absorb regulatory compliance costs upstream or reformulate around restricted synthetic precursors.
Pricing Analysis
Short lead-time premiums for EFSA-approved natural flavors command significant contract uplifts against spot-market artificial alternatives facing delisting risk. Three-tier pricing structure across premium natural, standard artificial, and economy blended tiers reflects certification burden and thermal performance differentials. Pricing pressure stems from vanillin feedstock volatility at Nordic pulp mills, squeezing mid-tier compounders. Industrial bakery groups in France exhibit highest price sensitivity due to volume scale, while Swiss precision fermentation specialists face least sensitivity given captive bioreactor capacity.
Supply Chain Analysis
EU Green Deal local-content mandates and Farm to Fork traceability requirements are reshaping sourcing patterns toward captive Spanish citrus networks and Madagascar vanilla cooperatives. Supply concentrates in Germany, Switzerland, and Spain, with critical dependencies on Nordic lignin for vanillin alternatives, Madagascar vanilla orchid harvests, and Swiss-Danish precision fermentation infrastructure. Single-source vulnerability runs through Madagascar vanilla cooperatives facing EFSA due diligence obligations. Distribution runs through direct procurement relationships between food manufacturers and botanical extractors, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
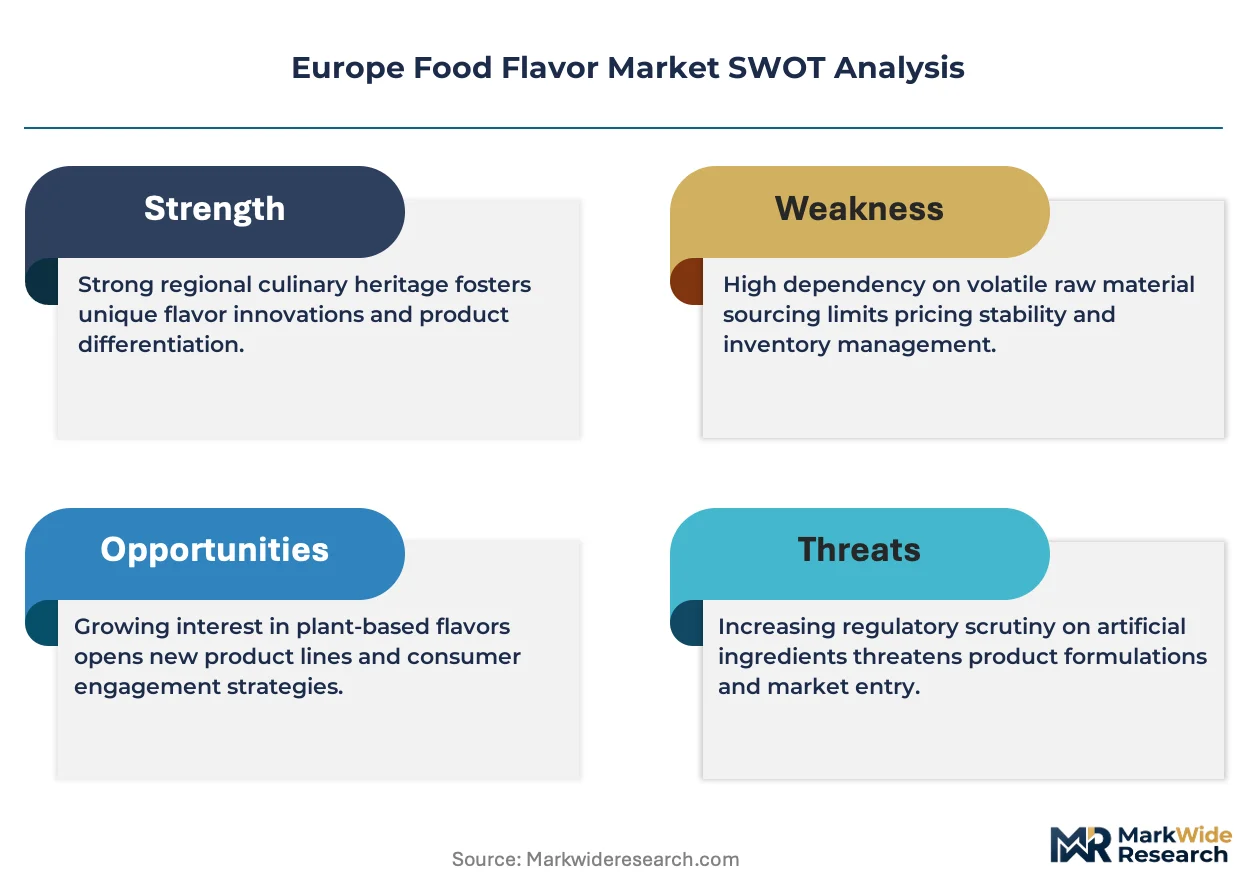
EFSA novel food approval timelines and REACH authorization restrictions have erected substantial compliance moats that favor incumbent flavor houses with dedicated regulatory affairs capacity over capital-constrained challengers.
For Market Incumbents: Anchor market position through backward integration into Spanish citrus and Madagascar vanilla cooperative networks, securing captive feedstock for clean-label expansion. Expand precision fermentation capacity in Switzerland and Denmark to capture yeast-derived dairy note demand from German plant-based manufacturers. Defend against biotech specialist encroachment by accelerating EFSA submission pipelines for fermentation-derived molecules. For New Entrants and Emerging Players: Begin with Poland and Romania's underpenetrated food manufacturing bases, where multinational brands are regionalizing supply chains post-pandemic and local technical service capacity remains scarce. Target bakery and beverage applications in Warsaw and Łódź industrial zones, leveraging enzyme-assisted extraction methods to circumvent F-Gas Regulation cost pressures on cryogenic alternatives. Pursue co-development partnerships with mid-sized Polish dairy processors seeking sodium-reduction synergies. For Investors and Strategic Acquirers: Re-rating potential sits with Swiss-Danish precision fermentation operators given expanding bioreactor capacity and collapsing cost gaps between natural-labeled and artificial alternatives. Long-term viability favors biotechnology-anchored platforms over petrochemical-dependent compounders facing REACH substance restrictions. Monitor ECHA substance evaluation announcements as inflection signals for accelerated artificial flavor delistings and corresponding natural alternative demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Botanical Sourcing | Direct procurement relationships with Spanish citrus processors secure EFSA-compliant feedstock for clean-label positioning. |
| Precision Fermentation Scale-Up | Multi-thousand-liter bioreactor investments in Switzerland compress yeast-derived lactone costs against petrochemical alternatives. |
| Regulatory Affairs Capacity Expansion | Dedicated EFSA novel food submission teams accelerate approval timelines and tie up competitor regulatory resources. |
| Enzyme-Assisted Extraction Transition | Technology shift from cryogenic methods circumvents F-Gas Regulation refrigerant phasedown cost escalations. |
| Taste Modulation Portfolio Extension | Sodium-reduction synergies for savory applications address EU member state sugar and salt reformulation mandates. |
Research Methodology
Independent corroboration across flavor house R&D directors, German and French dairy procurement leads, Spanish botanical cooperative managers, and EFSA regulatory affairs specialists underwrites the qualitative findings. Primary fieldwork combined structured interviews with these stakeholders and secondary validation from EFSA flavoring substance approval databases, REACH authorization lists, EU customs trade data, and SEC filings of listed flavor houses. Bottom-up volume estimates from application-level consumption patterns triangulate against top-down market size assessments.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects in natural versus artificial flavor segments. The analytical framework models product type, form, application, and end-user dimensions alongside fermentation-versus-extraction technology pathways. CAGRs derive from regression analysis against plant-based protein expansion rates, EFSA approval velocity, and REACH restriction timelines. Forecast inputs incorporate bioreactor capacity commissioning schedules and citrus harvest yield variability.
EFSA novel food approval delays, REACH substance restriction acceleration, and precision fermentation yield shortfalls are the dominant revision risks to projection assumptions. Forecasts reflect documented stakeholder input and disclosed regulatory timelines without contingency for unannounced ECHA evaluations or biotech platform failures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Global Acerola Extracts Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market
Flavorings and Food Additives
Beef Flavors Market
Flavorings and Food Additives
Beverage Flavoring Market
Flavorings and Food Additives
Cholic Acid Market
Flavorings and Food Additives
Poria Cocos Extract Market
Flavorings and Food Additives
Natural Flavors Market
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
Asia-Pacific Vanilla Beans and Extract Market
Flavorings and Food Additives
North America Licorice Extract Market
Flavorings and Food Additives
Betanin Food Color Market
Flavorings and Food Additives
Chocolate Flavoring Compounds Market
Flavorings and Food Additives
Italy Food Flavor and Enhancer Market
Flavorings and Food Additives
Global Syrup Market
Flavorings and Food Additives
Egypt Food Flavor and Enhancer Market
Flavorings and Food Additives
Dairy Flavors Market