
 Oxo-Biodegradable Plastic Packaging Market | 2026-2036
Oxo-Biodegradable Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Oxo-Biodegradable Plastic Packaging Market Analytics
Asset-light leasing models for pro-oxidant masterbatch production lines are fragmenting capital requirements across mid-tier compounders. Symphony Environmental Technologies Plc leverages its UK patent estate to sustain technology licensing revenue across emerging markets. Wells Plastics Ltd anchors British manufacturing scale with backward integration into additive synthesis. EPI Environmental Technologies Inc. competes through North American distributor networks that control regional technical service capacity.
Oxo-biodegradable plastic packaging incorporates transition-metal catalysts, typically cobalt or manganese stearates at 1-3% loading, that accelerate polyethylene chain scission under thermal and oxidative stress to enable fragmentation and subsequent microbial assimilation. The primary commercial purpose is to reduce persistence of conventional plastic litter in terrestrial and marine environments while maintaining processability on standard extrusion equipment. Polyethylene film dominates volume throughput due to mature blown-film infrastructure and cost parity with conventional resins. Food packaging absorbs the largest margin pool as retail chains demand certified shelf-life performance alongside biodegradation claims. Bag formats lag in premium positioning but occupy high-volume institutional procurement channels.
EFSA maintains active evaluation protocols for oxo-biodegradable additive migration limits, while India's BIS has notified draft standards for oxo-biodegradable carry bags under Plastic Waste Management Rules. REACH registration requirements for cobalt-based pro-oxidants constrain European formulation flexibility and elevate compliance costs for imported masterbatches. Stakeholders must monitor whether pending EFSA opinions trigger cascading restrictions across EU member state implementation regimes or open pathway for harmonized certification.
Market Dynamics
EFSA's ongoing review of cobalt and manganese stearate migration thresholds is compressing formulation flexibility across European converters while redirecting procurement volumes toward BIS-certified Indian suppliers and MOHAP-compliant Gulf channels.
Growth Catalysts
- MOHAP Import Standards:The UAE's tightened single-use plastic regulations are redirecting Gulf procurement toward certified oxo-biodegradable alternatives, opening institutional volume channels for film-grade converters.
- Food Retail Certification:European supermarket chains now mandate shelf-life performance alongside biodegradation claims, pulling margin-rich film orders from certified compounders.
- Maharashtra-Gujarat Corridor:India's BIS-certified converter base supplies domestic FMCG brands, capturing replacement demand as conventional plastic faces state-level restrictions.
Market Restraints
- REACH Registration Burden:Cobalt-based pro-oxidant compliance costs constrain European formulation flexibility and elevate masterbatch import expenses.
- Technical Fragmentation Threshold:Oxo-biodegradable films require precise thermal-oxidative stress windows to trigger chain scission, limiting performance predictability across variable climates.
- Polyethylene Film Substitution:Conventional PE maintains cost parity and mature blown-film infrastructure, anchoring volume in price-sensitive institutional channels.
Strategic Opportunities
- EFSA Harmonization Pathway:Pending opinions may open EU-wide certification standards, reducing member-state implementation fragmentation for compliant additive suppliers.
- Marine-Grade Formulations:Transition-metal catalyst optimization for saltwater degradation environments addresses unmet institutional procurement in coastal jurisdictions.
- Asset-Light Leasing Models:Pro-oxidant masterbatch production line leasing fragments capital requirements, enabling mid-tier compounder entry without full facility investment.
Industry Challenges
- Migration Testing Timelines:EFSA additive safety threshold evaluations extend certification cycles, freezing product launches and inventory commitments.
- Blown-Film Retrofit Complexity:Standard extrusion equipment requires pro-oxidant dispersion calibration, demanding process engineering expertise scarce among legacy converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxo-Biodegradable Plastic Packaging Market |
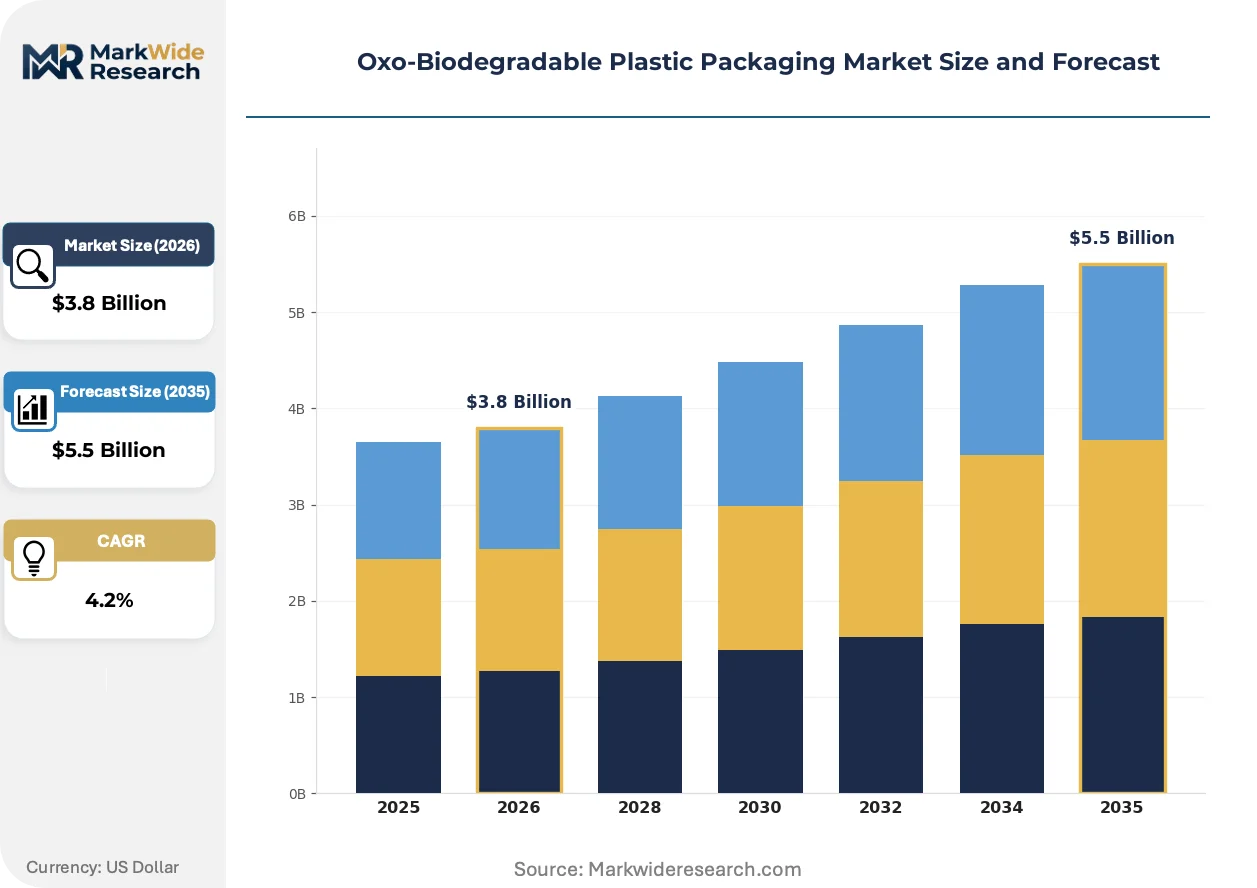
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Polystyrene, Polyvinyl Chloride Product Form: Film, Bag, Container, Wrap End User: Food Packaging, Personal Care, Electronics Packaging, Retail Packaging Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Willow Ridge Plastics Inc., NatureWorks LLC, Symphony Environmental Technologies Plc, BiologiQ Inc., Add-X Biotech AB, Wells Plastics Ltd, Mondi Group, Natur-Tec, EPI Environmental Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxo-Biodegradable Plastic Packaging Market Evolving Landscape
Formulation chemistry, regulatory harmonization pressure, and buyer procurement restructuring are converging to reshape competitive positioning across the oxo-biodegradable packaging value chain.
Non-cobalt pro-oxidant systems utilizing manganese and iron complexes are collapsing the regulatory compliance burden that has constrained European market access. Food packaging buyers in Germany and France are accelerating qualification programs for these alternative catalysts. The shift is compressing technology licensing windows for incumbent patent holders while opening formulation partnerships for additive suppliers with metal-free intellectual property.
REACH registration requirements for cobalt stearates are forcing European compounders to restructure supply relationships toward pre-registered masterbatch importers. The industrial consequence is elevated working capital requirements and elongated qualification timelines for new film-grade products. Blown-film converters in Italy and Spain are responding by consolidating procurement volumes with established REACH-compliant suppliers, reducing qualified vendor pools.
Retail chain sustainability scorecards now weight biodegradation certification alongside unit economics, rotating procurement authority from packaging managers to centralized compliance functions. Institutional buyers in the UAE and Saudi Arabia are displacing spot-market purchasing with multi-year framework agreements tied to MOHAP certification. This concentration is most visible across Gulf supermarket private-label programs, where technical service capacity has become a tiebreaker criterion in supplier selection.
Oxo-Biodegradable Plastic Packaging Market Segmentation
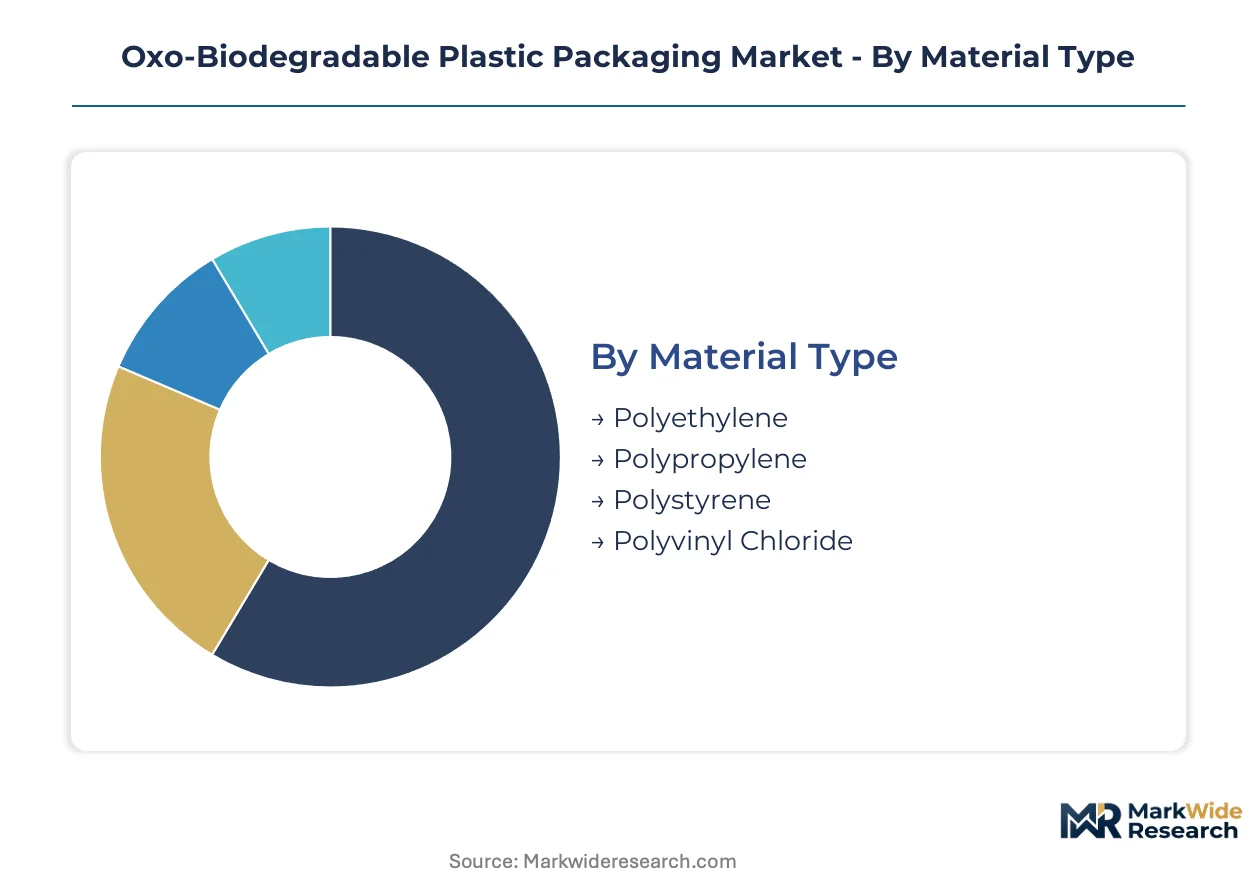
Segmentation in oxo-biodegradable packaging tracks how pro-oxidant additive compatibility varies across polymer matrices and how regulatory certification requirements fragment addressable markets by end-use. Buyers prioritize segments where biodegradation claims align with established performance testing protocols.
Material Type:
Mature blown-film infrastructure dominates polyethylene processing, while emerging catalyst formulations unlock polypropylene expansion in thermoforming applications.
- Polyethylene:Low-density and linear-low-density grades incorporate cobalt or manganese stearates at 1-3% loading without extrusion equipment modification. Maharashtra and Gujarat converters supply BIS-certified PE film to India's FMCG sector as state-level plastic bans tighten.
- Polypropylene:Higher crystallinity demands modified pro-oxidant dispersion systems to achieve comparable fragmentation kinetics. European compounders are accelerating manganese-complex formulations to bypass REACH registration burdens on cobalt stearates.
- Polystyrene:Foamed and solid grades serve protective packaging for electronics with limited thermal-oxidative stress exposure.
- Polyvinyl Chloride:Plasticizer migration conflicts constrain additive loading flexibility, restricting oxo-biodegradable claims to rigid profile applications.
Polyethylene handles the majority of throughput; polypropylene is expanding most quickly as thermoformed food trays gain retail certification traction.
Product Form:
Film formats command premium positioning through shelf-life certification, while bag volumes concentrate in institutional procurement channels where unit economics dominate.
- Film:Blown and cast structures achieve sub-50 micron gauges with maintained tensile properties for automated packaging lines. German and French supermarket chains now mandate film-grade biodegradation certification alongside oxygen barrier performance.
- Bag:T-shirt and die-cut configurations serve high-volume grocery and waste collection applications. MOHAP-compliant bag suppliers are capturing multi-year framework agreements across UAE and Saudi Arabia supermarket private-label programs.
- Container:Thermoformed and injection-molded formats target deli and prepared food segments with modified atmosphere requirements.
- Wrap:Cling and stretch variants compete with conventional PE on equipment compatibility and elongation recovery.
Film commands the steepest margin premium; bag volumes are climbing the fastest on Gulf institutional procurement restructuring.
End User:
Food packaging absorbs compliance investment due to migration testing requirements, while electronics and personal care segments follow certification spillover.
- Food Packaging:Direct contact applications demand EFSA-aligned additive safety thresholds and shelf-life validation. Retail chain sustainability scorecards now rotate procurement authority to centralized compliance functions that weight biodegradation certification alongside unit economics.
- Personal Care:Secondary and tertiary packaging for cosmetics leverages food-grade certification pathways with reduced migration testing intensity.
- Electronics Packaging:Protective foams and antistatic films prioritize static dissipation over biodegradation speed, constraining pro-oxidant loading ranges.
- Retail Packaging:Non-food merchandise bags and display wraps follow institutional buyer mandates where MOHAP or BIS certification serves as entry ticket.
Food packaging concentrates margin capture; retail packaging is gaining share fastest on regulatory displacement of conventional plastics.
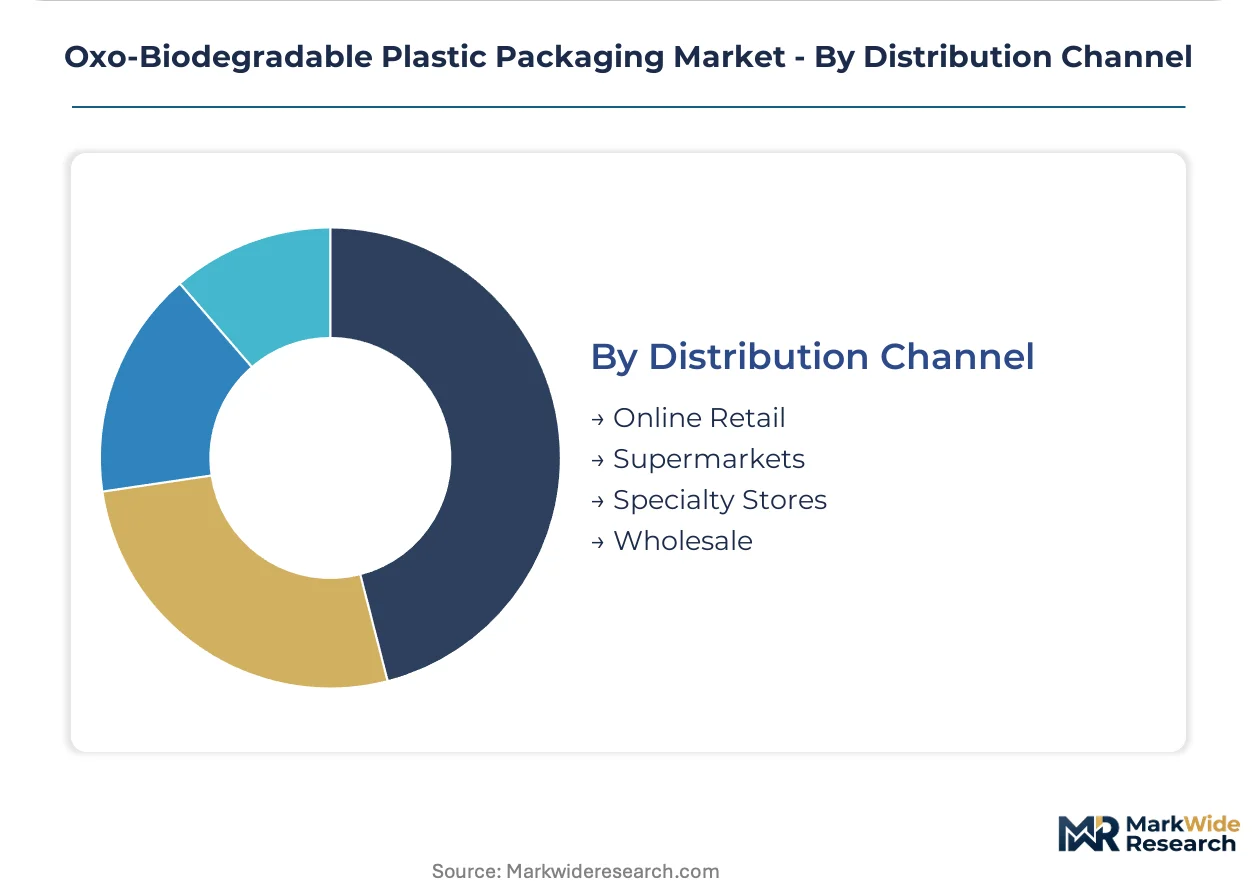
Distribution Channel:
Direct technical service relationships anchor high-volume film procurement, while spot-market channels fragment for standardized bag formats.
- Online Retail:E-commerce packaging buyers specify oxo-biodegradable mailers through sustainability procurement portals with tiered certification requirements.
- Supermarkets:Centralized private-label programs in the UAE and Saudi Arabia consolidate volumes with MOHAP-certified suppliers possessing regional technical service capacity.
- Specialty Stores:Premium positioning channels for compostable-claim adjacent products with consumer-facing certification labeling.
- Wholesale:Institutional and foodservice distributors aggregate demand from price-sensitive buyers with limited specification enforcement.
Supermarkets lock in the largest committed volumes; online retail is expanding most quickly on e-commerce sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian converters capture pricing power through BIS certification premiums while European compounders absorb REACH compliance cost penalties. Gulf procurement channels redirect volume toward MOHAP-compliant suppliers as UAE import standards tighten.
United Arab Emirates
Supermarket private-label programs in Dubai and Abu Dhabi consolidate multi-year procurement agreements with certified film suppliers. MOHAP's tightened single-use plastic import standards disqualify conventional polyethylene from institutional channels. The Jebel Ali industrial corridor hosts masterbatch compounders serving Gulf retail chains with technical service capacity as a tiebreaker criterion.
India
Maharashtra and Gujarat industrial corridors supply BIS-certified converters to domestic FMCG brands facing state-level plastic restrictions. The Plastic Waste Management Rules draft standards for oxo-biodegradable carry bags accelerate certification timelines for compounders. Ahmedabad and Mumbai host blown-film operations capturing replacement demand as conventional plastic faces regulatory displacement.
Germany
Supermarket chains mandate shelf-life performance alongside biodegradation claims, pulling margin-rich film orders from REACH-compliant compounders. EFSA's ongoing cobalt stearate migration reviews freeze product launches for non-registered additive suppliers. The Rhine-Ruhr industrial region anchors formulation partnerships for manganese-complex alternatives bypassing registration burdens.
United Kingdom
Technology licensing revenue sustains patent holders as asset-light leasing models fragment capital requirements for mid-tier compounders. Symphony Environmental Technologies leverages UK patent estates across emerging market distributor networks. The Midlands manufacturing belt hosts backward-integrated additive synthesis operations serving film-grade converters.
United States
North American distributor networks control regional technical service capacity for institutional buyers qualifying alternative catalyst systems. EPA regulatory positioning on oxo-biodegradable claims influences state-level procurement specifications for food packaging. The Gulf Coast petrochemical corridor supplies polyethylene resin to compounders developing marine-grade formulations for coastal jurisdictions.
Oxo-Biodegradable Plastic Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation IP and captive additive supply. The vendor base organizes around three strategic archetypes: patent-anchored technology licensors, backward-integrated compounders, and distributor-network-dependent service providers. Competitive moves concentrate on REACH-compliant formulation pivots and Gulf certification capture. Technology licensing windows compress as non-cobalt alternatives bypass regulatory barriers.
Among UK-based technology licensors, Symphony Environmental Technologies Plc and Wells Plastics Ltd occupy positions at opposite ends of the integration spectrum. Symphony exemplifies the patent-licensing archetype with revenue streams tied to emerging market access. Wells Plastics anchors British manufacturing scale through in-house additive synthesis. EPI Environmental Technologies Inc. represents the North American distributor-network model where regional technical service capacity determines institutional procurement outcomes.
| Leading Market Players |
|---|
| Willow Ridge Plastics Inc. |
| NatureWorks LLC |
| Symphony Environmental Technologies Plc |
| BiologiQ Inc. |
| Add-X Biotech AB |
| Wells Plastics Ltd |
| Mondi Group |
| Natur-Tec |
| EPI Environmental Technologies Inc. |
| Others |
Value Network & Pricing Analysis
The Jebel Ali-Dubai freight corridor's container cost dynamics compress margin pools for European compounders while amplifying pricing power for BIS-certified Indian suppliers serving Gulf institutional buyers. Supply concentration in Maharashtra-Gujarat industrial corridors feeds directly into three-tier pricing stratification across premium REACH-compliant, standard BIS-certified, and economy spot-market tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that separate MOHAP-certified premium tiers from spot-market economy grades. Price differentiation hinges on EFSA-aligned additive safety thresholds and volume scale commitments, with cost compression in standard tiers intensifying due to REACH registration burdens on cobalt stearates. Food packaging procurement teams exhibit lowest price sensitivity while institutional bag buyers drive aggressive unit economics negotiations.
Supply Chain Analysis
Tariff exposure between Germany and India dominates supply chain risk calculus for European compounders restructuring procurement relationships. Raw material dependencies center on Chinese cobalt stearate precursors, Saudi polyethylene resin, and Indian manganese-complex alternatives. Distribution runs through masterbatch importer networks with captive technical service capacity anchoring high-volume film procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around certification interoperability as MOHAP, BIS, and pending EFSA standards create gated ecosystem access. Masterbatch formulation IP is becoming the interoperability layer that determines supplier tier membership.
For Market Incumbents: Build regulatory certification moats through REACH-compliant manganese-complex R&D partnerships and backward integration into additive synthesis. Symphony Environmental Technologies and Wells Plastics demonstrate divergent paths: patent licensing revenue streams versus captive manufacturing scale. Defensive consolidation should target Gulf technical service capacity to capture MOHAP framework agreement volumes. For New Entrants and Emerging Players: Mid-tier compounders in India's industrial corridors represent the most penetrable entry point, leveraging asset-light leasing models for pro-oxidant masterbatch production lines. Marine-grade formulations for coastal UAE and Saudi Arabia jurisdictions offer uncertified white space. Go-to-market execution should anchor on BIS certification partnerships with Ahmedabad and Mumbai blown-film operators. For Investors and Strategic Acquirers: Patent-anchored technology licensors with emerging market distributor networks present the highest long-term viability framing across the 5-10 year regulatory harmonization window. The inflection signal to watch is EFSA's pending cobalt stearate migration opinion triggering cascading EU member state implementation regimes or opening harmonized certification pathways.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Pivot | Manganese-complex alternatives bypass ECHA registration burdens and unlock German supermarket procurement. |
| Gulf Certification Capture | MOHAP compliance secures multi-year framework agreements with UAE and Saudi Arabia retail chains. |
| Asset-Light Production Leasing | Pro-oxidant masterbatch line leasing fragments capital requirements for mid-tier Indian compounders. |
| Marine-Grade Catalyst Optimization | Saltwater degradation formulations address unmet institutional procurement in Dubai and Abu Dhabi coastal zones. |
| Backward Integration into Additive Synthesis | In-house cobalt and manganese stearate production anchors British manufacturing scale against import cost volatility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA additive safety evaluations, BIS draft standard notifications, and MOHAP import compliance circulars. Primary interviews engaged masterbatch plant managers, blown-film converter procurement leads, FMCG packaging directors, and Gulf retail chain sustainability officers. Secondary validation drew from customs trade data, REACH registration databases, and Plastic Waste Management Rule filings. Bottom-up volume triangulation against top-down market sizing anchored projection integrity.
Forecast inputs incorporate material type segmentation across polyethylene, polypropylene, polystyrene, and polyvinyl chloride matrices; product form dimensions spanning film, bag, container, and wrap formats; and end-use bifurcation between food packaging and retail institutional channels. CAGRs derive from regression analysis of historical procurement volumes against regulatory enforcement timelines. Industry-specific inputs include EFSA opinion publication schedules and Maharashtra state-level plastic restriction implementation phases.
Practitioners should monitor EFSA cobalt stearate threshold determinations, BIS final standard promulgation, and MOHAP enforcement intensity for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Biodegradable Food Packaging Market
Biodegradable Packaging
Middle East and Africa Biodegradable Film Market
Biodegradable Packaging
North America Biodegradable Film Market
Biodegradable Packaging
Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biodegradable Packaging Products Market
Biodegradable Packaging
North America Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Mushroom-Based Biodegradable Packaging Solutions Market
Biodegradable Packaging
Bioplastic Packaging Market
Biodegradable Packaging
Biodegradable Lids Market
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
Botanical Packaging Market
Biodegradable Packaging
Biodegradable Meal Trays Market
Biodegradable Packaging
Bioadhesives for Packaging Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Global Biodegradable Tableware Market
Biodegradable Packaging
Biopolymer Packaging Market