
 Vein Recognition Biometrics Market | 2026-2036
Vein Recognition Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Vein Recognition Biometrics Market Analysis
Japanese sensor manufacturers is rebalancing capacity toward near-infrared module production for vein recognition systems. Fujitsu Ltd. leverages its semiconductor heritage to sustain leadership in palm-vein algorithm development. Hitachi, Ltd. anchors its position through captive finger-vein sensor manufacturing. NEC Corporation differentiates via integrated multimodal biometric platforms that incorporate vein recognition alongside facial and iris matching.
Vein recognition biometrics authenticate identity by capturing subcutaneous vascular patterns illuminated through near-infrared light at wavelengths between 700 and 1000 nanometers, creating unique templates that resist spoofing since blood flow characteristics must match stored patterns. Financial services applications command the largest deployment base as banks replace fingerprint systems with contactless palm-vein terminals for ATM access and branch authentication. Near infrared technology dominates current installations while multispectral imaging represents the fastest-expanding segment due to its enhanced liveness detection capabilities. Cloud-based deployment models are gaining traction among retail and hospitality end users seeking centralized template management across distributed locations.
FDA guidance on biometric device cybersecurity, the EU AI Act's risk classification framework for biometric identification systems, and Japan's JIS biometric standards collectively shape product certification requirements and cross-border market access conditions. Compliance costs favor established vendors with dedicated regulatory affairs teams over emerging entrants. Stakeholders must monitor evolving interoperability standards between vein recognition and existing physical access control infrastructures as enterprise buyers increasingly demand unified credential management.
Market Dynamics
Contactless authentication mandates in financial services are compressing deployment timelines for vein recognition terminals, forcing sensor manufacturers to prioritize near-infrared module capacity over legacy fingerprint component lines.
Growth Catalysts
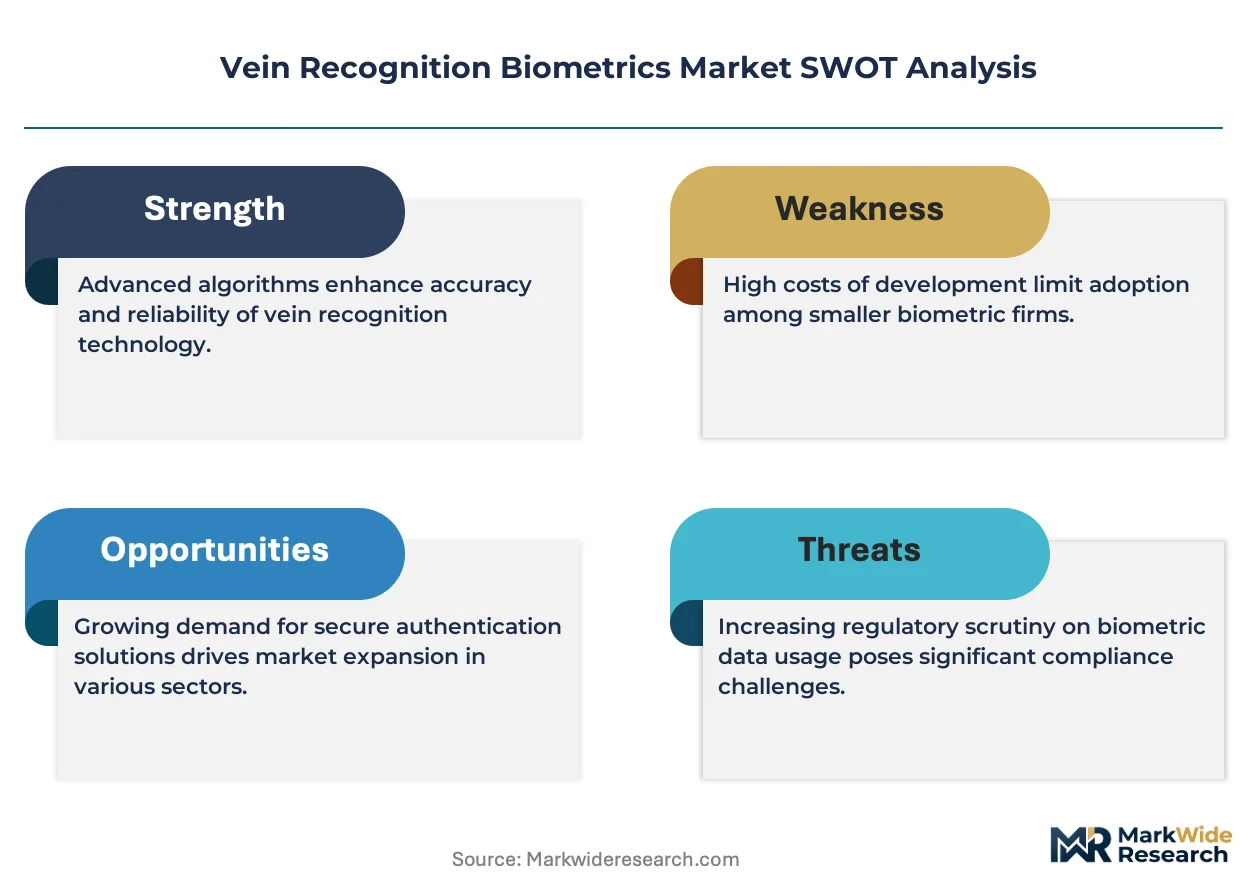
- EU AI Act risk classification:The framework's stringent requirements for biometric identification systems elevate privacy-preserving modalities like vein recognition above facial recognition in procurement evaluations for high-risk applications.
- Japan's manufacturing automation:Factory floor access control systems in automotive and electronics assembly plants are integrating finger-vein terminals to eliminate shared credential hygiene risks.
- Multispectral imaging advances:Enhanced liveness detection capabilities address spoofing vulnerabilities that previously constrained deployment in unattended environments.
Market Restraints
- Near-infrared sensor concentration:Japanese and South Korean suppliers control captive production of specialized CMOS modules, creating supply vulnerability for non-integrated algorithm vendors.
- GDPR biometric data processing requirements:Template storage and cross-border transfer restrictions impose compliance architecture costs that favor enterprise-scale deployments over mid-market adoption.
- Fingerprint system installed base:Existing contact-based infrastructure in banking and government facilities represents sunk capital that delays vein recognition refresh cycles.
Strategic Opportunities
- German healthcare digitization:Hospital patient identification and pharmaceutical dispensing workflows present underpenetrated demand for palm-vein authentication systems.
- Cloud template management:Centralized biometric-as-a-service architectures enable retail and hospitality chains to deploy distributed vein recognition without on-premise infrastructure investment.
- ISO/IEC 30107-3 presentation attack detection standards:Certification alignment creates procurement preference for compliant vendors in government and critical infrastructure tenders.
Industry Challenges
- Multimodal integration complexity:Enterprise buyers demand unified credential management across vein, facial, and iris systems, requiring API standardization that exceeds current interoperability frameworks.
- Specialized optical engineering talent:Near-infrared lens design and vascular pattern algorithm development skills concentrate in Japanese semiconductor clusters, constraining vendor expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vein Recognition Biometrics Market |
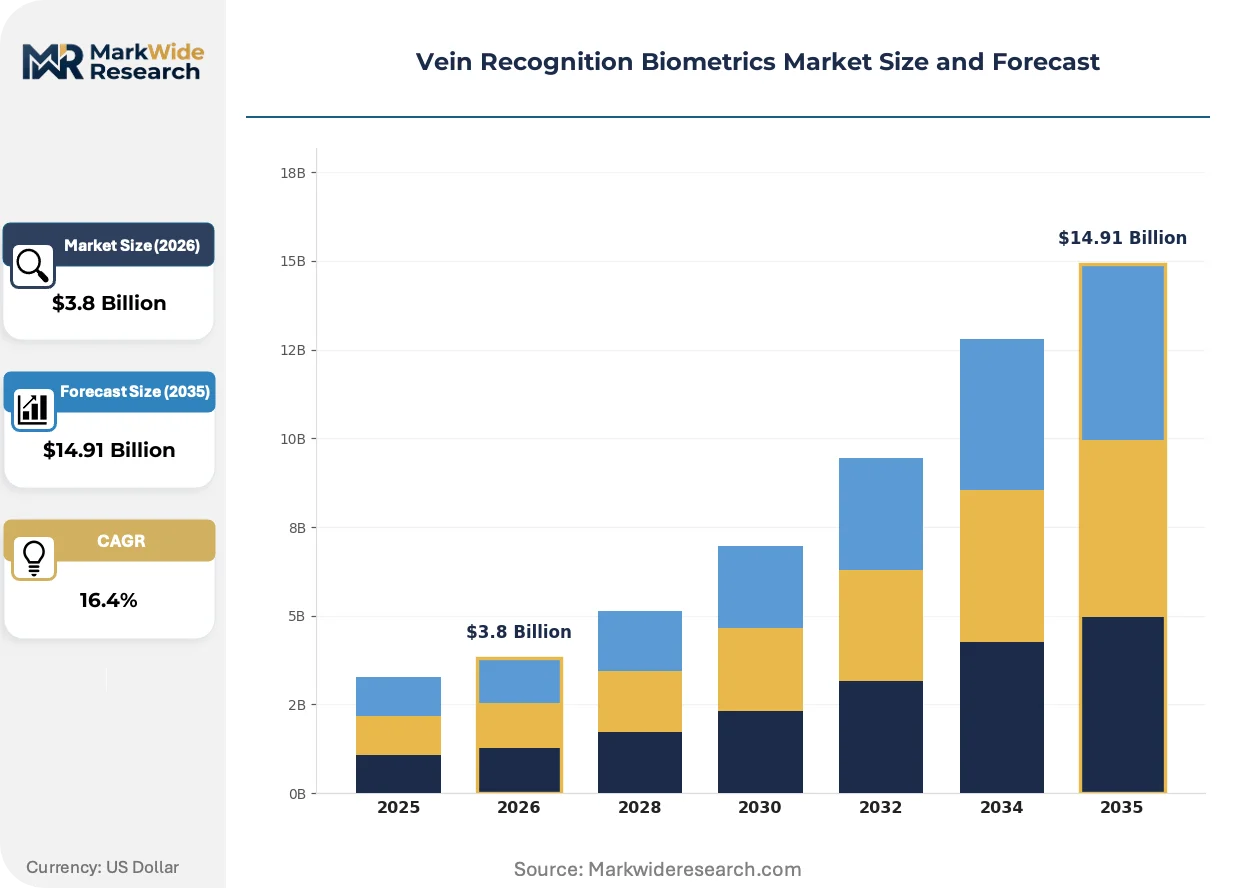
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Near Infrared, 3D Imaging, Optical Sensing, Multispectral Imaging Application: Financial Services, Healthcare, Security Access, Time & Attendance End User: Retail, Government, Education, Hospitality Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | M2SYS Technology, Safran, Fujitsu Ltd., IdentyTech Solutions, ZKTeco, Hitachi, Ltd., BioEnable Technologies, Saint Deem, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vein Recognition Biometrics Market Emerging Trajectories
Algorithmic advances in vascular pattern matching are compressing authentication latency while expanding deployment environments beyond climate-controlled interiors.
Multispectral imaging is automating liveness verification through simultaneous capture of visible and near-infrared wavelengths. Financial institutions in South Korea are deploying these systems at airport lounges and premium banking branches. The technology is automating the elimination of supervised authentication stations, reducing staffing requirements for high-security access points.
Japan's METI biometric standards revision is mandating interoperability testing for vein recognition modules deployed in government facilities. Manufacturers must submit to JIS-certified laboratory evaluation before national procurement eligibility. Japanese system integrators are accelerating pre-certification investments to secure positioning in upcoming municipal digital ID infrastructure tenders.
Subscription-based authentication service models are displacing perpetual license purchases among mid-market retail chains. Vein recognition vendors in Germany are piloting per-transaction pricing for point-of-sale identity verification. This shift is most visible in grocery and pharmacy segments where seasonal volume fluctuations make fixed capital commitments uneconomical.
Vein Recognition Biometrics Market Segmentation
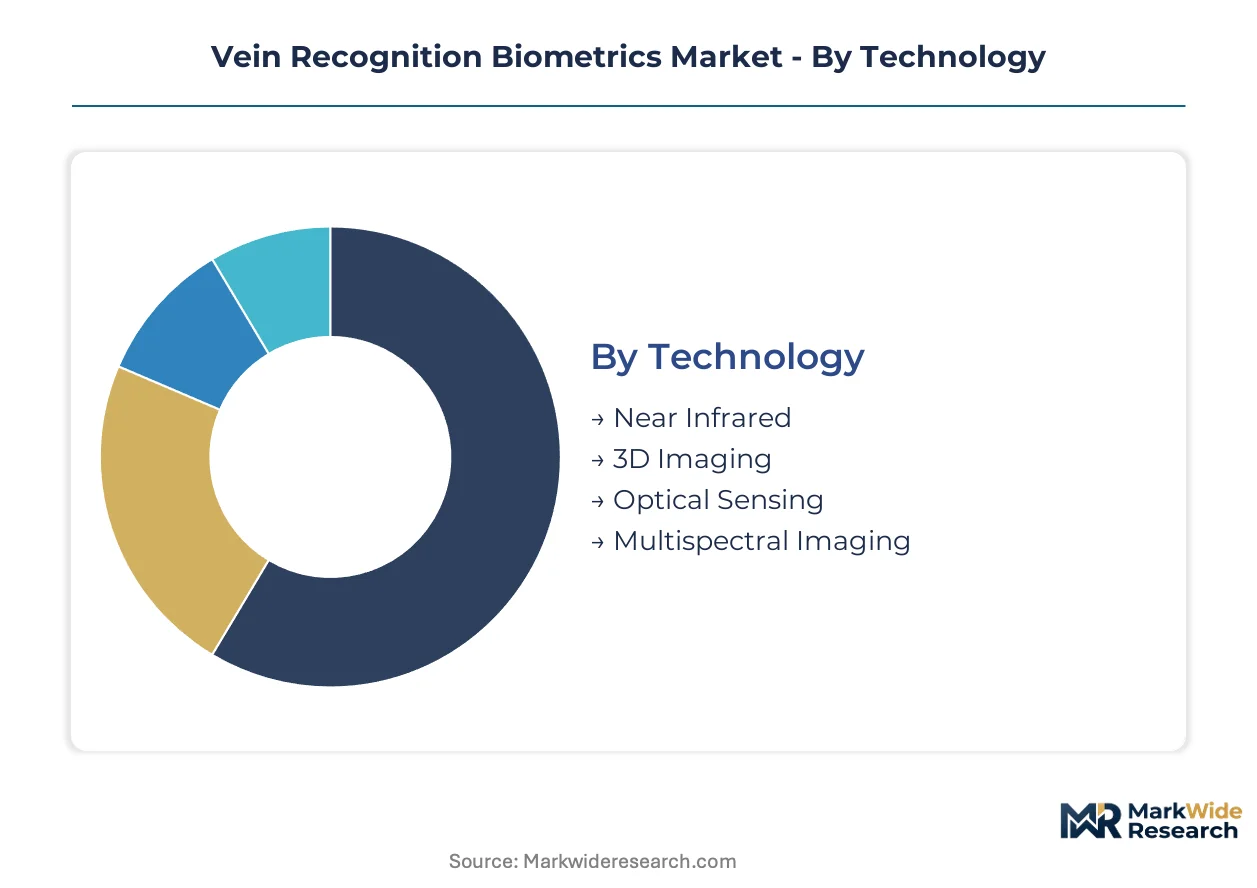
Vein recognition biometrics segment along four intersecting axes that determine procurement priorities and vendor positioning. Technology selection dictates hardware cost structures and spoofing resistance. Application context shapes compliance requirements and integration complexity.
Technology:
Near-infrared illumination wavelengths between 700 and 1000 nanometers define the technical foundation of vascular pattern capture systems.
- Near Infrared:Dominant illumination method using 850nm wavelength LEDs to penetrate skin tissue and reveal subcutaneous vascular structures. Financial services in Japan and South Korea deploy this technology for ATM and branch authentication due to proven reliability in climate-controlled environments. Maturity of CMOS sensor supply chains keeps unit economics favorable for high-volume manufacturing.
- Multispectral Imaging:Simultaneous capture across visible and near-infrared spectra enables automated liveness detection without human supervision. South Korean airport lounges and German pharmaceutical dispensing workflows adopt these systems for unattended high-security access points. Enhanced spoofing resistance justifies premium hardware costs in regulated environments.
- 3D Imaging:Depth-aware vascular reconstruction adds geometric verification to pattern matching.
- Optical Sensing:Conventional photodiode arrays for cost-sensitive entry-level deployments.
Near Infrared leads on scale; Multispectral Imaging leads on momentum.
Application:
End-use context determines regulatory exposure and integration architecture requirements.
- Financial Services:ATM access control and branch teller authentication drive the largest installed base. EU AI Act risk classification elevates privacy-preserving vein recognition above facial recognition for high-risk biometric identification. Contactless mandates accelerate replacement of fingerprint terminals.
- Security Access:Physical entry control for critical infrastructure and corporate facilities demands ISO/IEC 30107-3 presentation attack detection certification. Government tenders in Germany and Japan specify compliant multimodal platforms.
- Healthcare:Patient identification and medication dispensing workflows present underpenetrated demand.
- Time & Attendance:Workforce management applications prioritize cost efficiency over liveness detection sophistication.
Financial Services commands the largest revenue pool; Healthcare shows the steepest expansion trajectory.
End User:
Organizational scale and compliance maturity shape deployment model preferences.
- Government:National ID infrastructure and municipal digital identity programs require JIS-certified interoperability testing in Japan. Procurement eligibility depends on laboratory evaluation of vein recognition modules.
- Retail:Mid-market chains favor subscription-based authentication services over perpetual licenses. German grocery and pharmacy segments pilot per-transaction pricing to match seasonal volume fluctuations.
- Education:Campus access and examination proctoring applications.
- Hospitality:Premium hotel chains and airport lounges seek centralized template management.
Government drives certification standards; Retail is climbing the fastest on cloud service adoption.
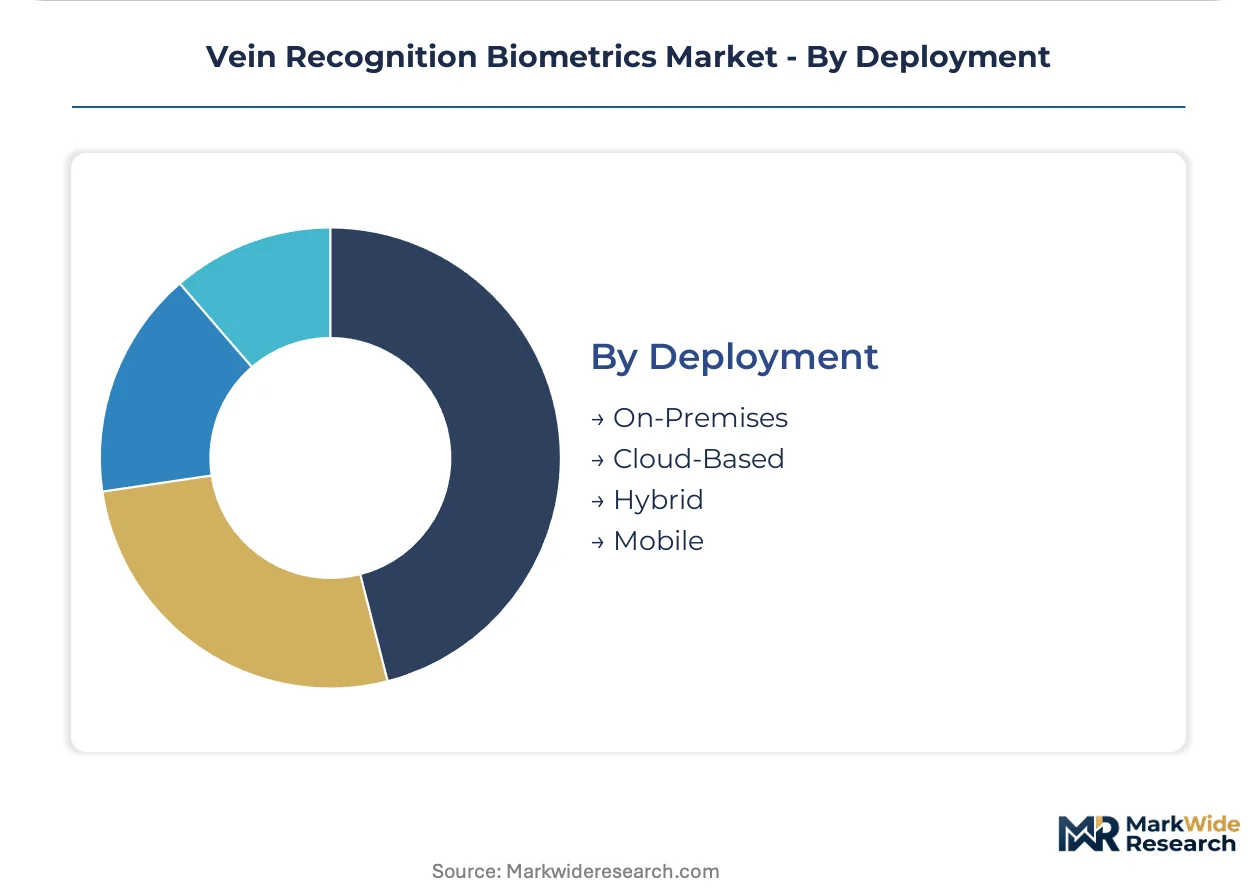
Deployment:
Infrastructure ownership models determine capital allocation and data sovereignty compliance.
- Cloud-Based:Centralized biometric-as-a-service architectures enable distributed deployment without on-premise infrastructure. GDPR template storage and cross-border transfer restrictions impose compliance architecture costs that favor enterprise-scale retail and hospitality chains.
- On-Premises:Local template storage satisfies data residency requirements for government and financial institutions. Higher upfront capital commitment delays refresh cycles in facilities with existing fingerprint infrastructure.
- Hybrid:Edge processing with cloud synchronization for multi-site enterprises.
- Mobile:Smartphone-integrated near-infrared modules for portable authentication.
On-Premises retains the largest installed base; Cloud-Based gains share fastest among new deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as compliance cost differentials between jurisdictions drive near-infrared module manufacturing toward established semiconductor clusters. Japanese and South Korean suppliers leverage captive CMOS fabrication to serve financial services demand, while European vendors absorb GDPR certification overhead to access government procurement channels.
Japan
Factory floor automation in automotive and electronics assembly plants drives finger-vein terminal demand for hygiene-critical access control. METI's biometric standards revision mandates JIS-certified interoperability testing for government facility deployments. The Kanto region around Tokyo concentrates system integrators accelerating pre-certification investments for municipal digital ID infrastructure tenders.
Germany
Hospital patient identification and pharmaceutical dispensing workflows present expansion opportunities for palm-vein authentication systems. The EU AI Act's risk classification framework elevates privacy-preserving modalities in high-risk biometric procurement evaluations. Bavaria's industrial automation cluster integrates vein recognition into manufacturing execution systems for regulated production environments.
South Korea
Airport lounges and premium banking branches deploy multispectral imaging terminals for unattended high-security access points. The country's national biometric standards align with ISO/IEC 30107-3 presentation attack detection requirements. Seoul Capital Area fintech operators pilot per-transaction pricing models for retail point-of-sale identity verification.
United States
Financial services contactless authentication mandates compress deployment timelines for ATM and branch infrastructure refresh cycles. FDA guidance on biometric device cybersecurity shapes product certification requirements for cross-border market access. Greater Boston's healthcare technology corridor evaluates palm-vein systems for patient identification workflow integration.
China
Manufacturing automation investments in electronics assembly create demand for factory floor access control systems with liveness detection capabilities. GB standards for biometric data protection impose localization requirements on template storage architectures. The Yangtze River Delta semiconductor cluster develops domestic near-infrared sensor supply chains to reduce import dependency.
Vein Recognition Biometrics Market Vendor Landscape
Japanese producers anchor the sensor manufacturing tier; German and South Korean specialists hold algorithm development and system integration positions. The vendor structure concentrates around three strategic archetypes: captive semiconductor fabricators with backward integration into near-infrared module production, multimodal platform integrators combining vein recognition with complementary biometrics, and cloud-native authentication service providers. Capacity expansion in Japanese CMOS foundries and strategic partnerships between sensor makers and financial technology deployers constitute the dominant competitive moves.
Within the captive fabrication tier, Fujitsu Ltd. and Hitachi, Ltd. represent integrated hardware-software positioning through semiconductor heritage and sensor manufacturing lineage. NEC Corporation occupies a position exemplifying multimodal platform architecture, anchoring enterprise-scale deployments that unify credential management across biometric modalities. These three Japanese entities collectively illustrate how regulatory compliance capabilities and captive production capacity create procurement preference in government and financial services tenders.
| Leading Market Players |
|---|
| M2SYS Technology |
| Safran |
| Fujitsu Ltd. |
| IdentyTech Solutions |
| ZKTeco |
| Hitachi, Ltd. |
| BioEnable Technologies |
| Saint Deem |
| NEC Corporation |
| Others |
Supply Flow & Price Mechanics
Captive semiconductor fabrication in Japanese and South Korean foundries anchors both supply security and pricing power for near-infrared sensor modules, creating tiered procurement economics that favor integrated vendors over pure-play algorithm developers. This backward integration into CMOS production lines insulates dominant suppliers from component cost volatility while compressing margins for non-captive competitors.
Pricing Analysis
Distributor margins on vein recognition terminals range from 15% to 25% depending on certification tier, with direct-to-OEM volume contracts commanding steeper discounts. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by ISO/IEC 30107-3 PAD certification status and after-sales service bundling. Pricing pressure stems from cloud-native authentication service providers entering with subscription models that displace perpetual license revenue. Mid-market retail chains exhibit highest price sensitivity, while government tenders prioritize certification compliance over unit cost.
Supply Chain Analysis
Optical engineering talent shortages in the Kanto and Seoul Capital Area clusters constrain expansion of near-infrared lens design and vascular pattern algorithm development capacity. Module assembly concentrates in Japan, South Korea, and Taiwan, drawing from specialized 850nm wavelength LED and CMOS sensor inputs. Single-source vulnerability around Japanese captive CMOS production creates exposure for non-integrated vendors. Distribution runs through system integrators serving financial services and government verticals, with direct OEM relationships dominating enterprise-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vein recognition biometrics constitute a late-cycle quality story as EU AI Act risk classification redirects procurement toward privacy-preserving modalities with superior spoofing resistance. Financial services contactless mandates accelerate replacement of legacy fingerprint infrastructure with premium-certified vein terminals.
For Market Incumbents: Cement algorithm differentiation through multispectral imaging R&D investments that automate liveness detection without human supervision. Fortify captive sensor production in Japanese foundries against emerging Chinese CMOS supply chains. Prioritize JIS and ISO/IEC 30107-3 certification maintenance to defend government tender eligibility against cloud-native entrants.
For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for privacy-preserving biometric positioning against facial recognition incumbents in high-risk procurement evaluations. Target German healthcare digitization workflows for patient identification and pharmaceutical dispensing as the most penetrable vertical. Pursue biometric-as-a-service subscription models to bypass capital-intensive on-premise infrastructure requirements.
For Investors and Strategic Acquirers: Roll-up economics work for multimodal platform integrators because enterprise buyers increasingly demand unified credential management across vein, facial, and iris systems. Five-to-ten year viability hinges on regulatory compliance capabilities and cloud template management infrastructure. Monitor cloud service adoption rates among mid-market retail chains as the inflection signal for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| JIS Certification Investment | METI standards revision mandates laboratory evaluation before Japanese government procurement eligibility. |
| Multispectral Imaging Product Launch | South Korean airport lounges deploy automated liveness detection for unattended high-security access points. |
| Cloud Template Management Platform | GDPR-compliant biometric-as-a-service architectures enable distributed retail deployment without on-premise infrastructure. |
| Healthcare Workflow Integration Partnership | German hospital patient identification systems present underpenetrated demand for palm-vein authentication. |
| Backward Integration into Near-Infrared Module Production | Captive CMOS fabrication insulates vendors from Japanese and South Korean supplier concentration risks. |
Methodological Framework
Coverage spans Japan, South Korea, Germany, and the United States, with primary inputs from each regional cluster combining interviews with biometric system integrators, financial services security officers, healthcare IT procurement managers, and optical sensor manufacturing executives. Secondary validation draws from METI biometric standards documentation, EU AI Act regulatory filings, FDA cybersecurity guidance, and ISO/IEC 30107-3 certification records. Bottom-up demand modeling from end-user deployment data triangulates against top-down market sizing from supplier capacity disclosures.
Rate-of-change decomposition separates volume expansion from value migration across technology tiers, deployment models, and application verticals throughout the forecast period. Segmentation dimensions include illumination method, application context, end-user organizational scale, and infrastructure ownership model. CAGRs derive from installed base refresh cycle analysis, regulatory mandate implementation timelines, and cloud service adoption trajectory across retail and hospitality chains. Near-infrared sensor supply constraints and multispectral imaging cost curves inform technology transition assumptions.
Revisions become necessary when regulatory enforcement timelines shift, supply chain disruptions alter module availability, or multimodal integration standards achieve interoperability breakthroughs. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Global Biometric Identification Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
IRIS Biometrics Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market
Biometrics & Identity Management
FIDO Authentication Market
Biometrics & Identity Management
Biometric Bike Locks Market
Biometrics & Identity Management
Biometric Smart Cards Market
Biometrics & Identity Management
Global Biometric Technology Market
Biometrics & Identity Management
Authentication Solution Market
Biometrics & Identity Management
Latin America Biometrics Market
Biometrics & Identity Management
Military Biometrics Market
Biometrics & Identity Management
Biometric Point-Of-Sale Terminals Market
Biometrics & Identity Management
ID Verification Market
Biometrics & Identity Management
United States Biometrics Market
Biometrics & Identity Management
Biometric Passport Market