
 Middle East and Africa Biofertilizers Market | 2026-2036
Middle East and Africa Biofertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Biofertilizers Market Foresight
Market Context
Synthetic nitrogen is restructuring cost equations across Egyptian and Moroccan farming systems as urea price volatility pushes growers toward rhizobia-based alternatives. UPL Limited leverages its distribution footprint across Sub-Saharan Africa to preempt channel access for biological inputs. Lallemand Inc anchors its position through yeast-fermentation expertise adapted to arid-soil microbiome conditions. Novonesis Group differentiates via enzymatic co-formulation platforms that extend product stability in high-temperature storage environments.
Technical Definition and Segment Structure
Middle East and Africa biofertilizers comprise live microbial preparations containing nitrogen-fixing bacteria, phosphate-solubilizing fungi, or plant-growth-promoting rhizobacteria formulated in carrier materials with colony counts typically exceeding 10^8 CFU per gram for agricultural application. These preparations function primarily to enhance nutrient availability in saline-alkaline soils prevalent across the region's dominant cereal and vegetable production zones. Liquid biofertilizers lead volume uptake due to compatibility with drip irrigation infrastructure spreading across Israeli and Jordanian desert agriculture, while granular formulations sustain margin pools where mechanical broadcasting dominates wheat cultivation in Ethiopia and Sudan. The organic farming end-use channel registers the steepest adoption trajectory as Gulf state food security programs prioritize domestic biological input sourcing.
Regulatory Framework and Outlook
South Africa's Registrar of Act 36 of 1947 governs biological product registration timelines, while Egypt's Ministry of Agriculture and Land Reclamation enforces import permit requirements for foreign-manufactured inoculants that constrain market entry velocity. The African Union's Fertilizer and Soil Health Summit framework coordinates cross-border harmonization efforts that will reshape product labeling and efficacy documentation standards. Stakeholders must monitor how Saudi Arabia's SFDA and UAE's MOHAP extend their food safety mandates into biological input supply chain traceability requirements.
Market Dynamics
Synthetic nitrogen price volatility is compressing Egyptian and Moroccan farming margins, accelerating rhizobia-based formulation trials across the Nile Delta and Marrakech-Safi corridor. Urea import dependency is restructuring procurement calendars and forcing biological input validation at commercial scale.
Growth Catalysts
- Egypt's import permit requirements:Domestic blending facilities gain protected market access as foreign inoculant registrations face extended timelines. Local production capacity is scaling to capture this regulatory shelter.
- Drip irrigation infrastructure:Israeli and Jordanian desert agriculture operators are integrating liquid biofertilizer injection systems. Compatibility with precision fertigation protocols is accelerating microbial adoption in water-stressed vegetable zones.
- Phosphorus-solubilizing formulations:Nile Delta growers confronting soil salinity are prioritizing fungal inoculants over rock phosphate applications. Field trials demonstrate yield recovery in alkaline conditions without synthetic amendment stacking.
Market Restraints
- Carrier material cost volatility:Peat and vermiculite sourcing from East African suppliers faces climate-driven harvest inconsistency. Formulation economics compress when carrier prices spike during drought cycles.
- Cold chain gaps in Sub-Saharan distribution:Viable cell count degradation during ambient-temperature transport from South African production hubs to Kenyan and Ethiopian end-users constrains efficacy guarantees.
- Synthetic nitrogen substitution economics:Urea price collapses during Russian export surges temporarily invert the cost advantage for biological alternatives. Grower switching calculus remains tethered to spot fertilizer markets.
Strategic Opportunities
- Sudan's mechanized wheat belt:Granular biofertilizer broadcasting equipment penetration lags behind seed drill adoption. Equipment retrofit partnerships could unlock volume in this underpenetrated cultivation zone.
- Saudi Arabia's SFDA traceability mandates:Biological input supply chain documentation requirements favor integrated producers with in-house quality verification. First-movers capturing certification infrastructure will secure preferred supplier status.
- Enzymatic co-formulation with biostimulants:Novonesis-type platforms combining microbial inoculants with protein hydrolysates are expanding into high-value export crop segments. Premium positioning in date palm and citrus orchards justifies formulation complexity.
Industry Challenges
- Microbiologist talent scarcity:Quality control laboratories in Morocco and Egypt struggle to staff CFU enumeration and contamination testing roles. Training pipeline gaps extend product release timelines.
- Act 36 registration documentation:South Africa's biological product approval process demands multi-season efficacy data that delays revenue recognition for new entrants. Capital lockup periods strain SME balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Biofertilizers Market |
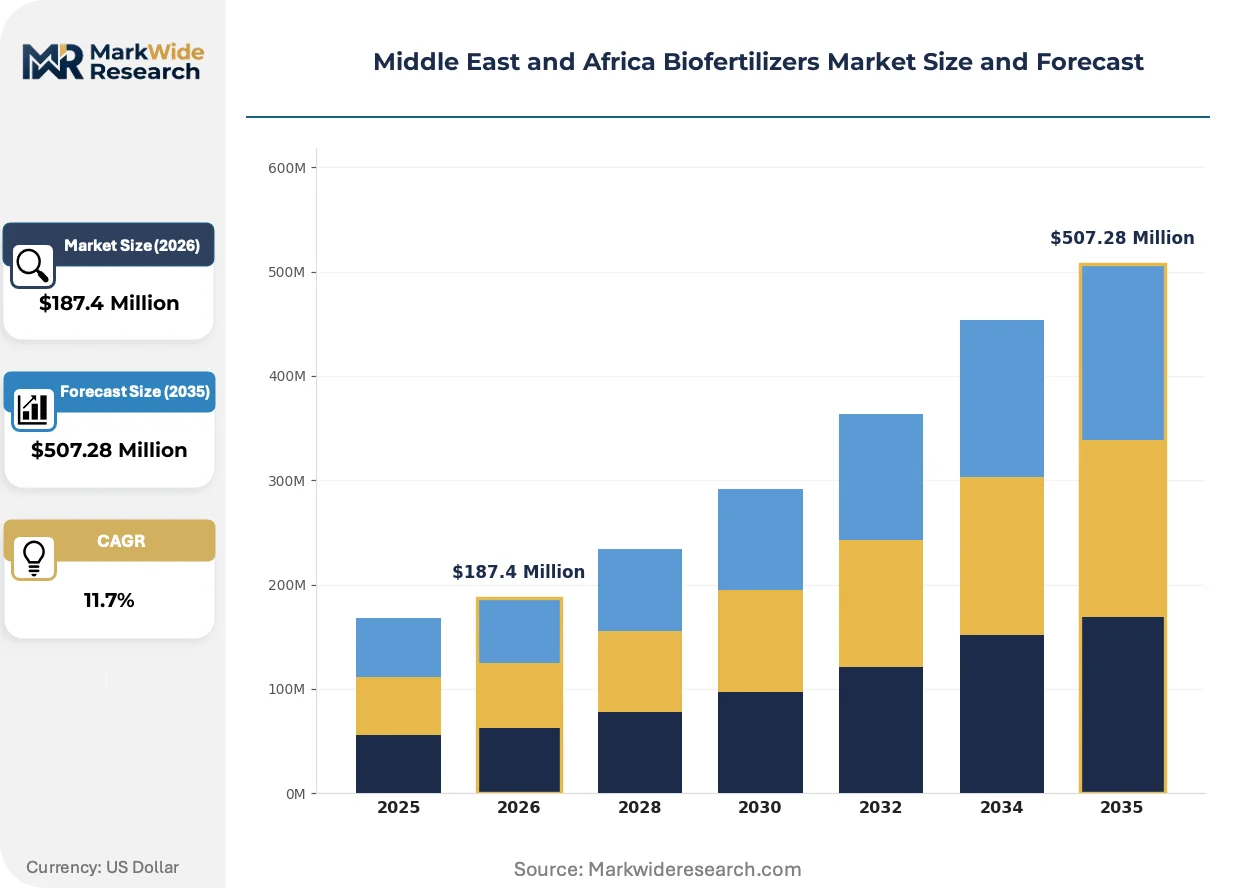
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Biofertilizers, Granular Biofertilizers, Powder Biofertilizers, Biofertilizer Coatings Application: Agronomic Crops, Horticultural Crops, Forage Crops, Turf and Ornamentals End Use Industry: Agriculture, Horticulture, Forestry, Organic Farming Distribution Channel: Online Sales, Retail Stores, Wholesalers, Agricultural Cooperatives |
| Companies Covered | UPL Limited, Lallemand Inc, Corteva Agriscience, Novonesis Group, Rizobacter Argentina S.A., Symborg, FMC Corporation, IPL Biologicals Limited, Biomax, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Biofertilizers Market Shifts & Advancements
Multi-strain consortia formulations are displacing single-species inoculants across commercial agriculture. This shift reflects grower demand for stacked functional traits and supplier efforts to differentiate beyond commodity nitrogen fixation.
Consortium-based microbial products combining nitrogen-fixing bacteria with phosphate-solubilizing fungi and plant-growth-promoting rhizobacteria are expanding into South African specialty crop programs. Table grape and citrus exporters facing EU residue standards are adopting these complex formulations to reduce synthetic input dependency. The technology is expanding into contract farming arrangements where packhouses specify biological protocols for export certification compliance.
South Africa's Registrar of Act 36 of 1947 is tightening efficacy documentation requirements for biological soil amendments. Foreign manufacturers now face extended field trial obligations before registration approval, compressing market entry velocity for new entrants. Domestic blenders with established trial networks are capturing protected market share as regulatory friction intensifies.
Buyers in Egypt's Nile Delta farming corridor are consolidating procurement through agricultural cooperative federations rather than individual dealer relationships. These federations negotiate volume-based pricing and technical support packages directly with formulation suppliers. The consolidation is most visible in Kafr El Sheikh and Dakahlia governorates where water user associations have extended their mandate into input sourcing coordination.
Middle East and Africa Biofertilizers Market Segmentation
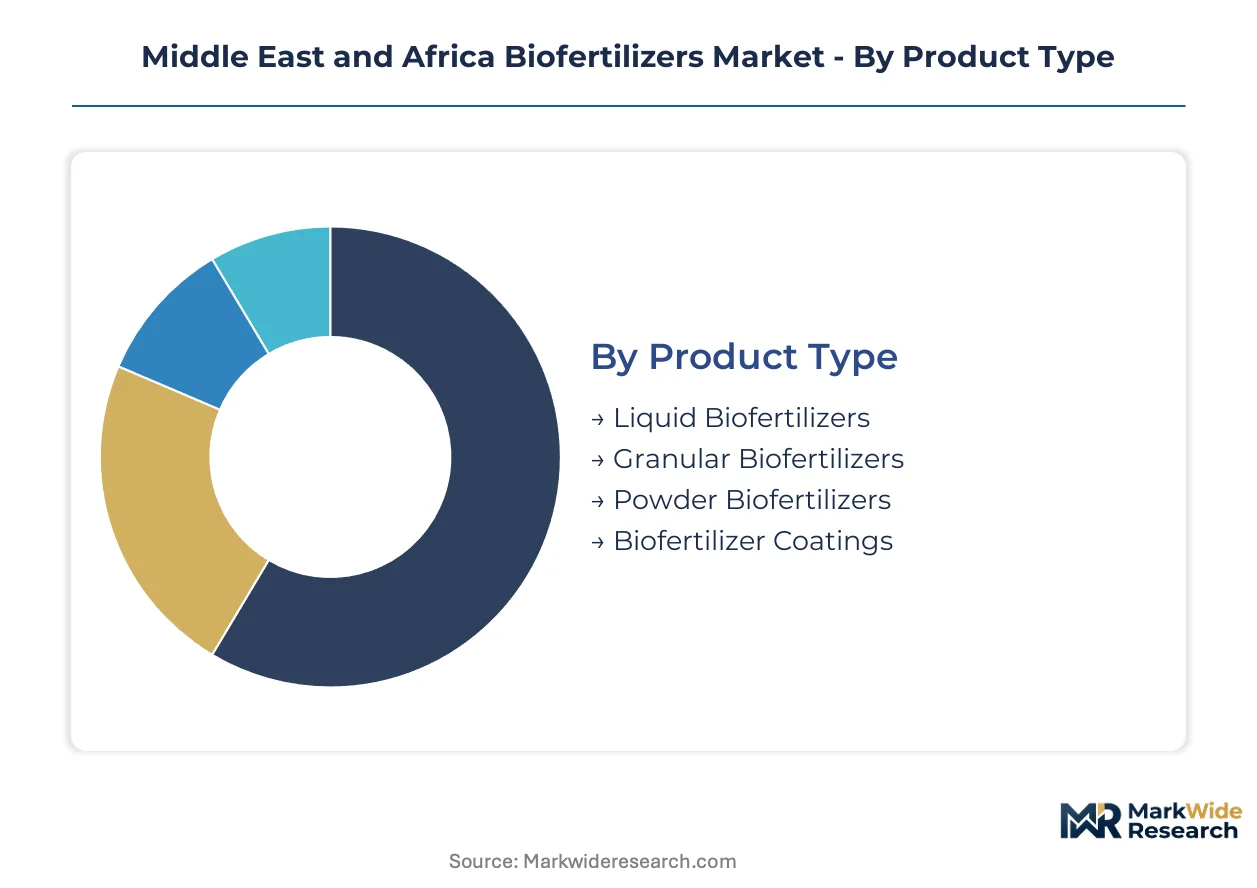
Formulation physics and irrigation infrastructure dictate product selection across Middle East and Africa biofertilizers. Each segment category carries distinct capital requirements, regulatory exposure, and margin profiles that shape supplier positioning.
Product Type:
Liquid and granular formats demand divergent production footprints. Fermentation tanks and sterile filling lines require substantial upfront investment, while granular compaction and coating equipment scales more incrementally.
- Liquid Biofertilizers:Microbial suspensions in aqueous carriers with colony counts exceeding 10^8 CFU per milliliter. Israeli and Jordanian desert agriculture operators inject these formulations through drip irrigation infrastructure, with precision fertigation compatibility driving adoption in water-stressed vegetable zones.
- Granular Biofertilizers:Microbial preparations bound to mineral carriers for mechanical broadcasting. Wheat cultivation across Ethiopia and Sudan sustains demand where seed drill penetration exceeds liquid injection system deployment.
- Powder Biofertilizers:Lyophilized or air-dried microbial concentrates requiring reconstitution before application. Smallholder cooperatives in Kenya favor this format for transport economics and extended ambient storage stability.
- Biofertilizer Coatings:Microbial films applied directly to seed surfaces. South African specialty crop producers use these for table grape and citrus export programs facing EU residue standard compliance.
Granular biofertilizers absorb the bulk of installed capacity; liquid biofertilizers are expanding most quickly.
Application:
Crop value per hectare determines formulation sophistication and price tolerance. High-value horticultural segments justify multi-strain consortia and enzymatic co-formulations that commodity grain applications cannot support.
- Agronomic Crops:Cereal and legume production across the Nile Delta and Sudan's mechanized wheat belt. Urea price volatility is accelerating rhizobia-based formulation trials as growers seek nitrogen fixation alternatives.
- Horticultural Crops:Table grape, citrus, and date palm cultivation for export markets. EU residue standards and packhouse certification requirements are mandating biological protocol adoption in South African and Egyptian operations.
- Forage Crops:Alfalfa and clover production for dairy and livestock feed. Moroccan dairy cooperatives are integrating phosphate-solubilizing inoculants to reduce imported rock phosphate dependency.
- Turf and Ornamentals:Golf course and landscaping applications concentrated in Gulf state urban developments. Saudi Arabia's domestic food security programs are prioritizing biological input sourcing for municipal greening projects.
Horticultural crops command premium formulation pricing; agronomic crops dominate volume throughput.
End Use Industry:
Certification requirements and subsidy eligibility fragment customer economics. Organic farming channels face mandatory biological input compliance, while conventional agriculture responds to spot fertilizer market arbitrage.
- Agriculture:Broadacre cereal and oilseed production across rainfed and irrigated systems. Egypt's Ministry of Agriculture and Land Reclamation enforces import permit requirements that protect domestic blending facilities.
- Horticulture:Intensive fruit and vegetable cultivation under protected structures or precision irrigation. Israeli desert agriculture operators integrate liquid biofertilizer injection with climate-controlled greenhouse systems.
- Forestry:Plantation establishment and reforestation programs. Limited commercial penetration reflects extended rotation periods and public-sector procurement cycles.
- Organic Farming:Certified operations across Gulf state food security initiatives. Domestic biological input sourcing mandates are accelerating local production capacity scaling.
Conventional agriculture channels absorb majority volume; organic farming is climbing the fastest.
Distribution Channel:
Channel selection determines working capital intensity and technical service obligations. Direct cooperative relationships lock in volume commitments but demand agronomic support infrastructure.
- Online Sales:E-commerce platforms serving smallholder farmers with limited dealer access. Kenyan and Ethiopian buyers are consolidating orders through mobile-enabled marketplaces.
- Retail Stores:Agro-dealer networks with localized inventory and credit extension. South Africa's Registrar of Act 36 of 1947 governs product registration timelines that constrain foreign manufacturer shelf placement.
- Wholesalers:Regional distributors managing bulk logistics from South African production hubs. Cold chain gaps during ambient-temperature transport to Sub-Saharan end-users constrain efficacy guarantees.
- Agricultural Cooperatives:Federated procurement across Egypt's Nile Delta farming corridor. Kafr El Sheikh and Dakahlia governorate water user associations have extended mandates into input sourcing coordination.
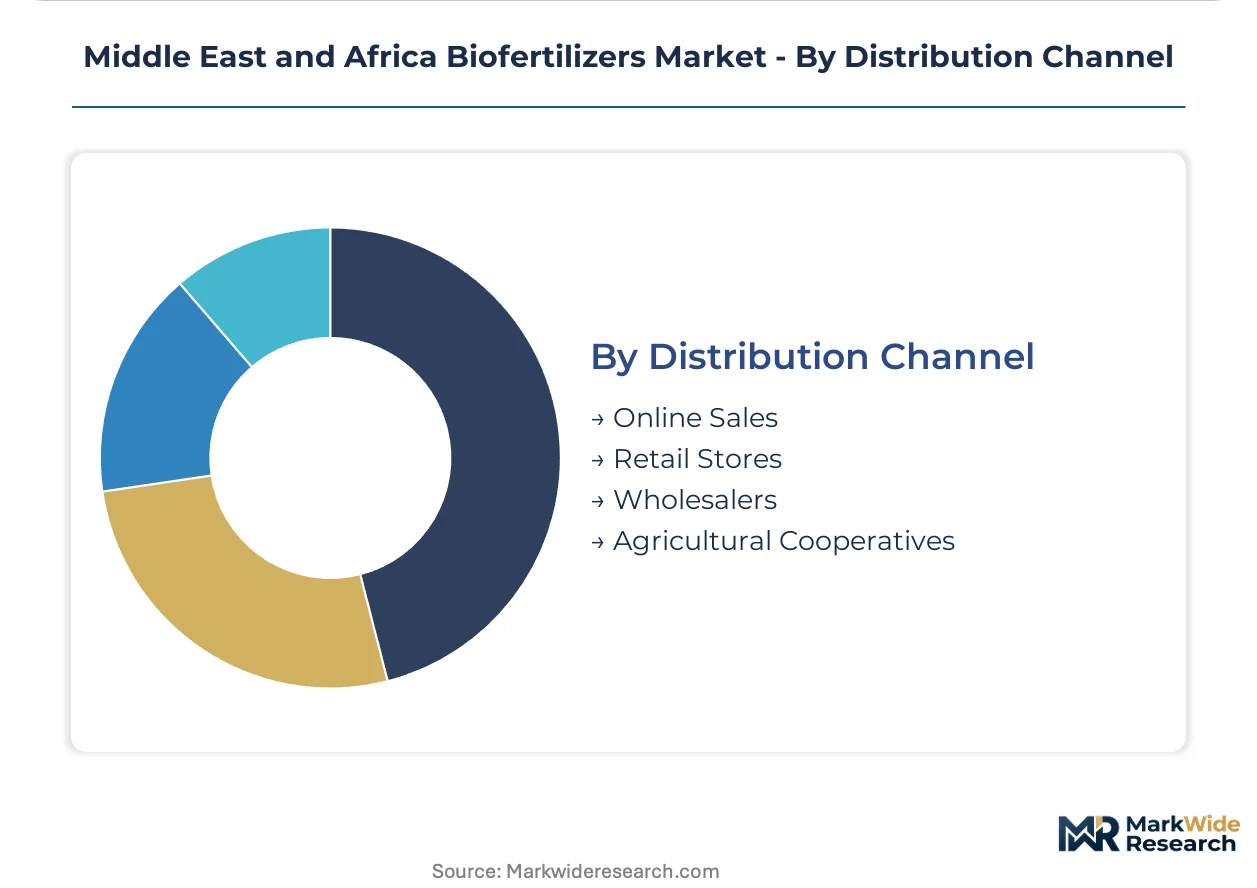
Agricultural cooperatives are gaining share fastest; retail stores retain the deepest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's Nile Delta farming corridor concentrates demand for phosphorus-solubilizing formulations where water-stressed growers face soil salinity constraints. South African specialty crop producers drive microbial inoculant adoption to meet EU export residue standards. Morocco's regulatory tightening and Sudan's mechanized wheat expansion complete the regional demand map.
Egypt
Nile Delta vegetable growers prioritize liquid biofertilizer integration with drip irrigation systems to combat alkaline soil conditions. The Ministry of Agriculture and Land Reclamation enforces import permit requirements that protect domestic blending facilities from foreign competition. Kafr El Sheikh and Dakahlia governorates host cooperative federations consolidating procurement through water user associations.
South Africa
Table grape and citrus exporters adopt multi-strain consortia to reduce synthetic nitrogen dependency ahead of EU certification audits. The Registrar of Act 36 of 1947 governs biological product registration timelines with multi-season efficacy documentation demands. Western Cape fruit packhouses now specify biological protocols for export compliance.
Morocco
Dairy cooperatives integrate phosphate-solubilizing inoculants to cut imported rock phosphate reliance in forage production. The national fertilizer regulator has tightened import certification rules for biological soil amendments. Marrakech-Safi corridor growers trial rhizobia-based alternatives as urea price volatility compresses margins.
Israel
Desert agriculture operators inject liquid biofertilizers through precision fertigation infrastructure in water-stressed vegetable zones. The national agricultural research system validates microbial efficacy under arid-soil microbiome conditions. Negev desert greenhouses anchor regional liquid formulation demand.
Sudan
Mechanized wheat belt expansion sustains granular biofertilizer broadcasting where seed drill penetration exceeds liquid injection deployment. Federal agricultural extension programs promote biological input validation at commercial scale. Gezira Scheme irrigation districts represent underpenetrated volume potential.
Middle East and Africa Biofertilizers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fermentation-based producers commanding premium positioning in liquid formulations while regional blenders capture protected share behind import barriers. Market structure tilts toward consolidation among multi-strain consortium developers and fragmentation in single-species commodity supply. Three archetypes dominate: multinational agrochemicals with biological portfolios, dedicated microbial fermentation houses, and regional formulators leveraging regulatory shelter. Competitive moves concentrate on backward integration into carrier material sourcing and enzymatic co-formulation partnerships.
Among multinational agrochemicals with biological portfolios, UPL Limited and Corteva Agriscience occupy positions spanning distribution infrastructure and seed treatment integration. Dedicated microbial fermentation is exemplified by Lallemand Inc and Novonesis Group, representing yeast-fermentation expertise and enzymatic stability platforms respectively. Regional formulators include Rizobacter Argentina S.A. and Symborg, sitting within regulatory shelter zones where import friction protects local blending economics.
| Leading Market Players |
|---|
| UPL Limited |
| Lallemand Inc |
| Corteva Agriscience |
| Novonesis Group |
| Rizobacter Argentina S.A. |
| Symborg |
| FMC Corporation |
| IPL Biologicals Limited |
| Biomax |
| Others |
Supply & Pricing Matrix
Peat and vermiculite carrier material costs cascade through formulation economics from East African harvest zones to Egyptian blending facilities, compressing margin pools when drought cycles spike input prices while drip irrigation compatibility commands premium positioning in Israeli desert agriculture.
Pricing Analysis
Volume throughput concentrates in granular formulations for Ethiopian and Sudanese wheat cultivation, while liquid biofertilizers capture margin premiums through precision fertigation bundling in Jordanian and Israeli vegetable zones. Price differentiation hinges on CFU concentration certification and cold chain guarantee tiers, with economy-grade powder formats serving Kenyan smallholder cooperatives at stripped-down price points. Pricing pressure stems from urea spot market volatility that periodically inverts biological substitution economics. Conventional agronomic buyers exhibit acute price sensitivity; export-facing South African horticultural operators tolerate premium multi-strain consortia for EU compliance.
Supply Chain Analysis
Regional distribution centers in Johannesburg and Cairo anchor hub-and-spoke patterns radiating toward Nairobi and Khartoum, with ambient-temperature transport legs degrading viable cell counts before Kenyan end-use. Manufacturing concentration rests on South Africa, Egypt, and Morocco, with fermentation capacity expansion lagging formulation demand across Sub-Saharan nodes. Raw material dependencies draw from East African peat deposits, Indian fermentation substrates, and European enzymatic stabilizers. Single-source vulnerability concentrates in carrier material harvest zones exposed to climate-driven supply interruption. Distribution runs through agricultural cooperative federations consolidating Nile Delta procurement alongside traditional agro-dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-strain consortia formulations are displacing single-species inoculants across commercial agriculture, with stacked functional traits replacing legacy nitrogen-fixing commodity products.
For Market Incumbents: Acquire fermentation capacity in Egyptian free zones to exploit import permit regulatory shelter against foreign manufacturer delays. Backward integration into East African carrier material sourcing hedges drought-cycle price spikes threatening formulation economics. Defensive patenting around enzymatic co-formulation platforms blocks Novonesis-type competitor expansion into date palm and citrus premium segments. For New Entrants and Emerging Players: E-commerce platforms serving Ethiopian and Kenyan smallholders bypass capital-intensive retail network buildout while capturing cooperative federation procurement consolidation in Kafr El Sheikh and Dakahlia governorates. White-space penetration targets Sudan's mechanized wheat belt granular broadcasting equipment retrofit partnerships. Mobile-enabled marketplace entry unlocks volume before cold chain infrastructure gaps constrain established South African hub competitors. For Investors and Strategic Acquirers: Egypt's Ministry of Agriculture and Land Reclamation extending import permit timelines is the leading indicator that domestic blending facility valuations will appreciate as regulatory friction intensifies. Five-to-ten year viability favors integrated producers with in-house quality verification capturing Saudi SFDA traceability mandate first-mover status. Acquisition target archetype: regional formulators with established Act 36 trial networks in South Africa. Monitor African Union Fertilizer and Soil Health Summit harmonization framework implementation as cross-border labeling standardization signal.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier Material Backward Integration | Upstream control over East African peat and vermiculite sourcing insulates formulation economics from drought-driven harvest volatility. |
| Enzymatic Co-Formulation Partnership | Protein hydrolysate platform alliances extend product stability in high-temperature Saudi and UAE storage environments. |
| Act 36 Registration Investment | Multi-season efficacy documentation capabilities accelerate South African biological product approval timelines versus foreign entrants. |
| Cooperative Federation Direct Supply | Bypassing agro-dealer networks captures Nile Delta volume consolidation through water user association procurement mandates. |
| Cold Chain Infrastructure Buildout | Refrigerated transport from Johannesburg production hubs preserves viable cell counts for Kenyan and Ethiopian end-users. |
Research Methodology
Multi-period observation of urea price volatility patterns, drip irrigation infrastructure deployment, and import permit approval timelines anchored the trend analysis, supplemented by interviews with fermentation plant managers, Egyptian Ministry of Agriculture and Land Reclamation registration officers, South African Registrar of Act 36 documentation specialists, Nile Delta cooperative federation procurement leads, and Israeli desert agriculture irrigation engineers. Secondary validation drew from African Union Fertilizer and Soil Health Summit framework documents, Egyptian customs biological input trade records, South African agricultural chemical registration databases, and Jordanian precision agriculture technology adoption reports. Bottom-up facility capacity estimates triangulated against top-down regional demand projections.
Segment-weighting across formulation type, crop application value tier, and distribution channel structure shaped the analytical framework, with liquid versus granular physics and organic farming certification requirements as cross-cutting dimensions. CAGRs were derived from installed capacity expansion trajectories, regulatory timeline assumptions, and substitution elasticity parameters calibrated to synthetic nitrogen spot market behavior. Industry-specific forecast inputs incorporated drip irrigation penetration rates in Israeli and Jordanian desert zones and cooperative federation procurement consolidation velocity in Egypt's Nile Delta corridor.
The model holds under sustained urea price volatility and regulatory import friction; deviation toward synthetic fertilizer price collapse or harmonized cross-border biological product standards would shift competitive positioning toward multinational fermentation houses. Forecasts reflect documented assumptions regarding carrier material harvest consistency and ambient transport degradation rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Brazil Biocontrol Agents Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
Asia-Pacific Agricultural Biologicals Market
Bio-Agriculture
North America Biocontrol Agents Market
Bio-Agriculture
China Biocontrol Agents Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Global Biofungicides Market
Bio-Agriculture
Brazil Biofertilizers Market
Bio-Agriculture
US Biofungicide Market
Bio-Agriculture
China Biostimulants Market
Bio-Agriculture
Aquatic Animal Vaccines Market
Bio-Agriculture
Asia-Pacific Biological Organic Fertilizers Market
Bio-Agriculture
Bioethanol Yeast Market